
 Smart Aquarium Devices Market | 2026-2036
Smart Aquarium Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Aquarium Devices Market Insights
Commercial aquarium operators is rotating toward automated monitoring systems as home aquarist growth moderates. Neptune Systems leverages proprietary controller architecture to dominate reef-system automation in North America. OASE sustains European market presence through integrated filtration-to-digital platform design. EcoTech Marine differentiates via high-output LED programming for coral photosynthesis optimization.
Smart aquarium devices encompass networked hardware and software systems that automate, monitor, and regulate aquatic environments through sensor feedback loops, typically operating within temperature ranges of 20-28°C and pH bands of 6.5-8.5 for freshwater or 8.1-8.4 for marine systems. These systems serve commercial aquaria, research laboratories, and hobbyist installations by reducing mortality rates and labor inputs through real-time parameter alerting and autonomous corrective action. Monitoring Systems and Water Quality Sensors command the largest installed base due to their role as prerequisite infrastructure for all downstream automation, while Cloud Integration represents the fastest-expanding technology tier as vendors shift recurring revenue from hardware sales to subscription-based remote management platforms. Lighting Solutions carries concentrated margin pools in the premium coral-keeping segment where spectral programmability justifies price premiums.
FDA oversight of antimicrobial claims on device coatings and EPA effluent standards for commercial discharge shape product development requirements in the United States, while the EU Green Deal and REACH chemical restrictions constrain material choices for European manufacturers. Japan's METI energy-efficiency benchmarks for consumer electronics extend to aquarium controller standby power, creating compliance costs for import brands. Stakeholders must weigh regulatory fragmentation against the margin advantages of unified global platform architectures.
Market Dynamics
Commercial aquaria operators now prioritize cloud-integrated sensor platforms over standalone controllers, driven by EPA effluent discharge mandates and the EU Green Deal's resource-efficiency requirements. This shift compresses hardware margins while expanding recurring software revenue pools for vendors capable of unified platform architectures.
Growth Catalysts
- EU Green Deal mandates:The EU's resource-efficiency directives force commercial aquaria to adopt real-time water quality monitoring, accelerating replacement of legacy manual testing systems across German and Dutch public aquaria.
- Marine research institutions:Universities and government laboratories in Japan and the United States deploy automated coral propagation systems requiring precise spectral control and nutrient dosing automation.
- Cloud platform migration:Vendors bundle sensor hardware with subscription-based remote management, converting capital expenditure into predictable operational budgets for multi-site aquarium operators.
Market Restraints
- Semiconductor supply concentration:Microcontroller and sensor chip sourcing remains concentrated among East Asian foundries, exposing aquarium controller manufacturers to lead time volatility and allocation constraints.
- REACH chemical restrictions:The European Chemicals Agency constrains material choices for sensor housings and antimicrobial coatings, forcing reformulation cycles that extend product development timelines.
- Technical interoperability gaps:Proprietary communication protocols between competing controller brands prevent seamless multi-vendor system integration, locking buyers into single-supplier ecosystems.
Strategic Opportunities
- India's emerging aquaculture sector:Shrimp and ornamental fish farming operations remain underpenetrated by automation, presenting first-mover advantages for ruggedized, cost-optimized monitoring systems.
- METI energy-efficiency standards:Japan's standby power benchmarks for consumer electronics create compliance differentiation for vendors achieving sub-watt controller idle consumption.
- AI-driven predictive analytics:Convergence of machine learning with historical water parameter databases enables mortality risk forecasting before visible stress symptoms emerge in sensitive marine species.
Industry Challenges
- Embedded systems firmware expertise:Aquarium controller development requires rare cross-disciplinary talent combining marine biology knowledge with real-time operating system programming.
- Multi-jurisdiction certification timelines:Simultaneous FCC electromagnetic compliance, CE marking, and METI electrical safety approvals extend product launch windows by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Aquarium Devices Market |
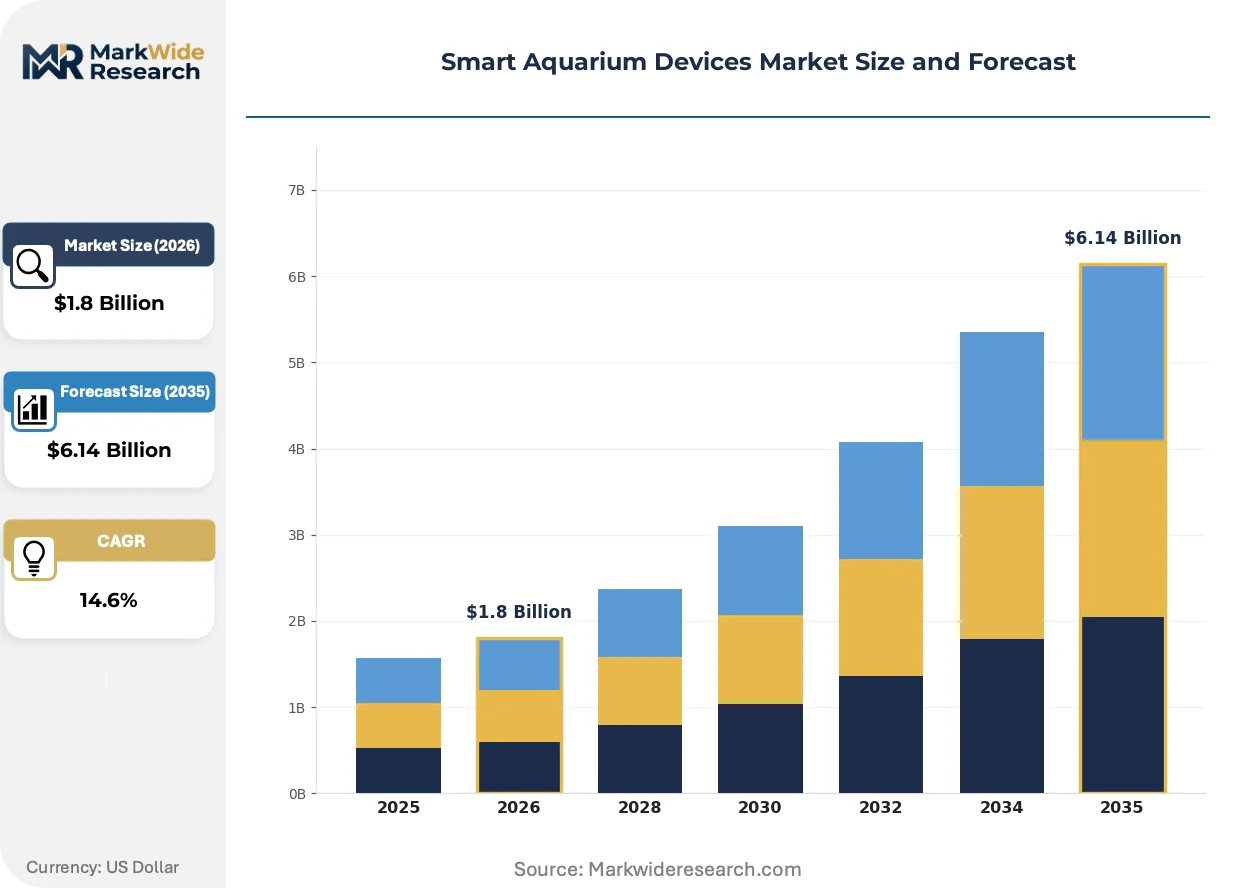
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $6.14 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monitoring Systems, Lighting Solutions, Automatic Feeders, Water Quality Sensors Technology: IoT, Bluetooth, Wi-Fi, Cloud Integration End User: Home Aquarists, Commercial Aquariums, Research Institutions, Educational Facilities Distribution Channel: Online Retailers, Specialty Stores, Direct Sales, Wholesale |
| Companies Covered | Neptune Systems, OASE, Petkit, Felix Smart, Koller Products, GHL, Seneye, EcoTech Marine, Fluval, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Aquarium Devices Market Trends and Innovations
Open-architecture controller software is dismantling proprietary ecosystem lock-in, enabling third-party developers to build modular automation apps. This democratization accelerates feature innovation while eroding vendor margin protection.
Edge computing is fragmenting aquarium automation architectures. Local sensor nodes now process water quality data onboard rather than transmitting raw streams to cloud servers, reducing latency for critical pH correction loops. Public aquaria in Germany and research facilities in California adopt hybrid edge-cloud configurations. The technology is fragmenting vendor business models by decoupling hardware sales from mandatory subscription dependencies.
EPA effluent standards for commercial discharge are tightening nutrient monitoring requirements. Aquarium operators must now document continuous nitrogen and phosphorus levels rather than periodic sampling. Large-scale commercial facilities in the United States face the steepest compliance burdens, driving demand for certified reference sensors with audit-trail logging capabilities.
Service unbundling is altering buyer-vendor relationships. Aquarium operators increasingly separate hardware procurement from installation and calibration services, sourcing technical labor through regional aquaculture consultants rather than manufacturer field teams. This pattern is most pronounced among mid-sized commercial aquaria in Florida and Mediterranean coastal zones where specialized marine technician networks have matured.
Smart Aquarium Devices Market Segmentation
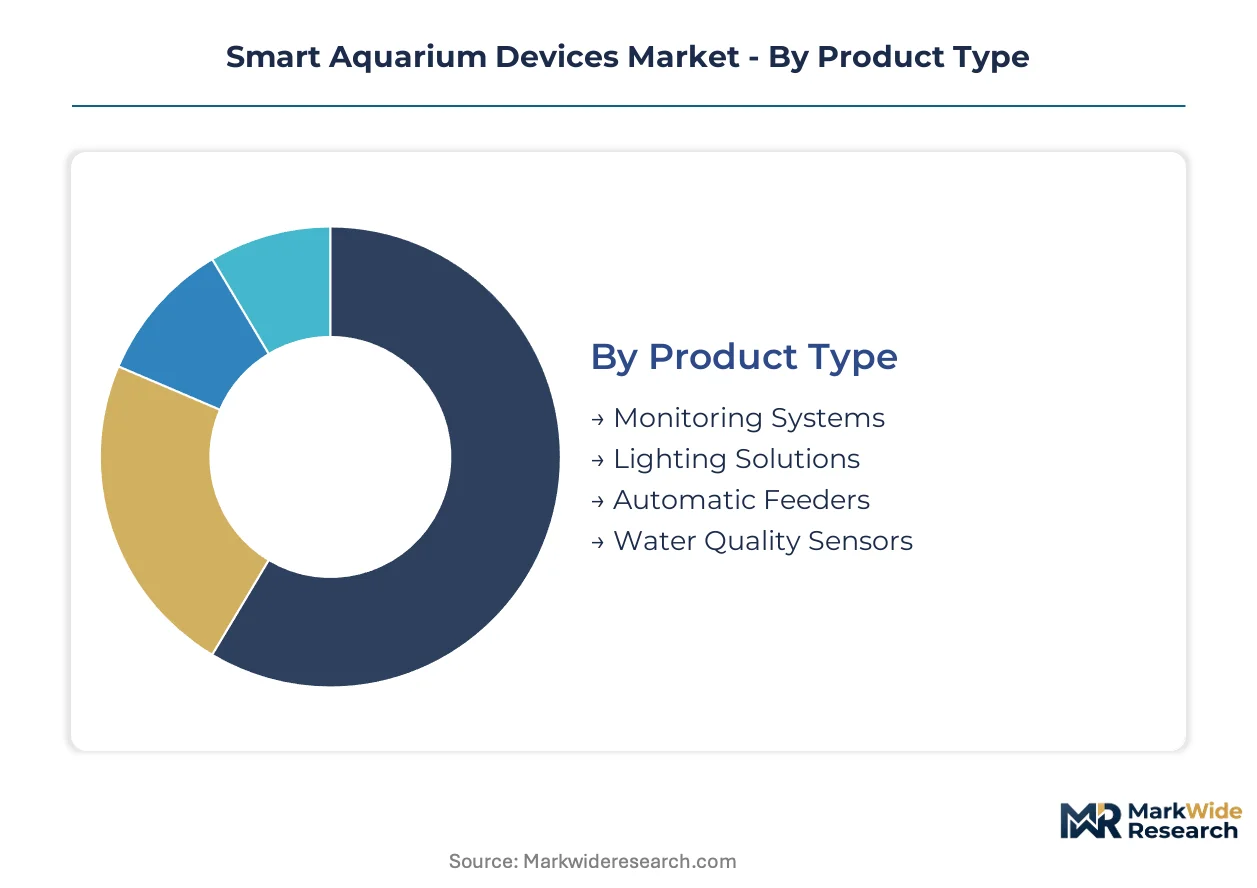
Segmentation in the Smart Aquarium Devices Market reveals distinct substitution pressures across hardware and service tiers. Product type divisions expose vulnerability of standalone controllers to integrated platform bundles, while technology segments show connectivity standards competing for protocol dominance.
Product Type:
Substitution pressure concentrates most intensely in the controller and sensor tiers, where integrated platforms displace standalone hardware through bundled software subscriptions.
- Monitoring Systems:Multi-parameter controllers automate temperature, pH, salinity, and dissolved oxygen regulation through programmable setpoints and alarm thresholds. German public aquaria and Japanese research facilities drive replacement demand as EPA effluent mandates and METI efficiency standards obsolete legacy manual systems. These systems anchor the volume base while Cloud Integration gains share at the steepest rate.
- Lighting Solutions:Spectral-programmable LED arrays deliver precise photosynthetically active radiation for coral propagation and planted freshwater systems. Premium reef-keeping segments in the United States absorb highest price points where spectral customization justifies margin premiums over fixed-spectrum alternatives.
- Automatic Feeders:Precision dispensers with programmable scheduling and portion control reduce labor inputs for commercial multi-tank operations.
- Water Quality Sensors:Discrete probes for ammonia, nitrite, nitrate, and phosphate detection serve as prerequisite infrastructure for downstream automation loops.
Monitoring Systems anchor the volume base while Lighting Solutions gains share at the steepest rate among premium installation tiers.
Technology:
Cost tier stratification separates enterprise-grade cloud architectures from consumer-focused local connectivity, with interoperability gaps fragmenting buyer choices.
- IoT:Cellular and LPWAN-enabled devices transmit telemetry across distributed commercial sites without local network dependency. Shrimp farming operations in India and ornamental aquaculture clusters in Southeast Asia adopt ruggedized IoT sensors where terrestrial connectivity remains unreliable.
- Cloud Integration:Subscription-based remote management platforms convert capital expenditure into operational budgets through predictive analytics and multi-site dashboards. Multi-state aquarium operators in the United States prioritize these platforms for centralized compliance documentation under tightening EPA nutrient monitoring requirements.
- Wi-Fi:Standard 2.4 GHz and 5 GHz connectivity dominates residential installations with reliable broadband infrastructure.
- Bluetooth:Short-range protocols persist in entry-level hobbyist controllers where cost minimization outweighs remote access requirements.
Wi-Fi dominates unit shipments in mature markets while Cloud Integration expands most quickly among commercial operators seeking operational expenditure conversion.
End User:
Application maturity diverges sharply, with commercial and research segments demanding audit-trail capabilities that home installations rarely require.
- Commercial Aquariums:Public aquaria, marine parks, and large-scale ornamental breeding facilities require certified reference sensors with continuous data logging for regulatory compliance. Facilities in Germany and the United States face the steepest documentation burdens under EU Green Deal resource-efficiency mandates and EPA effluent discharge standards.
- Research Institutions:University laboratories and government marine biology stations deploy automated coral propagation systems with precise nutrient dosing and spectral control. California and Japanese research clusters lead adoption of AI-integrated predictive mortality forecasting for sensitive species.
- Home Aquarists:Residential reef-keeping and freshwater hobbyist segments moderate growth as cloud platform migration concentrates vendor attention on commercial accounts.
- Educational Facilities:Schools and public science centers balance durability requirements against budget constraints in mid-scale installation tiers.
Commercial Aquariums generate the highest average revenue per installation while Research Institutions adopt predictive analytics capabilities at the leading edge.
Distribution Channel:
Customer type fragmentation separates procurement specialists seeking unbundled hardware from operators demanding full-service integration.
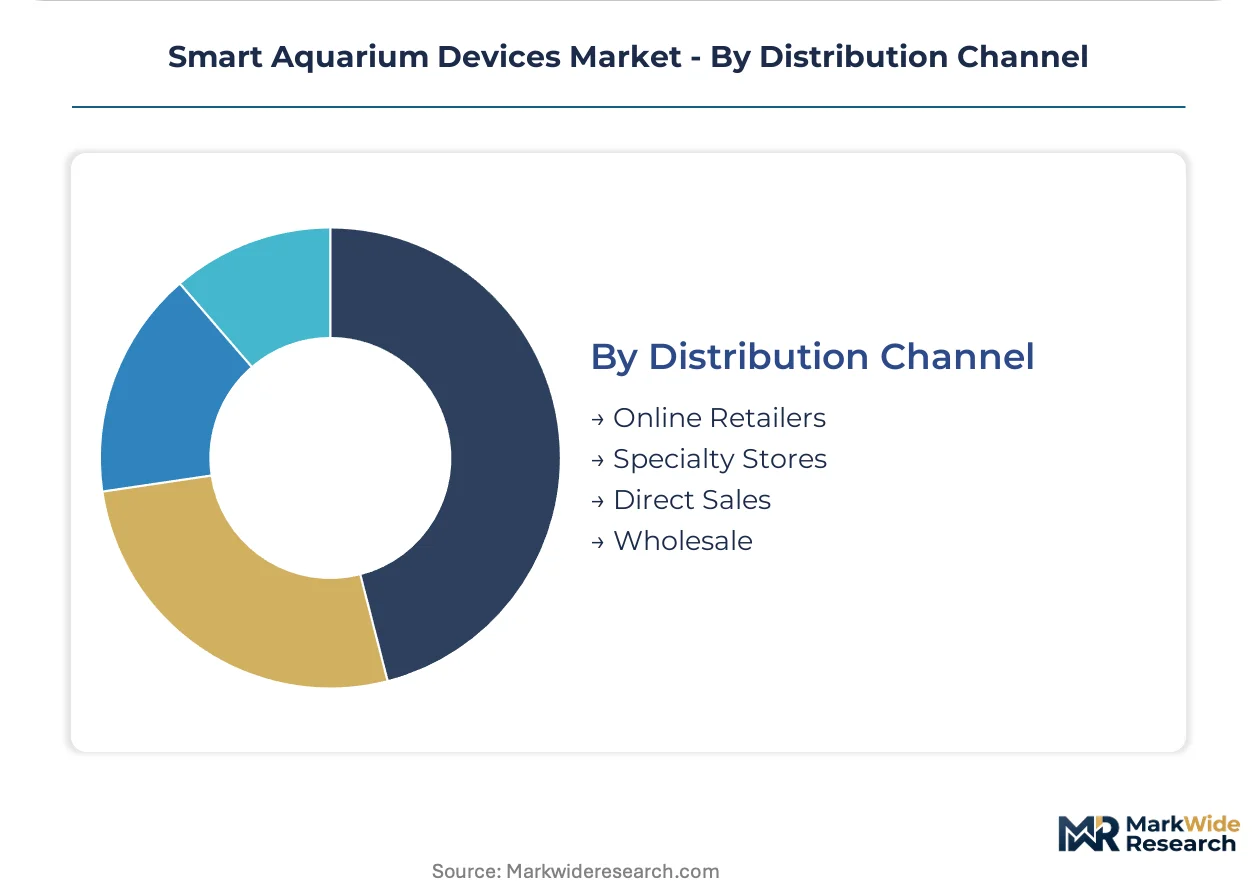
- Online Retailers:E-commerce platforms aggregate comparison shopping for hobbyist-grade controllers and replacement sensors, with fastest growth in markets where marine technician networks remain underdeveloped.
- Specialty Stores:Regional aquaculture consultants and dedicated aquarium retailers provide installation and calibration services that manufacturers increasingly unbundle from hardware sales. Florida and Mediterranean coastal zones exhibit the most mature specialty service networks.
- Direct Sales:Manufacturer field teams target large commercial accounts with customized platform architectures and multi-year service agreements.
- Wholesale:Distributor networks supply bulk sensor replacements and controller upgrades for multi-site operators.
Specialty Stores retain strongest position in service-intensive commercial tiers while Online Retailers capture the steepest volume expansion in underpenetrated geographies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German manufacturers export cloud-integrated sensor platforms to commercial aquaria across the United States and Japan, establishing a dominant trade corridor in automated water quality infrastructure.
United States
Marine research institutions in California and public aquaria in Florida drive demand for certified reference sensors with continuous audit-trail logging. EPA effluent discharge standards for commercial facilities mandate real-time nitrogen and phosphorus monitoring. The Greater Boston cluster anchors coral propagation research requiring precise spectral control systems.
Germany
Public aquaria in Berlin and Hamburg prioritize resource-efficiency upgrades under EU Green Deal directives. ECHA REACH chemical restrictions constrain sensor housing materials, forcing reformulation cycles among domestic manufacturers. The Bavaria region concentrates development of integrated filtration-to-digital platforms for European commercial operators.
Japan
University laboratories in the Kanto region deploy automated nutrient dosing systems for sensitive marine species propagation. METI energy-efficiency benchmarks for consumer electronics extend to aquarium controller standby power, creating compliance differentiation for sub-watt idle consumption designs. The Osaka-Kobe manufacturing corridor produces high-precision pH and dissolved oxygen probes.
India
Shrimp farming operations in Andhra Pradesh and ornamental fish breeding in West Bengal remain underpenetrated by automation, presenting first-mover opportunities for ruggedized monitoring systems. The country's national aquaculture regulator emphasizes biosecurity documentation that IoT-enabled platforms can streamline. Gujarat's emerging aquaculture parks attract pilot deployments of cost-optimized cellular sensors.
United Kingdom
Marine biology stations in Scotland and public science centers in London balance durability requirements against constrained capital budgets. CE marking alignment with EU technical standards maintains cross-border equipment compatibility despite regulatory divergence. The Southwest England marine research cluster adopts hybrid edge-cloud configurations for latency-sensitive parameter correction.
Smart Aquarium Devices Market Competitive Landscape
Listed leaders compete with private specialists across proprietary controller architectures, creating a tiered structure where scale advantages clash with niche customization capabilities. The vendor base organizes around three strategic archetypes: integrated platform bundlers, spectral lighting specialists, and regional filtration-to-digital designers. Consolidation pressure concentrates among mid-scale controller manufacturers lacking cloud subscription revenue streams. Dominant competitive moves include strategic partnerships for semiconductor supply security and geographic expansion into India's emerging aquaculture belt.
Within the integrated platform tier, Neptune Systems and OASE exemplify contrasting regional dominance patterns, with the former anchoring North American reef-system automation and the latter sustaining European market presence through unified hardware-software architectures. EcoTech Marine occupies a position among spectral-programmable lighting specialists serving premium coral-keeping segments where photosynthesis optimization justifies price premiums. These three entities represent the archetype spectrum: proprietary controller architecture, integrated filtration-to-digital design, and high-output LED programmability respectively.
| Leading Market Players |
|---|
| Neptune Systems |
| OASE |
| Petkit |
| Felix Smart |
| Koller Products |
| GHL |
| Seneye |
| EcoTech Marine |
| Fluval |
| Others |
Pricing and Supply Chain Analysis
Forty-five to sixty-day microcontroller lead times from East Asian foundries directly compress hardware margins while amplifying pricing power for vendors with captive semiconductor inventories. This inventory tension shapes how commercial aquarium operators negotiate bundled platform contracts against standalone sensor procurement.
Pricing Analysis
Next-generation cloud-integrated controllers command 40-60% price premiums over prior-generation Wi-Fi-local units, while entry-level Bluetooth devices face steepest erosion. Three-tier pricing structure across premium cloud-subscription, standard connected-hardware, and economy standalone levels dominates commercial procurement. Price differentiation rests on certification grade—EPA audit-trail compliance for nutrient monitoring versus hobbyist-grade accuracy—and bundled calibration service depth. Cost compression in the mid-tier intensifies because IoT sensor commoditization accelerates faster than software differentiation. Home aquarists exhibit highest price sensitivity, while German public aquaria and multi-state US operators absorb premium tiers for compliance documentation capabilities.
Supply Chain Analysis
Port congestion on the Shanghai-Los Angeles lane elevates inbound logistics costs for sensor housings and LED driver components arriving from Chinese contract manufacturers. Semiconductor fabrication concentrates in Taiwan, South Korea, and Japan, while precision pH probe assembly localizes in Germany and Japan. Raw material dependencies span rare-earth phosphors for coral-optimized LEDs, marine-grade stainless for submersible housings, and antimicrobial coating precursors constrained by ECHA REACH restrictions. Single-source vulnerability in microcontroller allocation from TSMC and Samsung Foundry exposes controller vendors to allocation rationing during demand spikes. Distribution runs through specialty aquaculture consultants in Florida and Mediterranean zones, with direct manufacturer sales capturing large commercial accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cloud subscription revenue layers for multi-site remote management expand faster than hardware unit sales, converting capital expenditure into recurring operational budgets for commercial operators.
For Market Incumbents: Secure semiconductor supply through multi-year foundry allocation agreements before capacity constraints deepen. Defend margin position by backward integration into pH probe membrane production, reducing dependency on Japanese sensor specialists facing METI energy-efficiency compliance costs. Prioritize certification investment in EPA audit-trail logging capabilities to lock in US commercial aquaria facing effluent discharge mandates. For New Entrants and Emerging Players: Calibration-as-a-service gaps in India's shrimp farming belt expose white-space where incumbents under-serve ruggedized, cost-optimized monitoring demand. Target Andhra Pradesh and Gujarat aquaculture parks with cellular-enabled IoT sensors bypassing unreliable terrestrial infrastructure. Deploy through regional aquaculture consultants rather than direct sales to minimize upfront channel investment. For Investors and Strategic Acquirers: Long-term, this sits as a recurring-revenue infrastructure play because cloud platform migration converts one-time hardware transactions into decade-long subscription relationships. Acquisition targets should display unified hardware-software architectures with existing commercial account bases. Watch for inflection when EPA nutrient monitoring rules tighten documentation frequency from monthly to continuous logging.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies sensor hardware with cloud subscription tiers for multi-site operators facing EPA compliance. |
| Backward Integration | Captive production of pH probe membranes reduces Japanese supplier dependency and lead-time volatility. |
| Geographic Expansion | First-mover deployment in India's shrimp belt leverages underpenetrated automation demand and biosecurity documentation requirements. |
| Strategic Partnership | Foundry allocation agreements with TSMC or Samsung Foundry secure microcontroller supply against allocation rationing. |
| Certification Investment | EPA audit-trail logging capabilities differentiate premium tiers for commercial aquaria facing discharge mandates. |
Research Methodology
A standing panel of commercial aquarium operations directors, marine research laboratory managers, aquaculture procurement leads, and controller firmware engineers provided ongoing calibration against market developments. Primary interviews combined with secondary validation from EPA effluent discharge filings, METI energy-efficiency benchmark disclosures, EU Green Deal implementation reports, and customs trade data for sensor component flows. Bottom-up unit shipment estimates triangulated against top-down addressable market sizing across technology and end-use segments.
Consistency checks validated volume and value outputs against external benchmarks including semiconductor allocation reports and aquaculture automation capex surveys. The analytical framework modeled product type, technology connectivity standard, end-user application maturity, and regional regulatory cluster across the projection horizon. CAGRs derived from segment-level growth rate reconciliation with macroeconomic aquaculture investment trends and cloud platform adoption curves. Forecast inputs incorporated sensor replacement cycle compression and subscription revenue conversion rates for multi-site operators.
Underlying assumptions cover sustained EPA enforcement of nutrient monitoring rules, stable East Asian foundry capacity allocation, and continued EU Green Deal resource-efficiency mandate expansion, with deviation risk concentrated in semiconductor supply disruptions and regulatory timeline delays. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Consumer Electronics
Global Bluetooth Mono Earpieces Market
Consumer Electronics
Apple Accessories Market
Consumer Electronics
DVD Remote Controls Market
Consumer Electronics
Wet Wipes Market
Consumer Electronics
US Mobile Phone Accessories Market
Consumer Electronics
Professional Headset Market
Consumer Electronics
Blu Ray Players Market
Consumer Electronics
Mobile Accessories Market
Consumer Electronics
Global Earphones and Headphones Market
Consumer Electronics
US Knife Sharpening Service Market
Consumer Electronics
Pool Speakers Market
Consumer Electronics
Waterproof Speaker Market
Consumer Electronics
India Consumer Electronics Market
Consumer Electronics
China Smartphone Market
Consumer Electronics
HiFi Electronics Market
Consumer Electronics
Gaming PC Market