
 North America Gaming Accessories Market | 2026-2036
North America Gaming Accessories Market Size, Share, and Industry Trends Forecast 2026-2036
North America Gaming Accessories Market Analytics
Buyer concentration in North America is realigning as esports organizations and streaming collectives consolidate purchasing power while cloud gaming services fragment demand across casual subscribers. Logitech International SA leverages its Swiss-American engineering footprint to sustain dominance in wireless mouse and keyboard categories. Corsair Gaming Inc. anchors its position through in-house production of mechanical switches and RGB ecosystems. Razer Inc. differentiates via software-hardware integration targeted at competitive gamers.
Gaming accessories encompass input peripherals, audio equipment, and control devices engineered with sub-millisecond polling rates, optical mechanical switches, and low-latency wireless protocols for interactive entertainment. Headsets incorporating spatial audio and active noise cancellation command premium positioning, while controllers with haptic feedback and adaptive triggers represent the fastest-growing product category. Competitive gamers and streamers drive margin concentration through recurring upgrade cycles, whereas casual gamers and cloud gamers expand volume through budget-tier keyboards and mice distributed via online retail and mass merchants.
The FCC governs radio frequency emissions from wireless gaming peripherals through Part 15 certification, while Health Canada and the PMRA oversee chemical compliance in polymer housings and flame-retardant coatings. The EPA's evolving e-waste directives and state-level extended producer responsibility laws in California and Washington reshape material selection and end-of-life collection obligations. Stakeholders must monitor regulatory harmonization pressures between Washington and Ottawa as cross-border supply chains face divergent compliance timelines.
Market Dynamics
Esports organization procurement consolidation and FCC Part 15 certification timelines for wireless peripherals are compressing product development cycles while fragmenting volume across cloud gaming casual subscribers.
Growth Catalysts
- California and Texas arena construction:Purpose-built esports venues in Los Angeles, San Francisco, Dallas, and Austin are accelerating hardware refresh rates for precision peripherals with sub-millisecond polling requirements.
- FCC equipment authorization streamlining:Pre-certification testing partnerships with Telecommunication Certification Bodies are reducing wireless controller and headset time-to-market for compliant manufacturers.
- Optical mechanical switch adoption:Competitive gamers are driving replacement cycles for keyboards featuring infrared actuation and zero-debounce delay architectures.
Market Restraints
- Rare earth magnet supply concentration:Neodymium dependency for haptic actuator motors creates input cost volatility tied to Chinese export quota fluctuations.
- Extended producer responsibility compliance:California and Washington state e-waste directives impose end-of-life collection infrastructure costs that compress margin structures for polymer-intensive peripheral categories.
- Wireless protocol interference density:2.4 GHz spectrum saturation in urban gaming cafes degrades latency consistency below competitive thresholds.
Strategic Opportunities
- Canadian prairie provinces:Saskatchewan and Manitoba present underpenetrated demand for mid-tier streaming peripherals as remote content creation clusters emerge outside Toronto and Vancouver.
- Spatial audio-vision convergence:Headset manufacturers integrating head-tracking with adaptive trigger controllers can capture premium positioning in virtual reality gaming transitions.
- US-Mexico nearshoring incentives:IRA domestic content provisions and USMCA cumulation rules are creating assembly relocation opportunities for controller production.
Industry Challenges
- FCC Part 15 certification backlog:Wireless peripheral approval queues at accredited test labs are extending product launch timelines by four to six months.
- RGB ecosystem integration complexity:Synchronization protocols across motherboard, peripheral, and lighting software stacks require specialized firmware engineering talent in short supply.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Gaming Accessories Market |
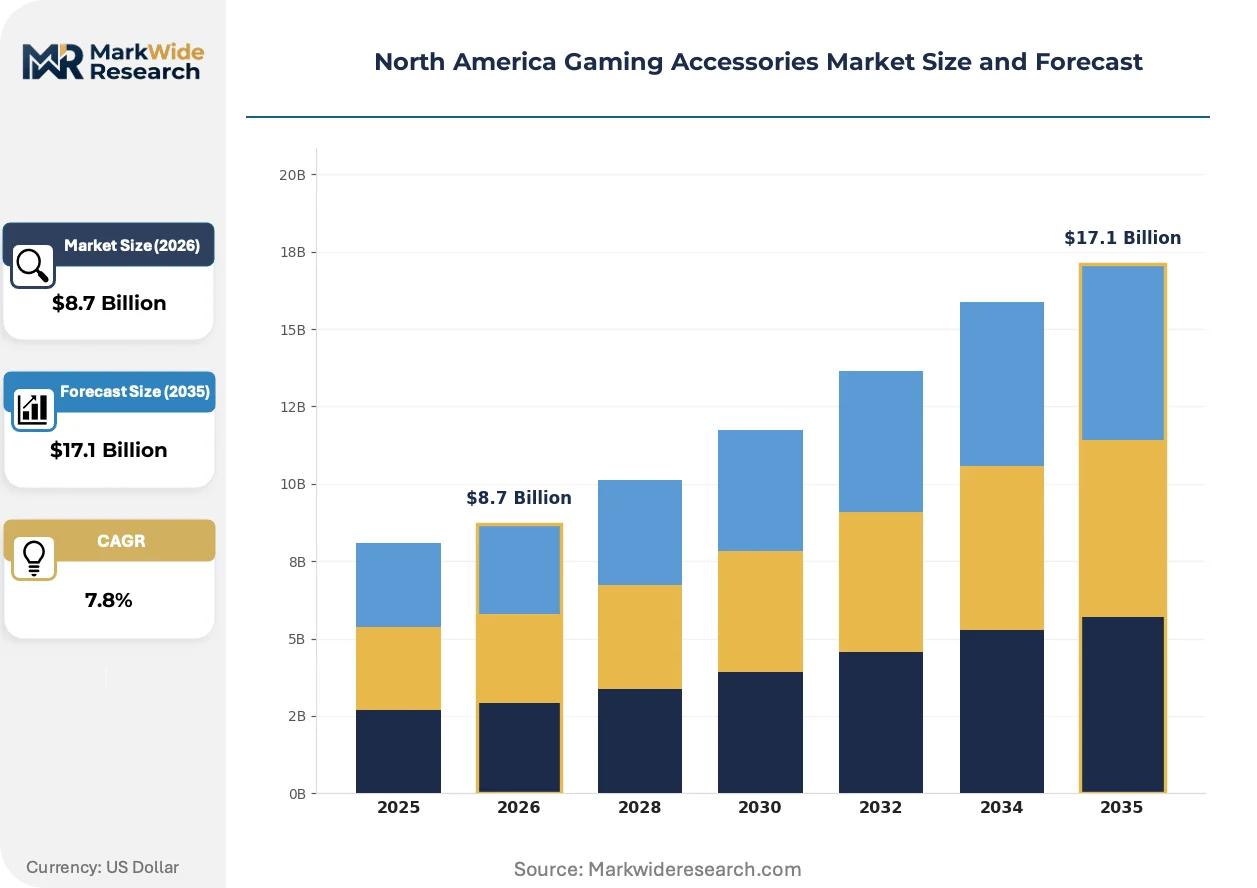
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $17.1 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Headsets, Keyboards, Mice, Controllers End User: Casual Gamers, Competitive Gamers, Streamers, Cloud Gamers Price Tier: Premium, Mid-Range, Budget, Luxury Distribution Channel: Online Retail, Specialty Stores, Mass Merchants, Direct Sales |
| Companies Covered | Logitech International SA, Razer Inc., Corsair Gaming Inc., SteelSeries, HyperX, Turtle Beach Corporation, Cooler Master Technology Inc., Dell Technologies Inc., ASUS, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Gaming Accessories Market Evolving Landscape
Hardware-software integration depth and regulatory compliance automation are redefining competitive differentiation in gaming peripherals, with modular architectures displacing monolithic product designs.
Hot-swappable switch sockets are modularizing mechanical keyboard construction. Esports teams and enthusiast builders are adopting standardized 3-pin and 5-pin MX-compatible footprints at accelerating rates. This modularity is compressing replacement cycles from full-board purchases to component-level upgrades.
California's SB-54 extended producer responsibility framework is mandating recycled content thresholds for polymer housings. Manufacturers are reformulating ABS and PBT blends to meet 30% post-consumer recycled minimums. Peripheral lines targeting West Coast distribution are prioritizing mass balance-certified supply chains.
Cloud gaming subscribers are fragmenting demand away from premium peripheral bundles toward budget-tier, platform-agnostic controllers. Mass merchant and direct-to-consumer channels are capturing volume previously concentrated in specialty retail. This pattern is most visible in Texas and Florida metropolitan markets where casual gamer density exceeds competitive player concentration.
North America Gaming Accessories Market Segmentation
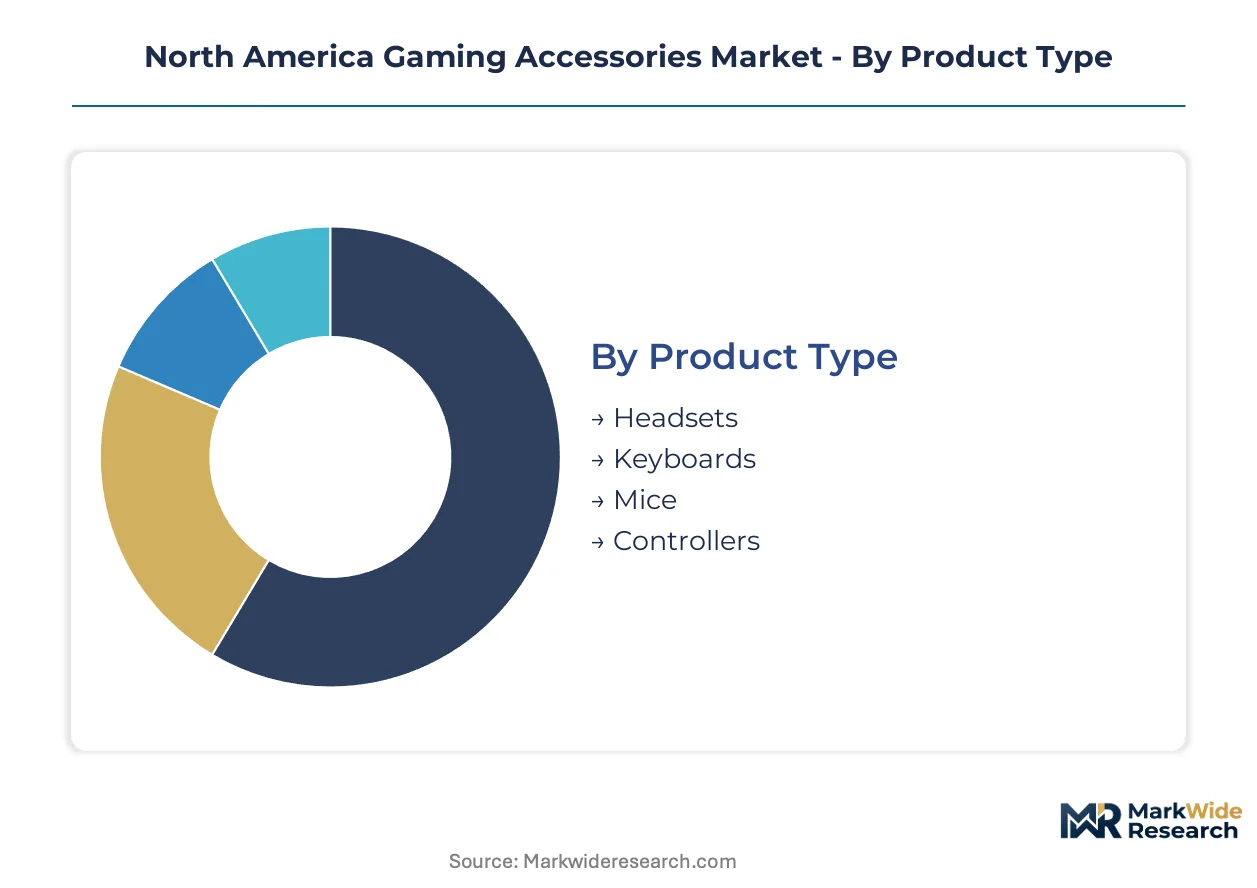
Hardware specialization and user workflow intensity create distinct performance tiers across North American gaming peripherals. Segmentation reveals where margin concentration aligns with technical specifications versus volume scale.
Product Type:
Standalone peripherals dominate competitive environments while embedded controller systems anchor console ecosystems across United States and Canadian households.
- Headsets:Spatial audio architectures with active noise cancellation and 3D positional tracking command premium positioning. Demand concentrates in California and Texas streaming studio buildouts where broadcast-quality microphone arrays and low-latency wireless protocols are non-negotiable specifications.
- Controllers:Haptic feedback motors with adaptive trigger resistance and gyroscopic aiming represent the fastest-expanding hardware category. FCC Part 15 certification requirements for 2.4 GHz and Bluetooth protocols shape development timelines for manufacturers targeting esports arena procurement in Dallas and Los Angeles.
- Keyboards:Optical mechanical switches with hot-swappable sockets and sub-millisecond polling rates serve competitive player replacement cycles.
- Mice:Ultra-lightweight honeycomb chassis with PixArt optical sensors and PTFE glide skates target FPS specialist configurations.
Controllers lead volumes today; headsets are gaining share fastest on spatial audio-vision convergence.
End User:
Customer workflow intensity determines peripheral refresh frequency and price tolerance across the value chain.
- Competitive Gamers:Sub-millisecond latency requirements and tournament-grade durability standards drive 12-to-18-month replacement cycles. Esports organization procurement consolidation in California and Texas is standardizing on optical mechanical keyboards and lightweight mice with 8K Hz polling.
- Streamers:Broadcast-quality audio capture and RGB ecosystem synchronization command premium bundle pricing. Los Angeles and Austin content creation clusters are accelerating demand for headset-controller combinations with seamless OBS integration.
- Casual Gamers:Platform-agnostic controllers and membrane keyboards distributed via mass merchants dominate volume.
- Cloud Gamers:Low-latency wireless protocols and budget-tier peripherals prioritize convenience over customization.
Casual gamers anchor volume scale; competitive gamers concentrate margin capture.
Price Tier:
Cost stratification aligns with certification grade, material specification, and software integration depth rather than geography.
- Premium:Aircraft-grade aluminum chassis, PBT double-shot keycaps, and proprietary wireless protocols with sub-1ms latency. Esports arena construction in Texas and California is standardizing on this tier for tournament deployment.
- Mid-Range:ABS construction with optical mechanical switches and standardized 2.4 GHz wireless captures streaming collective procurement.
- Budget:Membrane keyboards and generic controllers with basic haptic feedback serve cloud gaming subscriber expansion.
- Luxury:Limited-edition collaborations with CNC-machined components and custom firmware target collector segments.
Mid-Range drives unit economics; Premium is climbing the fastest on esports infrastructure investment.
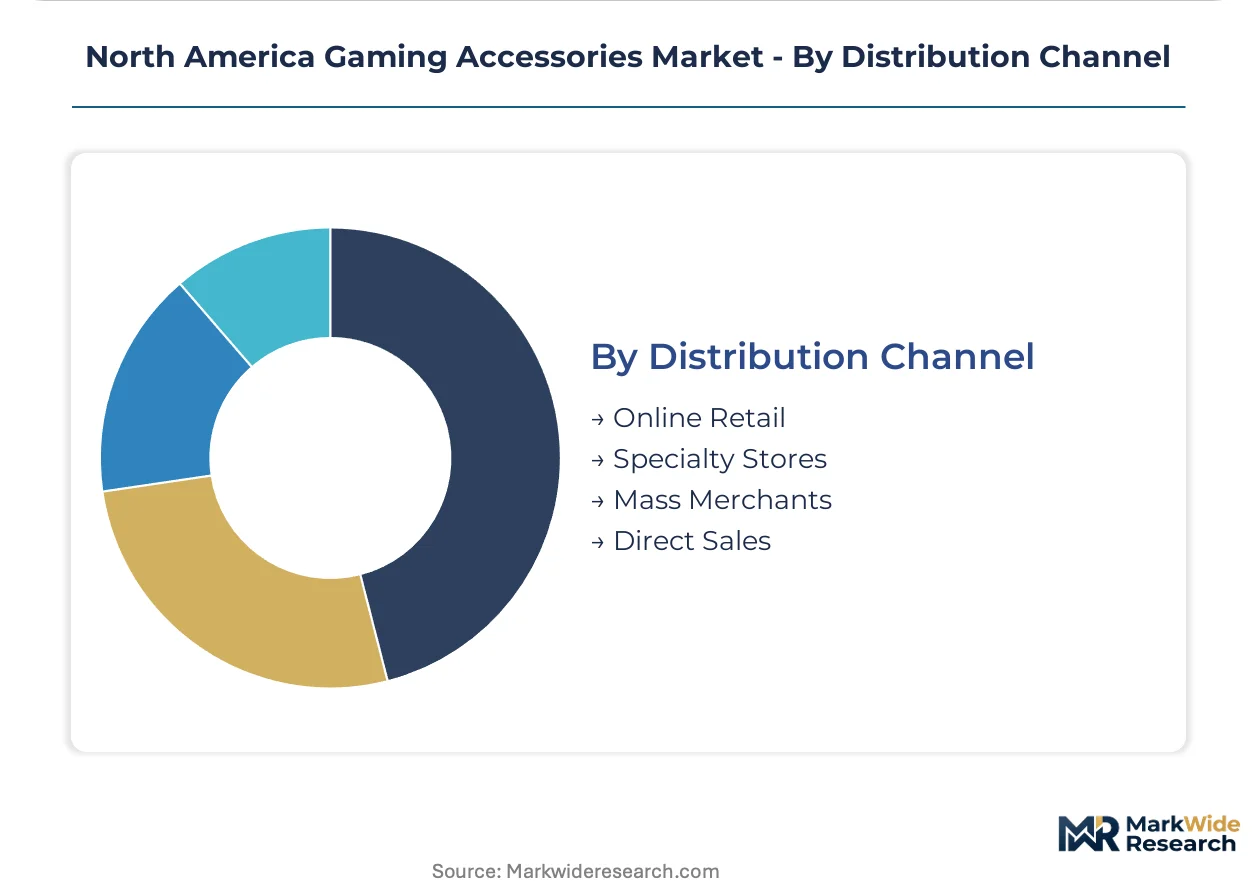
Distribution Channel:
Channel selection reflects buyer type density and technical support requirements across metropolitan markets.
- Online Retail:Direct-to-consumer platforms with configuration tools and firmware download portals capture enthusiast self-selection. Amazon and manufacturer storefronts dominate competitive gamer and streamer procurement in California and Texas.
- Specialty Stores:Hands-on switch testing and build consultation services anchor mechanical keyboard customization.
- Mass Merchants:Walmart and Target distribution captures casual gamer and cloud gamer volume in Florida and Midwest metropolitan areas.
- Direct Sales:Enterprise contracts with esports organizations and arena operators bypass retail markup.
Online retail leads transaction volume; direct sales is expanding most quickly on B2B procurement consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Engineering talent clusters in California, Texas, and Ontario anchor peripheral innovation pipelines across the continent.
United States
California and Texas dominate esports arena construction and streaming studio buildouts, accelerating hardware refresh cycles for precision peripherals. FCC Part 15 certification requirements for wireless controllers and headsets compress product development timelines for manufacturers targeting Los Angeles and Dallas procurement clusters. Purpose-built venues in Austin and San Francisco standardize on optical mechanical switches and sub-millisecond polling rate specifications.
Canada
Toronto and Vancouver content creation hubs concentrate demand for broadcast-quality headsets with spatial audio and active noise cancellation. Health Canada and PMRA oversight of chemical compliance in polymer housings shapes material selection for peripheral manufacturers distributing across provincial markets. Saskatchewan and Manitoba present emerging demand for mid-tier streaming peripherals as remote creator clusters expand beyond traditional coastal centers.
Mexico
USMCA cumulation rules and IRA domestic content provisions are drawing controller assembly operations toward northern border states and Baja California manufacturing zones. The country's federal consumer protection agency oversees electronics labeling and warranty compliance for gaming peripherals entering the domestic retail channel. Mexico City metropolitan area consumption patterns favor platform-agnostic controllers distributed through mass merchant channels serving casual gamer expansion.
North America Gaming Accessories Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across hardware and software integration vectors. The vendor base stratifies into three tiers: Swiss-American engineering houses with wireless protocol expertise, Asian-origin specialists with RGB ecosystem depth, and diversified electronics conglomerates leveraging distribution scale. Competitive positioning hinges on in-house switch production, firmware customization capabilities, and esports organization sponsorship lock-ins. M&A activity targets mechanical switch foundries and spatial audio engineering teams, while strategic partnerships with Telecommunication Certification Bodies accelerate FCC approval timelines.
Within the pure-play specialist tier, Logitech International SA exemplifies Swiss-American engineering integration, Corsair Gaming Inc. represents in-house mechanical switch production archetypes, and Razer Inc. anchors software-hardware convergence positioning. These three structures illustrate the competitive vectors defining procurement consolidation patterns across California and Texas esports infrastructure buildouts.
| Leading Market Players |
|---|
| Logitech International SA |
| Razer Inc. |
| Corsair Gaming Inc. |
| SteelSeries |
| HyperX |
| Turtle Beach Corporation |
| Cooler Master Technology Inc. |
| Dell Technologies Inc. |
| ASUS |
| Others |
Value Network & Pricing Analysis
Optical mechanical switch production migration from traditional contact-based assemblies to infrared actuation architectures is compressing per-unit manufacturing costs while concentrating supplier leverage among Taiwanese and Chinese precision component foundries. This dual shift simultaneously erodes margin buffers for brands without captive switch production and amplifies procurement power for esports organizations placing bulk orders across California and Texas arena buildouts.
Pricing Analysis
Bundled peripheral suites for esports organizations contrast with unbundled direct-to-consumer transactions for enthusiast builders. Three-tier pricing structure across premium tournament-grade, mid-range streaming, and economy cloud-gaming tiers separates certification-grade FCC Part 15 wireless from basic Bluetooth alternatives. Cost compression in the economy tier is intensifying because mass merchant channel consolidation demands volume rebates. Casual gamers exhibit highest price sensitivity; competitive esports organizations demonstrate lowest sensitivity due to standardization requirements.
Supply Chain Analysis
Regional distribution centers in Los Angeles, Dallas, and Toronto anchor hub-and-spoke fulfillment patterns for North American peripheral distribution. Manufacturing concentrates in China, Taiwan, and Vietnam for PCB assemblies, mechanical switches, and sensor modules. Neodymium magnet supplies for haptic actuators draw from Chinese rare earth processing facilities. Single-source vulnerability in optical sensor ICs from PixArt and Avago creates procurement risk. Distribution runs through Amazon fulfillment networks, direct-to-consumer manufacturer portals, and mass merchant DCs serving Florida and Midwest metropolitan clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
North America gaming accessories function as a stable compounder market where esports infrastructure investment sustains replacement cycle velocity across economic cycles.
For Market Incumbents: Deploy in-house switch production capabilities to defend margin structures against optical mechanical commoditization. Capture esports organization procurement consolidation through direct sales contracts that bypass retail markup. Counter emerging white-label entrants from Shenzhen by accelerating FCC pre-certification partnerships with Telecommunication Certification Bodies.
For New Entrants and Emerging Players: Spatial audio-vision convergence technology offers entry wedge into headset-controller bundle white space. Target Saskatchewan and Manitoba streaming collectives with mid-tier peripherals as remote creator clusters expand beyond Toronto and Vancouver coastal centers. Pursue platform-agnostic controller positioning for cloud gaming subscriber acquisition in Texas and Florida mass merchant channels.
For Investors and Strategic Acquirers: Roll-up economics work for mechanical switch foundries and spatial audio engineering teams because esports organization standardization creates durable supplier relationships with switching costs. Five-to-ten year viability hinges on firmware customization capabilities rather than hardware specifications alone. Monitor FCC Part 15 certification queue lengths as inflection indicator for wireless peripheral launch velocity and inventory risk accumulation.
| Strategic Initiative | Industry Significance |
|---|---|
| In-House Switch Production | Corsair's captive Kailh partnerships demonstrate margin protection against optical mechanical price erosion. |
| FCC Pre-Certification Partnership | Telecommunication Certification Body relationships compress wireless headset time-to-market for Los Angeles arena procurement. |
| Spatial Audio Engineering Acquisition | Head-tracking integration with adaptive triggers captures premium positioning in VR gaming transitions. |
| Canadian Prairie Distribution Expansion | Saskatchewan and Manitoba remote creator clusters present underpenetrated mid-tier streaming peripheral demand. |
| US-Mexico Nearshoring Relocation | USMCA cumulation rules and IRA domestic content provisions draw controller assembly toward Baja California zones. |
Research Methodology
Coverage spans the United States, Canada, and Mexico, with primary inputs from each national market. Primary interviews incorporated esports organization procurement directors, streaming collective technical leads, peripheral manufacturer product managers, and FCC compliance consultants. Secondary validation drew from SEC 10-K filings, FCC equipment authorization databases, Health Canada chemical compliance notices, and USMCA trade flow records. Bottom-up unit economics triangulated against top-down category spend estimates.
Granularity-level modeling deployed product-type splits for headsets, controllers, keyboards, and mice; end-user segmentation across competitive gamers, streamers, casual gamers, and cloud subscribers; and price-tier stratification by certification grade and material specification. CAGRs were derived from replacement cycle velocity assumptions tied to esports arena construction pipelines and optical mechanical switch adoption curves. Forecast inputs included FCC Part 15 certification timeline distributions and cloud gaming subscriber penetration trajectories across Texas and Florida metropolitan markets.
The model holds under stable esports infrastructure investment and intact USMCA supply chain access; deviation in Chinese rare earth export quotas or California extended producer responsibility enforcement stringency would shift peripheral cost structures. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Consumer Electronics
Digital Writing Instruments Market
Consumer Electronics
Smart TV Sticks Market
Consumer Electronics
Tattoo Stencil Printer Market
Consumer Electronics
Chromebook Market
Consumer Electronics
IoT in Consumer Electronics Market
Consumer Electronics
Russia Gaming Gadgets Market
Consumer Electronics
North America Refurbished and Used Mobile Phones Market
Consumer Electronics
Portable Stick Market
Consumer Electronics
Computing Mouse Market
Consumer Electronics
United States Soundbar Market
Consumer Electronics
Asia-Pacific Mobile Phone Accessories Market
Consumer Electronics
Air Tube Headset Market
Consumer Electronics
Consumer Electronics Electric Motor Market
Consumer Electronics
Sports Electronics Market
Consumer Electronics
Middle East and Africa Refurbished and Used Mobile Phones Market
Consumer Electronics
Gaming Phone Market