
 Smart TV Market | 2026-2036
Smart TV Market Size, Share, and Industry Trends Forecast 2026-2036
Smart TV Market Analysis
Platform licensing revenue is rewriting profit allocation across the Smart TV value chain. Samsung Electronics leverages its Tizen operating system to capture recurring content distribution fees. TCL Corporation anchors its expansion through cost-efficient QLED manufacturing at massive scale. Hisense competes aggressively on price while building proprietary VIDAA platform stickiness.
A Smart TV integrates a television receiver with internet connectivity, embedded processor, and an operating system capable of running applications, streaming protocols, and voice recognition with typical resolutions spanning 4K UHD at 3840×2160 pixels. Its primary commercial purpose is to merge broadcast content with over-the-top streaming services, interactive advertising, and smart home control interfaces. OLED panels command the highest margin pools due to self-emissive pixel technology and premium positioning, while LED remains the volume backbone for emerging-market penetration. The residential end-user segment dominates unit shipments, though hospitality represents the fastest-growing deployment category as hotel chains standardize on cast-enabled, centrally managed displays.
The FCC regulates electromagnetic emissions and broadband device certification in the United States, while the EU Ecodesign Directive and CE marking framework enforce energy efficiency and interoperability standards across European markets. China's MIIT and GB standards govern wireless transmission protocols and cybersecurity requirements for connected display devices. Stakeholders must monitor how fragmented streaming service bundling and evolving data privacy mandates reshape both hardware specifications and recurring revenue architectures.
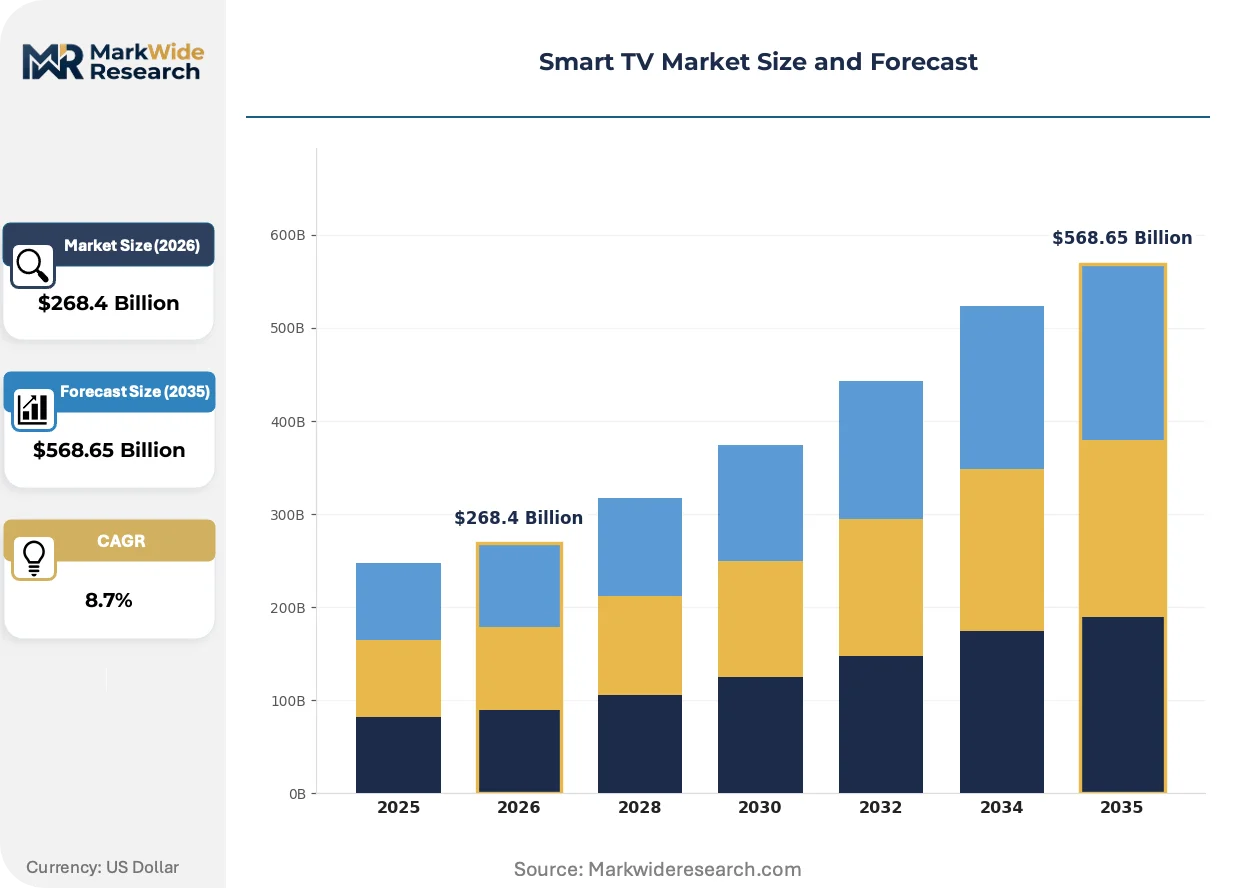
Market Dynamics
Platform economics are restructuring profit capture in Smart TV manufacturing, shifting margin pools from hardware assembly toward recurring content licensing and advertising inventory management.
Growth Catalysts
- Broadband Infrastructure Expansion:India's TRAI-mandated fiber deployment targets and PLI scheme incentives for local display manufacturing are accelerating household upgrade cycles from basic LED to connected panels.
- Hospitality Standardization:Global hotel chains are mandating cast-enabled, centrally managed displays as a guest retention tool, creating a pull-through market for enterprise-grade Smart TV procurement.
- EU Ecodesign Directive:Tightening standby power limits for networked displays are forcing efficiency improvements that simultaneously reduce operating costs and enable premium positioning.
Market Restraints
- Panel Supply Concentration:OLED substrate production concentrates in South Korean and Taiwanese fabs, creating vulnerability to single-source disruption and input cost volatility.
- Operating System Fragmentation:Proprietary platforms (Tizen, VIDAA, webOS) create developer friction and content licensing complexity that slows application ecosystem maturation.
- Silicon Supply Constraints:Advanced SoC fabrication for 4K/8K processing remains concentrated at TSMC and Samsung Foundry, limiting volume scaling for mid-tier manufacturers.
Strategic Opportunities
- Rural India Penetration:Underpenetrated secondary cities and rural districts present white-space demand as Jio and Airtel expand affordable fiber-to-the-home coverage.
- Smart Home Integration:Convergence between Smart TV interfaces and Matter protocol standards creates hub positioning for controlling lighting, climate, and security systems.
- Refurbishment Channels:Certified pre-owned programs and trade-in platforms offer new revenue streams while addressing sustainability compliance under EU CSRD disclosure requirements.
Industry Challenges
- Content Licensing Complexity:Fragmented streaming rights across geographic territories force manufacturers to negotiate territory-by-territory distribution agreements.
- Cybersecurity Certification Burden:China's GB standards and EU cybersecurity labeling requirements impose testing timelines that delay product launches by 4-6 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart TV Market |
| Market Size in 2026 | $268.4 Billion |
| Market Size in 2035 | $568.65 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: 4K UHD, OLED, QLED, LED Technology: Smart Operating System, Voice Control, Streaming Capability, Wireless Connectivity Screen Size: 32 inch, 43 inch, 55 inch, 65 inch End User: Residential, Commercial, Educational, Hospitality |
| Companies Covered | Hisense, Xiaomi, Samsung Electronics, Roku, Vizio, TCL Corporation, Sony, Amazon, LG Electronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart TV Market Emerging Trajectories
Display technology evolution is compressing replacement cycles while regulatory pressure on energy consumption and data governance reshapes hardware specifications and business model architecture.
MicroLED backlighting is digitizing zone-based dimming control with precision that matches OLED contrast performance at LED cost structures. Samsung and TCL are integrating this technology into premium 75-inch-plus panels for residential cinema installations. The shift is digitizing how manufacturers segment premium tiers, collapsing the historical price gap between QLED and entry OLED.
The EU Ecodesign Directive's 2023 standby power amendments are forcing redesign of always-on voice recognition circuits and network maintenance functions. Manufacturers must now implement hardware-off states that sever cloud connectivity, complicating smart assistant integration. European market SKUs are diverging from global templates as brands optimize for compliance rather than feature parity.
Enterprise procurement through hospitality and healthcare channels is consolidating around five-year total-cost-of-ownership contracts that bundle hardware, content licensing, and remote management. Marriott International and IHG are negotiating directly with manufacturers, bypassing traditional AV integrators. This channel compression is most visible in North American and Western European commercial deployments where standardization reduces in-room support burden.
Smart TV Market Segmentation
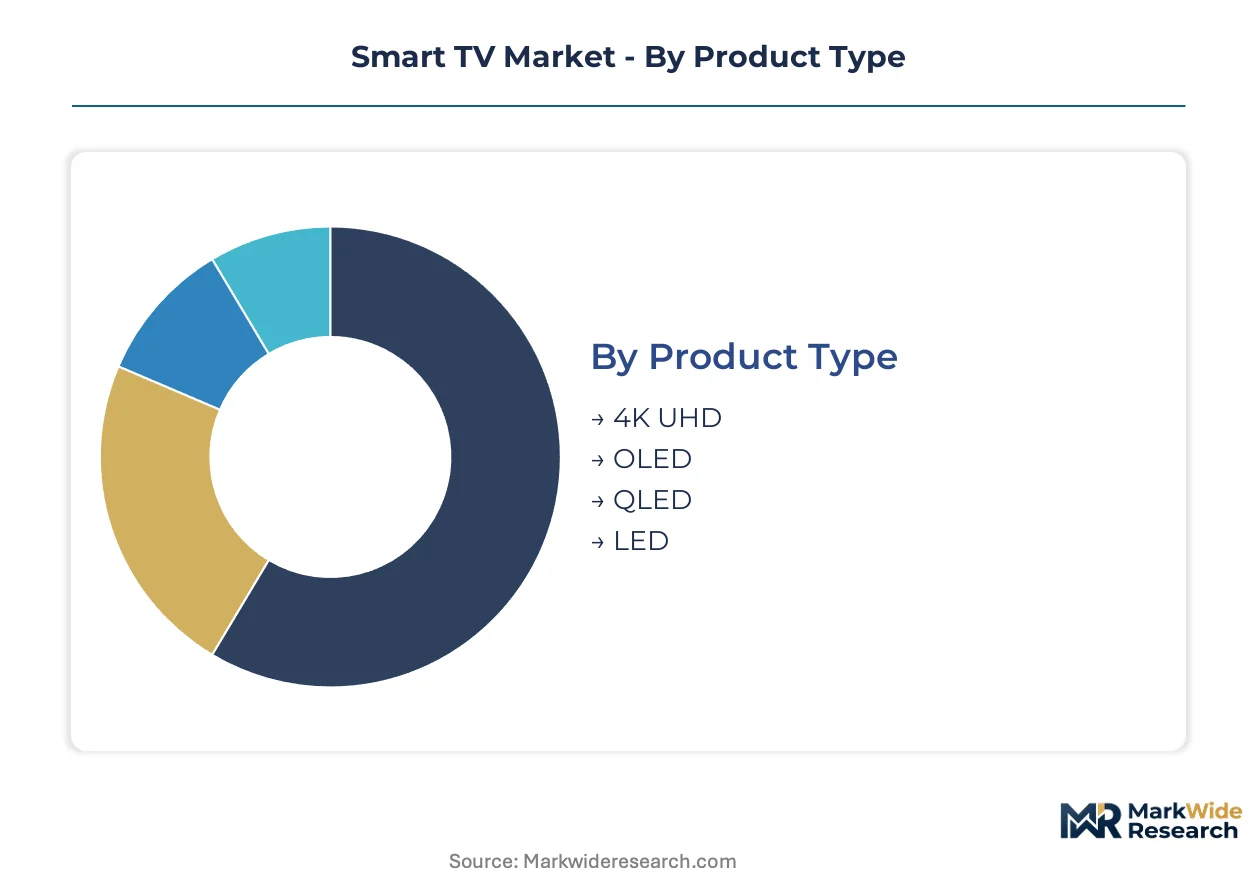
Smart TV segmentation reveals how display technology, interface architecture, and deployment context fragment profit pools across the value chain. Manufacturers optimize SKU portfolios around resolution tiers, operating system ecosystems, and enterprise procurement patterns that reshape margin capture and replacement cycle timing.
Product Type:
The use-case spectrum spans cinema-grade home entertainment to cost-conscious emerging-market penetration, with panel chemistry determining both manufacturing complexity and pricing architecture.
- 4K UHD:Resolution standard at 3840×2160 pixels now dominates mainstream residential replacement cycles across India and Southeast Asia. TRAI-mandated fiber expansion in Indian secondary cities accelerates household upgrades from HD to connected 4K panels.
- OLED:Self-emissive pixel technology eliminates backlighting layers, enabling infinite contrast ratios and sub-3mm panel thickness. Premium residential installations and boutique hospitality deployments absorb the highest manufacturing yields from South Korean fabs.
- QLED:Quantum dot enhancement layers expand color gamut coverage while preserving LED cost structures. TCL's captive manufacturing at massive scale anchors mid-premium positioning between entry LED and flagship OLED.
- LED:Edge-lit and direct-lit configurations remain the volume backbone for rural India and price-sensitive commercial procurement.
The dominant share belongs to 4K UHD, while OLED is closing the gap fastest.
Technology:
Interface sophistication separates premium positioning from commodity hardware, with voice recognition and streaming protocol support now baseline expectations rather than differentiators.
- Smart Operating System:Tizen, VIDAA, webOS, and Android TV fragment developer resources and content licensing negotiations. Samsung's Tizen ecosystem captures recurring distribution fees from streaming partners, shifting margin pools from assembly to platform economics.
- Voice Control:Far-field microphone arrays and natural language processing enable hands-free content search and smart home command integration. EU Ecodesign Directive amendments forcing hardware-off standby states complicate always-on voice recognition circuit design.
- Streaming Capability:Native application support for Netflix, Disney+, and regional platforms eliminates external device dependencies. Hospitality chains mandate cast-enabled, centrally managed streaming as a guest retention standard.
- Wireless Connectivity:Wi-Fi 6E and Bluetooth 5.2 protocols support multi-device screen mirroring and peripheral pairing.
Smart Operating System anchors manufacturer profitability, with Voice Control expanding most quickly as smart home integration deepens.
Screen Size:
Residential room dimensions and commercial installation constraints segment demand into distinct volume tiers with diverging supply chain economics.
- 32 inch:Compact form factor dominates secondary bedroom installations and budget hospitality procurement in India. Local PLI scheme incentives reduce import dependency for sub-40-inch panel assembly.
- 43 inch:Living room standard for emerging-market apartments balances viewing distance with furniture integration. Indian e-commerce festivals and EMI financing options concentrate upgrade demand in this tier.
- 55 inch:Premium residential threshold where 4K resolution benefits become perceptible at typical seating distances. MicroLED backlighting integration first penetrates at this size class before scaling to larger formats.
- 65 inch:Cinema-room and luxury hospitality installations drive the steepest expansion trajectory as panel yields improve and freight economics normalize.
43 inch maintains volume leadership, while 65 inch gains share fastest in North American and Western European premium segments.
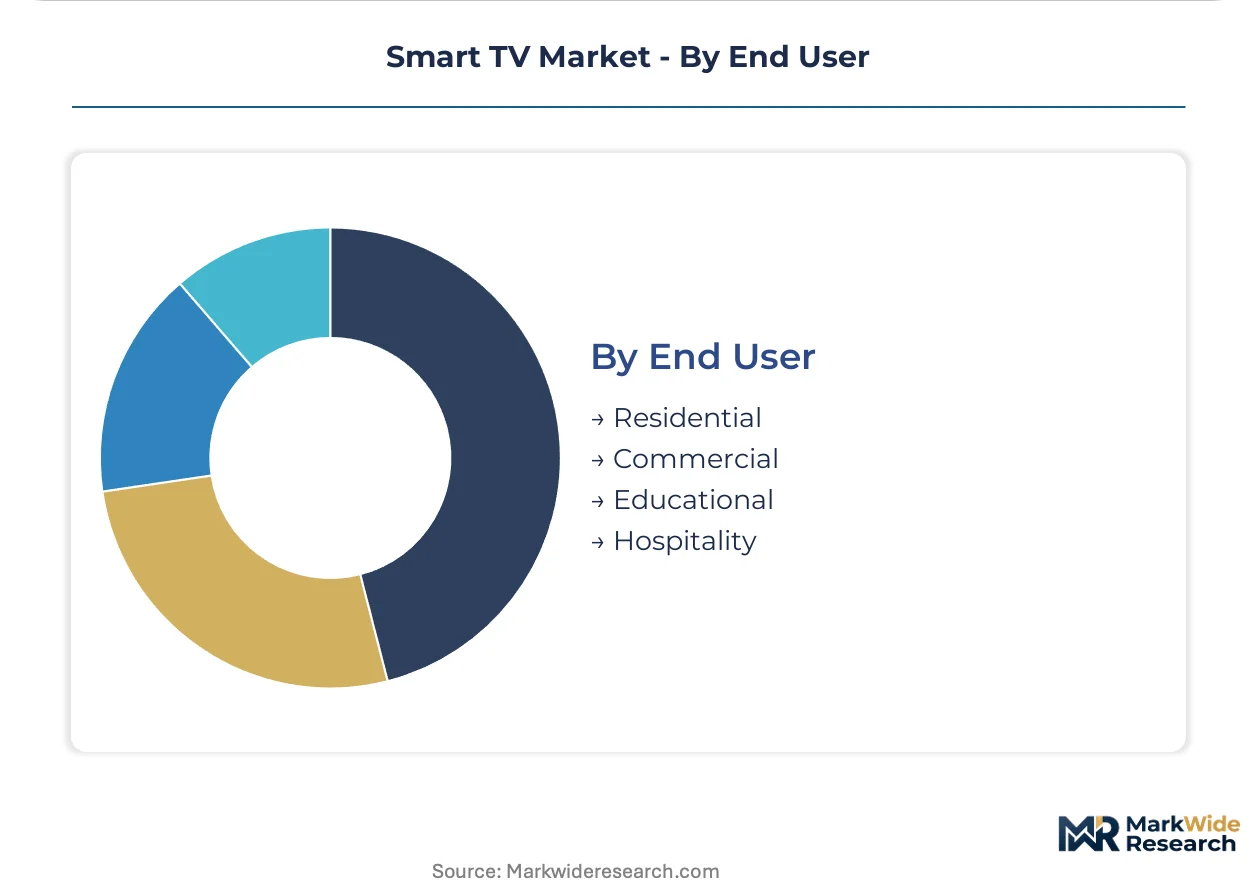
End User:
Procurement authority and total-cost-of-ownership calculation methods diverge sharply between individual consumers and institutional buyers.
- Residential:Individual purchase decisions prioritize content ecosystem breadth, voice assistant compatibility, and aesthetic integration. Replacement cycles compress as streaming service bundling and gaming console upgrades drive panel turnover.
- Commercial:Corporate meeting room and digital signage deployments emphasize remote manageability and extended warranty terms. Five-year TCO contracts bundle hardware, content licensing, and support services.
- Educational:K-12 and university procurement standardizes on interactive whiteboard integration and device management platforms. Bulk purchasing consortia extract volume discounts from manufacturers.
- Hospitality:Marriott International and IHG negotiate directly with manufacturers for cast-enabled, centrally managed displays. This channel is climbing the fastest as hotel chains standardize in-room entertainment as a guest retention tool.
Residential commands absolute volume, though Hospitality demonstrates the steepest growth curve as enterprise procurement consolidates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indian households demonstrate extreme price elasticity, driving volume through sub-$300 43-inch LED panels, while German and Japanese buyers absorb 65-inch OLED premiums with minimal demand contraction. This divergence shapes manufacturing allocation and platform licensing strategies across regional supply chains.
United States
Enterprise procurement through Marriott International and IHG dominates commercial volume, with cast-enabled hospitality displays replacing traditional AV integrator channels. FCC broadband device certification governs Wi-Fi 6E implementation in connected panels. Manufacturing concentration clusters in Mexico's Baja California assembly plants serving North American fulfillment.
China
Domestic absorption of 55-inch and 65-inch QLED panels drives replacement cycles as urban households upgrade from first-generation smart displays. MIIT GB standards enforce cybersecurity testing timelines that delay product launches by 4-6 months. Yangtze River Delta fabrication hubs in Suzhou and Hefei concentrate quantum dot film deposition capacity.
India
Jio and Airtel fiber-to-the-home expansion in secondary cities accelerates household upgrades from basic LED to connected 4K panels. TRAI-mandated infrastructure targets and PLI scheme incentives for local display assembly reduce import dependency. Manufacturing investment concentrates in Noida and Sri City special economic zones for sub-43-inch panel SKUs.
Germany
EU Ecodesign Directive standby power amendments force hardware-off circuit redesigns that sever always-on cloud connectivity. CE marking frameworks and CSRD sustainability disclosure requirements shape procurement criteria for commercial installations. Industrial R&D clusters in Dresden and Munich drive MicroLED backlighting development for premium residential cinema segments.
South Korea
OLED substrate production from Samsung Display and LG Display fabs supplies premium tiers globally, creating single-source vulnerability to disruption. KCC certification governs electromagnetic emissions for domestic market deployment. Gumi and Paju industrial complexes anchor self-emissive pixel manufacturing yields for 55-inch and larger formats.
Smart TV Market Vendor Landscape
Platform-integrated conglomerates and display-specialist assemblers split the market along vertical control lines. Samsung Electronics and LG Electronics anchor the consolidated tier through captive OLED fabrication and proprietary operating systems, while TCL Corporation and Hisense occupy the scale-driven mid-tier through cost-efficient quantum dot manufacturing. Competitive maneuvering concentrates on backward integration into panel supply and content licensing fee capture rather than hardware differentiation alone.
Within the platform-integrated tier, Samsung Electronics exemplifies operating system economics through Tizen licensing revenue, while LG Electronics occupies a comparable position through webOS ecosystem control. TCL Corporation anchors the scale-specialist archetype through massive QLED manufacturing. Hisense represents aggressive price-positioning combined with proprietary VIDAA platform development. These three companies collectively illustrate how profit pools migrate from assembly toward recurring content distribution fees.
| Leading Market Players |
|---|
| Hisense |
| Xiaomi |
| Samsung Electronics |
| Roku |
| Vizio |
| TCL Corporation |
| Sony |
| Amazon |
| LG Electronics |
| Others |
Supply Flow & Price Mechanics
South Korean OLED substrate production from Samsung Display and LG Display fabs concentrates premium panel supply, anchoring margin capture at the display technology tier while compressing assembly margins for downstream brands. This upstream concentration forces manufacturers to differentiate through platform licensing fees and content distribution revenue rather than hardware premiums alone.
Pricing Analysis
After-sales revenue from extended content licensing agreements and advertising inventory management drives lifetime value beyond the initial hardware transaction. Three-tier pricing structure across premium OLED, standard QLED, and economy LED levels segments buyer archetypes, with Indian residential consumers demonstrating extreme price elasticity at sub-$300 entry points while German buyers absorb 65-inch OLED premiums with minimal demand contraction. Cost compression in the mid-tier QLED segment is intensifying because TCL's massive manufacturing scale enables aggressive positioning. Hospitality procurement demonstrates the least price sensitivity due to five-year total-cost-of-ownership contract structures.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk calculations for North American fulfillment. Panel fabrication concentrates in South Korea, Taiwan, and China, with advanced SoC processing for 4K/8K video tethered to TSMC and Samsung Foundry capacity. Quantum dot film deposition and OLED substrate production represent critical input dependencies vulnerable to single-source disruption. Distribution runs through Mexico's Baja California assembly plants for North American markets, with Noida and Sri City special economic zones capturing Indian domestic assembly.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
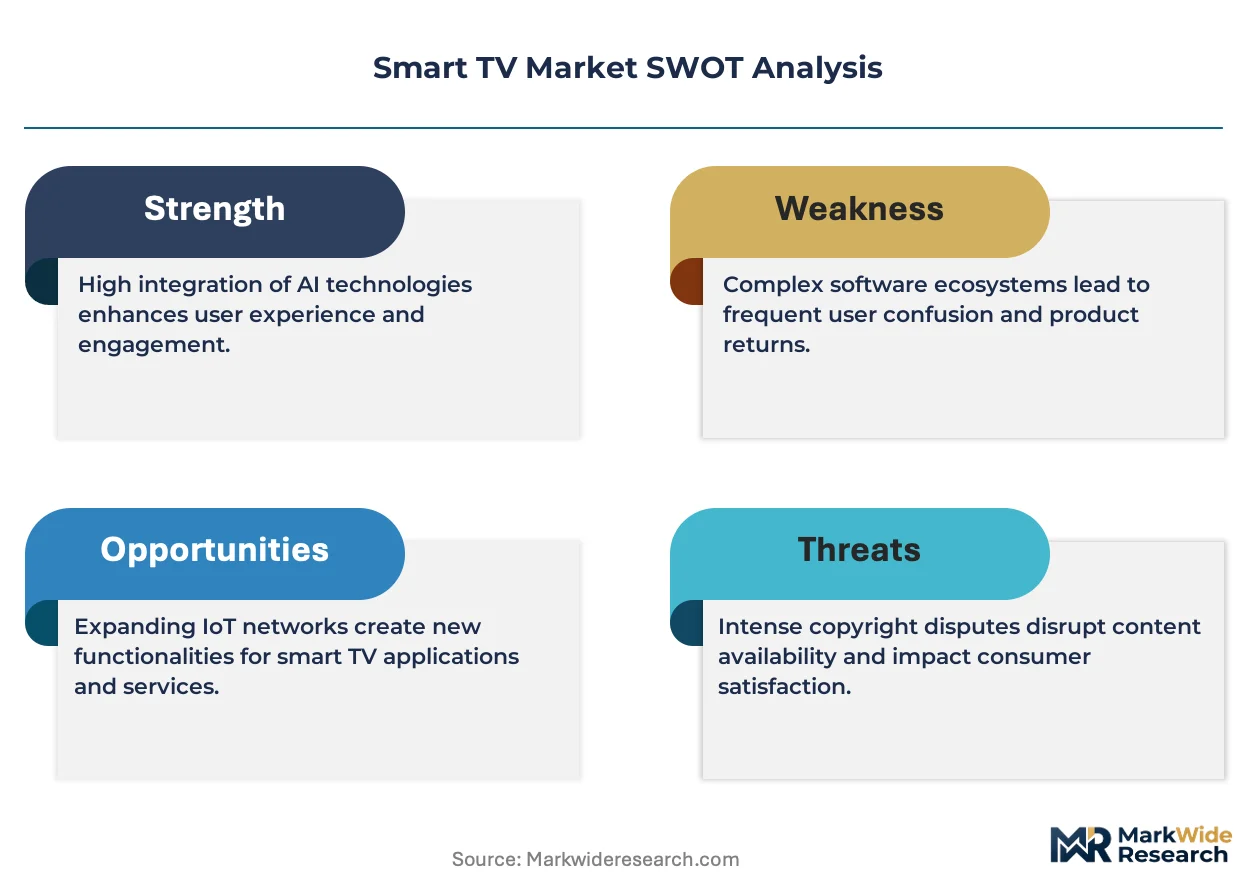
Profit migration toward platform economics and content licensing has created acute scarcity in operating system development expertise and streaming partnership negotiation capability, favoring conglomerates with captive software ecosystems over pure hardware assemblers.
For Market Incumbents: Harden defensive positioning by deepening backward integration into OLED substrate production and expanding proprietary platform stickiness through exclusive content distribution agreements. The threat of MicroLED backlighting cost convergence demands accelerated R&D investment in self-emissive pixel architectures. Channel control through direct hospitality procurement relationships with Marriott International and IHG represents the priority lever for margin defense. For New Entrants and Emerging Players: Rural Indian districts with underpenetrated fiber-to-the-home infrastructure present the most penetrable white-space target for cost-efficient LED volume deployment. Secondary cities in Southeast Asia offer comparable expansion corridors as broadband infrastructure matures. A go-to-market angle anchored to local PLI scheme manufacturing incentives and EMI financing partnerships enables competitive positioning without direct confrontation with established platform ecosystems. For Investors and Strategic Acquirers: Capital is best deployed toward display-specialist assemblers with proven quantum dot manufacturing scale and emerging proprietary operating system development. Long-term viability across the projection horizon rests on backward integration depth and content licensing revenue diversification. The signal to monitor is consolidation in hospitality procurement channels, where direct manufacturer negotiations displace traditional AV integrators and reshape volume allocation.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Ecosystem Expansion | Tizen and VIDAA licensing revenue shifts margin pools from hardware assembly toward recurring content distribution. |
| Backward Integration into Panel Supply | Captive OLED substrate production reduces single-source vulnerability to South Korean fab disruption. |
| Hospitality Direct Procurement | Marriott International and IHG negotiations compress channel margins while securing five-year TCO contracts. |
| MicroLED Backlighting Scale-Up | Samsung and TCL integration into 75-inch-plus panels collapses historical price gaps with entry OLED. |
| Rural India Distribution Buildout | Jio and Airtel fiber expansion enables household upgrade cycles from basic LED to connected 4K panels. |
Methodological Framework
Operator-level perspectives from display technology procurement managers, hospitality IT directors, streaming platform partnership leads, and semiconductor supply planners anchored the qualitative base. Primary interviews combined with secondary validation from SEC filings, customs and trade data, FCC certification databases, and EU Ecodesign Directive regulatory filings. Bottom-up unit shipment modeling and top-down value chain triangulation cross-verified segment-level estimates.
Scenario-bracketing around broadband infrastructure deployment pace, panel yield improvements, and regulatory compliance timelines structured the analytical framework across the projection horizon. Segmentation dimensions modeled include display technology tier, operating system ecosystem, screen size class, and end-user procurement archetype. CAGRs derived from replacement cycle compression analysis, hospitality standardization adoption curves, and emerging-market household penetration trajectories. Industry-specific inputs incorporated TRAI-mandated fiber targets, PLI scheme incentive structures, and EU standby power amendment compliance costs.
Macroeconomic conditions sit as an overlay; deviation in consumer discretionary spending, semiconductor capital expenditure cycles, or cross-border tariff regimes would shift the trajectory. Forecasts reflect documented assumptions regarding panel supply concentration persistence and streaming service bundling evolution. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Consumer Electronics
Waterproof Headphones Market
Consumer Electronics
Vape Market
Consumer Electronics
Asia-Pacific Refurbished and Used Mobile Phones Market
Consumer Electronics
Soft Support Products Market
Consumer Electronics
Wireless Speakers Market
Consumer Electronics
China Massage Equipment Market
Consumer Electronics
China Refurbished Smartphone Market
Consumer Electronics
Smart Television and Set-Top Box Market
Consumer Electronics
Mobile Cases and Covers Market
Consumer Electronics
Global Laptop Skins Market
Consumer Electronics
Smart Mirror Market
Consumer Electronics
Consumer Electronics Electric Motor Market
Consumer Electronics
Portable Smart Speaker Market
Consumer Electronics
Global Tablet Keyboards Market
Consumer Electronics
TV Mirror Market
Consumer Electronics
Europe Cigarette Lighter Market