
 4K Television Market | 2026-2036
4K Television Market Size, Share, and Industry Trends Forecast 2026-2036
4K Television Market Analysis
The capital-intensity divergence between in-house panel producers and assembly-dependent brands is bifurcating competitive tiers in the 4K television industry. Samsung Electronics leverages captive OLED and QD-OLED fabrication to command premium positioning. TCL Technology anchors volume competitiveness through vertical control over LCD and Mini LED supply chains.
A 4K television delivers a display resolution of 3840 × 2160 pixels, four times the pixel density of Full HD, enabling sharper image reproduction for streaming, gaming, and broadcast content. Smart TV functionality has become the default integration layer, with operating systems enabling app ecosystems and voice control. OLED TV panels capture the premium margin pool due to self-emissive pixel architecture and superior contrast ratios, while QLED TV variants sustain growth in the mid-to-premium tier through quantum dot color enhancement at lower manufacturing cost.
The FCC in the United States mandates ATSC 3.0 broadcast compatibility, which accelerates 4K-capable tuner adoption in North American sets. The EU Ecodesign Directive and Energy Labeling Framework constrain standby power and peak brightness efficiency, shaping panel selection and backlight architecture. China's GB standards and MIIT certification requirements enforce electromagnetic compatibility and energy consumption thresholds for domestic sale. Stakeholders must monitor how broadcast infrastructure rollouts and streaming codec licensing reshape hardware refresh cycles.
Market Dynamics
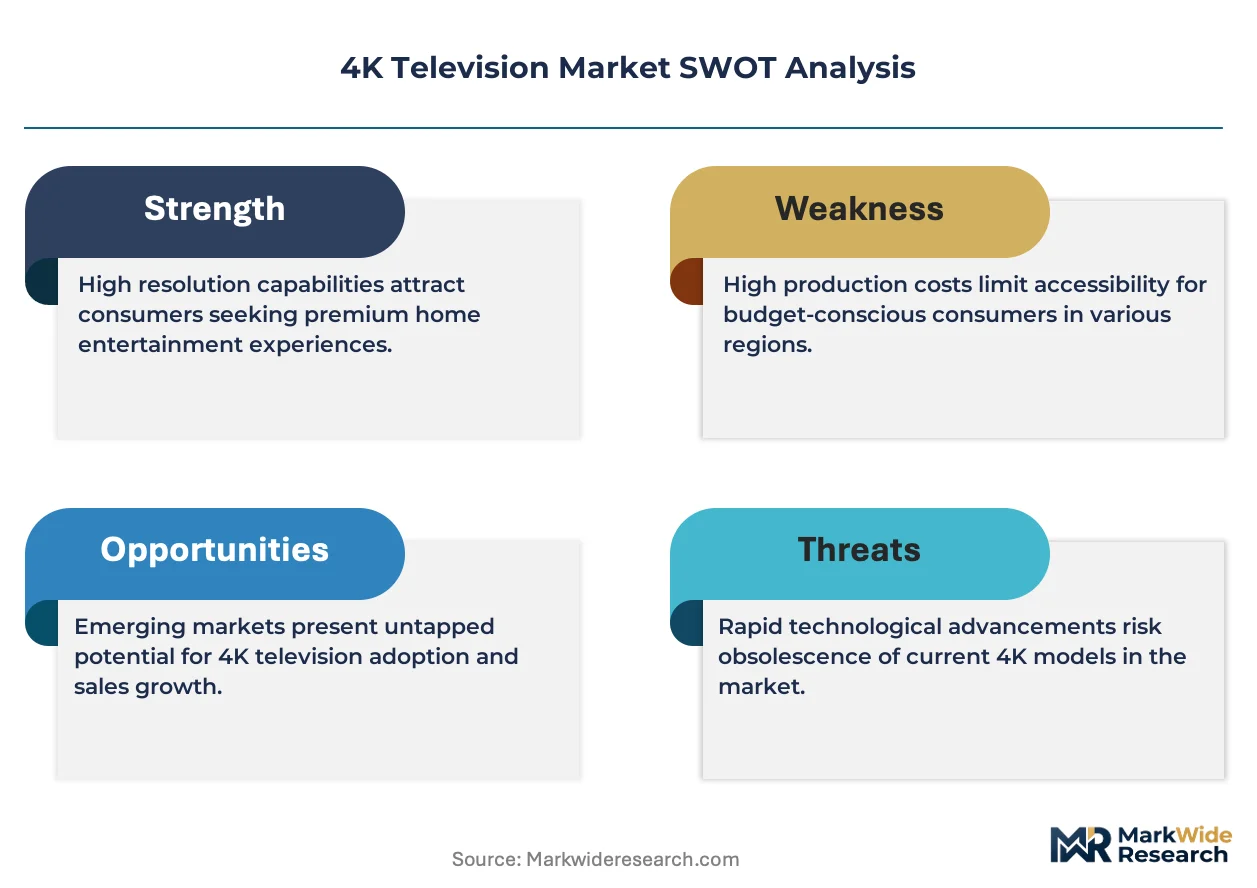
The transition from LCD to self-emissive display technologies is compressing refresh cycles and fragmenting procurement patterns across residential, hospitality, and commercial verticals.
Growth Catalysts
- ATSC 3.0 Mandate:The FCC's broadcast standard compels North American manufacturers to integrate 4K-capable tuners, forcing hardware upgrades across the installed base.
- Hospitality Upgrades:Dubai and Singapore hotel chains are standardizing guest room displays to 4K specifications, creating concentrated procurement volumes in premium segments.
- Energy-Efficient Backlighting:China's dual carbon goals accelerate Mini LED adoption, rewarding manufacturers with lower power consumption profiles and preferential domestic certification pathways.
Market Restraints
- Panel Supply Concentration:Captive OLED fabrication capacity concentrates among Korean and Japanese producers, constraining independent brands to LCD and Mini LED alternatives.
- Raw Material Volatility:Quantum dot phosphor and indium tin oxide prices fluctuate with rare earth processing constraints, compressing margin predictability for QLED variants.
- Technical Limitation:Burn-in susceptibility on self-emissive panels limits commercial deployment in static-content environments like airport signage and menu boards.
Strategic Opportunities
- Rural India Penetration:Underpenetrated tier-3 and tier-4 cities present white space as electrification expands and middle-class consumers trade up from HD sets.
- Gaming-Optimized Displays:120Hz variable refresh rate panels with HDMI 2.1 convergence capture premium positioning among console and PC gaming segments.
- EU Ecodesign Tailwind:The Energy Labeling Framework's efficiency tiers create competitive differentiation for manufacturers achieving A-grade standby power ratings.
Industry Challenges
- Display Engineer Scarcity:Shortage of professionals skilled in quantum dot inkjet printing and Micro LED mass transfer techniques delays production scale-up.
- Certification Timeline Compression:Simultaneous MIIT electromagnetic compatibility and GB energy consumption approvals in China extend product launch windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 4K Television Market |
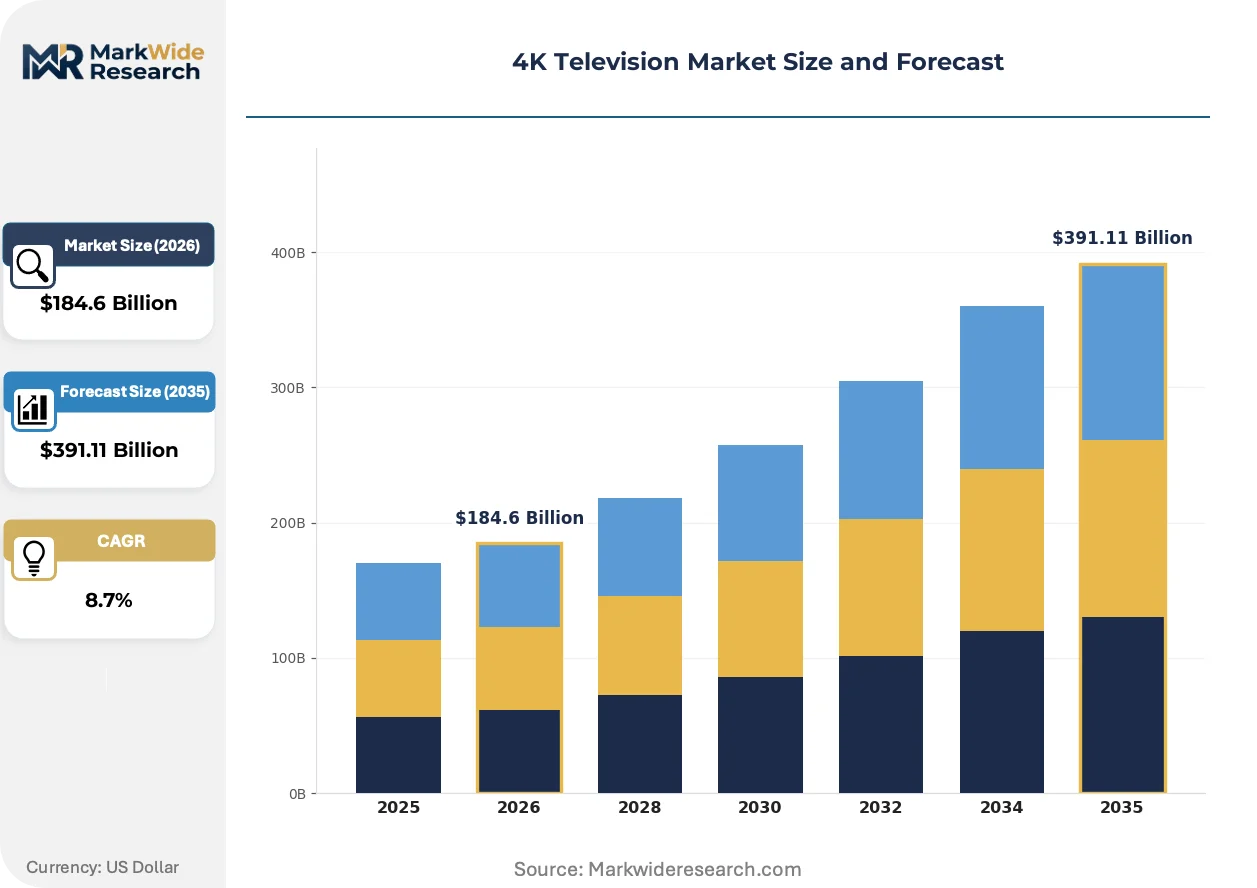
| Market Size in 2026 | $184.6 Billion |
| Market Size in 2035 | $391.11 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart TV, UHD TV, OLED TV, QLED TV Display Technology: LED, LCD, Mini LED, Micro LED Screen Size: 55 Inch, 65 Inch, 75 Inch, 85 Inch Price Tier: Budget, Mid-range, Premium, Ultra-Premium |
| Companies Covered | Samsung Electronics, LG Electronics, Sony Corporation, TCL Technology, Hisense, Panasonic Corporation, Sharp Corporation, VIZIO, Skyworth Digital Holdings, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
4K Television Market Emerging Trajectories
Display architecture is splitting into two performance tiers as manufacturing capabilities diverge and end-use requirements sharpen. This fragmentation reshapes competitive positioning across consumer and commercial segments.
Mini LED backlighting is bifurcating the premium LCD segment from conventional edge-lit designs. Hospitality chains in Singapore and Dubai specify full-array local dimming for guest room installations. The technology is bifurcating procurement patterns between cost-optimized volume plays and specification-driven premium tenders.
REACH substance restrictions and RoHS amendments in Europe constrain heavy metal content in quantum dot formulations. Manufacturers reformulate cadmium-free phosphor chemistries to maintain market access. Premium QLED lines face compliance-driven cost inflation while competing against OLED alternatives exempt from parallel material constraints.
Streaming service bundling is compressing replacement cycles as Netflix, Disney+, and regional platforms mandate 4K HDR compatibility for full feature access. Indian urban retailers report accelerated trade-in activity as consumers prioritize app ecosystem integration over panel longevity. This behavior concentrates demand in 55-inch and 65-inch form factors where living room viewing distances optimize perceived resolution gains.
4K Television Market Segmentation
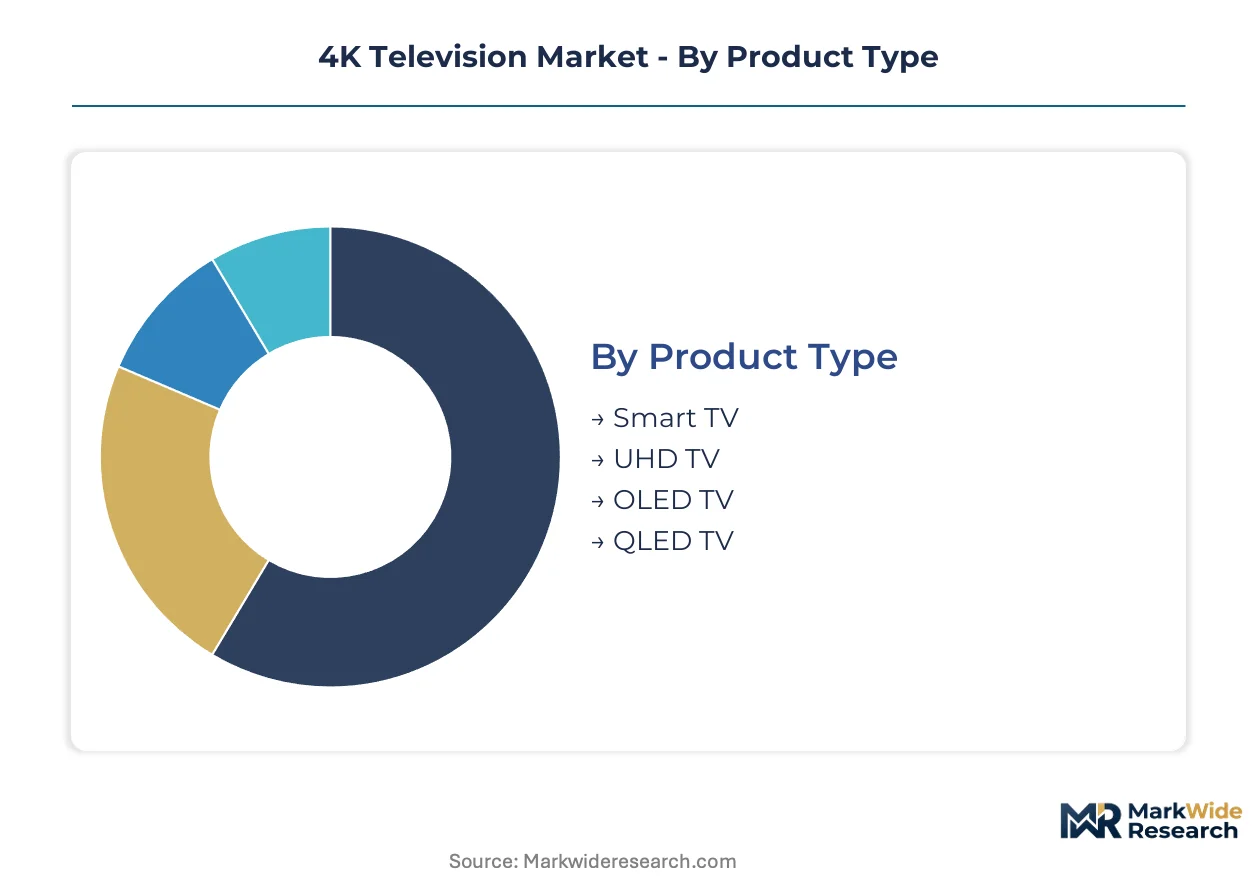
4K television segmentation reveals how procurement patterns fragment across residential, hospitality, and commercial verticals. Manufacturers configure product lines around display architecture, screen geometry, and price positioning to capture distinct margin pools.
Product Type:
Domestic consumption in China and India drives volume for integrated smart platforms, while export-led demand from Dubai and Singapore hospitality chains concentrates in specification-heavy display categories.
- OLED TV:Self-emissive pixel architecture eliminates backlight layers, enabling infinite contrast ratios and sub-millimeter panel thickness. Dubai hotel chains specify OLED for luxury suites where image quality commands rate premiums. Burn-in susceptibility limits airport and retail signage deployment.
- QLED TV:Quantum dot color enhancement layers boost color gamut coverage without self-emissive panel costs. Samsung Electronics leverages captive QD-OLED fabrication to defend premium positioning against LCD alternatives. REACH substance restrictions in Europe force cadmium-free phosphor reformulation, inflating compliance costs.
- Smart TV:Integrated operating systems enable streaming app ecosystems and voice control as default functionality.
- UHD TV:Basic 4K resolution panels without advanced smart features serve price-sensitive replacement demand in India's tier-3 cities.
OLED TV holds the largest share; momentum sits with QLED TV as manufacturers balance performance against fabrication constraints.
Display Technology:
Cost tier fragmentation separates edge-lit volume plays from full-array local dimming tenders in premium hospitality procurement.
- Mini LED:Dense backlight zones enable precise local dimming with near-OLED contrast at lower manufacturing cost. Singapore hotel chains specify full-array Mini LED for guest room installations requiring 4K HDR compatibility. China's dual carbon goals accelerate adoption through preferential MIIT certification pathways for energy-efficient designs.
- Micro LED:Chip-scale LED bonding eliminates backlight and color filter layers, enabling modular scalability beyond conventional panel sizes. Display engineer scarcity in quantum dot inkjet printing and mass transfer techniques delays production scale-up for consumer price points.
- LED:Edge-lit and direct-lit configurations dominate budget tier production for emerging market volume.
- LCD:Conventional liquid crystal panels with quantum dot enhancement sustain mid-range competitiveness through TCL's vertical supply chain control.
LCD holds the largest share; Micro LED is climbing the fastest despite manufacturing bottlenecks.
Screen Size:
Application-driven geometry splits between living room viewing distances and commercial installation requirements.
- 65 Inch:The form factor optimizes perceived resolution gains at typical living room distances of 2.5 to 3 meters. Indian urban retailers report accelerated trade-in activity concentrated in this size bracket as middle-class consumers prioritize app ecosystem integration.
- 55 Inch:Compact geometry suits apartment dwellers in dense Asian cities where space constraints limit display dimensions. Streaming service bundling compresses replacement cycles as Netflix and Disney+ mandate 4K HDR compatibility for full feature access.
- 75 Inch:Large-format panels capture home theater installations in suburban US and Australian markets.
- 85 Inch:Extra-large displays serve commercial conferencing and luxury residential segments where wall space permits immersive scaling.
65 Inch holds the largest share; 75 Inch is gaining share fastest on home theater demand.
Price Tier:
Customer type stratification aligns procurement authority with specification requirements across retail, hospitality, and institutional channels.
- Premium:Full-array local dimming, 120Hz variable refresh rates, and HDMI 2.1 convergence target gaming-optimized positioning. Console and PC gaming segments in South Korea and Japan drive specification requirements that cascade into global product planning.
- Mid-range:Quantum dot enhancement without local dimming captures trade-up demand from HD sets in India's tier-2 cities. Electrification expansion and rising disposable income create white space as consumers prioritize screen size over advanced features.
- Budget:Basic 4K resolution without smart functionality serves price-sensitive replacement cycles in underpenetrated rural markets.
- Ultra-Premium:Self-emissive OLED and Micro LED prototypes command flagship positioning for early adopters and luxury hospitality specification.
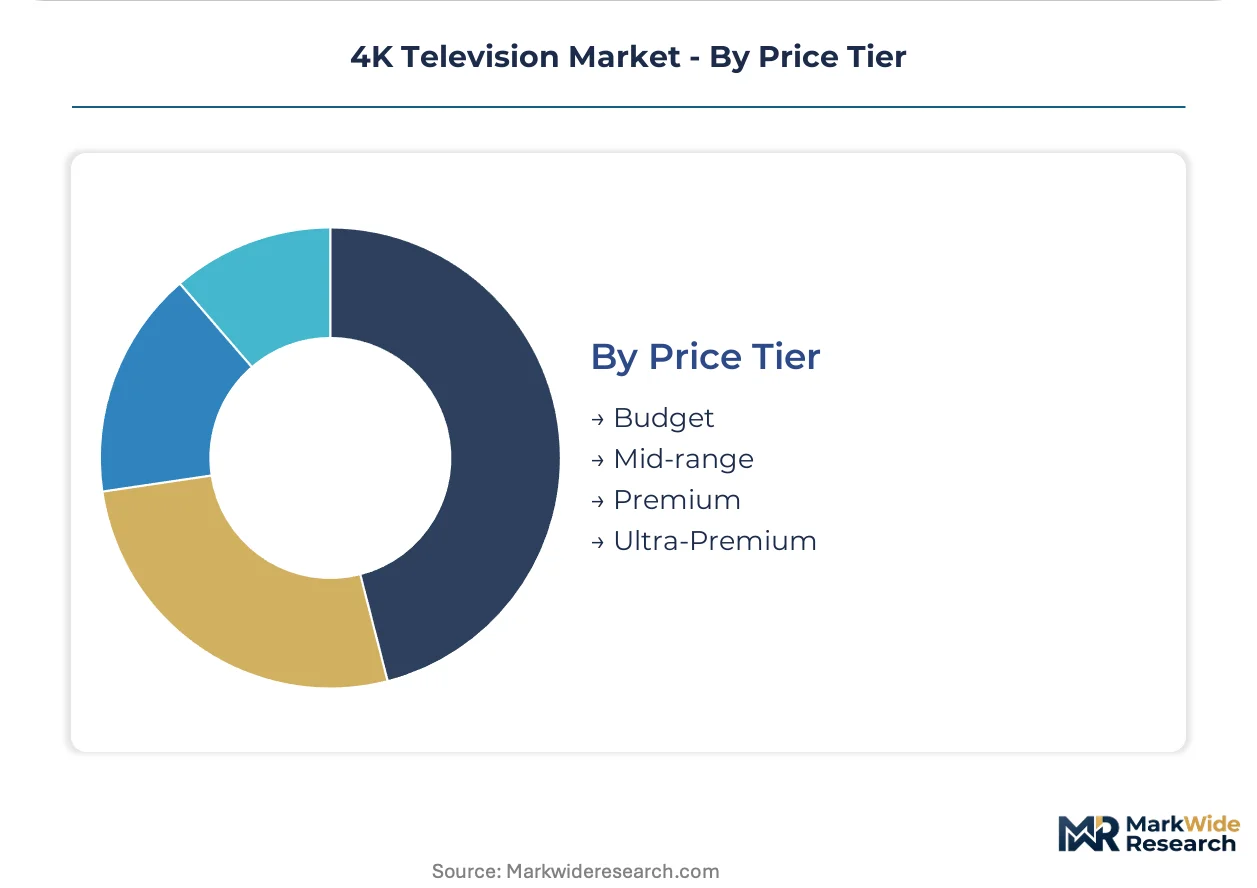
Mid-range holds the largest share; Premium is expanding most quickly on gaming and streaming convergence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in display panels tilt heavily toward East Asian fabrication hubs, with finished set assembly dispersing to regional consumption centers. Import dependency for OLED substrates concentrates procurement leverage among Korean and Japanese suppliers, while Chinese vertical integration over LCD and Mini LED components reshapes export competitiveness.
China
Domestic absorption of 4K panels exceeds external shipments as urban households complete HD-to-4K replacement cycles. MIIT certification pathways for energy-efficient designs align with dual carbon goals, accelerating Mini LED adoption in premium domestic lines. The Yangtze River Delta cluster around Suzhou and Hefei anchors captive LCD and emerging OLED fabrication capacity.
United States
ATSC 3.0 tuner mandates compress hardware refresh cycles as broadcast infrastructure rolls out in major metropolitan markets. The FCC's spectrum reallocation policies shape tuner module procurement specifications for North American-bound sets. Assembly operations in Mexico's Baja California and Chihuahua feed US retail channels with tariff-advantaged finished goods.
South Korea
OLED panel exports sustain fabrication margins despite LCD price erosion in commodity segments. METI-equivalent industrial policy supports QD-OLED process development through targeted R&D tax credits. The Gumi and Tangjeong industrial complexes concentrate self-emissive display engineering talent and pilot production lines.
India
Urban retail corridors in Mumbai and Delhi-NCR drive 55-inch and 65-inch form factor demand as middle-class consumers prioritize streaming app integration. BIS certification requirements for electronic goods extend product launch timelines for imported sets. The Sriperumbudur electronics cluster near Chennai attracts CKD assembly investments seeking proximity to Tamil Nadu's consumer base.
Germany
EU Ecodesign Directive efficiency tiers differentiate retail positioning as consumers respond to A-grade energy labeling. REACH substance restrictions constrain quantum dot phosphor formulations in QLED sets bound for European markets. The Munich-Stuttgart corridor concentrates premium retail distribution and commercial hospitality specification authority.
4K Television Market Vendor Landscape
Concentration sits with vertically integrated panel producers who command captive supply of critical display substrates. Korean and Japanese fabricators dominate self-emissive OLED capacity, constraining independent brands to LCD and Mini LED alternatives. Three archetypes define competitive positioning: integrated panel-set producers, assembly-dependent brands, and contract manufacturers serving private label programs. Strategic moves center on backward integration into backlight component production and geographic diversification of final assembly to manage tariff exposure.
Among integrated fabricators, Samsung Electronics and LG Electronics exemplify the captive-panel archetype with in-house OLED and QD-OLED production. TCL Technology occupies a distinct position through upstream control over LCD and Mini LED supply chains, enabling volume competitiveness without self-emissive panel dependency. These three anchors illustrate how fabrication depth determines margin capture across premium and mass-market tiers.
| Leading Market Players |
|---|
| Samsung Electronics |
| LG Electronics |
| Sony Corporation |
| TCL Technology |
| Hisense |
| Panasonic Corporation |
| Sharp Corporation |
| VIZIO |
| Skyworth Digital Holdings |
| Others |
Supply Flow & Price Mechanics
Captive OLED fabrication scale in South Korea and Japan establishes asymmetric cost floors that independent brands cannot match without LCD or Mini LED pivots. This concentration amplifies pricing power for self-emissive panel holders while compressing margins for assembly-dependent competitors sourcing open-cell substrates.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Price differentiation rests on panel architecture grade and MIIT energy certification tier, with A-grade standby ratings commanding retail premiums. Cost compression in budget LCD tiers is intensifying because of quantum dot phosphor volatility and indium tin oxide supply constraints. Hospitality procurement teams in Dubai and Singapore show least price sensitivity, while India's tier-3 retail consumers drive hardest bargain negotiations.
Supply Chain Analysis
Container availability constraints on Busan-to-Long Beach lanes inflate inbound logistics costs for North American-bound finished sets. Panel supply concentrates in South Korea, Japan, and China, with display substrates drawing from rare earth processing facilities in Inner Mongolia and Jiangxi province. Single-source vulnerability sits with Korean OLED substrate monopolists. Distribution runs through Mexico's Baja California assembly hubs for tariff-advantaged US market access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where regulatory entrenchment through FCC ATSC 3.0 mandates and EU Ecodesign tiers creates sticky certification requirements that new entrants cannot rapidly replicate.
For Market Incumbents: Fortify captive panel supply through backward integration into Mini LED backlight component production. Add bonded assembly capacity in Vietnam or Indonesia to diversify tariff exposure beyond Mexico. The threat of Micro LED scale-up by specialized fabricators demands pre-emptive R&D positioning in mass transfer techniques. For New Entrants and Emerging Players: Gaming-optimized display calibration services represent an under-served layer where incumbents cede margin to third-party integrators. White space concentrates in India's tier-3 cities where electrification expands addressable base. A direct-to-installer go-to-market angle bypasses established retail channel gatekeepers. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors vertically integrated panel-set producers with captive OLED or QD-OLED fabrication. Long-term viability across the analysis window hinges on display architecture transition timing. The acquisition target archetype is LCD-to-Mini LED converters with established BIS certification pathways. Watch Micro LED pilot production yield rates as inflection indicator for next-generation displacement risk.| Strategic Initiative | Industry Significance |
|---|---|
| QD-OLED Capacity Expansion | Samsung Electronics' captive fabrication secures premium positioning against LCD alternatives in hospitality procurement. |
| Mini LED Backlight Integration | TCL Technology's upstream control enables volume competitiveness under China's dual carbon certification pathways. |
| Gaming Display Calibration Services | Third-party integrators capture margin from 120Hz VRR specification complexity in South Korean esports venues. |
| BIS Certification Fast-Tracking | CKD assembly investments near Chennai reduce launch timeline friction for India-bound product lines. |
| Cadmium-Free Phosphor Reformulation | REACH compliance investment maintains European market access against OLED alternatives exempt from parallel constraints. |
Methodological Framework
Cross-validation between primary interviews and secondary regulatory filings anchors the qualitative findings. Conversations with display engineering directors, hospitality procurement managers, retail category buyers, and MIIT certification consultants informed supply-side dynamics. Secondary sources include FCC equipment authorization databases, EU Ecodesign implementing measures, BIS electronic goods registration records, and customs trade flow data. Bottom-up panel shipment analysis triangulates against top-down consumer electronics retail audit estimates.
Sensitivity analysis around ATSC 3.0 rollout pace and dual carbon policy enforcement intensity shapes the projection horizon. Segmentation dimensions modeled include display architecture, screen geometry, price positioning, and regional regulatory cluster. CAGRs derive from installed base replacement cycle analysis and streaming service 4K HDR mandate adoption curves. Panel fabrication capacity utilization and quantum dot phosphor pricing volatility feed as key forecast inputs.
Underlying assumptions cover stable rare earth processing supply and continued FCC spectrum reallocation timelines, with deviation risk concentrated in trade policy shifts and Micro LED manufacturing breakthroughs. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Consumer Electronics
India Consumer Electronics Market
Consumer Electronics
Portable Media Player Market
Consumer Electronics
Bluetooth Speakers Market
Consumer Electronics
Russia Gaming Gadgets Market
Consumer Electronics
China Smartphone Market
Consumer Electronics
US Mobile Phone Accessories Market
Consumer Electronics
Global White Noise Machines Market
Consumer Electronics
Subwoofer Market
Consumer Electronics
Vape Market
Consumer Electronics
Electronic Products Rental Market
Consumer Electronics
Global Bluetooth Mono Earpieces Market
Consumer Electronics
Global Automated Laundromat Services Market
Consumer Electronics
Mobile Phone Accessories Market
Consumer Electronics
Portable Stick Market
Consumer Electronics
Earphones Market
Consumer Electronics
Gaming Computer Market