
 Smart Headphones Market | 2026-2036
Smart Headphones Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Headphones Market Intelligence
The EU Green Deal is expanding pressure on electronics manufacturers to adopt circular design practices and reduce e-waste footprints. Apple Inc. leverages its closed-loop material program and in-house chip design to control supply chain sustainability narratives. Sony Corporation anchors its premium positioning through proprietary noise cancellation algorithms and studio-grade audio calibration. Samsung Electronics competes across multiple price tiers through vertical manufacturing of displays, semiconductors, and batteries.
Smart headphones are wearable audio devices integrating wireless connectivity, active noise cancellation, voice recognition, and biometric sensors into ear-worn or head-worn form factors, typically operating via Bluetooth protocols with 20 Hz to 20 kHz frequency response ranges. Their primary purpose spans immersive entertainment, hands-free communication, health monitoring, and spatial audio for virtual environments. In-ear wireless models lead volume shipments due to portability and fitness integration, while over-ear noise cancellation variants command the dominant margin pool among professionals and audiophiles. Touch control interfaces are maturing as a baseline expectation, whereas voice assistant integration represents the fastest-growing technology dimension as natural language processing migrates to edge computing architectures.
The Federal Communications Commission governs radio frequency emissions and spectrum allocation for wireless audio transmission in the United States, while the EU's Radio Equipment Directive mandates interoperability and electromagnetic compatibility standards for devices sold across member states. China's Ministry of Industry and Information Technology certifies Bluetooth and radio modules through compulsory GB standards, creating a fragmented compliance landscape that shapes product development timelines and market access costs. Stakeholders must monitor evolving battery safety regulations and right-to-repair mandates that will determine whether modular designs become a compliance floor or a competitive differentiator.
Market Dynamics
Hybrid work permanence and the EU Green Deal's ecodesign mandates are compressing product development cycles while forcing modular, repairable architectures into smart headphone roadmaps. Manufacturers must now engineer for disassembly alongside acoustic performance.
Growth Catalysts
- Active noise cancellation:Enterprise IT procurement of ANC headsets for distributed teams is expanding fleet deployment volumes across North America and Western Europe.
- EU Green Deal ecodesign requirements:Mandatory recycled content thresholds and repairability scoring are accelerating circular design investments among premium-tier manufacturers.
- Shenzhen manufacturing cluster:Concentrated component suppliers and ODM capabilities around Huawei Technologies and domestic brands compress time-to-market for new entrants.
Market Restraints
- Lithium-polymer battery cost volatility:Raw material price swings for cobalt and lithium carbonate squeeze margin structures in mid-tier product lines.
- Bluetooth module supply concentration:Dependence on a limited base of certified radio module vendors creates qualification bottlenecks and allocation risk.
- Biometric sensor accuracy limitations:Heart rate and SpO2 measurement reliability in ear-worn form factors remains below clinical-grade thresholds, constraining health monitoring claims.
Strategic Opportunities
- Spatial audio for virtual environments:Head tracking and object-based rendering convergence with AR/VR platforms opens enterprise training and gaming verticals.
- India PLI scheme for electronics manufacturing:Production-linked incentives are attracting final assembly capacity for export-oriented and domestic consumption models.
- Right-to-repair mandates:Modular battery and driver replacement requirements in France and forthcoming EU legislation create first-mover advantage for repair-friendly architectures.
Industry Challenges
- Acoustic engineering talent scarcity:Shortage of DSP firmware developers and psychoacoustic specialists delays algorithm tuning and certification timelines.
- Multi-jurisdiction radio certification:Sequential FCC, CE marking, and MIIT GB standard testing extends product launch windows by four to six months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Headphones Market |
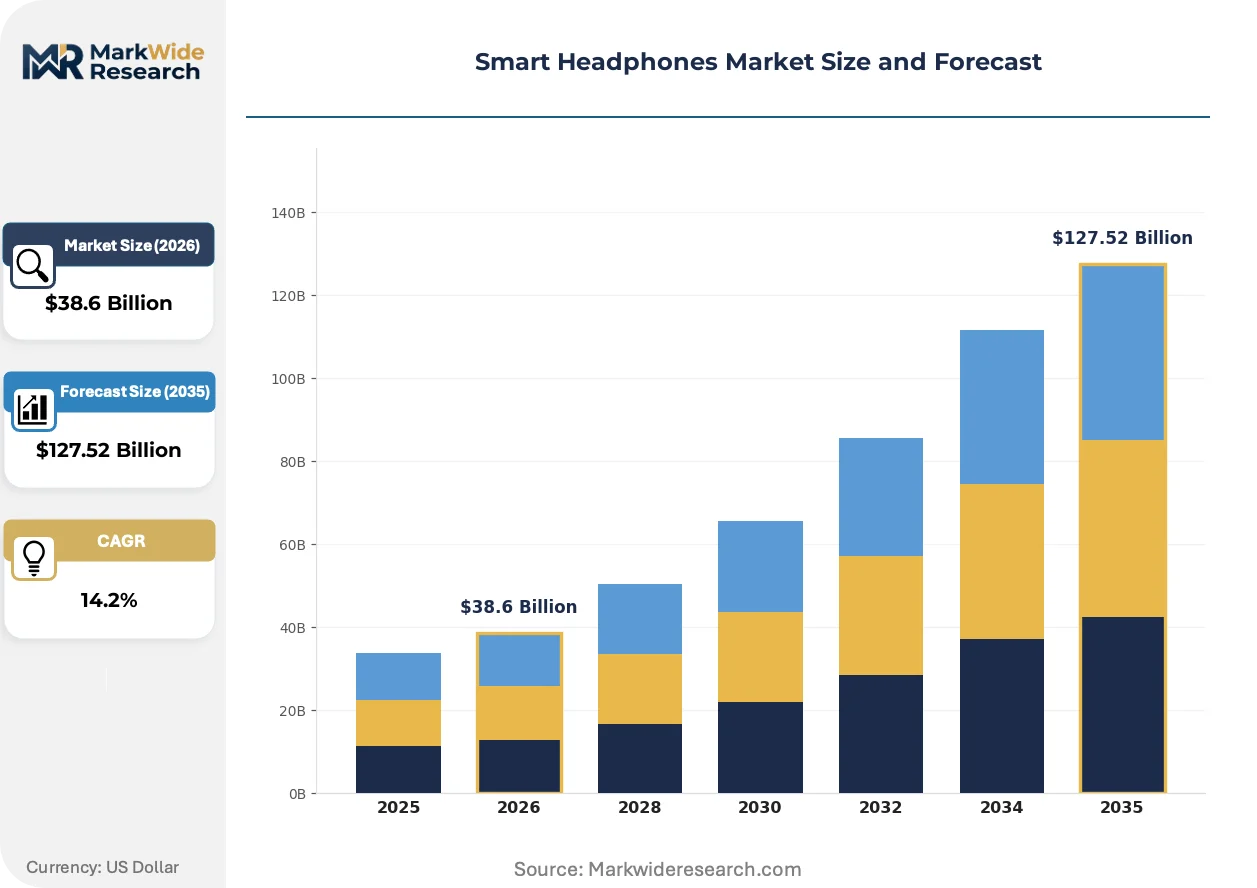
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $127.52 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Over-Ear, In-Ear, On-Ear, Wireless Technology: Noise Cancellation, Voice Assistant, Touch Control, Bluetooth End User: Consumers, Athletes, Professionals, Audiophiles Application: Music Listening, Fitness Tracking, Gaming, Communication |
| Companies Covered | Apple Inc., Samsung Electronics, Sony Corporation, Bose Corporation, Sennheiser Electronic GmbH & Co. KG, JBL (Harman International Industries), Jabra, Koninklijke Philips N.V., Huawei Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Headphones Market Strategic Shifts & Innovations
Edge AI inference is migrating onto headphone chipsets, enabling real-time audio processing without cloud dependency. This shift is compressing latency benchmarks while opening new interaction paradigms.
On-device neural processing units for voice recognition and adaptive noise cancellation are modularizing feature deployment across product tiers. Flagship models from Apple and Sony now run natural language understanding locally, while mid-range chipsets from MediaTek and Qualcomm are adopting similar architectures. Component standardization is modularizing the premium feature cascade, enabling faster capability diffusion downmarket.
The EU AI Act's risk classification framework for biometric identification systems is tightening compliance requirements for health-monitoring headphones sold across member states. Manufacturers must now document algorithmic transparency and data governance protocols before CE marking approval. Wearable audio products with SpO2 or stress detection face heightened scrutiny, pushing vendors toward privacy-by-design architectures and on-sensor data processing.
Enterprise procurement is consolidating around certified device programs that bundle hardware, fleet management, and support services. IT departments at financial services and professional services firms are displacing ad-hoc consumer purchases with standardized ANC headset deployments. This bundling trend is most visible in the United States, where HIPAA-aligned communication requirements and hybrid work policies are driving three-year replacement cycles.
Smart Headphones Market Segmentation
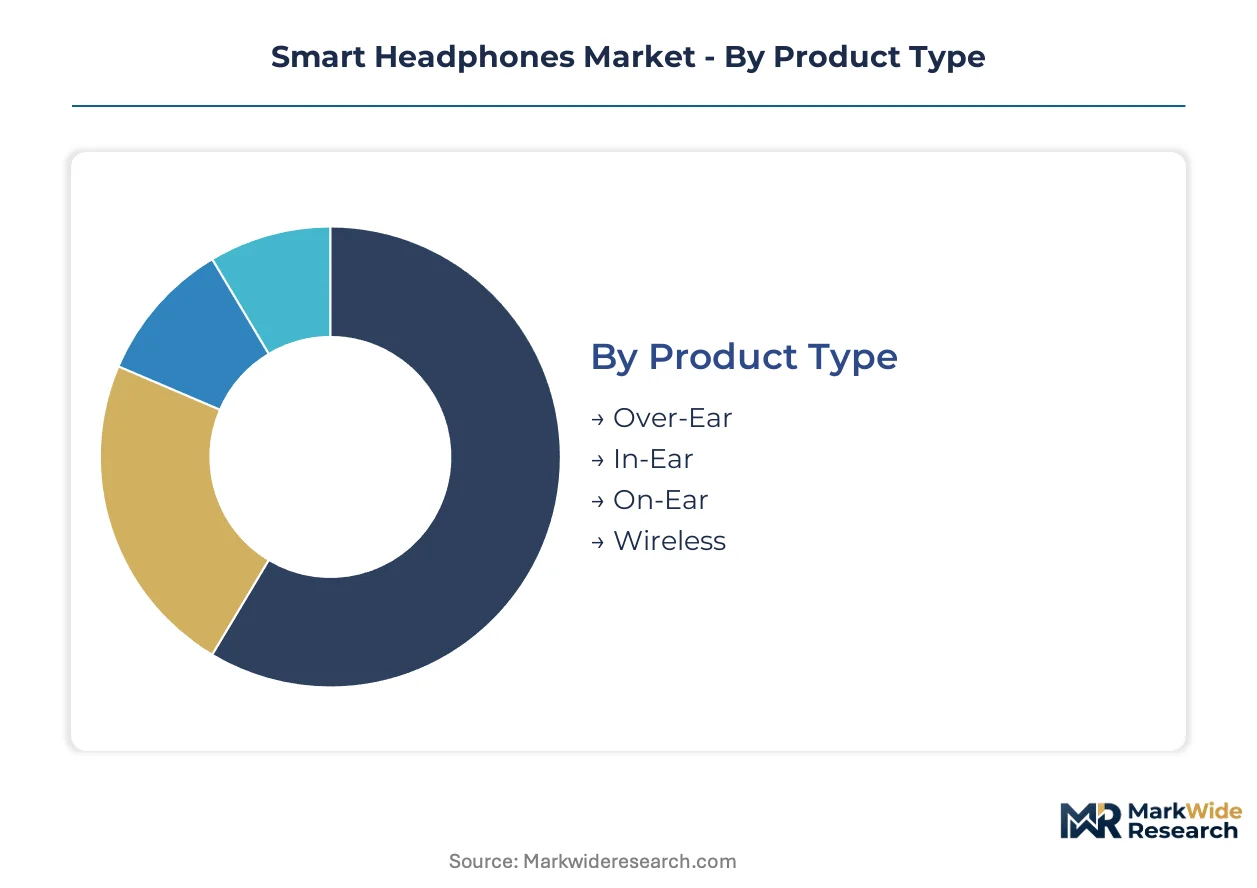
Segmentation in smart headphones separates volume commodities from margin-rich specialty tiers. Product architecture, interface modality, and user context each create distinct competitive arenas with divergent R&D priorities and certification requirements.
Product Type:
Volume concentrates in pocketable form factors while premium margins pool around acoustic isolation and driver scale.
- In-Ear:Compact silicone or foam-tipped housings seal the ear canal for passive isolation alongside active noise cancellation. Demand clusters among fitness users in China's Shenzhen manufacturing corridor, where local ODMs compress tooling costs for sports-integrated models with IPX4+ ratings.
- Over-Ear:Circumaural cushions enclose the pinna with 40mm+ dynamic drivers or planar magnetic arrays. Enterprise IT procurement in the United States drives fleet deployment of ANC variants for hybrid work compliance with HIPAA-aligned communication standards.
- On-Ear:Supra-aural pads rest against rather than around the ear, trading isolation for breathability. Lightweight construction appeals to commuter segments prioritizing situational awareness.
- Wireless:Cord-free operation via Bluetooth protocols spans all form factors, now baseline across price tiers rather than a distinct category.
Today's leader: In-Ear. Tomorrow's challenger: Over-Ear.
Technology:
Interface modality determines BOM cost structure and firmware development intensity.
- Noise Cancellation:Feedforward and feedback microphone arrays generate anti-phase waveforms for 20-40 dB attenuation. Adaptive algorithms from Sony and Apple set the performance ceiling that mid-tier chipsets from MediaTek and Qualcomm now approach.
- Voice Assistant:Natural language processing at the edge enables hands-free control without cloud latency. The EU AI Act's biometric risk classification tightens compliance for always-listening architectures sold across member states.
- Touch Control:Capacitive gesture surfaces replace physical buttons for volume and track navigation. Surface area constraints in In-Ear form factors limit gesture complexity.
- Bluetooth:Radio modules certified to FCC Part 15, CE marking, and MIIT GB standards enable wireless audio transmission. Supply concentration among Qualcomm and MediaTek creates allocation bottlenecks during semiconductor cycle peaks.
Noise Cancellation commands the dominant margin pool. Voice Assistant climbs the fastest on enterprise and automotive integration.
End User:
User sophistication dictates acoustic calibration depth and sensor integration density.
- Consumers:General-purpose listeners prioritizing convenience and brand recognition over technical specifications. Price elasticity is highest in this bracket.
- Professionals:Enterprise users requiring certified ANC performance for open-office productivity and video conferencing clarity. India's PLI scheme for electronics manufacturing is attracting final assembly capacity for export-oriented enterprise models.
- Athletes:Fitness-integrated users demanding biometric sensors, sweat resistance, and secure fit retention. Heart rate and SpO2 measurement reliability remains below clinical-grade thresholds, constraining health claims.
- Audiophiles:Critical listeners pursuing flat frequency response, low THD, and high-resolution codec support. Studio-grade calibration from Sony anchors premium positioning in this segment.
Professionals drive replacement cycles. Audiophiles defend margin structures.
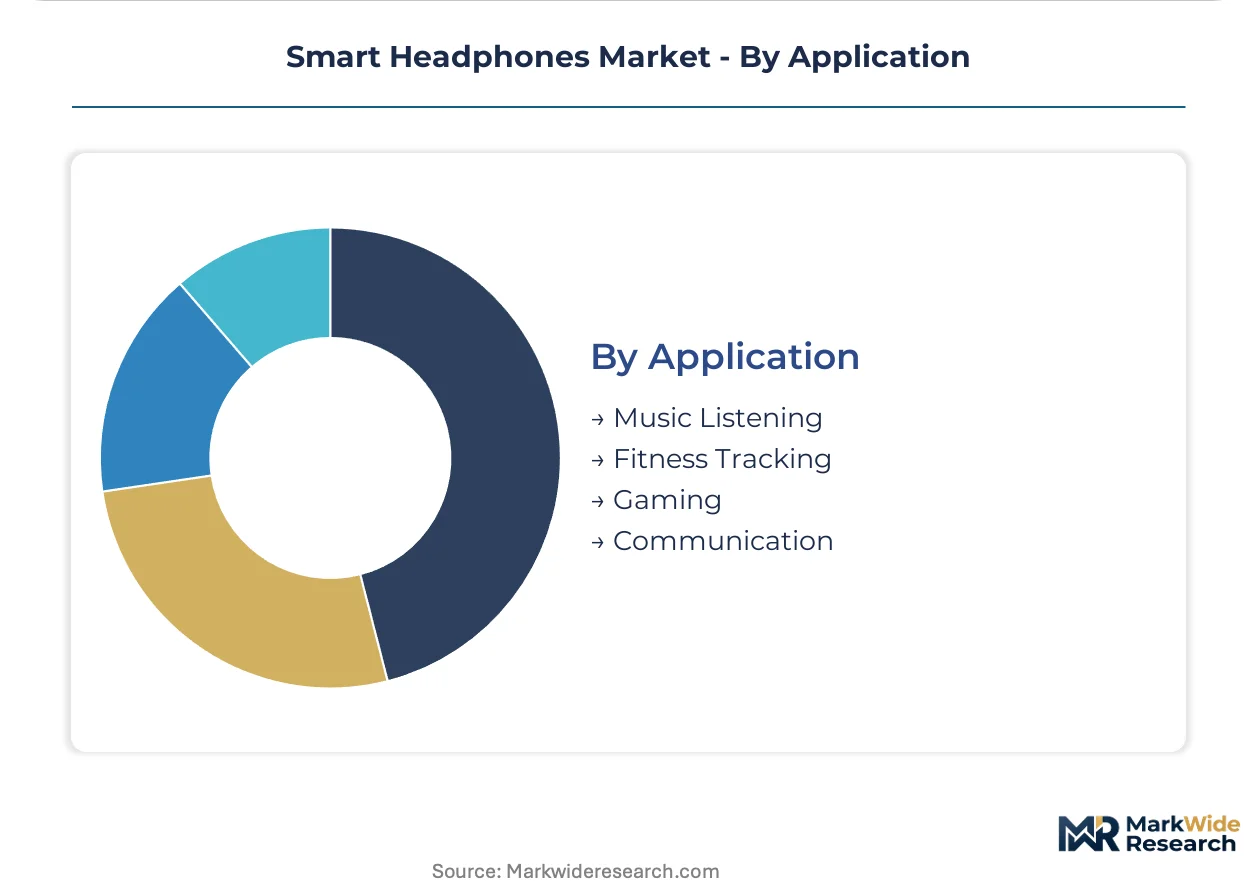
Application:
Use case specificity determines sensor payload and spatial audio processing requirements.
- Music Listening:Core entertainment use case spanning all price tiers. Codec support for LDAC, aptX HD, and AAC lossless differentiates premium tiers.
- Communication:Voice call clarity and beamforming microphone arrays for noisy environments. Enterprise procurement in financial services consolidates around certified device programs bundling hardware and fleet management.
- Fitness Tracking:Biometric monitoring during exercise with accelerometer and PPG sensor fusion. EU Green Deal ecodesign requirements push manufacturers toward modular, repairable designs for battery replacement.
- Gaming:Low-latency transmission and spatial audio with head tracking for positional cueing. Convergence with AR/VR platforms opens enterprise training verticals.
Communication anchors volume. Gaming expands most quickly on immersive platform convergence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The smart headphones industry traces its commercial origins to Japanese and American consumer electronics laboratories of the 1980s, where Sony and Bose pioneered portable active noise cancellation. Today's geographic distribution reflects this heritage while incorporating new manufacturing and demand centers across three continents.
United States
Enterprise IT procurement drives fleet deployment of ANC headsets for hybrid work compliance with HIPAA-aligned communication standards. The Federal Communications Commission governs radio frequency emissions through FCC Part 15 certification for Bluetooth transmission. Austin and San Francisco host software development clusters where edge AI firmware for voice recognition matures.
China
Shenzhen's manufacturing corridor concentrates component suppliers and ODM capabilities around Huawei Technologies and domestic brands, compressing tooling costs for sports-integrated models. The Ministry of Industry and Information Technology certifies Bluetooth modules through compulsory GB standards, fragmenting compliance timelines. Dongguan final assembly plants supply both export markets and surging domestic consumption.
Germany
Professional audio engineering traditions sustain premium-tier demand for studio-grade calibration and flat frequency response. The EU Green Deal's ecodesign requirements mandate recycled content thresholds and repairability scoring, accelerating circular design investments. Berlin and Munich anchor R&D clusters where psychoacoustic specialists tune adaptive noise cancellation algorithms.
Japan
Proprietary noise cancellation algorithms and high-resolution codec support defend margin structures among critical listeners. The Ministry of Economy, Trade and Industry oversees JIS standards alignment with international electromagnetic compatibility protocols. Tokyo and Osaka metropolitan areas concentrate audio engineering talent for DSP firmware development.
India
Production-linked incentives under the PLI scheme attract final assembly capacity for export-oriented enterprise models and domestic consumption. The Bureau of Indian Standards implements compulsory registration for wireless audio devices entering the market. Tamil Nadu and Karnataka electronics manufacturing zones host expanding final assembly operations for mid-tier product lines.
Smart Headphones Market Key Industry Players
Capital-heavy producers compete with asset-light designers across a tiered structure where integrated semiconductor and acoustic engineering capabilities separate premium positioning from commodity volume. The vendor base organizes around three strategic archetypes: vertically integrated technology conglomerates controlling chip design and firmware ecosystems; specialized audio houses leveraging heritage acoustic engineering; and contract-dependent brands relying on ODM flexibility for rapid SKU rotation. Dominant competitive moves include strategic patent licensing for noise cancellation algorithms and geographic diversification of final assembly to mitigate tariff exposure and qualify for regional incentive programs.
Among vertically integrated technology conglomerates, Apple Inc. and Samsung Electronics exemplify the capital-intensive archetype through captive semiconductor design and ecosystem lock-in strategies. Sony Corporation occupies a distinct position bridging heritage audio engineering with proprietary algorithm development, representing the specialized house model that defends premium tiers through technical differentiation rather than scale economics.
| Leading Market Players |
|---|
| Apple Inc. |
| Samsung Electronics |
| Sony Corporation |
| Bose Corporation |
| Sennheiser Electronic GmbH & Co. KG |
| JBL (Harman International Industries) |
| Jabra |
| Koninklijke Philips N.V. |
| Huawei Technologies |
| Others |
Cost & Logistics Intelligence
Captive semiconductor design and in-house firmware ecosystems anchor both supply security and pricing power for premium-tier manufacturers, while outsourced ODM relationships compress margins for volume players competing through Shenzhen's manufacturing corridor. This structural divergence separates brands that command acoustic algorithm premiums from those locked into commodity Bluetooth module sourcing.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates the market, with differentiation driven by certification grade for enterprise HIPAA compliance and proprietary noise cancellation algorithm performance. Cost compression in mid-tier product lines is intensifying because lithium-polymer battery raw material volatility squeezes margin structures. Enterprise IT procurement shows the lowest price sensitivity due to fleet standardization requirements, while fitness-integrated consumer segments exhibit the highest elasticity.
Supply Chain Analysis
Regional distribution centers in the United States and Germany operate hub-and-spoke patterns feeding enterprise procurement channels, while direct-to-consumer e-commerce bypasses traditional retail layers. Manufacturing concentrates in China, Vietnam, and India, with component sourcing drawing from Taiwan for Bluetooth chipsets and South Korea for display modules. Single-source vulnerability around Qualcomm and MediaTek radio modules creates allocation risk during semiconductor cycle peaks. Distribution runs through certified device program bundling hardware with fleet management services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion potential concentrates in premium tiers where edge AI firmware and modular repairable designs command pricing premiums, while component standardization drives cost-down curves across mid-range chipsets from MediaTek and Qualcomm.
For Market Incumbents: Hedge against biometric sensor commoditization by deepening proprietary algorithm moats in adaptive noise cancellation and spatial audio processing. Acquire DSP firmware development talent clusters in Berlin and Tokyo to defend technical differentiation. Expand certified device program partnerships with financial services IT departments to lock in three-year replacement cycles. For New Entrants and Emerging Players: Launch via India's PLI scheme for electronics manufacturing to qualify for production-linked incentives and access export-oriented enterprise assembly capacity. Target the on-ear commuter segment where situational awareness features remain underdeveloped relative to in-ear and over-ear saturation. Pursue white-label ODM relationships with Shenzhen manufacturers for rapid SKU rotation without captive semiconductor investment. For Investors and Strategic Acquirers: Consolidation pressure builds where acoustic engineering talent scarcity delays certification timelines and algorithm tuning. Long-term viability favors vertically integrated players controlling chip design, firmware ecosystems, and repairable hardware architectures. Watch for EU right-to-repair mandate enforcement as the inflection signal determining whether modular battery replacement becomes compliance floor or competitive differentiator.| Strategic Initiative | Industry Significance |
|---|---|
| Edge AI Chipset Integration | On-device neural processing from Apple and Sony compresses latency benchmarks without cloud dependency. |
| Modular Repairable Design Investment | EU Green Deal ecodesign requirements accelerate circular design investments among premium-tier manufacturers. |
| Certified Device Program Expansion | HIPAA-aligned enterprise procurement in the United States consolidates around bundled hardware and fleet management services. |
| Spatial Audio Platform Partnership | Head tracking convergence with AR/VR platforms opens enterprise training and gaming verticals for immersive audio. |
| PLI Scheme Manufacturing Localization | India's production-linked incentives attract final assembly capacity for export-oriented enterprise models and domestic consumption. |
Research Approach
Bottom-up end-use modeling reconciled against top-down supply-side tracking forms the analytical core of this study. Primary interviews with acoustic engineering directors, enterprise IT procurement officers, ODM manufacturing leads, and regulatory compliance specialists combined with secondary validation from FCC equipment authorization databases, EU CE marking registries, MIIT GB standard certifications, and customs trade flow records. Triangulation across these sources calibrated shipment volumes and pricing tiers.
Input-output matrices map Bluetooth chipset supply from Qualcomm and MediaTek against finished goods assembly in China, Vietnam, and India across the projection horizon. Segmentation dimensions include product architecture, interface modality, end-user sophistication, and application-specific sensor payload. CAGRs derive from regression analysis of historical shipment trajectories adjusted for technology substitution effects and regulatory mandate implementation timelines. Forecast inputs incorporate lithium-polymer battery cost curves and edge AI chipset adoption rates.
Forecast precision tightens around the base case; tail outcomes carry wider variance under lithium raw material price spikes and sequential multi-jurisdiction radio certification delays. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Consumer Electronics
Wireless Speakers Market
Consumer Electronics
Industrial Hearables Market
Consumer Electronics
Middle East and Africa Mobile Phone Accessories Market
Consumer Electronics
Smart TV Sticks Market
Consumer Electronics
Global Bluetooth Mono Earpieces Market
Consumer Electronics
Global Tablet Keyboards Market
Consumer Electronics
Ultra HD Action Camera Market
Consumer Electronics
Consumer Electronic Accessories Market
Consumer Electronics
Global Used Smartphones Market
Consumer Electronics
Global Laptop Skins Market
Consumer Electronics
Digital Writing Instruments Market
Consumer Electronics
Smart TV Market
Consumer Electronics
Gaming Laptops and Desktops Market
Consumer Electronics
Pet Monitoring Camera Market
Consumer Electronics
Ereader and Enotetaking Devices Market
Consumer Electronics
Tattoo Stencil Printer Market