
 US Refurbished and Used Mobile Phones Market | 2026-2036
US Refurbished and Used Mobile Phones Market Size, Share, and Industry Trends Forecast 2026-2036
US Refurbished and Used Mobile Phones Market Insights
The US refurbished and used mobile phones market is decoupling into two distinct tiers: premium certified-refurbished devices backed by manufacturer warranties and unverified used phones sold through peer-to-peer channels. Apple Inc. leverages its official refurbishment program to control quality benchmarks and capture margin pools in the premium tier. Samsung Electronics Co. Ltd competes through its certified pre-owned Galaxy program, while Amazon.com Inc. anchors volume throughput via its renewed marketplace infrastructure and logistics network.
Refurbished and used mobile phones encompass previously owned wireless communication devices that undergo diagnostic testing, component replacement, and software restoration to restore functional performance for resale. These devices typically receive battery replacements, screen repairs, and firmware updates to meet minimum operational standards for voice, data, and application processing. Smartphones dominate transaction volume due to their higher residual value and broader compatibility with carrier networks, while the condition spectrum from "Like New" to "Used" creates distinct price-performance brackets that concentrate margin in certified refurbishment. Online retail channels capture the fastest growth trajectory as direct-to-consumer platforms reduce intermediary markups and expand geographic access beyond physical store footprints.
The FCC mandates electromagnetic compatibility and equipment authorization for all commercialized wireless devices, creating compliance barriers that favor established refurbishers with testing capabilities. State-level right-to-repair laws in California and New York, alongside OSHA workplace safety standards for electronics handling facilities, further elevate operational requirements for market participants. Stakeholders must monitor evolving EPA e-waste disposal regulations and carrier unlocking policies that determine device eligibility for secondary market activation.
Market Dynamics
The US refurbished and used mobile phones market is splitting along certification lines as FCC equipment authorization requirements and state right-to-repair laws force operational bifurcation between compliant refurbishers and informal resellers.
Growth Catalysts
- Right-to-repair legislation:California and New York laws mandate parts availability and diagnostic access, lowering barriers for independent refurbishers to enter certified channels.
- Carrier unlocking mandates:FCC policies requiring post-contract device unlocking expand eligible inventory for secondary market activation across all major networks.
- Enterprise fleet refresh cycles:Corporate technology procurement departments are formalizing certified pre-owned device programs to reduce hardware expenditure.
Market Restraints
- Lithium-ion battery supply concentration:Replacement battery sourcing depends on concentrated Asian manufacturing, creating input cost volatility and quality inconsistency for US refurbishers.
- FCC certification costs:Electromagnetic compatibility testing and equipment authorization fees impose fixed cost barriers that exclude small-scale operators from commercial resale.
- 5G hardware incompatibility:Older device architectures lack millimeter-wave antenna modules, limiting resale value for pre-2020 smartphones as carriers sunset LTE priority.
Strategic Opportunities
- Texas urban corridor expansion:Dallas-Fort Worth and Houston metro areas show underpenetrated refurbishment throughput relative to device turnover rates.
- Insurance trade-in integration:Carrier and third-party device protection programs are creating captive supply streams for certified refurbishment pipelines.
- AI-driven diagnostics:Machine vision and automated testing platforms are compressing quality assurance timelines for high-volume refurbishment operations.
Industry Challenges
- Certified technician scarcity:Microsoldering and board-level repair skills required for advanced refurbishment face limited vocational training pipeline output.
- Software authentication complexity:Apple's parts pairing and Samsung's Knox security frameworks create integration friction for third-party component replacement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Refurbished and Used Mobile Phones Market |
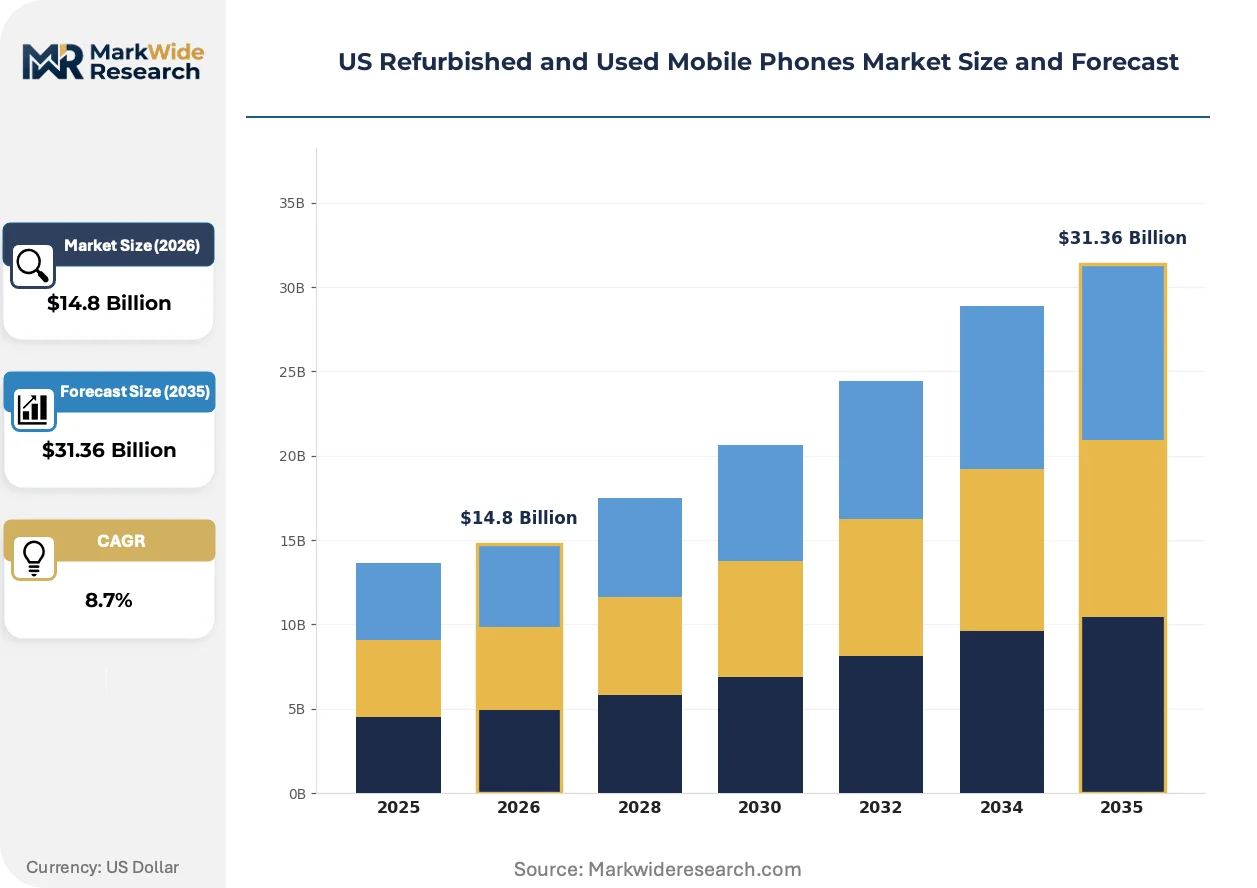
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $31.36 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smartphones, Feature Phones, Phablets, Luxury Phones Condition: Refurbished, Used, Open Box, Like New Sales Channel: Online Retail, Physical Stores, Carrier Stores, Auctions Brand: Certain Apple Models, Samsung Galaxy, Google Pixel, Motorola |
| Companies Covered | Apple Inc., Samsung Electronics Co. Ltd, Amazon.com Inc., Verizon Communications Inc., AT&T Inc., Back Market, Swappa, Gazelle, eBay Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Refurbished and Used Mobile Phones Market Trends and Innovations
Automation is penetrating diagnostic and grading workflows while regulatory pressure on e-waste disposal intensifies recovery economics. These forces are compressing refurbishment cycle times and reshaping competitive requirements for scale.
Automated optical inspection systems are absorbing quality grading functions previously performed by human technicians. High-volume refurbishers in California and Texas facilities are deploying machine vision for cosmetic condition assessment. This technology is absorbing margin pressure from labor cost inflation while standardizing grading consistency across distributed operations.
New York's Digital Fair Repair Act is forcing manufacturers to release diagnostic software and spare parts to independent repair providers. The legislation compresses OEM control over aftermarket service revenue. Certified refurbishers in New York State are expanding capacity to capture diverted warranty repair volume.
Enterprise procurement departments are unbundling device lifecycle management from carrier service contracts. Large employers in finance and healthcare verticals are establishing direct relationships with certified refurbishers for fleet deployment. This pattern is most visible in California where sustainability reporting requirements accelerate circular economy adoption.
US Refurbished and Used Mobile Phones Market Segmentation
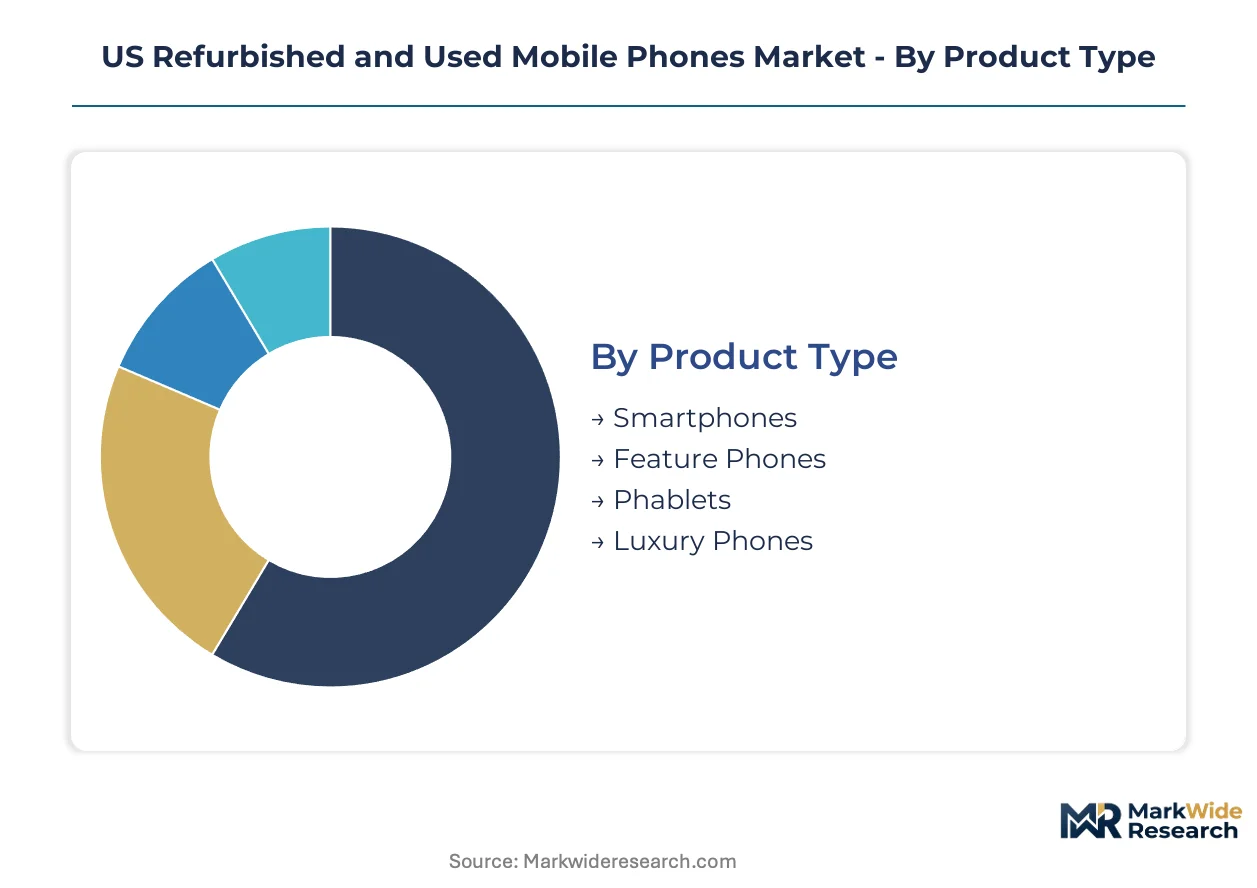
Certification requirements from the FCC and state-level right-to-repair laws create divergent compliance burdens across product tiers and sales channels. Segmentation reveals which device categories absorb testing costs and which channels capture margin from warranty-backed resale.
Product Type:
FCC equipment authorization mandates apply uniformly across all wireless devices, though battery replacement and antenna testing complexity varies sharply by form factor.
- Smartphones:Full-function touchscreen devices with cellular modems, GPS, and application processors dominate refurbishment economics. California and Texas facilities process the highest throughput, driven by carrier trade-in programs and enterprise fleet refresh cycles that generate predictable supply.
- Feature Phones:Basic voice-and-text devices with limited data capability. Demand concentrates in rural markets and senior demographics where simplified interfaces outweigh smartphone functionality; minimal FCC recertification burden supports low-margin viability.
- Phablets:Oversized smartphones with diagonal displays exceeding six inches. Screen replacement costs and battery sourcing challenges compress margins relative to standard smartphones.
- Luxury Phones:Premium-tier devices from specialized manufacturers with precious metal or exotic material construction. Limited refurbishment infrastructure and constrained parts availability restrict volume despite high unit margins.
Smartphones sit at the top of the volume ranking, with phablets climbing the fastest as enterprise procurement shifts toward larger-screen fleet deployment.
Condition:
Condition grading determines warranty eligibility, return policy terms, and price positioning within carrier and retail channels.
- Refurbished:Devices restored to manufacturer-specified functional standards through diagnostic testing, component replacement, and software reinstallation. Battery replacement and screen refurbishment are standard; FCC recertification or carrier activation approval is mandatory for commercial resale.
- Used:Pre-owned devices sold without systematic restoration or quality certification. Peer-to-peer platforms and independent dealers dominate; consumer protection exposure limits institutional buyer participation.
- Open Box:Devices returned within retail return windows with original packaging and accessories intact. Minimal functional testing required; cosmetic grading focuses on packaging integrity rather than device wear.
- Like New:Devices exhibiting negligible cosmetic wear and full functional performance indistinguishable from new retail stock. Premium pricing captures buyers seeking warranty-backed alternatives to new device purchases.
Refurbished inventory commands the highest absolute volume, with Like New devices expanding most quickly as manufacturer-certified programs scale.
Sales Channel:
Channel selection dictates compliance exposure, geographic reach, and margin capture from logistics efficiency.
- Online Retail:Direct-to-consumer platforms with nationwide fulfillment infrastructure. Amazon's renewed marketplace and specialized refurbisher websites absorb volume from price-sensitive buyers outside major metro areas; return logistics and warranty administration create operational complexity.
- Physical Stores:Independent electronics retailers and dedicated refurbishment chains with in-person inspection and same-day pickup. California and Florida host the densest store networks; rent and labor costs pressure unit economics.
- Carrier Stores:Verizon, AT&T, and T-Mobile retail locations with certified pre-owned programs. Device unlocking mandates and activation system integration create captive demand; trade-in credits subsidize new device purchases while feeding refurbishment pipelines.
- Auctions:B2B liquidation platforms and government surplus sales for bulk device acquisition. Insurance claim salvage and enterprise fleet disposal generate supply; buyer assumes testing and refurbishment risk.
Carrier Stores lead transaction volume, with Online Retail gaining share fastest as logistics networks compress delivery timelines for remote buyers.
Brand:
Manufacturer repair policy and parts availability determine third-party refurbishment feasibility and warranty program structure.
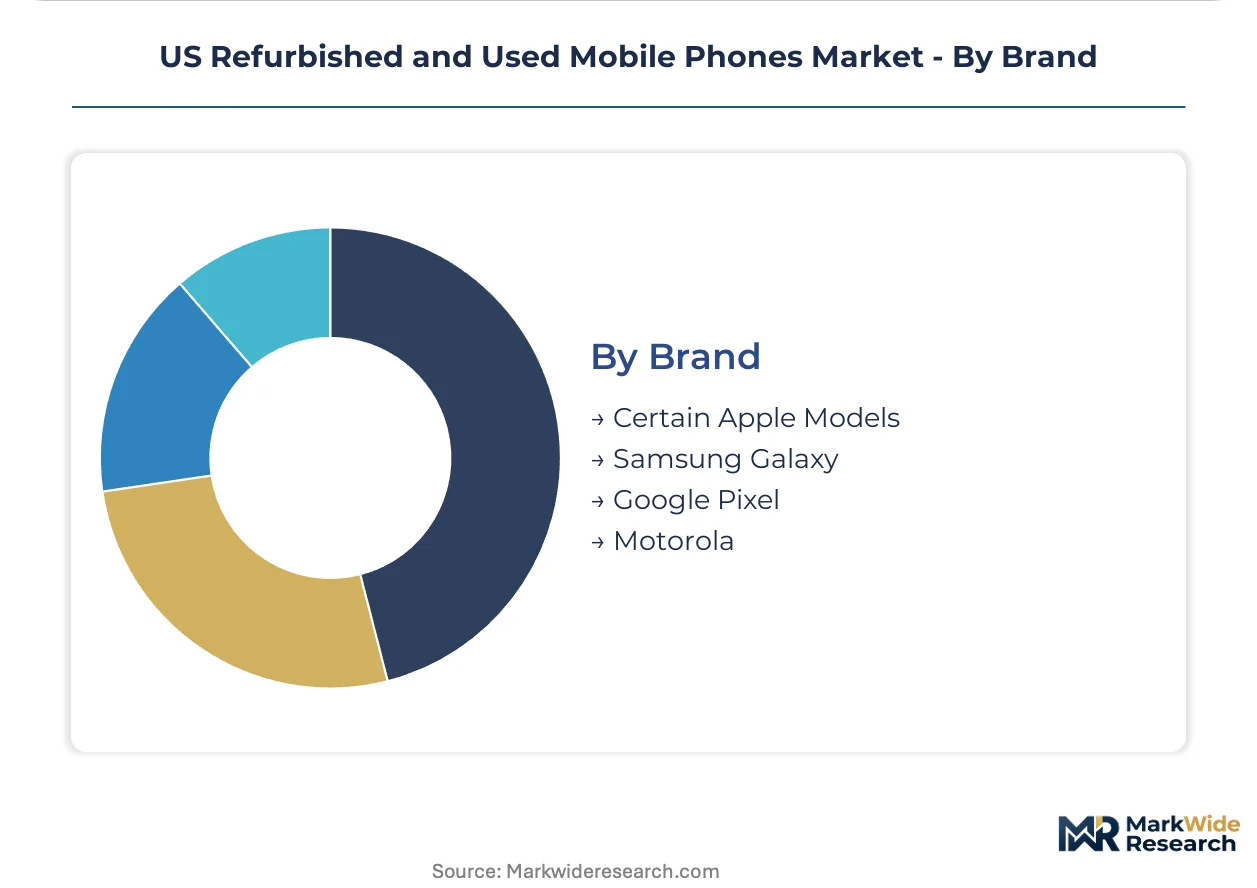
- Certain Apple Models:iPhone lines with established refurbishment infrastructure and strong residual value. Parts pairing restrictions and proprietary diagnostic tools limit independent repair; Apple's official program sets quality benchmarks.
- Samsung Galaxy:Android flagship and mid-tier devices with broad carrier compatibility. Knox security frameworks create software authentication friction for component replacement; certified pre-owned program competes directly with Apple.
- Google Pixel:Android devices with clean software experience and rapid security update commitment. Limited retail presence concentrates resale through online channels; modular design simplifies battery and screen replacement.
- Motorola:Budget and mid-tier devices with straightforward hardware architecture. Minimal software lockdown supports independent refurbishment; enterprise and government contracts generate predictable fleet turnover.
Certain Apple Models anchor volume rankings, with Google Pixel expanding most quickly as enterprise procurement prioritizes rapid security patch delivery.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
California and Texas dominate refurbishment throughput, while Florida and New York Metro exhibit divergent growth trajectories shaped by regulatory and demographic factors.
California
Enterprise fleet refresh cycles and carrier trade-in density drive volume concentration in Los Angeles and San Francisco Bay Area corridors. The state's Digital Fair Repair Act mandates parts availability and diagnostic access for independent refurbishers. San Jose hosts the densest cluster of high-volume refurbishment facilities processing manufacturer-certified inventory.
Texas
Dallas-Fort Worth and Houston metro areas show underpenetrated refurbishment capacity relative to device turnover rates. OSHA workplace safety standards for electronics handling facilities elevate operational compliance costs for new market entrants. Austin's technology sector generates substantial enterprise device disposal streams feeding certified pre-owned pipelines.
Florida
Senior demographic concentration sustains demand for simplified feature phones alongside smartphone refurbishment. State consumer protection statutes impose warranty disclosure requirements on secondary market sellers. Miami-Dade and Broward counties anchor the Southeast's highest physical store penetration for in-person device inspection.
New York Metro
Urban density and transit-dependent lifestyles accelerate replacement cycles among Manhattan and Brooklyn consumers. The Digital Fair Repair Act compresses OEM control over aftermarket service revenue. Long Island and northern New Jersey suburbs concentrate insurance trade-in processing facilities serving regional carrier partnerships.
Southeast
Atlanta and Charlotte logistics hubs enable rapid inventory redistribution across lower-cost markets. FCC device certification requirements favor established refurbishers with electromagnetic compatibility testing capabilities. Georgia's warehouse infrastructure supports Amazon renewed marketplace fulfillment for remote buyers throughout the region.
US Refurbished and Used Mobile Phones Market Competitive Landscape
Top-tier vendors anchor manufacturer-certified programs, while independent refurbishers and peer-to-peer platforms occupy fragmented lower tiers. The market exhibits bifurcated concentration: Apple and Samsung control premium certification standards, Amazon absorbs volume through logistics scale, and dozens of regional operators compete on price. Three archetypes dominate: OEM-controlled refurbishment programs, marketplace platforms with fulfillment infrastructure, and specialized trade-in aggregators. Competitive moves center on insurance partnership capture and diagnostic automation deployment.
Within the OEM-controlled tier, Apple Inc. and Samsung Electronics Co. Ltd exemplify vertically integrated refurbishment models that set quality benchmarks and capture margin pools. Amazon.com Inc. anchors the marketplace platform archetype through renewed marketplace infrastructure and logistics network density. These three entities occupy positions that shape certification requirements and consumer trust thresholds across the broader competitive field.
| Leading Market Players |
|---|
| Apple Inc. |
| Samsung Electronics Co. Ltd |
| Amazon.com Inc. |
| Verizon Communications Inc. |
| AT&T Inc. |
| Back Market |
| Swappa |
| Gazelle |
| eBay Inc. |
| Others |
Pricing and Supply Chain Analysis
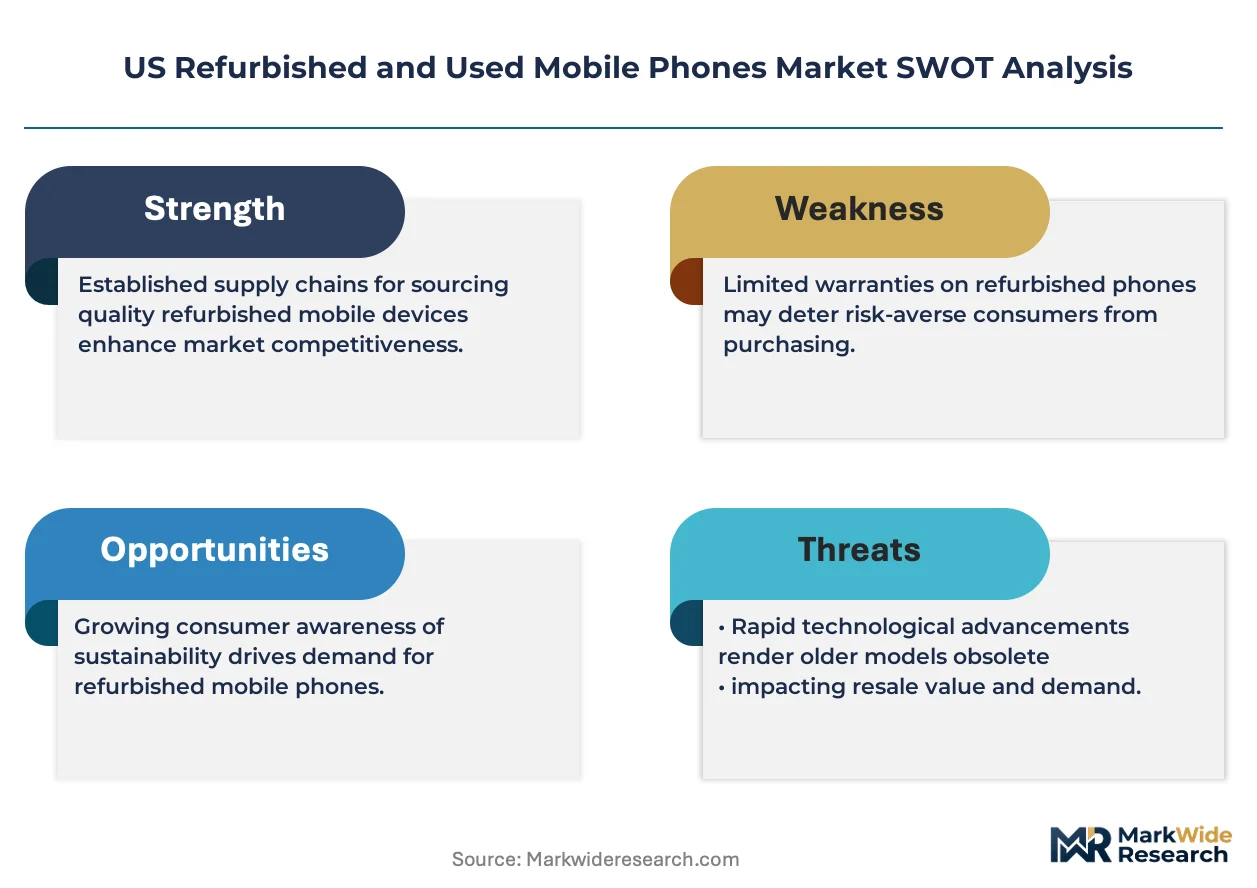
Lithium-ion battery replacement costs flow from concentrated Asian manufacturing through refurbishment economics to price tiers at US retail. Carrier unlocking mandates and FCC certification fees compress margins for independent operators while OEM-controlled programs absorb compliance overhead into premium positioning.
Pricing Analysis
Capacity additions in Texas refurbishment facilities are reshaping price floors for certified pre-owned smartphones. Three-tier pricing structure across manufacturer-certified, third-party refurbished, and unverified used levels segments buyers by risk tolerance and warranty demand. Price differentiation centers on FCC recertification status and battery replacement provenance. Pricing pressure stems from lithium-ion supply volatility, with budget-conscious institutional buyers driving softness at the economy tier while enterprise procurement sustains premium tier stability.
Supply Chain Analysis
Reverse-logistics flows from carrier trade-in programs and insurance claim salvage feed refurbishment pipelines through diagnostic hubs in California and Texas. Component sourcing draws from China, South Korea, and Taiwan for replacement batteries, display assemblies, and antenna modules. Single-source vulnerability concentrates in OEM-controlled parts pairing systems that restrict third-party component authentication. Distribution runs through Amazon's renewed marketplace, carrier retail locations, and specialized refurbisher direct-to-consumer platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US refurbished and used mobile phones market functions as a stable compounder, with enterprise fleet refresh cycles and right-to-repair legislation generating predictable supply and demand expansion.
For Market Incumbents: Cement certification infrastructure investments to defend against independent refurbishers leveraging California and New York diagnostic access laws. Carrier partnership exclusivity and automated optical inspection deployment protect margin pools from price erosion at the economy tier. FCC equipment authorization capabilities create regulatory moats that exclude small-scale competitors. For New Entrants and Emerging Players: Enter via the Texas urban corridor where refurbishment capacity lags device turnover rates in Dallas-Fort Worth and Houston metro areas. Insurance trade-in integration offers the most penetrable supply channel, with AI-driven diagnostics enabling rapid quality assurance scale without legacy technician dependency. Direct-to-consumer online positioning bypasses rent-burdened physical store networks. For Investors and Strategic Acquirers: Roll-up economics work for regional refurbishment specialists with established FCC testing capabilities because carrier unlocking mandates and enterprise procurement formalization concentrate volume among compliant operators. Five-to-ten-year viability rests on circular economy adoption acceleration and sustainability reporting requirements. Monitor state right-to-repair expansion as the inflection signal for independent refurbisher competitive positioning.| Strategic Initiative | Industry Significance |
|---|---|
| Diagnostic Automation Deployment | Machine vision systems compress quality assurance timelines for high-volume California and Texas facilities. |
| Carrier Partnership Expansion | Trade-in program integration captures captive supply streams feeding certified refurbishment pipelines. |
| Enterprise Fleet Contracting | Direct procurement relationships with finance and healthcare verticals reduce carrier intermediary dependency. |
| Right-to-Repair Compliance Investment | Diagnostic software access and parts availability positioning captures diverted warranty repair volume in New York. |
| Insurance Trade-in Integration | Device protection program partnerships create predictable salvage inventory for certified pre-owned pipelines. |
Research Methodology
Bottom-up enterprise procurement modeling reconciled against top-down carrier trade-in volume tracking forms the analytical core. Primary interviews with refurbishment facility operators, carrier device lifecycle managers, enterprise IT procurement directors, and insurance claim processors combined with secondary validation from FCC equipment authorization databases, carrier unlocking compliance filings, and state legislative records. Triangulation against OSHA workplace safety inspection data and EPA e-waste disposal reports anchored supply-side estimates.
Historical trendline analysis of refurbishment throughput and pricing spreads informed projection frameworks across the analysis window. Segmentation dimensions modeled include device condition tier, certification status, sales channel structure, and regional regulatory cluster. CAGRs derived from fitted growth curves adjusted for carrier unlocking mandate implementation timelines and right-to-repair legislative adoption patterns. Enterprise fleet refresh cycle data and battery replacement cost indices served as industry-specific forecast inputs.
Inputs from carrier trade-in program disclosures and state regulatory filings were available through the study window; gaps in independent refurbisher financial reporting introduce uncertainty bands around market share estimates. Forecasts reflect documented assumptions regarding FCC certification cost trajectories and lithium-ion supply stability. Practitioners should monitor state-level right-to-repair expansion and 5G network sunset announcements for early signals of inventory value and device eligibility shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Consumer Electronics
Camera Case Market
Consumer Electronics
Closed Back Studio Headphone Market
Consumer Electronics
Pet Monitoring Camera Market
Consumer Electronics
Tattoo Machine Market
Consumer Electronics
Consumer Electronics Repair and Maintenance Market
Consumer Electronics
Digital Cloud Picture Frame Market
Consumer Electronics
Headphones Market
Consumer Electronics
Stylus Pen Market
Consumer Electronics
Portable Media Player Market
Consumer Electronics
Home Entertainment Devices Market
Consumer Electronics
Sleep Headphones Market
Consumer Electronics
UAE Consumer Electronics Market
Consumer Electronics
Tablet Market
Consumer Electronics
Phone Tripod Market
Consumer Electronics
Gaming Laptops and Desktops Market
Consumer Electronics
Asia-Pacific Mobile Phone Accessories Market