
 United States Eyewear Market | 2026-2036
United States Eyewear Market Size, Share, and Industry Trends Forecast 2026-2036
United States Eyewear Market Intelligence
Premium progressive lens specifications is unwinding across the United States Eyewear Market as consumers trade up from basic bifocals. Luxottica Retail controls the largest brick-and-mortar footprint through LensCrafters and Pearle Vision banners. Warby Parker leverages direct-to-consumer distribution to undercut traditional optical markups. National Vision Holdings, Inc. anchors value-priced segments through Walmart Inc. and Sam's Club locations.
United States Eyewear encompasses vision correction devices, sun protection optics, and occupational safety lenses fabricated from plastic, metal, glass, or polycarbonate substrates, with prescription accuracy measured in diopter increments and impact resistance rated under ANSI Z87.1 for industrial applications. Prescription Glasses generate the deepest revenue pool due to recurring exam-driven replacement cycles, while Contact Lenses capture above-average margins through subscription replenishment models. Sunglasses exhibit seasonal concentration in coastal states but retain year-round volume through fashion-oriented polycarbonate frames.
FDA medical device regulations govern contact lens safety and marketing claims, while ANSI Z80 standards define prescription lens tolerances, and state-level optometry boards control exam frequency and telehealth expansion. These overlapping frameworks elevate compliance costs for new entrants but protect incumbent service networks. Stakeholders must monitor state legislation around online prescription verification and scope-of-practice battles between optometrists and online retailers.
Market Dynamics
The United States Eyewear Market is experiencing structural pressure from the aging baby-boomer demographic, which is accelerating demand for progressive lenses and presbyopia-correcting interventions while simultaneously compressing replacement cycles for traditional single-vision prescriptions.
Growth Catalysts
- Telehealth expansion:State-level optometry boards in California and Florida have relaxed remote prescription verification protocols, enabling digital-first retailers to capture exam-driven lens replacement demand without physical clinic infrastructure.
- ANSI Z87.1 workplace mandates:OSHA enforcement of industrial eye protection standards across manufacturing and construction sectors is institutionalizing recurring safety eyewear procurement programs with defined replacement schedules.
- Polycarbonate substrate adoption:Lightweight impact-resistant lens materials are displacing glass and conventional plastic in both prescription and plano sunwear categories, reducing breakage returns and enabling thinner high-index fabrications.
Market Restraints
- EssilorLuxottica supply concentration:Vertical integration of lens casting, coating, and frame manufacturing within a single holding structure limits price negotiation leverage for independent optical retailers and regional chains.
- Acetate and metal input volatility:Italian and Chinese acetate sheet suppliers face petrochemical feedstock cost swings that transmit unpredictably into frame wholesale pricing, compressing margin visibility for distributors.
- FDA Class II device pathways:Extended premarket notification timelines for novel contact lens materials and myopia-control optical designs delay revenue recognition for R&D-intensive manufacturers by 18-36 months.
Strategic Opportunities
- Myopia management protocols:Orthokeratology and multifocal soft lens fitting for pediatric populations represents an underpenetrated clinical service layer with recurring replacement economics distinct from standard vision correction.
- Blue-light filtering coatings:Digital device exposure concerns among remote workers in Texas and Washington tech corridors are creating discretionary upgrade demand for anti-fatigue lens treatments without prescription changes.
- Subscription replenishment models:Direct-to-consumer daily disposable contact lens auto-ship programs are capturing younger wearer cohorts before they establish loyalty with brick-and-mortar optical providers.
Industry Challenges
- Optician training pipeline gaps:Community college optical technology programs in the Midwest and Southeast face enrollment declines, constraining skilled labor availability for independent practice expansion.
- Electronic health record integration:Small optical practices struggle with HIPAA-compliant interoperability between refractive measurement devices, insurance verification systems, and lens laboratory order platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Eyewear Market |
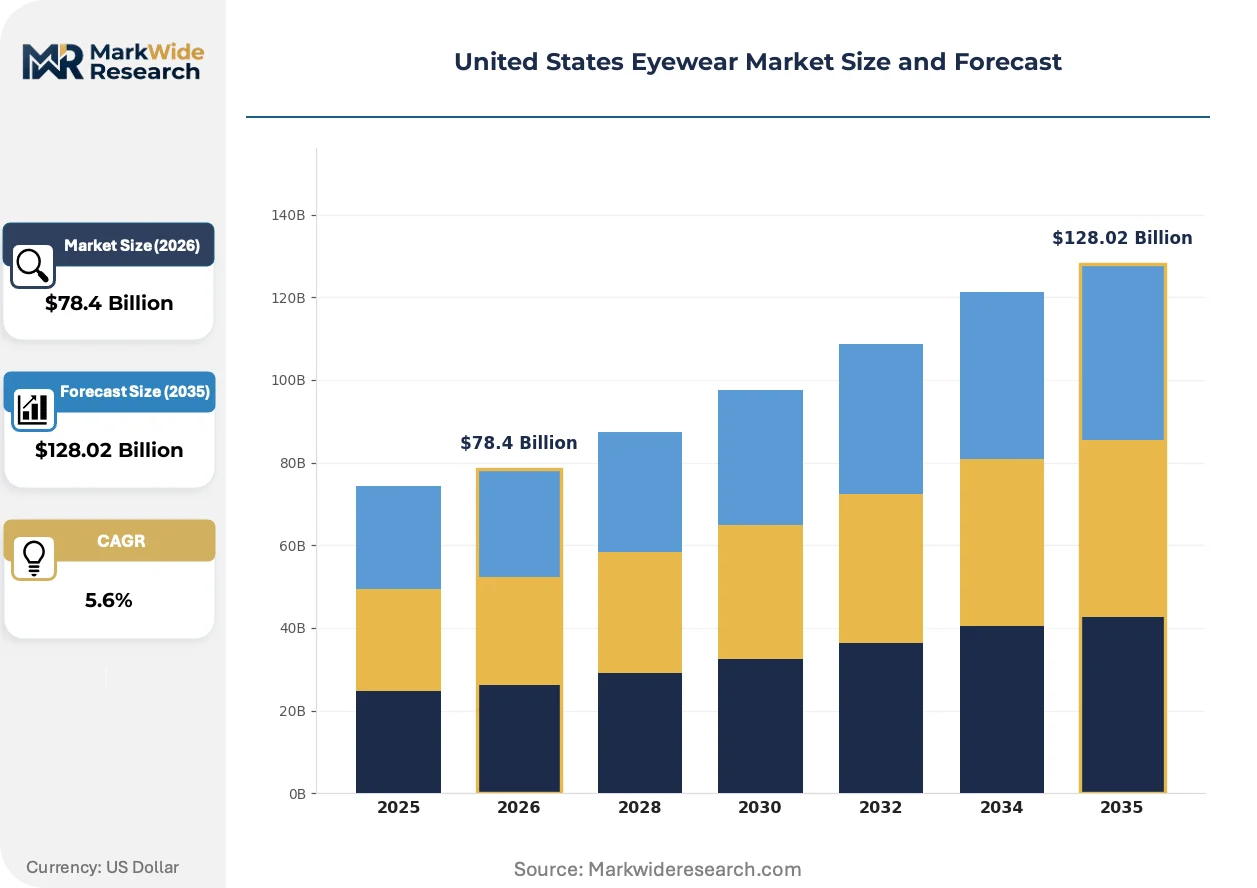
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $128.02 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Prescription Glasses, Sunglasses, Contact Lenses, Safety Glasses End User: Children, Adults, Senior Citizens, Athletes Material: Plastic, Metal, Glass, Polycarbonate Distribution Channel: Optical Stores, Online Retail, Supermarkets, Specialty Stores |
| Companies Covered | EyeCare Partners LLC, MyEyeDr., Luxottica Retail, AEG Vision, Visionworks of America, Inc., Walmart Inc., Costco Optical, Warby Parker, National Vision Holdings, Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Eyewear Market Strategic Shifts & Innovations
Digital measurement technologies and biometric customization are compressing the traditional optical supply chain, eliminating multiple fitting appointments while raising precision expectations for lens centration and frame personalization.
Freeform digital surfacing equipment is miniaturizing from industrial lab installations to in-store desktop units, enabling same-day progressive lens production at select retail locations. Regional optical chains in Arizona and Nevada are deploying these systems to differentiate against e-commerce competitors with immediate fulfillment. The technology is compressing the traditional wholesale lab intermediary layer and capturing margin previously allocated to centralized fabrication networks.
FDA guidance documents on 3D-printed medical devices are clarifying quality system requirements for custom-manufactured spectacle frames and patient-specific lens geometries. Additive manufacturing equipment suppliers must now demonstrate biocompatibility validation protocols equivalent to conventional injection molding processes. Specialty frame fabricators in California and New York are responding by establishing captive ISO 13485 quality management systems ahead of anticipated enforcement actions.
Employer-sponsored vision benefit designs are unbundling frame allowances from lens coverage, creating separate reimbursement ceilings that steer members toward value-priced retailers. Large self-insured employers in the manufacturing and logistics sectors are contracting with national vision plan administrators to restrict out-of-network optical spending. This procurement pattern is most visible in Ohio and Pennsylvania, where industrial employer density sustains narrow network vision plan participation rates above national averages.
United States Eyewear Market Segmentation
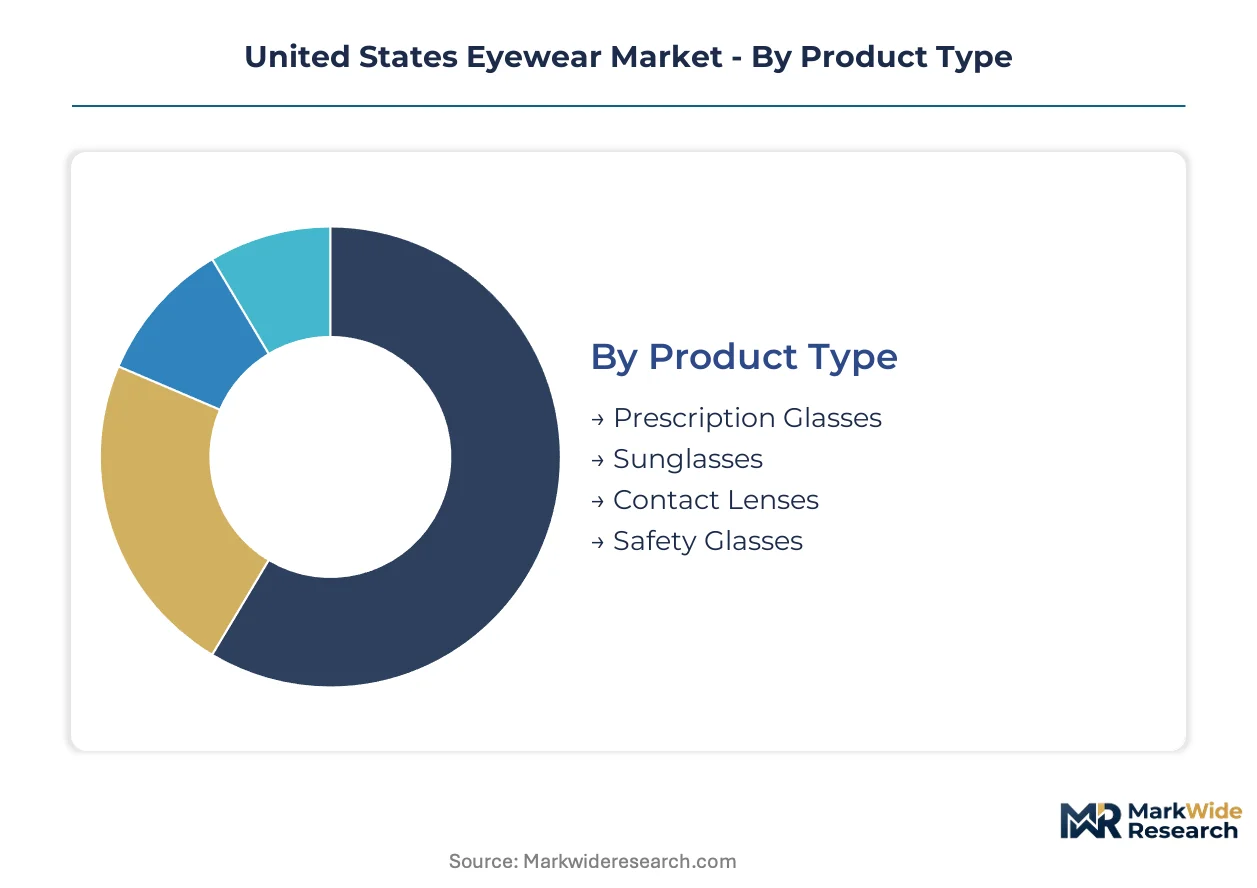
Segmentation in the United States Eyewear Market reveals distinct procurement patterns across age cohorts and material preferences. Understanding these divisions enables targeted positioning against telehealth-enabled competitors and vertically integrated retail networks.
Product Type:
Domestic consumption dominates across all product categories, with limited export activity given the prescription-driven nature of core demand.
- Prescription Glasses:Fabricated from plastic, metal, or polycarbonate substrates with diopter-precision surfacing. California and Florida metro corridors sustain the deepest replacement cycles as aging populations drive progressive lens upgrades.
- Sunglasses:Seasonal volume concentrates in coastal states, though fashion-oriented polycarbonate frames retain year-round demand. Planar sun protection competes against prescription-integrated photochromic alternatives.
- Contact Lenses:FDA Class II medical device classification governs material safety and marketing claims. Subscription replenishment models capture younger wearer cohorts before brick-and-mortar loyalty forms.
- Safety Glasses:ANSI Z87.1-rated impact resistance for industrial applications. OSHA workplace mandates across manufacturing and construction sectors institutionalize recurring procurement programs.
Prescription Glasses holds the largest share; momentum sits with Contact Lenses.
End User:
Cost tier stratification separates premium clinical services from value-priced retail channels across demographic groups.
- Children:Myopia management protocols including orthokeratology and multifocal soft lens fitting represent an underpenetrated clinical service layer with recurring replacement economics.
- Adults:Digital device exposure concerns in Texas and Washington tech corridors drive discretionary demand for blue-light filtering coatings without prescription changes.
- Senior Citizens:Progressive lens specifications are displacing basic bifocals as the baby-boomer demographic ages. Dense retirement migration to Florida and Arizona sustains optical service expansion.
- Athletes:Lightweight polycarbonate and impact-resistant frame designs dominate. Prescription sports goggles face competition from contact lens-plus-protective-eyewear combinations.
Senior Citizens command the deepest revenue pool; Children offer the steepest expansion trajectory.
Material:
Supply concentration for acetate sheet and metal alloys creates input cost volatility that transmits unpredictably into frame wholesale pricing.
- Plastic:Conventional CR-39 and high-index formulations remain cost-competitive for standard prescriptions. Community college optical technology program enrollment declines in the Midwest constrain skilled fabrication labor.
- Metal:Titanium and stainless steel alloys dominate premium frame segments. Italian and Chinese supplier concentration limits price negotiation leverage for independent retailers.
- Glass:Heaviest substrate with superior optical clarity but declining share due to breakage risk and weight disadvantages. Retained in specialty high-prescription applications.
- Polycarbonate:Lightweight impact-resistant material displacing glass and conventional plastic across prescription and plano categories. Freeform digital surfacing enables thinner high-index fabrications.
Plastic retains volume leadership; Polycarbonate is climbing the fastest.
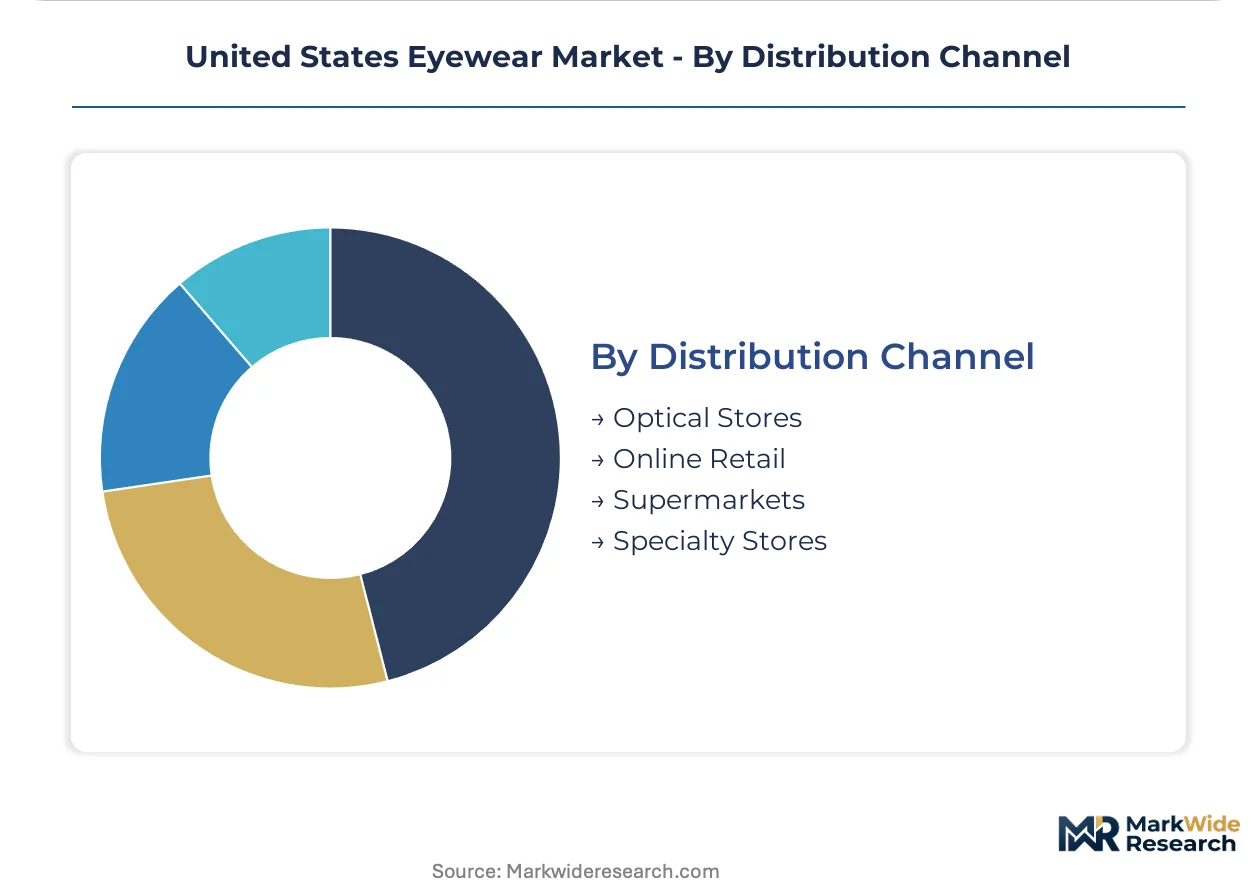
Distribution Channel:
Channel selection directly determines margin capture against Luxottica Retail's brick-and-mortar dominance and Warby Parker's direct-to-consumer undercutting.
- Optical Stores:LensCrafters and Pearle Vision banners control the largest physical footprint. Same-day progressive lens production via in-store freeform surfacing differentiates against e-commerce competitors.
- Online Retail:State-level optometry board relaxation of remote prescription verification in California and Florida enables digital-first capture of exam-driven replacement demand.
- Supermarkets:Walmart Inc. and Sam's Club locations anchor value-priced segments through National Vision Holdings partnerships. Narrow network vision plan designs steer members toward these channels.
- Specialty Stores:Employer-sponsored benefit unbundling of frame allowances from lens coverage creates separate reimbursement ceilings. Self-insured manufacturers in Ohio and Pennsylvania sustain above-average participation rates.
Optical Stores maintain the largest share; Online Retail is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States Eyewear Market operates with minimal export activity given prescription-driven demand, while coastal states and retirement corridors concentrate procurement volume. Domestic production serves regional optical networks with limited cross-border trade in finished frames or surfaced lenses.
California
Tech corridor remote workers in Silicon Valley and San Francisco generate discretionary demand for blue-light filtering coatings without prescription changes. State-level optometry boards have relaxed remote prescription verification protocols, enabling digital-first retailers to capture exam-driven replacement demand. Los Angeles and San Diego sustain fashion-oriented polycarbonate frame volume through year-round sun protection needs.
Florida
Dense retirement migration sustains the deepest progressive lens replacement cycles as aging populations displace basic bifocals. OSHA workplace mandates across Tampa and Orlando construction sectors institutionalize recurring ANSI Z87.1 safety eyewear procurement. Miami optical service expansion concentrates on presbyopia-correcting interventions for senior citizens.
Texas
Austin and Dallas tech corridors drive anti-fatigue lens treatment upgrades among digital device-intensive workforces. Employer-sponsored vision benefit unbundling steers manufacturing and logistics sector employees toward narrow network retailers. Houston's industrial employer density sustains above-average safety eyewear participation rates.
New York Metro
Fashion-forward polycarbonate frame demand concentrates in Manhattan and Brooklyn retail corridors with distinct seasonal concentration patterns. FDA medical device regulations govern contact lens distribution through established clinical service networks. Specialty frame fabricators in the region are establishing captive ISO 13485 quality management systems ahead of anticipated enforcement actions on 3D-printed devices.
Arizona
Regional optical chains deploy in-store freeform digital surfacing systems to differentiate against e-commerce competitors with same-day progressive lens production. Phoenix and Tucson retirement communities accelerate presbyopia-correcting intervention demand. Community college optical technology program enrollment constraints in the broader Southwest limit skilled labor availability for independent practice expansion.
United States Eyewear Market Key Industry Players
Concentration sits with vertically integrated retail-laboratory combinations and direct-to-consumer challengers. The market structure tiered across premium clinical services, mass-market retail partnerships, and digital-native distribution models. Three archetypes dominate: brick-and-mortar banners with captive fabrication networks, value-priced retail alliances with big-box anchors, and subscription-enabled direct-to-consumer platforms. Competitive moves center on same-day production capability deployment and telehealth-enabled prescription capture.
Within the brick-and-mortar tier, Luxottica Retail and National Vision Holdings, Inc. exemplify divergent scale strategies. Warby Parker occupies a position as the direct-to-consumer archetype, leveraging remote verification protocols to undercut traditional optical markups. These three anchors represent the competitive vectors reshaping channel economics.
| Leading Market Players |
|---|
| EyeCare Partners LLC |
| MyEyeDr. |
| Luxottica Retail |
| AEG Vision |
| Visionworks of America, Inc. |
| Walmart Inc. |
| Costco Optical |
| Warby Parker |
| National Vision Holdings, Inc. |
| Others |
Cost & Logistics Intelligence
EssilorLuxottica's captive lens casting and coating capacity anchors price floors across prescription and sunwear categories, compressing margin negotiation leverage for independent optical retailers while institutionalizing three-tier pricing stratification across premium, standard, and economy levels.
Pricing Analysis
Industrial OEM buyers anchor subscription replenishment pricing for daily disposable contact lenses, with price differentiation driven by FDA Class II certification tier and volume scale commitments. Cost compression in value-priced retail channels is intensifying because narrow network vision plan designs steer members toward Walmart and Sam's Club locations. Price-sensitive procurement concentrates among self-insured manufacturing employers in Ohio and Pennsylvania, while premium clinical services exhibit lowest sensitivity due to presbyopia-correcting intervention stickiness.
Supply Chain Analysis
Italian acetate sheet suppliers and Chinese metal alloy foundries underwrite frame manufacturing input concentration, with petrochemical feedstock volatility transmitting unpredictably into wholesale pricing. Raw material dependencies center on titanium alloys, stainless steel, and polycarbonate resin substrates. Single-source vulnerability concentrates in Luxottica's vertical control over lens casting and coating. Distribution runs through captive retail-laboratory combinations, direct-to-consumer platforms, and big-box anchor partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
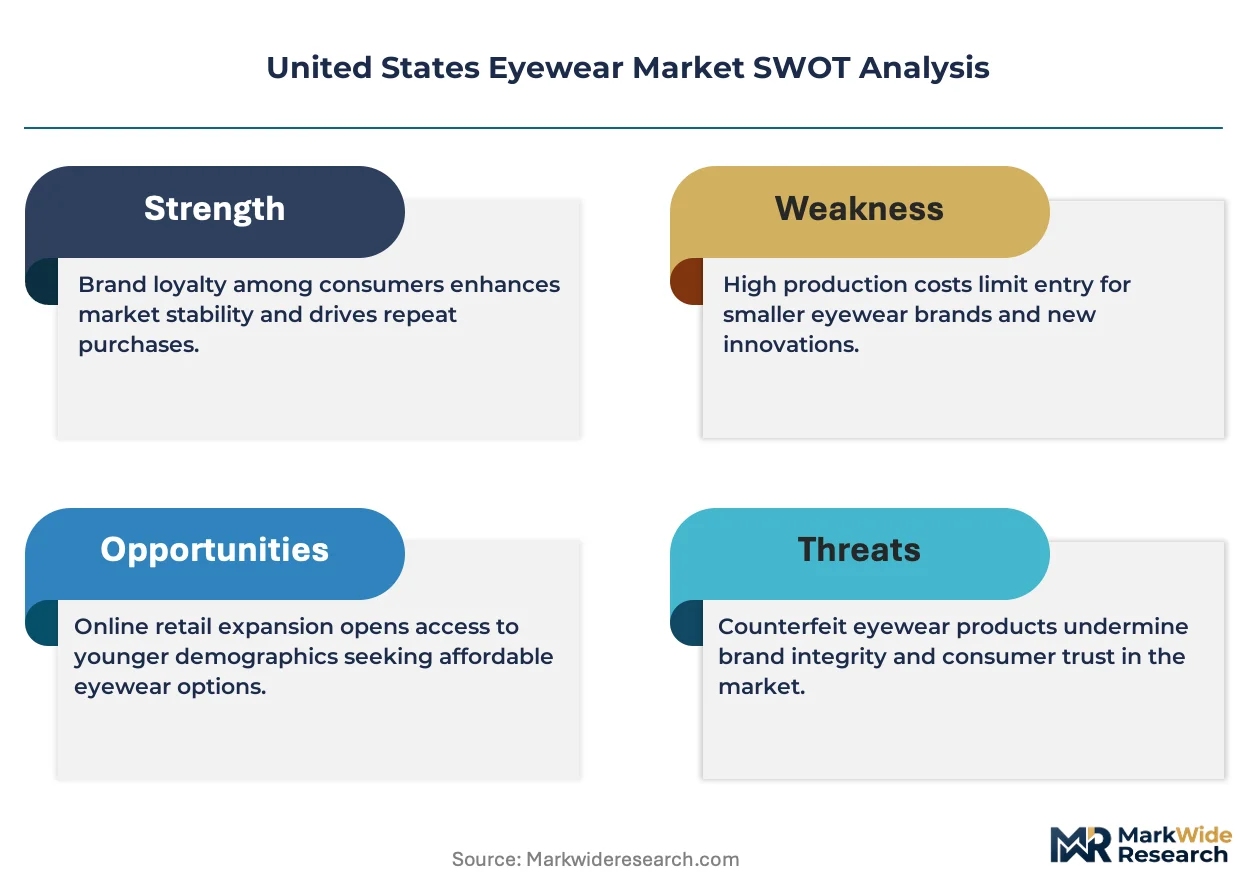
Telehealth-enabled prescription verification and in-store freeform digital surfacing represent converging technological inflections disrupting traditional optical economics. Stakeholders must position against these vectors to capture recurring replacement demand and same-day fulfillment premiums.
For Market Incumbents: Shield brick-and-mortar loyalty through immediate progressive lens production deployment at select retail locations, compressing fulfillment timelines against Warby Parker's remote verification model. Deepen upstream control over lens casting capacity to defend margin position against EssilorLuxottica supply concentration. Channel control through narrow network vision plan contracting remains critical in manufacturing-dense geographies.
For New Entrants and Emerging Players: Anchor in pediatric myopia management protocols, where orthokeratology and multifocal soft lens fitting represent underpenetrated clinical services with recurring replacement economics distinct from commoditized vision correction. Target Texas and Washington tech corridors for blue-light filtering coating upgrades among remote workforces. Go-to-market through employer-sponsored benefit unbundling creates reimbursement ceiling arbitrage.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among subscription-enabled daily disposable contact lens platforms capturing younger wearer cohorts before brick-and-mortar loyalty forms. Long-term viability favors regional optical chains deploying in-store freeform surfacing systems to differentiate against e-commerce competitors. Watch state-level optometry board relaxation of remote prescription verification protocols as inflection indicator for digital-first capture acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| In-Store Freeform Surfacing Deployment | Same-day progressive lens production at Arizona and Nevada retail locations compresses e-commerce fulfillment advantages. |
| Subscription Replenishment Model Launch | Auto-ship daily disposable contact lens programs capture younger cohorts before brick-and-mortar loyalty forms. |
| Narrow Network Vision Plan Contracting | Self-insured Ohio and Pennsylvania manufacturers steer members toward value-priced retail channels. |
| Pediatric Myopia Management Protocol Development | Orthokeratology and multifocal soft lens fitting creates underpenetrated clinical service layer with recurring economics. |
| ISO 13485 Quality System Establishment | California and New York frame fabricators prepare for anticipated FDA enforcement on 3D-printed medical devices. |
Research Approach
Findings reconcile primary fieldwork against secondary review of FDA 510(k) filings, ANSI Z80 and Z87.1 standard documentation, state optometry board regulatory records, and optical industry trade data. Interviews with independent optometrists, optical laboratory operations directors, vision plan administrators, and frame manufacturing procurement leads inform demand-side and supply-side validation. Bottom-up prescription volume modeling triangulates against top-down retail channel revenue aggregation.
Segmentation dimensions modeled include product type, end user demographic, material substrate, and distribution channel across the projection horizon. CAGRs derive from replacement cycle analysis, demographic cohort sizing, and channel shift elasticity parameters. Forecast inputs incorporate telehealth adoption curves, ANSI workplace mandate enforcement intensity, and polycarbonate substrate displacement rates from glass and conventional plastic.
Decision-makers should treat outputs as directional under stable FDA Class II device pathway timelines and state-level scope-of-practice regulations; material deviation would warrant model refresh. Practitioners should keep alternative scenarios live as online prescription verification legislation and 3D-printed medical device enforcement actions evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Eyewear
Latin America Eyewear Market
Eyewear
Face and Ear Bow Market
Eyewear
Smart Sunglasses Market
Eyewear
Goggles Market
Eyewear
Plano Sunglasses Market
Eyewear
Wooden Eyewear Market
Eyewear
North America Eyewear Market
Eyewear
Sunglasses Market
Eyewear
Anti-Blue Light Glasses Market
Eyewear
Blue Light Glasses Market
Eyewear
Smart Eyewear Market
Eyewear
Middle East Eyewear Market
Eyewear
Europe Eyewear Market
Eyewear
Polarized Sunglasses Market
Eyewear
3D Printing in Eyewear Market
Eyewear
China Anti-Blue Ray Myopia Lenses Market