
 Global Home Audio System Market | 2026-2036
Global Home Audio System Market Size, Share, and Industry Trends Forecast 2026-2036
Global Home Audio System Market Analysis
China is narrowing its cost advantage in speaker driver and amplifier module production as Southeast Asian facilities scale assembly lines for export markets. Samsung Electronics leverages captive semiconductor supply to control chipset costs for its soundbar portfolio. Bose Corporation sustains premium positioning through proprietary acoustic engineering and direct-to-consumer channel dominance. Sony Corporation anchors high-resolution audio credibility with proprietary codec ecosystems that lock in enthusiast segments.
Home audio systems encompass electro-acoustic equipment designed for domestic sound reproduction, typically spanning frequency responses from 20 Hz to 20 kHz through combinations of transducers, enclosures, and signal-processing electronics. Manufacturing emphasizes precision-molded cones, neodymium magnets, and DSP-tuned crossovers to achieve flat response curves and spatial imaging accuracy for music and cinema applications. Soundbar configurations lead volume shipments due to television audio upgrade cycles, while smart technology integration is capturing margin pools through voice-assistant compatibility and multi-room streaming protocols. Wireless connectivity dominates new product introductions as Bluetooth and Wi-Fi standards displace legacy wired installations in residential environments.
The EU F-Gas Regulation and REACH chemical restrictions constrain enclosure materials and refrigerants used in climate-controlled production facilities, while the FCC in the United States enforces RF emission limits on wireless transmitters embedded in smart speakers. Japan's METI sets efficiency benchmarks that shape power-supply designs for products exported across Asia. Stakeholders must monitor evolving interoperability mandates and energy-labeling schemes that will determine which product architectures qualify for mainstream retail placement.
Market Dynamics
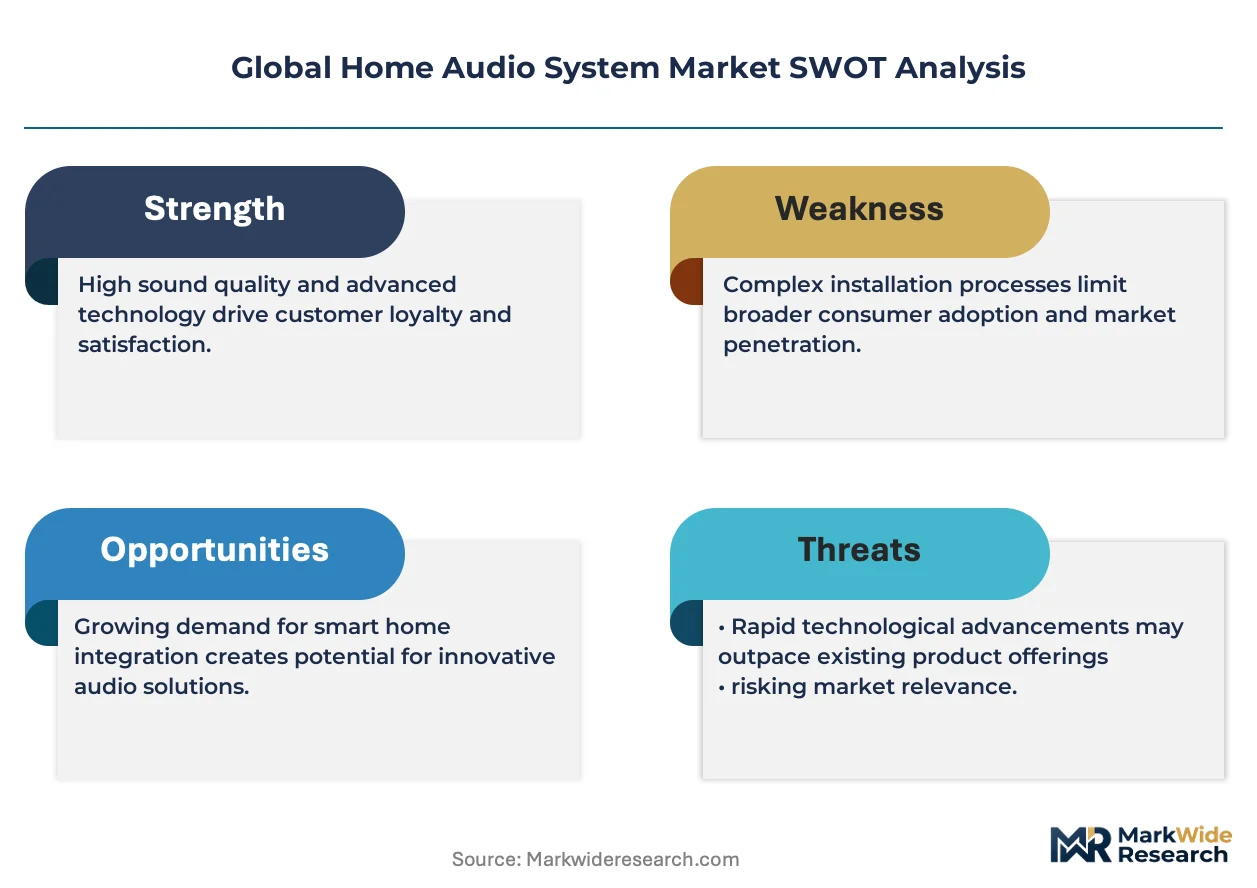
The residential upgrade cycle for television audio equipment is compressing replacement timelines while smart-home interoperability mandates force chipset architecture redesigns across the supply base.
Growth Catalysts
- EU Ecodesign Directive:Energy-efficiency mandates accelerate replacement of legacy amplifier designs with Class-D and GaN-based power stages in European retail channels.
- Voice-assistant integration:Smart speaker compatibility requirements drive microcontroller and DSP content increases in soundbar and bookshelf configurations.
- Neodymium magnet supply:China's dominance in rare-earth processing enables cost-competitive driver motor assemblies for mid-market wireless systems.
Market Restraints
- Neodymium price volatility:Rare-earth export quota fluctuations from Chinese state planners inject cost uncertainty into driver bill-of-materials.
- EU F-Gas Regulation:Refrigerant restrictions on climate-controlled production facilities raise enclosure manufacturing costs for European-sourced products.
- Bluetooth codec fragmentation:Proprietary low-latency protocols from ecosystem vendors create interoperability friction for multi-brand home installations.
Strategic Opportunities
- India residential construction:Urban housing stock expansion creates first-time buyer pools for entry-level soundbar and satellite speaker packages.
- Matter protocol adoption:Cross-platform smart home standardization reduces engineering overhead for multi-assistant product variants.
- Direct-to-consumer channels:Bypassing traditional audio-visual retail layers captures margin pools previously allocated to distributor networks.
Industry Challenges
- Acoustic engineering talent:DSP tuning and spatial audio algorithm development skills concentrate among a limited pool of specialized practitioners.
- RF certification timelines:FCC and CE marking procedures for Wi-Fi 6E and emerging 6 GHz band implementations extend product launch schedules.
- Legacy wired infrastructure:Existing in-wall speaker cabling in premium residential stock complicates wireless retrofit positioning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Home Audio System Market |
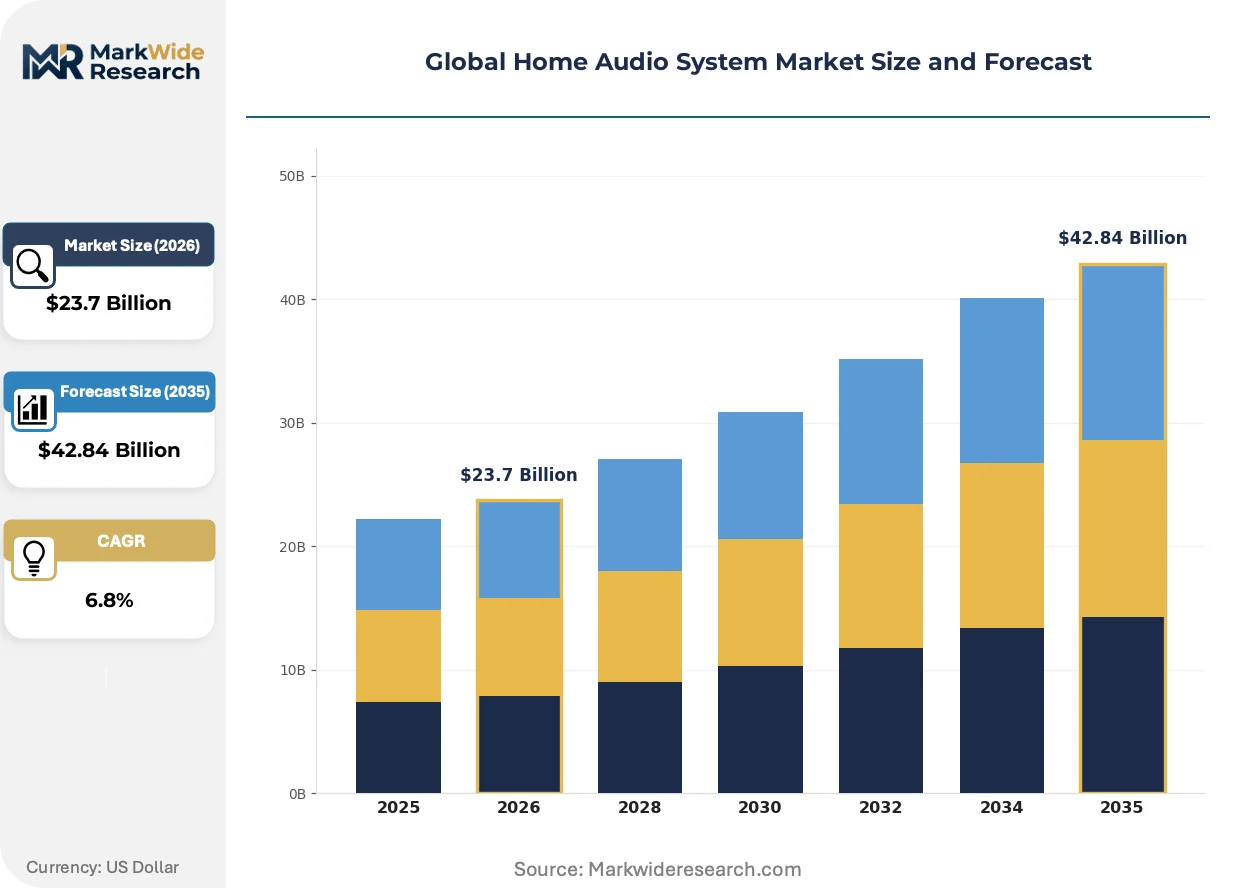
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $42.84 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Soundbar, Home Theater, Stereo System, Bluetooth Speaker Technology: Wired, Wireless, Smart, Digital End User: Residential, Commercial, Automotive, Professional Distribution Channel: Online Retail, Specialty Stores, Hypermarkets, Direct Sales |
| Companies Covered | Samsung Electronics, Bose Corporation, Sonos, Inc., Harman International, Sony Corporation, LG Electronics, Panasonic Holdings Corporation, Yamaha Corporation, JVCKENWOOD Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Home Audio System Market Emerging Trajectories
Wireless protocol maturation and computational audio processing are redrawing competitive boundaries between traditional loudspeaker manufacturers and consumer electronics platforms.
Beamforming microphone arrays and neural-network noise suppression are collapsing the distinction between dedicated home theater processors and all-in-one soundbar architectures. Residential buyers in North American and Western European markets now expect voice control and room-correction capabilities as baseline features rather than premium add-ons. This compression eliminates standalone AV receiver categories below mid-tier price bands.
Japan's METI efficiency benchmarks for standby power consumption are forcing power-supply redesigns across products exported to Asian markets. Manufacturers must integrate zero-watt standby circuits and adaptive voltage scaling to maintain retail placement eligibility. High-resolution audio amplifier segments face the steepest engineering cost increases under these mandates.
Streaming service bundling is altering hardware procurement patterns as Spotify, Apple Music, and Amazon Music tie subscription trials to device purchases. Big-box retailers and direct channels now compete on exclusive content offers rather than specification differentiation alone. Germany and the United Kingdom exhibit the most pronounced shift toward subscription-tied hardware transactions.
Global Home Audio System Market Segmentation
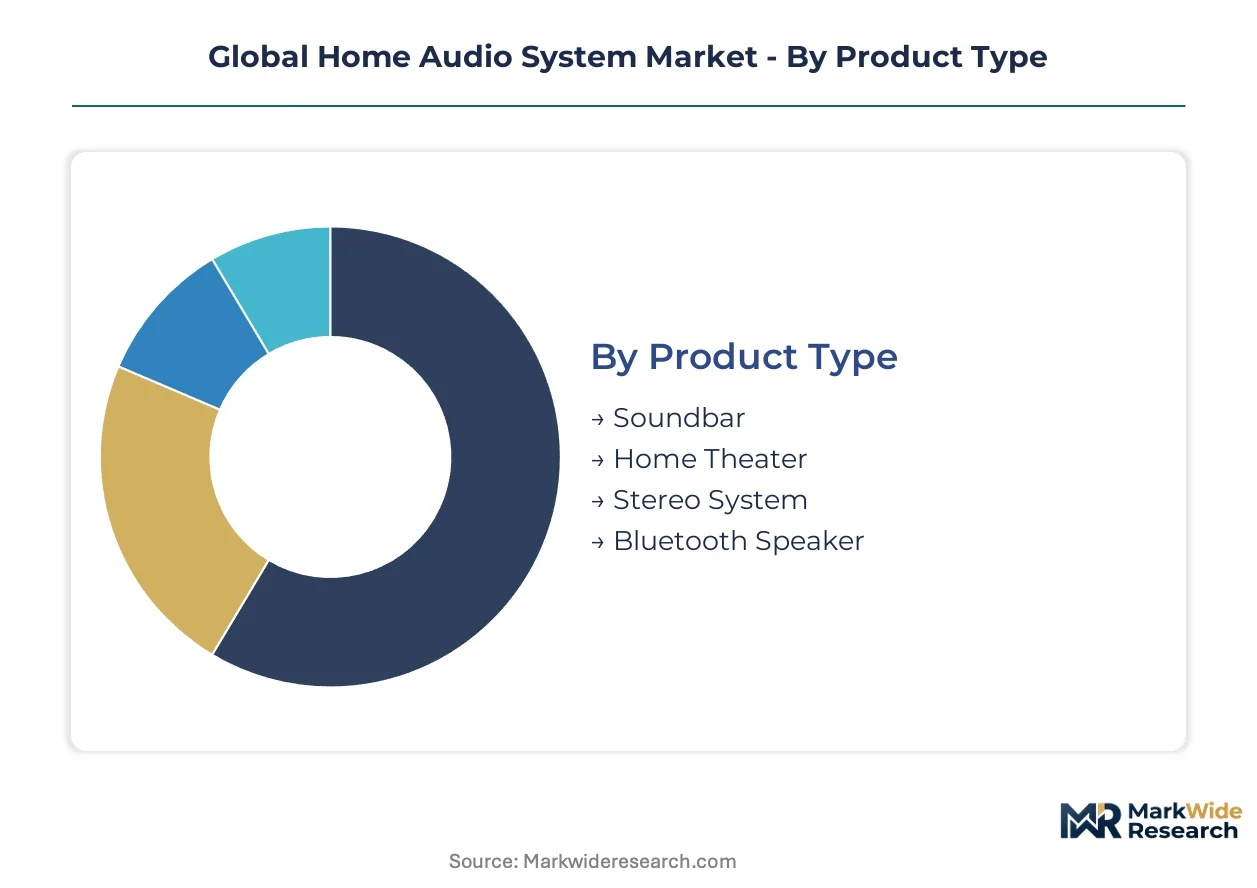
Segmentation in home audio systems reveals divergent service intensity profiles across product architectures. Soundbar deployments demand minimal installation support while whole-home distributed audio requires ongoing calibration services. Manufacturers structure warranty terms and channel economics around these support burden differentials.
Product Type:
After-sales service intensity varies dramatically across physical form factors, with enclosure complexity and driver count determining field service requirements.
- Soundbar:Single-enclosure designs with integrated amplifiers minimize installation overhead. Residential television upgrade cycles in Germany and the United States concentrate replacement demand, though slim profiles limit acoustic output versus discrete speaker arrays.
- Home Theater:Multi-channel configurations with subwoofer modules and surround satellites require room-specific calibration and cable management. Professional installation services in premium residential developments in China generate recurring revenue streams for integrators.
- Stereo System:Two-channel bookshelf or floor-standing configurations appeal to enthusiast segments prioritizing source component flexibility.
- Bluetooth Speaker:Portable battery-powered units target outdoor and mobile use cases with minimal support infrastructure.
By volume, Soundbar leads. By growth pace, Home Theater is ahead.
Technology:
Cost tier stratification separates legacy architectures from semiconductor-intensive smart platforms, with bill-of-materials spreads exceeding 300 percent between entry wired and flagship smart configurations.
- Wireless:Bluetooth and Wi-Fi protocols dominate new residential installations, eliminating in-wall cabling requirements. FCC certification for 2.4 GHz and 5 GHz bands adds regulatory overhead that constrains vendor entry in United States markets.
- Smart:Voice-assistant integration with microphone arrays and cloud connectivity commands premium positioning. DSP content for far-field voice recognition and multi-room synchronization drives microcontroller costs toward mid-tier amplifier levels.
- Wired:Analog and digital interconnects persist in professional monitoring and legacy residential infrastructure.
- Digital:Pure digital amplification with USB or optical inputs serves computer-audio and gaming segments.
By installed base, Wireless dominates. By margin expansion, Smart is climbing the fastest.
End User:
Application context determines acoustic performance requirements, with residential cinema use tolerating broader frequency response variance than professional monitoring applications.
- Residential:Living room and dedicated home cinema installations represent the volume anchor, with streaming service integration now baseline. Urban housing stock expansion in India creates first-time buyer pools for entry-level soundbar packages.
- Professional:Recording studios and broadcast facilities demand flat response curves and calibrated listening environments. Japan's METI efficiency benchmarks shape power-supply designs for products exported across Asian markets.
- Commercial:Retail and hospitality background music systems prioritize reliability over fidelity.
- Automotive:Cabin-specific tuning and space constraints drive specialized enclosure designs.
By unit shipments, Residential leads. By specification stringency, Professional shows the steepest expansion trajectory.
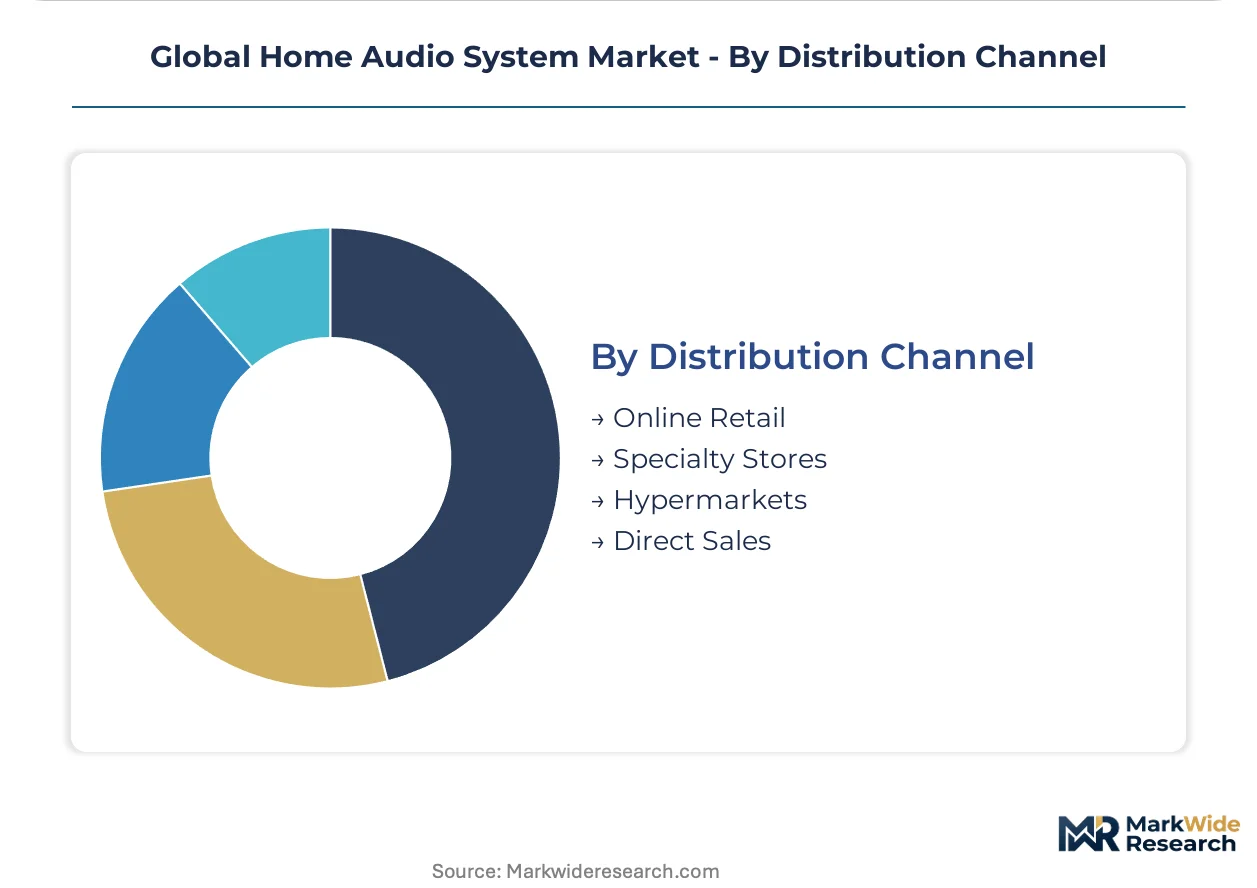
Distribution Channel:
Channel margin structures reflect inventory carrying costs and technical consultation requirements, with direct sales capturing pools previously allocated to distributor networks.
- Online Retail:E-commerce platforms aggregate comparison shopping and subscription bundling, with Amazon and regional equivalents displacing traditional audio-visual retail layers. Germany and the United Kingdom exhibit pronounced shifts toward subscription-tied hardware transactions.
- Specialty Stores:Demonstration rooms and trained staff justify premium positioning for high-resolution audio configurations. Acoustic engineering talent concentrates among limited pools of specialized practitioners that these channels employ.
- Hypermarkets:Mass merchandisers move volume SKUs with minimal sales assistance.
- Direct Sales:Manufacturer-owned channels bypass retail markups for enthusiast segments.
By transaction volume, Online Retail leads. By customer lifetime value, Direct Sales is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Shenzhen anchors Asia-Pacific electronics export capacity, while Rotterdam's container terminals handle European distribution for finished audio equipment. These maritime gateways shape inventory velocity and regional pricing power for manufacturers serving consumer markets.
United States
Residential television upgrade cycles concentrate demand in Texas and California metro corridors. FCC RF emission limits for Wi-Fi 6E and 6 GHz wireless transmitters extend product certification timelines. Austin's technology corridor hosts engineering operations for voice-assistant integration platforms.
Germany
EU Ecodesign Directive mandates compress replacement timelines for legacy amplifier designs in Berlin and Munich retail channels. REACH chemical restrictions constrain enclosure materials sourcing for climate-controlled production. Bavaria's industrial clusters specialize in precision-molded driver components for premium soundbar configurations.
China
Neodymium magnet supply dominance enables cost-competitive driver motor assemblies for mid-market wireless systems. MIIT efficiency benchmarks and GB standards shape power-supply designs for domestic and export markets. The Yangtze River Delta concentrates final assembly capacity for Bluetooth and smart-enabled speaker exports.
India
Urban housing stock expansion in Maharashtra and Karnataka creates first-time buyer pools for entry-level soundbar packages. BIS certification requirements for electronic goods add regulatory lead time for new product introductions. Delhi-NCR retail corridors show pronounced shifts toward subscription-tied hardware transactions.
Japan
METI standby power consumption benchmarks force zero-watt standby circuit integration in products exported across Asian markets. High-resolution audio amplifier segments face steep engineering cost increases under these mandates. Osaka-Kobe industrial zones maintain specialized acoustic engineering talent pools for DSP tuning applications.
Global Home Audio System Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in driver and amplifier module supply. The vendor base stratifies across captive semiconductor houses, acoustic engineering boutiques, and scale-driven consumer electronics platforms. Three archetypes dominate: ecosystem-locked platforms with voice-assistant integration, premium acoustic specialists with direct-to-consumer channels, and diversified electronics conglomerates with vertical component control. Competitive moves concentrate on strategic partnerships for multi-room protocol licensing and backward integration into rare-earth magnet sourcing.
Among diversified electronics conglomerates, Samsung Electronics and Sony Corporation occupy positions shaped by captive semiconductor supply and proprietary codec ecosystems respectively. Bose Corporation exemplifies the premium acoustic specialist archetype through direct-to-consumer channel dominance. These three anchors represent divergent responses to voice-assistant integration mandates and wireless protocol standardization pressures.
| Leading Market Players |
|---|
| Samsung Electronics |
| Bose Corporation |
| Sonos, Inc. |
| Harman International |
| Sony Corporation |
| LG Electronics |
| Panasonic Holdings Corporation |
| Yamaha Corporation |
| JVCKENWOOD Corporation |
| Others |
Supply Flow & Price Mechanics
Rare-earth export quota volatility from Chinese state planners compresses margin buffers across mid-market wireless speaker tiers while simultaneously accelerating Southeast Asian assembly diversification. This commodity chokepoint widens spreads between entry-level Bluetooth units and GaN-equipped smart soundbars, forcing manufacturers to absorb cost swings or push premium positioning.
Pricing Analysis
Volume-discount tiering structures separate flagship smart configurations with voice-assistant integration from stripped-down wired alternatives. Price differentiation hinges on DSP content levels and FCC certification grade for Wi-Fi 6E transmitters. Cost compression in entry-tier soundbars intensifies because neodymium magnet supply uncertainty forces inventory hedging. Mass-market retailers exhibit highest price sensitivity, while direct-to-consumer channels sustain premium tolerance through acoustic engineering narratives.
Supply Chain Analysis
Export-control regimes limiting semiconductor manufacturing equipment flows to Chinese fabs concentrate advanced DSP and amplifier chip sourcing in Taiwan, South Korea, and the United States. Driver motor assemblies draw from China's rare-earth processing dominance, while enclosure molding feeds from Vietnam and Indonesia facilities. Single-source vulnerability sits with Yangtze River Delta final assembly concentration. Distribution runs through Shenzhen port exports and Rotterdam hub-and-spoke networks into European retail.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized acoustic engineering talent pools remain thinner than smart-platform integration capabilities, creating persistent bottlenecks for DSP tuning and spatial audio algorithm development. This capability asymmetry rewards firms that lock practitioner networks before protocol standardization commoditizes hardware differentiation.
For Market Incumbents: Insulate premium positioning by deepening backward integration into neodymium magnet sourcing partnerships and securing exclusive Matter protocol licensing windows before cross-platform standardization erodes ecosystem lock-in. Captive semiconductor supply, as demonstrated by Samsung Electronics' soundbar chipset control, remains the decisive margin defense against fabless entrants. For New Entrants and Emerging Players: Urban housing stock expansion across Maharashtra and Karnataka offers first-time buyer pools underserved by incumbent service infrastructure. Entry-level soundbar packages with subscription-tied hardware transactions represent the most penetrable wedge, particularly through Amazon and Flipkart channel partnerships that bypass traditional audio-visual retail layers. For Investors and Strategic Acquirers: The market sits at a protocol-transition phase that favors acoustic engineering boutiques with direct-to-consumer channel dominance over diversified electronics platforms facing voice-assistant integration mandates. Long-term viability across the projection horizon rests on DSP algorithm IP rather than assembly scale. Watch Matter certification timelines as the inflection indicator for multi-assistant product architecture consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rare-Earth Sourcing | Neodymium magnet supply partnerships with Chinese processors stabilize driver motor assembly costs. |
| Matter Protocol Certification Investment | Cross-platform smart home standardization reduces engineering overhead for multi-assistant variants. |
| Direct-to-Consumer Channel Expansion | Bose Corporation's acoustic engineering boutiques demonstrate margin capture without distributor markups. |
| GaN-Based Amplifier Architecture Migration | EU Ecodesign Directive mandates accelerate Class-D power stage replacement in European retail. |
| Voice-Assistant Platform Partnership | Amazon Alexa and Google Assistant integration requirements drive microcontroller content increases. |
Methodological Framework
Desk research of customs trade records, FCC equipment authorization databases, and EU Ecodesign compliance filings preceded structured interviews with acoustic engineering directors, smart platform integration leads, and retail category buyers across Germany, China, and the United States. Primary fieldwork with neodymium magnet procurement specialists and DSP firmware developers was cross-validated against secondary sources including MIIT efficiency benchmark disclosures and METI standby power regulations. Bottom-up bill-of-materials analysis and top-down retail audit triangulation anchored volume and value estimates.
Fixed assumptions across the modeling period include sustained rare-earth export quota regimes from Chinese state planners, continued Wi-Fi 6E band availability in major markets, and stable streaming service bundling economics. Segmentation dimensions modeled encompass product architecture, connectivity protocol, voice-assistant integration tier, and regional regulatory cluster. CAGRs were derived from replacement cycle compression rates and smart-home interoperability mandate phase-in schedules, with neodymium price volatility bands and RF certification timeline distributions as key uncertainty inputs.
Practitioners should monitor F-Gas Regulation enforcement intensity and REACH chemical restriction expansions for early signals of European manufacturing cost recalibration. Material shifts in MIIT efficiency benchmark stringency or FCC 6 GHz band allocation would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Consumer Electronics
Used and Refurbished Smartphone Market
Consumer Electronics
United States Stylus Pen Market
Consumer Electronics
Streaming Devices Market
Consumer Electronics
Industrial Hearables Market
Consumer Electronics
Europe Smart TV Market
Consumer Electronics
Pet Cameras Market
Consumer Electronics
Earphones Market
Consumer Electronics
Refurbished Electronics Market
Consumer Electronics
Universal Remote Controls Market
Consumer Electronics
Smart Aquarium Devices Market
Consumer Electronics
Global Hearable Devices Market
Consumer Electronics
North America Smart TV Market
Consumer Electronics
DVD Remote Controls Market
Consumer Electronics
Education PC Market
Consumer Electronics
United States Smart TV Market
Consumer Electronics
Sleep Headphones Market