
 Android TV Box Market | 2026-2036
Android TV Box Market Size, Share, and Industry Trends Forecast 2026-2036
Android TV Box Market Insights
Shenzhen's ODM ecosystem is recalibrating production lines toward certified Android TV OS devices as uncertified AOSP boxes face mounting platform restrictions. Google leverages its Widevine DRM and Play Services licensing to control access to premium streaming apps on certified hardware. Amazon competes through Fire OS, a forked Android variant that sustains a closed content-and-commerce loop. Xiaomi anchors volume in India and Southeast Asia through aggressive pricing on Google-certified streaming boxes.
An Android TV box is a dedicated streaming device running Android OS on ARM-based SoCs, typically featuring HDMI output, Wi-Fi or Ethernet connectivity, and codec support for H.264, H.265, and AV1 video formats, designed to deliver over-the-top video content to television displays. Streaming devices dominate unit shipments as cord-cutting households replace legacy cable boxes with app-based alternatives. The 4K HDR technology segment captures premium pricing as consumers upgrade from 1080p hardware, while custom firmware variants occupy a gray-market niche with limited app compatibility. Enterprises and hospitality represent faster-growing end-user categories as commercial deployers seek centralized device management and branded content portals.
The FCC governs radio emissions and electromagnetic compatibility for Android TV boxes sold in the United States, while the EU's REACH and RoHS frameworks restrict hazardous substances in electronics sold across member states. India's BIS certification mandate for electronics imports is tightening quality gates for uncertified streaming hardware entering through e-commerce channels. Stakeholders must monitor how platform holders tighten Android TV OS certification requirements and how regional content licensing reshapes which streaming services preload on factory firmware.

Market Dynamics
Google's tightening Widevine DRM certification requirements are restructuring competitive access to premium streaming apps, forcing Shenzhen ODMs to abandon uncertified AOSP firmware and migrate production lines toward licensed Android TV OS hardware.
Growth Catalysts
- India's BIS electronics mandate:Import quality gates are accelerating replacement cycles for legacy cable set-tops as telecom operators converge broadband and video services.
- Hospitality sector deployment:Southeast Asian hotel chains are standardizing on centralized device management platforms for in-room streaming hardware.
- AV1 codec hardware decoding:Next-generation ARM SoCs are reducing bandwidth costs for 4K HDR streaming services.
Market Restraints
- SoC supply concentration:Premium streaming chipset production clusters with Taiwan semiconductor foundries, exposing hardware vendors to allocation volatility.
- Widevine L1 certification friction:Google's hardware attestation requirements extend product development timelines by 4-6 months for uncertified ODMs.
- HDMI royalty stacking:Patent pool fees from HDMI LA and HDCP licensing add fixed cost burdens to sub-$30 retail price points.
Strategic Opportunities
- Enterprise MDM integration:Commercial deployers seek branded content portals with remote firmware management for hospitality and healthcare verticals.
- EU REACH substance restrictions:RoHS compliance leadership creates positioning advantages for certified hardware vendors in member state procurement.
- Wi-Fi 6E spectrum expansion:Unlicensed 6 GHz band support enables low-latency cloud gaming applications on streaming hardware.
Industry Challenges
- Play Services licensing complexity:Google's MADA agreements restrict hardware customization and preload partnerships for smaller ODMs.
- FCC electromagnetic compliance:Radio emission testing for Wi-Fi and Bluetooth modules extends time-to-market for new hardware designs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Android TV Box Market |
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $25.87 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Streaming Devices, Console, Digital Video Recorders, Media Players Technology: 4K HDR, 1080p, Android OS, Custom Firmware End User: Households, Educational Institutions, Enterprises, Hospitality Distribution Channel: Online Retail, Electronics Stores, Wholesale, Direct Sales |
| Companies Covered | Mecool, Google, H96 Max, UBOX, Tanix, NVIDIA, Amazon, Formuler, Xiaomi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Android TV Box Market Trends and Innovations
Platform certification requirements and codec evolution are compressing hardware replacement cycles while reshaping which firmware variants survive in retail channels.
AV1 hardware decoding is electrifying streaming efficiency. The royalty-free codec reduces bandwidth consumption by 30-50% versus H.265 for equivalent visual quality. Netflix and YouTube are prioritizing AV1 streams for compatible devices. This compression advantage is electrifying demand for Amlogic and MediaTek SoCs with dedicated AV1 decode blocks.
India's BIS certification mandate for electronics imports is tightening quality enforcement. The quality gate requires safety and interoperability testing for all streaming hardware sold through e-commerce channels. Uncertified gray-market AOSP boxes face delisting from Amazon India and Flipkart. Domestic assemblers with BIS registration are capturing shelf space from direct-import competitors.
Commercial buyers are consolidating procurement around Google-certified hardware with enterprise device management APIs. Hospitality chains and telecom operators now require remote firmware updates and kiosk-mode lockdown capabilities. This specification shift favors ODMs with GMS licensing over AOSP firmware specialists. Deployment concentration is most visible in India's hotel renovation wave and Southeast Asian co-living property developments.
Android TV Box Market Segmentation
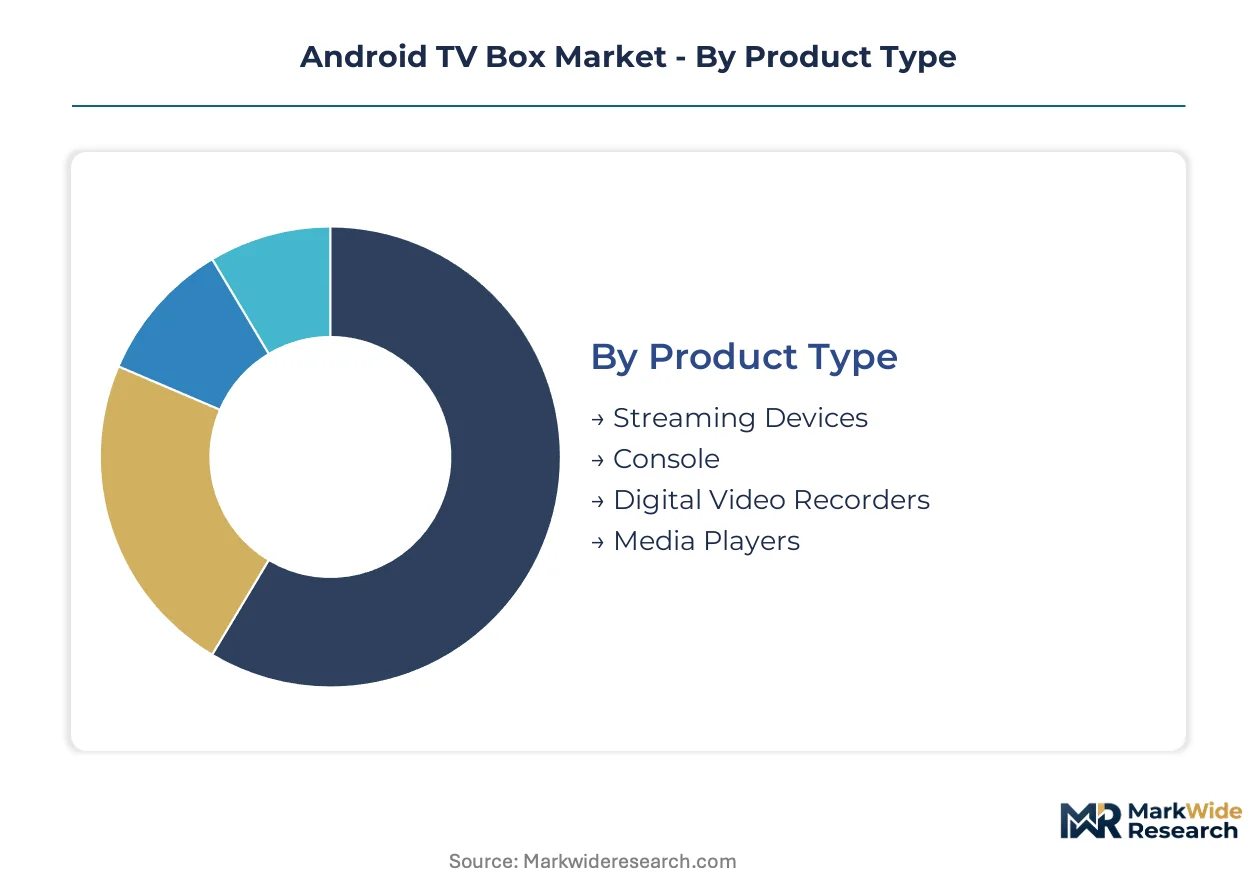
Android TV box segmentation reveals how hardware specifications, deployment contexts, and procurement channels fragment purchasing decisions across consumer and commercial buyers. Understanding these divides exposes where certified Android TV OS devices command premium positioning versus where uncertified alternatives retain footholds.
Product Type:
Volume shipments concentrate in streaming hardware while premium pricing attaches to multi-function devices with integrated storage or gaming capabilities.
- Streaming Devices:Dedicated HDMI dongles and set-top boxes running Android TV OS on ARM SoCs, typically featuring Wi-Fi 6 and AV1 decode blocks. India's telecom-cable convergence is accelerating replacement cycles for legacy cable boxes as Reliance Jio and Airtel bundle streaming hardware with broadband subscriptions.
- Console:Hybrid streaming-gaming devices with expanded RAM, USB peripheral support, and cloud gaming service integration. Southeast Asian co-living developments and gaming cafes are standardizing on these units for shared entertainment spaces, driven by GeForce Now and Xbox Cloud Gaming availability.
- Digital Video Recorders:Android-based units with integrated tuners and local storage for over-the-air or cable recording. Niche demand persists among cord-cutters seeking time-shifted broadcast content without cloud subscription fees.
- Media Players:Audio-focused Android devices with SPDIF or analog outputs for music streaming and home theater integration. Audiophile segments in Japan and Germany sustain this category despite video-centric market momentum.
Mature deployment sits with Streaming Devices. Newer deployment is concentrated in Console.
Technology:
Resolution tiers and firmware certification status create the primary cost-structure divide in hardware procurement.
- 4K HDR:Hardware with HDMI 2.1 output, HDR10+ or Dolby Vision support, and dedicated video processing engines. Hospitality chains across Thailand, Vietnam, and Indonesia are mandating 4K HDR specification for in-room streaming hardware to match guest television upgrades.
- 1080p:Entry-level chipsets with H.264 and H.265 decode, targeting price-sensitive households and secondary television installations. India's BIS enforcement is pushing uncertified 1080p AOSP boxes toward gray-market channels as Flipkart and Amazon India delist non-compliant hardware.
- Android OS:Google-certified Android TV OS devices with Widevine DRM L1, Play Services, and official app store access. Telecom operators in India and Southeast Asia require this certification for subsidized set-top deployments.
- Custom Firmware:AOSP-based variants without Google certification, relying on sideloaded applications and reduced DRM levels. Shenzhen ODMs are abandoning this segment as Netflix and Disney+ block uncertified hardware from HD streams.
Hardware refresh cycles favor 4K HDR. Volume concentration remains with Android OS certification.
End User:
Consumer households dominate unit shipments while commercial verticals command higher per-unit pricing through management platform requirements.
- Households:Individual purchasers replacing cable subscriptions with app-based streaming, prioritizing ease of setup and voice assistant integration. India's urban middle-class expansion is driving set-top replacement as broadband penetration crosses 50 million fiber connections.
- Educational Institutions:Schools and universities deploying Android TV boxes for digital signage, classroom display management, and distance learning endpoints. Budget constraints favor certified hardware with bulk pricing and centralized device management APIs.
- Enterprises:Corporate deployers seeking branded content portals, kiosk-mode lockdown, and remote firmware management for lobby displays and meeting room systems. GMS licensing with enterprise APIs commands 40-60% pricing premiums over consumer equivalents.
- Hospitality:Hotels, serviced apartments, and co-living operators standardizing on in-room streaming with property-specific content curation and guest analytics. Southeast Asian renovation waves in Bangkok, Jakarta, and Manila are accelerating procurement of managed Android TV deployments.
Installed base concentration sits with Households. Steepest expansion trajectory is concentrated in Hospitality.
Distribution Channel:
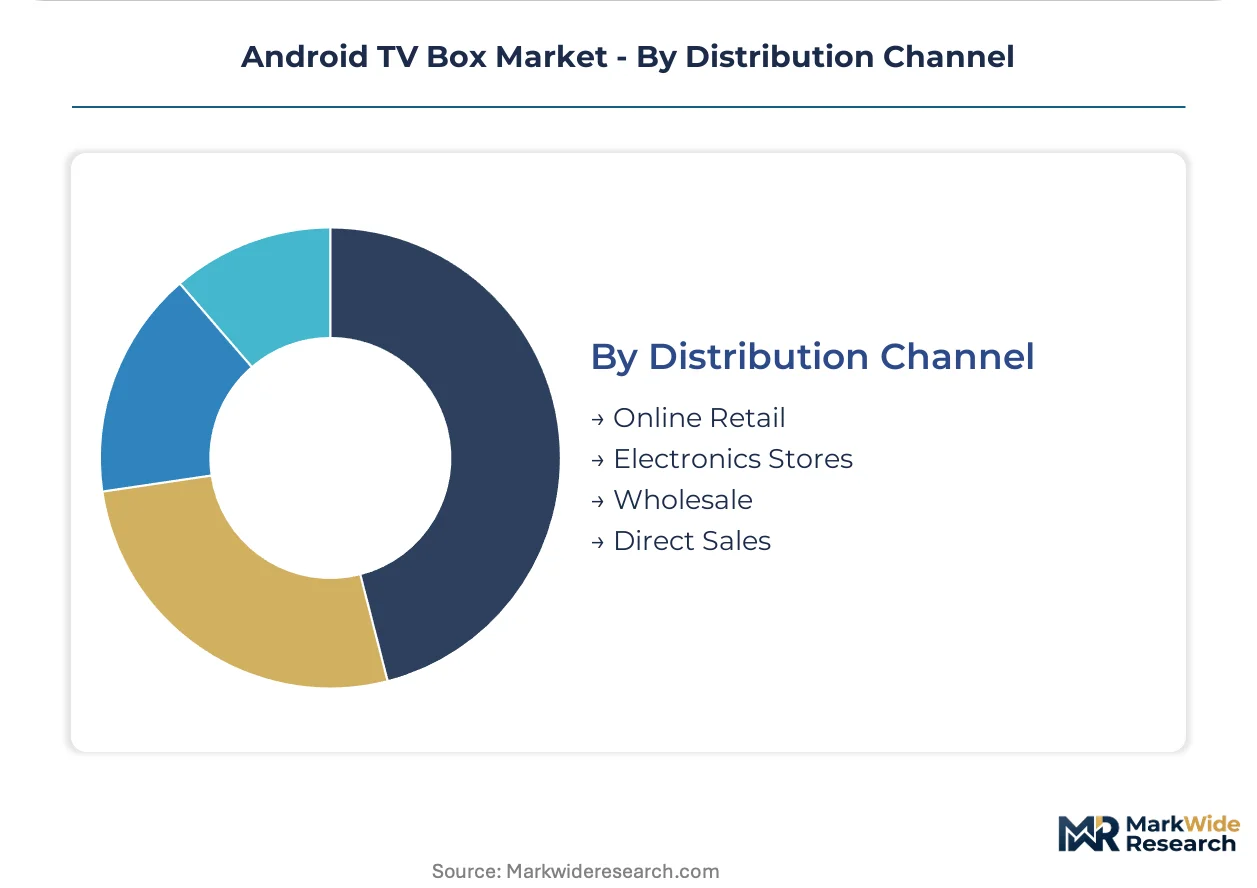
Channel selection correlates with buyer sophistication and certification requirements, with certified hardware concentrating in formal retail.
- Online Retail:Amazon, Flipkart, Lazada, and Shopee marketplaces dominating consumer purchases, with algorithmic visibility favoring BIS-certified or equivalent compliant listings. India's e-commerce electronics regulations are reshaping seller composition toward domestic-registered entities.
- Electronics Stores:Physical retail chains including Croma, Reliance Digital, and regional electronics markets providing hands-on evaluation and immediate availability. Staff recommendation influence sustains importance in tier-2 and tier-3 Indian cities.
- Wholesale:Bulk procurement channels serving regional distributors, system integrators, and hospitality procurement consortia. Volume pricing and custom firmware preload capabilities differentiate wholesale offerings.
- Direct Sales:Manufacturer-direct channels for enterprise and hospitality accounts requiring customized device management integration and dedicated support SLAs. Xiaomi, Amazon, and specialized ODMs maintain direct sales teams for commercial verticals.
Transaction volume sits with Online Retail. Account value concentration is shifting toward Direct Sales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shenzhen's component ecosystem supplies the ARM SoCs and HDMI modules that feed assembly lines across three continents. Raw material flows from Taiwanese foundries and Korean memory fabs converge in Guangdong Province before dispersing to regional fulfillment centers.
United States
Cord-cutting households and hospitality procurement drive demand for certified streaming hardware. FCC electromagnetic compliance testing for Wi-Fi and Bluetooth modules extends hardware development timelines by 8-12 weeks. Los Angeles and Miami serve as primary distribution hubs for North American retail and commercial deployments.
India
Telecom-cable convergence accelerates set-top replacement cycles as Reliance Jio and Airtel bundle streaming hardware with fiber subscriptions. BIS certification mandates for electronics imports are delisting uncertified AOSP boxes from Amazon India and Flipkart. Domestic assemblers in Noida and Chennai capture shelf space from direct-import competitors.
Germany
Audiophile segments sustain demand for media-focused Android players with SPDIF outputs and home theater integration. EU REACH substance restrictions and RoHS compliance requirements create procurement advantages for certified hardware vendors in public sector tenders. Berlin and Munich anchor commercial deployment for enterprise digital signage and meeting room systems.
Japan
Gaming-cafe operators and co-living developments standardize on hybrid streaming-gaming devices with cloud service integration. METI efficiency standards and JIS interoperability frameworks govern consumer electronics quality gates. Tokyo and Osaka concentrate procurement decisions for hospitality chains renovating properties ahead of major event cycles.
Brazil
Price-sensitive households in secondary cities drive volume for entry-level 1080p streaming hardware. ANVISA electromagnetic compatibility requirements and customs enforcement tighten quality gates for direct-import electronics. São Paulo's electronics wholesale district channels distribution to regional retailers throughout the Mercosur trade zone.
Android TV Box Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue hospitality-specific device management integrations. The vendor base clusters around three archetypes: Google-certified ODMs with GMS licensing, Amazon's vertically integrated Fire OS ecosystem, and Shenzhen-based specialists pivoting from AOSP firmware. Dominant competitive moves include Widevine L1 certification acquisition and enterprise MDM platform partnerships.
Within the platform-holder tier, Google and Amazon exemplify divergent ecosystem strategies—licensed Android TV OS versus forked Fire OS with captive commerce loops. NVIDIA occupies a position at the premium-performance vector with gaming-optimized hardware. Xiaomi anchors volume leadership in India and Southeast Asia through aggressive pricing on Google-certified streaming boxes.
| Leading Market Players |
|---|
| Mecool |
| H96 Max |
| UBOX |
| Tanix |
| NVIDIA |
| Amazon |
| Formuler |
| Xiaomi |
| Others |
Pricing and Supply Chain Analysis
Certification-grade bifurcation between Google-certified Android TV OS hardware and uncertified AOSP firmware creates parallel pricing ladders that track directly to supply chain complexity. Widevine L1 attestation requirements extend development timelines by 4-6 months for Shenzhen ODMs lacking GMS licensing, compressing margins at the commodity tier while insulating premium vendors from price erosion.
Pricing Analysis
Warranty and enterprise support bundling separates hospitality procurement contracts from bare-hardware consumer transactions. Three-tier pricing structure across premium, standard, and economy levels reflects Widevine certification status, with GMS-licensed devices commanding 40-60% premiums over AOSP equivalents. Cost compression in the 1080p tier intensifies because India's BIS enforcement is delisting uncertified imports from Amazon India and Flipkart. Hospitality chains and telecom operators exhibit the least price sensitivity due to management platform requirements, while price-sensitive households in Brazil and India's tier-3 cities drive volume at sub-$30 entry points.
Supply Chain Analysis
Single-source vulnerability sits with Taiwan semiconductor foundries fabricating premium ARM SoCs for Amlogic and MediaTek. Component sourcing draws from Taiwanese foundries for SoCs, Korean memory fabs for DDR and NAND, and Guangdong Province for HDMI modules and PCB assembly. Tariff exposure threatens margin stability as regional trade frameworks shift. Distribution runs through Shenzhen ODMs to regional fulfillment centers in Los Angeles, Mumbai, and São Paulo, with direct sales channels capturing enterprise and hospitality accounts requiring customized firmware integration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Foundry allocation constraints for advanced ARM SoCs are propping pricing power among certified hardware vendors, creating a supply-constrained market structure that favors incumbents with established GMS licensing.
For Market Incumbents: Deploy Widevine L1 certification acquisition as a defensive moat against gray-market AOSP competitors. Consolidate position through backward integration into firmware development capabilities and exclusive preload partnerships with streaming services. Channel control through direct hospitality sales teams protects margin structure against Amazon and Flipkart algorithmic visibility shifts. For New Entrants and Emerging Players: BIS certification mandates in India open a window for domestic assemblers in Noida and Chennai to capture shelf space from direct-import competitors. Target enterprise device management integration for Southeast Asian hospitality renovation cycles, where procurement decisions concentrate in Bangkok, Jakarta, and Manila. Pursue white-label manufacturing partnerships with telecom operators bundling streaming hardware with fiber subscriptions. For Investors and Strategic Acquirers: Re-rating potential sits with GMS-licensed ODMs with proven enterprise API development given hospitality sector consolidation around centralized management platforms. Long-term viability hinges on AV1 codec hardware decode capabilities and Wi-Fi 6E integration. Monitor Widevine certification backlog queues at Google as an inflection indicator for competitive access timing.| Strategic Initiative | Industry Significance |
|---|---|
| Widevine L1 Certification Acquisition | GMS licensing unlocks Netflix and Disney+ HD streams, excluding uncertified competitors from premium tiers. |
| Enterprise MDM Platform Integration | Hospitality chains in Thailand and Indonesia now require remote firmware management for in-room deployments. |
| AV1 Hardware Decode Block Integration | Amlogic and MediaTek SoCs with dedicated AV1 engines reduce bandwidth costs for 4K HDR streaming services. |
| Domestic Assembly Registration | BIS-compliant facilities in Noida and Chennai capture e-commerce shelf space from direct-import gray-market vendors. |
| Direct Hospitality Sales Channel Buildout | Custom firmware preload and SLA-backed support commands pricing premiums over consumer retail channels. |
Research Methodology
Independent corroboration across ODM engineering directors, hospitality procurement managers, and telecom operator device strategists underwrites the qualitative findings. Primary interviews with Shenzhen manufacturing executives, streaming service platform engineers, and Indian e-commerce category buyers combined with secondary validation from BIS certification databases, FCC equipment authorization filings, and customs import records. Bottom-up shipment estimates triangulate against top-down addressable market calculations across consumer and commercial segments.
Rate-of-change decomposition isolates volume growth from value expansion across the projection horizon. Segmentation dimensions modeled include product type, resolution tier, firmware certification status, end-user vertical, and distribution channel. CAGRs derive from installed base replacement cycle analysis and broadband penetration trajectories. Forecast inputs incorporate ARM SoC allocation schedules from Taiwanese foundries and AV1 codec adoption curves from Netflix and YouTube.
Caveats apply where foundry capacity reallocation, Google certification requirement changes, or regional content licensing shifts could materially shift the outlook. Forecasts reflect documented assumptions regarding telecom-cable convergence timing and hospitality renovation cycle intensity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Consumer Electronics
Vibrating Alarm Clock Market
Consumer Electronics
Europe Refurbished and Used Mobile Phones Market
Consumer Electronics
Asia-Pacific Professional Audio-Visual Systems Market
Consumer Electronics
Global Wireless Headphones Market
Consumer Electronics
Consumer Electronics Electric Motor Market
Consumer Electronics
Mannequin Head Market
Consumer Electronics
Refurbished Computer and Laptop Market
Consumer Electronics
Russia Gaming Gadgets Market
Consumer Electronics
Gun Care Products Market
Consumer Electronics
Pillow Holder for Tablets Market
Consumer Electronics
Vaporizer Market
Consumer Electronics
Learning Remote Controls Market
Consumer Electronics
China Refurbished Smartphone Market
Consumer Electronics
Subwoofer Market
Consumer Electronics
Smart Aquarium Devices Market
Consumer Electronics
Smartphone Screen Protector Market