
 Australia Pet Boarding Market | 2026-2036
Australia Pet Boarding Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Pet Boarding Market Insights
Aftermarket service revenue from grooming and training add-ons is reshaping profitability models across the Australia Pet Boarding Market. Dogtopia Enterprises leverages its franchise network to sustain premium positioning in metropolitan corridors. Hanrob Pet Hotels anchors its competitive edge through airport-adjacent locations and veterinary partnerships. Kip differentiates via technology-integrated booking systems and standardized care protocols.
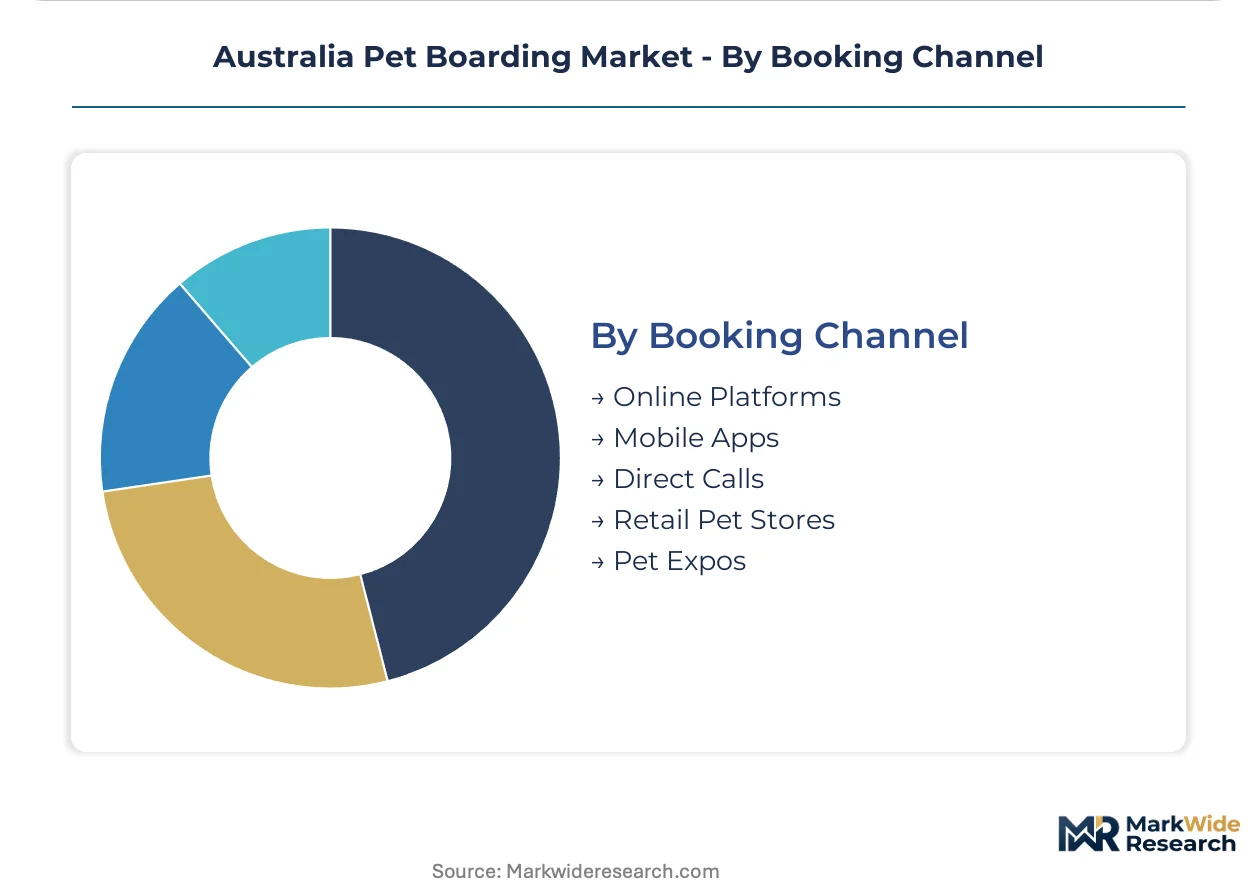
Pet boarding encompasses temporary housing and supervised care services for companion animals, typically delivered through climate-controlled kennels or free-range social environments with staff-to-pet ratios, vaccination verification, and structured activity schedules. The primary commercial purpose is to substitute owner care during travel, illness, or work commitments while ensuring animal welfare compliance. Overnight boarding occupies the largest revenue share among service types due to higher per-night yields and extended ancillary service attachment. Online platforms and mobile apps represent the fastest-expanding booking channel, capturing digitally native pet owners who prioritize convenience and transparent pricing. The dogs segment dominates pet type demand, though specialized care for small mammals is gaining traction among niche urban consumers.
The Australian Consumer Law, state-level Prevention of Cruelty to Animals Acts, and local council kennel licensing requirements collectively govern facility standards, staff training minima, and hygiene auditing frequencies. These frameworks elevate operational costs but simultaneously create barriers against informal competitors, professionalizing the sector. TGA-adjacent biosecurity protocols and the RSPCA's accreditation programs further influence facility design and service scope. Stakeholders must monitor evolving state welfare codes and digital platform compliance obligations to secure long-term operating authority and consumer trust.
Market Dynamics
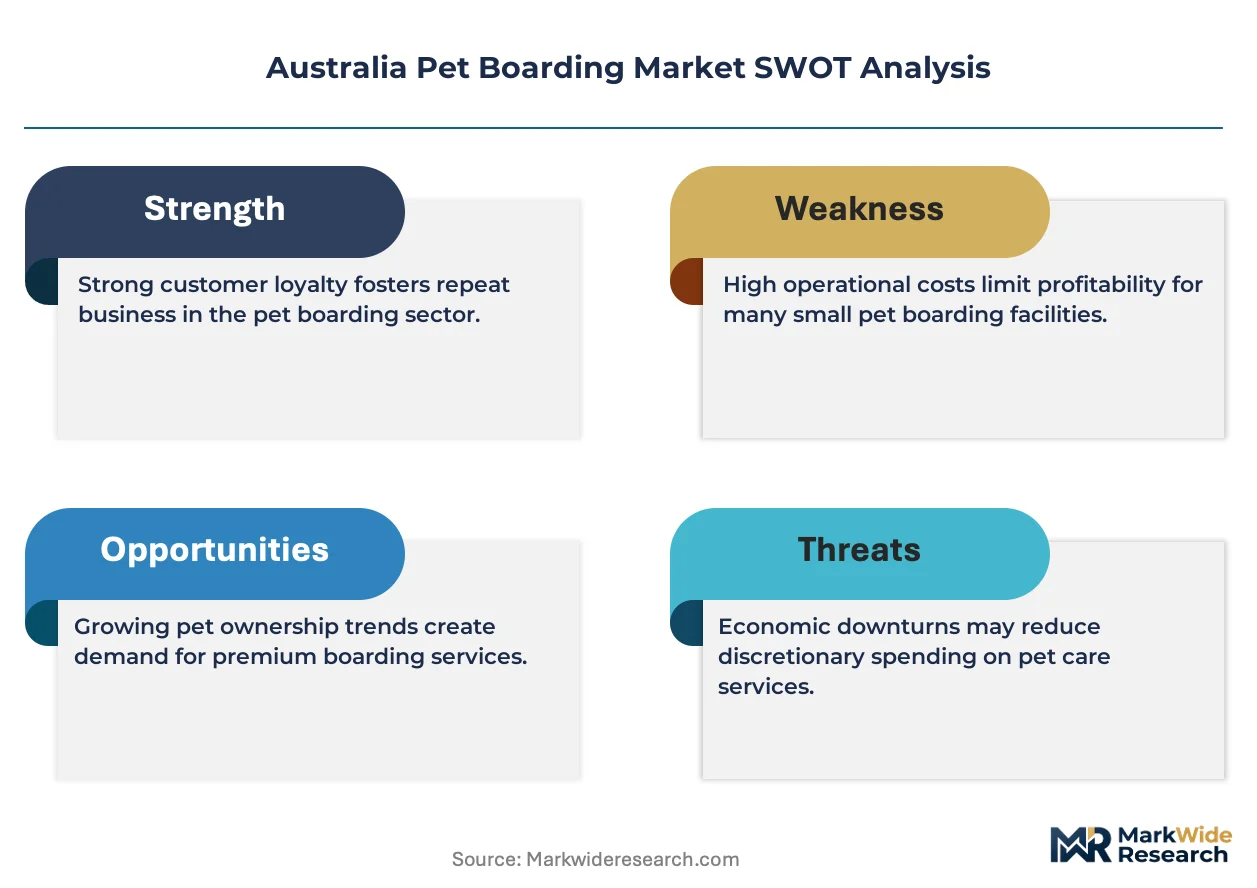
Dual-income apartment households in Sydney, Melbourne, and Brisbane are compressing traditional pet ownership models, forcing boarding operators to absorb veterinary-grade biosecurity costs and 24/7 staffing ratios that informal competitors cannot match.
Growth Catalysts
- RSPCA Accreditation Programs:State-level animal welfare codes under the Prevention of Cruelty to Animals Acts mandate facility auditing, professionalizing sector entry barriers and filtering out substandard operators.
- Airport-Adjacent Real Estate:Premium positioning near Sydney Kingsford Smith and Melbourne Tullamarine captures business travelers with compressed turnaround schedules and elevated willingness-to-pay for convenience.
- Pet Humanization Psychology:Urban professionals anthropomorphize companion animals, converting discretionary travel spending into premium boarding services with attached grooming and training modules.
Market Restraints
- Veterinary Labor Pool Constraints:TGA-adjacent biosecurity protocols require on-call veterinary partnerships that regional operators cannot secure at viable cost structures.
- Metropolitan Real Estate Concentration:Sydney and Melbourne CBD-adjacent industrial zoned land for kennel construction trades at residential-comparable rates, compressing facility expansion margins.
- Informal Peer-to-Peer Substitution:Unregulated home-based pet sitting platforms bypass licensing requirements and RSPCA standards, undercutting compliant operators on price.
Strategic Opportunities
- Western Australia Underpenetration:Perth and regional WA exhibit lower boarding facility density per capita than eastern seaboard cities, presenting greenfield expansion corridors for standardized franchise models.
- Small Mammal Specialized Care:Rabbit, guinea pig, and reptile boarding remains underserved relative to canine volume, commanding premium pricing from niche urban demographics.
- Australian Consumer Law Digital Platform Obligations:Emerging compliance requirements for online booking transparency create first-mover advantages for technology-integrated operators with established data infrastructure.
Industry Challenges
- Certified Animal Attendant Skill Scarcity:TAFE-level qualifications in animal care remain undersupplied relative to facility expansion rates, inflating wage costs and constraining service quality consistency.
- Legacy Kenn Management System Integration:Family-owned operators resist cloud-based booking and health record platforms, fragmenting customer experience and impeding centralized marketing efficiency.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Pet Boarding Market |
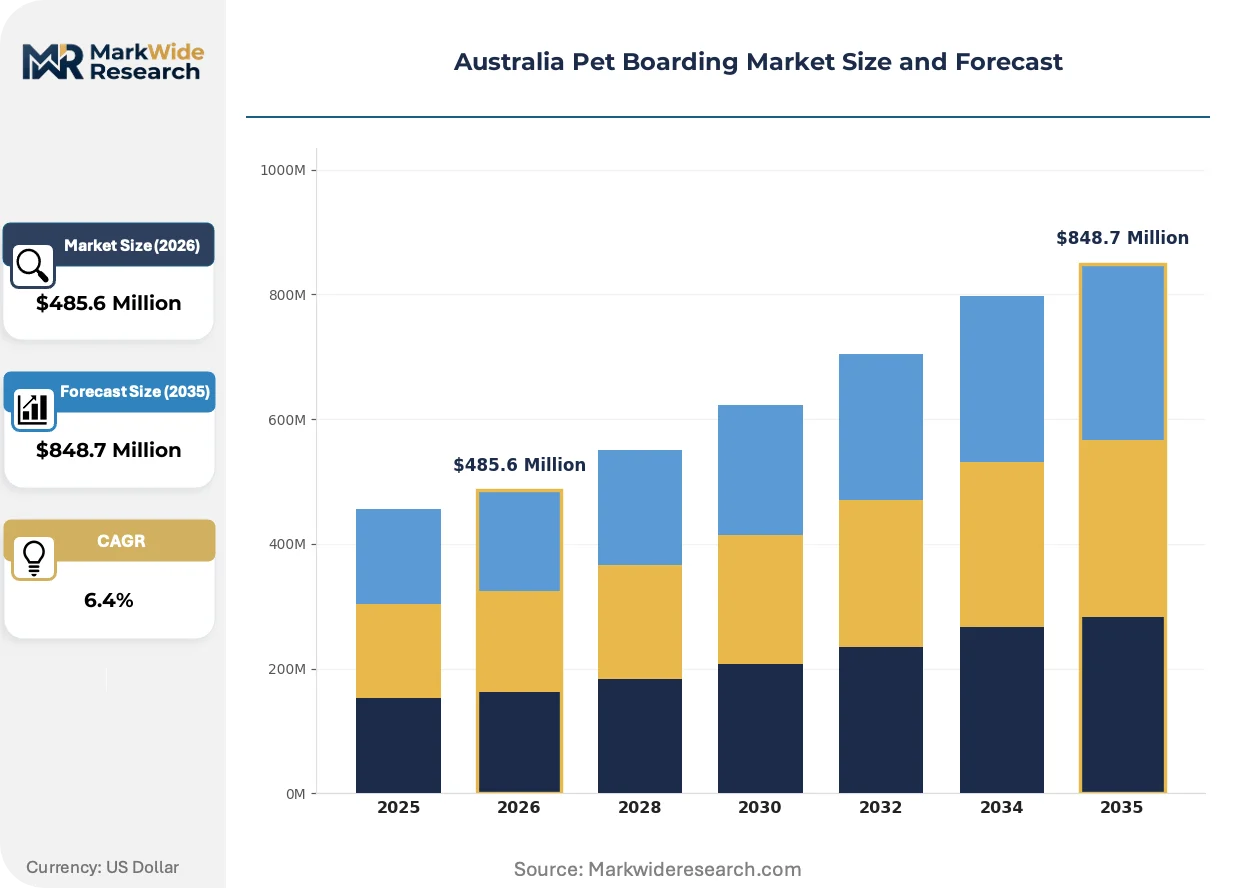
| Market Size in 2026 | $485.6 Million |
| Market Size in 2035 | $848.7 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Daycare, Overnight Boarding, Grooming, Training, Specialized Care Pet Type: Dogs, Cats, Birds, Small Mammals, Reptiles Customer Type: Individual Owners, Veterinarians, Pet Sitters, Rescue Organizations, Kennel Clubs Booking Channel: Online Platforms, Mobile Apps, Direct Calls, Retail Pet Stores, Pet Expos |
| Companies Covered | Dogtopia Enterprises, Pets at Home Group PLC, Kip, Wag Group Co, American Pet Resort, Hanrob Pet Hotels, Rover, PetBacker, Alida's Pet Resort, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Pet Boarding Market Trends and Innovations
Technology is compressing operational friction across booking, care documentation, and owner communication channels, while regulatory tightening and shifting household structures reshape competitive positioning.
Live-streaming camera networks and mobile application interfaces are virtualizing the owner-boarding facility relationship. Digitally native pet owners in Sydney and Melbourne now expect real-time visual access and automated health updates as baseline service features. This capability compression is virtualizing traditional trust-building mechanisms, enabling newer entrants to compete on transparency without decades of reputation accumulation.
The Australian Consumer Law and state-based Prevention of Cruelty to Animals Acts are tightening facility design mandates, including ventilation standards, isolation protocols, and staff-to-pet ratio minima. These frameworks are elevating capital requirements for new market entry while simultaneously creating compliance moats for incumbent operators with established veterinary partnerships. Metropolitan councils in Brisbane and Adelaide are responding with accelerated licensing review timelines for applicants demonstrating RSPCA accreditation.
Subscription-based daycare memberships are displacing transactional overnight bookings among dual-income professionals with predictable work-travel patterns. Corporate partnerships with CBD employers are emerging as a channel innovation, bundling pet boarding with employee wellness programs. This behavioral shift concentrates most visibly in Melbourne's inner suburbs, where apartment density and professional services employment overlap most densely.
Australia Pet Boarding Market Segmentation
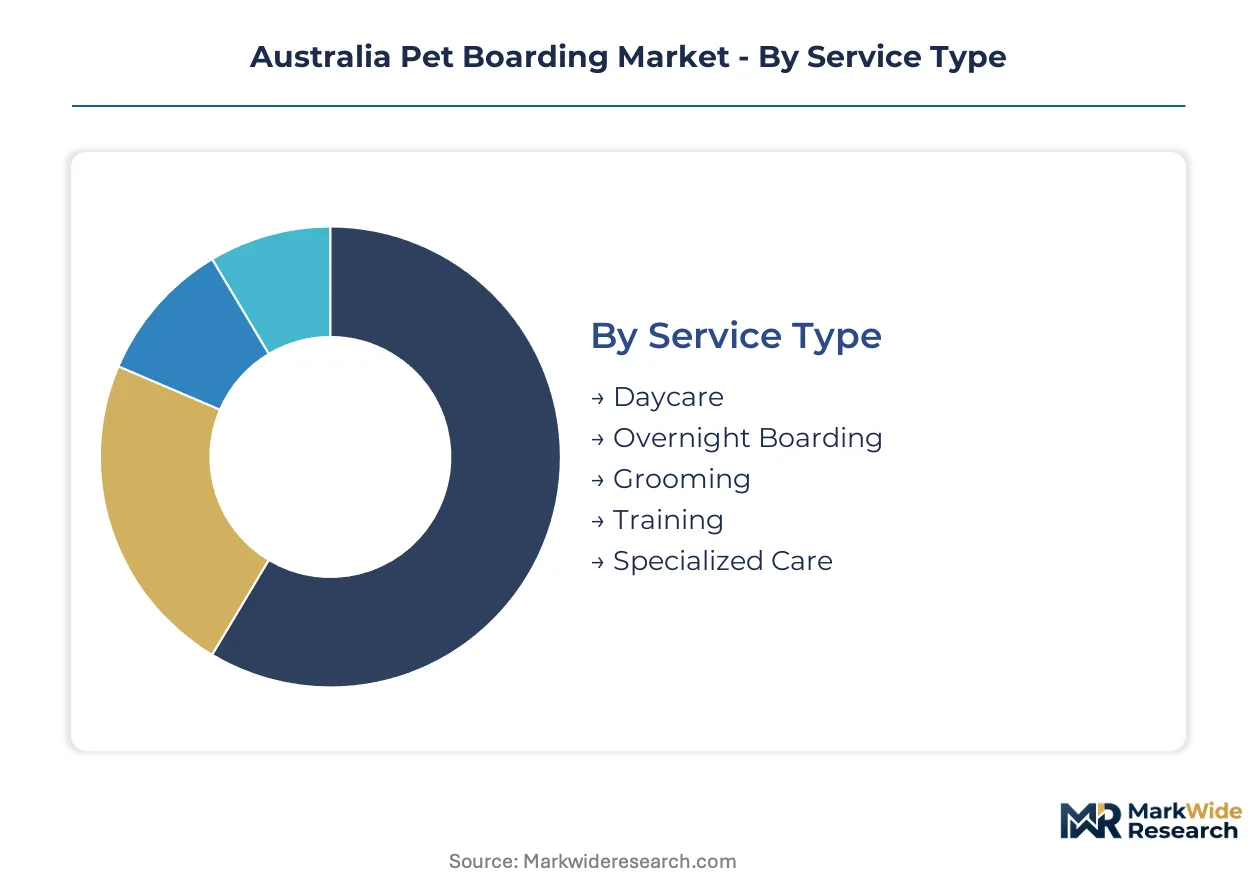
Service configuration, species specialization, and booking modality define competitive positioning across the Australia Pet Boarding Market. Operators must align facility design and staffing ratios with distinct demand profiles that vary by customer type and channel preference.
Service Type:
Cost tier differentiation separates basic accommodation from premium experiential packages with attached wellness modules.
- Overnight Boarding:Climate-controlled kennels and free-range social environments with 24/7 staffing ratios generate the highest per-unit revenue through extended ancillary attachment. Demand concentrates in Sydney, Melbourne, and Brisbane airport corridors where business travelers prioritize convenience over price sensitivity.
- Daycare:Structured activity schedules and supervised socialization deliver recurring subscription revenue from dual-income apartment households. Melbourne's inner suburbs exhibit the densest concentration of corporate partnership programs bundling daycare with employee wellness benefits.
- Grooming:Hygiene maintenance and breed-standard styling operate as margin-accretive add-ons rather than standalone revenue centers.
- Training:Behavioral modification and obedience protocols extend customer lifetime value through multi-session engagement.
- Specialized Care:Medical boarding and post-surgical recovery services require veterinary partnerships that regional operators struggle to secure under TGA-adjacent biosecurity protocols.
Overnight Boarding commands the established base. The steepest expansion runs through Daycare.
Pet Type:
Application requirements diverge sharply across species, dictating facility infrastructure and staff certification needs.
- Dogs:Vaccination verification, exercise yard access, and pack-socialization protocols dominate facility design and operational protocols. Sydney and Melbourne metropolitan corridors absorb the majority of canine volume through premium-positioned franchise networks.
- Small Mammals:Rabbit, guinea pig, and exotic rodent boarding remains structurally underserved relative to canine infrastructure, commanding premium pricing from niche urban demographics in Brisbane and Perth.
- Cats:Feline-specific isolation protocols and stress-minimization environments require dedicated wing construction that many multi-species facilities omit.
- Birds:Avian boarding demands specialized ventilation and noise-control engineering that elevates capital requirements beyond standard kennel construction.
- Reptiles:Temperature-controlled habitats and species-specific husbandry expertise constrain supply to a handful of specialized operators.
Dogs anchor volume concentration. Small Mammals deliver the fastest margin expansion.
Customer Type:
Volume scale and purchasing authority separate individual decision-makers from institutional procurement channels.
- Individual Owners:Discretionary spending on companion animal welfare drives premium service attachment and subscription conversion. Dual-income apartment households in Sydney, Melbourne, and Brisbane exhibit the highest per-pet expenditure on bundled boarding-grooming-training packages.
- Veterinarians:Referral partnerships and medical boarding referrals channel high-acuity cases toward facilities with on-call veterinary coverage.
- Pet Sitters:Informal competitors operating through unregulated home-based platforms undercut compliant operators on price while bypassing RSPCA accreditation requirements.
- Rescue Organizations:Volume contracting and grant-funded placements prioritize cost efficiency over amenity provision.
- Kennel Clubs:Breed-specific events and show circuits generate concentrated seasonal demand for short-duration, high-standard accommodation.
Individual Owners generate the revenue foundation. Veterinarians unlock the highest-value referral pathways.
Booking Channel:
Customer acquisition cost and lifetime value trajectories vary dramatically across digital and traditional touchpoints.
- Online Platforms:Transparent pricing comparison and review aggregation compress trust-building timelines for new market entrants. Sydney and Melbourne digitally native pet owners now expect real-time availability and automated health updates as baseline functionality.
- Mobile Apps:Push-notification engagement and subscription management tools enable recurring revenue conversion with lower friction than web-based alternatives.
- Direct Calls:High-touch consultation and complex booking requirements persist for first-time customers and specialized care inquiries.
- Retail Pet Stores:Co-location with veterinary clinics and pet supply retailers captures impulse bookings during routine shopping trips.
- Pet Expos:Annual events and breed shows concentrate lead generation for premium and specialized service providers.
Online Platforms capture the volume base. Mobile Apps are climbing the fastest on engagement metrics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity fractures across state boundaries, with Perth and Adelaide operators absorbing steeper discount pressure than Sydney and Melbourne premium corridors where convenience commands substantial premiums.
New South Wales
Dual-income households in Sydney's eastern suburbs and North Shore generate the densest concentration of subscription daycare demand. The state's Prevention of Cruelty to Animals Act enforcement through the RSPCA accreditation program elevates facility compliance costs. Airport-adjacent clusters near Kingsford Smith capture business traveler volume through premium overnight positioning.
Victoria
Melbourne's inner-north apartment density sustains the nation's highest corporate partnership penetration for bundled employee wellness programs. Local council kennel licensing requirements under the Victorian Code of Practice for the Operation of Boarding Establishments mandate ventilation and isolation protocols. The Docklands and Southbank corridors concentrate technology-integrated operators targeting digitally native professionals.
Queensland
Brisbane's subtropical climate drives demand for climate-controlled facilities with elevated cooling infrastructure investments. The Animal Care and Protection Act Queensland imposes staff-to-pet ratio minima that filter substandard operators. Gold Coast and Sunshine Coast tourism corridors generate seasonal demand spikes requiring flexible capacity scaling.
Western Australia
Perth exhibits the lowest facility density per capita among state capitals, compressing price competition and preserving margin structures for early entrants. The state's Department of Primary Industries and Regional Development oversees kennel licensing with biosecurity protocols aligned to TGA-adjacent standards. Regional WA beyond the metropolitan perimeter remains substantially underserved, presenting greenfield expansion corridors.
South Australia
Adelaide's smaller metropolitan scale constrains premium pricing power relative to eastern seaboard cities, forcing operators toward efficiency-focused models. The Dog and Cat Management Act and local council bylaws govern facility standards with RSPCA accreditation increasingly expected by consumers. The Adelaide Hills corridor shows emerging demand for specialized small mammal boarding among niche demographics.
Australia Pet Boarding Market Competitive Landscape
Premium-positioned franchise networks and technology-integrated independents split the market along convenience-versus-trust vectors. Consolidation pressure concentrates in metropolitan corridors where real estate costs and compliance burdens filter family-owned legacy operators. Two archetypes dominate: airport-adjacent full-service hotels with veterinary partnerships, and app-enabled platforms with standardized care protocols. Competitive moves center on geographic expansion into underpenetrated secondary cities and backward integration into captive grooming and training service modules.
Within the premium hotel tier, Hanrob Pet Hotels anchors airport-corridor positioning through location strategy and veterinary network density. Dogtopia Enterprises exemplifies franchise scalability with metropolitan corridor concentration. Kip occupies the technology-integrated vector, representing standardized protocols and digital-first customer acquisition. These three illustrate how divergent strategic foundations—real estate, network scale, and platform infrastructure—can coexist without direct substitution.
| Leading Market Players |
|---|
| Dogtopia Enterprises |
| Pets at Home Group PLC |
| Kip |
| Wag Group Co |
| American Pet Resort |
| Hanrob Pet Hotels |
| Rover |
| PetBacker |
| Alida's Pet Resort |
| Others |
Pricing and Supply Chain Analysis
Sydney's airport-corridor facility cluster concentrates premium overnight capacity, translating location scarcity into pricing power that informal peer-to-peer operators cannot replicate under RSPCA accreditation costs.
Pricing Analysis
Grooming and training add-ons drive lifetime value expansion beyond base boarding fees. Three-tier pricing structure across premium, standard, and economy levels separates RSPCA-accredited facilities from unlicensed home-based competitors, with veterinary partnership tiers commanding additional premiums. Cost compression in economy tiers is intensifying because informal platform operators bypass licensing requirements and facility standards. Corporate partnership buyers exhibit lowest price sensitivity, while rescue organizations and grant-funded channels absorb maximum discount pressure.
Supply Chain Analysis
Certified animal attendant labor scarcity between TAFE institutions and metropolitan facility networks dominates operational risk exposure. Australia sources veterinary-grade biosecurity equipment from domestic distributors and climate-control infrastructure from China and Germany. Single-source vulnerability concentrates in specialized small mammal habitat suppliers serving niche urban demographics. Distribution runs through franchise networks for standardized protocols and direct-to-consumer mobile platforms for subscription conversion.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent operators must defend against unregulated home-based pet sitting platforms that undercut compliant facilities on price while evading RSPCA accreditation mandates.
For Market Incumbents: Build compliance moats through RSPCA accreditation and veterinary partnership density. Deepen backward integration into captive grooming and training service modules to capture add-on revenue. Secure airport-adjacent real estate in Sydney and Melbourne before residential-comparable zoning rates compress expansion margins further. For New Entrants and Emerging Players: Pursue greenfield expansion into Perth and regional Western Australia where facility density per capita lags eastern seaboard cities. Target small mammal specialized care segments in Brisbane and Adelaide Hills corridors where supply constraints enable premium pricing. Launch with technology-integrated booking platforms featuring real-time camera access to compress trust-building timelines against established reputation. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors franchise networks with standardized care protocols and centralized data infrastructure over fragmented family-owned legacy operators. Five-to-ten year viability hinges on consolidation capture in metropolitan corridors where compliance burdens filter subscale competitors. Monitor corporate partnership penetration rates in Melbourne's inner suburbs as inflection indicator for subscription daycare model scalability.| Strategic Initiative | Industry Significance |
|---|---|
| RSPCA Accreditation Investment | Professionalizes sector entry barriers under Prevention of Cruelty to Animals Acts enforcement. |
| Veterinary Partnership Network | Unlocks medical boarding referrals and TGA-adjacent biosecurity protocol compliance. |
| Technology Platform Integration | Enables real-time owner communication and subscription management for digitally native customers. |
| Corporate Wellness Partnership | Captures recurring daycare demand from dual-income apartment households in CBD corridors. |
| Small Mammal Specialized Care | Addresses structural undersupply in rabbit, guinea pig, and reptile boarding for niche urban demographics. |
Research Methodology
A spread of perspectives from facility operators, veterinary practice managers, corporate HR benefits administrators, and TAFE animal care program directors converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation against RSPCA accreditation databases, local council kennel licensing records, and Australian Consumer Law enforcement guidance. Bottom-up facility capacity modeling and top-down household pet ownership projections were triangulated for demand estimation.
Demand-supply balance dynamics shaped the analytical framework across the analysis window. Segmentation dimensions included service type configuration, pet species specialization, booking channel preference, and metropolitan corridor density. CAGRs were derived from trend extrapolation with cross-validation against facility expansion rates and staffing qualification pipeline outputs. Corporate partnership adoption curves and mobile platform penetration metrics served as industry-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in dual-income household formation rates, metropolitan apartment construction, and discretionary travel expenditure would shift the trajectory. Forecasts reflect documented assumptions about regulatory enforcement intensity and informal competitor platform growth. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
Dog Raincoats Market
Pet Care Products
South America Pet Treats Market
Pet Care Products
Aquarium and Fish Bowls Market
Pet Care Products
Argentina Pet Food Market
Pet Care Products
Cat Diets Market
Pet Care Products
UAE Cat Food Market
Pet Care Products
UK Pet Treats Market
Pet Care Products
Pet Food Market
Pet Care Products
Pet Pee Pads Market
Pet Care Products
Pet Gadgets Market
Pet Care Products
Automatic and Smart Pet Feeder Market
Pet Care Products
Pet Fitness Care Market
Pet Care Products
Indonesia Pet Care Market
Pet Care Products
High Protein Dog Food Market
Pet Care Products
Modern Cat Furniture Market
Pet Care Products
Pet Tag Market