
 India Power EPC Market | 2026-2036
India Power EPC Market Size, Share, and Industry Trends Forecast 2026-2036
India Power EPC Market Foresight
CEA technical standards for grid connectivity and voltage regulation is expanding compliance burdens for new entrants. Bharat Heavy Electricals Limited leverages its captive manufacturing of supercritical boilers and turbine generators to dominate thermal retrofits. Larsen & Toubro Limited sustains its position through integrated EPC capabilities spanning substations, transmission lines, and renewable balance-of-plant systems. Tata Projects Limited specializes in ultra-mega solar park development, anchoring its pipeline in Rajasthan and Gujarat.
Power EPC encompasses the end-to-end design, engineering, procurement of equipment, and construction execution for generation, transmission, and distribution infrastructure, typically governed by CEA technical standards specifying voltage classes from 33 kV to 765 kV and renewable integration protocols. Its primary purpose is delivering bankable, grid-compliant energy assets under fixed-price, milestone-linked contracts. Engineering and procurement services capture disproportionate margin pools due to proprietary design optimization and long-term equipment sourcing relationships. Solar technology leads current order books, though green hydrogen and hybrid configurations represent the fastest-expanding technology segment. Mega projects above 500 MW concentrate among a handful of integrated contractors, while small and medium-scale distributed solar and industrial captive plants fragment across regional specialists.
BIS certification for electrical equipment, CEA grid standards, and state-level renewable purchase obligations collectively shape project viability timelines and localization requirements. The MNRE production-linked incentive scheme for solar modules and the green hydrogen mission are redirecting procurement toward domestic manufacturing ecosystems. Stakeholders must monitor evolving CEA storage mandates and state transmission utility tendering rhythms to align pre-bid engineering investments with executable contract pipelines.
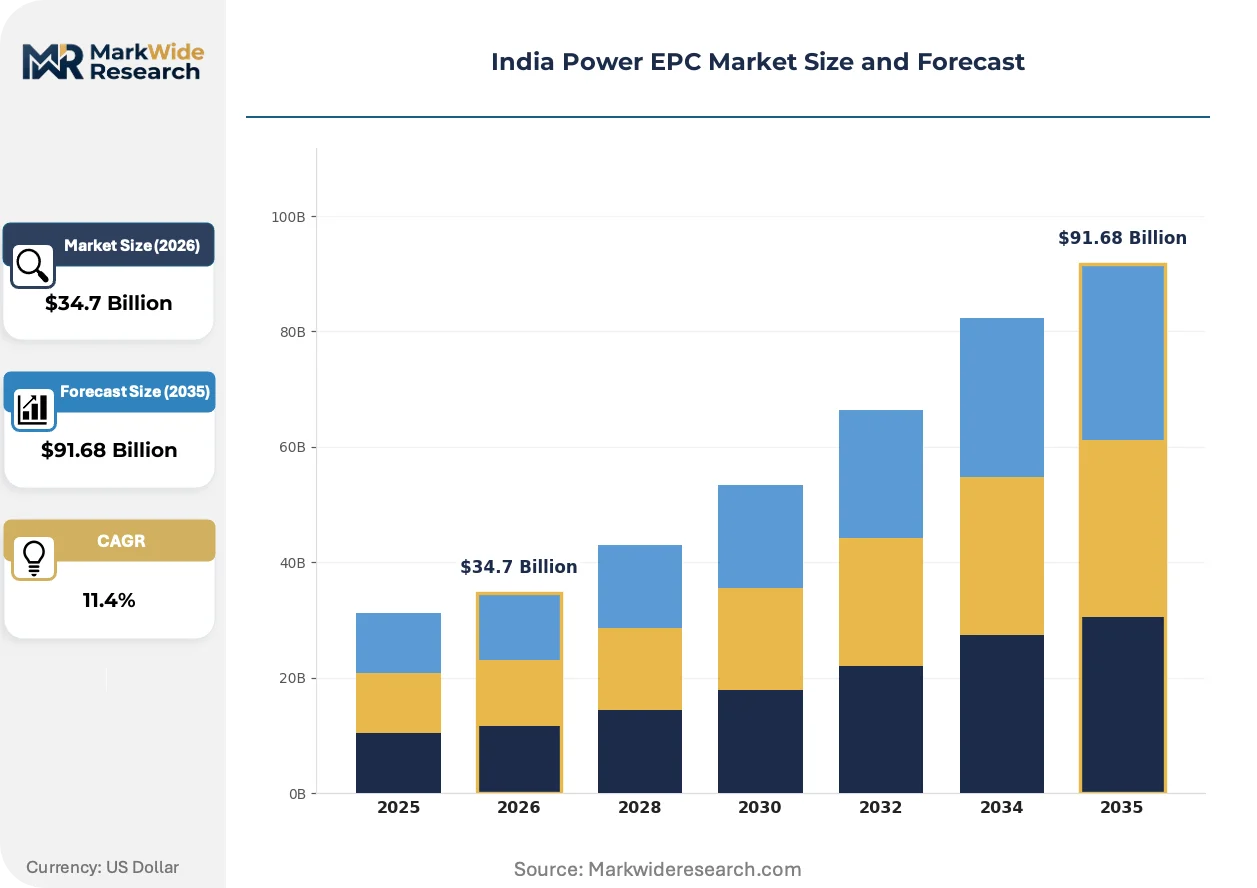
Market Dynamics
State distribution utilities in Gujarat, Rajasthan, and Karnataka are accelerating renewable integration procurement, compressing project timelines and elevating contractor technical thresholds for grid-compliant execution.
Growth Catalysts
- CEA Grid Code Revisions:Updated voltage regulation and connectivity standards are mandating advanced inverter capabilities and storage co-location, expanding contract scopes for integrated EPC providers.
- MNRE Green Hydrogen Mission:Electrolyzer manufacturing and hydrogen hub development are creating parallel demand streams for power infrastructure with dedicated offtake guarantees.
- Solar-Wind Hybrid Parks:Land-use optimization and shared transmission infrastructure are driving bundled procurement models in Rajasthan and Karnataka.
Market Restraints
- Domestic Module Supply Bottlenecks:PLI scheme ramp-up lags behind tendered capacity, forcing developers to absorb imported equipment cost volatility or face commissioning penalties.
- Discom Financial Stress:State distribution utility payment delays and letter-of-credit constraints are elevating working capital requirements for contractors.
- Land Acquisition Friction:Revenue land conversion and transmission right-of-way disputes in Gujarat and Maharashtra are extending pre-construction timelines by 12-18 months.
Strategic Opportunities
- Green Hydrogen Export Corridors:Mundra and Hazira port-linked electrolyzer clusters are emerging as anchor demand for dedicated renewable generation and high-voltage substation buildouts.
- Battery Energy Storage System Mandates:CEA storage obligation trajectories are creating new EPC verticals combining solar PV, lithium-ion integration, and grid-forming inverters.
- Industrial Captive Renewables:Open-access regulatory relaxation in Karnataka and Tamil Nadu is enabling direct corporate power purchase agreements bypassing discom intermediation.
Industry Challenges
- Grid-Code Compliance Engineering:CEA frequency response and fault-ride-through specifications require specialized power systems expertise scarce among regional contractors.
- Multi-Technology Integration:Solar-wind-battery hybrid configurations demand cross-functional engineering teams capable of optimizing DC-AC ratios and storage dispatch algorithms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Power EPC Market |
| Market Size in 2026 | $34.7 Billion |
| Market Size in 2035 | $91.68 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Engineering, Procurement, Construction, Project Management Technology: Solar, Wind, Biomass, Hydro End User: Government, Private Sector, Utilities, Independent Power Producers Project Size: Small Scale, Medium Scale, Large Scale, Mega Projects |
| Companies Covered | Bharat Heavy Electricals Limited, Larsen & Toubro Limited, Tata Projects Limited, Sterlite Power Transmission Limited, KEC International, Kalpataru Projects International Limited, Reliance Infrastructure Ltd, Techno Electric & Engineering Company, Power Mech Projects, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Power EPC Market Shifts & Advancements
Digitization of project lifecycle management and modular construction methodologies are compressing execution timelines while elevating quality assurance standards across generation and transmission infrastructure.
Containerized substation solutions with factory-integrated protection and control systems are overtaking conventional brick-and-mortar switchyard construction. State transmission utilities in Rajasthan and Madhya Pradesh are specifying these for remote renewable evacuation projects. The shift is overtaking traditional EPC margin structures by transferring engineering risk to equipment OEMs and reducing on-site labor dependencies.
BIS certification requirements for solar inverters and switchgear are tightening equipment qualification timelines. The Central Electricity Authority has mandated revised testing protocols for grid-forming inverters above 10 MW. Domestic manufacturers are responding with captive testing facilities in Gujarat and Tamil Nadu to accelerate product certification cycles.
Discoms are unbundling engineering-procurement from construction execution in mega solar park tenders. Gujarat Urja Vikas Nigam Limited and Rajasthan Renewable Energy Corporation Limited have piloted separate E and C contracts, enabling specialist firms to compete without integrated balance sheets. The restructuring is most visible in the 500 MW-plus category where construction-only contractors from the roads and industrial infrastructure sectors are entering power EPC.
India Power EPC Market Segmentation
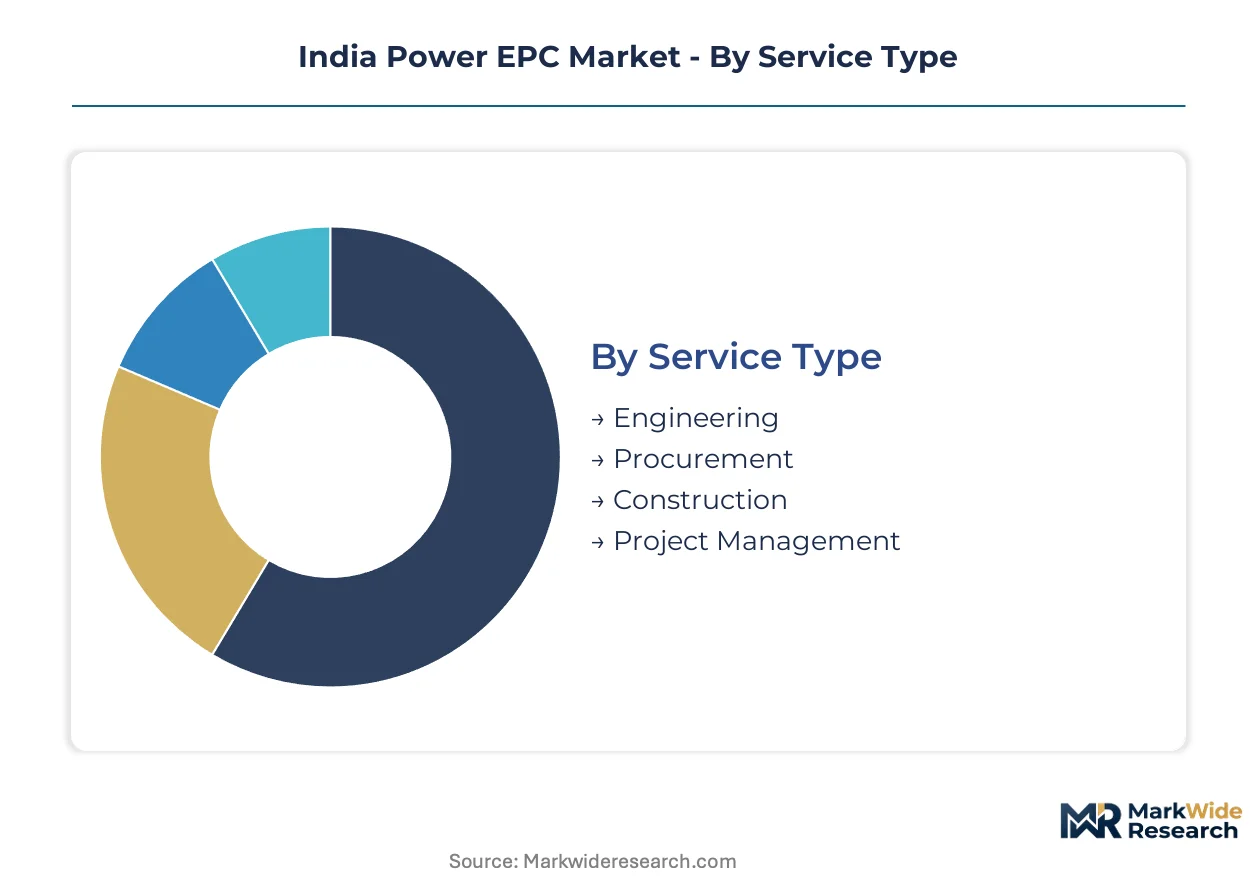
Power EPC contractors in India deploy distinct capability configurations across service bundles, generation technologies, and client categories. Segment boundaries determine margin capture, working capital intensity, and regulatory exposure for project developers and construction firms alike.
Service Type:
Engineering commands premium pricing while construction captures volume share in India's project pipeline.
- Engineering:Proprietary design optimization for grid-forming inverters and hybrid DC-AC ratios differentiates specialist consultants. Gujarat and Rajasthan solar-wind parks concentrate demand for CEA-compliant interconnection studies and voltage regulation modeling.
- Procurement:Long-term equipment sourcing relationships with domestic module manufacturers under PLI schemes and imported inverter distributors define competitive position. Discoms in Karnataka specify BIS-certified switchgear, compressing qualification timelines for procurement agents.
- Construction:Balance-of-plant execution including civil works, mounting structures, and cabling dominates headcount deployment. Regional contractors from roads and industrial infrastructure sectors are entering through unbundled tenders in 500 MW-plus solar parks.
- Project Management:Milestone-linked oversight of multi-contractor sites requires scheduling software and quality assurance protocols. Mega projects in Rajasthan demand dedicated PMO structures coordinating EPC workstreams with state transmission utility evacuation timelines.
Today's leader: Engineering. Tomorrow's challenger: Project Management.
Technology:
Solar dominates current order books while emerging applications reshape technology mix.
- Solar:Utility-scale PV and solar-wind hybrid configurations anchor contractor portfolios. Land-use optimization in Rajasthan and Gujarat drives bundled procurement with shared transmission infrastructure.
- Wind:Repowering of aging turbines and greenfield hybrid installations concentrate in Tamil Nadu and Karnataka. Hub-height elevation and nacelle assembly logistics favor contractors with heavy-lift equipment fleets.
- Biomass:Cogeneration plants for sugar mills and rice husk facilities in Maharashtra and Punjab require fuel handling expertise. CEA grid codes for distributed generation create compliance complexity for regional specialists.
- Hydro:Small hydro projects in Himalayan states face geological risk and environmental clearance delays. Run-of-river designs in Uttarakhand and Himachal Pradesh demand specialized tunneling and penstock installation capabilities.
Solar maintains volume leadership. Green hydrogen-linked electrolyzer demand represents the steepest expansion trajectory for power infrastructure buildouts.
End User:
Utility procurement patterns diverge sharply from private sector risk appetites.
- Government:Central Public Sector Undertaking tenders through SECI and NTPC specify domestic content requirements and extended payment security. MNRE green hydrogen mission allocations are redirecting EPC capacity toward electrolyzer manufacturing clusters.
- Private Sector:Corporate renewable purchase agreements in Karnataka and Tamil Nadu bypass discom intermediation through open-access regulatory relaxation. Direct offtake contracts compress developer margins but accelerate commissioning timelines.
- Utilities:State distribution companies in Gujarat, Rajasthan, and Karnataka dominate renewable integration procurement. Letter-of-credit constraints and payment delays elevate working capital requirements for contractors.
- Independent Power Producers:Merchant solar and hybrid projects without long-term PPAs concentrate development risk. Mundra and Hazira port-linked export-oriented hydrogen hubs are emerging as anchor demand for dedicated generation assets.
Utility tenders drive current volume. Private sector open-access arrangements are climbing the fastest as regulatory frameworks mature.
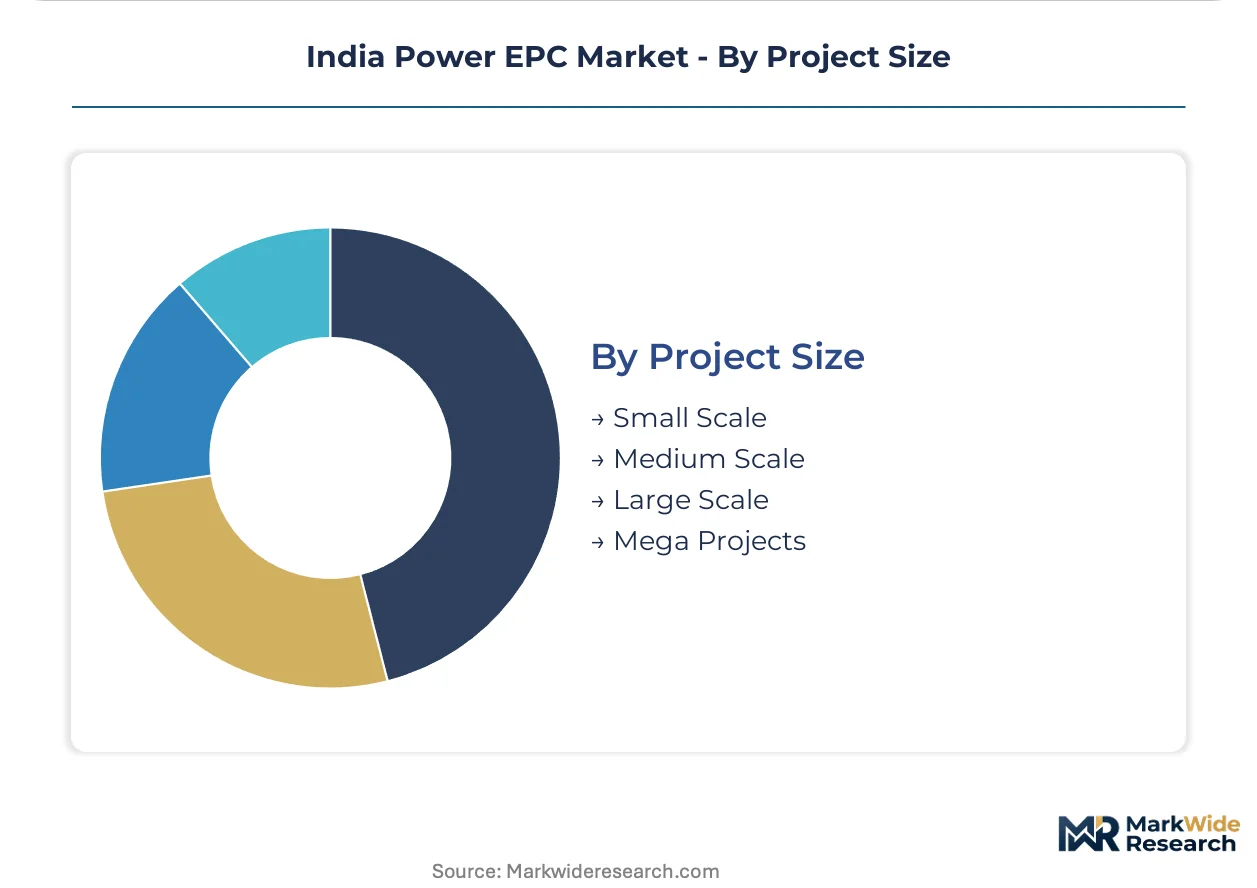
Project Size:
Mega projects concentrate among integrated contractors while distributed segments fragment across regional players.
- Small Scale:Industrial captive plants below 10 MW and rooftop commercial installations proliferate across Maharashtra and Tamil Nadu. Discom net metering policy variations create jurisdictional complexity for standardized EPC offerings.
- Medium Scale:10-100 MW open-access solar parks in Karnataka and Andhra Pradesh serve corporate offtakers. Land aggregation and transmission connectivity pose execution risks for mid-tier developers.
- Large Scale:100-500 MW utility-scale projects require integrated engineering-procurement-construction capabilities. Containerized substation specifications from Rajasthan and Madhya Pradesh transmission utilities are compressing execution timelines.
- Mega Projects:Above 500 MW solar-wind hybrid parks in Rajasthan and Gujarat concentrate among Larsen & Toubro, Tata Projects, and Bharat Heavy Electricals Limited. Unbundled E-and-C tender pilots enable construction-only contractors to compete without integrated balance sheets.
Mega projects anchor integrated contractor revenues. Medium-scale open-access configurations are gaining share fastest as corporate procurement accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled project management talent and specialized engineering expertise cluster in Gujarat, Rajasthan, and Karnataka, anchoring execution capacity for utility-scale renewable infrastructure.
Gujarat
Solar-wind hybrid parks and green hydrogen export hubs at Mundra and Hazira drive procurement acceleration. CEA grid connectivity standards mandate advanced inverter capabilities and storage co-location for new projects. The Kutch region concentrates electrolyzer manufacturing clusters with dedicated renewable generation buildouts.
Rajasthan
Ultra-mega solar parks above 500 MW dominate contractor portfolios and state transmission utility tendering. MNRE production-linked incentive schemes redirect module procurement toward domestic manufacturing ecosystems. Jodhpur and Jaisalmer districts host the densest concentration of hybrid renewable installations with shared evacuation infrastructure.
Karnataka
Open-access regulatory relaxation enables direct corporate power purchase agreements bypassing discom intermediation. BIS certification requirements for switchgear compress equipment qualification timelines for procurement agents. The Pavagada solar park and surrounding districts anchor distributed solar and industrial captive plant development.
Maharashtra
Revenue land conversion disputes and transmission right-of-way friction extend pre-construction timelines by 12-18 months. State renewable purchase obligations shape project viability timelines for developers. Nagpur and Pune industrial corridors concentrate biomass cogeneration and rice husk facility EPC demand.
Tamil Nadu
Wind repowering and greenfield hybrid installations concentrate contractor heavy-lift equipment deployment. Open-access arrangements for corporate offtakers accelerate commissioning timelines compared to utility tenders. The state hosts captive testing facilities for grid-forming inverters to accelerate BIS certification cycles.
India Power EPC Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across bundled and unbundled contract structures. The market exhibits tiered consolidation where integrated contractors capture mega projects above 500 MW while regional specialists fragment small and medium-scale segments. Strategic archetypes span state-owned heavy engineering enterprises, diversified infrastructure conglomerates, and emerging construction-only entrants from roads and industrial sectors. Dominant competitive moves include unbundling of engineering-procurement from construction execution and backward integration into captive equipment manufacturing.
Within the integrated infrastructure tier, Larsen & Toubro Limited and Tata Projects Limited exemplify full-service EPC positioning spanning substations, transmission lines, and renewable balance-of-plant systems. Bharat Heavy Electricals Limited occupies a distinctive position as a state-owned heavy engineering enterprise with captive manufacturing capabilities. These three entities anchor the competitive structure for mega-scale renewable and thermal retrofit projects across Gujarat, Rajasthan, and Karnataka.
| Leading Market Players |
|---|
| Bharat Heavy Electricals Limited |
| Larsen & Toubro Limited |
| Tata Projects Limited |
| Sterlite Power Transmission Limited |
| KEC International |
| Kalpataru Projects International Limited |
| Reliance Infrastructure Ltd |
| Techno Electric & Engineering Company |
| Power Mech Projects |
| Others |
Supply & Pricing Matrix
MNRE green hydrogen mission mandates gate both qualified EPC supply and premium-tier pricing access for electrolyzer-linked infrastructure buildouts. CEA grid code revisions and BIS certification requirements stratify contractor tiers, with integrated providers commanding fixed-price premiums while unbundled specialists compete on construction-only rates.
Pricing Analysis
The bundled-versus-unbundled service split defines pricing architecture across India's power EPC landscape. Integrated engineering-procurement-construction contracts capture premium margins through proprietary design optimization and milestone-linked payment security, while unbundled construction-only tenders in 500 MW-plus solar parks compress rates through roads-sector entrant competition. Price differentiation hinges on CEA grid-code compliance certification and domestic content qualification under PLI schemes. Pricing pressure intensifies in construction tiers as state transmission utilities pilot separate E-and-C contracts, forcing margin compression on civil works and balance-of-plant execution. Government tenders through SECI and NTPC exhibit lowest price sensitivity due to extended payment security, whereas private open-access corporate PPAs drive sharper negotiation on engineering fees.
Supply Chain Analysis
Dual-sourcing requirements for critical electrical equipment mandate multi-supplier qualification across module, inverter, and switchgear categories. Geographic supply concentration centers on China for lithium-ion battery cells and power electronics, Vietnam for assembly-tier components, and domestic Indian manufacturing under PLI schemes for solar modules. Raw material dependencies span polysilicon, rare earth magnets for wind turbines, and copper for cabling infrastructure. Supply chain risk from tariff exposure on Chinese inverter imports forces developers toward BIS-certified domestic alternatives with longer qualification cycles. Distribution runs through state transmission utility tendering channels in Gujarat, Rajasthan, and Karnataka, with equipment OEMs bypassing EPC intermediaries in containerized substation specifications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The India Power EPC Market functions as a regulatory compounder where CEA storage obligation trajectories and MNRE green hydrogen allocations compound demand visibility for prepared contractors.
For Market Incumbents: Cement dominance in mega-project pipelines through captive manufacturing of grid-forming inverters and supercritical components that regional competitors cannot replicate. Deepen backward integration into electrolyzer manufacturing clusters at Mundra and Hazira before green hydrogen tender volumes accelerate. Defend margin position by securing long-term module supply relationships under PLI schemes, insulating against import cost volatility that threatens unbundled construction-only entrants. For New Entrants and Emerging Players: Launch via unbundled construction-only contracts in 500 MW-plus solar parks where integrated balance sheets are no longer mandatory. Target medium-scale open-access solar configurations in Karnataka and Tamil Nadu, where regulatory relaxation enables direct corporate PPAs with faster commissioning timelines than utility tenders. Penetrate through specialized project management services coordinating multi-contractor sites, leveraging scheduling software differentiation against legacy EPC workflows. For Investors and Strategic Acquirers: Roll-up economics work for regional construction specialists with proven execution in Gujarat and Rajasthan because unbundled tender pilots fragment mega-project execution into separable workstreams. Acquire mid-tier EPC firms holding BIS certification relationships and state utility pre-qualification status rather than greenfield capability builds. Watch CEA storage mandate implementation velocity as the inflection signal determining lithium-ion integration demand and battery energy storage system EPC vertical viability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Electrolyzer Manufacturing | MNRE green hydrogen mission allocations redirect EPC capacity toward dedicated hydrogen hub buildouts at port-linked clusters. |
| Containerized Substation Specification Adoption | Rajasthan and Madhya Pradesh transmission utilities transfer engineering risk to equipment OEMs, compressing traditional EPC margins. |
| Unbundled E-and-C Contract Pursuit | GUVNL and RRECL pilot structures enable construction-only contractors from roads sectors to compete without integrated balance sheets. |
| Grid-Forming Inverter Certification Investment | CEA revised testing protocols above 10 MW create qualification barriers favoring firms with captive Gujarat and Tamil Nadu facilities. |
| Open-Access Regulatory Arbitrage Positioning | Karnataka and Tamil Nadu direct corporate PPA frameworks accelerate commissioning timelines compared to discom-intermediated utility tenders. |
Research Methodology
Bottom-up utility procurement modeling reconciled against top-down EPC contractor order book tracking forms the analytical core of this study. Primary interviews with state transmission utility planning officers, IPP project developers, EPC contracting executives, and grid operations specialists combined with secondary validation against CEA technical standard filings, MNRE mission documents, SECI tender databases, and state discom procurement records. Triangulation across these sources ensures demand-side consumption estimates align with supply-side capacity deployment.
Input-output matrices map generation capacity additions by technology and scale tier against contractor execution bandwidth and equipment procurement lead times. Segmentation dimensions span service type, generation technology, end-user category, and project size class. CAGRs derive from regression analysis of historical tender volumes, policy trajectory modeling, and capacity factor assumptions across the projection horizon. Industry-specific forecast inputs include CEA storage obligation trajectories and PLI scheme domestic manufacturing ramp curves.
Several conditions sit outside the modeled scope, including geopolitical disruption to polysilicon or rare earth supply chains, acute discom financial distress triggering payment default cascades, and judicial intervention halting land acquisition for transmission corridors. Forecasts reflect documented assumptions regarding regulatory implementation timelines and technology cost curves. Deviation in CEA grid code enforcement stringency or MNRE green hydrogen subsidy allocation velocity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Equipment
Global Transformerless UPS Market
Power Equipment
Power Analyzers Market
Power Equipment
Portable Power Station Market
Power Equipment
Australia Power EPC Market
Power Equipment
Equatorial Guinea Power EPC Market
Power Equipment
Induction Heating System Market
Power Equipment
Wind Turbine Equipment Market
Power Equipment
SCR Power Controller Market
Power Equipment
North America Gas Turbine Market
Power Equipment
Thailand Power Market
Power Equipment
Global Exhaust Heat Recovery System Market
Power Equipment
Power Recovery Winches Market
Power Equipment
Kazakhstan Power EPC Market
Power Equipment
Power Plant Maintenance Market
Power Equipment
Process Plants Gas Turbine Market
Power Equipment
United Kingdom Power EPC Market