
 Global Distributed Energy Generation Market | 2026-2036
Global Distributed Energy Generation Market Size, Share, and Industry Trends Forecast 2026-2036
Global Distributed Energy Generation Market Analysis
Data center and healthcare campus demand is restructuring the commercial end-user segment for distributed energy generation. General Electric Company leverages its gas turbine and battery hybridization expertise to anchor utility-scale microgrid projects. Siemens Energy AG competes on electrolyzer-integrated solutions that sustain green hydrogen linkages to distributed solar farms. Schneider Electric dominates building-level energy management software that controls on-grid and off-grid switching logic.
Distributed energy generation encompasses modular power production systems—typically sub-50 MW capacity—sited near consumption points and often incorporating reciprocating engines, photovoltaic arrays, small wind turbines, or solid oxide fuel cells with combined heat and recovery cycles. These systems serve industrial facilities, campuses, and residential clusters seeking supply resilience and demand charge reduction. Solar technology leads installation volume across residential and commercial segments, though fuel cells command premium margin pools in baseload-critical applications. Microgrid architecture is the fastest-growing installation type, driven by islanding capability requirements in hurricane-prone and grid-unstable zones. Small and medium scale systems occupy the broadest addressable base, while utility scale deployments concentrate among independent power producers and campus operators.
The EPA enforces emissions standards for stationary reciprocating engines that shape natural gas generator set specifications across US industrial sites. EMA and CE marking frameworks govern fuel cell and biomass system safety certifications for European commercial deployments. India's CEA mandates grid code compliance for all distributed resources above designated capacity thresholds, directing inverter and protection relay procurement. Stakeholders must monitor evolving interconnection tariff structures and carbon border adjustment mechanisms to calibrate technology portfolios and geographic deployment sequencing.
Market Dynamics
Commercial microgrid deployments across data centers and healthcare campuses are restructuring procurement patterns for on-site power, compressing project timelines and forcing equipment suppliers to bundle hardware with software-defined control layers.
Growth Catalysts
- EU Green Deal:The framework accelerates interconnection standards for behind-the-meter assets across European industrial zones, streamlining permitting for commercial solar-plus-storage installations.
- India rural electrification mandates:Central Electricity Authority directives converge with industrial backup requirements, creating dual-demand pull for modular gas turbine and photovoltaic hybrid systems.
- Electrolyzer-integrated microgrids:Green hydrogen linkages to distributed solar farms unlock islanding capability for baseload-critical facilities seeking supply resilience.
Market Restraints
- Natural gas price volatility:Stationary reciprocating engine economics fluctuate with pipeline supply constraints, compressing project IRRs for US industrial cogeneration proposals.
- Inverter supply concentration:Power electronics manufacturing clusters in East Asia create single-source vulnerability for grid-forming inverter procurement across European campus operators.
- EPA emissions compliance:Tier 4 final standards for stationary engines impose after-treatment cost burdens that erode distributed generation payback periods against utility rates.
Strategic Opportunities
- India commercial and industrial segment:Underpenetrated distributed solar-plus-diesel hybridization presents white space for turnkey microgrid developers serving manufacturing clusters.
- US state-level net metering reforms:Evolving interconnection tariff structures in California and New York create regulatory arbitrage for behind-the-meter battery dispatch optimization.
- Fuel cell-solid oxide convergence:Combined heat and power recovery cycles paired with electrolyzer waste heat integration unlock premium margin pools in hospital and university campuses.
Industry Challenges
- Protection relay engineering talent scarcity:Grid code compliance for distributed resources above CEA-mandated thresholds requires specialized skills concentrated among aging utility engineering workforces.
- Legacy building management system integration:Schneider Electric and competing energy management software must bridge Modbus and BACnet protocols to enable seamless on-grid/off-grid switching logic.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Distributed Energy Generation Market |
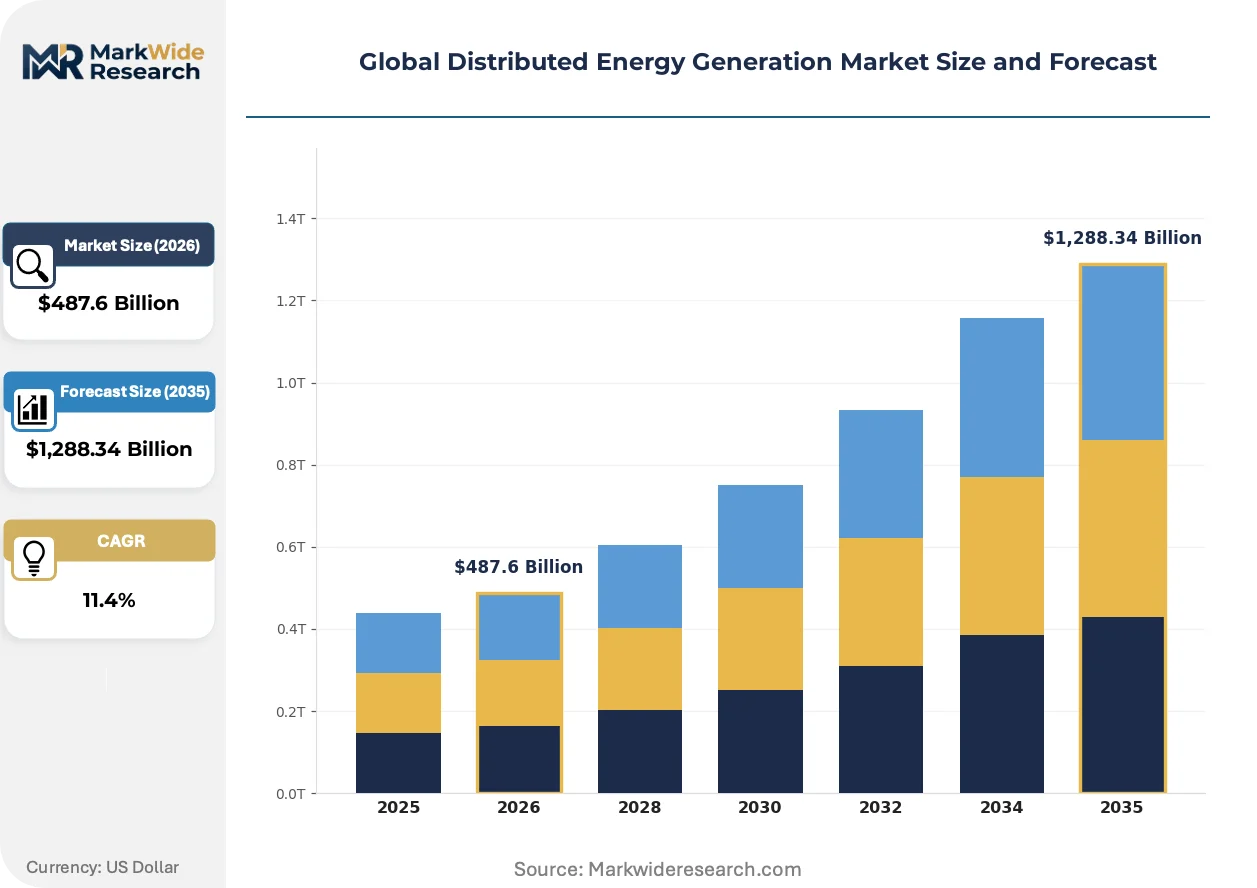
| Market Size in 2026 | $487.6 Billion |
| Market Size in 2035 | $1,288.34 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Solar, Wind, Biomass, Fuel Cells End User: Residential, Commercial, Industrial, Agricultural Installation Type: On-Grid, Off-Grid, Hybrid, Microgrid Capacity Range: Small Scale, Medium Scale, Large Scale, Utility Scale |
| Companies Covered | General Electric Company, Siemens Energy AG, Schneider Electric, Caterpillar Inc., Cummins Inc., Mitsubishi Electric Corp., Bloom Energy, Vestas Wind Systems A/S, Capstone Turbine Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Distributed Energy Generation Market Emerging Trajectories
Hybridization architectures are collapsing technology silos that historically separated thermal generation from electrochemical storage and power electronics control.
Containerized battery-gas turbine hybrid systems are unifying spinning reserve and frequency regulation functions within single skid-mounted packages. Data center operators in hurricane-prone US Gulf Coast states are adopting these configurations to compress project development timelines from 24 months to 14 months. The technology is unifying procurement decisions that previously required separate RFPs for generation and storage assets.
Carbon border adjustment mechanisms are reshaping equipment sourcing strategies for European independent power producers. The EU's phased implementation of embedded carbon tariffs on imported steel and aluminum is forcing inverter and enclosure manufacturers to certify supply chain emissions or face margin compression. Campus operators in Germany and the Netherlands are now requiring Scope 3 documentation as a contract precondition.
Energy-as-a-service contracting is displacing traditional equipment ownership models among US healthcare systems. Hospital facility managers in Texas and Florida are transferring capex risk to microgrid developers in exchange for 15-year power purchase agreements with guaranteed uptime clauses. This shift concentrates operational expertise with specialized developers while fragmenting vendor relationships for prime equipment suppliers.
Global Distributed Energy Generation Market Segmentation
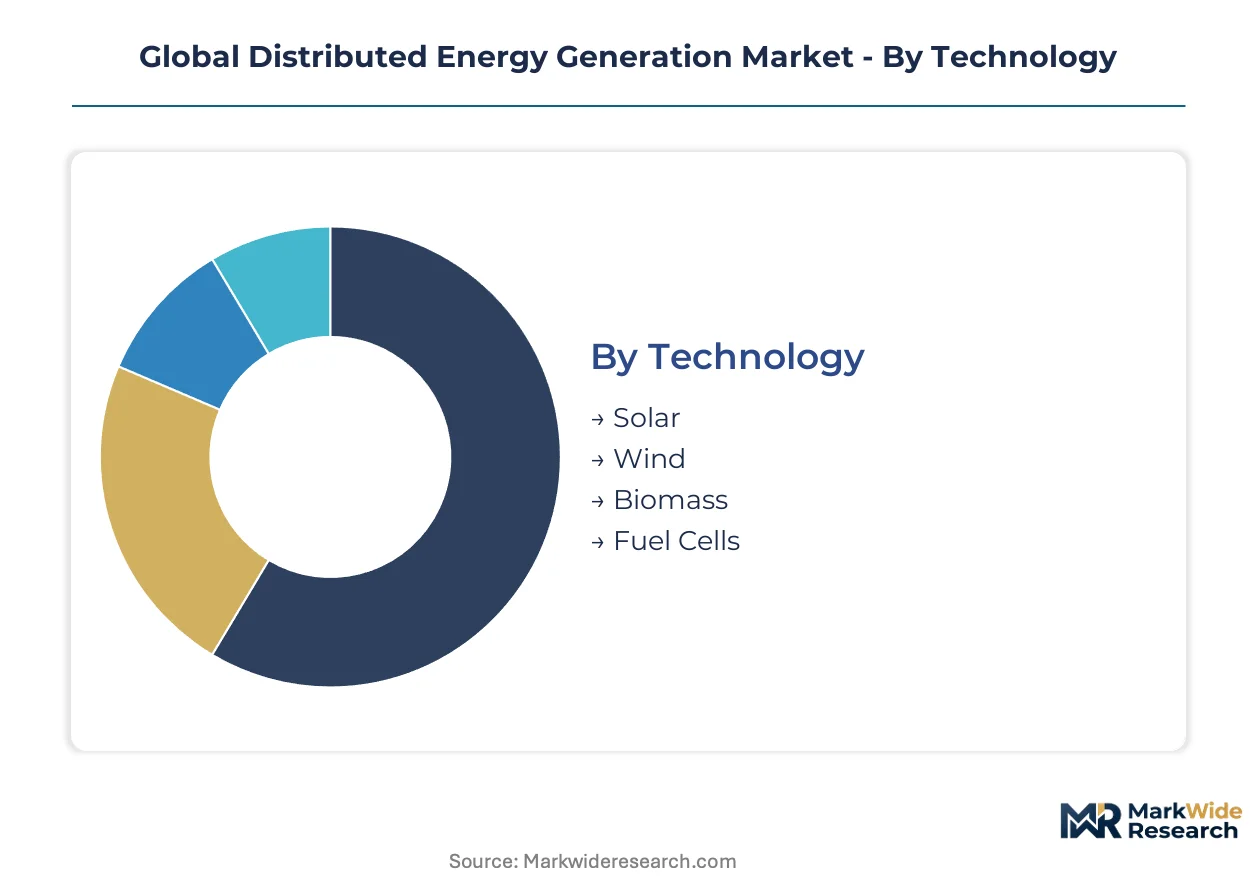
Distributed energy generation markets fragment across four critical dimensions that determine equipment specifications, project economics, and procurement channels. Technology choice dictates capital intensity and regulatory exposure. End-user segment shapes financing structures and resilience requirements. Installation type and capacity range together define grid interconnection complexity and operator skill demands.
Technology:
Photovoltaic arrays and electrochemical conversion systems anchor the technology landscape with diverging cost curves and duty-cycle profiles.
- Solar:Crystalline silicon and thin-film photovoltaic modules dominate residential rooftop and commercial ground-mount deployments. Installation volume concentrates across Indian manufacturing clusters and US data center campuses where EPA renewable energy credits offset interconnection costs.
- Fuel Cells:Solid oxide and proton exchange membrane systems deliver baseload power with combined heat recovery for hospital and university microgrids. Premium margins attach to electrolyzer-integrated configurations that sustain green hydrogen production during grid outages.
- Wind:Small-scale horizontal and vertical axis turbines serve agricultural pumping and remote telecom loads where solar irradiance proves insufficient.
- Biomass:Anaerobic digesters and gasification units process agricultural residue for rural electrification in India and combined heat applications in European district heating networks.
Mature deployment sits with solar photovoltaic systems. Newer deployment is concentrated in fuel cell-solid oxide hybrid configurations.
End User:
Customer archetypes separate by resilience requirements, load predictability, and access to capital markets for project finance.
- Commercial:Data center and healthcare campus operators drive procurement for microgrid architectures with islanding capability. Texas and Florida hospital systems favor energy-as-a-service contracting to transfer capex risk while securing guaranteed uptime clauses.
- Industrial:Manufacturing facilities deploy gas turbine and battery hybrid systems to manage demand charges and process continuity. India's CEA grid code compliance mandates shape inverter and protection relay specifications for facilities above designated capacity thresholds.
- Residential:Behind-the-meter solar-plus-storage installations respond to state-level net metering reforms in California and New York, with interconnection tariff arbitrage driving battery dispatch optimization.
- Agricultural:Remote pumping and cold storage loads adopt small wind and biomass solutions where grid extension proves uneconomical.
Volume leadership belongs to commercial end users. Margin expansion concentrates with industrial microgrid developers.
Installation Type:
Grid coupling architecture determines control system complexity, regulatory jurisdiction, and revenue stacking opportunities.
- Microgrid:Islanding-capable systems unify generation, storage, and load management under single control layers. Hurricane-prone US Gulf Coast states compress project timelines from 24 months to 14 months through containerized battery-gas turbine packages.
- Hybrid:Solar-plus-diesel and solar-plus-battery configurations serve Indian manufacturing clusters with dual-mode operation across grid-connected and off-grid states.
- On-Grid:Behind-the-meter assets participate in wholesale markets through FERC Order 2222 aggregation frameworks.
- Off-Grid:Standalone systems address rural electrification mandates in India and remote mining camps in Australia.
Regulatory complexity peaks with microgrid architectures. Simplified permitting attaches to established on-grid configurations.
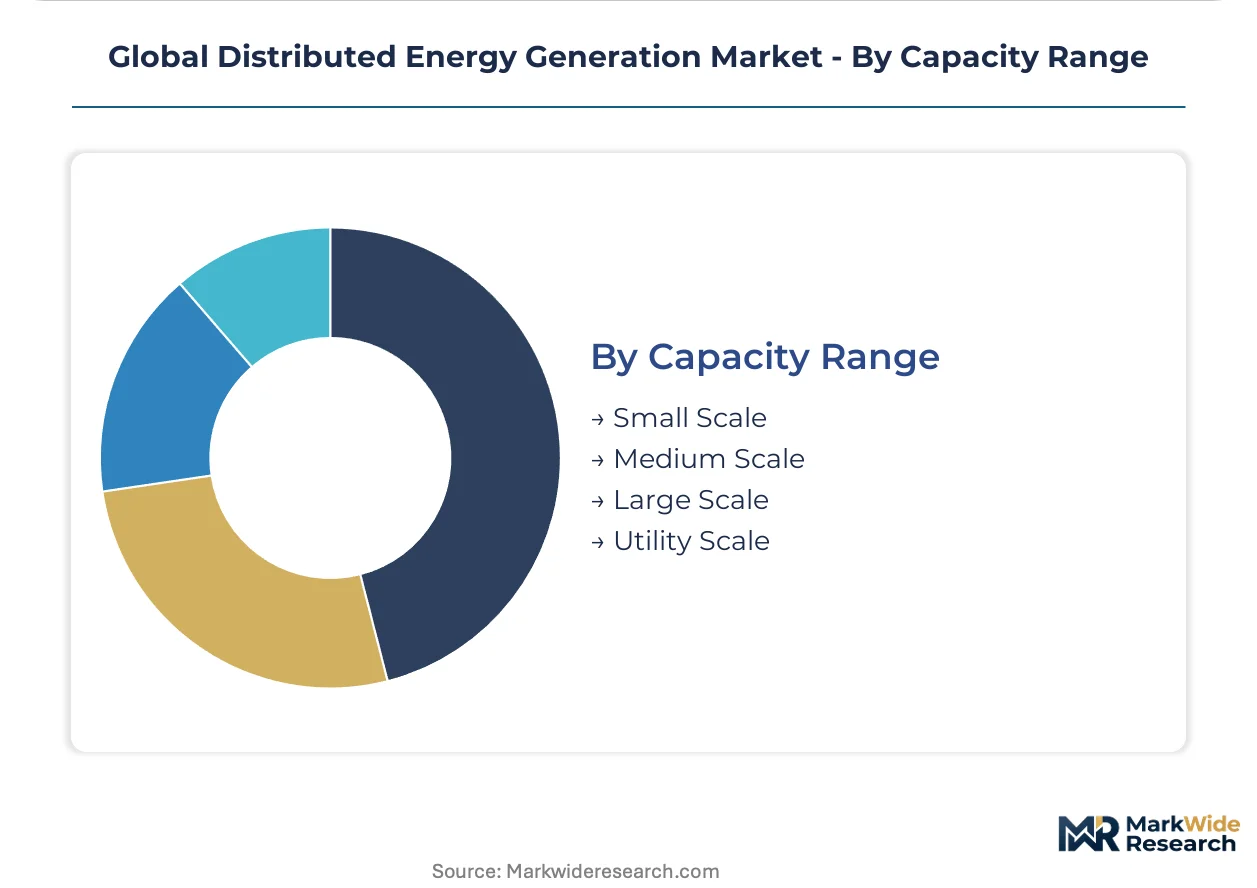
Capacity Range:
Scale thresholds segment equipment suppliers, engineering procurement construction contractors, and financing channels.
- Utility Scale:Sub-50 MW installations near load centers anchor independent power producer portfolios and campus operator self-generation strategies.
- Medium Scale:Commercial building and industrial facility systems occupy the broadest addressable base with standardized inverter and protection relay packages.
- Small Scale:Residential and agricultural deployments concentrate inverter supply vulnerability in East Asian manufacturing clusters.
- Large Scale:District energy and multi-building campus systems require specialized grid-forming controls and legacy building management system integration.
Equipment standardization is highest at medium scale. Custom engineering demands concentrate at utility scale.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in India and tax credit territories across the United States concentrate distributed energy deployment, while EU carbon border mechanisms reshape equipment sourcing decisions for European campus operators.
United States
Data center construction in Virginia's Loudoun County and Texas's Hays County drives demand for containerized battery-gas turbine hybrids. State-level net metering reforms in California and New York compress interconnection timelines for behind-the-meter solar-plus-storage. FERC Order 2222 aggregation frameworks enable wholesale market participation for campus microgrids in PJM and ERCOT territories.
India
Rural electrification mandates in Uttar Pradesh and Bihar converge with industrial backup requirements in Gujarat's manufacturing corridors. Central Electricity Authority grid code compliance directs inverter procurement for facilities above designated capacity thresholds. Tamil Nadu's solar parks and Maharashtra's industrial clusters anchor hybrid microgrid deployments serving textile and automotive suppliers.
Germany
Campus operators in North Rhine-Westphalia and Bavaria require Scope 3 documentation for inverter and enclosure procurement under phased carbon border adjustment implementation. EU Green Deal interconnection standards streamline permitting for commercial solar-plus-storage in industrial zones. EMA safety certifications govern fuel cell deployments for hospital microgrids in Berlin and Munich metropolitan areas.
China
Dual carbon goals accelerate distributed photovoltaic deployment in Jiangsu and Zhejiang manufacturing belts. GB standards and MIIT regulations shape power electronics specifications for grid-forming inverters. Yangtze River Delta data center clusters adopt electrolyzer-integrated configurations to sustain green hydrogen production during grid instability events.
Australia
Remote mining camps in Western Australia and Queensland drive off-grid diesel-solar hybrid demand where grid extension proves uneconomical. State-level renewable energy targets in New South Wales and Victoria compress project development timelines for agricultural pumping applications. TGA-equivalent electrical safety frameworks govern inverter certification for behind-the-meter residential installations.
Global Distributed Energy Generation Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated technology conglomerates commanding utility-scale microgrid deployments while regional fabricators capture standardized residential inverter volumes. The vendor base organizes into three strategic archetypes: turbine-battery hybridization specialists, building-level energy management software providers, and fuel cell-solid oxide convergence engineers. M&A activity concentrates on control software acquisitions, while capacity expansion targets East Asian power electronics manufacturing clusters.
Among turbine and power generation conglomerates, General Electric Company and Siemens Energy AG occupy positions anchoring utility-scale project development. Schneider Electric exemplifies the building-level control software archetype through energy management platforms governing on-grid and off-grid switching logic. These three entities represent distinct competitive vectors—hardware hybridization, electrolyzer integration, and software-defined microgrid control—that structure procurement decisions across commercial and industrial end users.
| Leading Market Players |
|---|
| General Electric Company |
| Siemens Energy AG |
| Schneider Electric |
| Caterpillar Inc. |
| Cummins Inc. |
| Mitsubishi Electric Corp. |
| Bloom Energy |
| Vestas Wind Systems A/S |
| Capstone Turbine Corporation |
| Others |
Supply Flow & Price Mechanics
Grid-forming inverter engineering talent concentrated in Germany and California commands wage premiums that compress pricing-tier spreads between premium-certified and standard-grade microgrid control systems. Labor-cost differentials between these specialized engineering clusters and emerging technical centers in India widen margin pools for equipment suppliers able to source qualified protection relay design capability at lower cost points.
Pricing Analysis
Short lead-time premiums attach to containerized battery-gas turbine hybrid systems where data center operators in hurricane-prone zones compress procurement cycles. Three-tier pricing structure across premium, standard, and economy levels separates UL-certified islanding controls from CE-marked commercial packages and uncertified industrial inverters. Pricing pressure stems from East Asian power electronics manufacturing scale flooding standard-grade inverter markets. Industrial manufacturing clusters in India exhibit highest price sensitivity, while US healthcare campuses prioritize guaranteed uptime over unit cost.
Supply Chain Analysis
CE marking and UL certification gating restricts inverter and protection relay sourcing to qualified manufacturing facilities in China, South Korea, and Germany. Power electronics production draws from polysilicon feedstocks, lithium-ion cell supply, and rare earth magnet flows concentrated in East Asian processing corridors. Single-source vulnerability runs through Taiwanese semiconductor foundry capacity serving grid-forming control chipsets. Distribution runs through EPC contractors and specialized microgrid developers rather than direct OEM-to-end-user channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Power electronics manufacturing capacity constraints in qualified facilities prop pricing power for certified equipment suppliers, creating supply-constrained market dynamics that favor incumbents with secured foundry relationships.
For Market Incumbents: Acquire grid-forming inverter software stacks to anchor control-layer differentiation against emerging digital-native entrants. Backward integration into power semiconductor sourcing mitigates single-source exposure from East Asian foundry concentration. Capacity addition in Indian engineering centers captures labor-cost arbitrage for protection relay development. For New Entrants and Emerging Players: Energy-as-a-service digital platforms offer route-to-market acceleration for microgrid developers seeking hospital and university campus contracts. White space concentrates in Indian commercial and industrial solar-plus-diesel hybridization where turnkey integration capability remains underpenetrated. Direct-to-utility sales channels bypass established EPC relationships in deregulated US state markets. For Investors and Strategic Acquirers: Re-rating potential sits with electrolyzer-integrated microgrid specialists given EU carbon border adjustment implementation accelerating green hydrogen linkages. Long-term viability favors asset-light control software developers with recurring revenue streams over capital-intensive turbine manufacturers. Watch FERC Order 2222 aggregation framework adoption rates as inflection indicator for behind-the-meter battery dispatch optimization demand.| Strategic Initiative | Industry Significance |
|---|---|
| Electrolyzer-Integrated Microgrid Development | EU Green Deal carbon border mechanisms force Scope 3 documentation requirements onto campus operators. |
| Grid-Forming Inverter Software Acquisition | CEA-mandated protection relay compliance in India creates specialized engineering scarcity premiums. |
| Containerized Battery-Gas Turbine Packaging | US Gulf Coast data center demand compresses project timelines from 24 months toward 14 months. |
| Energy-as-a-Service Platform Launch | Texas and Florida healthcare systems transfer capex risk through 15-year power purchase agreements. |
| East Asian Power Electronics Capacity Expansion | Inverter supply concentration creates single-source vulnerability for European campus operators. |
Methodological Framework
EIA databases, IEA market reports, and FERC interconnection filings formed the secondary backbone for capacity deployment and regulatory trend validation. Primary interviews with utility planning officers, IPP project developers, EPC contractors, and grid operators cross-referenced against customs data and equipment certification records. Bottom-up project pipeline analysis triangulated with top-down macroeconomic scenario modeling to anchor volume and value estimates.
Historical trendline analysis of capacity additions and technology cost curves established baseline growth trajectories across the projection horizon. Segmentation modeling incorporated fuel source, generation capacity tier, project scale, regulatory framework, and regional grid type dimensions. CAGRs derived from fitted growth curves adjusted for policy discontinuities and interconnection queue backlogs. Forecast inputs included solar module price trajectories and natural gas pipeline capacity constraints.
Inputs from CEA regulatory filings and EPA emissions compliance databases were available through the study window; gaps in real-time interconnection queue status introduce uncertainty bands around near-term deployment timing. Forecasts reflect documented assumptions regarding policy continuity and technology cost reduction rates. Material shifts in FERC Order 2222 implementation pace or EU carbon border adjustment phase-in schedules warrant model refresh.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Generation
India Thermal Power Plant Market
Power Generation
Philippines Power Generation EPC Market
Power Generation
India Gas Generator Market
Power Generation
On-Grid Combined Heat and Power Market
Power Generation
Australia Thermal Power Market
Power Generation
Power Sector North America Gas Turbine MRO Market
Power Generation
Peaking Power Plant Market
Power Generation
Brazil Power Plant EPC Market
Power Generation
United Kingdom Combined Heat and Power (CHP) Market
Power Generation
Global Gas Turbines Market
Power Generation
Wind Power EPC Market
Power Generation
Global Gensets Market
Power Generation
South America Thermal Power Market
Power Generation
Gas Gensets Market
Power Generation
Stirling Engine Market
Power Generation
Myanmar Power Generation EPC Market