
 Virtual Data Optimizer Market | 2026-2036
Virtual Data Optimizer Market Size, Share, and Industry Trends Forecast 2026-2036
Virtual Data Optimizer Market Intelligence
GDPR is realigning the cost-of-entry calculus for virtual data optimizer vendors serving European enterprise accounts. IBM Corporation leverages deep mainframe integration heritage to anchor high-assurance government workloads. Microsoft Corporation competes through native Azure optimization layers that extend hybrid cloud reach. Red Hat, Inc. specializes in open-source data services that sustain price flexibility for mid-market Linux deployments.
Virtual Data Optimizer denotes software-defined storage technology that applies inline compression, deduplication, and intelligent tiering to reduce physical storage footprint while maintaining sub-millisecond access latency for active datasets. The technology serves primary industrial purposes in backup acceleration, disaster recovery orchestration, and database performance optimization across virtualized infrastructure estates. Cloud-based deployment now leads solution type growth as enterprises exit capital-intensive on-premise refresh cycles, while data deduplication captures concentrated margin pools due to patented algorithmic differentiation among incumbent suppliers. Bandwidth optimization segments show fastest trajectory in telecommunications provider environments where 5G core network data volumes strain backhaul economics.
FCC broadband infrastructure rules in the United States, EU AI Act data governance provisions, and China's GB standards for cloud service security collectively shape product certification requirements and cross-border deployment permissions. ISO 27001 and SOC 2 Type II attestations function as table-stakes credentials for vendor shortlists in financial services and government procurement channels. Stakeholders must monitor evolving data sovereignty rulings across jurisdictions to determine whether distributed edge architectures or centralized cloud instances deliver superior compliance-adjusted returns.
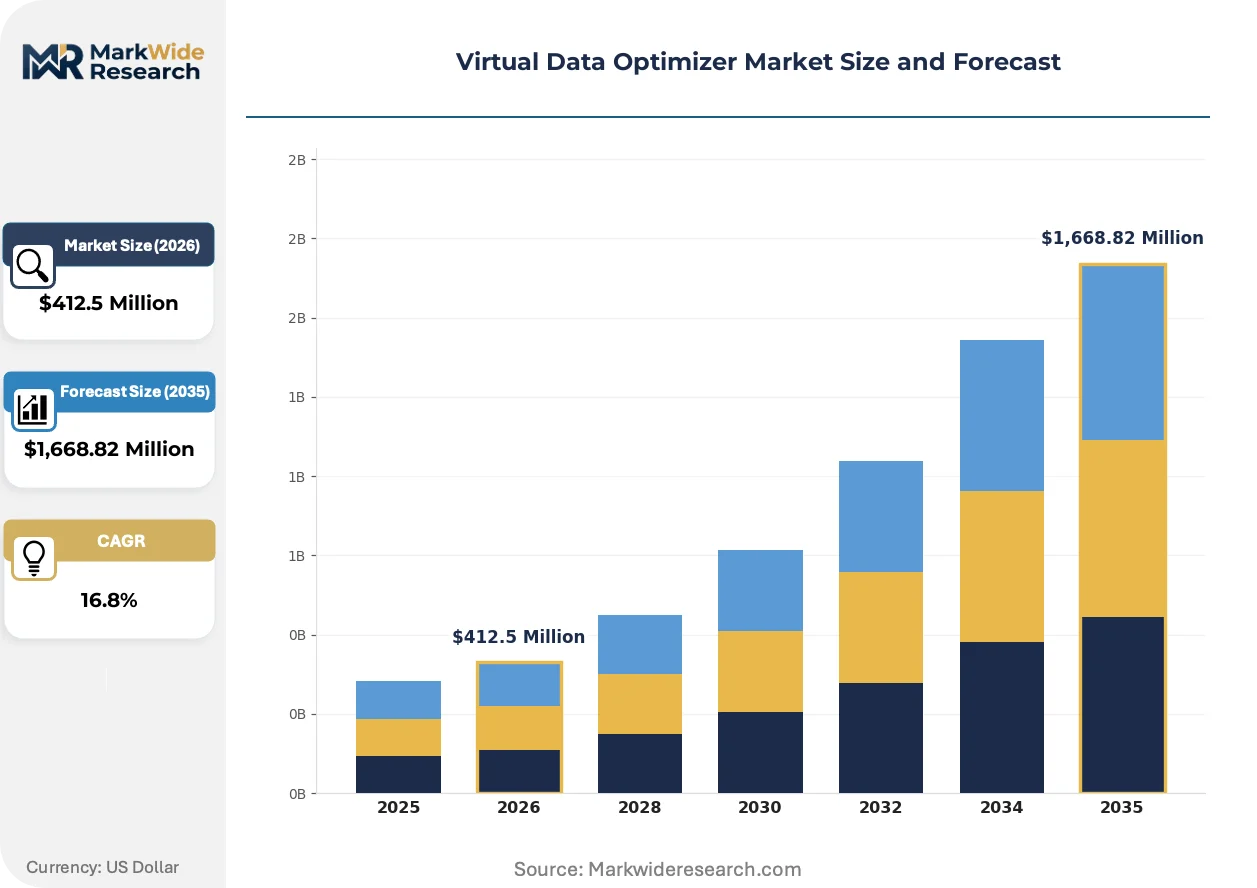
Market Dynamics
Cloud migration mandates across enterprise IT estates are compressing refresh cycles for legacy storage architectures while hyperscale data center construction reshapes procurement priorities toward software-defined consumption models.
Growth Catalysts
- EU AI Act data governance provisions:Financial services firms in Europe are expanding virtual data optimizer deployment to manage exponential data growth under stricter algorithmic accountability mandates. The regulation forces retention and auditability standards that compression and tiering technologies address directly.
- 5G core network expansion:Telecommunications providers are adopting bandwidth optimization segments at the fastest trajectory as backhaul economics strain under massive data volumes. Virtual data optimizers reduce transport costs for mobile network operators.
- Federal cloud-first directives:United States government procurement priorities are redirecting capital toward cloud-native storage optimization. Federal agencies now require inline deduplication and intelligent tiering for primary dataset management.
Market Restraints
- Patented algorithmic concentration:Data deduplication margin pools concentrate among incumbent suppliers with protected intellectual property, creating barriers for new entrants seeking price-competitive positioning.
- Silicon supply volatility:Specialized accelerator chips for compression workloads face fabrication bottlenecks at advanced nodes, extending lead times for high-performance appliance deployments.
- Legacy mainframe integration friction:IBM Corporation's deep mainframe heritage anchors high-assurance government workloads, creating switching costs for agencies seeking alternative vendor ecosystems.
Strategic Opportunities
- Edge computing architectures:Distributed edge deployments across manufacturing and autonomous vehicle infrastructure create demand for lightweight optimization software that operates without centralized cloud connectivity.
- ISO 27001 attestation expansion:Financial services and government procurement channels increasingly require SOC 2 Type II credentials as table-stakes, opening vendor shortlist positions for certified mid-market specialists.
- Hybrid cloud orchestration convergence:Native Azure optimization layers are extending reach across on-premise and public cloud estates, enabling unified data services that span heterogeneous infrastructure.
Industry Challenges
- Data sovereignty compliance complexity:Evolving rulings across jurisdictions force vendors to architect separate instances for localized residency requirements, multiplying operational overhead without proportional revenue expansion.
- Sub-millisecond latency preservation:Maintaining access performance for active datasets while applying inline compression demands specialized engineering talent scarce in mainstream storage disciplines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Virtual Data Optimizer Market |
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $1,668.82 Million |
| CAGR (2026 – 2036) | 16.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premise, Cloud-Based, Hybrid, Edge Computing Solution Type: Data Compression, Deduplication, Data Caching, Bandwidth Optimization, Data Tiering Application: Backup & Recovery, Disaster Recovery, Big Data Management, Database Optimization, Server Virtualization End User: Telecommunications Providers, Financial Services Firms, Media Enterprises, Government Agencies, Educational Institutions |
| Companies Covered | IBM Corporation, Microsoft Corporation, Oracle Corporation, Hewlett Packard Enterprise, Red Hat, Inc., Fujitsu Limited, VMware, Inc., SAP SE, Intel Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Virtual Data Optimizer Market Strategic Shifts & Innovations
Intelligent tiering algorithms are actively displacing static storage policies as the dominant architecture for enterprise data lifecycle management, with machine learning inference now governing placement decisions.
Inline compression hardware is integrating neural processing units that analyze dataset entropy patterns in real-time. Financial services trading platforms are adopting these accelerators at compressed deployment timelines. The technology is integrating predictive models that pre-position data before access requests arrive, collapsing retrieval latency for high-velocity workloads.
China's GB standards for cloud service security are mandating encryption-at-rest and access logging specifications that virtual data optimizer vendors must certify against. Domestic providers are reconfiguring software stacks to satisfy these attestations before foreign competitors complete compliance. State-owned enterprises and critical infrastructure operators represent the most affected buyer segment, with procurement specifications now excluding uncertified alternatives.
Consumption-based pricing models are displacing perpetual license structures across mid-market enterprise accounts. Managed service providers are capturing margin through bundled optimization-as-a-service offerings that unbundle hardware procurement from software entitlement. North American manufacturing verticals show the most visible acceleration toward operational expenditure structures, with automotive suppliers leading the transition away from capital-intensive on-premise refresh cycles.
Virtual Data Optimizer Market Segmentation
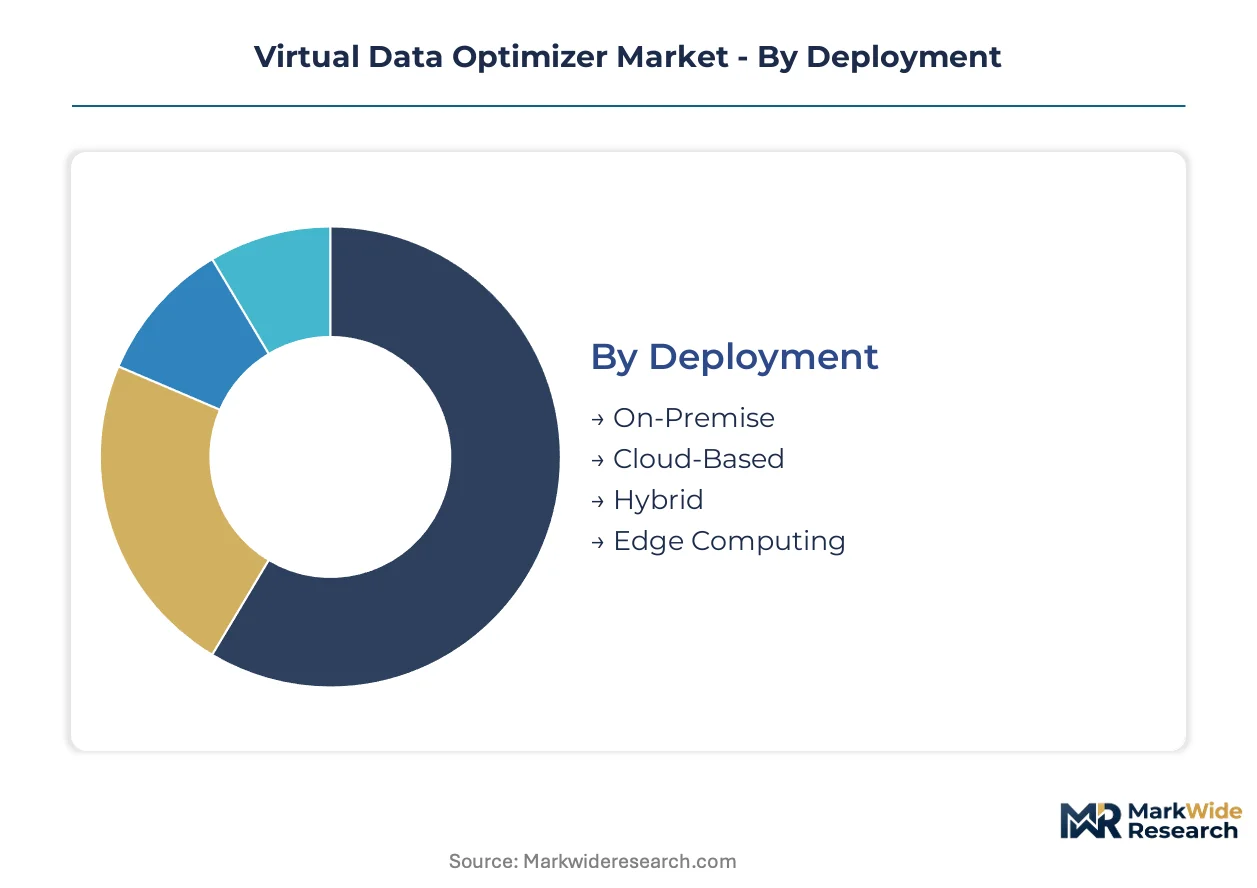
Segmentation reveals how procurement priorities diverge across infrastructure maturity levels and regulatory exposure. Cloud-native buyers prioritize operational flexibility while regulated sectors demand certified on-premise control. Understanding these splits enables vendors to align product roadmaps with buyer willingness-to-pay curves.
Deployment:
Volume concentrates in cloud-based configurations while premium pricing persists in specialized edge deployments.
- Cloud-Based:Consumption models dominate enterprise procurement as organizations exit capital-intensive refresh cycles. Financial services firms in the United States drive demand through federal cloud-first directives that mandate inline optimization for primary datasets.
- On-Premise:High-assurance workloads require physical infrastructure control under data sovereignty mandates. European banking regulators enforce residency requirements that keep significant deployment share in localized hardware despite cloud migration trends.
- Hybrid:Orchestration layers span heterogeneous estates for unified data services. Manufacturing verticals favor this architecture for staged cloud transitions without operational disruption.
- Edge Computing:Lightweight optimization software operates without centralized connectivity for autonomous systems. Telecommunications providers deploy at 5G base stations to reduce backhaul transport costs.
Today's leader: Cloud-Based. Tomorrow's challenger: Edge Computing.
Solution Type:
Margin pools concentrate in algorithmically differentiated segments while commoditized functions compete on price.
- Deduplication:Patented hashing algorithms create vendor lock-in through proprietary intellectual property. Incumbents with protected compression methods command premium pricing in government procurement channels requiring SOC 2 Type II attestation.
- Data Compression:Neural processing units now accelerate entropy analysis in real-time for trading platforms. Financial services adoption concentrates in high-velocity workloads where latency preservation determines competitive advantage.
- Bandwidth Optimization:Telecommunications providers adopt at the steepest expansion trajectory as mobile data volumes strain transport economics. 5G core network expansion directly correlates with procurement acceleration.
- Data Caching:Predictive pre-positioning collapses retrieval latency for database workloads. Media enterprises deploy for content delivery acceleration across distributed CDN nodes.
- Data Tiering:Machine learning inference governs placement decisions displacing static policies. Intelligent algorithms now dominate enterprise lifecycle management architecture.
Margin accretion favors Deduplication. Volume expansion favors Bandwidth Optimization.
Application:
Backup functions generate recurring revenue streams while database optimization commands project-based premium pricing.
- Backup & Recovery:Inline compression accelerates transfer windows for enterprise protection policies. Cloud migration mandates reshape procurement toward software-defined consumption models.
- Database Optimization:Sub-millisecond latency requirements demand specialized engineering talent scarce in mainstream storage disciplines. Financial services trading platforms drive specification intensity.
- Disaster Recovery:Orchestration capabilities determine vendor selection for business continuity planning. Regulatory mandates across multiple jurisdictions enforce retention and auditability standards.
- Big Data Management:Intelligent tiering reduces physical footprint for analytics workloads. Hyperscale data center construction prioritizes optimization in procurement specifications.
- Server Virtualization:Density improvements extend hardware refresh cycles for capital-constrained IT estates. Mid-market enterprises favor this entry point for optimization technology adoption.
Recurring revenue anchors Backup & Recovery. Premium projects concentrate in Database Optimization.
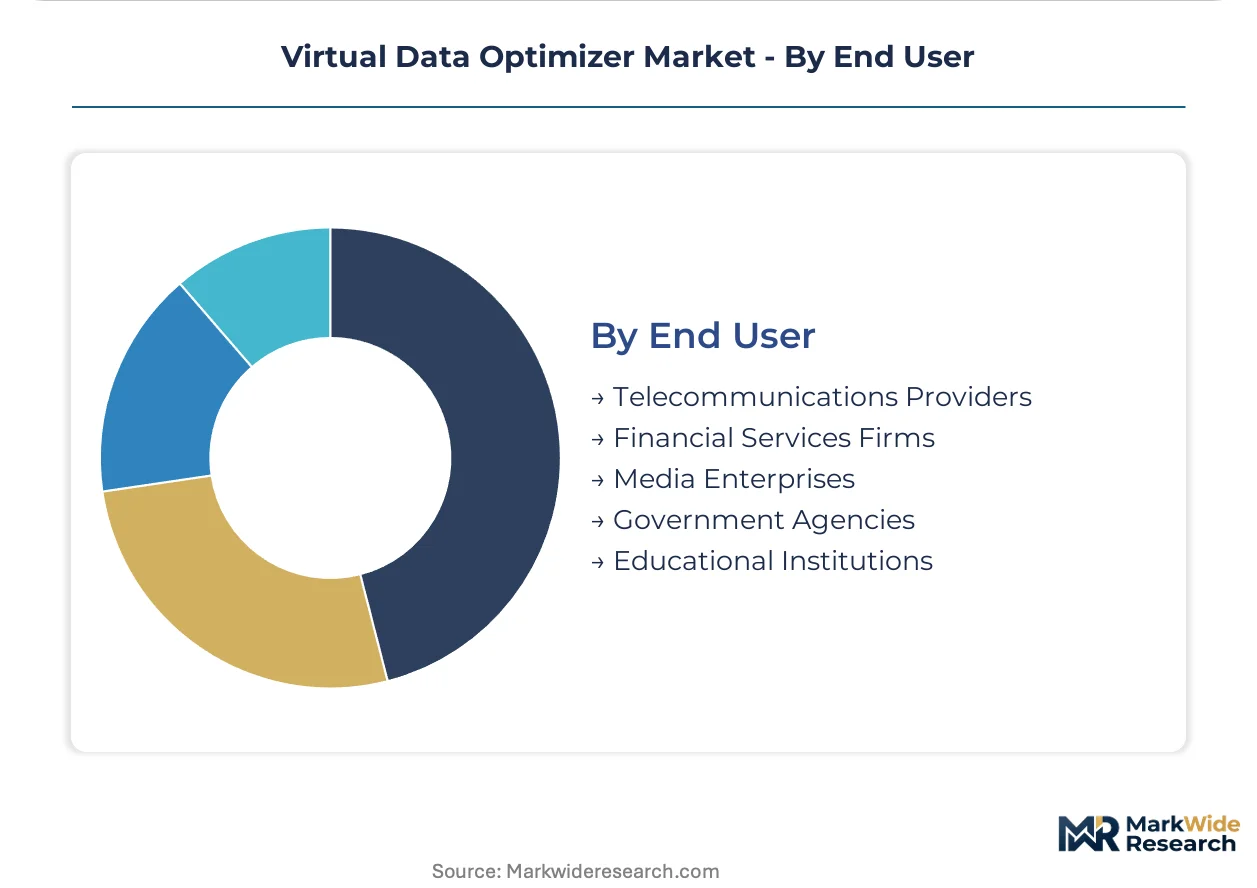
End User:
Procurement sophistication varies sharply between regulated incumbents and technology-native challengers.
- Financial Services Firms:GDPR and EU AI Act compliance mandates force algorithmic accountability investments. Retention standards drive deduplication and tiering procurement across European enterprise accounts.
- Telecommunications Providers:5G core network data volumes strain backhaul economics. Bandwidth optimization adoption climbs fastest among mobile network operators managing transport cost pressure.
- Government Agencies:Federal cloud-first directives in the United States redirect capital toward cloud-native storage. ISO 27001 and SOC 2 Type II function as table-stakes credentials for vendor shortlists.
- Media Enterprises:Content delivery requirements prioritize caching and compression for global distribution. CDN integration determines vendor selection criteria.
- Educational Institutions:Budget constraints favor open-source data services with price flexibility. Research data management creates specialized tiering requirements.
Regulated premium: Financial Services Firms. Volume expansion: Telecommunications Providers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized compression engineering talent concentrates in United States technology corridors, European financial centers, and East Asian semiconductor clusters, anchoring regional deployment patterns for virtual data optimizer infrastructure.
United States
Hyperscale data center construction in Northern Virginia and Dallas-Fort Worth drives procurement volume for cloud-native optimization layers. FCC broadband infrastructure rules mandate data governance specifications for federal contractor eligibility. Financial services firms in New York and Chicago deploy inline deduplication under SEC record-keeping enforcement.
Germany
Automotive manufacturers in Stuttgart and Munich adopt hybrid orchestration for staged cloud transitions without operational disruption. EU AI Act data governance provisions enforce algorithmic accountability standards that compression technologies address. Industrial machinery clusters in Baden-Württemberg integrate intelligent tiering for predictive maintenance data lakes.
China
State-owned enterprises in Beijing and Shanghai reconfigure software stacks to satisfy GB standards for cloud service security before foreign competitors complete compliance. MIIT mandates encryption-at-rest specifications for critical infrastructure operators. Domestic providers dominate procurement in Yangtze River Delta data center zones.
Japan
Financial services trading platforms in Tokyo adopt neural processing unit accelerators for real-time entropy analysis. METI promotes software-defined storage adoption through industrial digitalization incentives. Osaka-based telecommunications providers deploy bandwidth optimization at 5G base stations to reduce backhaul transport costs.
United Kingdom
GDPR realignment forces retention and auditability investments across London financial services accounts. FCA operational resilience rules mandate disaster recovery orchestration capabilities for systemic institutions. Manchester and Edinburgh technology clusters specialize in open-source data services for mid-market price flexibility.
Virtual Data Optimizer Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. Patent-protected deduplication algorithms create vendor lock-in through proprietary intellectual property concentration. Three archetypes dominate: mainframe-integrated incumbents, cloud-native platform extenders, and open-source middleware specialists. Competitive moves center on hybrid cloud orchestration convergence and ISO 27001 attestation expansion for financial services procurement channels.
Within the mainframe-integrated tier, IBM Corporation anchors high-assurance government workloads through deep heritage positioning. Microsoft Corporation exemplifies cloud-native platform extension through native Azure optimization layers. Red Hat, Inc. occupies the open-source specialist position, sustaining price flexibility for mid-market Linux deployments. These three represent distinct strategic vectors rather than direct substitution competitors.
| Leading Market Players |
|---|
| IBM Corporation |
| Microsoft Corporation |
| Oracle Corporation |
| Hewlett Packard Enterprise |
| Red Hat, Inc. |
| Fujitsu Limited |
| VMware, Inc. |
| SAP SE |
| Intel Corporation |
| Others |
Cost & Logistics Intelligence
Private-equity-rolled-up storage software specialists anchor pricing discipline through portfolio company cross-selling mandates while simultaneously compressing supply chain costs through centralized silicon procurement offices in Taiwan and South Korea. This ownership structure concentrates negotiation leverage against foundry partners and enforces margin protection through bundled service packaging that obscures component-level pricing transparency.
Pricing Analysis
Bundled optimization-as-a-service offerings now dominate enterprise procurement while unbundled perpetual licenses persist only in government accounts with frozen capital budgets. Three-tier pricing structure across premium, standard, and economy levels differentiates by SOC 2 Type II certification grade and neural processing unit acceleration availability. Pricing pressure stems from open-source middleware alternatives eroding mid-market license values. Educational institutions exhibit highest price sensitivity due to constrained budgets, while financial services trading platforms show lowest sensitivity where latency preservation commands premium outlays.
Supply Chain Analysis
Neural processing unit fabrication rests on Taiwan Semiconductor Manufacturing capacity allocation and Samsung Foundry advanced node availability, with Intel Foundry Services emerging as a tertiary option. Specialized compression accelerator chips, high-bandwidth memory modules, and precision timing components constitute critical input dependencies. Single-source vulnerability concentrates in EUV lithography equipment held by ASML in the Netherlands. Distribution runs through hyperscale cloud marketplaces for cloud-based deployments and value-added resellers with security clearances for government channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage opportunities concentrate in European edge computing deployments where GDPR data residency requirements inflate local pricing premiums against standardized cloud rates available in United States hyperscale zones. Regulatory friction creates sustainable margin expansion for vendors with established EU operational footprints.
For Market Incumbents: Acquire specialized deduplication algorithm portfolios to fortify intellectual property moats against open-source compression libraries eroding proprietary value. Incumbents should anchor high-assurance government workloads through FedRAMP certification investments while extending hybrid orchestration layers to capture manufacturing verticals executing staged cloud transitions. Patent-protected hashing methods remain the critical defensive lever against price-competitive challengers. For New Entrants and Emerging Players: The premium-to-economy pricing gap in bandwidth optimization segments creates entry opportunity for telecommunications-focused specialists. New entrants should target mid-market Linux deployments in North American manufacturing verticals where Red Hat's open-source positioning has not yet saturated account penetration. A channel partnership strategy with managed service providers enables rapid scale without direct enterprise sales infrastructure. For Investors and Strategic Acquirers: Valuations sit cheapest among edge computing pure-plays lacking hyperscale cloud marketplace distribution. Long-term viability over the next decade hinges on adaptive compliance architecture spanning evolving data sovereignty rulings across multiple jurisdictions. ISO 27001 attestation velocity among mid-market specialists signals acquisition timing for portfolio consolidation plays.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Cloud Orchestration Platform | Unified data services span heterogeneous estates for manufacturing cloud transitions. |
| Neural Processing Unit Integration | Real-time entropy analysis accelerates financial services trading platform procurement. |
| Edge Computing Software Stack | Lightweight optimization operates without centralized connectivity for 5G base stations. |
| ISO 27001 Attestation Expansion | SOC 2 Type II credentials open government and financial services vendor shortlists. |
| Open-Source Middleware Specialist Acquisition | Price flexibility sustains mid-market Linux deployment competitiveness against bundled offerings. |
Research Approach
Direct dialogue with enterprise storage architects, cloud procurement officers, telecommunications network planners, and federal IT security officers grounded qualitative findings in operational reality. Secondary validation drew from hyperscaler capex disclosures, FCC broadband infrastructure filings, EU AI Act regulatory texts, and SEC 10-K software revenue segmentations. Bottom-up and top-down triangulation reconciled vendor shipment data with enterprise adoption surveys across deployment models.
Bottom-up modeling aggregated individual segment trajectories while top-down analysis constrained totals against macro IT infrastructure spending patterns. Segmentation dimensions spanned deployment architecture, solution type differentiation, application workload, and end-user regulatory exposure. CAGRs derived from fitted growth curves applied to base-year estimates, with neural processing unit penetration rates and 5G capital expenditure cycles serving as industry-specific demand drivers throughout the projection horizon.
Caveats apply where semiconductor fabrication bottlenecks, evolving data sovereignty rulings, or open-source compression library maturation could materially shift the outlook. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center and Networking
Global Subscriber Data Management Market
Data Center and Networking
Network Function Virtualization (NFV) Market
Data Center and Networking
Global Data Fabric Market
Data Center and Networking
Data Center Servers Market
Data Center and Networking
Ethernet Transceivers Market
Data Center and Networking
Europe Data Center Networking Market
Data Center and Networking
Nosql Market
Data Center and Networking
Global WAN Optimization Market
Data Center and Networking
Data Center Interconnect Market
Data Center and Networking
Global Data Warehouse As a Service (Dwaas) Market
Data Center and Networking
Saudi Arabia Data Center Server Market
Data Center and Networking
Nigeria Data Center Networking Market
Data Center and Networking
Dark Fiber Network Market
Data Center and Networking
Global Data Lakes Market
Data Center and Networking
Data Warehousing Market
Data Center and Networking
Software Defined Networking (SDN) and Network Function Virtualization (NFV) Market