
 Graph Database Market | 2026-2036
Graph Database Market Size, Share, and Industry Trends Forecast 2026-2036
Graph Database Market Analysis
Cloud marketplace channels are reshaping how enterprises procure graph database infrastructure, with hyperscaler listings displacing traditional direct-sales relationships. Neo4j leverages its native graph engine to dominate developer-led adoption through AWS Marketplace and Azure listings. Amazon Web Services sustains competitive pressure with Neptune's tight integration into broader analytics pipelines. TigerGraph differentiates through distributed architecture claims that target multi-terabyte workloads in telecommunications and finance.
Graph databases store data as nodes, edges, and properties rather than rows and columns, enabling traversal queries that execute in milliseconds across billions of relationships for use cases like real-time recommendation engines and network topology analysis. Cloud-Based deployment leads adoption as enterprises retire on-premises data centers and seek elastic scaling for variable query loads. Fraud Detection applications command premium pricing due to stringent SLA requirements and regulatory scrutiny in banking. Database Management solutions anchor vendor revenue through recurring subscription models, while Analytics modules represent the fastest-expanding margin pool as customers layer graph algorithms atop existing data lakes.
The EU AI Act, GDPR, and SEC cybersecurity disclosure rules shape product roadmaps by mandating explainability in automated decision systems and granular audit trails for sensitive data relationships. HIPAA constrains healthcare deployments in the United States, pushing vendors toward FedRAMP and HITRUST certifications. Stakeholders must monitor how generative AI integration alters query patterns and whether vector-graph hybrid architectures emerge as the dominant technical standard.
Market Dynamics
Cloud-native deployment architectures are forcing incumbent vendors to rearchitect legacy graph engines for elastic scaling, while the EU AI Act's explainability mandates are rewriting procurement specifications across European financial services procurement teams.
Growth Catalysts
- EU AI Act compliance mandates:Automated decision systems in European banking now require auditable relationship mapping, accelerating procurement of graph-based lineage tools.
- Real-time fraud detection workloads:Financial institutions are replacing batch-based anti-money laundering systems with millisecond-latency graph traversals across transaction networks.
- Vector-graph hybrid architectures:Generative AI retrieval pipelines are converging embedding stores with property graphs to ground large language model outputs in structured relationship data.
Market Restraints
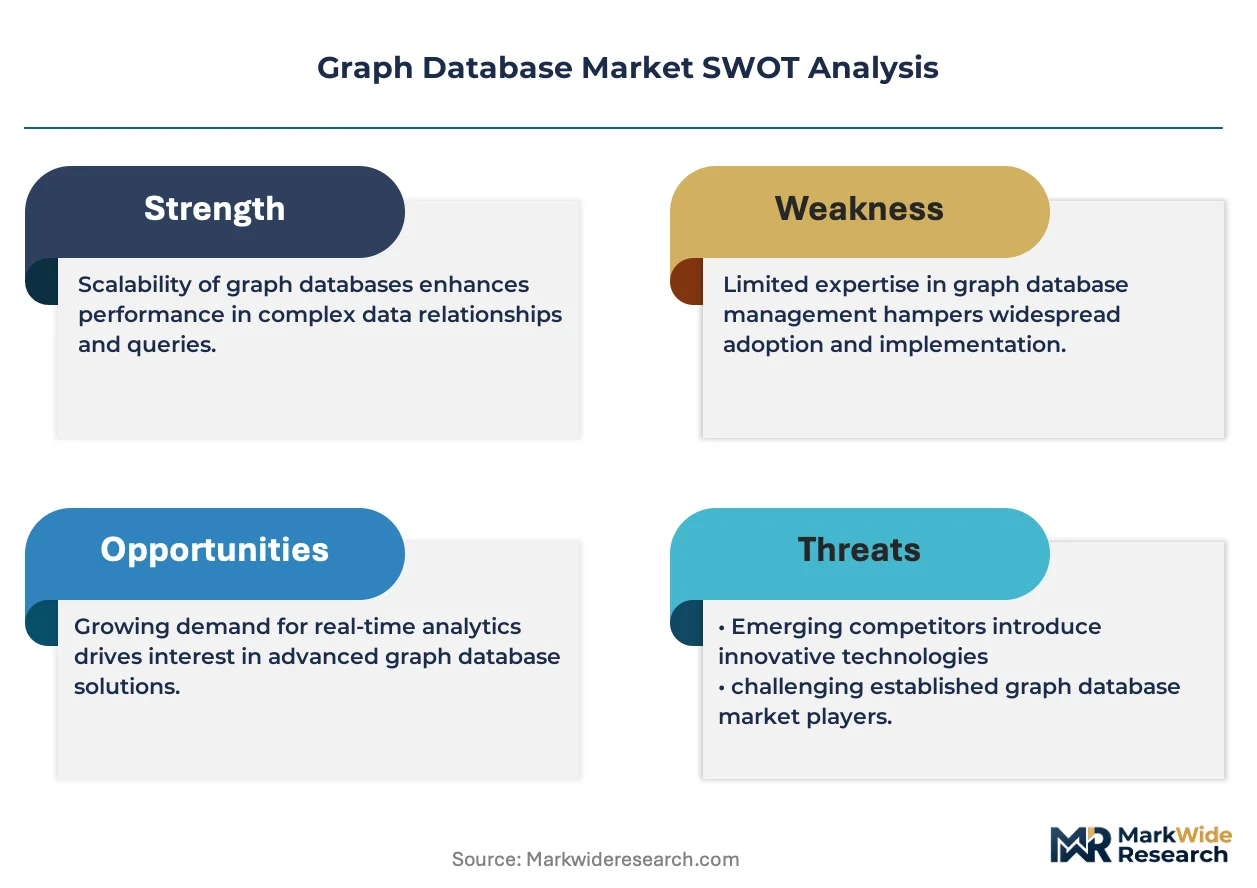
- Specialized query language fragmentation:Cypher, Gremlin, and GQL dialects create portability friction and lock-in risk for enterprise data architecture teams.
- Cloud infrastructure cost volatility:Elastic scaling of billion-edge traversals generates unpredictable compute consumption patterns that strain IT budget forecasting.
- Graph schema design expertise scarcity:The shortage of data engineers proficient in modeling complex networks limits enterprise deployment velocity outside technology clusters.
Strategic Opportunities
- Healthcare knowledge graph expansion:HIPAA-compliant clinical decision support systems represent an underpenetrated vertical for patient journey and drug interaction mapping.
- Supply chain resilience mandates:The SEC's cybersecurity disclosure rules are pushing manufacturers toward graph-based vendor risk visibility and component traceability.
- FedRAMP authorization pathways:Cloud-native graph vendors can capture federal agency workloads through accelerated security certification programs.
Industry Challenges
- Legacy data warehouse integration complexity:Enterprises struggle to federate graph queries across existing SQL-based analytics pipelines without ETL latency penalties.
- Multi-model database substitution pressure:Document and wide-column stores are adding lightweight graph extensions that satisfy simpler relationship queries at lower total cost.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Graph Database Market |
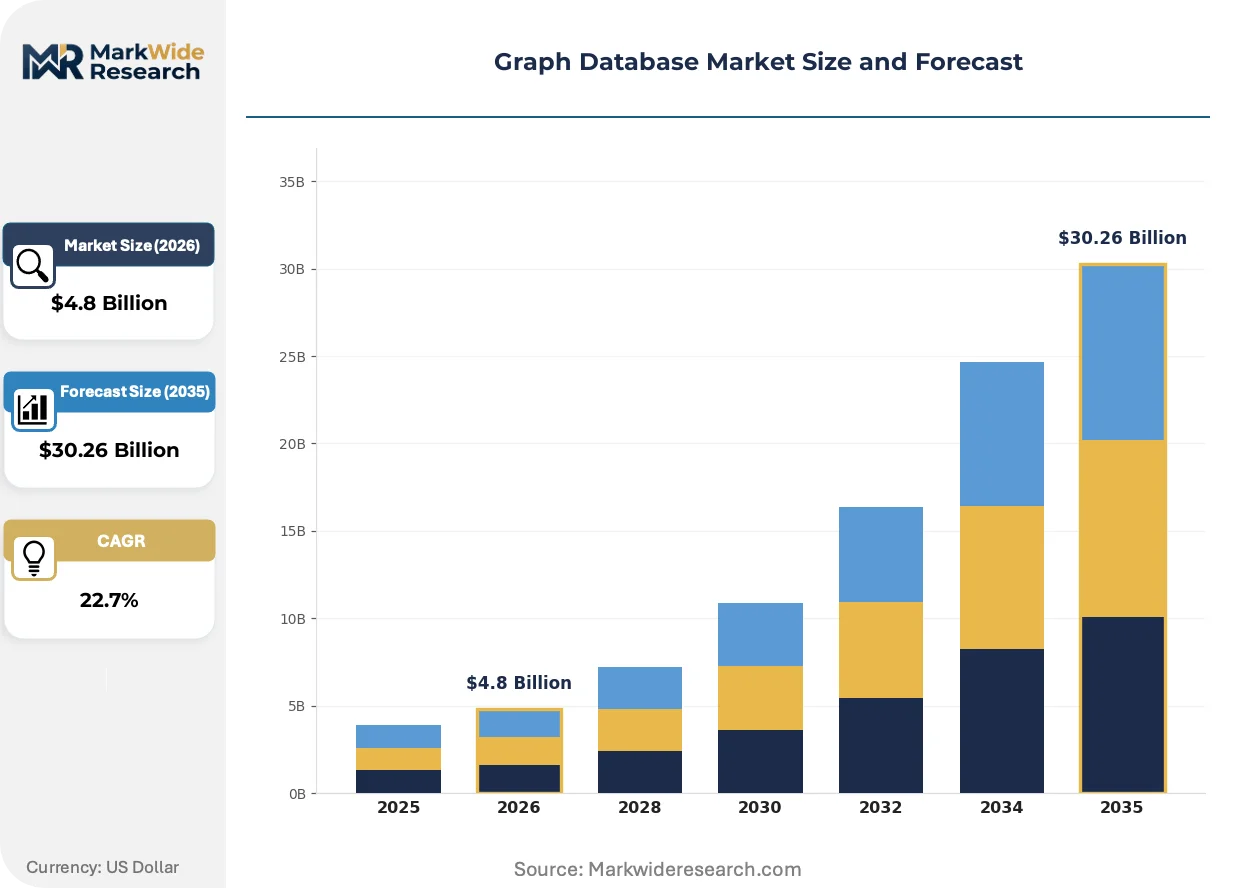
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $30.26 Billion |
| CAGR (2026 – 2036) | 22.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud-Based, Hybrid, Multi-Cloud Application: Fraud Detection, Recommendation Engines, Network Analysis, Social Graphs End User: Healthcare, Retail, Telecommunications, Finance Solution: Database Management, Analytics, Data Integration, Visualization |
| Companies Covered | Neo4j, Amazon Web Services, Oracle, Microsoft, IBM, TigerGraph, DataStax, ArangoDB, Stardog, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Graph Database Market Emerging Trajectories
Vector indexing capabilities are merging with native graph storage to enable semantic search across unstructured content while preserving structural relationship context for explainable AI pipelines.
Native vector storage extensions are digitizing how recommendation engines combine collaborative filtering with content-based similarity. Retail and media platforms are adopting these hybrids to reduce cold-start latency for new users. The technology is digitizing competitive differentiation in real-time personalization stacks.
The EU AI Act's risk-based classification system is mandating algorithmic impact assessments for high-stakes automated decisions. Graph databases are becoming the preferred audit substrate for tracing model inputs through training data lineage. European financial services procurement teams are embedding these requirements into RFP scoring criteria.
Enterprise buying committees are consolidating vendor relationships through cloud marketplace procurement channels. Hyperscaler listings with integrated billing and identity management are displacing direct enterprise sales motions. This pattern concentrates in United States technology clusters where AWS and Azure consumption commitments drive infrastructure selection.
Graph Database Market Segmentation
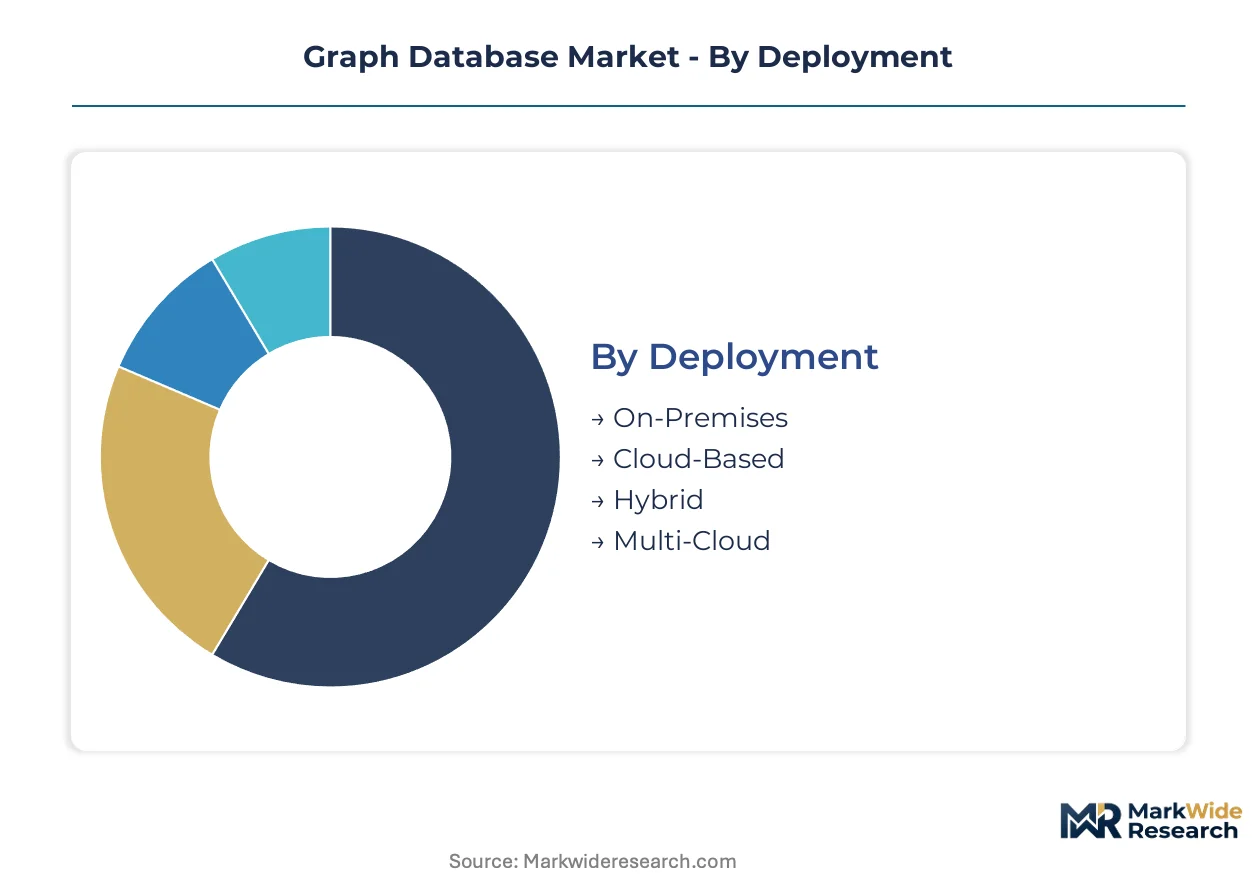
Graph database procurement varies sharply by operational maturity, with cloud-native architectures displacing legacy stacks in financial services while regulated industries retain hybrid controls. Segmentation reveals how deployment choices cascade into application priorities and end-user economics.
Deployment:
Mature on-premises installations coexist with emerging multi-cloud strategies as enterprises navigate data sovereignty requirements.
- On-Premises:Hardware-controlled environments deliver sub-millisecond latency for fixed workloads. Banking regulators in Germany and Switzerland mandate air-gapped deployments for core transaction systems, preserving incumbent vendor relationships despite higher TCO.
- Cloud-Based:Elastic compute pools scale traversal queries across variable demand curves. United States technology clusters in San Francisco and New York drive consumption through AWS and Azure marketplace commitments, displacing direct procurement channels.
- Hybrid:Sensitive relationship data remains on-premises while analytics workloads burst to public cloud. Japanese automotive manufacturers use this architecture to protect supply chain topology while enabling cross-border logistics optimization.
- Multi-Cloud:Vendor-agnostic orchestration layers distribute graph fragments across competing hyperscalers. Early adopters in Netherlands fintech seek to avoid platform lock-in as the EU AI Act transparency mandates intensify audit requirements.
Cloud-Based handles the majority of throughput; Multi-Cloud is gaining share fastest as procurement committees diversify infrastructure risk.
Application:
Cost tier stratification separates mission-critical fraud workflows from experimental recommendation pilots.
- Fraud Detection:Real-time traversal of transaction networks identifies anomalous relationship patterns in milliseconds. Premium pricing reflects stringent SLAs and regulatory scrutiny from the SEC and EU banking supervisors.
- Recommendation Engines:Collaborative filtering algorithms combine user behavior graphs with content similarity vectors. Streaming platforms in South Korea deploy these hybrids to reduce cold-start latency for new subscribers.
- Network Analysis:Topology mapping reveals vulnerability cascades in telecommunications infrastructure. Australian carriers use graph centrality metrics to prioritize fiber repair sequences during outage events.
- Social Graphs:Relationship density calculations power connection suggestions and community detection. Professional networking platforms maintain massive property graphs where edge creation rates exceed millions per second.
Fraud Detection commands the steepest price premiums; Recommendation Engines are expanding most quickly as generative AI retrieval pipelines converge with vector storage.
End User:
Customer type differentiation separates regulated verticals with compliance overhead from digital-native sectors seeking velocity.
- Healthcare:HIPAA-compliant knowledge graphs map patient journeys and drug interactions across clinical systems. United States hospital networks push vendors toward FedRAMP and HITRUST certifications before procurement approval.
- Retail:Real-time personalization engines traverse product affinity networks during checkout flows. French luxury houses deploy graph-based attribution to trace counterfeit supply chains through vendor relationship mapping.
- Telecommunications:Network topology databases track equipment dependencies for outage prediction. Indian operators model 5G cell tower adjacencies to optimize radio frequency propagation across dense urban corridors.
- Finance:Anti-money laundering systems replace batch processing with continuous transaction monitoring. Singaporean banks integrate graph lineage tools to satisfy MAS technology risk management guidelines.
Finance generates the deepest vendor engagement; Healthcare shows the steepest expansion trajectory as clinical decision support systems digitize.
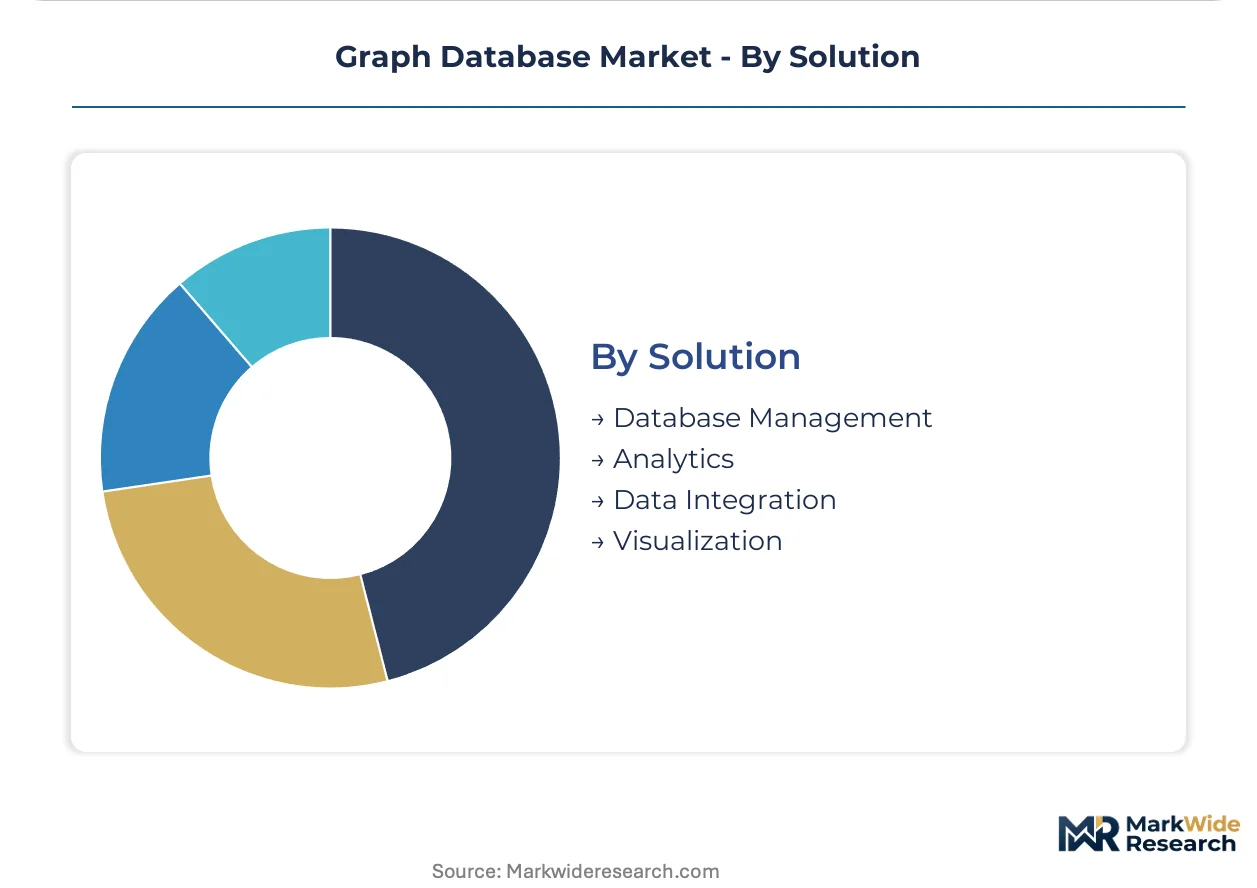
Solution:
Margin concentration follows the value chain upstream from visualization tools toward core database engines.
- Database Management:Native graph storage engines with ACID guarantees anchor subscription revenue. Property graph and RDF stores compete for workload suitability across enterprise architecture teams.
- Analytics:Algorithm libraries execute centrality, community detection, and pathfinding at scale. Graph data science modules attach to existing data lakes, representing the fastest-expanding margin pool.
- Data Integration:ETL pipelines federate graph queries across SQL warehouses and document stores. Schema mapping tools reduce friction when migrating from relational legacy systems.
- Visualization:Interactive explorers render billion-node networks in browser-based interfaces. Link analysis interfaces serve investigative analysts in law enforcement and compliance functions.
Database Management captures the recurring revenue base; Analytics climbs the fastest as customers layer graph algorithms atop existing infrastructure investments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU AI Act compliance deadlines are accelerating procurement cycles across European banking sectors, while cloud marketplace commitments in the United States concentrate vendor relationships through AWS and Azure consumption agreements.
United States
Financial institutions in New York and San Francisco technology clusters are replacing batch-based anti-money laundering systems with real-time graph traversals. SEC cybersecurity disclosure rules mandate auditable relationship mapping for vendor risk visibility. Boston-based healthcare networks push vendors toward FedRAMP and HITRUST certifications before procurement approval for clinical knowledge graphs.
Germany
Automotive manufacturers deploy hybrid architectures to protect supply chain topology while enabling cross-border logistics optimization. BaFin supervisory mandates require air-gapped graph deployments for core transaction systems, preserving on-premises infrastructure despite higher TCO. Munich and Stuttgart engineering clusters model 5G network dependencies and component traceability for electric vehicle platforms.
Singapore
Monetary Authority of Singapore technology risk management guidelines drive bank procurement of graph-based lineage tools for model explainability. Maritime trade platforms traverse vessel relationship networks to identify sanctions-evasion patterns. The city-state's fintech corridor attracts multi-cloud orchestration vendors seeking to serve ASEAN regulatory diversity.
Japan
Automotive supply chain resilience mandates from METI push manufacturers toward graph-based component traceability and vendor risk visibility. Tokyo and Nagoya industrial clusters use network topology databases to track equipment dependencies for outage prediction. Hybrid deployment patterns protect sensitive relationship data domestically while analytics workloads burst to regional cloud infrastructure.
Netherlands
Amsterdam fintech early adopters seek vendor-agnostic orchestration layers to avoid platform lock-in as EU AI Act transparency mandates intensify audit requirements. Dutch banks integrate graph algorithms into existing data lakes to satisfy algorithmic impact assessment obligations. Rotterdam logistics platforms model multimodal transport networks for carbon footprint optimization across European distribution corridors.
Graph Database Market Vendor Landscape
On the supply side, the industry is consolidating around three strategic tiers: hyperscaler-integrated engines, independent native graph specialists, and multi-model database incumbents adding graph extensions. The competitive landscape fragments across cloud-native pure-plays, legacy database vendors rearchitecting for elastic scaling, and venture-backed challengers targeting distributed architectures. Dominant competitive moves include cloud marketplace listing expansion to capture hyperscaler consumption commitments, and vector-graph hybrid development to serve generative AI retrieval pipelines.
Within the native graph specialist tier, Neo4j and TigerGraph exemplify contrasting architectural bets—property graph depth versus distributed scale claims—while Amazon Web Services anchors the hyperscaler-integrated position through Neptune's tight integration with broader analytics pipelines. These three companies represent the primary competitive anchors shaping procurement criteria across financial services and telecommunications verticals.
| Leading Market Players |
|---|
| Neo4j |
| Amazon Web Services |
| Oracle |
| Microsoft |
| IBM |
| TigerGraph |
| DataStax |
| ArangoDB |
| Stardog |
| Others |
Supply Flow & Price Mechanics
Undercapacity in distributed graph engine development across European engineering clusters is compressing vendor margins while amplifying pricing power for hyperscaler-integrated alternatives. Cloud marketplace procurement commitments in United States technology clusters are reshaping how enterprises negotiate subscription tiers, with consumption-based billing displacing traditional enterprise licensing.
Pricing Analysis
Volume-discount tiering structures stratify across enterprise scale commitments, with consumption-based SaaS subscriptions anchoring mid-market procurement and dedicated instance pricing serving regulated financial services. Price differentiation hinges on FedRAMP certification tier and query throughput SLA guarantees, with HIPAA-compliant deployments commanding substantial premiums over standard cloud offerings. Cost compression in on-premises hardware bundles is intensifying because hyperscaler marketplace credits are subsidizing cloud migration budgets. Mid-market healthcare networks exhibit the sharpest price sensitivity, while global banking conglomerates prioritize latency guarantees over per-core licensing costs.
Supply Chain Analysis
Extended payment terms from hyperscaler marketplace programs are easing cash conversion cycles for independent graph vendors competing against vertically integrated cloud providers. Graph database infrastructure draws from semiconductor fabrication concentrated in Taiwan, South Korea, and the United States, with memory module sourcing tethered to Japanese and Korean component suppliers. Single-source vulnerability in specialized vector processing hardware creates procurement risk for vendors developing hybrid architectures. Distribution runs through AWS Marketplace and Azure Marketplace channels, with direct enterprise sales motions retreating to complex regulated deployments requiring custom compliance engineering.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Graph database markets operate as defensive-moat businesses where regulatory entrenchment creates formidable switching costs. EU AI Act compliance mandates and FedRAMP certification requirements lock banking and federal customers into validated vendor relationships.
For Market Incumbents: Insulate core revenue by accelerating FedRAMP authorization pathways for federal agency capture and deepening query optimization engineering for multi-terabyte financial services workloads. Multi-model database substitution pressure from document stores adding lightweight graph extensions threatens margin compression in mid-market segments. Vertical integration into native vector storage capabilities addresses generative AI retrieval pipeline demand. For New Entrants and Emerging Players: Japanese automotive supply chain resilience mandates represent the most penetrable white-space target, with METI-driven component traceability requirements outpacing incumbent vendor coverage. Healthcare knowledge graph expansion for HIPAA-compliant clinical decision support systems offers secondary entry velocity. Cloud-native pure-plays should pursue channel partnerships with systems integrators serving Japanese manufacturing clusters rather than direct enterprise sales. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across cloud-native deployment architectures as containerized graph engines reduce dedicated infrastructure requirements. Acquisition target archetypes include vector-graph hybrid specialists with production-grade lineage tooling and established EU AI Act audit trail implementations. The signal to watch is hyperscaler marketplace revenue concentration exceeding direct sales mix, indicating channel-dependent valuation vulnerability.| Strategic Initiative | Industry Significance |
|---|---|
| Vector-Graph Hybrid Development | Converges embedding stores with property graphs to ground LLM outputs in auditable relationship data for EU AI Act compliance. |
| Cloud Marketplace Listing Expansion | Captures AWS and Azure consumption commitments displacing direct procurement channels in United States technology clusters. |
| FedRAMP Authorization Acceleration | Unlocks federal agency workloads through streamlined security certification pathways for HIPAA-adjacent healthcare deployments. |
| Healthcare Knowledge Graph Expansion | Addresses underpenetrated clinical decision support vertical with patient journey mapping and drug interaction analytics. |
| Multi-Cloud Orchestration Investment | Serves Dutch fintech and Netherlands early adopters seeking vendor-agnostic infrastructure for EU AI Act audit requirements. |
Methodological Framework
Desk research of SEC cybersecurity disclosure filings, hyperscaler capex disclosures, and EU regulatory impact assessments preceded structured interviews with CTOs at financial services institutions, IT procurement officers at healthcare networks, platform engineers at telecommunications operators, and channel partners serving automotive supply chain verticals. Secondary validation drew from EBA stress test documentation, MAS technology risk management guidelines, and cloud marketplace vendor listing data. Bottom-up deployment model sizing triangulated against top-down vertical spending estimates.
Assumption sets held cloud infrastructure cost curves and EU AI Act implementation timelines fixed while varying generative AI adoption velocity and vector-graph hybrid architecture penetration rates across the projection horizon. Segmentation dimensions modeled include deployment architecture, application workload type, end-user vertical, solution component tier, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted spending trajectories incorporating query volume growth curves and subscription pricing evolution patterns.
The forecast holds incumbent behavior within observed patterns; aggressive moves by venture-backed distributed architecture challengers or hyperscaler predatory pricing would shift outcomes. Macroeconomic contraction in technology spending, regulatory delay in EU AI Act enforcement, or breakthrough multi-model database performance would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center and Networking
Global Data Fabric Market
Data Center and Networking
Vietnam Data Center Networking Market
Data Center and Networking
Canada Data Center Networking Market
Data Center and Networking
APAC Data Center Networking Market
Data Center and Networking
DNA Digital Data Storage Market
Data Center and Networking
Dynamic Data Management System Market
Data Center and Networking
Philippines Data Center Networking Market
Data Center and Networking
Taiwan Data Center Networking Market
Data Center and Networking
Global Virtual Private Network Market
Data Center and Networking
Infrastructure As a Service Market
Data Center and Networking
Network Virtualization Software Market
Data Center and Networking
Global Enterprise Networking Market
Data Center and Networking
Europe Data Center Interconnect Market
Data Center and Networking
Automotive Data Management Market
Data Center and Networking
Network Slicing Market
Data Center and Networking
Converged Data Platform Market