
 Vietnam Data Center Server Market | 2026-2036
Vietnam Data Center Server Market Size, Share, and Industry Trends Forecast 2026-2036
Vietnam Data Center Server Market Insights
Silicon carbide power modules is repositioning thermal design for high-density rack servers deployed in tropical climates. Dell Technologies leverages vertical integration across server assembly and cooling subsystems to control cost curves in Vietnam's price-sensitive procurement environment. Huawei Technologies Co. Ltd. anchors geographic dominance through pre-certified infrastructure bundles aligned with domestic telecom builds. Super Micro Computer Inc. specializes in liquid-cooled architectures that sustain compute density where ambient temperatures exceed design thresholds.
A data center server is a compute appliance engineered to process, store, and manage networked workloads in centralized or distributed facilities, typically incorporating multi-socket processors, ECC memory, redundant power supplies, and hot-swappable storage bays rated for continuous operation. Rack servers dominate procurement volumes among Vietnamese cloud operators seeking standardized density per square meter, while hyper-converged infrastructure captures margin pools by collapsing storage, compute, and networking into single-vendor stacks that reduce integration overhead. Edge computing deployments are accelerating fastest in manufacturing zones near Hai Phong and Da Nang where latency constraints rule out centralized processing.
Vietnam's Ministry of Information and Communications enforces data localization mandates through Decree 53 and related cybersecurity frameworks, compelling foreign platforms to establish domestic server footprints. The national power regulator coordinates with Vietnam Electricity to prioritize grid connections for certified data center zones, directly shaping site selection and capacity timelines. BIS-equivalent technical standards for electromagnetic compatibility and energy efficiency filter import eligibility for server hardware. Stakeholders must weigh colocation partnerships against captive facility investments as land and power commitments in the north tighten through the decade.
Market Dynamics
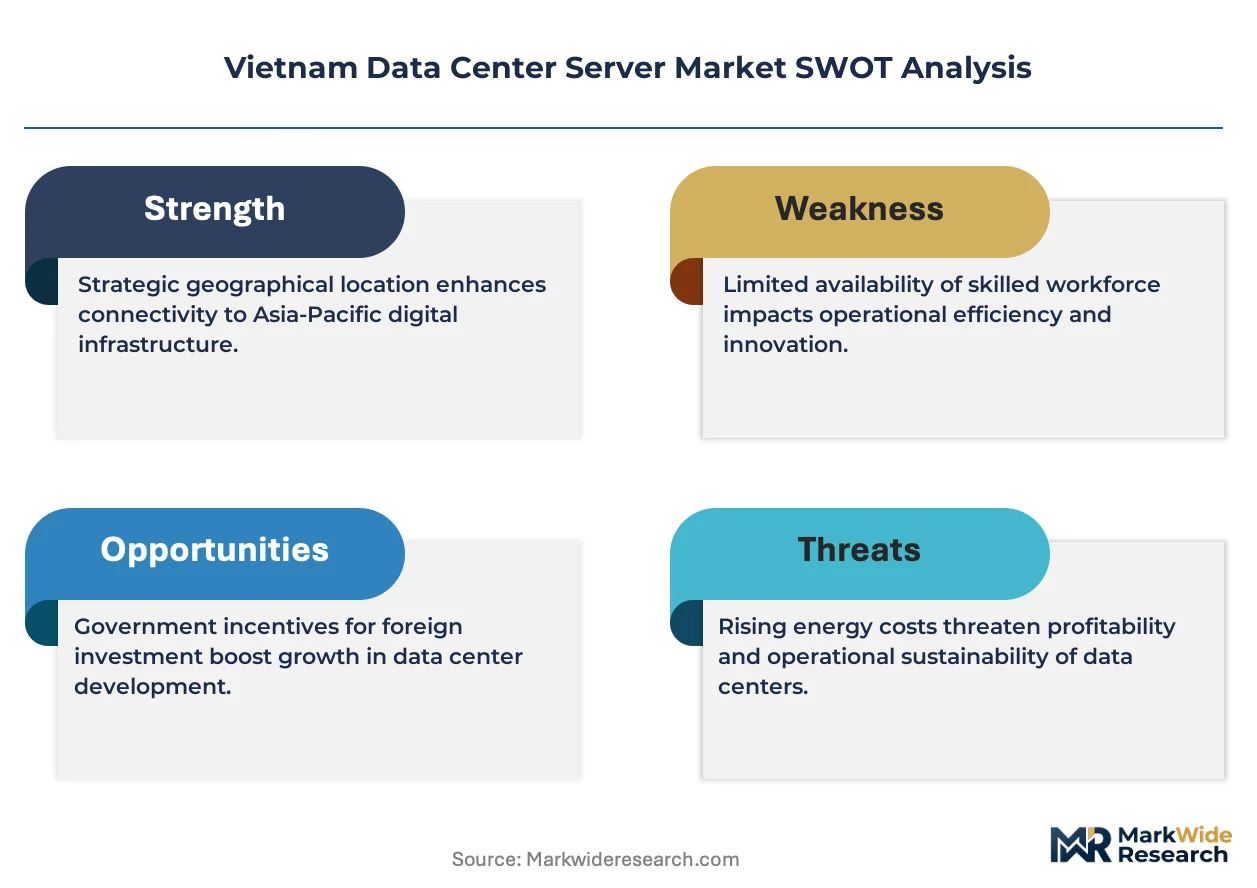
Data localization mandates are compressing procurement timelines for domestic server capacity, forcing foreign cloud platforms to establish physical infrastructure ahead of organic demand curves. This regulatory pressure is reshaping site selection, cooling architecture, and supplier relationships across the Vietnamese market.
Growth Catalysts
- Decree 53 localization requirements:The Ministry of Information and Communications mandates domestic storage of citizen personal data, compelling foreign platforms to procure local server hardware rather than rely on regional hubs.
- Hyperscale cloud expansion:Global providers are commissioning multi-megawatt facilities in Ho Chi Minh City and Hanoi, driving rack server volumes for standardized density configurations.
- Silicon carbide power modules:Wide-bandgap semiconductors enable higher thermal efficiency in tropical ambient conditions, reducing cooling overhead for high-density deployments.
Market Restraints
- Industrial land scarcity in northern corridors:Certified data center zones around Hanoi face tightening land and power commitments, extending lead times for grid connections through Vietnam Electricity coordination.
- Import certification friction:BIS-equivalent electromagnetic compatibility and energy efficiency standards filter hardware eligibility, creating compliance overhead for non-domestic suppliers.
- Copper and rare earth price volatility:Server power supply and motherboard materials face input cost uncertainty, pressuring margin structures in price-sensitive procurement environments.
Strategic Opportunities
- Edge computing in manufacturing zones:Latency-sensitive workloads near Hai Phong and Da Nang industrial parks create demand for micro data centers outside centralized hubs.
- Liquid-cooled architecture adoption:Ambient temperatures exceeding traditional air-cooled design thresholds favor direct-to-chip cooling systems for sustained compute density.
- Hyper-converged infrastructure bundles:Single-vendor stacks collapsing storage, compute, and networking reduce integration overhead for mid-tier domestic operators.
Industry Challenges
- Certified data center engineering talent:Specialized skills in high-voltage electrical design and precision cooling system commissioning remain concentrated among a limited pool of regional specialists.
- Legacy facility retrofit complexity:Existing colocation sites built for lower power densities require substantial electrical and mechanical upgrades to accommodate contemporary rack configurations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vietnam Data Center Server Market |
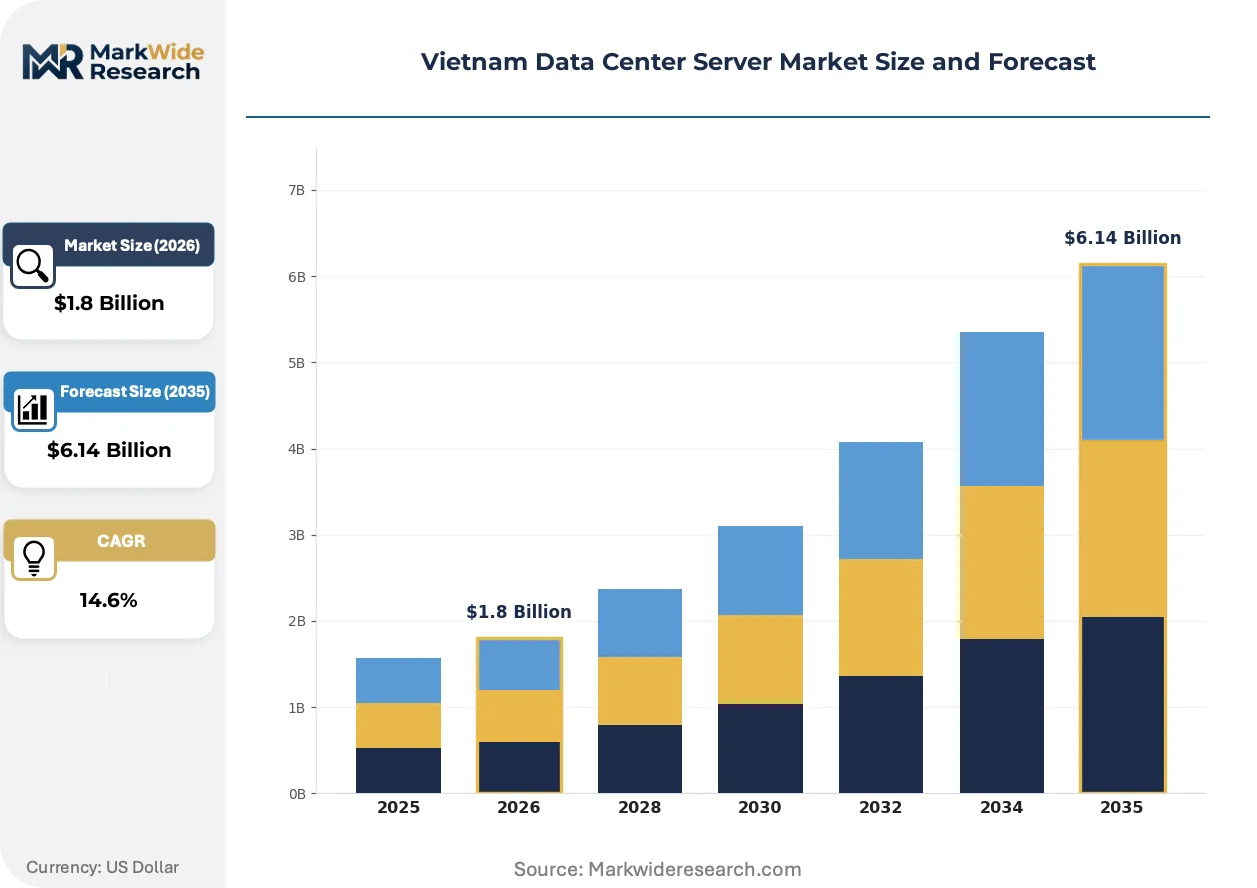
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $6.14 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rack Server, Blade Server, Tower Server, Hyper-Converged Infrastructure End User: Telecommunication, BFSI, Government, Manufacturing Technology: Virtualization, Cloud Computing, Edge Computing, Artificial Intelligence Deployment Model: On-Premises, Colocation, Hybrid, Dedicated Hosting |
| Companies Covered | Dell Technologies, Hewlett Packard Enterprise, Cisco Systems, Lenovo Group Ltd., Inspur Group, Huawei Technologies Co. Ltd., IBM Corporation, Fujitsu Ltd., Super Micro Computer Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vietnam Data Center Server Market Trends and Innovations
Thermal management innovation is dominating vendor roadmaps as tropical deployment conditions expose the limits of conventional cooling. Three converging developments are restructuring procurement priorities and supplier positioning.
Silicon carbide power modules are consolidating thermal design standards for high-density rack servers. Vietnamese hyperscale operators are adopting these wide-bandgap semiconductors to sustain power conversion efficiency above ambient design thresholds. The technology is consolidating supplier differentiation around thermal performance guarantees rather than raw compute specifications.
Decree 53 and its implementing cybersecurity frameworks are mandating physical data residency with enforcement through the Ministry of Information and Communications. Foreign platforms must establish domestic server footprints or face operational restrictions. Cloud providers are responding by accelerating facility commissioning timelines and prioritizing northern grid connections certified by Vietnam Electricity.
Domestic enterprises are unbundling hardware procurement from managed services, shifting toward direct server purchases with separate maintenance contracts. This fragmentation is disrupting traditional channel relationships where systems integrators bundled hardware, installation, and ongoing support. The pattern is most visible among state-owned enterprises in the Red River Delta corridor seeking greater cost transparency.
Vietnam Data Center Server Market Segmentation
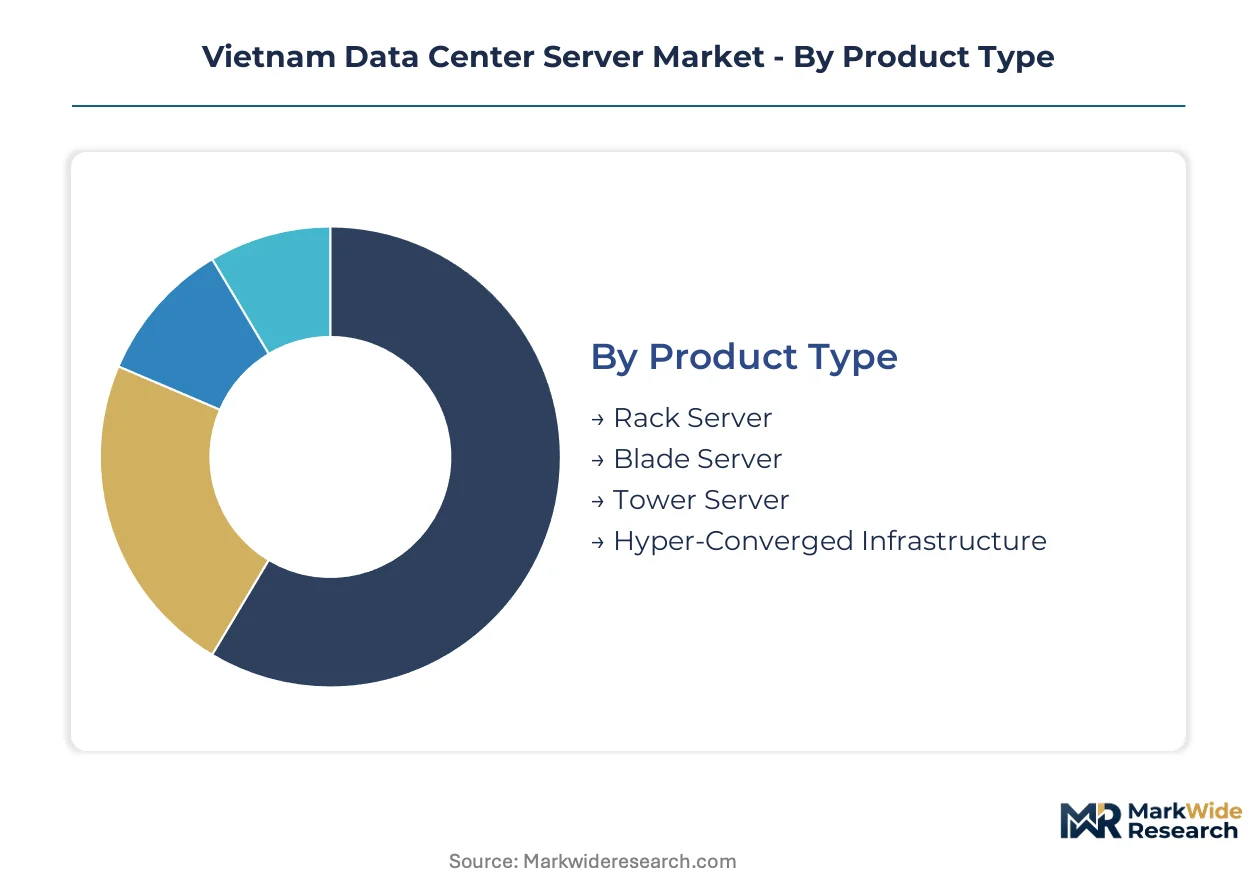
Server procurement patterns in Vietnam diverge sharply across deployment configurations and workload types. Understanding these fault lines reveals where localization mandates, thermal constraints, and cloud expansion reshape vendor priorities.
Product Type:
Upgrade cycles for existing facilities favor modular replacements that preserve rack footprints while lifting power density. Procurement officers weigh thermal headroom against capital outlay when refreshing legacy installations.
- Rack Server:Standardized 1U-4U enclosures dominate hyperscale builds in Ho Chi Minh City and Hanoi. Operators prioritize density per square meter where land costs in northern certified zones climb steadily.
- Hyper-Converged Infrastructure:Integrated compute-storage-networking stacks reduce integration overhead for mid-tier domestic enterprises. State-owned operators in the Red River Delta corridor increasingly favor disaggregated hardware procurement from managed services.
- Blade Server:Shared infrastructure chassis serve high-density computing clusters with centralized power and cooling management.
- Tower Server:Standalone vertical enclosures address small-scale deployments and branch office workloads outside centralized facilities.
Rack servers sit at the top of the volume ranking, with hyper-converged infrastructure climbing the fastest.
End User:
Cost tier segmentation separates price-sensitive state procurement from premium private deployments. Budget transparency requirements reshape how different buyer categories evaluate total cost of ownership.
- Telecommunication:Domestic carriers anchor server demand through infrastructure bundles aligned with 5G core network builds. Vietnam's Ministry of Information and Communications certification requirements filter vendor eligibility for these procurements.
- Government:Decree 53 mandates compress procurement timelines for citizen data storage systems. Ministries accelerate domestic server commissioning ahead of organic demand curves.
- BFSI:Banking and insurance institutions balance latency requirements against regulatory compliance for financial transaction data.
- Manufacturing:Industrial zones near Hai Phong and Da Nang drive edge computing deployments where centralized processing fails latency constraints.
Telecommunication captures the largest procurement volumes, while manufacturing gains share fastest on factory-floor digitization.
Technology:
Application-driven segmentation tracks how workload characteristics dictate server architecture choices. Thermal design and power conversion efficiency separate viable configurations from obsolete approaches.
- Cloud Computing:Multi-tenant virtualization platforms demand standardized hardware with redundant power supplies and hot-swappable components. Silicon carbide power modules enable sustained efficiency where ambient temperatures exceed legacy design thresholds.
- Edge Computing:Distributed processing nodes near industrial parks require compact form factors with minimal cooling infrastructure. Latency-sensitive manufacturing workloads in Hai Phong and Da Nang rule out centralized hub architectures.
- Virtualization:Resource abstraction layers maximize hardware utilization across consolidated workloads.
- Artificial Intelligence:GPU-accelerated training and inference workloads drive specialized accelerator integration in high-density configurations.
Cloud computing maintains volume leadership, with edge computing expanding most quickly on manufacturing zone deployment.
Deployment Model:
Customer type segmentation distinguishes captive facility investments from service-based consumption. Land scarcity in northern corridors tilts preference toward asset-light arrangements for foreign platforms.
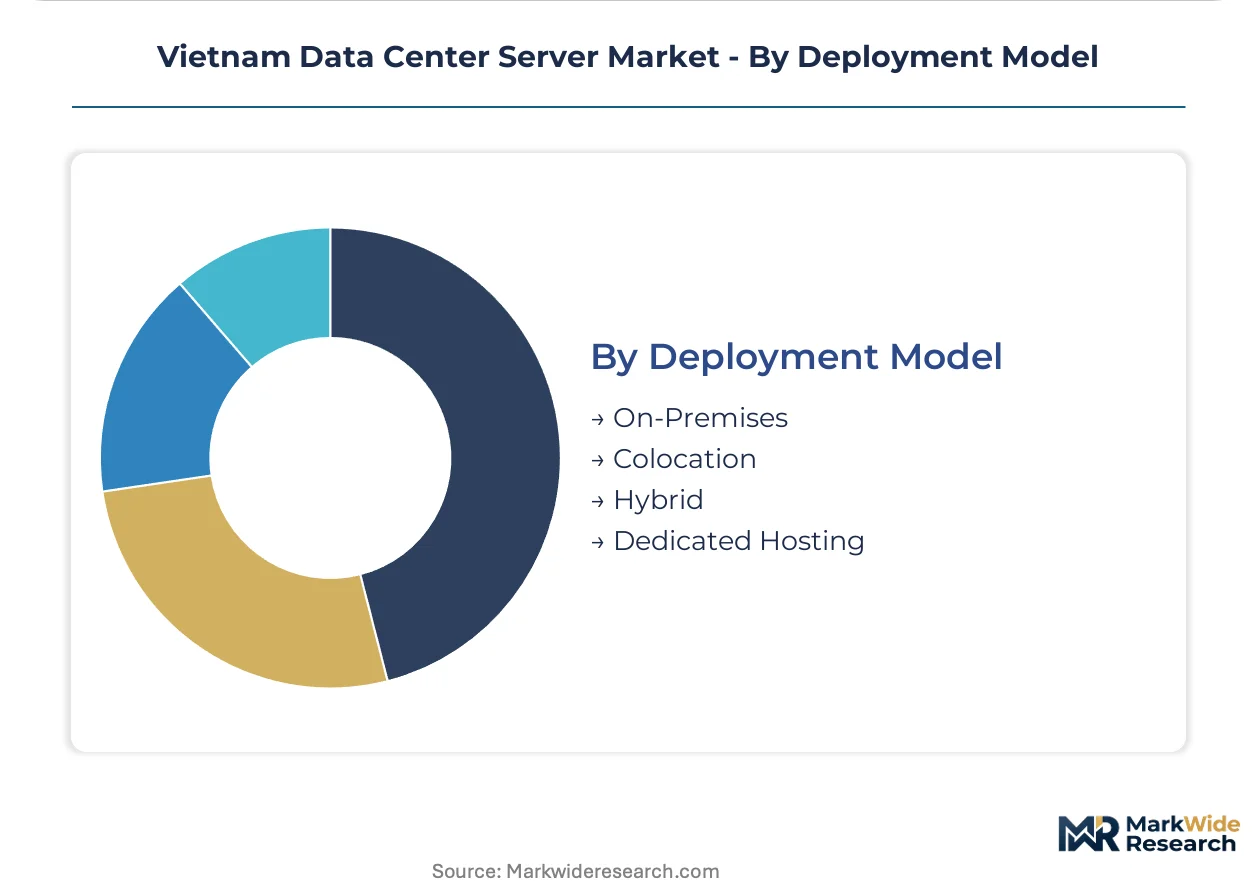
- Colocation:Third-party facility leases allow foreign cloud providers to satisfy Decree 53 residency requirements without direct real estate exposure. Vietnam Electricity-certified grid connections in northern zones remain the binding constraint on capacity expansion.
- On-Premises:Captive data centers serve state-owned enterprises seeking full operational control over citizen data. These installations face legacy retrofit complexity when upgrading electrical and mechanical systems for contemporary rack densities.
- Hybrid:Mixed public-private infrastructure orchestration addresses workload portability requirements across regulatory boundaries.
- Dedicated Hosting:Single-tenant managed environments provide isolation guarantees for compliance-sensitive applications.
Colocation leads procurement volumes among foreign entrants, while on-premises deployments steepen on state-sector transparency mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Red River Delta corridor anchors Vietnam's data center server deployment, with certified zones around Hanoi commanding priority grid connections from Vietnam Electricity. Foreign cloud providers concentrate buildouts in this northern cluster to satisfy Decree 53 mandates while accessing industrial power rates. Southern expansion in Ho Chi Minh City proceeds on different cost structures and land availability.
Red River Delta
Hyperscale operators prioritize this northern corridor for Vietnam Electricity-certified grid infrastructure and available industrial land. The Ministry of Information and Communications coordinates with provincial authorities to fast-track permits for facilities storing citizen data under Decree 53. Bac Ninh and Hai Duong provinces host the densest concentration of commissioned server capacity.
Ho Chi Minh City Metro
Commercial demand from financial services and foreign enterprise headquarters drives rack server procurement in Vietnam's southern economic hub. Land scarcity and higher power tariffs compress facility margins compared to northern builds. District 7 and Thu Duc City absorb most new colocation investments from foreign platforms seeking proximity to regional headquarters.
Da Nang and Central Coast
Manufacturing digitization in industrial parks surrounding Da Nang accelerates edge computing deployments for latency-constrained factory automation. The central location offers submarine cable landing diversity for international connectivity. Quang Nam province hosts emerging micro data center clusters serving automotive and electronics suppliers.
Hai Phong Manufacturing Belt
Deep-water port access and export-oriented industrial zones attract edge infrastructure for real-time logistics and quality control systems. Foreign manufacturers in Dinh Vu and Deep C industrial parks commission localized server capacity to avoid latency to centralized hubs. The northern port city's power grid remains subordinate to Red River Delta priority allocation.
Can Tho and Mekong Delta
Agricultural processing and cold chain logistics generate modest demand for tower and edge server configurations. Limited grid capacity and absence of Vietnam Electricity-certified data center zones constrain hyperscale interest. Provincial operators rely on colocation partnerships with Ho Chi Minh City-based facilities for regulatory-compliant data residency.
Vietnam Data Center Server Market Competitive Landscape
Capacity expansion dominates the current landscape as foreign cloud providers accelerate facility commissioning ahead of Decree 53 enforcement deadlines. The vendor base stratifies across three tiers: global systems integrators with captive assembly networks, regional specialists in tropical thermal design, and domestic distributors of certified hardware bundles. Strategic archetypes include full-stack infrastructure providers, component specialists in power and cooling subsystems, and channel partners navigating BIS-equivalent import certification. M&A activity and strategic partnerships with Vietnam Electricity-certified facility operators constitute the primary competitive moves reshaping supplier relationships.
Among US-based technology conglomerates, Dell Technologies and Hewlett Packard Enterprise occupy positions exemplifying integrated server and services bundling for price-sensitive procurement environments. Huawei Technologies Co. Ltd. represents the geographic anchoring archetype through pre-certified infrastructure aligned with domestic telecom builds. Super Micro Computer Inc. sits within the thermal specialization tier, with liquid-cooled architectures addressing ambient temperature thresholds that exceed conventional air-cooled design limits.
| Leading Market Players |
|---|
| Dell Technologies |
| Hewlett Packard Enterprise |
| Cisco Systems |
| Lenovo Group Ltd. |
| Inspur Group |
| Huawei Technologies Co. Ltd. |
| IBM Corporation |
| Fujitsu Ltd. |
| Super Micro Computer Inc. |
| Others |
Pricing and Supply Chain Analysis
Hyperscale cloud operators in the Red River Delta corridor command pricing leverage through consolidated procurement volumes that compress supplier margins across rack server and cooling subsystem tiers. Their aggregated demand shapes contract structures that favor long-term offtake agreements with silicon carbide power module and precision cooling vendors, locking in thermal performance guarantees against commodity input volatility.
Pricing Analysis
Copper and rare earth input cost pass-through dominates server motherboard and power supply pricing, with Vietnamese procurement officers negotiating quarterly adjustment clauses to buffer margin erosion. Price differentiation centers on BIS-equivalent certification tier and liquid-cooled thermal performance grade, with premium SKUs commanding substantial uplifts for Decree 53-compliant data residency deployments. Pricing pressure intensifies as state-owned enterprises unbundle hardware from managed services, forcing vendors to absorb integration overhead previously captured in bundled contracts. Domestic telecom carriers prove least price-sensitive due to 5G core network build timelines, while mid-tier manufacturing firms in Hai Phong and Da Nang drive hardest bargain on edge server configurations.
Supply Chain Analysis
Workforce availability constraints in Malaysia, Thailand, and Vietnam itself limit captive assembly expansion for server chassis and power distribution units, pushing vendors toward automated production lines. Raw material dependencies center on copper cathodes from Chile and Indonesia, rare earth oxides from China and Myanmar, and silicon carbide substrates from Japan and the United States. Single-source vulnerability in wide-bandgap semiconductor substrates creates exposure to export licensing restrictions. Distribution runs through Vietnam Electricity-certified facility operators who control grid connection priority, with channel partners navigating BIS-equivalent import certification friction for non-domestic hardware brands.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vietnam's data center server market has entered a late-cycle quality phase where thermal performance guarantees and Decree 53 certification speed separate viable suppliers from commodity players. Premium liquid-cooled architectures and pre-certified infrastructure bundles capture widening margin pools as foreign cloud platforms accelerate commissioning timelines.
For Market Incumbents: To counter Huawei Technologies Co. Ltd.'s geographic anchoring through domestic telecom infrastructure bundles, Dell Technologies and Hewlett Packard Enterprise must deepen backward integration into silicon carbide power module sourcing and establish captive cooling subsystem assembly in Bac Ninh province. Certification investment in BIS-equivalent electromagnetic compatibility testing facilities accelerates import eligibility timelines and locks out non-compliant regional competitors. For New Entrants and Emerging Players: Launch via direct server sales with separate maintenance contracts targeting state-owned enterprises in the Red River Delta corridor seeking procurement transparency unbundled from systems integrator markups. Edge computing deployments in Da Nang and Hai Phong manufacturing zones offer the most penetrable white space, with micro data center configurations addressing latency constraints that centralized hubs cannot satisfy. Go-to-market positioning should emphasize tropical thermal design expertise and Vietnam Electricity-certified grid connection partnerships. For Investors and Strategic Acquirers: Domestic cloud service providers and Vietnam Electricity-certified facility operators constitute the most active acquirer category in this space, consolidating land and power commitments ahead of tightening northern corridor availability. Long-term viability over a multi-year horizon rests on thermal specialization capabilities and Decree 53 compliance infrastructure rather than raw compute scale. Monitor silicon carbide substrate export licensing developments as the critical inflection signal for supply-side margin compression.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Power Module Integration | Wide-bandgap semiconductors enable sustained efficiency where ambient temperatures exceed legacy air-cooled design thresholds. |
| Decree 53 Certification Fast-Tracking | Ministry of Information and Communications pre-approval compresses facility commissioning timelines for foreign cloud entrants. |
| Liquid-Cooled Architecture Deployment | Direct-to-chip cooling systems sustain compute density in tropical conditions that conventional approaches cannot address. |
| Vietnam Electricity Grid Partnership | Certified zone priority connections from the national power regulator determine site selection and capacity expansion feasibility. |
| Hyper-Converged Infrastructure Bundling | Single-vendor compute-storage-networking stacks reduce integration overhead for mid-tier domestic operators unbundling procurement. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with data center facility operators, Vietnam Electricity grid planning officers, server procurement managers at hyperscale cloud providers, and cooling subsystem engineering specialists with secondary validation. SEC filings from Dell Technologies and Super Micro Computer Inc., Vietnam Ministry of Information and Communications decree documentation, Vietnam Electricity certified zone registries, and BIS-equivalent technical standards databases anchored supply-side and regulatory intelligence. Bottom-up server shipment tracking by product configuration and end-use vertical triangulated against top-down facility capacity buildout estimates across the Red River Delta and Ho Chi Minh City metro clusters.
Historical reference periods spanning pre-Decree 53 enforcement and post-mandate procurement acceleration anchored the forecast window, with analytical frameworks modeling product type segmentation across rack servers, hyper-converged infrastructure, blade servers, and tower servers alongside deployment model splits between colocation, on-premises, hybrid, and dedicated hosting. Technology segmentation captured cloud computing, edge computing, virtualization, and artificial intelligence workload characteristics. CAGRs derived from facility commissioning timelines, Vietnam Electricity grid connection queue data, and hyperscale capex disclosure patterns. Silicon carbide power module adoption curves and liquid-cooled architecture penetration rates served as industry-specific forecast modifiers.
Forecast precision tightens around the base case; tail outcomes carry wider variance under Ministry of Information and Communications enforcement intensity shifts and Vietnam Electricity grid prioritization reallocations. Forecasts reflect assumptions on Decree 53 compliance timeline adherence, rare earth and copper price trajectory stability, and certified data center engineering talent pool expansion. Material deviation in silicon carbide substrate export licensing or northern industrial land availability triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center and Networking
Thailand Data Center Networking Market
Data Center and Networking
Global Internet Protocol Television (IPTV) CDN Market
Data Center and Networking
Fog Networking Market
Data Center and Networking
Network Optimization Services Market
Data Center and Networking
Data Center Networks Market
Data Center and Networking
Australia Data Center Networking Market
Data Center and Networking
Middle East Data Center Networking Market
Data Center and Networking
Dedicated Internet Access Market
Data Center and Networking
Indonesia Data Center Networking Market
Data Center and Networking
Mobile Data Market
Data Center and Networking
Saudi Arabia Data Center Server Market
Data Center and Networking
Germany Data Center Networking Market
Data Center and Networking
GPU Database Market
Data Center and Networking
Global Software Defined Networking (SDN) Market
Data Center and Networking
Europe Data Center Market
Data Center and Networking
Ethernet Transceivers Market