
 Mobile Data Offload Market | 2026-2036
Mobile Data Offload Market Size, Share, and Industry Trends Forecast 2026-2036
Mobile Data Offload Market Insights
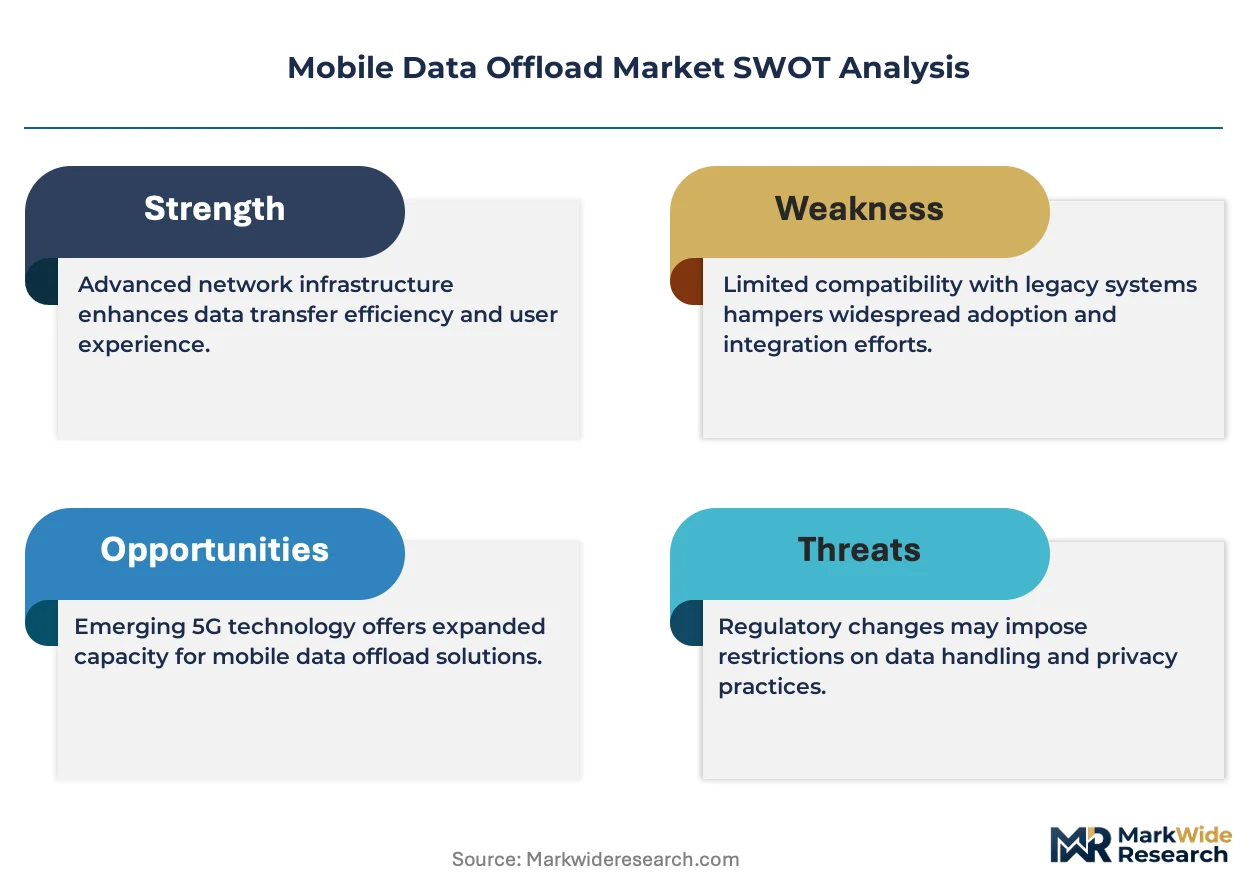
The carrier-Wi-Fi channel is fragmenting as mobile operators disaggregate traffic across heterogeneous access layers. Ericsson leverages its cloud-native core portfolio to anchor multi-access edge computing deployments. Nokia differentiates through Open RAN-compatible offload orchestration platforms. Qualcomm sustains chipset-level integration across licensed and unlicensed spectrum bands.
Mobile data offload encompasses the engineered redirection of cellular traffic to complementary radio access technologies, typically operating at 2.4 GHz and 5 GHz unlicensed bands or licensed-assisted access spectra, to preserve macro network capacity and reduce subscriber-perceived latency. Wi-Fi offload retains the dominant traffic volume share while 5G-based offload represents the fastest-expanding technology segment as carriers deploy NR-U and private network slices. Enterprise end user segments command premium service model pricing, whereas consumer smartphone offload remains a high-volume, lower-margin pool.
The FCC governs unlicensed spectrum power limits and Citizens Broadband Radio Service access tiers that directly shape small cell and Wi-Fi hotspot deployment economics. ETSI and 3GPP standards frameworks define interworking protocols between cellular core networks and trusted WLAN access points, creating compliance gates for equipment certification. Stakeholders must monitor spectrum reauthorization timelines and Open RAN interoperability mandates to calibrate R&D roadmaps against evolving access network architectures.
Market Dynamics
Carrier densification imperatives are forcing mobile network operators to disaggregate traffic across heterogeneous radio access layers, compressing the traditional macro-centric architecture into distributed multi-access edge computing deployments. This structural shift elevates Wi-Fi and 5G NR-U from cost-saving afterthoughts to core capacity management instruments.
Growth Catalysts
- CBRS Priority Access Licenses:The FCC's three-tier spectrum framework unlocks enterprise private network deployments across manufacturing campuses and logistics hubs, creating dedicated offload corridors independent of macro congestion.
- Video traffic saturation:Smartphone streaming consumption is overwhelming licensed spectrum allocations, compelling carriers to engineer seamless Wi-Fi handoff protocols for subscriber retention.
- Open RAN interoperability mandates:O-RAN Alliance specifications are standardizing interfaces between disaggregated radio units and edge orchestrators, lowering vendor lock-in barriers for multi-technology deployments.
Market Restraints
- Small cell site acquisition costs:Municipal permitting timelines and pole attachment fees in dense urban clusters inflate deployment economics beyond rural macro alternatives.
- Silicon supply concentration:Advanced Wi-Fi 6E and 5G NR-U chipset fabrication depends on Taiwan-based foundry capacity, exposing rollout schedules to geopolitical disruption.
- Unlicensed spectrum interference:2.4 GHz and 5 GHz band congestion from residential IoT deployments degrades quality-of-service metrics for carrier-managed hotspots.
Strategic Opportunities
- India's enterprise manufacturing corridor:TRAI's delicensing of 5 GHz and 6 GHz bands for indoor industrial use creates greenfield private network opportunities absent legacy Wi-Fi infrastructure.
- Neutral host infrastructure models:Third-party venue operators are monetizing stadium and airport deployments through multi-carrier service level agreements, decoupling capital burden from single-operator balance sheets.
- AI-driven radio resource management:Machine learning algorithms converging with real-time network telemetry enable predictive traffic steering across licensed and unlicensed layers.
Industry Challenges
- Multi-vendor integration complexity:Disaggregated Open RAN architectures demand specialized systems integration talent scarce in traditional cellular engineering teams.
- 3GPP release synchronization:Interworking protocol certification timelines lag commercial deployment pressures, forcing carriers to ship pre-standard implementations requiring subsequent firmware remediation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mobile Data Offload Market |
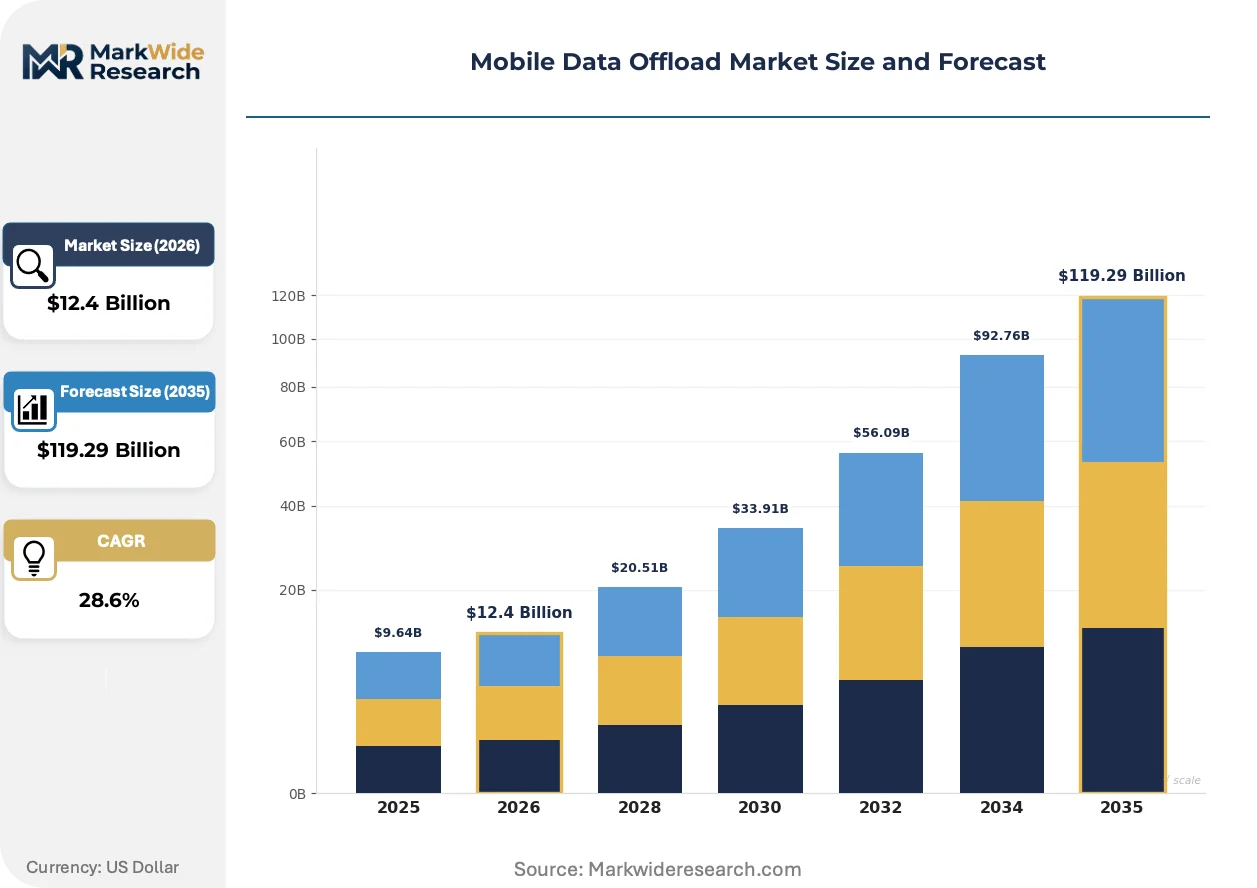
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $119.29 Billion |
| CAGR (2026 – 2036) | 28.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Offloading Technology: Wi-Fi, LTE, 5G, Bluetooth End User Segment: Smartphone Users, IoT Devices, Enterprises, Consumers Data Type: Video, Voice, Text, Gaming Service Model: Cloud-Based, On-Premises, Hybrid, Managed Services |
| Companies Covered | Ericsson, Nokia, T-Mobile, Qualcomm, Huawei, Verizon, Cisco, Samsung, AT&T, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mobile Data Offload Market Trends and Innovations
Intelligent traffic orchestration is replacing static offload policies with real-time, context-aware routing decisions that dynamically balance subscriber experience against network economics. This transformation redefines how carriers architect capacity at the network edge.
Passpoint 2.0 and Wi-Fi Calling integration is collapsing the perceptual boundary between cellular and unlicensed access for smartphone subscribers. Enterprise IT departments are mandating seamless authentication across campus deployments. The structural consequence is collapsing carrier willingness to subsidize standalone hotspot hardware in favor of software-defined radio convergence.
The FCC's 6 GHz band expansion for unlicensed use is redrawing spectrum allocation economics for indoor enterprise coverage. Automated frequency coordination rules are enabling higher-power outdoor deployments previously restricted to licensed carriers. Dense urban commercial real estate in the United States is responding with neutral host infrastructure investments that pool multi-operator access under single-venue management.
Subscription models for connectivity are fragmenting as enterprise buyers unbundle network access from device management and security services. Channel partners in the United States are displacing direct carrier relationships for mid-market deployments through managed service wrappers. This shift concentrates procurement leverage among systems integrators serving distributed retail and healthcare verticals.
Mobile Data Offload Market Segmentation
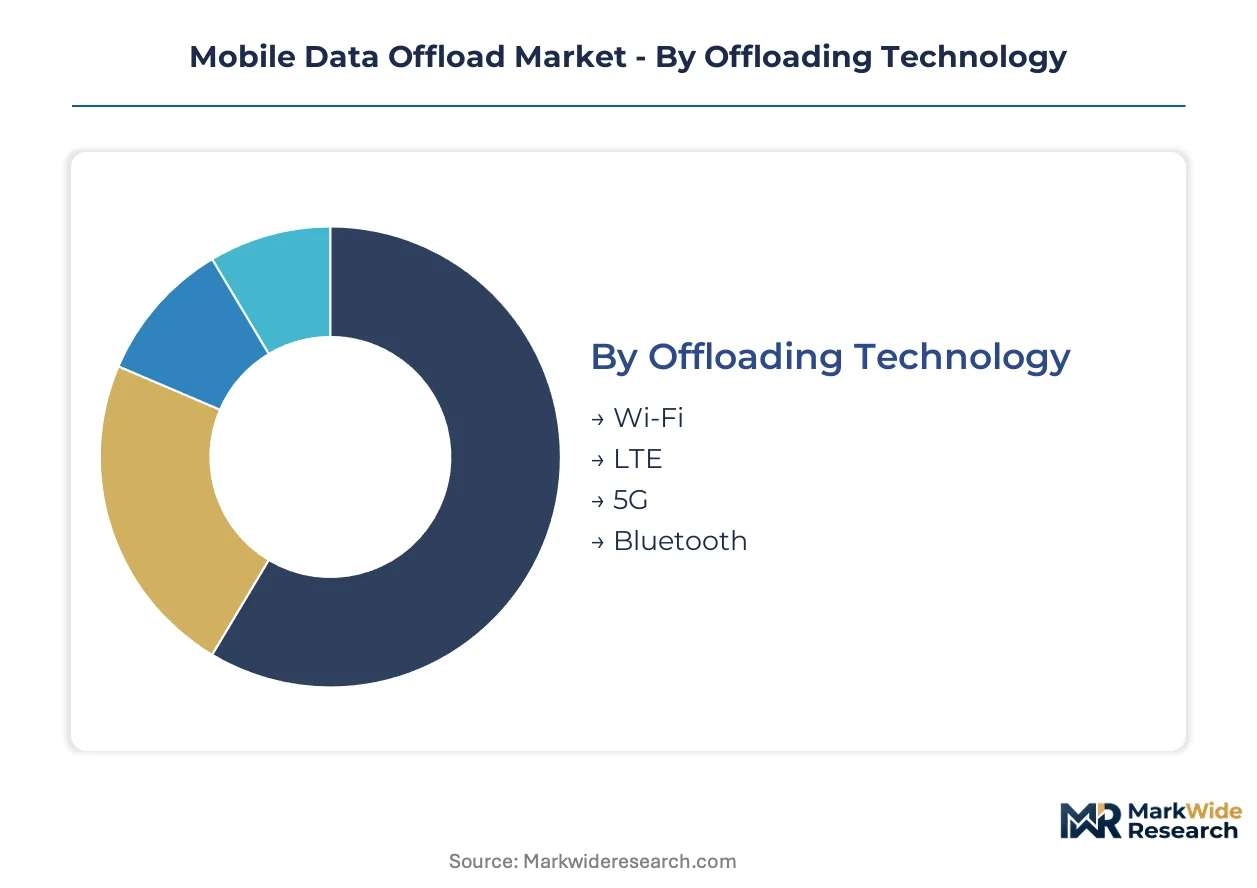
Mobile data offload architectures fragment across technology layers, user contexts, and service delivery modes. Each segmentation dimension carries distinct procurement economics and deployment velocity that reshape carrier capital allocation.
Offloading Technology:
Technology selection determines spectrum access rights, power budgets, and handoff complexity for traffic steering decisions.
- Wi-Fi:Operating across 2.4 GHz, 5 GHz, and 6 GHz unlicensed bands with IEEE 802.11ax/802.11be physical layers. Dense urban United States deployments concentrate in transit corridors and stadium venues where Passpoint 2.0 automates subscriber authentication. Municipal permitting delays constrain small cell site acquisition economics.
- 5G:NR-U and licensed-assisted access extend cellular coverage into unlicensed spectrum while maintaining 5G core anchoring. Carrier densification strategies in the United States prioritize enterprise private network slices for manufacturing campuses. CBRS Priority Access Licenses unlock dedicated capacity corridors independent of macro congestion.
- LTE:Licensed-Assisted Access and LTE-WLAN Aggregation provide backward-compatible traffic steering for legacy device populations. Spectrum refarming pressures diminish fresh deployment interest.
- Bluetooth:Low-energy protocols enable proximity-based offload for ultra-short-range IoT sensor backhaul. Volume remains constrained by range limitations and mesh complexity.
Wi-Fi commands the established base. The steepest expansion runs through 5G.
End User Segment:
Customer type governs pricing power, service level requirements, and contract tenure structures.
- Enterprises:Manufacturing, logistics, and healthcare verticals procure dedicated private network slices with guaranteed latency thresholds. United States campus deployments leverage CBRS Priority Access Licenses for quality-of-service isolation from public macro traffic. Procurement concentrates through systems integrators unbundling access from security management.
- Smartphone Users:Consumer handoff represents high-volume, lower-margin traffic pools where seamless Wi-Fi calling integration drives subscriber retention. Video streaming saturation compels carriers to engineer transparent authentication protocols.
- IoT Devices:Sensor arrays and connected machinery generate asymmetric uplink-heavy traffic patterns suited for unlicensed spectrum aggregation. Deployment lags await standardized low-power wide-area interoperability.
- Consumers:Residential broadband substitution and public hotspot roaming constitute discretionary usage with limited willingness to pay for premium tiers.
Smartphone users anchor volume scale. Enterprise contracts deliver margin expansion.
Data Type:
Traffic classification shapes compression tolerances, latency budgets, and routing priority algorithms.
- Video:Dominant traffic volume requiring high sustained throughput with moderate latency tolerance. Streaming platforms drive carrier Wi-Fi offload engineering for subscriber quality-of-experience preservation.
- Voice:Real-time session initiation protocol demands sub-150ms latency with jitter constraints. Wi-Fi calling integration collapses perceptual boundaries between cellular and unlicensed access layers.
- Gaming:Interactive cloud gaming services impose stringent upstream latency requirements favoring edge-compute proximity over raw bandwidth.
- Text:Asynchronous messaging imposes minimal resource allocation with near-zero quality-of-service sensitivity.
Video sustains infrastructure load. Gaming traffic is climbing the fastest.
Service Model:
Delivery architecture determines capital ownership, operational control, and upgrade cadence flexibility.
- Cloud-Based:Centralized orchestration platforms enable rapid policy propagation across distributed access points. United States mid-market retail deployments favor managed service wrappers displacing direct carrier relationships.
- Managed Services:Third-party venue operators assume operational burden through multi-carrier service level agreements. Neutral host infrastructure pools capital burden across competing operators in airport and stadium environments.
- Hybrid:Split control plane and user plane deployment accommodates data sovereignty requirements while retaining cloud scalability for non-sensitive traffic.
- On-Premises:Dedicated hardware ownership persists in defense and critical infrastructure verticals with air-gapped security mandates.
Cloud-based delivery holds current preference. Managed services are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The transatlantic submarine cable landing stations at Virginia Beach and Bude, Cornwall anchor data traffic exchange between North American carrier networks and European mobile operators managing offload congestion.
United States
Carrier densification strategies in Manhattan and downtown Chicago drive small cell deployments across 2.4 GHz and 5 GHz bands. FCC 6 GHz automated frequency coordination rules unlock higher-power outdoor Wi-Fi installations previously restricted to licensed spectrum. Neutral host infrastructure in Atlanta's Mercedes-Benz Stadium pools multi-operator access under single-venue management.
Germany
Industrial automation corridors in Bavaria and Baden-Württemberg procure private 5G campus networks with guaranteed latency isolation. BSI cybersecurity certification mandates shape equipment procurement for critical manufacturing infrastructure. Munich's automotive cluster deploys NR-U slices for real-time machine-to-machine coordination.
China
MIIT spectrum refarming directives accelerate 5G standalone core deployments across Yangtze River Delta manufacturing hubs. GB standards for wireless local area networks enforce domestic encryption protocols in enterprise offload installations. Shenzhen's electronics assembly complexes integrate unlicensed spectrum aggregation for sensor backhaul density.
India
TRAI delicensing of 5 GHz and 6 GHz bands for indoor industrial use creates greenfield private network opportunities in Gujarat's pharmaceutical corridors. PLI scheme incentives for telecom equipment manufacturing reduce import dependency for Wi-Fi 6E access point deployment. Bangalore's IT parks negotiate direct fiber backhaul agreements bypassing congested macro networks.
South Korea
Seoul Capital Area cloud gaming services impose stringent edge-compute proximity requirements favoring 5G NR-U over raw bandwidth expansion. MSIT spectrum allocation policies prioritize licensed-assisted access for augmented reality traffic steering. Busan port logistics operators deploy CBRS-equivalent local licenses for automated container tracking.
Mobile Data Offload Market Competitive Landscape
On the supply side, the industry is consolidating around three distinct capability layers: cloud-native core infrastructure, radio access silicon, and multi-access edge orchestration. Equipment vendors and semiconductor designers occupy separate competitive tiers with limited vertical overlap. Strategic moves concentrate on Open RAN interoperability certification and AI-driven radio resource management partnerships.
Within the infrastructure tier, Ericsson and Nokia represent divergent architectural philosophies for disaggregated access networks. Qualcomm anchors the silicon layer with cross-spectrum integration capabilities spanning licensed and unlicensed bands. These three entities exemplify how specialization across the protocol stack creates mutual dependency rather than direct substitution.
| Leading Market Players |
|---|
| Ericsson |
| Nokia |
| T-Mobile |
| Qualcomm |
| Huawei |
| Verizon |
| Cisco |
| Samsung |
| AT&T |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in Taiwan-based foundry capacity for advanced Wi-Fi 6E and 5G NR-U chipsets is compressing semiconductor pricing while extending supplier payment terms for equipment vendors. This utilization dynamic concentrates bargaining power with mobile network operators procuring at volume scale, forcing infrastructure providers to absorb margin compression through supply-chain finance facilities.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs procurement, with enterprise private network slices commanding premium rates for guaranteed latency isolation while consumer smartphone offload pools trade at commodity margins. Price differentiation centers on certification grade—FCC Part 15 compliance versus CBRS Priority Access License tiers—and volume scale of access point deployments. Pricing pressure stems from neutral host infrastructure models pooling multi-carrier demand under single-venue management, eroding single-operator pricing leverage. Enterprise manufacturing verticals exhibit lowest price sensitivity due to quality-of-service mandates, whereas consumer retail segments drive aggressive cost compression.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities are proliferating as Taiwan, China, and South Korea anchor semiconductor fabrication for baseband processors and radio frequency front-end modules. Raw material dependencies center on gallium nitride substrates, high-purity silicon wafers, and rare earth elements for power amplifiers. Single-source vulnerability concentrates in TSMC's advanced node capacity for 5G NR-U chipsets, exposing rollout schedules to geopolitical disruption. Distribution runs through systems integrators serving mid-market retail and healthcare verticals, displacing direct carrier relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where regulatory entrenchment through FCC spectrum licensing and 3GPP certification requirements creates durable barriers against unlicensed competitor encroachment.
For Market Incumbents: Insulate core revenue streams by deepening Open RAN interoperability certification investments that lock out non-compliant challengers, while adding edge compute capacity in United States manufacturing corridors to preempt neutral host displacement. The threat of AI-driven radio resource management startups demands rapid orchestration platform consolidation through backward integration into cloud-native core software stacks.
For New Entrants and Emerging Players: India's pharmaceutical and electronics manufacturing corridors present underpenetrated greenfield terrain where TRAI's 6 GHz delicensing eliminates legacy Wi-Fi infrastructure competition. Target enterprise private network deployments in Gujarat and Bangalore IT parks through direct fiber backhaul partnerships bypassing congested macro networks, leveraging PLI scheme incentives to compress equipment import costs.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among managed service providers wrapping connectivity with security and device management for mid-market retail verticals, suggesting durable cash flow quality absent pure hardware cyclicality. Over the projection horizon, acquisition focus should center on systems integrators with established channel relationships in distributed healthcare and logistics. The signal to monitor is FCC 6 GHz automated frequency coordination rulemaking, which would accelerate outdoor deployment economics and reshape infrastructure valuation multiples.
| Strategic Initiative | Industry Significance |
|---|---|
| Open RAN Interoperability Certification | FCC and O-RAN Alliance mandates standardize interfaces, lowering vendor lock-in barriers for multi-technology deployments. |
| AI-Driven Radio Resource Management | Machine learning convergence with real-time telemetry enables predictive traffic steering across licensed and unlicensed spectrum layers. |
| Neutral Host Infrastructure Partnership | Third-party venue operators pool multi-carrier access under single-venue management in stadium and airport environments. |
| CBRS Priority Access License Acquisition | FCC three-tier spectrum framework unlocks enterprise private network corridors independent of macro congestion. |
| Cloud-Native Core Platform Integration | Ericsson and Nokia anchor multi-access edge computing deployments through disaggregated software architectures. |
Research Methodology
Initial hypotheses were tested against primary input from mobile network operator infrastructure planners, Open RAN systems integration specialists, and enterprise IT procurement directors, then refined through secondary validation against FCC spectrum allocation filings, 3GPP release documentation, and carrier capex disclosures. Bottom-up modeling of access point deployment volumes triangulated with top-down carrier spending surveys to converge on market sizing estimates.
Demand-supply-balance framing anchored the analytical framework across the analysis window, with segmentation dimensions spanning offloading technology layers, end user verticals, and service delivery models. CAGRs were derived from installed base growth rates and traffic volume elasticity assumptions, incorporating FCC 6 GHz rulemaking timelines and CBRS auction participation data as industry-specific forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by hyperscale cloud providers entering private network infrastructure would shift outcomes beyond modeled boundaries. Macroeconomic contraction in enterprise capital expenditure, regulatory delay in spectrum reauthorization, or breakthroughs in satellite-to-device connectivity would prompt forecast revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center and Networking
Europe Data Center Market
Data Center and Networking
DNA Digital Data Storage Market
Data Center and Networking
China Data Center Networking Market
Data Center and Networking
South America Data Center Networking Market
Data Center and Networking
Managed Network Services Market
Data Center and Networking
Global Enterprise Networking Market
Data Center and Networking
Nigeria Data Center Networking Market
Data Center and Networking
Brazil Data Center Networking Market
Data Center and Networking
Global Content Delivery Network (CDN) Software Market
Data Center and Networking
Data Center Market
Data Center and Networking
Asia-Pacific Data Virtualization Market
Data Center and Networking
Broadband Network Gateway Market
Data Center and Networking
Software Defined Networking (SDN) and Network Function Virtualization (NFV) Market
Data Center and Networking
Europe Data Center Networking Market
Data Center and Networking
Europe Data Center Interconnect Market
Data Center and Networking
Fog Networking Market