
 Cluster Computing Market | 2026-2036
Cluster Computing Market Size, Share, and Industry Trends Forecast 2026-2036
Cluster Computing Market Analysis
Multi-source provisioning for GPU clusters is recalibrating how enterprises balance capital efficiency against supply security. Amazon Web Services, Inc. leverages its global data center footprint to offer reserved instance models for sustained workloads. Microsoft Corporation anchors its position through deep integration with Azure AI infrastructure and enterprise software stacks. CoreWeave specializes in bare-metal NVIDIA GPU provisioning, competing on latency-sensitive rendering and training pipelines.
Cluster computing denotes interconnected commodity or specialized servers operating as unified systems through high-speed interconnects such as InfiniBand or Ethernet fabrics, delivering aggregated compute for parallel processing tasks. Its primary purpose centers on solving computationally intensive problems across scientific simulation, artificial intelligence training, and large-scale data analytics. Hardware configurations dominate capital allocation, though cloud-based deployment is capturing growth as enterprises prioritize operational flexibility over fixed infrastructure. Machine learning use cases are expanding fastest, while high-performance computing maintains mature, stable demand from government and academic buyers.
FDA guidelines on AI-enabled medical devices, EPA energy efficiency standards for data centers, and EU GDPR data localization requirements collectively shape cluster procurement specifications and geographic placement decisions. NIST cybersecurity frameworks further constrain how research institutions architect multi-tenant environments. Stakeholders must monitor evolving export controls on advanced semiconductors and their cascading effects on cluster refresh cycles and vendor selection criteria.
Market Dynamics
InfiniBand interconnect bottlenecks and NVIDIA GPU supply constraints are forcing enterprises to rearchitect procurement timelines and vendor diversification strategies. Research institutions now negotiate multi-year allocation contracts eighteen months ahead of deployment.
Growth Catalysts
- Climate modeling mandates:European national weather services and oceanography institutes are expanding HPC budgets to meet IPCC reporting deadlines. Germany's DKRZ facility anchors continental coordination.
- EU AI Act compliance infrastructure:Data sovereignty requirements under GDPR Article 44 are redirecting cloud spend toward EU-located bare-metal clusters. Procurement specifications now embed geographic residency clauses.
- Liquid cooling adoption:Direct-to-chip thermal management is extending rack density limits by forty percent in hyperscale deployments. Denmark's district heating integration models demonstrate circular energy recovery.
Market Restraints
- Advanced semiconductor export controls:US Bureau of Industry and Security licensing delays are extending cluster refresh cycles for Chinese research institutions by twelve to eighteen months.
- Copper and rare earth price volatility:Power distribution busbars and permanent magnet motors in cooling systems face input cost swings tied to DRC cobalt and Chilean copper concentrate markets.
- InfiniBand switch port scarcity:Single-source dependency on Mellanox/NVIDIA interconnect silicon creates allocation risk for training clusters exceeding two thousand nodes.
Strategic Opportunities
- India's semiconductor mission:Ministry of Electronics and Information Technology incentives for domestic chip packaging are attracting HPC assembly investments near Gujarat's Dholera cluster.
- Federated learning architectures:Cross-border medical research consortia are piloting split-model training across sovereign data enclaves. Swiss university hospitals coordinate through the Personalised Health initiative.
- Carbon-aware scheduling software:Real-time grid intensity data integration is automating workload migration to low-emission periods. Finnish CSC datacenters leverage Nordic hydroelectric surplus.
Industry Challenges
- Parallel programming talent scarcity:MPI and CUDA optimization expertise concentrates in national laboratory ecosystems. Commercial enterprises compete for PhD-level systems architects through targeted visa programs.
- Legacy workload migration complexity:Fortran-based simulation codes require manual refactoring for GPU acceleration. Aerospace engineering firms maintain dual x86 and accelerator clusters during transition periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cluster Computing Market |
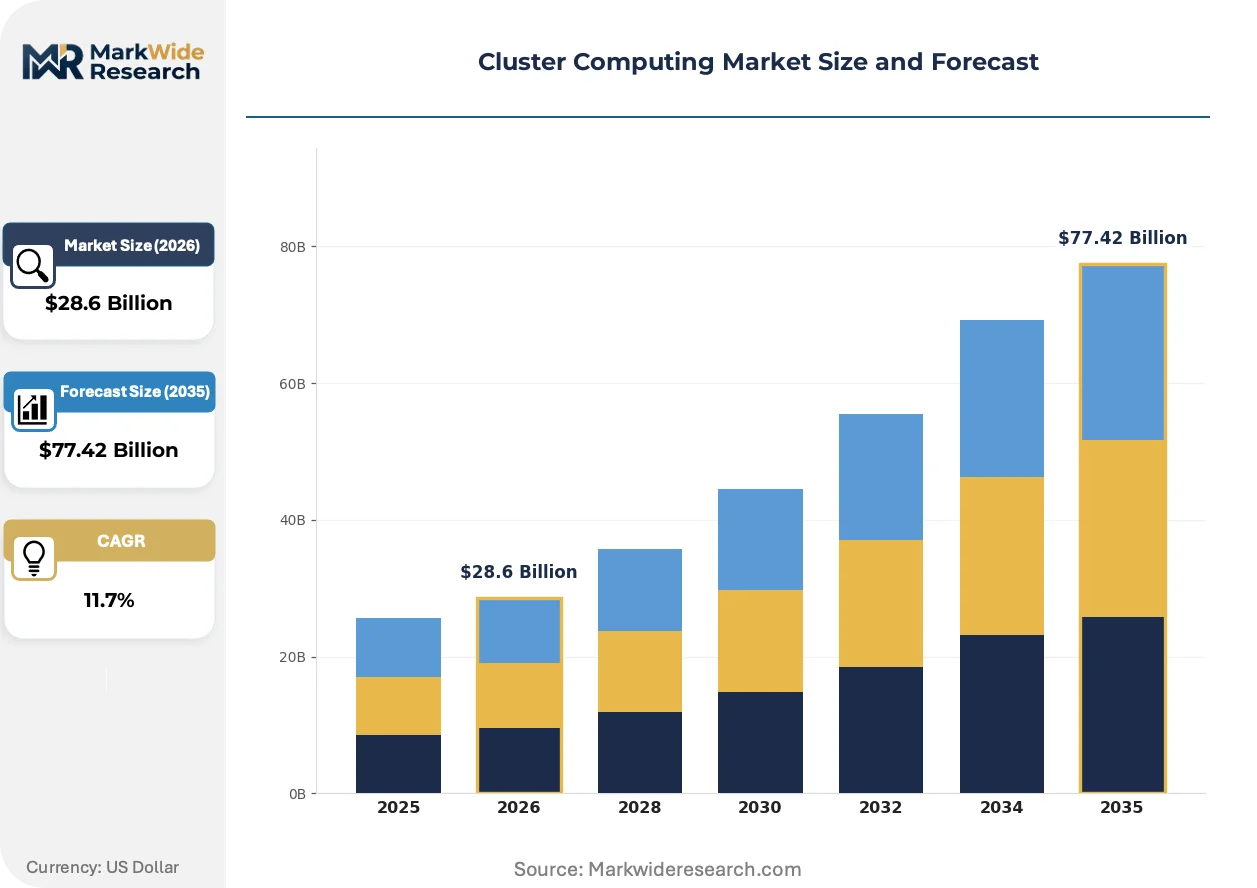
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $77.42 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Hardware, Software, Integration Services, Maintenance Services Deployment Model: On-premises, Cloud-based, Hybrid, Managed End User Industry: Research Institutions, BFSI, Manufacturing, Telecommunications Use Case: Data Analytics, High-Performance Computing, Machine Learning, Simulation |
| Companies Covered | IBM Corporation, Alibaba Group, Amazon Web Services, Inc., Databricks, CoreWeave, Microsoft Corporation, Oracle Corporation, Huawei Cloud, Alphabet Inc. (Google LLC), Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cluster Computing Market Emerging Trajectories
Workload orchestration software and sovereign cloud architectures are fragmenting traditional vendor consolidation patterns. Buyers now assemble multi-supplier stacks rather than accepting vertically integrated platforms.
Composable disaggregated infrastructure is automating resource pooling across compute, memory, and storage silos. Financial services firms in London and Singapore are deploying CXL-enabled fabrics to dynamically reconfigure trading risk simulations. This architecture is automating the elimination of stranded capacity in seasonal burst workloads.
EPA Energy Star datacenter certification and EU Code of Conduct for Datacentre Energy Efficiency are mandating power usage effectiveness disclosures. Colocation providers in Virginia and Frankfurt now publish real-time carbon intensity metrics. Hyperscale buyers are embedding these standards into request-for-proposal scoring matrices.
Reserved capacity contracting is displacing on-demand pricing for sustained AI training pipelines. Biotechnology firms in Boston and Basel are negotiating three-year bare-metal leases with guaranteed GPU allocation. European procurement teams prioritize this model to satisfy CSRD scope three emissions tracking requirements.
Cluster Computing Market Segmentation
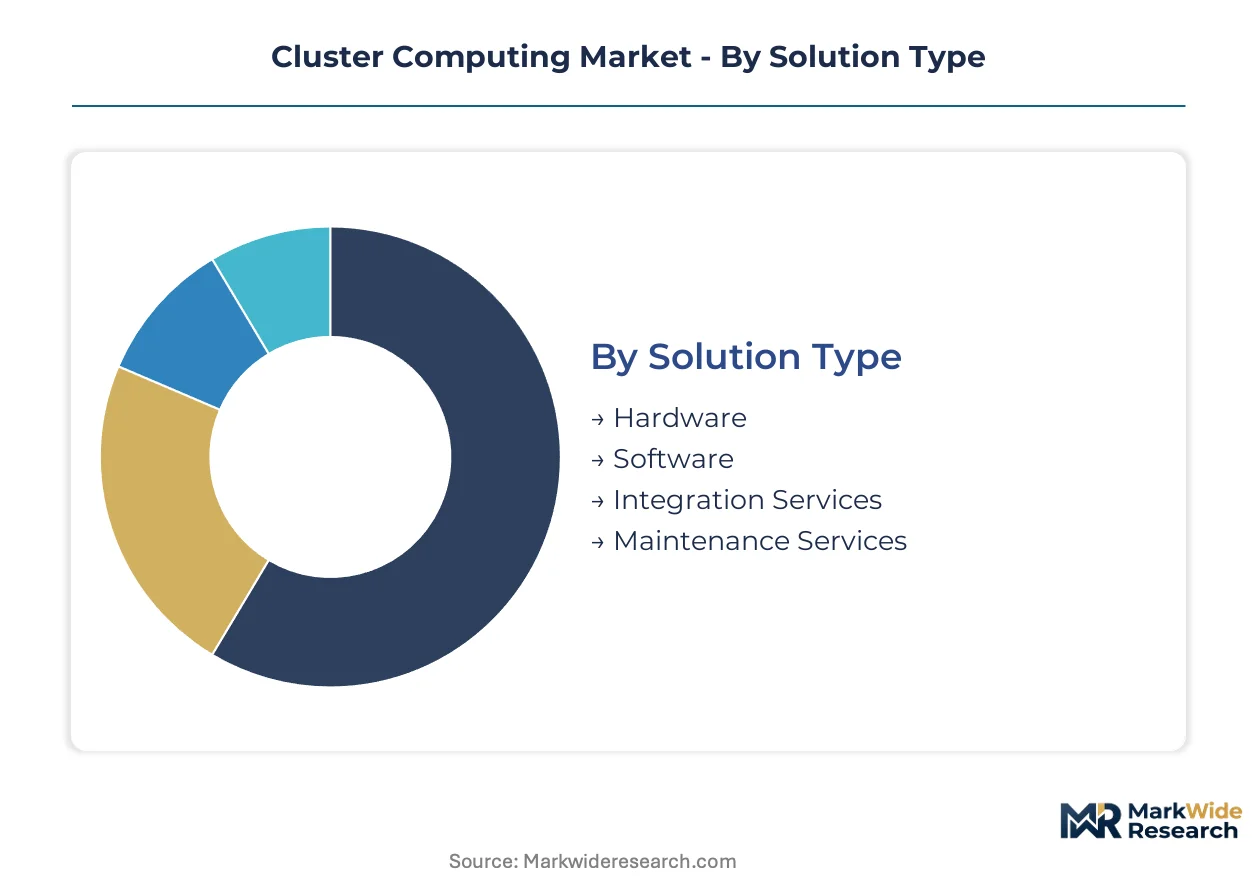
Cluster computing procurement patterns diverge sharply across solution stacks and operational models. Buyers prioritize capital efficiency in hardware, subscription flexibility in software, and sovereign control in deployment architecture.
Solution Type:
Cost tier separates enterprise buyers from research institutions negotiating multi-year allocation contracts.
- Hardware:Server nodes, interconnect fabrics, and GPU accelerators constitute the capital-heavy foundation. Germany's Fraunhofer institutes anchor continental demand as EU AI Act compliance mandates localized bare-metal infrastructure for sensitive workloads.
- Software:Workload schedulers, cluster management platforms, and parallel file systems enable resource orchestration. Financial services firms in London deploy CXL-enabled fabrics to dynamically reconfigure trading risk simulations across pooled resources.
- Integration Services:System architects configure heterogeneous hardware stacks and optimize MPI implementations for specific workloads.
- Maintenance Services:Field engineers perform predictive component replacement and firmware updates to minimize training pipeline interruptions.
Volume sits with Hardware; growth tilts toward Software.
Deployment Model:
Application criticality determines whether buyers absorb capital burden or prioritize operational agility.
- On-premises:Dedicated facilities house owned infrastructure with full physical control. Denmark's district heating integration models demonstrate circular energy recovery from direct-to-chip liquid cooling systems.
- Cloud-based:Hyperscale providers offer reserved instance models for sustained AI training pipelines. Biotechnology firms in Boston negotiate three-year bare-metal leases with guaranteed GPU allocation.
- Hybrid:Burst capacity extends on-premises clusters into cloud during peak simulation windows.
- Managed:Third-party operators assume infrastructure lifecycle responsibility including refresh planning and compliance auditing.
Cloud-based deployments are climbing the fastest as CSRD scope three emissions tracking requirements reshape procurement specifications.
End User Industry:
Customer type dictates performance thresholds, budget cycles, and regulatory exposure.
- Research Institutions:National laboratories and university consortia run climate modeling and genomics workloads. Germany's DKRZ facility coordinates European national weather services expanding HPC budgets to meet IPCC reporting deadlines.
- BFSI:Banks and insurers deploy risk analytics and fraud detection clusters. Swiss university hospitals pilot federated learning architectures across sovereign data enclaves for cross-border medical research.
- Manufacturing:Automotive and aerospace firms maintain dual x86 and accelerator clusters during Fortran-based simulation code refactoring for GPU acceleration.
- Telecommunications:Network operators process subscriber analytics and optimize radio access network planning through distributed computing.
Research Institutions command installed base; BFSI shows steepest expansion trajectory.
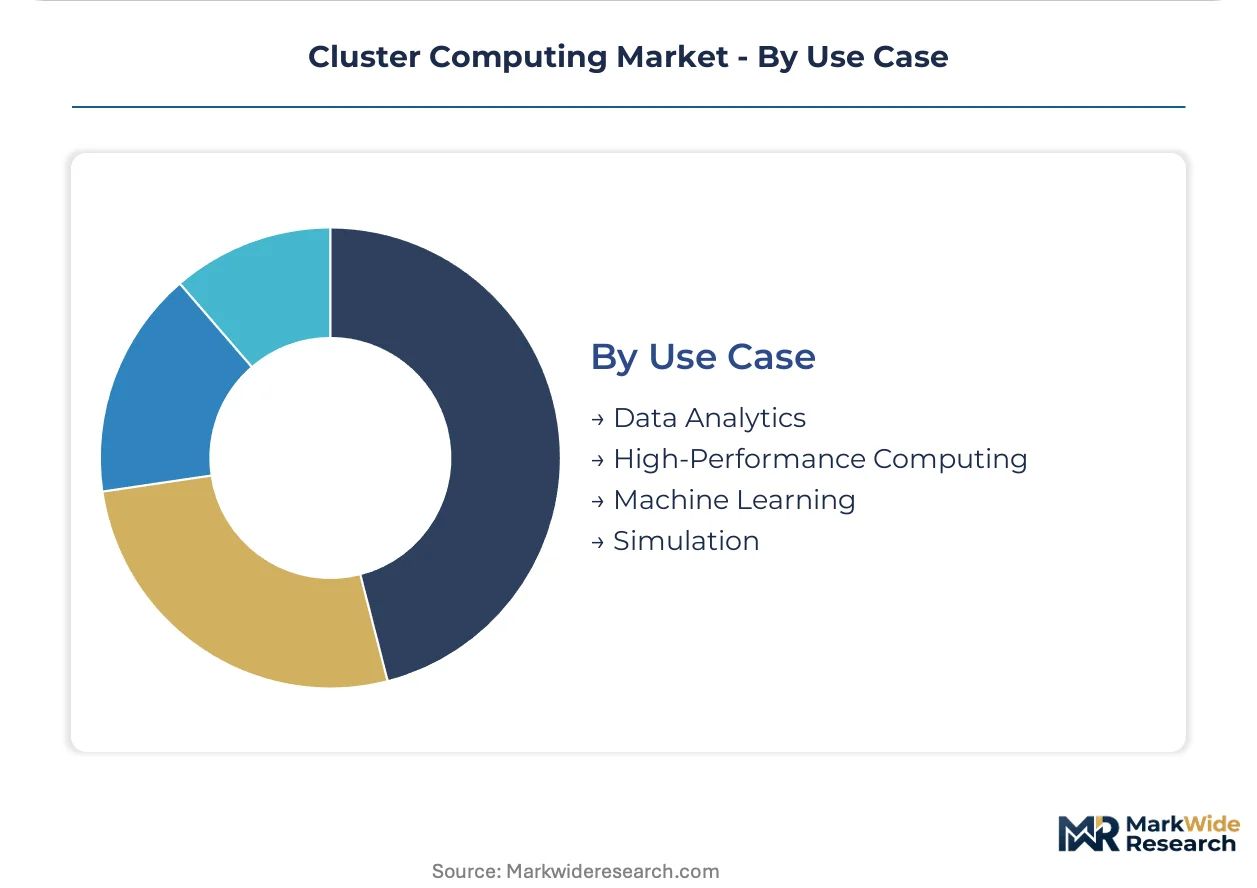
Use Case:
Maturity curve separates established simulation workloads from emerging AI pipelines.
- Data Analytics:Large-scale ETL and business intelligence processing aggregates operational datasets. Finnish CSC datacenters leverage Nordic hydroelectric surplus through carbon-aware scheduling software integrating real-time grid intensity data.
- High-Performance Computing:Established scientific simulation maintains stable demand from government and academic buyers with predictable refresh cycles.
- Machine Learning:Training pipelines for foundation models drive GPU cluster procurement. InfiniBand switch port scarcity from single-source NVIDIA interconnect silicon creates allocation risk for clusters exceeding two thousand nodes.
- Simulation:Physics-based modeling in automotive crash testing and drug discovery requires deterministic parallel execution.
High-Performance Computing retains volume dominance; Machine Learning is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Rare earth processing capacity in China's Inner Mongolia and Jiangxi provinces anchors upstream supply security for magnetic components in cooling systems and power distribution hardware deployed across major computing clusters worldwide.
United States
National laboratory ecosystems at Oak Ridge and Argonne drive sustained HPC procurement for climate and materials science workloads. The Department of Energy's Advanced Scientific Computing Research program mandates domestic fabrication content thresholds for exascale deployments. Northern Virginia's datacenter corridor concentrates hyperscale cloud capacity where Amazon Web Services and Microsoft operate reserved GPU allocation facilities.
Germany
Fraunhofer institutes and the DKRZ climate computing center anchor continental demand for bare-metal infrastructure compliant with EU AI Act data sovereignty requirements. The country's national IT regulator enforces GDPR Article 44 geographic residency clauses in public research tenders. Bavaria's Munich-Leipzig corridor hosts Europe's densest concentration of liquid-cooled training clusters integrated with district heating networks.
China
Domestic semiconductor packaging investments near Shanghai and Beijing sustain cluster assembly despite advanced GPU export control licensing delays. The Ministry of Industry and Information Technology's dual carbon goals mandate power usage effectiveness disclosures for new datacenter approvals. Yangtze River Delta facilities pilot CXL-enabled composable fabrics for financial risk analytics workloads.
India
Ministry of Electronics and Information Technology production-linked incentives for domestic chip packaging attract HPC assembly investments near Gujarat's Dholera semiconductor cluster. The country's central bank guidelines on data localization redirect cloud spend toward Mumbai and Hyderabad facilities. Bangalore's research institutions negotiate multi-year GPU allocation contracts for genomics and climate modeling pipelines.
Switzerland
Swiss university hospitals coordinate federated learning architectures for cross-border medical research under the Personalised Health initiative. Swissmedic and the Federal Data Protection and Information Commissioner enforce strict data enclave requirements for sensitive health workloads. Zurich and Geneva host sovereign bare-metal clusters serving EU research consortia seeking GDPR-compliant alternatives to hyperscale clouds.
Cluster Computing Market Vendor Landscape
Strategic partnerships dominate the current landscape as vendors assemble multi-supplier stacks rather than accepting vertically integrated platforms. The market structures around three distinct tiers: hyperscale cloud providers with global datacenter footprints, specialized bare-metal GPU operators focusing on latency-sensitive workloads, and systems integrators configuring heterogeneous hardware for research institutions. Competitive positioning hinges on reserved capacity contracting for sustained AI training pipelines and sovereign cloud certifications for EU compliance.
Within the hyperscale tier, Amazon Web Services and Microsoft Corporation anchor enterprise demand through deep integration with AI infrastructure and enterprise software stacks. CoreWeave occupies a specialized position exemplifying the bare-metal GPU provisioning archetype, competing on latency-sensitive rendering and training pipelines. Among China-based operators, Huawei Cloud represents the domestic sovereign cloud alternative serving institutions navigating export control constraints.
| Leading Market Players |
|---|
| IBM Corporation |
| Alibaba Group |
| Amazon Web Services, Inc. |
| Databricks |
| CoreWeave |
| Microsoft Corporation |
| Oracle Corporation |
| Huawei Cloud |
| Alphabet Inc. (Google LLC) |
| Others |
Supply Flow & Price Mechanics
Liquid cooling retrofits and direct-to-chip thermal architectures are compressing total cost of ownership curves while concentrating procurement leverage among specialized subsystem vendors. Denmark's district heating integration models demonstrate how circular energy recovery clauses in bare-metal contracts now bundle thermal output guarantees with compute pricing, reshaping how buyers evaluate lifecycle economics against upfront capital outlays.
Pricing Analysis
Warranty bundling separates premium bare-metal providers from commodity cloud resellers, with multi-year field engineering contracts and guaranteed GPU allocation clauses commanding fifteen to twenty percent premiums over unbundled on-demand instances. Three-tier pricing structure across reserved capacity, spot interruptible, and managed bare-metal levels stratifies buyer segments, with biotechnology firms in Boston and Basel absorbing premium tiers for CSRD scope three emissions tracking compliance while academic consortia optimize for spot pricing. Cost compression in standard cloud tiers is intensifying because hyperscale providers are cross-subsidizing AI training workloads with enterprise software attach rates. Research institutions exhibit highest price sensitivity due to grant-funded budget cycles, whereas financial services firms prioritize latency guarantees over unit economics.
Supply Chain Analysis
NVIDIA certification gating for InfiniBand interconnect silicon creates single-source bottlenecks that constrain cluster scaling beyond two thousand nodes, forcing buyers to pre-negotiate multi-year allocation contracts eighteen months ahead of deployment. Taiwan, South Korea, and the United States anchor advanced semiconductor fabrication, while China's Inner Mongolia and Jiangxi provinces concentrate rare earth processing for magnetic components in cooling systems and power distribution hardware. Copper concentrate from Chilean mines and cobalt from DRC operations feed power distribution busbars and permanent magnet motors, exposing infrastructure builds to commodity price volatility. Distribution runs through direct OEM relationships for hyperscale deployments and systems integrator channels for research institutions requiring heterogeneous stack configuration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU AI Act's data sovereignty mandates erect a compliance moat that advantages EU-located bare-metal operators over hyperscale cloud alternatives, transforming geographic certification into a durable barrier to entry for infrastructure providers serving sensitive workloads.
For Market Incumbents: Anticipate InfiniBand switch port scarcity by securing multi-year NVIDIA allocation contracts before competitor lock-in solidifies, and deepen backward integration into liquid cooling subsystem design to capture margin pools migrating from compute hardware to thermal management. CoreWeave's bare-metal specialization threatens hyperscale incumbents in latency-sensitive rendering pipelines, while EPA Energy Star certification investments defend positioning in sustainability-conscious procurement evaluations. For New Entrants and Emerging Players: EU AI Act compliance infrastructure in Germany opens a window for sovereign cloud alternatives to hyperscale providers, particularly for Fraunhofer institute and DKRZ facility tenders embedding GDPR Article 44 geographic residency clauses. India's Ministry of Electronics and Information Technology production-linked incentives near Gujarat's Dholera cluster represent the most penetrable geography for HPC assembly investments, with Bangalore research institutions offering anchor demand for genomics and climate modeling pipelines. Lead with carbon-aware scheduling software integration as a differentiated go-to-market angle, leveraging Finnish CSC datacenter models for reference architecture credibility. For Investors and Strategic Acquirers: Exit pathways concentrate in specialized bare-metal GPU operators with reserved capacity contracting depth and sovereign cloud certifications, rather than undifferentiated cloud resellers facing hyperscale pricing pressure. Long-term viability hinges on sustained AI training pipeline demand from biotechnology and financial services verticals, with CXL-enabled composable fabric capabilities serving as a defensible technology moat. Watch InfiniBand switch port allocation announcements from NVIDIA as an inflection indicator for vendor consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Reserved Capacity Contracting | Biotechnology firms in Boston negotiate three-year bare-metal leases with guaranteed GPU allocation to satisfy CSRD emissions tracking. |
| Sovereign Cloud Certification | EU AI Act compliance infrastructure redirects cloud spend toward Germany-located bare-metal clusters with GDPR Article 44 residency clauses. |
| Liquid Cooling Integration | Denmark's district heating models demonstrate circular energy recovery extending rack density limits by forty percent in hyperscale deployments. |
| CXL-Enabled Fabric Deployment | Financial services firms in London and Singapore dynamically reconfigure trading risk simulations across pooled compute and memory resources. |
| Carbon-Aware Scheduling Software | Finnish CSC datacenters leverage Nordic hydroelectric surplus through real-time grid intensity data integration automating workload migration. |
Methodological Framework
Independent corroboration across hyperscaler capex disclosures, national laboratory procurement records, and EU tender databases underwrites the qualitative findings in this study. Primary interviews with HPC facility directors, cloud procurement officers at biotechnology firms, systems integrators configuring heterogeneous stacks, and thermal engineering specialists provided operational context on InfiniBand bottlenecks and liquid cooling adoption trajectories. Secondary validation drew from Department of Energy Advanced Scientific Computing Research program filings, EPA Energy Star datacenter certification registries, and Fraunhofer institute annual reports. Bottom-up cluster deployment counts and top-down infrastructure spending estimates were reconciled to anchor volume projections.
Historical reference periods spanning pre-pandemic baseline through export control implementation phases established the forecast anchor for modeling adoption curve shifts. The analytical framework segments by solution type, deployment model, end user industry, and use case maturity, with sovereign compliance intensity serving as an additional cross-cutting dimension across the projection horizon. CAGRs were derived from deployment velocity differentials between machine learning training pipelines and established high-performance computing simulation workloads, incorporating GPU allocation contract lead times and rare earth price volatility assumptions as industry-specific forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for CXL-enabled composable fabrics or photonic interconnects would alter the outlook for vendor consolidation patterns and procurement timeline compression. Forecasts reflect assumptions regarding sustained AI training demand, export control stability, and rare earth supply continuity that could revise projections if disrupted. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center and Networking
Data Center Services Market
Data Center and Networking
Data Center Interconnect Market
Data Center and Networking
Global Database Management System (DBMS) Market
Data Center and Networking
New Zealand Data Center Networking Market
Data Center and Networking
Datacenter Network Consulting and Integration Service Market
Data Center and Networking
APAC Data Center Networking Market
Data Center and Networking
Data Center Servers Market
Data Center and Networking
Global Storage Area Network (SAN) Switches Market
Data Center and Networking
Global DNS Service Market
Data Center and Networking
South Africa Data Center Networking Market
Data Center and Networking
Poland Data Center Networking Market
Data Center and Networking
Singapore Data Center Networking Market
Data Center and Networking
Global Software Defined Networking (SDN) Market
Data Center and Networking
Denmark Data Center Networking Market
Data Center and Networking
Global Network Operating Systems Market
Data Center and Networking
US Dark Fiber Network Market