
 Egypt LED Lighting Market | 2026-2036
Egypt LED Lighting Market Size, Share, and Industry Trends Forecast 2026-2036
Egypt LED Lighting Market Intelligence
The gap between premium smart-enabled fixtures and basic commodity bulbs is broadening across Egyptian distribution channels. Inventronics leverages its driver technology portfolio to anchor high-reliability commercial installations. G'nK Group sustains broad retail penetration through conventional fixture lines. Elios differentiates by specializing in architectural accent and hospitality-grade luminaires.
LED lighting denotes solid-state illumination using semiconductor diodes emitting visible light when electrical current passes through a p-n junction, typically operating at 2–4 volts DC with luminous efficacy exceeding 100 lumens per watt. Its primary purpose is to displace incandescent and fluorescent sources across commercial, industrial, and outdoor infrastructure. Bulbs and tubes retain volume leadership in residential replacement cycles, while panels and high bays capture margin pools in commercial and industrial new-build specifications. Smart lighting and solar-integrated technology segments are expanding fastest as facility managers seek automated controls and off-grid reliability.
The Egyptian Organization for Standardization and Quality enforces energy efficiency labeling and product safety certification for electrical lighting equipment entering domestic commerce. Egypt's Ministry of Electricity and Renewable Energy promotes LED adoption through demand-side management programs and tariff restructuring for industrial consumers. Stakeholders must monitor regulatory tightening on import standards and local assembly incentives to calibrate sourcing and manufacturing decisions.
Market Dynamics
The Egyptian LED Lighting Market pivots on mandatory energy efficiency labeling enforced by the Egyptian Organization for Standardization and Quality, which accelerates replacement cycles and compresses demand for legacy fluorescent fixtures across commercial corridors.
Growth Catalysts
- Suez Canal Economic Zone industrialization:Heavy manufacturing expansion drives high-bay and floodlight specifications in warehouse and logistics facilities.
- Egyptian Ministry of Electricity demand-side management programs:Tariff restructuring for industrial consumers subsidizes LED retrofits in energy-intensive sectors.
- Smart driver integration:Embedded controls enable daylight harvesting and occupancy sensing in Alexandria hospitality developments.
Market Restraints
- Import dependency on semiconductor substrates:Driver IC and LED chip sourcing concentrates in East Asian supply chains, exposing Egyptian assemblers to currency volatility.
- Local certification bottlenecks:Egyptian Organization for Standardization and Quality testing queue delays product launches by 8-14 weeks.
- Fluorescent T8 residual stock:Grey-market tubular imports from unregulated sources undercut compliant LED pricing in price-sensitive residential segments.
Strategic Opportunities
- Upper Egypt off-grid solar-LED bundling:Rural electrification gaps create captive demand for photovoltaic-integrated street and home lighting.
- Cairo-Alexandria corridor smart city pilots:Municipal IoT infrastructure tenders specify networked luminaires with centralized dimming protocols.
- Local assembly incentives:Industrial Development Authority tariff exemptions on imported components reward domestic fixture manufacturing.
Industry Challenges
- Embedded systems firmware expertise scarcity:Smart lighting deployment outpaces availability of programmers capable of DALI-2 and wireless mesh configuration.
- Legacy electrical contractor skill gaps:Installation workforce trained on magnetic ballast systems requires reskilling for DC driver and control wiring.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Egypt LED Lighting Market |
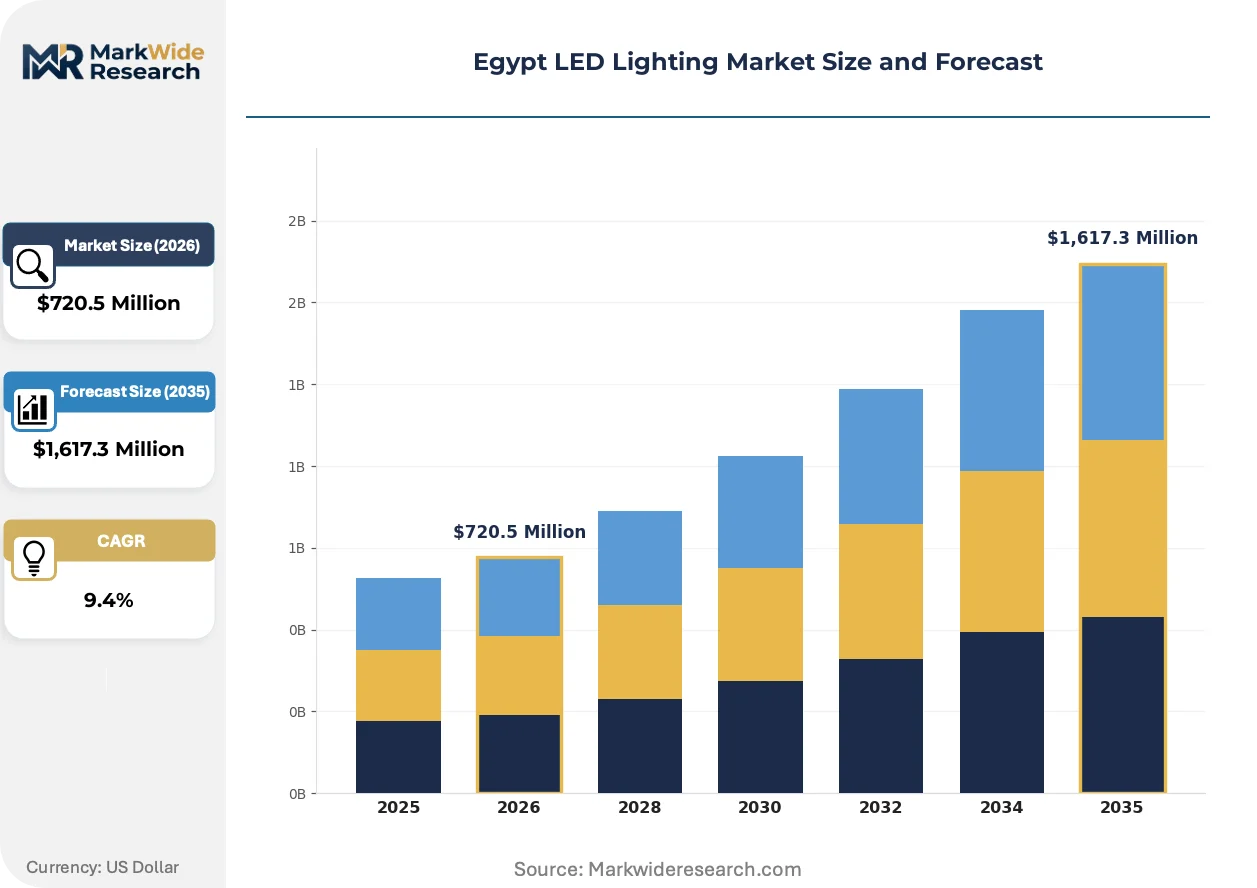
| Market Size in 2026 | $720.5 Million |
| Market Size in 2035 | $1,617.3 Million |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bulbs, Tubes, Panels, High Bays End User: Residential, Commercial, Industrial, Outdoor Technology: Smart Lighting, RGB, Tunable White, Solar Application: Retail, Hospitality, Office, Sports |
| Companies Covered | Inventronics, G'nK Group, Elios, The Lounge Event Planner, Tactic, Egyptian Saudi Company, Lighthouse, NewLevel Events, Aimex Egypt, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Egypt LED Lighting Market Strategic Shifts & Innovations
Human-centric lighting specifications and solar-hybrid architectures are reconfiguring product roadmaps across Egyptian commercial and infrastructure verticals.
Tunable white LED engines with circadian rhythm programming are consolidating specification authority in healthcare and education sectors. Cairo hospital groups and Alexandria university campuses specify variable correlated color temperature systems for patient recovery and student alertness optimization. This consolidation compresses demand for static-CCT panels and rewards suppliers with in-house spectral engineering capability.
Egyptian Organization for Standardization and Quality expanded safety testing protocols for lithium-ion battery-integrated solar luminaires in 2024. The regulation mandates UN 38.3 transportation certification and local thermal runaway testing for off-grid streetlight tenders. Rural electrification contractors now face extended qualification timelines, favoring established suppliers with pre-certified product platforms.
Facility managers in Greater Cairo commercial towers now unbundle lighting maintenance from capital purchase contracts. Third-party service providers assume responsibility for lumen depreciation monitoring and group relamping, displacing traditional distributor-led transactional sales. This servitization concentrates procurement authority among integrated facility management firms with multi-site portfolios.
Egypt LED Lighting Market Segmentation
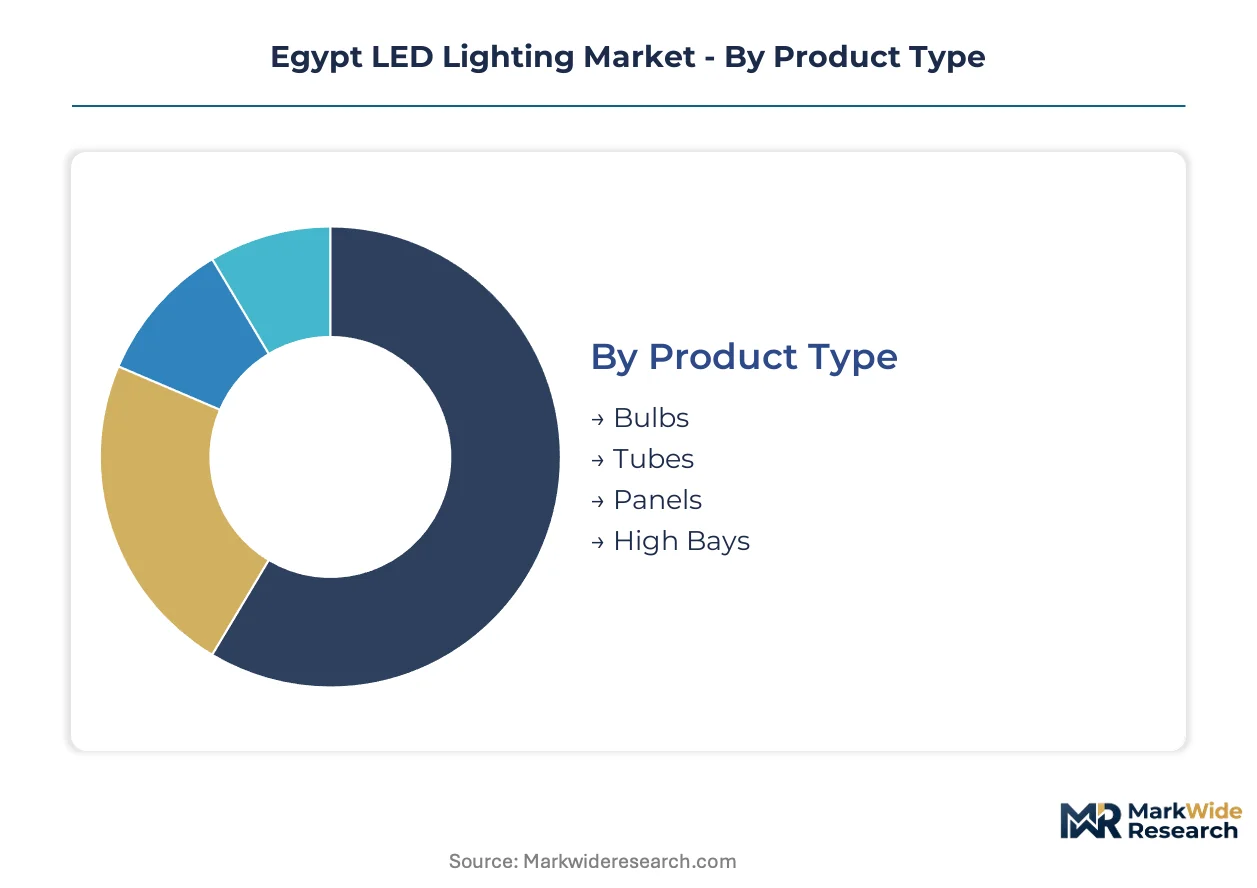
Egyptian procurement patterns diverge sharply between price-driven residential replacement cycles and specification-intensive commercial new-builds. Segmentation reveals where margin pools concentrate versus where volume flows, guiding supplier resource allocation across Cairo-Alexandria corridor projects and Upper Egypt rural electrification.
Product Type:
Cost tier drives buyer selection, with initial fixture price dominating residential decisions while total cost of ownership governs commercial and industrial specifications.
- Panels:Edge-lit and back-lit flat panels deliver uniform illumination through diffused LED arrays, typically 600x600mm or 1200x600mm formats. Greater Cairo commercial towers specify these for open-plan offices, with Egyptian Organization for Standardization and Quality energy labeling compressing demand for non-compliant imports.
- High Bays:High-lumen industrial fixtures mount 15-40 feet above factory floors, utilizing specialized heat sinks and driver architectures for 50,000-hour lifespans. Suez Canal Economic Zone warehouse and logistics facilities drive specification authority here, with heavy manufacturing expansion accelerating replacement of metal halide legacy systems.
- Bulbs:Standard A19 and decorative form factors serve residential retrofit demand across price-sensitive segments.
- Tubes:T8 and T5 linear replacements compete against grey-market fluorescent residual stock in commercial retrofit applications.
Volume sits with Bulbs; growth tilts toward High Bays.
End User:
Application maturity shapes procurement sophistication, with Industrial buyers demanding specification-grade reliability and Residential segments prioritizing point-of-sale availability.
- Industrial:Energy-intensive manufacturing facilities operate 16-24 hour production cycles, making lumen maintenance and driver reliability critical. Egyptian Ministry of Electricity tariff restructuring subsidizes LED retrofits in cement, steel, and chemical processing plants across the industrial corridor.
- Commercial:Retail, office, and hospitality facilities balance aesthetic requirements with operational cost control. Alexandria hotel developments and Cairo corporate headquarters specify tunable white and smart-enabled systems for daylight harvesting and occupancy sensing.
- Residential:Individual households and small landlords drive replacement bulb volume through conventional retail channels.
- Outdoor:Municipal street lighting and infrastructure applications concentrate procurement authority in government tenders.
Procurement sophistication peaks with Industrial; expansion accelerates fastest in Commercial.
Technology:
Integration complexity separates premium specifications from commodity procurement, with embedded controls and renewable coupling commanding margin premiums.
- Smart Lighting:Networked luminaires with DALI-2, wireless mesh, or proprietary protocols enable centralized dimming, occupancy sensing, and energy analytics. Cairo-Alexandria corridor smart city pilots specify these for municipal IoT infrastructure, though embedded systems firmware expertise scarcity constrains deployment velocity.
- Solar:Photovoltaic-integrated luminaires with lithium-ion storage serve off-grid applications. Egyptian Organization for Standardization and Quality expanded safety testing protocols for battery-integrated systems, extending qualification timelines for rural electrification contractors.
- Tunable White:Variable correlated color temperature engines support circadian rhythm programming in healthcare and education verticals.
- RGB:Color-mixing architectures address architectural accent and entertainment lighting specifications.
Adoption breadth favors Tunable White; specification growth tilts toward Smart Lighting.
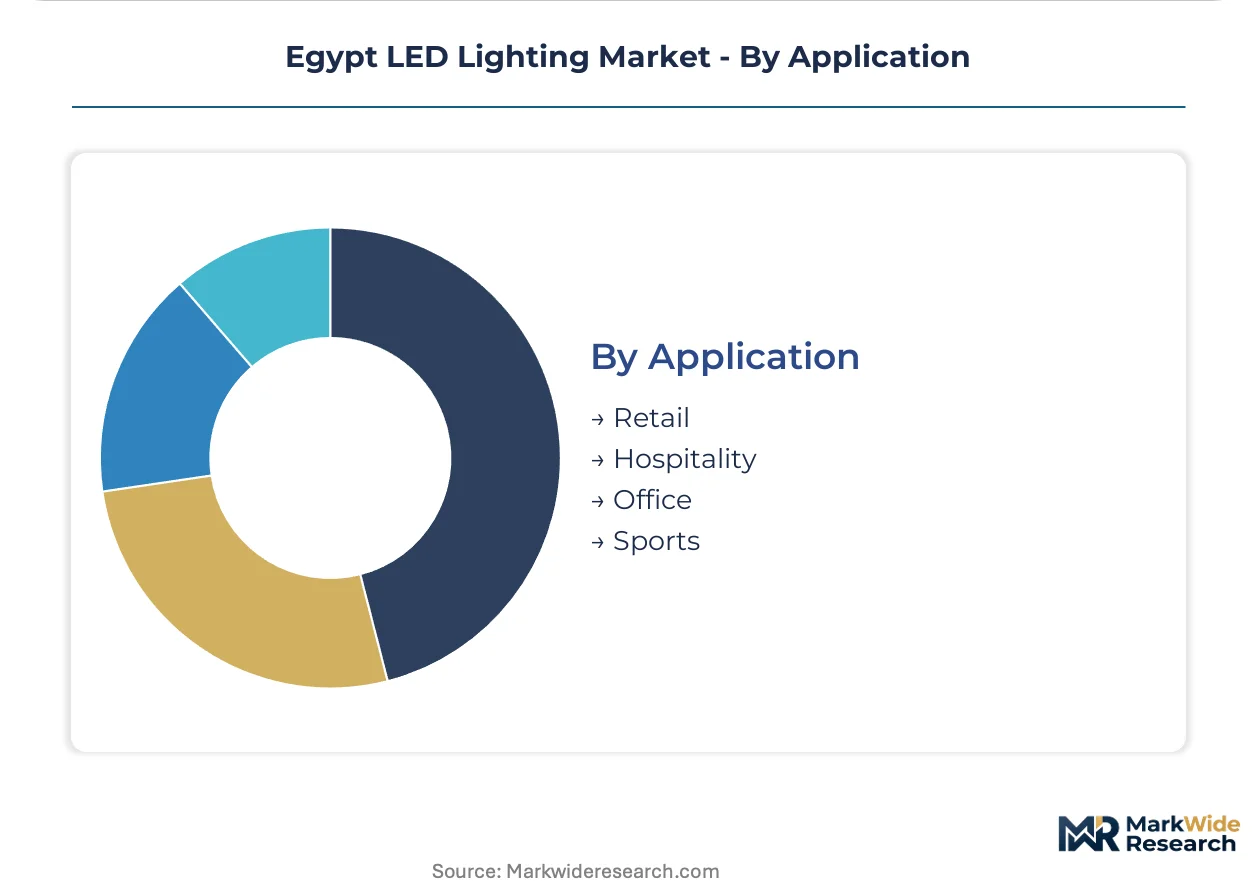
Application:
Facility type determines performance requirements, with hospitality and sports venues demanding specialized optical engineering versus standardized office deployments.
- Hospitality:Hotels, restaurants, and entertainment venues prioritize aesthetic flexibility, dimming performance, and fixture concealment. Alexandria resort developments and Cairo boutique hotel renovations drive demand for architectural-grade luminaires with custom finishes and precise beam control.
- Sports:Arena and stadium lighting requires high-output floodlight arrays with minimal glare and broadcast-quality color rendering. New Cairo sports complex developments and Alexandria football venue upgrades specify these for professional competition standards.
- Office:Corporate workplace lighting emphasizes uniformity, glare control, and energy compliance.
- Retail:Merchandise display applications balance color rendering with operational cost management.
Specification intensity concentrates in Sports; project volume sits with Office.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Greater Cairo anchors LED lighting procurement volume through commercial tower retrofits and new-build specifications, while Alexandria drives hospitality-grade architectural demand and smart city pilot deployments.
Greater Cairo
Commercial tower retrofits and corporate headquarters construction consume specification-grade panels and tunable white systems. Egyptian Organization for Standardization and Quality energy efficiency labeling compresses demand for non-compliant imports. New Cairo business district developments specify networked luminaires with centralized dimming protocols.
Alexandria
Resort renovations and boutique hotel developments drive demand for architectural-grade accent luminaires with custom finishes. Alexandria smart city pilots embed IoT infrastructure with municipal tenders specifying DALI-2 networked controls. Alexandria university campuses deploy variable correlated color temperature systems for student alertness optimization.
Suez Canal Economic Zone
Heavy manufacturing expansion accelerates high-bay and floodlight specifications in warehouse and logistics facilities. Egyptian Ministry of Electricity tariff restructuring subsidizes LED retrofits in cement and steel processing plants. Port-centric industrial clusters displace metal halide legacy systems with 50,000-hour lifespan fixtures.
Upper Egypt
Rural electrification gaps create captive demand for photovoltaic-integrated street and home lighting systems. Egyptian Organization for Standardization and Quality expanded safety testing protocols for lithium-ion battery-integrated solar luminaires in 2024. Off-grid solar-LED bundling concentrates procurement among rural electrification contractors with pre-certified product platforms.
Delta Region
Agricultural processing facilities and textile mills operate energy-intensive production cycles requiring lumen maintenance reliability. Demand-side management programs target industrial consumers with subsidized retrofit financing. Mansoura and Tanta industrial zones specify driver-reliable fixtures for 16-24 hour operational schedules.
Egypt LED Lighting Market Key Industry Players
Premium-margin players sit above commodity-margin players across technology integration and certification compliance dimensions. The vendor base stratifies between driver-technology specialists, broad retail distributors, and architectural-grade fabricators. Three archetypes dominate: semiconductor-anchored technology suppliers, conventional fixture assemblers with retail penetration, and hospitality-focused design specialists. Competitive moves concentrate on local assembly qualification and smart control firmware development.
Within the technology-anchored tier, Inventronics exemplifies driver-technology specialization for high-reliability commercial installations. G'nK Group occupies a position among broad retail distributors sustaining conventional fixture lines across price-sensitive segments. Elios represents the architectural-grade specialization vector, focusing on hospitality and accent luminaire specifications. These three companies illustrate the market's tripartite structure without exhaustively mapping competitive positions.
| Leading Market Players |
|---|
| Inventronics |
| G'nK Group |
| Elios |
| The Lounge Event Planner |
| Tactic |
| Egyptian Saudi Company |
| Lighthouse |
| NewLevel Events |
| Aimex Egypt |
| Others |
Cost & Logistics Intelligence
Smart-commodity bifurcation splits Egyptian LED procurement into specification-grade commercial contracts and price-driven residential replacement cycles, with Egyptian Organization for Standardization and Quality certification tiers determining which suppliers capture margin versus volume positions. This divergence channels premium buyers toward integrated driver-technology providers while grey-market imports feed price-sensitive segments through parallel distribution networks.
Pricing Analysis
Value-based pricing anchored to energy savings outcomes dominates commercial and industrial specifications, with Egyptian Ministry of Electricity demand-side management programs subsidizing payback-period calculations for cement and steel plant retrofits. Price differentiation rests on certification grade against EOSQ energy labeling and driver reliability warranties, with industrial buyers least sensitive to upfront fixture cost. Cost compression in residential bulbs intensifies because grey-market fluorescent T8 residual stock undercuts compliant LED pricing.
Supply Chain Analysis
Certification and qualification gating through Egyptian Organization for Standardization and Quality testing queues create 8-14 week entry barriers that favor established suppliers with pre-certified platforms. Driver IC and LED chip sourcing concentrates in China, Taiwan, and South Korea, exposing Egyptian assemblers to currency volatility against semiconductor substrate costs. Single-source vulnerability runs through East Asian substrate suppliers. Distribution runs through industrial distributors for commercial projects and conventional retail channels for residential replacement cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Egypt's LED lighting sector sits in a technology-transition phase where solid-state semiconductor diodes displace legacy fluorescent and metal halide infrastructure across commercial, industrial, and municipal applications.
For Market Incumbents: Hedge against grey-market import erosion by deepening backward integration into driver assembly within Industrial Development Authority tariff-exempt zones, while locking multi-site facility management contracts through servitized maintenance bundling that displaces transactional distributor relationships.
For New Entrants and Emerging Players: Rural electrification contractors represent the most penetrable channel partner type for photovoltaic-integrated solar-LED bundling in Upper Egypt, where pre-certified lithium-ion battery platforms create qualification moats against unqualified competitors and government tender access depends on established contractor relationships.
For Investors and Strategic Acquirers: Re-rating potential sits with driver-technology specialists given smart city infrastructure tenders specifying DALI-2 networked controls across the Cairo-Alexandria corridor. Long-term viability favors suppliers with in-house spectral engineering and firmware development capability. Embedded systems programming scarcity signals inflection when training pipeline output crosses deployment demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Local Assembly Qualification | Industrial Development Authority tariff exemptions reward domestic fixture manufacturing over import-dependent models. |
| Smart Driver Integration | DALI-2 and wireless mesh capability captures Cairo-Alexandria corridor municipal IoT infrastructure tenders. |
| Solar-LED Bundling Certification | UN 38.3 and local thermal runaway testing compliance unlocks Upper Egypt rural electrification procurement. |
| Servitized Maintenance Contracts | Integrated facility management firms displace distributor-led sales through lumen depreciation monitoring agreements. |
| Firmware Development Investment | In-house embedded systems capability addresses programmer scarcity constraining smart lighting deployment velocity. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with commercial lighting specifiers, industrial facility managers, electrical contractors, and distribution channel partners. Egyptian Organization for Standardization and Quality certification databases, Egyptian Ministry of Electricity demand-side management program disclosures, and Suez Canal Economic Zone industrial development records provided foundational secondary validation. Bottom-up project pipeline tracking and top-down market sizing triangulated volume estimates.
Segment-level granularity modeled product type, end user, technology integration, and application dimensions across the projection horizon, with regional splits across Greater Cairo, Alexandria, Suez Canal Economic Zone, Upper Egypt, and Delta Region industrial clusters. CAGRs derived from fitted growth curves against historical replacement cycle data and policy-driven demand acceleration. Forecast inputs incorporated industrial electricity tariff restructuring schedules and smart city pilot tender timelines.
Caveats apply where Egyptian Organization for Standardization and Quality regulatory tightening or East Asian semiconductor supply disruptions could materially shift the outlook. Forecasts reflect assumptions on certification queue durations and subsidy program continuity. A model refresh is warranted upon material change in industrial electrification policy or lithium-ion battery safety protocol revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
LED
Global Waterproof LED Module Market
LED
Middle East LED Lights Market
LED
UK Outdoor LED Lighting Market
LED
Japan LED Market
LED
Global Chip on Board (COB) Light Emitting Diode Market
LED
Japan Outdoor LED Lighting Market
LED
Arrow LED Displays Market
LED
Asia Pacific Outdoor LED Lighting Market
LED
North America Outdoor LED Lighting Market
LED
China Outdoor LED Lighting Market
LED
UV-C LED Market
LED
LED Phosphor Materials Market
LED
Thailand LED Market
LED
Dot-Matrix LED Displays Market
LED
France Indoor LED Lighting Market
LED
China LED Lighting Market