
 RF and Microwave Diodes Market | 2026-2036
RF and Microwave Diodes Market Size, Share, and Industry Trends Forecast 2026-2036
RF and Microwave Diodes Market Analytics
The FCC's spectrum reallocation for 5G mmWave bands is pivoting the cost-of-entry calculus for RF diode suppliers, forcing new compliance investments in thermal management and linearity specifications. NXP Semiconductors leverages its GaN-on-SiC foundry partnerships to sustain leadership in defense-grade PIN diodes. Qorvo anchors North American supply security through in-house epitaxy for X-band and Ku-band components. Infineon Technologies dominates European automotive radar sockets with AEC-Q100-qualified Schottky variants.
RF and microwave diodes are two-terminal semiconductor devices engineered to rectify, switch, or generate signals at frequencies exceeding 300 MHz, with Schottky variants achieving cutoff frequencies above 1 THz through metal-semiconductor junctions that eliminate minority-carrier storage effects. These components serve as foundational building blocks in radar front-ends, 5G base station transceivers, and satellite communication payloads where switching speed and noise figure govern system performance. PIN diodes retain structural dominance in high-power switching applications due to their thick intrinsic region and controlled carrier lifetime, while GaN-based variants represent the fastest-growing technology segment as base station OEMs prioritize efficiency above 6 GHz. Silicon carbide substrates command premium positioning in aerospace and defense programs where radiation hardness and junction temperature tolerance above 200°C justify unit cost multiples against silicon alternatives.
The FCC, ETSI, and ITU-R frameworks collectively shape product roadmaps through emission masks, spurious limits, and spectrum allocation tables that dictate diode bandwidth and linearity requirements. Military procurement through the US DoD's Trusted Foundry Program and EU EDIDP creates bifurcated qualification paths that fragment vendor addressable markets. Stakeholders must monitor ongoing 3GPP Release 18 specifications for 5G-Advanced and corresponding national spectrum auctions to anticipate frequency band migrations that will obsolete incumbent diode architectures.
Market Dynamics
Defense electronics procurement across NATO allies is pivoting toward higher-frequency systems above 40 GHz, forcing diode suppliers to requalify manufacturing lines for mmWave performance bands and thermal specifications.
Growth Catalysts
- 5G mmWave spectrum reallocation:The FCC's auction of 24–47 GHz bands creates immediate demand for Schottky diodes with sub-picosecond switching speeds in base station transceivers.
- GaN-on-SiC substrate maturation:Epitaxial foundries in Germany's RF manufacturing corridor around Munich now supply defense-grade PIN diodes with junction temperatures exceeding 200°C.
- Automotive radar mandate expansion:EU vehicle safety regulations are accelerating AEC-Q100-qualified Schottky deployments in 77–81 GHz collision-avoidance systems.
Market Restraints
- Silicon carbide substrate scarcity:Limited 6-inch SiC wafer supply from Wolfspeed and Coherent concentrates high-reliability diode sourcing through single-source epitaxy partnerships.
- ITU-R spectrum harmonization delays:Fragmented national allocations for 5G-Advanced above 52 GHz force redundant SKU development for multi-market certification.
- GaN HEMT substitution in switching:Solid-state power amplifiers are displacing PIN diode limiters in certain radar front-end architectures above X-band frequencies.
Strategic Opportunities
- India's defense indigenization:The country's PLI scheme for electronic components offers tariff advantages for diode suppliers establishing local packaging and test facilities.
- 3GPP Release 18 integration:Convergence of 5G-Advanced timing synchronization requirements with satellite NTN standards creates demand for ultra-low-phase-noise varactor diodes.
- Direct OEM contracting:Tier-1 defense primes are bypassing distributors for PIN diode procurement, enabling captive design-in relationships with foundry partners.
Industry Challenges
- Compound semiconductor talent scarcity:Foundry engineers with GaN epitaxy expertise command premium compensation, constraining capacity expansion timelines.
- DoD Trusted Foundry Program compliance:Dual-source requirements for defense-grade components necessitate redundant qualification investments across geographically separated facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | RF and Microwave Diodes Market |
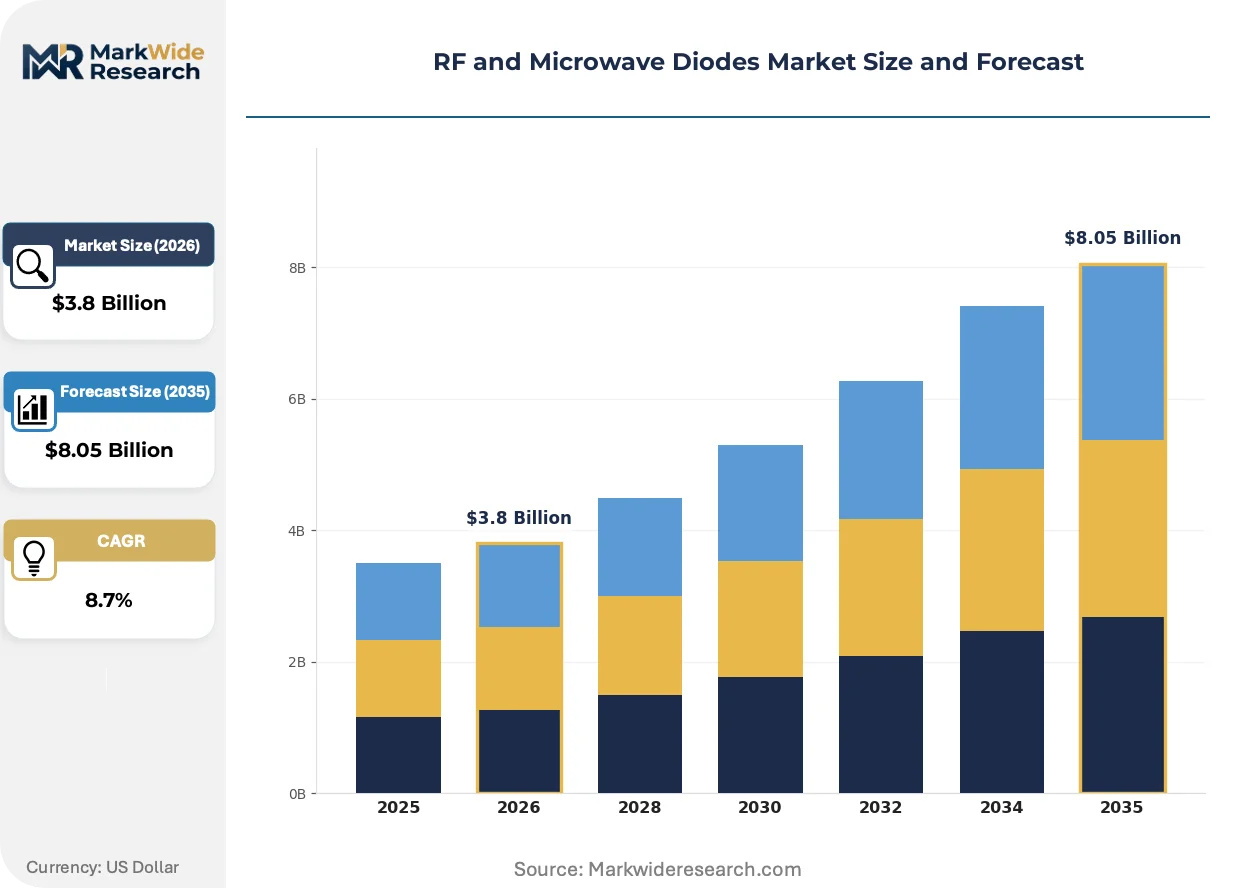
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Schottky Diodes, PIN Diodes, Varactor Diodes, Tunnel Diodes End User: Aerospace, Telecommunications, Consumer Electronics, Industrial Electronics Application: Power Amplifiers, Frequency Multipliers, Signal Mixing, Modulation Technology: Gallium Nitride, Silicon, Silicon Carbide, GaAs |
| Companies Covered | NXP Semiconductors, Qorvo, Skyworks Solutions, Vishay Intertechnology, Toshiba Electronic Devices, Infineon Technologies, Microchip Technology, STMicroelectronics, MACOM Technology Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
RF and Microwave Diodes Market Evolving Landscape
GaN-on-SiC heterointegration is compressing the traditional technology segmentation between power and RF diodes, enabling single-chip solutions that previously required discrete component stacking.
Monolithic integration of Schottky diodes with GaN HEMT power amplifiers is unifying the transmit-receive switch function in 5G massive MIMO arrays. Base station OEMs including Ericsson and Nokia are adopting these combined modules for 28 GHz and 39 GHz deployments. This unification is collapsing the historical separation between diode suppliers and compound semiconductor foundries, forcing joint process development agreements.
ETSI's harmonized standards for 5G-Advanced spectrum above 52 GHz are mandating tighter spurious emission masks that exceed legacy diode linearity specifications. Component vendors must redesign junction geometries and metalization stacks to meet the new limits. European automotive radar suppliers are most affected, as they simultaneously pursue ETSI compliance and AEC-Q100 qualification within compressed development cycles.
Defense procurement offices are consolidating vendor lists around pre-qualified dual-source arrangements, replacing fragmented spot-buying with multi-year framework agreements. This concentration is squeezing mid-tier diode suppliers without Trusted Foundry accreditation. The shift is most visible in US Navy and Air Force programs, where program managers now prioritize supply security over unit cost in source selection criteria.
RF and Microwave Diodes Market Segmentation
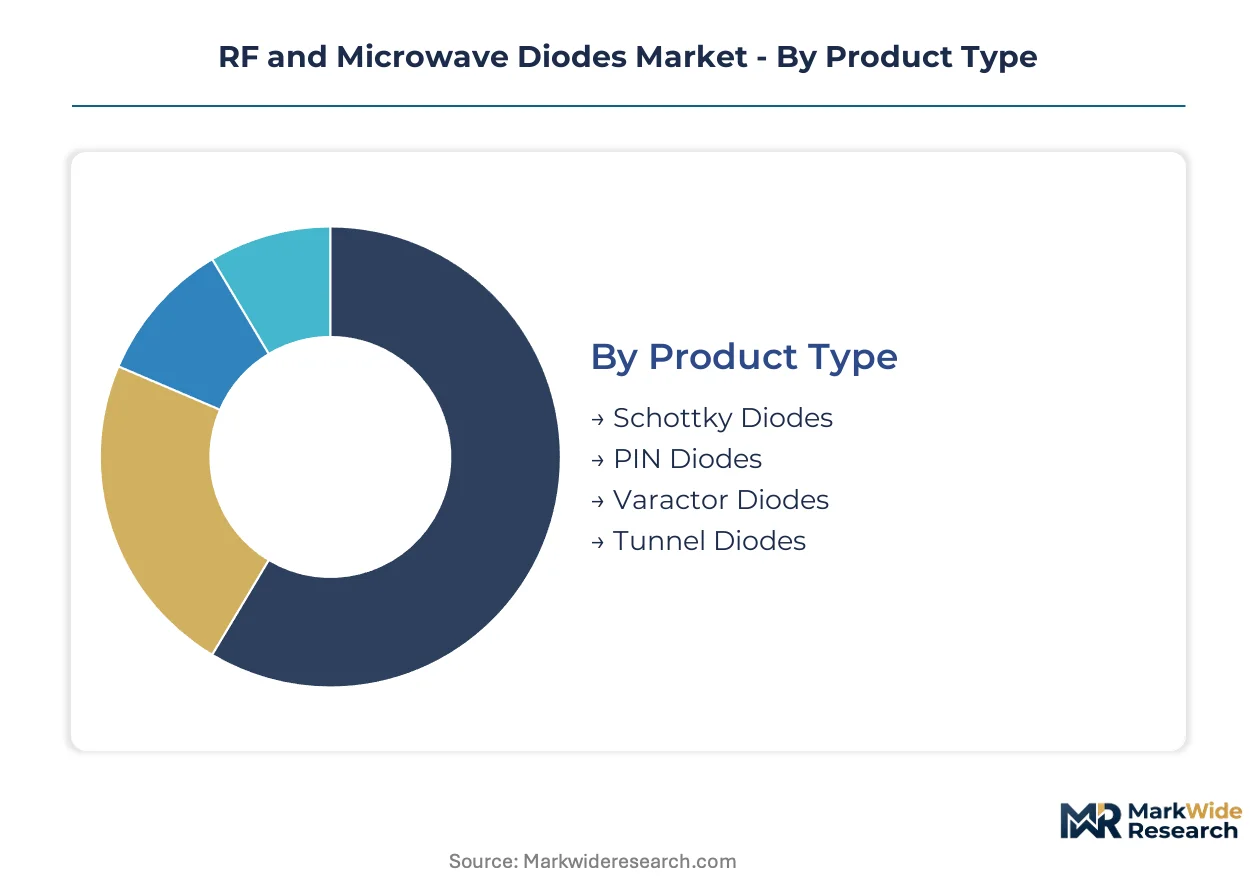
RF and microwave diode architectures diverge sharply across frequency bands, power handling, and substrate technologies. Segmentation clarity enables suppliers to align foundry investments with specific certification requirements and end-use qualification pathways.
Product Type:
Capital intensity peaks in PIN diode manufacturing, where thick intrinsic region epitaxy demands specialized reactor configurations and extended growth cycles.
- Schottky Diodes:Metal-semiconductor junctions eliminate minority-carrier storage, enabling cutoff frequencies above 1 THz. Demand concentrates in 5G base station transceivers across Germany's Munich-Nuremberg manufacturing corridor, driven by FCC mmWave spectrum reallocation mandates.
- PIN Diodes:Thick intrinsic regions with controlled carrier lifetime dominate high-power switching above 100W. NATO defense electronics procurement above 40 GHz absorbs premium-qualified units from Trusted Foundry Program-accredited suppliers.
- Varactor Diodes:Voltage-variable capacitance supports voltage-controlled oscillators in satellite communication payloads.
- Tunnel Diodes:Quantum tunneling enables negative resistance oscillators in specialized radar front-end applications.
Most installed capacity flows through PIN Diodes. Expansion is steepest in Schottky variants.
End User:
Customer qualification timelines stretch longest in aerospace programs, where radiation hardness testing and thermal cycling protocols extend design-in cycles.
- Aerospace:Satellite payloads and radar systems require junction temperature tolerance above 200°C. US DoD programs through the Trusted Foundry Program concentrate sourcing among dual-qualified suppliers.
- Telecommunications:5G massive MIMO arrays at 28 GHz and 39 GHz absorb high-volume Schottky and GaN-integrated modules. Ericsson and Nokia deployment schedules shape foundry capacity allocation.
- Consumer Electronics:Wi-Fi 6E and 7 front-end modules drive cost-optimized silicon Schottky demand.
- Industrial Electronics:RF heating and plasma processing equipment requires robust thermal management in continuous-operation environments.
Aerospace commands the highest unit margins. Telecommunications generates the steepest volume expansion trajectory.
Application:
Power amplifier integration demands the most complex co-design between diode suppliers and compound semiconductor foundries.
- Power Amplifiers:Monolithic GaN HEMT-diode integration unifies transmit-receive switching in 5G arrays. Base station OEMs in Germany's RF corridor drive joint process development agreements.
- Frequency Multipliers:Nonlinear harmonic generation for mmWave signal chains requires precise doping control in varactor and Schottky architectures.
- Signal Mixing:Diode ring and single-balanced configurations enable frequency translation in radar and communication receivers.
- Modulation:Amplitude and phase modulation circuits in satellite ground stations demand linearity specifications exceeding ETSI spurious emission masks.
Power Amplifiers anchor the largest revenue share. Frequency Multipliers are climbing the fastest as 5G-Advanced extends above 52 GHz.
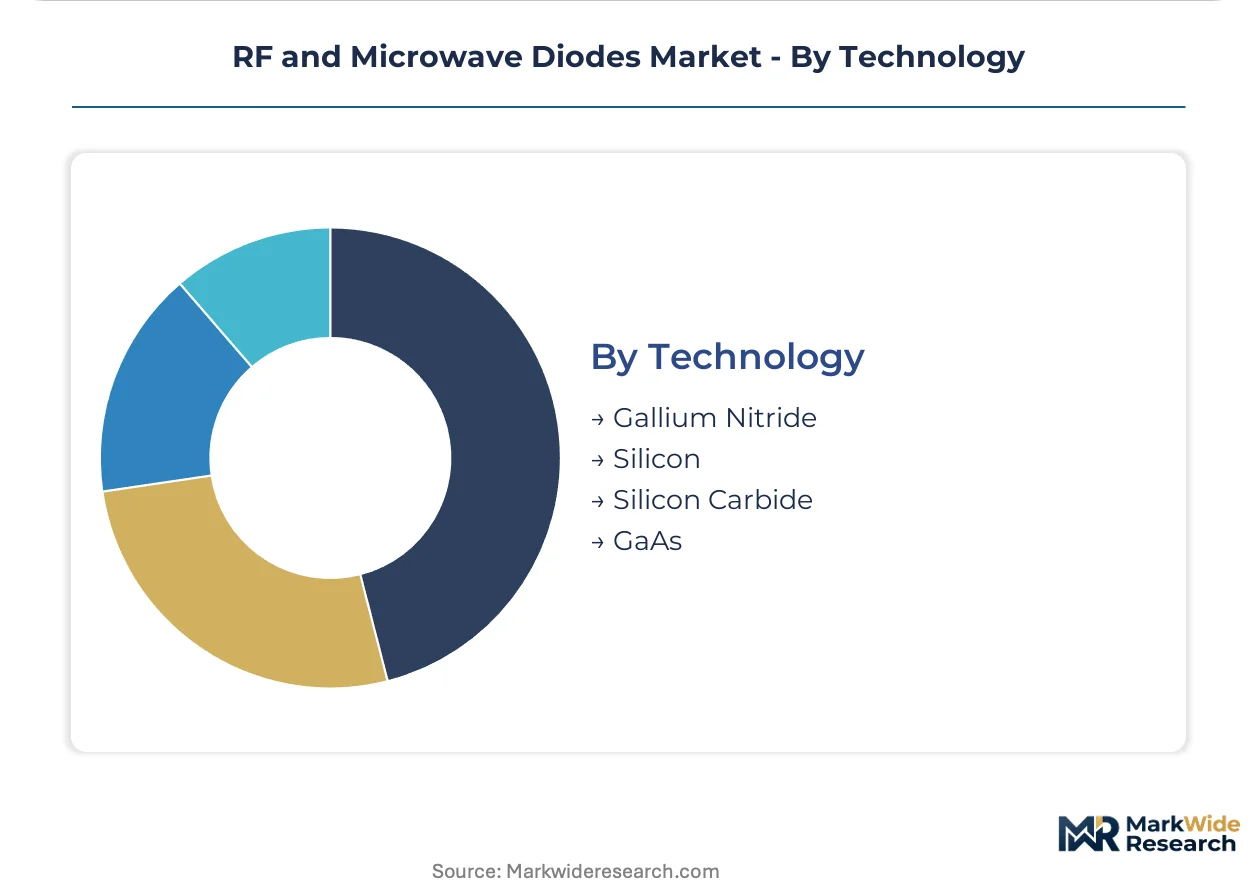
Technology:
Substrate material selection determines thermal budget, frequency ceiling, and radiation hardness trade-offs.
- Gallium Nitride:GaN-on-SiC heterointegration compresses traditional segmentation between power and RF functions. Defense-grade epitaxy from Munich-area foundries supplies NATO programs with junction temperatures exceeding 200°C.
- Silicon Carbide:6-inch wafer scarcity from Wolfspeed and Coherent concentrates high-reliability sourcing through single-source partnerships. Aerospace and defense programs absorb premium unit costs.
- Silicon:Mature CMOS-compatible processes serve cost-sensitive consumer and industrial applications below 6 GHz.
- GaAs:Established millimeter-wave performance in legacy defense and satellite systems, though GaN substitution accelerates above X-band.
Silicon retains the broadest installed base. Gallium Nitride shows the steepest capacity expansion as base station OEMs prioritize efficiency above 6 GHz.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Compound semiconductor process engineers cluster around Munich and Nuremberg, anchoring Europe's densest RF diode fabrication corridor. Defense procurement offices in Arlington and Tokyo compete for qualified GaN epitaxy talent. Bangalore's packaging specialists service both automotive radar and telecom infrastructure demand.
United States
The DoD's Trusted Foundry Program concentrates defense-grade PIN diode sourcing among dual-qualified suppliers. FCC spectrum reallocation for 5G mmWave bands above 24 GHz forces new compliance investments in thermal management specifications. Foundry partnerships in the Southwest anchor GaN-on-SiC capacity for X-band radar programs.
Germany
Automotive radar mandates from EU vehicle safety regulations accelerate AEC-Q100-qualified Schottky deployments in 77–81 GHz collision-avoidance systems. ETSI harmonized standards for 5G-Advanced above 52 GHz mandate tighter spurious emission masks exceeding legacy diode linearity specifications. The Munich-Nuremberg corridor supplies NATO defense programs with junction temperatures exceeding 200°C.
Japan
METI industrial policy supports domestic GaN epitaxy capacity for satellite communication payloads and base station transceivers. National spectrum auctions for 5G-Advanced bands align with 3GPP Release 18 timing synchronization requirements. Kyushu-based foundries specialize in high-reliability varactor diodes for phased array antennas.
China
MIIT spectrum allocation tables dictate diode bandwidth requirements for domestic 5G massive MIMO deployments at 28 GHz and 39 GHz. GB standards for automotive electronics push local Schottky qualification for 77 GHz radar modules. Yangtze River Delta packaging houses scale cost-optimized silicon variants for consumer Wi-Fi front-ends.
India
The PLI scheme for electronic components offers tariff advantages for diode suppliers establishing local packaging and test facilities. TRAI spectrum recommendations for 5G mmWave guide component certification roadmaps. Karnataka's defense electronics cluster absorbs indigenization requirements for radar limiters and switching modules.
RF and Microwave Diodes Market Competitive Landscape
The competitive structure tilts toward integrated device manufacturers with captive epitaxy capabilities. Vendor concentration intensifies around defense accreditation and automotive qualification gateways. Two archetypes dominate: compound semiconductor foundries with GaN-on-SiC heterointegration expertise, and diversified analog specialists leveraging CMOS-compatible silicon processes. Capacity expansion and strategic partnerships with base station OEMs constitute the primary competitive vectors.
Within the defense-accredited tier, NXP Semiconductors and Qorvo occupy positions shaped by Trusted Foundry Program requirements and NATO procurement specifications. Infineon Technologies exemplifies the automotive-qualified archetype, leveraging AEC-Q100 certification to secure radar socket dominance. These three anchors represent distinct strategic postures: foundry partnership reliance, in-house epitaxy control, and tier-1 OEM direct contracting relationships.
| Leading Market Players |
|---|
| NXP Semiconductors |
| Qorvo |
| Skyworks Solutions |
| Vishay Intertechnology |
| Toshiba Electronic Devices |
| Infineon Technologies |
| Microchip Technology |
| STMicroelectronics |
| MACOM Technology Solutions |
| Others |
Value Network & Pricing Analysis
NATO defense electronics procurement above 40 GHz forces diode suppliers to requalify manufacturing lines for mmWave performance bands, compressing margins on legacy silicon products while concentrating pricing power among Trusted Foundry Program-accredited vendors with captive GaN-on-SiC epitaxy.
Pricing Analysis
Bundled qualification-plus-volume contracts dominate defense procurement, while unbundled spot purchasing persists in automotive radar. Three-tier pricing structure across Trusted Foundry-certified, AEC-Q100-qualified, and commercial-grade tiers reflects certification investment recovery timelines. Cost compression in commercial silicon Schottky variants is intensifying because Yangtze River Delta packaging houses scale capacity for Wi-Fi front-ends. Automotive OEMs exhibit the highest price sensitivity due to AEC-Q100 qualification cost amortization pressures, while aerospace primes accept premium unit costs for radiation-hardened specifications.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale base station demand from Ericsson and Nokia, while distributor networks service fragmented industrial and consumer electronics buyers. Epitaxial wafer supply concentrates in Germany's Munich-Nuremberg corridor, the US Southwest, and Japan's Kyushu region. High-reliability diode manufacturing draws from 6-inch silicon carbide substrates, gallium nitride epitaxy services, and precious metal metallization stacks. Single-source vulnerability runs through Wolfspeed and Coherent SiC wafer allocations, where defense and aerospace programs compete for limited qualified supply.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where FCC spectrum reallocation for 5G mmWave bands above 24 GHz and ETSI harmonization for 5G-Advanced above 52 GHz continuously reset component certification requirements and foundry investment thresholds.
For Market Incumbents: Anticipate GaN HEMT substitution in radar limiters above X-band by deepening captive epitaxy partnerships in Germany's RF manufacturing corridor. Prioritize dual-source qualification investments across geographically separated Trusted Foundry Program facilities to defend defense procurement sockets against supply security audits. Accelerate AEC-Q100 certification roadmaps for 77–81 GHz automotive radar variants before EU vehicle safety mandate deadlines compress design-in windows. For New Entrants and Emerging Players: Capture India's PLI scheme tariff advantages by establishing local packaging and test facilities for defense radar limiters and switching modules. Karnataka's defense electronics cluster offers the most penetrable white-space for indigenization requirements, with TRAI spectrum recommendations providing component certification clarity. Pursue direct contracting relationships with Tier-1 defense primes bypassing distributor markups. For Investors and Strategic Acquirers: Asymmetric upside sits with compound semiconductor foundries possessing GaN-on-SiC heterointegration expertise and existing Trusted Foundry Program accreditation. Long-term viability hinges on 5G-Advanced and satellite NTN convergence timelines rather than cyclical defense spending. Watch 3GPP Release 18 timing synchronization specification finalization as the inflection indicator for ultra-low-phase-noise varactor diode demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Trusted Foundry Dual-Source Qualification | Meets US DoD supply security mandates for PIN diode procurement in NATO radar programs. |
| GaN-on-SiC Epitaxy Capacity Expansion | Supports junction temperatures exceeding 200°C for defense-grade switching applications. |
| AEC-Q100 Certification Investment | Unlocks 77–81 GHz automotive radar sockets under EU vehicle safety regulations. |
| Direct OEM Contracting Transition | Bypasses distributor markups in Tier-1 defense prime procurement consolidation. |
| India PLI Localization Buildout | Captures tariff advantages for packaging and test facilities in Karnataka's defense cluster. |
Research Methodology
Direct dialogue with RF component procurement managers at base station OEMs, defense electronics program officers, automotive radar system architects, compound semiconductor foundry engineers, and semiconductor distribution channel heads grounded the qualitative assessment. Secondary validation drew from FCC spectrum auction records, ETSI harmonized standards documentation, 3GPP Release 18 technical specifications, US DoD Trusted Foundry Program accreditation lists, and AEC-Q100 qualification databases. Bottom-up and top-down triangulation cross-checked foundry capacity announcements against OEM deployment schedules and defense procurement award notices.
Bottom-up modeling aggregated segment-level unit economics across Schottky, PIN, varactor, and tunnel diode architectures, while top-down verification tested aggregate market scale against compound semiconductor industry revenue disclosures. Segmentation dimensions spanned product type, end user qualification tier, application function, and substrate technology across the projection horizon. CAGRs derived from foundry capacity expansion timelines, spectrum auction completion dates, and automotive safety regulation implementation schedules. Forecast inputs included GaN epitaxy reactor installation counts, 6-inch SiC wafer supply allocations, and defense electronics procurement budget trajectories.
Spectrum harmonization delays above 52 GHz, GaN HEMT substitution acceleration in radar front-ends, and silicon carbide substrate supply disruption are the dominant revision risks to modeled outcomes. Forecasts embed assumptions regarding 3GPP specification finalization timing and Trusted Foundry Program accreditation continuity. Periodic stress-testing of base assumptions against foundry utilization rates and defense procurement award flows is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
RF Components
Radio Frequency Components Market
RF Components
5G Millimeter Wave RF Transceiver Market
RF Components
High Power RF Amplifier Module Market
RF Components
Radio Frequency Integrated Circuit (RFIC) Market
RF Components
RF Over Fiber (Rfof) Market
RF Components
433MHz Active RFID Reader Market
RF Components
Global Bulk Acoustic Wave (BAW) Filters Market
RF Components
Radio Frequency Duplexer Market
RF Components
Coaxial Splitters Market
RF Components
RF Gan Market
RF Components
Multiband Booster Market
RF Components
5G Gain Block Amplifier Market
RF Components
RF Isolator Market
RF Components
Global Ceramic Dielectric Filters Market
RF Components
US RFID Tags Market
RF Components
Latin America RFID Tags Market