
 Array Instruments Market | 2026-2036
Array Instruments Market Size, Share, and Industry Trends Forecast 2026-2036
Array Instruments Market Intelligence
China's Jiangsu province is fragmenting as new domestic entrants challenge incumbent array instrument suppliers. Thermo Fisher Scientific Inc. leverages its vertically integrated reagent-instrument ecosystem to sustain pricing power in high-complexity diagnostics. Agilent Technologies Inc. anchors its position through precision microarray manufacturing platforms that serve both research and clinical workflows. Illumina Inc. competes by specializing in next-generation sequencing-adjacent array technologies for genotyping applications.
Array instruments comprise integrated systems of multiplexed sensors—optical, electrical, temperature, and pressure elements—fabricated on planar substrates with feature resolutions below 100 micrometers, designed to capture spatially resolved data from biological, chemical, or physical samples. Their primary purpose spans industrial process control, environmental surveillance, and clinical diagnostic screening where parallel measurement throughput reduces per-sample cost and turnaround time. Optical sensors dominate current revenue pools due to mature fluorescence detection architectures, while MEMS-based arrays represent the fastest-expanding technology segment as semiconductor foundries apply wafer-scale fabrication economies to sensor miniaturization. Medical diagnostics applications command premium pricing relative to agricultural monitoring, reflecting stringent validation requirements and reimbursement dynamics.
FDA 510(k) pathways and the EU Medical Device Regulation shape product development timelines and clinical validation burdens for diagnostic array platforms seeking market access. China's NMPA implements GB standards for in-vitro diagnostic instruments that diverge from ISO 13485 harmonization, creating parallel compliance obligations for multinational suppliers. ISO 15189 laboratory accreditation requirements in Japan's clinical reference centers further filter eligible instrument vendors. Stakeholders must monitor regulatory divergence across FDA, EMA, and NMPA jurisdictions as a primary determinant of product portfolio prioritization and geographic launch sequencing.
Market Dynamics
Semiconductor foundries are transferring wafer-scale fabrication economies to MEMS sensor arrays, compressing unit costs for industrial automation buyers while fragmenting incumbent supplier margins in China's eastern manufacturing corridor.
Growth Catalysts
- EU Medical Device Regulation:Pharmaceutical laboratories in Germany are expanding procurement of multiplexed diagnostic platforms, creating validated demand pools for clinical-grade array instruments with traceable quality management systems.
- MEMS miniaturization:Domestic sensor producers in Jiangsu province are scaling planar substrate fabrication below 100 micrometers, enabling parallel measurement throughput that reduces per-sample operational cost for environmental surveillance networks.
- Optical fluorescence architectures:Mature detection systems dominate current revenue pools, with research and clinical workflows sustaining replacement cycles through incremental sensitivity improvements and reagent compatibility expansions.
Market Restraints
- Regulatory divergence:China's NMPA implements GB standards for in-vitro diagnostic instruments that diverge from ISO 13485 harmonization, forcing multinational suppliers to maintain parallel compliance documentation and quality management systems.
- Input concentration:Specialized planar substrate materials and precision photolithography equipment concentrate among a limited set of semiconductor foundry suppliers, exposing array instrument manufacturers to capacity allocation risk during demand surges.
- Substitution pressure:Next-generation sequencing platforms are encroaching on genotyping applications previously served by microarray technologies, compressing addressable market scope for sequencing-adjacent array products.
Strategic Opportunities
- Agricultural monitoring:Environmental surveillance applications currently command lower pricing than medical diagnostics, creating expansion potential for validated array platforms in soil chemistry and crop pathogen detection where regulatory burdens remain lighter.
- Technology convergence:Integration of electrical and temperature sensing elements with established optical arrays is enabling multi-modal data capture from single biological samples, differentiating platform offerings in high-complexity reference laboratories.
- Distribution innovation:Direct procurement relationships between domestic Chinese sensor producers and industrial automation buyers are bypassing traditional distributor channels, compressing margin capture for intermediaries while accelerating volume scale.
Industry Challenges
- Skill scarcity:Cross-functional expertise spanning semiconductor fabrication, biological assay development, and clinical validation protocols remains concentrated among specialized practitioners, constraining workforce expansion for platform developers.
- Certification timelines:FDA 510(k) pathways and parallel EMA technical documentation requirements extend product development cycles for diagnostic array platforms, delaying revenue recognition and increasing pre-market capital consumption.
- Legacy integration:Reference laboratories in Japan's ISO 15189-accredited centers require backward compatibility with existing laboratory information management systems, complicating instrument replacement decisions and elongating sales cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Array Instruments Market |
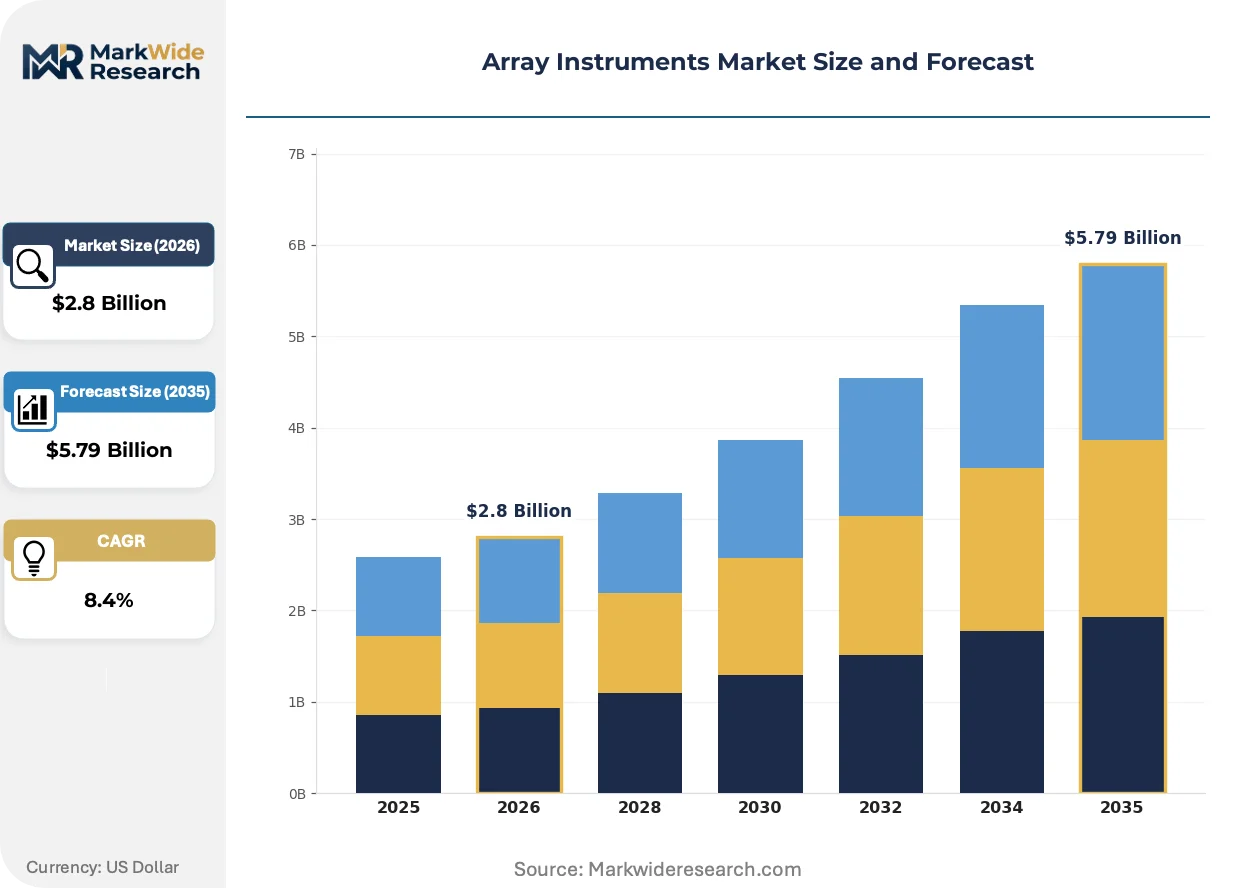
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.79 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Optical Sensors, Electrical Sensors, Temperature Probes, Pressure Sensors Application: Industrial Automation, Environmental Monitoring, Medical Diagnostics, Agricultural Practices End User: Manufacturers, Laboratories, Research Institutions, Healthcare Providers Technology: Digital Signal Processing, Wireless Communication, Analog Interfaces, MEMS |
| Companies Covered | Thermo Fisher Scientific Inc., Agilent Technologies Inc., Illumina Inc., QIAGEN, PerkinElmer Inc., Bio-RAD Laboratories Inc., Arrayit Corporation, Laboratory Corporation of America Holdings, Molecular Devices LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Array Instruments Market Strategic Shifts & Innovations
Digital twin architectures and cloud-native instrument control systems are virtualizing hardware functionality, enabling remote diagnostic calibration and predictive maintenance that reshapes service delivery economics for distributed instrument fleets.
Computational readout platforms are virtualizing traditional optical detection hardware by replacing dedicated fluorescence scanners with software-defined signal processing. Pharmaceutical laboratories in high-throughput screening operations are adopting these architectures fastest, drawn by reduced capital intensity and flexible assay reconfiguration. This virtualization is compressing the addressable market for standalone optical instruments while expanding recurring software revenue pools.
REACH substance restrictions and RoHS hazardous material limitations are tightening supply chain qualification requirements for planar substrate materials and sensor coatings used in European-deployed instruments. Manufacturers are reformulating material compositions and requalifying supplier bases to maintain CE marking eligibility. Clinical diagnostic platforms with extended validation timelines face the steepest compliance cost absorption.
Buying committees at consolidated hospital networks are unbundling after-sales service contracts from instrument procurement, negotiating direct relationships with third-party maintenance providers or building in-house technical capabilities. This disintermediation is visible most acutely in Germany's laboratory sector, where EU Medical Device Regulation technical documentation requirements have equipped buyers with sufficient regulatory literacy to evaluate non-OEM service alternatives.
Array Instruments Market Segmentation
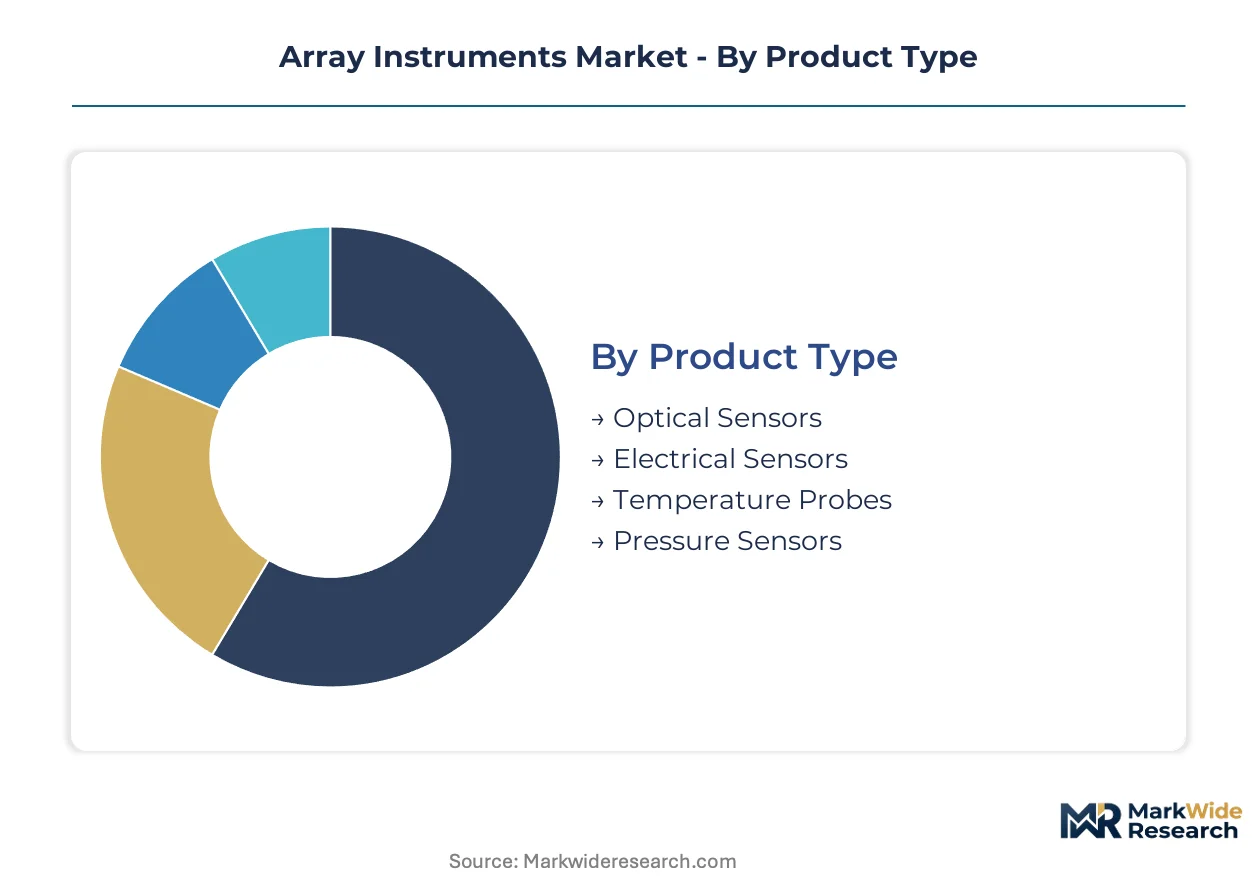
Array instrument segmentation reveals divergent service intensity and margin profiles across product architectures and buyer categories. Procurement patterns in Germany's pharmaceutical laboratories differ sharply from Jiangsu province's industrial automation corridors, shaping how suppliers configure aftermarket support and calibration protocols.
Product Type:
After-sales service intensity varies substantially across sensor modalities, with optical platforms requiring frequent recalibration and MEMS arrays demanding minimal field intervention.
- Optical Sensors:Fluorescence detection architectures integrate photomultiplier tubes and laser excitation sources with planar substrates below 100 micrometers. Demand concentrates in Germany's pharmaceutical laboratories where EU Medical Device Regulation traceability requirements mandate quarterly calibration cycles and certified service engineer visits.
- Electrical Sensors:Impedance and potentiometric arrays capture ionic concentration changes through microfabricated electrode geometries. China's eastern manufacturing corridor absorbs volume production as domestic buyers prioritize capital efficiency over premium service bundling.
- Temperature Probes:Thermocouple and resistance-based arrays serve process control applications with standardized replacement protocols.
- Pressure Sensors:Piezoresistive and capacitive microstructures monitor fluid dynamics in environmental surveillance networks.
Optical sensors hold the largest share; momentum sits with pressure sensors as semiconductor foundries transfer wafer-scale fabrication economies.
Application:
Cost tier stratification separates premium-validated clinical platforms from lighter-regulated environmental deployments, with pricing spreads exceeding threefold between medical diagnostics and agricultural monitoring.
- Medical Diagnostics:Multiplexed diagnostic platforms face FDA 510(k) and EU MDR validation burdens that extend development timelines and sustain premium pricing through reimbursement dynamics. Germany's hospital networks unbundle service contracts to negotiate directly with third-party maintenance providers.
- Industrial Automation:MEMS-based sensor arrays for process control command lower unit margins but accelerate volume scale through Jiangsu province's direct procurement relationships between domestic producers and manufacturing buyers.
- Environmental Monitoring:Soil chemistry and atmospheric sensing arrays face lighter regulatory burdens than clinical applications.
- Agricultural Practices:Crop pathogen detection and nutrient mapping platforms serve price-sensitive farming cooperatives with simplified validation requirements.
Medical diagnostics commands premium pricing; environmental monitoring is expanding most quickly as regulatory burdens remain lighter than clinical alternatives.
End User:
Customer type determines procurement sophistication, with consolidated hospital networks leveraging regulatory literacy to disintermediate traditional distributors while research institutions prioritize reagent compatibility over capital cost.
- Healthcare Providers:Consolidated hospital networks in Germany negotiate unbundled procurement of instruments and aftermarket services, using EU MDR technical documentation requirements to evaluate non-OEM alternatives. ISO 15189-accredited reference laboratories in Japan demand backward compatibility with legacy laboratory information management systems.
- Research Institutions:Academic and government laboratories prioritize optical fluorescence platforms with broad reagent compatibility and incremental sensitivity improvements over replacement cycles.
- Laboratories:Clinical and environmental testing facilities balance throughput requirements against per-sample operational cost targets.
- Manufacturers:Industrial automation buyers in China's eastern corridor scale MEMS fabrication through direct relationships with domestic sensor producers, bypassing distributor markups.
Healthcare providers represent the most demanding service segment; manufacturers are gaining share fastest through direct procurement channel compression.
Technology:
Maturity gradients separate established analog architectures from emerging computational readout platforms that virtualize traditional hardware functionality.
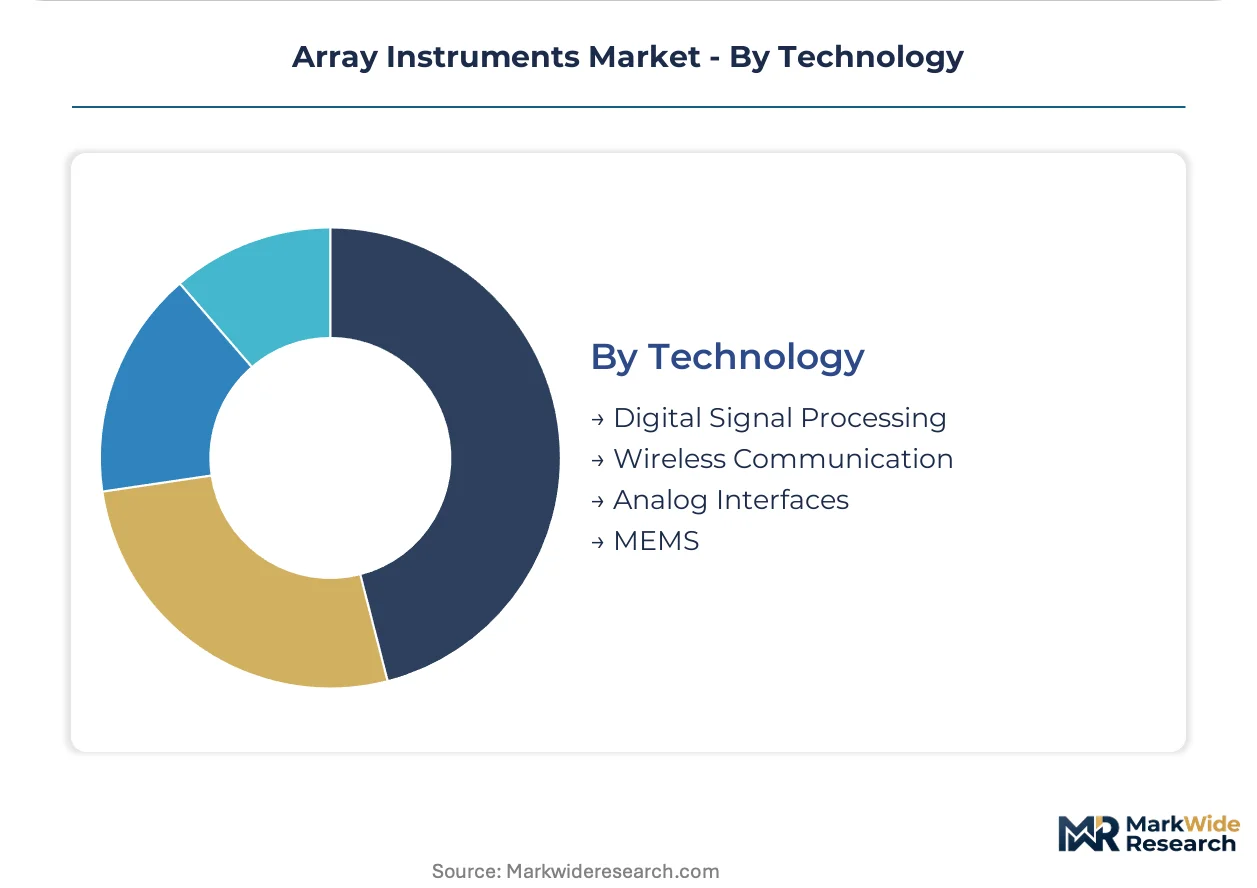
- MEMS:Microelectromechanical systems fabricated through semiconductor foundry processes enable sub-100 micrometer feature resolutions with wafer-scale cost compression. China's Jiangsu province scales planar substrate production for industrial automation buyers seeking parallel measurement throughput.
- Digital Signal Processing:Software-defined architectures replace dedicated fluorescence scanners with computational readout, reducing capital intensity for pharmaceutical laboratories in high-throughput screening operations while expanding recurring software revenue pools.
- Wireless Communication:LoRa and cellular-enabled arrays support distributed environmental surveillance networks with remote data transmission.
- Analog Interfaces:Traditional voltage and current output architectures persist in legacy industrial control systems requiring minimal reconfiguration.
Analog interfaces retain installed base dominance; digital signal processing is climbing the fastest as virtualization compresses standalone optical instrument addressable markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Semiconductor foundries in China and precision manufacturing clusters in Germany concentrate supply capacity for planar substrate fabrication. Domestic sensor producers in Jiangsu province scale MEMS arrays through wafer-scale economies. Pharmaceutical laboratories in Germany and industrial automation buyers in China's eastern corridor anchor differentiated demand pools.
United States
FDA 510(k) pathways shape product development timelines for diagnostic array platforms seeking market access. Pharmaceutical laboratories in high-throughput screening operations adopt computational readout architectures fastest. Greater Boston and San Diego biotech corridors concentrate demand for multiplexed genotyping applications.
Germany
EU Medical Device Regulation mandates traceable quality management systems for clinical-grade instruments. Pharmaceutical laboratories expand procurement of multiplexed diagnostic platforms with validated compliance documentation. Baden-Württemberg's precision engineering cluster supplies planar substrate materials to instrument manufacturers.
China
NMPA implements GB standards for in-vitro diagnostic instruments that diverge from ISO 13485 harmonization. Domestic sensor producers in Jiangsu province scale MEMS fabrication below 100 micrometers for industrial automation buyers. Yangtze River Delta manufacturing corridors absorb volume production through direct procurement relationships.
Japan
ISO 15189 laboratory accreditation requirements filter eligible instrument vendors for clinical reference centers. METI standards govern semiconductor fabrication equipment imports supporting domestic MEMS production. Kanto region's reference laboratories demand backward compatibility with legacy laboratory information management systems.
South Korea
MFDS regulates in-vitro diagnostic instruments with technical documentation requirements extending validation timelines. Seoul Capital Area hosts consolidated hospital networks negotiating unbundled instrument and service procurement. Domestic semiconductor foundries transfer wafer-scale fabrication economies to pressure sensor arrays for process control.
Array Instruments Market Key Industry Players
Vertically integrated life science conglomerates and specialized microarray fabricators split the market between reagent-instrument ecosystems and precision manufacturing platforms. Thermo Fisher Scientific Inc. anchors the first archetype through captive supply chains spanning reagents, instruments, and consumables. Agilent Technologies Inc. and Illumina Inc. occupy the second archetype, specializing in precision microarray manufacturing and sequencing-adjacent genotyping technologies respectively. Competitive moves concentrate on backward integration into planar substrate materials and geographic expansion through distributor bypass in China's eastern manufacturing corridor.
Within the vertically integrated tier, Thermo Fisher Scientific Inc. exemplifies the reagent-instrument ecosystem model. Agilent Technologies Inc. and Illumina Inc. represent specialized precision manufacturing, with the former serving research and clinical workflows and the latter focusing on next-generation sequencing-adjacent applications. QIAGEN occupies a position bridging sample preparation technologies with downstream array detection. These three companies collectively illustrate how supplier power concentrates among entities controlling either end-to-end workflows or不可替代 fabrication capabilities.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc. |
| Agilent Technologies Inc. |
| Illumina Inc. |
| QIAGEN |
| PerkinElmer Inc. |
| Bio-RAD Laboratories Inc. |
| Arrayit Corporation |
| Laboratory Corporation of America Holdings |
| Molecular Devices LLC |
| Others |
Cost & Logistics Intelligence
Single-source dependency on precision photolithography equipment determines both pricing tier spreads and supply chain shape in the array instruments market. Specialized planar substrate materials concentrate among limited semiconductor foundry suppliers, exposing manufacturers to capacity allocation risk that compresses margins in industrial automation tiers while sustaining premiums in clinical diagnostics.
Pricing Analysis
EU Medical Device Regulation dictates the pricing tier structure across the array instruments landscape. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated clinical platforms with traceable quality management systems from lighter-regulated environmental monitoring arrays and commodity industrial sensors. Price differentiation stems from certification grade and after-sales service bundling, with quarterly calibration cycles mandated for EU MDR compliance adding substantial service revenue to premium tiers. Cost compression in MEMS-based industrial segments is intensifying because domestic Chinese producers scale wafer-scale fabrication and bypass distributor markups through direct procurement relationships. Industrial automation buyers in Jiangsu province exhibit highest price sensitivity, while Germany's consolidated hospital networks demonstrate lowest sensitivity due to reimbursement dynamics and unbundled service negotiation sophistication.
Supply Chain Analysis
Export-control regimes restricting semiconductor fabrication equipment flows to Chinese foundries are reshaping geographic supply concentration. Taiwan, South Korea, and Germany anchor planar substrate material production and precision photolithography equipment manufacturing. Supply chains draw from specialized silicon wafers, photoresist coatings, and laser excitation sources as critical inputs. Single-source vulnerability concentrates in photolithography equipment where ASML-class systems face export licensing requirements. Distribution runs through direct procurement relationships between domestic Chinese sensor producers and industrial automation buyers, compressing traditional distributor channels in the eastern manufacturing corridor.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges as computational readout platforms virtualize traditional optical detection hardware, creating niche openings for software-defined architectures alongside established instrument ecosystems. Demand-side shift toward unbundled procurement in consolidated hospital networks fragments service revenue pools and enables new entrant positioning.
For Market Incumbents: Pre-empt substitution pressure from next-generation sequencing platforms by deepening reagent-instrument ecosystem lock-in through expanded assay compatibility menus. Anchor backward integration into planar substrate materials to defend against semiconductor foundry capacity allocation risk. Prioritize certification investment in China's NMPA GB standards compliance to maintain access against domestic entrant challenge. For New Entrants and Emerging Players: Agricultural monitoring in soil chemistry and crop pathogen detection offers the most penetrable white-space target, with lighter regulatory burdens than clinical alternatives and price-sensitive farming cooperatives receptive to validated platforms. Environmental surveillance networks in Southeast Asia present secondary expansion terrain. Pursue direct procurement channel establishment with industrial automation buyers to bypass distributor margin capture. For Investors and Strategic Acquirers: EU Medical Device Regulation reshapes the acquisition landscape by elevating quality management system documentation to strategic asset status. Long-term viability centers on platforms with validated compliance infrastructure spanning FDA, EMA, and NMPA jurisdictions. Target acquisition archetype: specialized microarray fabricators with captive planar substrate capabilities and existing ISO 13485 certification. Signal to watch: distributor bypass acceleration in China's Yangtze River Delta manufacturing corridors as indicator of pricing power erosion for instrument-only business models.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Planar Substrates | Captive supply of sub-100 micrometer feature resolution materials reduces foundry dependency for MEMS arrays. |
| CE Marking Pathway Investment | EU MDR technical documentation capabilities enable premium pricing in Germany's pharmaceutical laboratory procurement. |
| Software Companion Development | Computational readout platforms expand recurring revenue pools while compressing standalone optical instrument addressable markets. |
| Hospital System Partnership | Direct relationships with consolidated networks in Germany leverage regulatory literacy for unbundled service contract capture. |
| NMPA GB Standards Compliance | Parallel quality management systems maintain market access as China's domestic sensor producers scale MEMS fabrication. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with biomedical engineers at ISO 15189-accredited reference laboratories, procurement managers at Germany's consolidated hospital networks, plant engineers in Jiangsu province's industrial automation corridors, regulatory affairs specialists navigating FDA 510(k) pathways, and semiconductor foundry operations directors. Secondary validation drew from FDA 510(k) filings, EMA technical documentation databases, NMPA GB standards publications, and customs records of planar substrate material flows. Bottom-up segment sizing triangulated against top-down macroeconomic anchors.
Calibration across the analysis window employed multi-dimensional segmentation modeling across sensor modality, application regulatory tier, end-user procurement sophistication, and geographic compliance cluster. CAGRs derived from instrument shipment trajectories, replacement cycle analysis, and reagent pull-through ratios. Industry-specific forecast inputs incorporated MEMS fabrication capacity expansion schedules and EU MDR implementation phase-in timelines.
Macroeconomic conditions sit as an overlay; deviation in semiconductor capital expenditure cycles or reimbursement policy shifts in Germany's hospital sector would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory harmonization pace and foundry capacity allocation priorities. Cross-checking against hospital procurement database benchmarks and semiconductor equipment order backlogs is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytical Instruments
Modular Instruments Market
Analytical Instruments
Digital Multichannel Analyzer Market
Analytical Instruments
Asia-Pacific Handheld Spectrum Analyzer Market
Analytical Instruments
Global Nuclear Magnetic Resonance (NMR) Spectrometer Market
Analytical Instruments
Africa Digital Thermometer Market
Analytical Instruments
Gas Analyzer Market
Analytical Instruments
Conductivity Analyzers Market
Analytical Instruments
EPR (ESR) Spectrometer Market
Analytical Instruments
Analytical Balance Market
Analytical Instruments
Illuminometer Market
Analytical Instruments
Portable Gas Chromatograph Market
Analytical Instruments
Digital Vernier Caliper Market
Analytical Instruments
Flame Ionization Detectors Market
Analytical Instruments
Next Generation Mass Spectrometer Market
Analytical Instruments
Visualization Instruments for MIS Market
Analytical Instruments
Handheld Laser Measuring Instrument Market