
 Global RF Plasma Generator Market | 2026-2036
Global RF Plasma Generator Market Size, Share, and Industry Trends Forecast 2026-2036
Global RF Plasma Generator Market Foresight
Multi-source procurement for RF power components is consolidating around a smaller set of qualified suppliers with proven semiconductor track records. Advanced Energy Industries leverages its vertically integrated RF power solutions to sustain design-in relationships across leading foundries. MKS Instruments anchors its position through deep process control integration, while TRUMPF Hüttinger competes on precision matching network expertise for high-frequency etch applications.
An RF plasma generator converts electrical power into radio-frequency energy to ionize process gases and sustain controlled plasma discharges, typically operating at frequencies between 400 kHz and 13.56 MHz with output power ranging from hundreds of watts to tens of kilowatts. These systems enable precise material modification in vacuum environments for semiconductor wafer processing, thin film coating, and surface engineering applications. Capacitively coupled generators dominate volume sales for dielectric etch and deposition chambers, while inductively coupled configurations capture premium pricing in high-density plasma applications requiring superior uniformity. Pulsed plasma technology is gaining fastest adoption for atomic-scale etch control in advanced logic nodes, though continuous wave systems retain margin strength in mature process nodes where throughput optimization matters most.
EPA emissions standards and OSHA workplace exposure limits in the United States compel fabs to upgrade legacy plasma systems with enhanced exhaust handling and real-time effluent monitoring. Europe's REACH regulation and RoHS directives restrict hazardous substances in RF generator components, forcing redesigns of capacitors and cooling systems that shape supplier qualification timelines. Semiconductor fabricators must monitor how China's GB standards and dual carbon goals from MEE reshape local equipment sourcing requirements, as domestic substitution policies accelerate for critical process tools.
Market Dynamics
Pulsed RF plasma technology is compressing process windows for atomic-scale etch control while REACH and EPA emissions mandates force simultaneous hardware upgrades across installed bases.
Growth Catalysts
- Advanced node lithography:Semiconductor fabricators below 7nm require precision matching networks for high-aspect-ratio etch processes. Pyeongtaek's memory foundry cluster anchors procurement volume for these systems.
- REACH substance restrictions:ECHA's evolving candidate list forces redesigns of capacitors and cooling loops, creating replacement cycles for legacy generators in European fabs.
- Dual carbon targets:China's MEE enforcement of GB standards accelerates domestic equipment substitution, pulling local RF generator capacity expansion.
Market Restraints
- High-purity ceramic substrate costs:Alumina and aluminum nitride price volatility compresses margins for capacitively coupled generator manufacturers.
- Core component supplier concentration:Vacuum capacitors and solid-state RF power modules concentrate among Japanese and German component specialists.
- Continuous wave system lock-in:Mature node fabs resist pulsed plasma retrofits due to validated process recipes and requalification costs.
Strategic Opportunities
- Indian semiconductor manufacturing:PLI scheme disbursements for domestic fab construction create first-mover positioning for RF generator qualification programs.
- Compound semiconductor etch:Silicon carbide and gallium nitride power device fabrication requires high-density plasma configurations with premium pricing.
- Real-time effluent monitoring mandates:EPA and OSHA workplace exposure limits force integrated exhaust handling retrofits, expanding attach rates for subsystem suppliers.
Industry Challenges
- Plasma physics modeling expertise:Electromagnetic simulation and process chamber matching require specialized RF engineering talent scarce outside established semiconductor equipment hubs.
- Multi-frequency generator integration:Legacy single-frequency systems resist seamless retrofit with dual-frequency or pulsed architectures without full chamber replacement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global RF Plasma Generator Market |
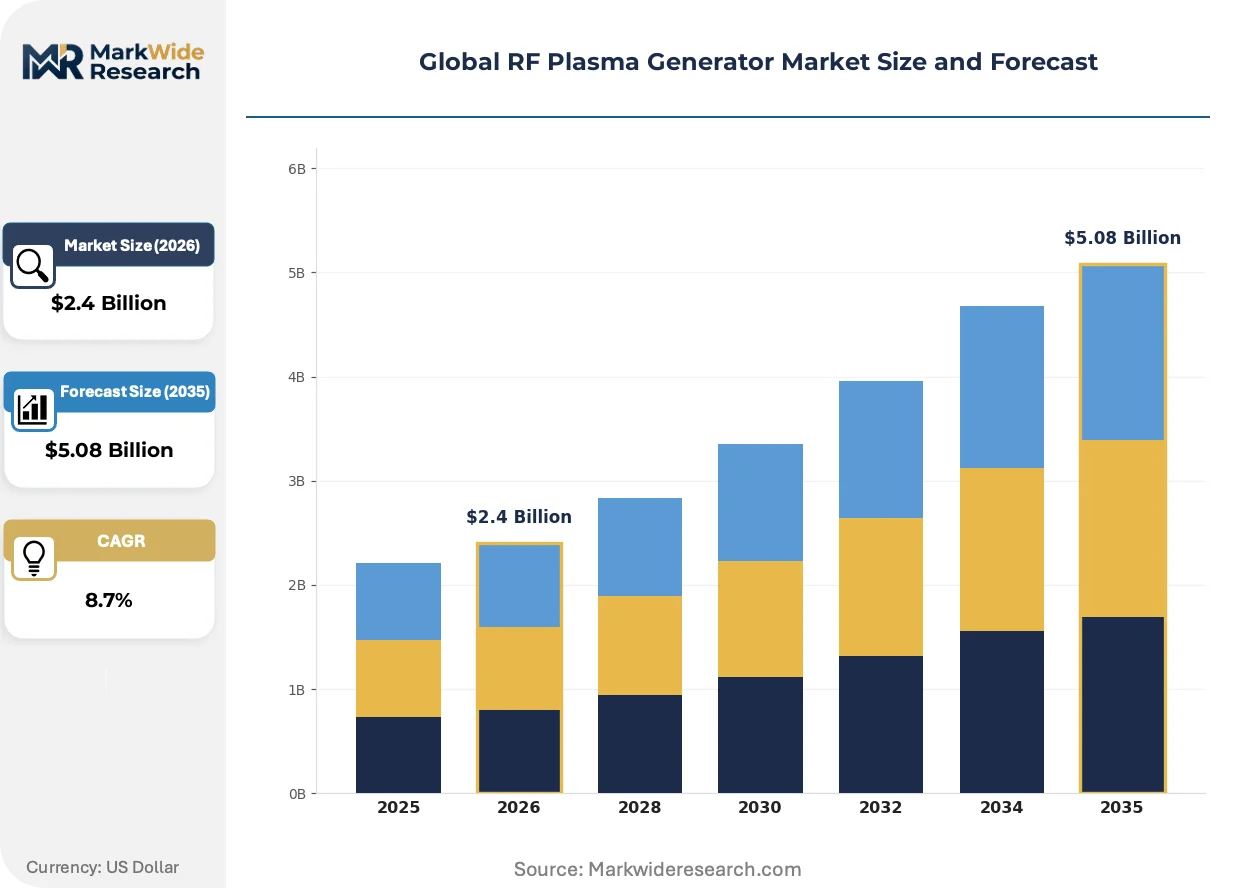
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $5.08 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Capacitively Coupled, Inductively Coupled, Magnetically Enhanced, Electron Cyclotron Resonance, Dielectric Barrier Technology: Low Frequency, Mid Frequency, High Frequency, Pulsed Plasma, Continuous Wave Application: Surface Treatment, Thin Film Deposition, Etching Processes, Ion Implantation, Sterilization End User: Semiconductor Fabricators, Research Laboratories, Aerospace Component Manufacturers, Photovoltaic Producers, Coating Specialists |
| Companies Covered | Comet Plasma Control Technologies, Adtec Plasma Technology, Advanced Energy Industries, Kyosan Electric Manufacturing, XP Power, MKS Instruments, Daihen Corporation, ULVAC, TRUMPF Hüttinger, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global RF Plasma Generator Market Shifts & Advancements
RF power delivery architectures are fragmenting across frequency bands and pulse modalities as process control requirements diverge between leading-edge logic and mature specialty devices.
Wideband impedance matching networks with embedded sensor arrays are decentralizing process control from central RF generators to chamber-level distributed modules. Memory chip fabricators in South Korea deploy these systems for real-time plasma uniformity correction. The shift compresses dependency on centralized generator tuning and enables faster recipe transitions.
REACH authorization requirements for per- and polyfluoroalkyl substances are forcing seals and cooling fluid reformulations across European-installed equipment bases. Generator manufacturers must requalify thermal management subsystems under shortened compliance deadlines. Dielectric etch chambers with legacy fluoropolymer components face accelerated replacement schedules.
Service contract unbundling is fragmenting aftermarket revenue streams as foundries bring predictive maintenance capabilities in-house. Third-party refurbishment specialists in Taiwan and Arizona capture generator overhaul volume previously held by original equipment manufacturers. The pattern concentrates in high-volume memory production sites with dedicated reliability engineering teams.
Global RF Plasma Generator Market Segmentation
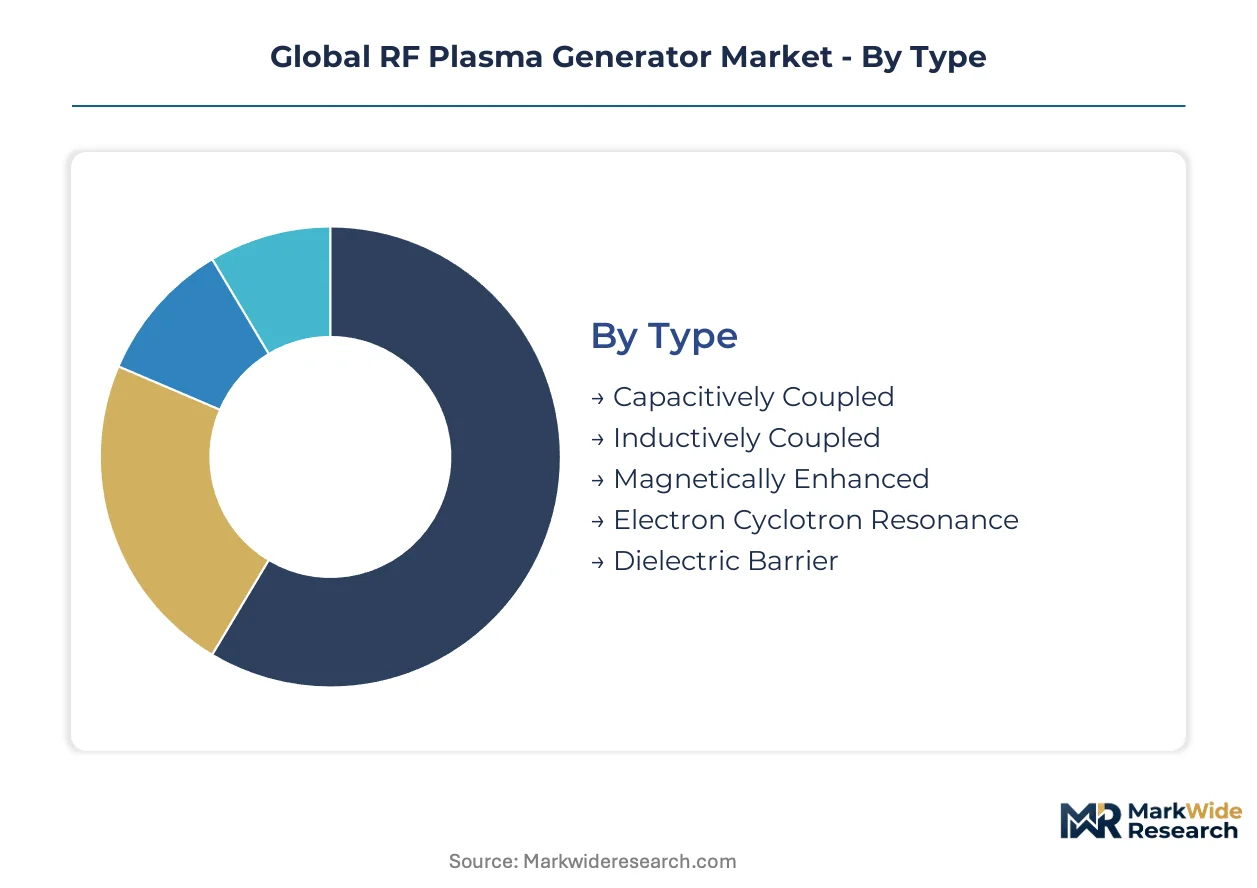
RF plasma generator procurement splits across multiple technical dimensions, with frequency architecture and coupling method determining equipment qualification pathways. Semiconductor fabricators prioritize matching network compatibility and pulse control precision over raw power specifications.
Type:
Equipment buyers select coupling architectures based on plasma density requirements and chamber retrofit constraints.
- Capacitively Coupled:These generators apply RF voltage across parallel plate electrodes to sustain moderate-density plasma discharges. South Korea's memory foundry cluster near Pyeongtaek drives procurement volume for dielectric etch and deposition chambers requiring proven reliability.
- Inductively Coupled:A coil configuration generates high-density plasma through electromagnetic induction, enabling superior uniformity for advanced logic nodes. Pyeongtaek fabricators below 7nm deploy these systems for high-aspect-ratio etch processes demanding atomic-scale precision.
- Magnetically Enhanced:Permanent magnet arrays confine plasma electrons to boost ionization efficiency at lower pressures.
- Electron Cyclotron Resonance:Microwave injection at electron cyclotron frequency produces ultra-high-density plasma for specialized etch applications.
- Dielectric Barrier:Insulated electrode configurations enable atmospheric pressure plasma generation for surface treatment outside vacuum environments.
Capacitively coupled systems lead on scale; inductively coupled configurations lead on momentum.
Technology:
Frequency selection determines process control granularity and chamber compatibility for existing installed bases.
- Low Frequency:Operating below 1 MHz, these generators deliver high ion bombardment energy for sputtering and reactive ion etch applications. Mature node fabs in Europe retain these systems for validated process recipes where throughput optimization outweighs precision gains.
- Mid Frequency:The 2-4 MHz range balances ion energy control with plasma density for dielectric film deposition. Semiconductor fabricators in East Asia specify these systems for batch processing equipment where recipe stability commands priority.
- High Frequency:Standard 13.56 MHz operation dominates volume production with established component supply chains and chamber design libraries.
- Pulsed Plasma:Modulated power delivery enables atomic-scale etch control through precise ion energy management.
- Continuous Wave:Uninterrupted RF output maintains maximum throughput for mature process nodes with stable plasma conditions.
Continuous wave technology dominates current installed capacity; pulsed plasma architectures expand most quickly.
Application:
Process requirements dictate generator specifications, with etch precision demands driving premium equipment selection.
- Surface Treatment:Plasma activation modifies material wettability and adhesion properties without thermal damage. Aerospace component manufacturers in Germany specify these systems for titanium and composite surface preparation prior to bonding operations.
- Thin Film Deposition:PECVD and sputtering processes require stable plasma sustainment for uniform coating thickness. Photovoltaic producers in China deploy high-frequency generators for silicon nitride anti-reflection coating on solar cell wafers.
- Etching Processes:Reactive ion and deep silicon etch applications demand precise ion energy distribution control.
- Ion Implantation:Plasma source ion implantation systems require high-density plasma generation for dopant species extraction.
- Sterilization:Low-temperature plasma enables medical device and pharmaceutical packaging decontamination without thermal degradation.
Etching processes command the highest equipment specification tier; surface treatment applications show steepest expansion trajectory.
End User:
Customer technical capabilities and volume requirements shape procurement patterns and service contract structures.
- Semiconductor Fabricators:Leading-edge foundries and memory producers constitute the dominant demand source, with qualification timelines spanning 18-24 months for new generator platforms. South Korea's Pyeongtaek cluster and Taiwan's Tainan Science Park anchor procurement concentration for advanced node production.
- Research Laboratories:University and national laboratory facilities prioritize experimental flexibility over production throughput. European research institutions under Horizon Europe funding constraints emphasize modular generator architectures enabling rapid frequency and power reconfiguration.
- Aerospace Component Manufacturers:Surface treatment and coating applications drive specialized plasma system procurement.
- Photovoltaic Producers:Solar cell fabrication lines specify cost-optimized generators for anti-reflection coating deposition.
- Coating Specialists:Job shop operations serving multiple industries require versatile plasma platforms with rapid recipe changeover.
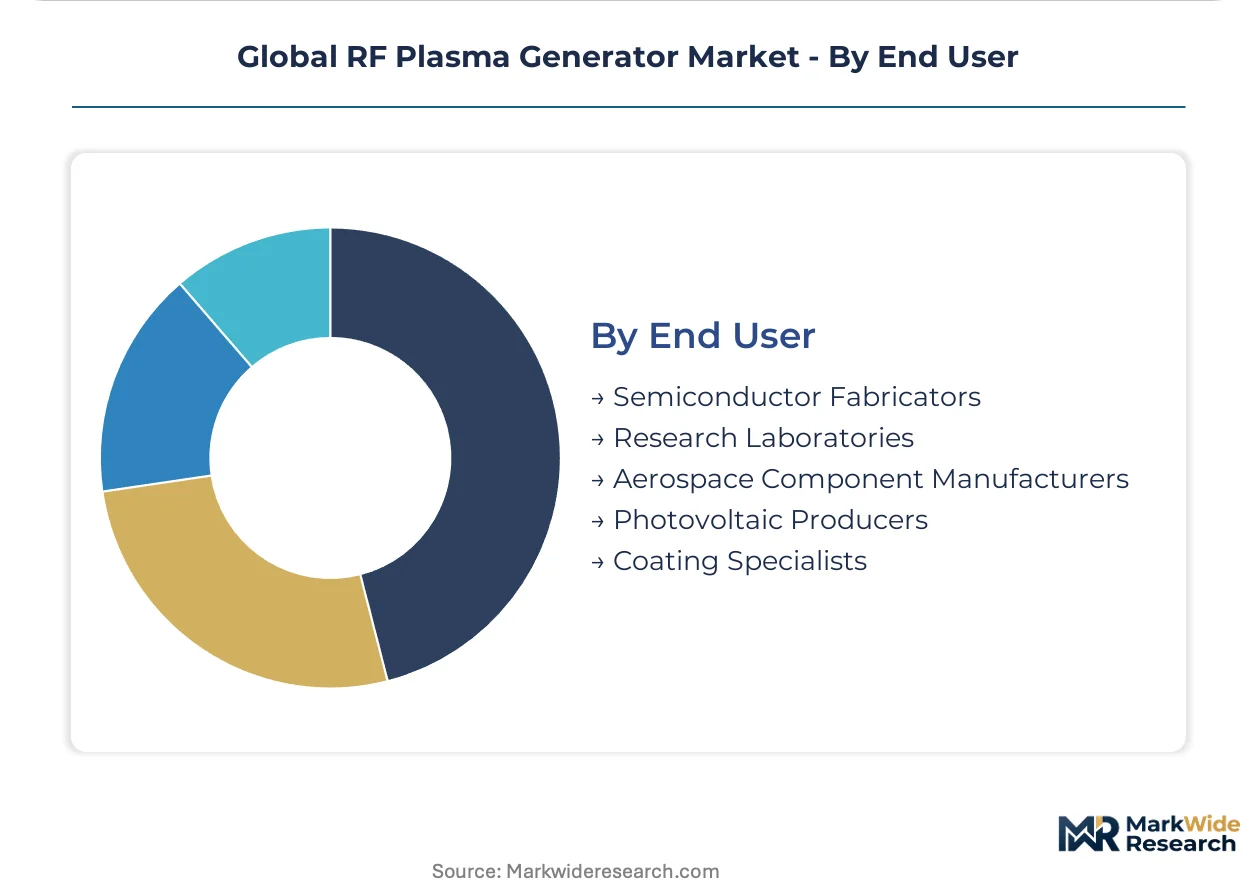
Semiconductor fabricators dominate absolute procurement value; research laboratories lead on technology evaluation influence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pyeongtaek's memory foundry cluster anchors procurement volume for advanced node RF plasma generators, while regulatory pressures across multiple jurisdictions reshape equipment sourcing patterns and supplier qualification timelines.
United States
EPA emissions standards and OSHA workplace exposure limits compel fabs to upgrade legacy plasma systems with enhanced exhaust handling. The IRA's domestic manufacturing incentives accelerate semiconductor facility construction in Arizona and Texas. Phoenix's emerging foundry hub attracts RF generator qualification programs from equipment suppliers seeking proximity to TSMC and Intel expansion sites.
South Korea
Memory chip fabricators below 7nm require precision matching networks for high-aspect-ratio etch processes. MFDS-equivalent industrial safety regulations enforce strict plasma effluent monitoring in Gyeonggi Province manufacturing zones. Pyeongtaek's foundry cluster concentrates procurement for dielectric etch and deposition chambers, with Samsung and SK Hynix driving specification standards.
China
Domestic substitution policies accelerate for critical process tools under MEE enforcement of GB standards and dual carbon goals. MIIT's semiconductor equipment localization targets pull capacity expansion for local RF generator manufacturers. Yangtze River Delta fabrication zones in Shanghai and Wuxi prioritize qualified domestic suppliers for mature node production lines.
Germany
REACH authorization requirements for per- and polyfluoroalkyl substances force seals and cooling fluid reformulations across installed equipment bases. ECHA's evolving candidate list compresses redesign timelines for thermal management subsystems. Dresden's silicon Saxony cluster sustains demand for precision matching networks in automotive and industrial semiconductor applications.
Japan
METI's semiconductor supply chain resilience initiatives strengthen domestic equipment vendor relationships with local fabricators. JIS standards govern RF generator safety and electromagnetic compatibility certification requirements. Kyushu's Kumamoto and Hiroshima production corridors maintain concentrated demand for high-frequency generators in specialty device manufacturing.
Global RF Plasma Generator Market Competitive Landscape
Global majors compete with regional champions across RF power architecture and process integration depth, producing a tiered supplier structure where scale advantages in component sourcing confront localization requirements in key markets. The vendor base separates into three strategic archetypes: vertically integrated RF power solution providers, precision matching network specialists, and modular subsystem integrators. Capacity expansion in East Asian foundry clusters and strategic partnerships for local service capabilities represent the dominant competitive moves reshaping market positioning.
Within the integrated RF power tier, Advanced Energy Industries and MKS Instruments exemplify suppliers anchoring design-in relationships through deep process control integration. TRUMPF Hüttinger occupies a position among precision matching network specialists competing on high-frequency etch application expertise. These three companies represent contrasting strategic postures—comprehensive platform breadth, chamber-level integration depth, and frequency-specific technical focus—without implying specific market share rankings or operational claims.
| Leading Market Players |
|---|
| Comet Plasma Control Technologies |
| Adtec Plasma Technology |
| Advanced Energy Industries |
| Kyosan Electric Manufacturing |
| XP Power |
| MKS Instruments |
| Daihen Corporation |
| ULVAC |
| TRUMPF Hüttinger |
| Others |
Supply & Pricing Matrix
Premium-mid-economy pricing differentiation across RF plasma generator tiers manifests in parallel supply chain configurations, where high-frequency pulsed systems command captive component sourcing while commodity continuous-wave units draw from distributed Asian component markets. This bifurcation concentrates margin capture among vertically integrated suppliers serving Pyeongtaek's memory foundries while compressing returns for modular assemblers dependent on spot-market vacuum capacitors.
Pricing Analysis
Input-cost pass-through from high-purity alumina and aluminum nitride ceramic substrates directly shapes generator pricing, with Japanese and German component specialists capturing value upstream. Pricing stratifies across premium, standard, and economy tiers based on frequency architecture sophistication and REACH-compliant thermal subsystem certification. Pricing pressure stems from Chinese domestic substitution policies accelerating local RF generator capacity expansion. Mature node fabs in Europe exhibit highest price sensitivity due to validated process recipe lock-in, while sub-7nm logic fabricators prioritize pulse control precision over unit cost.
Supply Chain Analysis
Regional distribution centers in Taiwan, South Korea, and Arizona maintain hub-and-spoke patterns to service semiconductor fabrication clusters with sub-48-hour generator replacement cycles. Vacuum capacitors and solid-state RF power modules concentrate among Japanese and German specialists, creating single-source vulnerability for critical matching network components. Distribution runs through authorized service partners with chamber-level integration capabilities rather than direct OEM fulfillment. Tariff exposure on Chinese-manufactured cooling systems and magnetic components reshapes supplier qualification timelines for European and North American fabs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in pulsed plasma architectures where atomic-scale etch control commands premium positioning, while continuous-wave system commoditization forces cost-down discipline through backward integration into ceramic substrate sourcing.
For Market Incumbents: Extend design-in relationships across leading foundries by deepening process control integration and expanding Arizona service hub capacity to capture TSMC and Intel proximity advantages. Counter emerging Chinese domestic substitution threats through accelerated REACH-compliant thermal subsystem requalification. Backward integration into solid-state RF power module production anchors margin defense against Japanese component specialist pricing leverage. For New Entrants and Emerging Players: India's PLI scheme disbursements for domestic fab construction open a window for first-mover RF generator qualification programs before procurement standards crystallize. Target compound semiconductor etch applications for silicon carbide and gallium nitride power devices, where high-density plasma configurations carry premium pricing and lower incumbent entrenchment. Pursue integrated exhaust handling retrofits as EPA and OSHA mandates expand attach rates for subsystem suppliers without challenging core generator incumbents directly. For Investors and Strategic Acquirers: Consolidation pressure builds where plasma physics modeling expertise scarcity outside established semiconductor equipment hubs limits standalone scaling. Five-to-ten-year viability favors precision matching network specialists with proven high-frequency etch track records over modular subsystem assemblers. Target acquisition archetype: mid-cap RF engineering houses with embedded electromagnetic simulation capabilities and existing foundry qualification relationships. Monitor MFDS-equivalent industrial safety regulation enforcement in Gyeonggi Province as signal for accelerated European-style effluent monitoring mandate adoption.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ceramic Substrates | Captive supply of high-purity alumina insulates margin from Japanese material specialist pricing volatility. |
| Regional Service Hub Expansion | Arizona and Taiwan facilities compress response times for Pyeongtaek and Phoenix foundry cluster uptime requirements. |
| Pulsed Plasma Architecture Development | Atomic-scale etch control capabilities unlock sub-7nm logic node procurement specifications at premium tier. |
| REACH-Compliant Thermal Subsystem Requalification | ECHA per- and polyfluoroalkyl substance authorizations force replacement cycles across European installed bases. |
| Predictive Maintenance Capability Buildout | In-house reliability engineering competes against third-party Taiwan and Arizona refurbishment specialists. |
Research Methodology
Multiple input streams — primary interviews with RF engineering directors and foundry procurement leads, secondary validation through SEC equipment supplier filings and SEMI industry association data — were reconciled through bottom-up and top-down triangulation. Semiconductor equipment specialists, plasma process engineers at memory and logic fabricators, and aftermarket service technicians in Taiwan and Arizona provided qualitative demand and competitive dynamics intelligence. Customs records, ECHA regulatory filings, and MIIT semiconductor equipment localization announcements supplied secondary market sizing anchors.
Data-stream reconciliation across the analysis window employed segmentation by coupling architecture, frequency band, pulse modality, and regional regulatory cluster to isolate growth contribution vectors. CAGRs were derived from equipment procurement tracking at named foundry expansion sites and replacement cycle modeling for REACH-driven thermal subsystem upgrades. Chamber-level integration depth and matching network compatibility emerged as critical forecast sensitivity parameters.
Revisions become necessary when EPA emissions standard enforcement intensifies, Chinese domestic substitution policy targets accelerate, or high-purity ceramic substrate supply disruptions materialize. Forecasts reflect documented assumptions regarding foundry construction timelines and regulatory compliance deadlines. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
RF Components
Radiofrequency Identification (RFID) Market
RF Components
Digital Radio Frequency Market
RF Components
5G Driver Amplifier Market
RF Components
Multilayer Coupled Inductor Market
RF Components
RF Acoustic Wave Filters Market
RF Components
Coaxial Connectors (RF) Market
RF Components
Space Traveling Wave Tube Amplifiers Market
RF Components
RF Mixers Market
RF Components
RF Interconnect Market
RF Components
RF Spectrum Analyzer Market
RF Components
Global RF and Microwave Power Transistors Market
RF Components
RF Power Detector Market
RF Components
Global Small Cell Power Amplifier Market
RF Components
Radio Frequency Counter Market
RF Components
RF and Microwave Diodes Market
RF Components
RF Passive Component Market