
 Monolithic Microwave Integrated Circuit (MMIC) Market | 2026-2036
Monolithic Microwave Integrated Circuit (MMIC) Market Size, Share, and Industry Trends Forecast 2026-2036
Monolithic Microwave Integrated Circuit (MMIC) Market Foresight
Multi-source foundry arrangements is expanding as fabless MMIC designers diversify beyond single GaAs suppliers. Qorvo leverages captive GaN fabrication to sustain margin structures in defense RF chains. Analog Devices anchors precision signal path portfolios through in-house SiGe BiCMOS capacity. Skyworks Solutions dominates cellular front-end module supply through tight foundry partnerships in Taiwan.
A Monolithic Microwave Integrated Circuit (MMIC) is a fully integrated microwave circuit fabricated on a single semiconductor substrate, typically operating between 300 MHz and 300 GHz with active elements such as transistors, diodes, and passive components including inductors, capacitors, and transmission lines lithographically patterned on-chip; these devices perform amplification, mixing, switching, and phase shifting for RF signal chains in compact, reproducible form factors. GaN MMICs now lead in high-power radar and 5G base station transmitters where thermal and breakdown performance outweigh cost premiums. CMOS MMICs occupy the fastest-growing volume tier in automotive radar and consumer mmWave connectivity as silicon economics displace compound semiconductors below 6 GHz.
FCC spectrum allocation rulings in the United States directly shape MMIC frequency targeting for commercial and defense programs. ETSI harmonization across European Union member states standardizes mmWave band plans for automotive and telecommunications deployment, while REACH compliance constrains material choices in III-V epitaxy processes. China's MIIT issues mandatory GB standards for domestic 5G equipment, creating non-tariff market access conditions for foreign MMIC suppliers. Stakeholders must monitor foundry node roadmaps and sovereign spectrum auctions as the primary variables determining product-market fit.
Market Dynamics
GaN process migration from GaAs is compressing foundry capacity allocation and forcing fabless designers into multi-source arrangements. Defense procurement acceleration in the United States and 5G base station volume concentration in China are pulling capacity toward divergent frequency and power specifications.
Growth Catalysts
- Defense Radar Modernization:United States Department of Defense procurement programs are accelerating MMIC adoption for next-generation active electronically scanned array radar and electronic warfare systems. GaN power amplifiers deliver superior thermal performance for high-duty-cycle operation.
- 5G Infrastructure Deployment:China's MIIT-mandated GB standards for domestic 5G equipment sustain volume requirements for massive MIMO power amplifier modules. State-backed carrier capex programs concentrate demand for sub-6 GHz and mmWave front ends.
- Automotive Radar Proliferation:77-81 GHz frequency allocation for advanced driver-assistance systems is expanding CMOS MMIC volumes. Silicon foundry economics enable cost reduction for mid-range vehicle platforms.
Market Restraints
- III-V Epitaxy Cost Volatility:MOCVD reactor utilization rates and precursor chemical pricing create input cost instability for GaN and GaAs foundry operations. Limited qualified substrate suppliers concentrate supply risk.
- Foundry Capacity Concentration:Taiwan-based pure-play foundries control disproportionate share of advanced GaAs and RF SOI capacity. Geopolitical friction threatens supply continuity for fabless designers.
- Thermal Management Limitations:High-power density GaN MMICs require diamond or advanced ceramic substrates that extend lead times. Packaging complexity constrains module miniaturization.
Strategic Opportunities
- India Telecom Infrastructure:TRAI spectrum auction schedules and domestic manufacturing incentives under PLI schemes create white space for power amplifier module suppliers. Local assembly partnerships bypass import duty structures.
- Satellite Terminal Miniaturization:Low Earth orbit constellation ground equipment demands Ka-band and Q-band MMICs in reduced form factors. Phased array flat-panel antennas enable consumer-grade pricing.
- EU Green Deal Alignment:REACH-compliant III-V epitaxy processes and energy-efficient base station transmitters qualify for sustainable procurement preferences. ETSI harmonization reduces multi-country certification burden.
Industry Challenges
- Compound Semiconductor Talent Scarcity:MOCVD operation and RF device physics expertise concentrates among aging workforce cohorts. University pipeline output lags foundry expansion timelines.
- Multi-Band Integration Complexity:5G New Radio carrier aggregation and mmWave beamforming require heterogeneous integration of GaN, GaAs, and CMOS die. Interposer yield and thermal co-design extend development cycles.
- ITAR and Export Control Compliance:United States State Department jurisdiction over defense-grade MMICs creates licensing delays for foreign foundry partnerships. Dual-use classification ambiguity traps commercial products.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Monolithic Microwave Integrated Circuit (MMIC) Market |
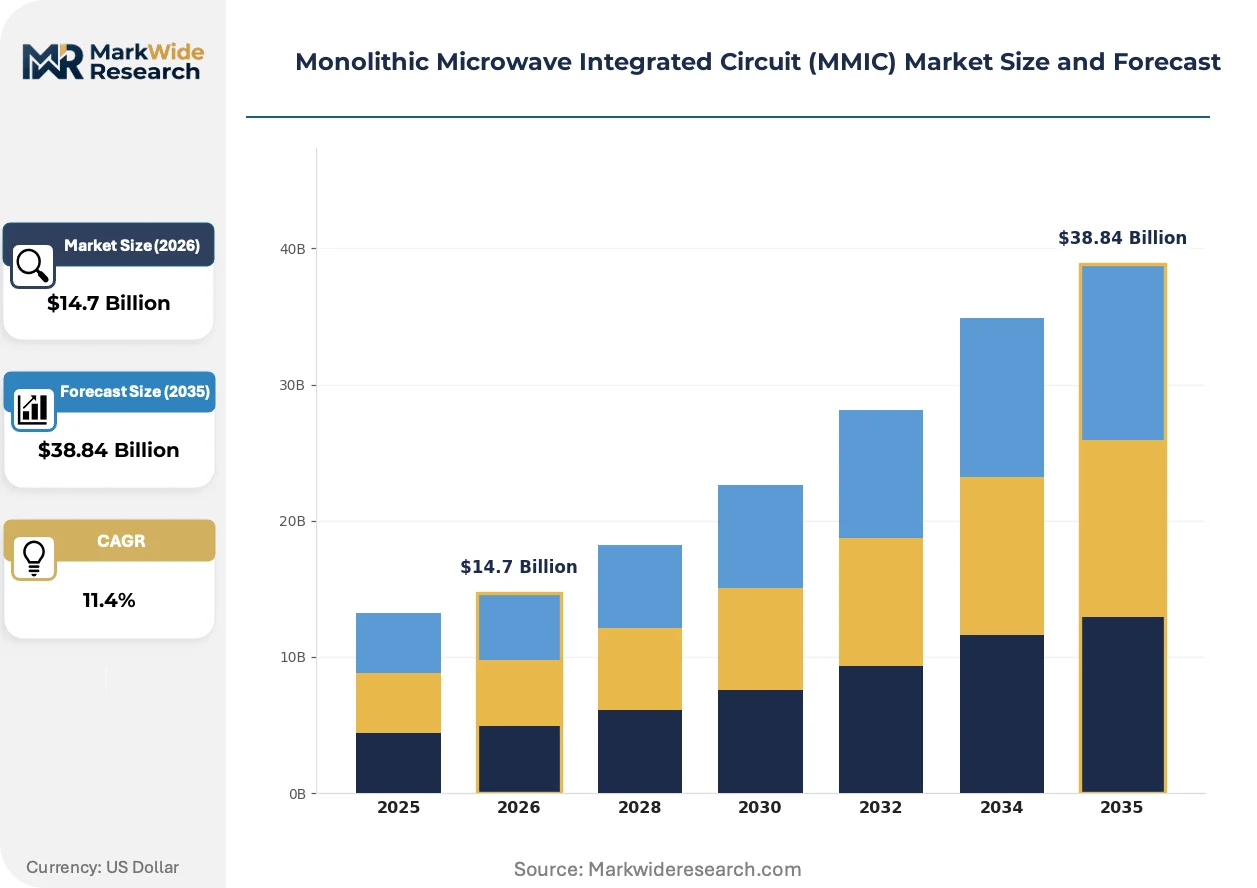
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $38.84 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: GaAs MMICs, GaN MMICs, SiGe MMICs, CMOS MMICs Technology: RF, Analog, Digital, Microwave Application: Telecommunications, Aerospace, Defense, Automotive End User: Satellites, Base Stations, Consumer Electronics, Industrial Equipment |
| Companies Covered | Analog Devices, WIN Semiconductors, Qorvo, Transcom, Infineon Technologies, MACOM, NXP Semiconductors, RFHIC, Skyworks Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Monolithic Microwave Integrated Circuit (MMIC) Market Shifts & Advancements
Process node diversification and sovereign spectrum allocation are fragmenting design roadmaps. Foundries must now support parallel development tracks for defense-qualified GaN, automotive-grade CMOS, and consumer mmWave silicon.
Gallium nitride on silicon carbide is electrifying high-power RF amplification. United States prime contractors are adopting GaN-on-SiC MMICs for next-generation radar transmit chains with accelerated qualification timelines. This substrate technology is electrifying the displacement of tube-based and GaAs solid-state amplifiers in electronic warfare and 5G base station applications.
FCC spectrum allocation rulings in the United States are reshaping frequency targeting for commercial MMIC portfolios. The 3.45 GHz and 48 GHz auction outcomes force redesign of power amplifier architectures and filter bank configurations. Defense contractors and cellular infrastructure OEMs are most affected, with product roadmaps pivoting toward newly licensed bands within 18-month windows.
Multi-source foundry qualification is altering procurement patterns for fabless MMIC designers. Tier-one cellular module suppliers now mandate dual-qualified GaAs sources for power amplifier die, displacing single-source volume commitments. This behavior is most visible in Taiwan and South Korea, where foundry partnerships determine front-end module supply security for smartphone OEMs.
Monolithic Microwave Integrated Circuit (MMIC) Market Segmentation
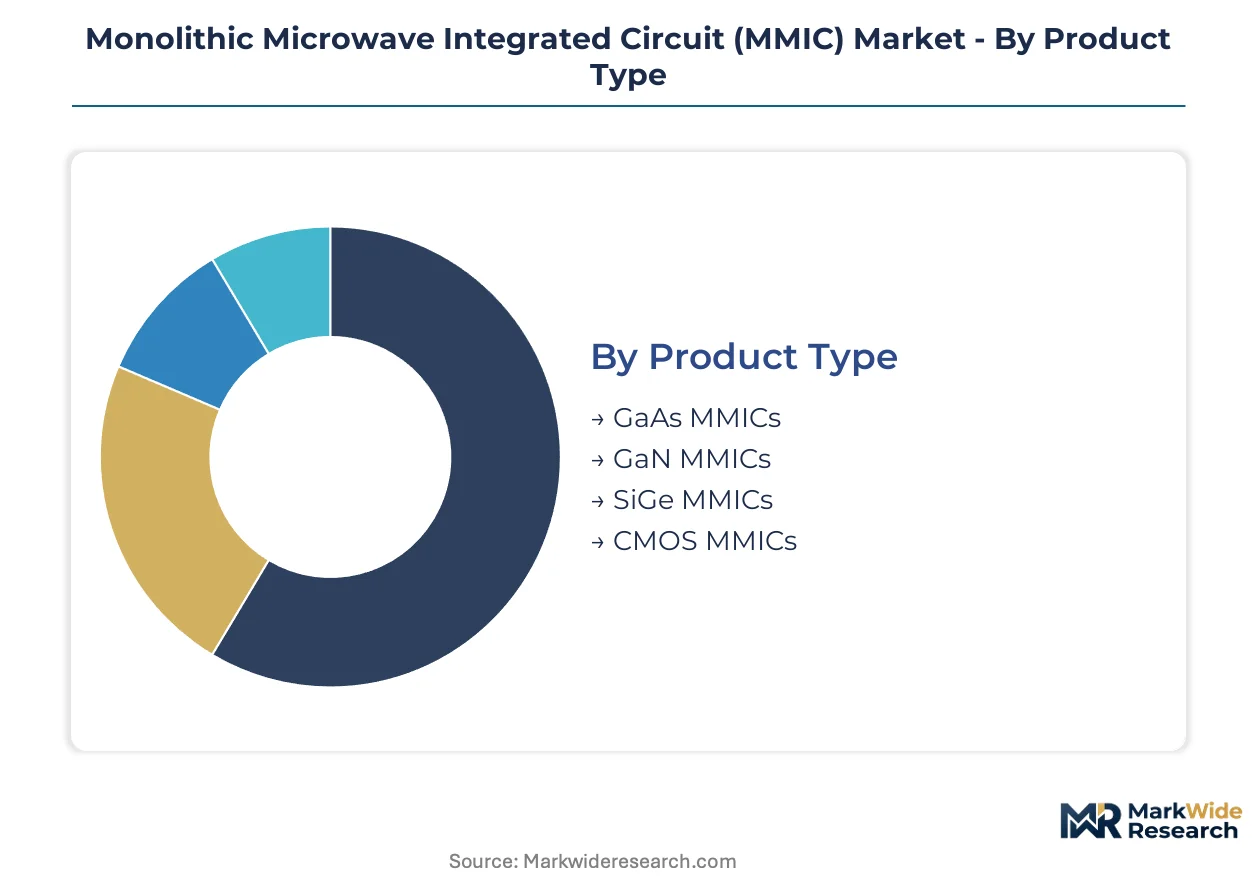
MMIC procurement patterns diverge sharply across frequency bands, power requirements, and substrate technologies. Foundry capacity allocation and defense qualification timelines create distinct competitive dynamics within each segment cluster.
Product Type:
Substrate material selection determines thermal performance, frequency ceiling, and foundry economics for MMIC designers.
- GaAs MMICs:Gallium arsenide substrates deliver mature low-noise amplification and moderate power handling through established MOCVD foundry infrastructure. Defense radar and legacy cellular infrastructure in the United States sustain volume demand despite GaN displacement at higher power tiers.
- GaN MMICs:Gallium nitride on silicon carbide enables power densities exceeding GaAs by an order of magnitude for active electronically scanned array transmit chains. China's 5G massive MIMO deployments and Pentagon radar modernization programs concentrate foundry capacity allocation toward this technology.
- SiGe MMICs:Silicon-germanium BiCMOS integration supports precision signal paths for instrumentation and automotive radar at intermediate frequencies.
- CMOS MMICs:Standard silicon foundry economics enable cost-optimized solutions for consumer mmWave and sub-6 GHz connectivity at volume scale.
Mature deployment sits with GaAs MMICs. Newer deployment is concentrated in GaN MMICs.
Technology:
Signal processing architecture separates cost-optimized consumer solutions from precision defense and instrumentation applications.
- RF MMICs:Radio frequency front-end integration spans power amplification, low-noise reception, and switching functions across 300 MHz to 6 GHz. Cellular base station and satellite ground terminal procurement concentrates demand for GaN and GaAs variants respectively.
- Microwave MMICs:Millimeter-wave operation above 30 GHz requires compound semiconductor or advanced CMOS nodes for beamforming and phased array applications. 5G mmWave infrastructure and automotive radar in Germany and Japan drive fastest technology qualification cycles.
- Analog MMICs:Continuous signal processing for mixers, attenuators, and phase shifters supports electronic warfare and test equipment applications.
- Digital MMICs:Mixed-signal integration with digital control interfaces enables software-defined radio architectures and adaptive beamforming systems.
RF MMICs command the largest revenue base. Microwave MMICs are climbing the fastest as mmWave spectrum allocation accelerates.
Application:
End-use specifications fragment procurement requirements across frequency range, environmental qualification, and volume scale.
- Telecommunications:Base station power amplifiers and small-cell front ends span sub-6 GHz and mmWave bands with divergent thermal and efficiency specifications. China's MIIT-mandated GB standards for 5G equipment create dedicated supply chains for domestic carrier procurement programs.
- Defense:Electronic warfare and radar systems demand ITAR-qualified GaN MMICs with accelerated radiation tolerance and hermetic packaging. United States Department of Defense procurement timelines prioritize domestic foundry sourcing for active electronically scanned array programs.
- Aerospace:Satellite payloads and avionics systems require radiation-hardened MMICs with extended temperature operation and space-qualified packaging protocols.
- Automotive:77-81 GHz radar integration for advanced driver-assistance systems exploits CMOS foundry economics at automotive grade qualification tiers.
Defense applications anchor premium pricing tiers. Telecommunications generates the steepest volume expansion trajectory.
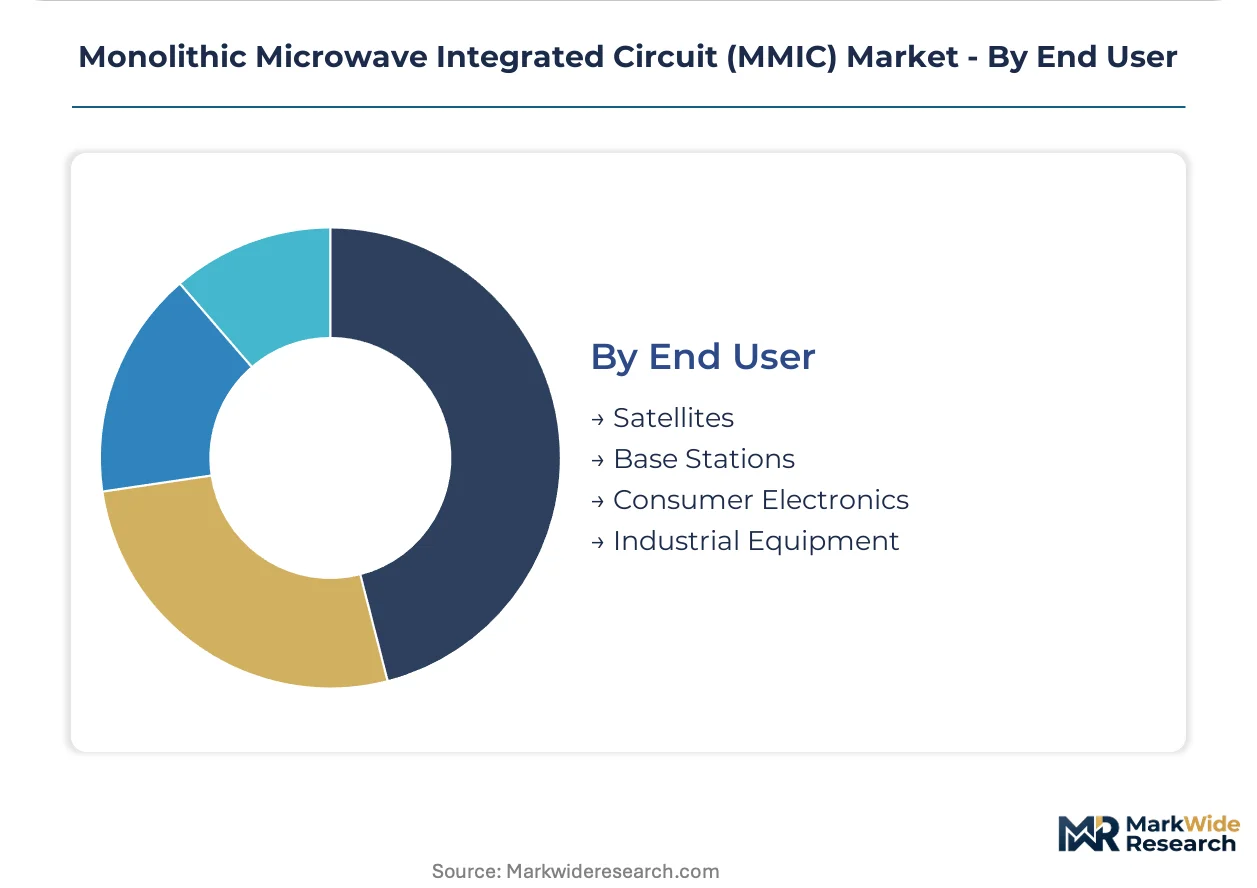
End User:
Customer scale and qualification requirements determine foundry partnership structures and margin capture potential.
- Base Stations:Massive MIMO infrastructure procurement by state-backed carriers in China sustains GaN power amplifier module volumes. Multi-source foundry qualification mandates from tier-one cellular OEMs fragment volume concentration across Taiwan and South Korea suppliers.
- Satellites:Low Earth orbit constellation terminals demand Ka-band and Q-band MMICs in compact phased array configurations. Flat-panel antenna miniaturization drives integration complexity for consumer-grade ground equipment pricing.
- Consumer Electronics:Smartphone front-end modules and WiFi connectivity exploit CMOS and RF SOI foundry economics at billion-unit annual scale.
- Industrial Equipment:Test and measurement instrumentation requires precision signal path MMICs with extended linearity and temperature stability specifications.
Consumer electronics delivers maximum volume scale. Base stations concentrate technology migration investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense procurement acceleration in the United States and 5G base station volume concentration in China are pulling foundry capacity toward divergent frequency and power specifications. MIIT-mandated GB standards and Pentagon radar modernization programs create distinct qualification pathways. Foundry partnerships in Taiwan and South Korea mediate supply security for smartphone OEMs and cellular infrastructure vendors.
United States
Department of Defense procurement programs are accelerating MMIC adoption for active electronically scanned array radar and electronic warfare systems. FCC spectrum allocation rulings at 3.45 GHz and 48 GHz force redesign of power amplifier architectures within compressed timelines. Defense contractors cluster in Massachusetts and California, where GaN-on-SiC qualification pipelines serve Pentagon transmit chain requirements.
China
State-backed carrier capex programs sustain massive MIMO power amplifier module volumes for sub-6 GHz and mmWave front ends. MIIT issues mandatory GB standards for domestic 5G equipment, creating non-tariff market access conditions for foreign MMIC suppliers. Yangtze River Delta fabrication complexes concentrate GaN foundry expansion to serve base station deployment targets.
Germany
Automotive OEMs at 77-81 GHz are expanding CMOS MMIC volumes for advanced driver-assistance systems across mid-range vehicle platforms. ETSI harmonization standardizes mmWave band plans while REACH compliance constrains material choices in III-V epitaxy processes. Bavaria and Baden-Württemberg host RF design centers coordinating with foundry partners in Taiwan.
South Korea
Smartphone OEM procurement mandates dual-qualified GaAs sources for power amplifier die, displacing single-source volume commitments. MFDS oversight of telecommunications equipment certification aligns with carrier infrastructure roadmaps. Seoul Capital Area module suppliers coordinate multi-source foundry qualification across Taiwan and domestic packaging facilities.
India
TRAI spectrum auction schedules and PLI scheme domestic manufacturing incentives create white space for power amplifier module suppliers. Local assembly partnerships bypass import duty structures for base station equipment. Karnataka and Telangana are emerging as electronics manufacturing clusters with foundry liaison offices serving telecom infrastructure tenders.
Monolithic Microwave Integrated Circuit (MMIC) Market Competitive Landscape
Multi-source foundry qualification dominates the current landscape as tier-one cellular module suppliers mandate dual-qualified GaAs sources. The vendor base separates into three strategic tiers: captive GaN fabricators serving defense RF chains, fabless designers dependent on Taiwan foundry partnerships, and precision signal path specialists with in-house SiGe BiCMOS capacity. Capacity expansion and strategic partnerships represent the dominant competitive moves, with foundry node roadmaps and sovereign spectrum auctions determining product-market fit.
Within the captive fabrication tier, Qorvo leverages internal GaN production to sustain margin structures in defense RF chains. Among fabless RF front-end specialists, Skyworks Solutions anchors cellular module supply through tight foundry partnerships in Taiwan. Precision signal path portfolios sit with Analog Devices, which maintains in-house SiGe BiCMOS capacity for instrumentation and automotive radar applications. These three exemplify divergent strategic responses to foundry capacity concentration and substrate technology migration.
| Leading Market Players |
|---|
| Analog Devices |
| WIN Semiconductors |
| Qorvo |
| Transcom |
| Infineon Technologies |
| MACOM |
| NXP Semiconductors |
| RFHIC |
| Skyworks Solutions |
| Others |
Supply & Pricing Matrix
GaN-on-SiC process migration from legacy GaAs MOCVD flows is compressing wafer economics while concentrating foundry ownership among qualified compound semiconductor houses. This substrate transition simultaneously elevates input costs for high-power die and restricts supply access to Pentagon-certified fabrication lines.
Pricing Analysis
Warranty and qualification-bundling arrangements separate ITAR-compliant defense die from unqualified commercial volumes. Three-tier pricing structure across ITAR-certified, automotive-grade, and consumer-tier qualification levels reflects foundry certification investment and radiation-hardening overhead. Price differentiation hinges on hermetic packaging inclusion and accelerated burn-in protocols. Defense contractors exhibit lowest price sensitivity due to sole-source qualification timelines, while consumer WiFi module suppliers face intense cost compression from CMOS foundry alternatives.
Supply Chain Analysis
Single-source vulnerability sits with Taiwan-based pure-play GaAs foundries controlling disproportionate RF SOI capacity. Raw material dependencies encompass silicon carbide substrates, high-purity gallium metal, and MOCVD precursor gases. Geopolitical friction across the Taiwan Strait threatens supply continuity for fabless designers. Distribution runs through tier-one cellular module suppliers in South Korea and smartphone OEM procurement hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Captive GaN fabrication and multi-source foundry qualification constitute a vertical-integration race. Players pursue upstream control over substrate supply and defense qualification pipelines as the decisive margin lever.
For Market Incumbents: Hedge against Taiwan foundry concentration by qualifying secondary GaAs sources in South Korea and domesticating GaN-on-SiC epitaxy capacity. Accelerate Pentagon radar program capture before next-generation active electronically scanned array awards consolidate. Secure long-term silicon carbide substrate offtake to preempt raw material bottlenecks. For New Entrants and Emerging Players: The price-point gap between ITAR-certified defense die and commercial-grade automotive MMICs offers white-space entry. Target India's PLI-backed telecom infrastructure tenders through local assembly partnerships that bypass import duty structures. Pursue satellite terminal miniaturization for low Earth orbit constellation ground equipment where phased array integration complexity deters established cellular suppliers. For Investors and Strategic Acquirers: Exit pathways concentrate in defense prime contractor acquisition of fabless GaN designers with ITAR-qualified product lines. Long-term viability favors compound semiconductor specialists with captive epitaxy and packaging integration. Watch Pentagon active electronically scanned array award announcements as the inflection signal for capacity allocation shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Source Foundry Qualification | Dual-qualified GaAs sourcing mitigates Taiwan concentration risk for tier-one cellular module suppliers. |
| Captive GaN-on-SiC Fabrication | In-house epitaxy capacity secures Pentagon radar transmit chain margins against foundry margin capture. |
| India PLI Localization Partnership | Domestic assembly structures bypass TRAI import duty barriers for base station power amplifier modules. |
| Satellite Terminal Miniaturization | Ka-band and Q-band MMIC integration enables consumer-grade pricing for flat-panel phased array antennas. |
| REACH-Compliant III-V Epitaxy | EU Green Deal alignment qualifies European base station transmitters for sustainable procurement preferences. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with RF device physicists, MOCVD operations directors, defense procurement officers, and cellular infrastructure procurement managers validated foundry capacity claims and qualification timelines. SEC 10-K disclosures, FCC spectrum auction records, MIIT GB standard publications, and Taiwan semiconductor trade statistics furnished cross-referenced demand signals. Bottom-up die volume estimates and top-down carrier capex allocations were triangulated against foundry revenue disclosures.
Data-stream reconciliation across substrate supplier shipments, equipment vendor order backlogs, and end-user procurement schedules shaped the analytical framework. Segmentation modeling spanned substrate technology, frequency band, power tier, application vertical, and regional regulatory cluster across the projection horizon. CAGRs were derived from foundry node roadmaps and sovereign spectrum auction schedules. Forecast inputs incorporated Pentagon radar modernization program timelines and China's MIIT-mandated 5G base station deployment targets.
Underlying measurement precision varies by segment; defense procurement volumes carry tighter precision than consumer WiFi module forecasts due to classified program visibility constraints. Forecasts reflect assumptions regarding foundry yield maturation and geopolitical continuity that material shifts in Taiwan Strait relations or export control rulings could revise. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
RF Components
SMD Resonator Market
RF Components
Phase Shifters Market
RF Components
Radio Frequency Integrated Circuit (RFIC) Market
RF Components
Small Signal Mosfets Market
RF Components
Multi-Mode Receiver Market
RF Components
Global Small Cell Power Amplifier Market
RF Components
Microwave Devices Market
RF Components
Millimeter Wave Equipment Market
RF Components
RF Front End Module Market
RF Components
Tunable Capacitors Market
RF Components
US RFID Tags Market
RF Components
RF Components Market
RF Components
Toroid Inductor Market
RF Components
Digital Radio Frequency Market
RF Components
RF Over Fiber (Rfof) Market
RF Components
Dielectric Resonator Market