
 Wheel Alignment Equipment Market | 2026-2036
Wheel Alignment Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Wheel Alignment Equipment Market Insights
The gap between premium diagnostic platforms and basic commodity alignment tools is expanding. Hunter Engineering Company leverages integrated camera-based architecture to dominate high-throughput dealership channels. Robert Bosch GmbH sustains brand strength across European aftermarket networks through modular system design. Launch Tech Co., Ltd. competes on cost-optimized electromechanical configurations for emerging market repair shops.
Wheel alignment equipment comprises precision measurement and adjustment apparatus that calibrates camber, caster, toe, and thrust angle parameters to manufacturer specifications, typically achieving resolution within 0.01 degrees using optical or electromechanical sensor arrays. Camera-based 3D alignment systems command the premium tier due to faster measurement cycles and reduced calibration drift, while 2D laser systems retain volume share in price-sensitive independent garages. Fleet maintenance represents the fastest-growing end-user segment as logistics operators internalize alignment services to minimize commercial vehicle downtime. Portable solutions are gaining traction among mobile service providers serving off-site agricultural and construction equipment.
NHTSA tire safety standards and EPA fuel efficiency regulations jointly elevate alignment accuracy requirements across US service facilities. The EU Green Deal and F-Gas Regulation indirectly pressure European workshops to optimize tire life and reduce replacement frequency through precise alignment protocols. Stakeholders must weigh technology refresh cycles against evolving OEM certification requirements that increasingly mandate specific equipment brands for warranty compliance.
Market Dynamics
Camera-based 3D alignment architecture is displacing electromechanical sensor arrays across commercial vehicle service networks, compressing measurement cycles while tightening calibration precision requirements for OEM-certified facilities.
Growth Catalysts
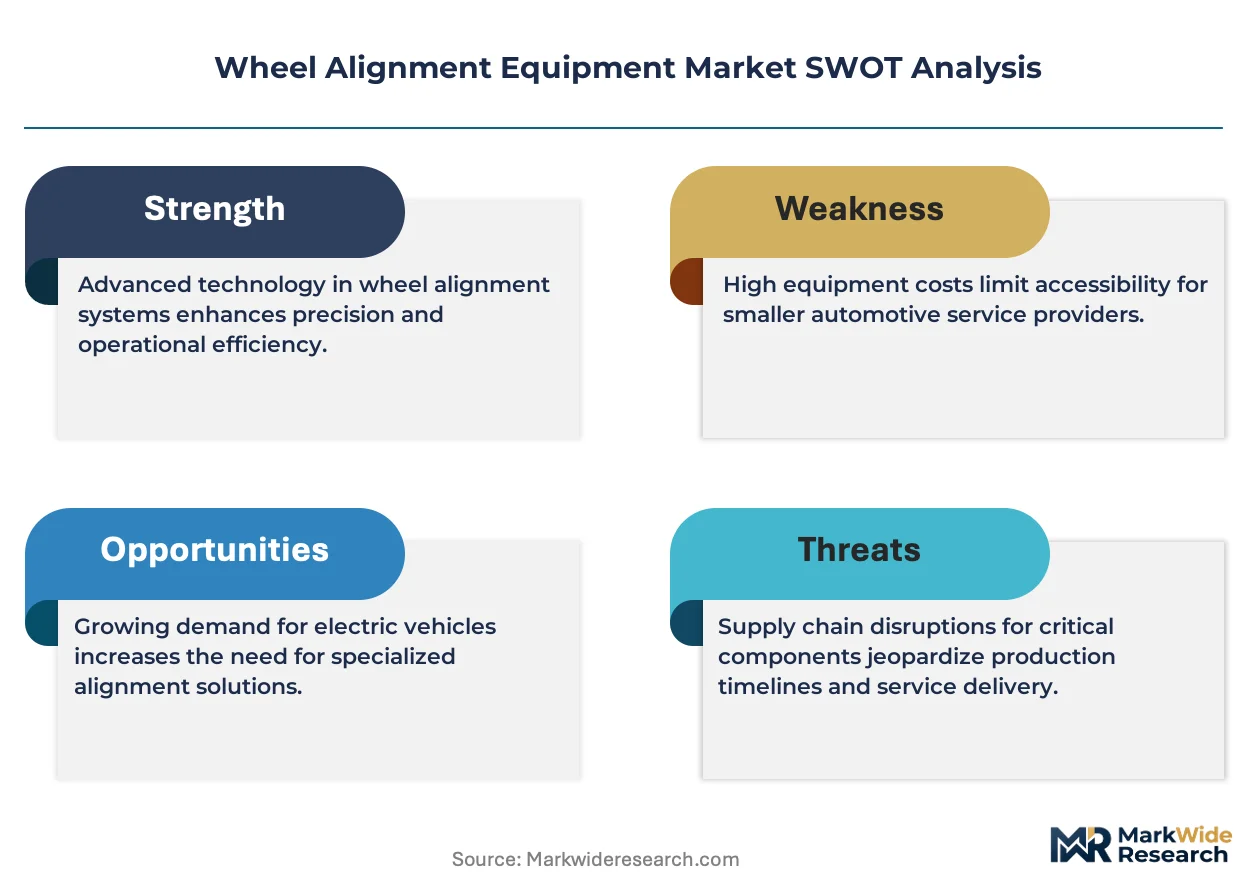
- NHTSA tire safety standards:US repair facilities face escalating accuracy mandates for camber and thrust angle calibration, forcing upgrades from manual gauges to computerized diagnostic platforms.
- Fleet maintenance internalization:Logistics operators across Germany and the Netherlands are building captive alignment bays to minimize commercial vehicle downtime and control service costs.
- EU F-Gas Regulation:Extended tire life requirements are pressuring European workshops to optimize replacement intervals through precision alignment protocols.
Market Restraints
- Optical component supply concentration:High-resolution camera modules for 3D systems depend on specialized sensor foundries concentrated in East Asian manufacturing clusters.
- Calibration gas cost volatility:Laser alignment systems require periodic recalibration using reference gas mixtures subject to commodity price swings.
- Technical limitation in outdoor environments:Camera-based systems experience measurement drift under direct sunlight, restricting deployment for mobile agricultural equipment services.
Strategic Opportunities
- India aftermarket penetration:Independent garages in Mumbai and Delhi remain underserved by precision alignment infrastructure, presenting white space for cost-optimized 2D laser configurations.
- Construction equipment mobility:Portable alignment solutions for off-site bulldozer and excavator fleets represent an emerging application segment with limited incumbent competition.
- ISO 9001 certification convergence:Quality management mandates are creating procurement preference for alignment equipment vendors with documented traceability protocols.
Industry Challenges
- Technician certification timelines:OEM warranty compliance increasingly requires facility-level accreditation that demands 6-12 month training programs for diagnostic platform operation.
- Legacy bay reconfiguration:Existing two-post lifts in independent garages require structural modifications to accommodate camera mounting arrays, extending installation cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wheel Alignment Equipment Market |
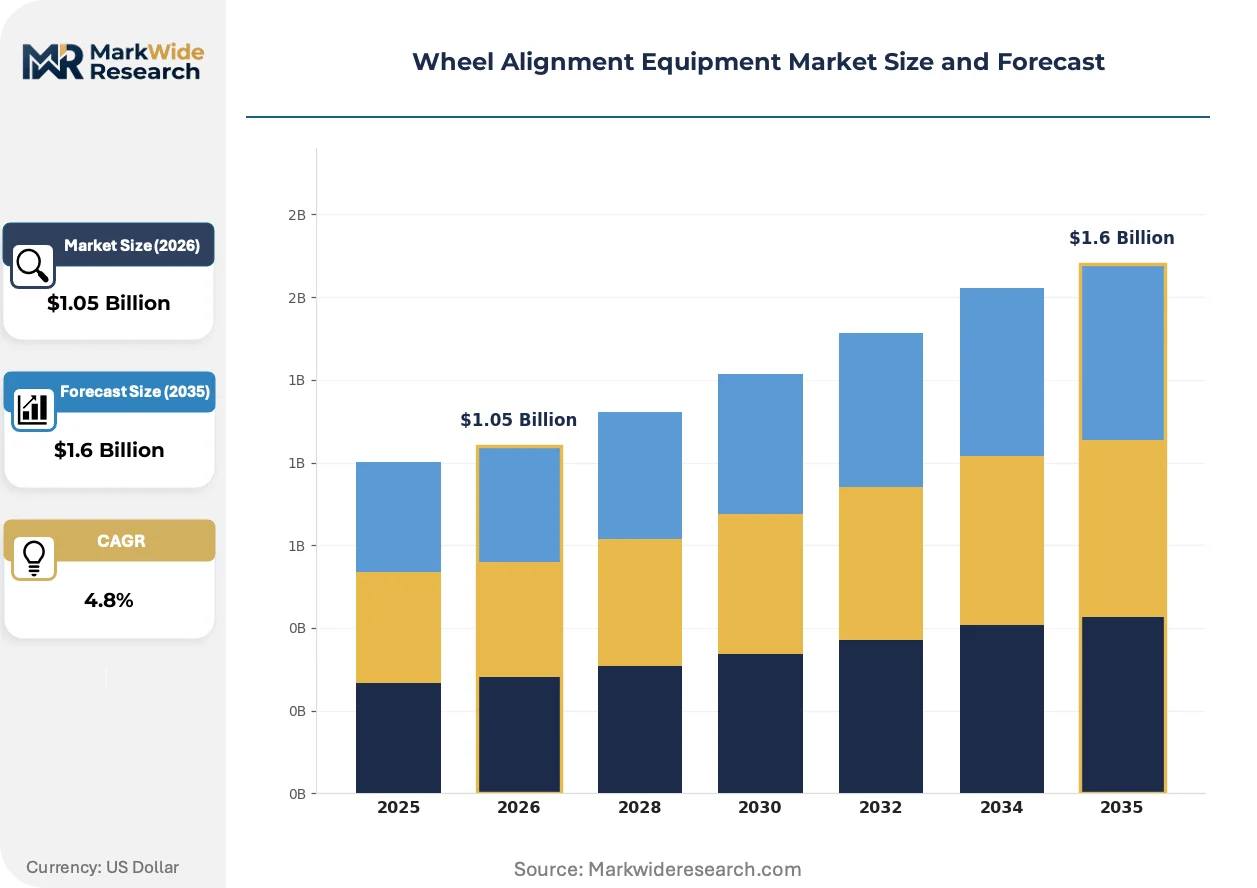
| Market Size in 2026 | $1.05 Billion |
| Market Size in 2035 | $1.6 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: 2D Alignment Systems, 3D Alignment Systems, Computerized Alignment Machines, Manual Alignment Tools End User: Automotive Repair Shops, Dealerships, Aftermarket Providers, Fleet Maintenance Technology: Laser Technology, Camera-Based Systems, Ultrasonic Technology, Electromechanical Devices Installation: Mobile Units, Permanent Installations, Portable Solutions, In-Ground Systems |
| Companies Covered | Continental AG, Robert Bosch GmbH, Hunter Engineering Company, CEMB Spa, Beissbarth Automotive GmbH, Snap-on Incorporated, Launch Tech Co., Ltd., CORGHI, MAHA Maschinenbau Haldenwang GmbH Co. KG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wheel Alignment Equipment Market Trends and Innovations
Measurement architecture is shifting from contact-based electromechanical sensors to non-contact optical arrays, compressing cycle times while expanding the addressable base of high-throughput service operations.
Machine vision algorithms are converging with cloud-based calibration databases to enable real-time specification updates across distributed equipment networks. Major fleet operators in the US and Germany are deploying these integrated systems to synchronize alignment protocols across multiple facility locations. This convergence is compressing the competitive window for standalone hardware vendors lacking software subscription revenue streams.
The EU Green Deal's tire lifecycle requirements are compelling workshops to document alignment accuracy as a condition for extended warranty claims. German KBA inspection protocols now reference ISO alignment standards for commercial vehicle roadworthiness certification. Independent garages in Bavaria and North Rhine-Westphalia are responding by consolidating procurement through cooperative buying groups to access certified equipment tier pricing.
Service bundling is fragmenting as fleet operators unbundle alignment from comprehensive maintenance contracts to negotiate direct equipment procurement. Third-party leasing channels for diagnostic platforms are displacing traditional distributor financing in the US independent garage segment. This behavioral shift is most visible among multi-location repair chains in Texas and California seeking off-balance-sheet equipment access.
Wheel Alignment Equipment Market Segmentation
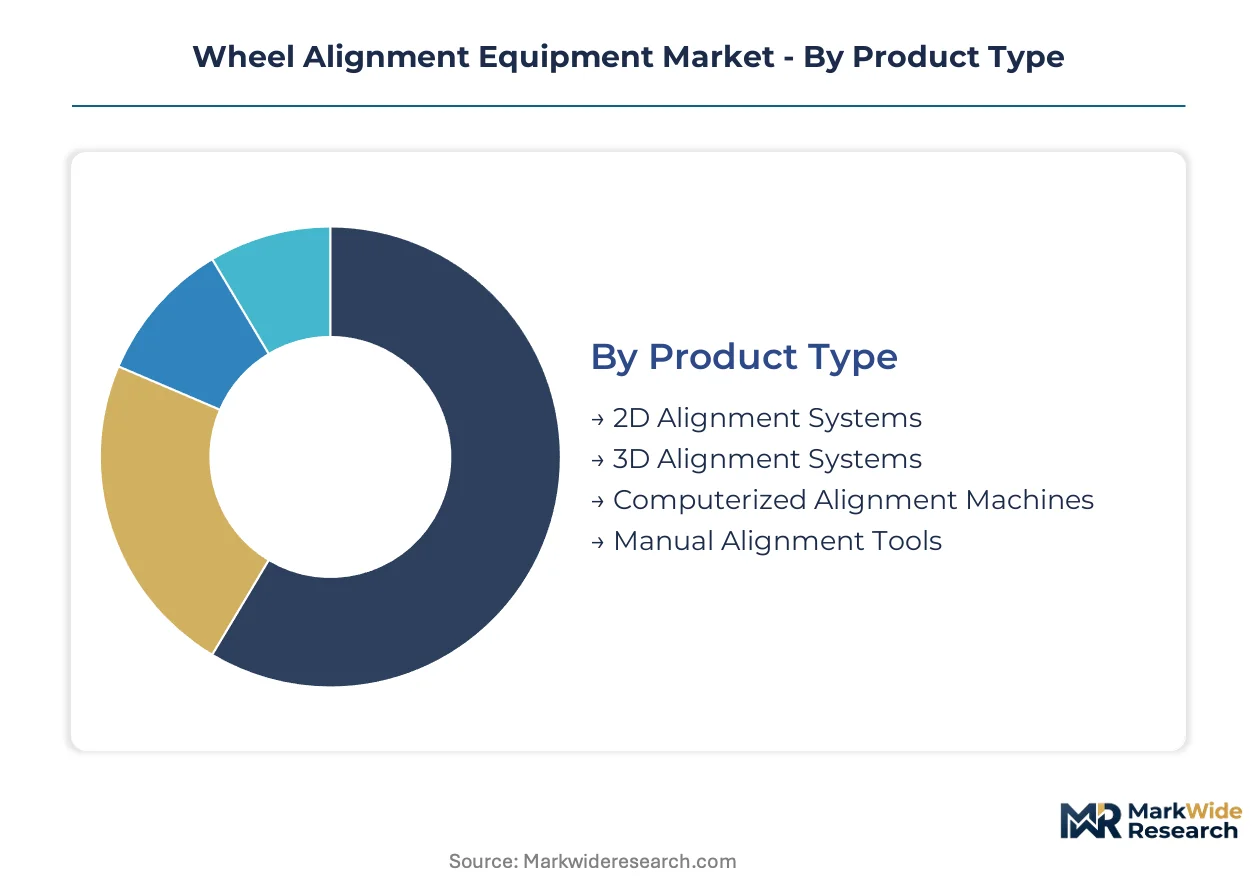
Segmentation in wheel alignment equipment reveals divergent technology investment patterns across service tiers. Repair facilities optimize procurement between precision measurement capabilities and bay throughput economics, while fleet operators prioritize standardization across distributed locations.
Product Type:
Volume concentration sits with 2D electromechanical platforms, while premium capture belongs to optical 3D architectures with integrated software ecosystems.
- 2D Alignment Systems:Laser or CCD sensor arrays measure camber and toe through two-dimensional plane geometry, achieving ±0.1 degree accuracy. Demand clusters in independent garages across India and Southeast Asia where equipment budgets constrain capital deployment. NHTSA compliance deadlines are forcing gradual displacement toward computerized alternatives.
- 3D Alignment Systems:Multi-camera triangulation captures full vehicle geometry in single measurement cycles, resolving to 0.01 degrees through machine-vision algorithms. OEM-certified dealerships in Germany and the Netherlands mandate these platforms for warranty compliance. Fleet maintenance internalization is accelerating procurement as logistics operators build captive service bays.
- Computerized Alignment Machines:Integrated diagnostic platforms combine measurement hardware with specification databases and reporting software.
- Manual Alignment Tools:Mechanical gauges and camber/caster plates persist in emerging market mobile services and agricultural equipment repair.
Today's leader: 3D Alignment Systems. Tomorrow's challenger: Computerized Alignment Machines.
End User:
Customer procurement authority separates centralized fleet operators from fragmented independent repair networks.
- Automotive Repair Shops:Independent garages in Texas and California represent price-sensitive volume demand, typically selecting 2D laser systems through third-party leasing channels. EPA fuel efficiency regulations are elevating accuracy requirements beyond legacy equipment capabilities.
- Fleet Maintenance:Logistics operators across Germany and the Netherlands are internalizing alignment services to minimize commercial vehicle downtime. These buyers command volume pricing and mandate equipment standardization across multi-location networks.
- Dealerships:OEM-certified service facilities face brand-mandated equipment specifications and technician certification requirements.
- Aftermarket Providers:Multi-location repair chains and franchise networks balance equipment standardization against regional cost variation.
Volume dominance: Automotive Repair Shops. Steepest expansion trajectory: Fleet Maintenance.
Technology:
Measurement modality determines calibration maintenance burden and environmental operating range.
- Camera-Based Systems:Stereoscopic vision arrays eliminate mechanical wear points and enable sub-minute measurement cycles. German KBA inspection protocols now reference ISO alignment standards that favor optical precision. Direct sunlight interference restricts deployment for mobile agricultural applications.
- Laser Technology:Time-of-flight and triangulation sensors deliver reliable performance in uncontrolled lighting conditions. 2D laser configurations retain installed base in price-sensitive markets despite slower cycle times.
- Ultrasonic Technology:Acoustic ranging systems occupy niche applications in heavy-duty vehicle alignment where optical line-of-sight is obstructed.
- Electromechanical Devices:Contact-based sensor arrays face accelerating displacement as calibration drift and mechanical wear increase total cost of ownership.
Installed base leader: Laser Technology. Displacement target: Electromechanical Devices.
Installation:
Physical configuration dictates equipment mobility and bay infrastructure requirements.
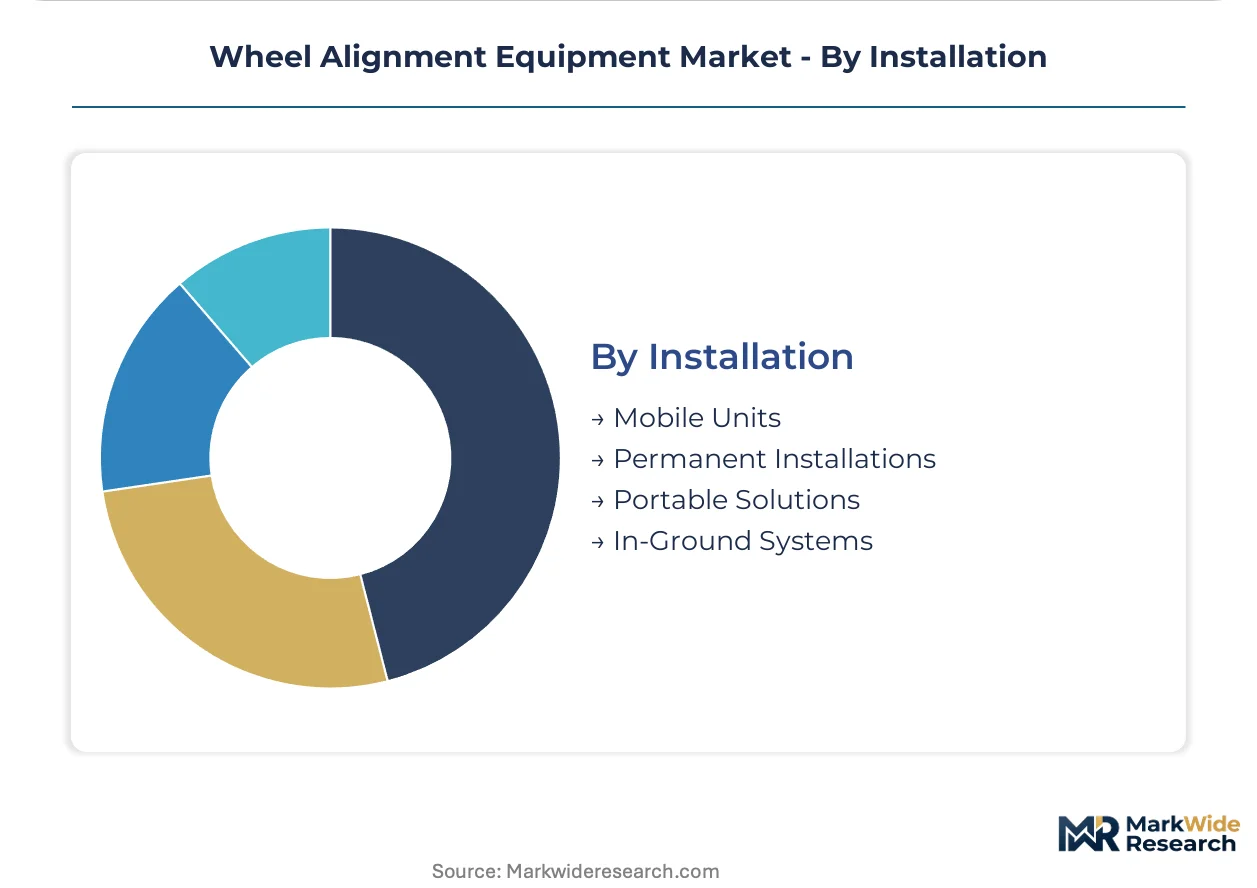
- Permanent Installations:Fixed camera mounting arrays and in-ground lift integrations dominate high-throughput dealership environments. Structural bay modifications extend installation cycles for legacy two-post lift conversions.
- Portable Solutions:Battery-powered measurement units with wireless data transmission enable off-site construction and agricultural equipment service. Limited incumbent competition characterizes this emerging application segment.
- Mobile Units:Vehicle-mounted alignment bays serve remote fleet locations and emergency roadside service.
- In-Ground Systems:Flush-mounted sensor platforms maximize bay flexibility and minimize trip hazards in high-volume operations.
Revenue concentration: Permanent Installations. White space opportunity: Portable Solutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled automotive technician pools in Germany and the United States anchor the highest-precision service infrastructure. Workshop density in Bavaria and North Rhine-Westphalia concentrates OEM-certified alignment capacity. Fleet operator procurement networks in Texas and California drive standardization requirements across multi-location maintenance facilities.
United States
NHTSA tire safety standards and EPA fuel efficiency regulations compel repair facilities to upgrade from manual gauges to computerized diagnostic platforms. Independent garages in Texas and California represent price-sensitive volume demand, typically selecting 2D laser systems through third-party leasing channels. Fleet operators across the Southwest and Southeast are internalizing alignment services to minimize commercial vehicle downtime.
Germany
OEM-certified service networks require precision alignment infrastructure, with KBA inspection protocols now referencing ISO alignment standards for commercial vehicle roadworthiness. The EU Green Deal and F-Gas Regulation pressure workshops to optimize tire life through precise alignment protocols. Bavaria and North Rhine-Westphalia host the densest concentration of certified equipment procurement through cooperative buying groups.
China
Domestic automotive production expansion generates aftermarket service infrastructure buildout across tier-one cities. GB standards and MIIT regulations establish baseline equipment requirements for commercial vehicle maintenance facilities. Yangtze River Delta and Pearl River Delta industrial clusters concentrate cost-optimized electromechanical system manufacturing for regional distribution.
India
Independent garages in Mumbai and Delhi remain underserved by precision alignment infrastructure, presenting white space for cost-optimized 2D laser configurations. BIS certification requirements are gradually elevating equipment standards beyond legacy manual gauge capabilities. Maharashtra and Gujarat industrial corridors host emerging distributor networks for mid-tier diagnostic platforms.
Netherlands
Logistics operators are building captive alignment bays to minimize commercial vehicle downtime and control service costs across Rotterdam-Antwerp port corridor operations. EU F-Gas Regulation compliance timelines accelerate workshop equipment refresh cycles. Randstad urban concentration drives standardization requirements for multi-location fleet maintenance networks.
Wheel Alignment Equipment Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across divergent technology investment models. The market structure consolidates around three tiers: integrated camera-based platform vendors, modular system specialists, and cost-optimized electromechanical fabricators. Strategic archetypes include premium-tier OEM certification enablers, aftermarket network standardization providers, and emerging market penetration specialists. Dominant competitive moves encompass technology licensing partnerships and geographic distributor consolidation.
Among German-based precision engineering groups, Robert Bosch GmbH and MAHA Maschinenbau Haldenwang GmbH Co. KG occupy positions within the modular system tier, exemplifying European aftermarket network strength. Hunter Engineering Company represents the integrated platform archetype, while Launch Tech Co., Ltd. sits within the cost-optimization segment for price-sensitive repair shop procurement.
| Leading Market Players |
|---|
| Continental AG |
| Robert Bosch GmbH |
| Hunter Engineering Company |
| CEMB Spa |
| Beissbarth Automotive GmbH |
| Snap-on Incorporated |
| Launch Tech Co., Ltd. |
| CORGHI |
| MAHA Maschinenbau Haldenwang GmbH Co. KG |
| Others |
Pricing and Supply Chain Analysis
Fleet operator unbundling of alignment services from comprehensive maintenance contracts is forcing equipment vendors to restructure pricing models and compress supply chain margins to capture direct procurement volume.
Pricing Analysis
Bundled-versus-unbundled service splits now dominate pricing architecture across the wheel alignment equipment landscape. Three-tier pricing structure across premium camera-based systems, standard 2D laser configurations, and economy electromechanical platforms separates OEM-certified dealerships from independent garages. Pricing pressure stems from third-party leasing channels displacing traditional distributor financing among multi-location repair chains. Automotive repair shops in Texas and California exhibit highest price sensitivity through off-balance-sheet equipment access demands, while fleet maintenance operators command volume pricing with lowest sensitivity due to standardization mandates.
Supply Chain Analysis
Workforce availability constraints in Yangtze River Delta and Pearl River Delta manufacturing clusters are elevating production costs for camera module assembly and sensor calibration. High-resolution optical components draw from specialized sensor foundries concentrated in China, South Korea, and Japan. Supply chain risk centers on single-source vulnerability for machine-vision processors subject to export control restrictions. Distribution runs through OEM-certified distributor networks in Germany and cooperative buying groups in Bavaria, alongside third-party leasing channels penetrating US independent garage segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Wheel alignment equipment functions as a stable compounder anchored by NHTSA tire safety standards and EPA fuel efficiency regulations that mandate recurring facility upgrades across US service networks.
For Market Incumbents: Cement market position through backward integration into optical sensor manufacturing to offset East Asian supply concentration risks. Deepen software subscription revenue streams to counter standalone hardware margin compression from third-party leasing channels. Prioritize ISO 9001 certification documentation to capture fleet operator procurement preference for traceability protocols. For New Entrants and Emerging Players: Portable battery-powered measurement units with wireless data transmission offer a technology-first wedge into underserved mobile agricultural and construction equipment services. Target independent garages in Mumbai and Delhi through cost-optimized 2D laser configurations distributed via emerging distributor networks in Maharashtra and Gujarat industrial corridors. Pursue cooperative buying group partnerships to bypass incumbent channel lock-in. For Investors and Strategic Acquirers: Asymmetric upside sits with modular system specialists possessing documented OEM certification pathways and established European aftermarket network presence. Long-term viability rests on recurring software revenue attachment rates rather than hardware shipment volumes. Monitor fleet operator captive bay buildout velocity in Germany and the Netherlands as inflection indicator for equipment standardization demand.| Strategic Initiative | Industry Significance |
|---|---|
| Software Subscription Migration | Recurring revenue attachment to camera-based 3D platforms counters hardware commoditization pressure from leasing channels. |
| Portable Product Line Launch | Battery-powered wireless units penetrate mobile agricultural equipment services with limited incumbent competition. |
| ISO 9001 Certification Investment | Documented traceability protocols unlock fleet operator procurement preference across German logistics networks. |
| Cooperative Buying Group Partnership | Channel consolidation in Bavaria and North Rhine-Westphalia reduces customer acquisition costs for mid-tier entrants. |
| Backward Integration into Optical Sensors | In-house production of high-resolution camera modules mitigates East Asian supply concentration risk. |
Research Methodology
Multiple input streams — primary interviews with fleet maintenance directors and automotive repair shop owners, technical discussions with OEM procurement teams, and distributor channel assessments — were reconciled against secondary validation from NHTSA regulatory filings, EPA fuel efficiency compliance databases, and vehicle production statistics. Equipment manufacturer SEC disclosures and German KBA inspection protocol documentation provided additional triangulation. Bottom-up demand aggregation across end-user segments was cross-checked against top-down market sizing from trade association membership data and industry publication revenue estimates.
Historical shipment patterns were cross-referenced against panel input from service facility operators to establish baseline trajectory assumptions across the projection horizon. Segmentation modeling incorporated product type tiers, end-user procurement authority structures, technology modality preferences, and installation configuration requirements. CAGRs were derived through iterative reconciliation of equipment replacement cycle analysis and regulatory compliance deadline impacts. Forecast inputs included fleet operator internalization timelines and OEM certification mandate expansion patterns.
The model holds under stable regulatory enforcement intensity and intact supply chain configurations; deviation in NHTSA standard revision timing or optical component export restrictions would shift equipment refresh cycle assumptions. Practitioners should monitor KBA protocol amendment proposals and East Asian sensor foundry capacity announcements for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Testing and Simulation
Transportation Predictive Analytics and Simulation Market
Automotive Testing and Simulation
Automotive Crash Test Dummies Market
Automotive Testing and Simulation
Vehicle Crash Testing Services Market
Automotive Testing and Simulation
Automotive Simulation Software Market
Automotive Testing and Simulation
Tire Testing Machine Market
Automotive Testing and Simulation
Automotive Emission Analyzer Market
Automotive Testing and Simulation
Commercial Vehicle and Off-Highway RADAR Market
Automotive Testing and Simulation
Vehicle Crash Testing System Market
Automotive Testing and Simulation
Electric Vehicle Test Equipment Market
Automotive Testing and Simulation
Automotive Diagnostic Tools Market
Automotive Testing and Simulation
Vehicle Testing Equipment Market
Automotive Testing and Simulation
Automotive Chassis Dynamometer Market
Automotive Testing and Simulation
Automotive on-Board Diagnostics Market
Automotive Testing and Simulation
Rail Track and Rolling Stock Advanced NDT Inspection Systems Market
Automotive Testing and Simulation
Vehicle Chassis Dynamometers Market
Automotive Testing and Simulation
High-Speed Highway Pilot and Lane Change Scenario Test Platforms Market