
 Transportation Predictive Analytics and Simulation Market | 2026-2036
Transportation Predictive Analytics and Simulation Market Size, Share, and Industry Trends Forecast 2026-2036
Transportation Predictive Analytics and Simulation Market Outlook
The capital-intensity divergence between cloud-native specialists and legacy infrastructure incumbents is redrawing competitive boundaries in transportation analytics. IBM Corporation leverages its hybrid cloud architecture to anchor large government contracts requiring sovereign data residency. Siemens AG specializes in physics-based simulation layers that dominate rail and roadway digital twin deployments.
Transportation predictive analytics and simulation encompasses algorithmic systems that process historical and real-time mobility data through machine learning pipelines and discrete-event simulation engines to forecast traffic flows, asset degradation, and network congestion with quantified confidence intervals. The primary industrial purpose centers on reducing operational uncertainty for capital-intensive infrastructure and vehicle fleets. Machine learning applications now capture the largest margin pools as freight operators prioritize predictive maintenance over reactive scheduling. Simulation tools represent the fastest-expanding segment as urban planners model autonomous vehicle penetration scenarios.
The Federal Highway Administration's guidance on real-time system management information and the EU AI Act's conformity assessment requirements for transport-critical algorithms are tightening product standards and reshaping vendor qualification pathways. The EPA's emissions modeling mandates for fleet compliance reporting further amplify demand for integrated simulation platforms. Stakeholders must monitor how emerging algorithmic auditing obligations in California and Germany will reshape procurement specifications and R&D allocation priorities.
Market Dynamics
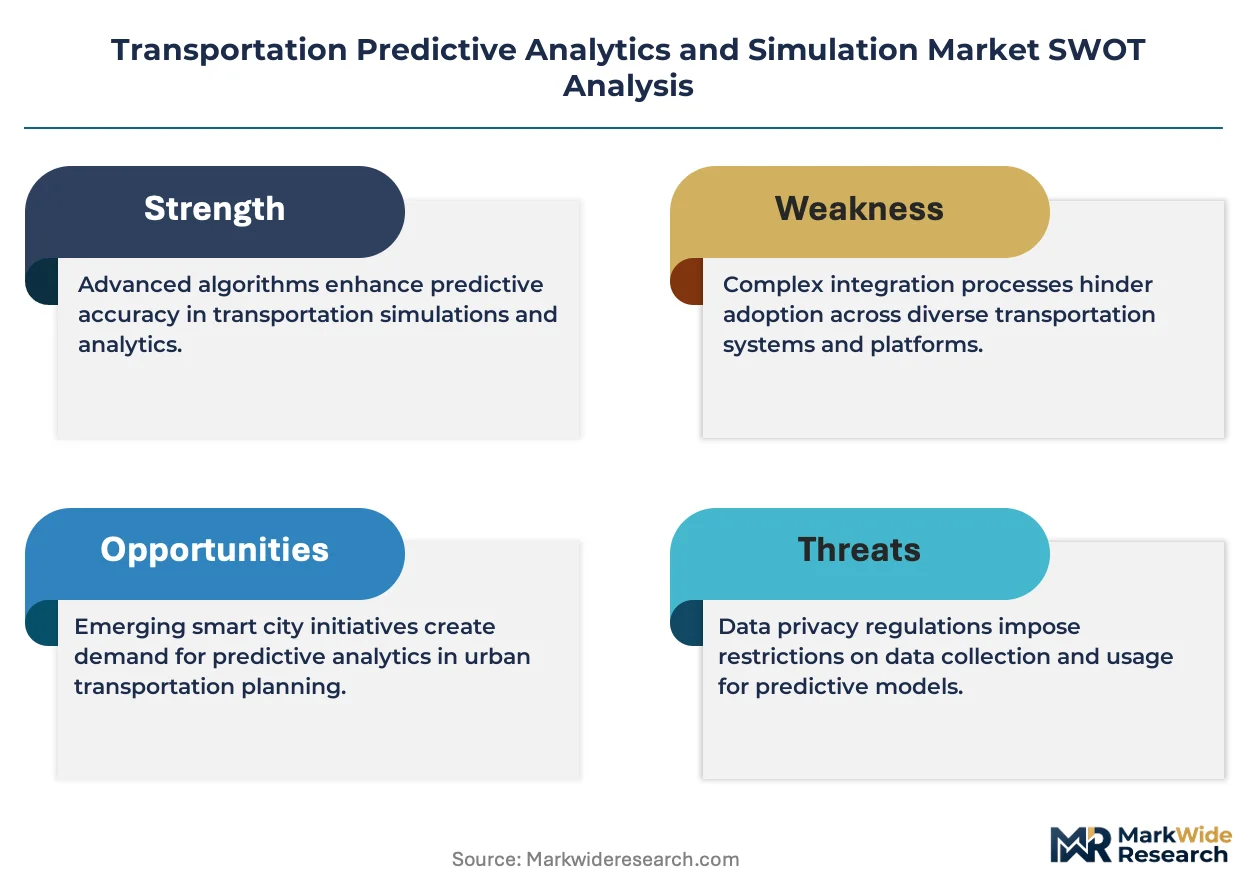
The EU AI Act's risk-based classification system for algorithmic decision-making is compressing vendor qualification timelines and forcing predictive analytics providers to restructure product architectures around conformity assessment requirements.
Growth Catalysts
- Fleet predictive maintenance mandates:Freight operators across North American freight corridors are expanding adoption of cloud-native platforms that forecast asset degradation before failure events interrupt corridor throughput.
- Digital twin co-development:Automotive OEMs and railway operators in Germany are building multimodal logistics networks that integrate physics-based simulation layers with real-time sensor feeds.
- EPA emissions modeling requirements:Fleet compliance reporting obligations are amplifying demand for integrated simulation platforms that unify predictive maintenance with regulatory documentation workflows.
Market Restraints
- Data sovereignty infrastructure costs:Government contracts requiring sovereign data residency force vendors to maintain redundant cloud architectures, elevating operational overhead relative to pure-cloud competitors.
- Algorithmic audit preparation burdens:California's emerging algorithmic auditing obligations are extending sales cycles as procurement teams await clarity on technical documentation standards.
- Legacy system integration friction:Incumbent transportation management systems built on decades-old architectures resist API-based connectivity, constraining deployment velocity for modern predictive platforms.
Strategic Opportunities
- Autonomous vehicle penetration modeling:Urban planners in Singapore and Dubai are commissioning simulation tools that model mixed-fleet scenarios, creating demand for new scenario-generation capabilities.
- Cross-modal cargo visibility:Port authorities and intermodal terminals seek unified platforms that correlate rail, roadway, and maritime predictive signals into single operational views.
- Physics-ML convergence:Vendors combining discrete-event simulation engines with neural network architectures can capture premium positioning in rail and roadway digital twin deployments.
Industry Challenges
- Simulation engineer scarcity:The specialized workforce capable of calibrating physics-based models against empirical traffic data remains concentrated among defense and aerospace contractors.
- ISO 26262 functional safety certification:Automotive-grade predictive systems require extensive documentation of failure modes and diagnostic coverage, extending development timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Transportation Predictive Analytics and Simulation Market |
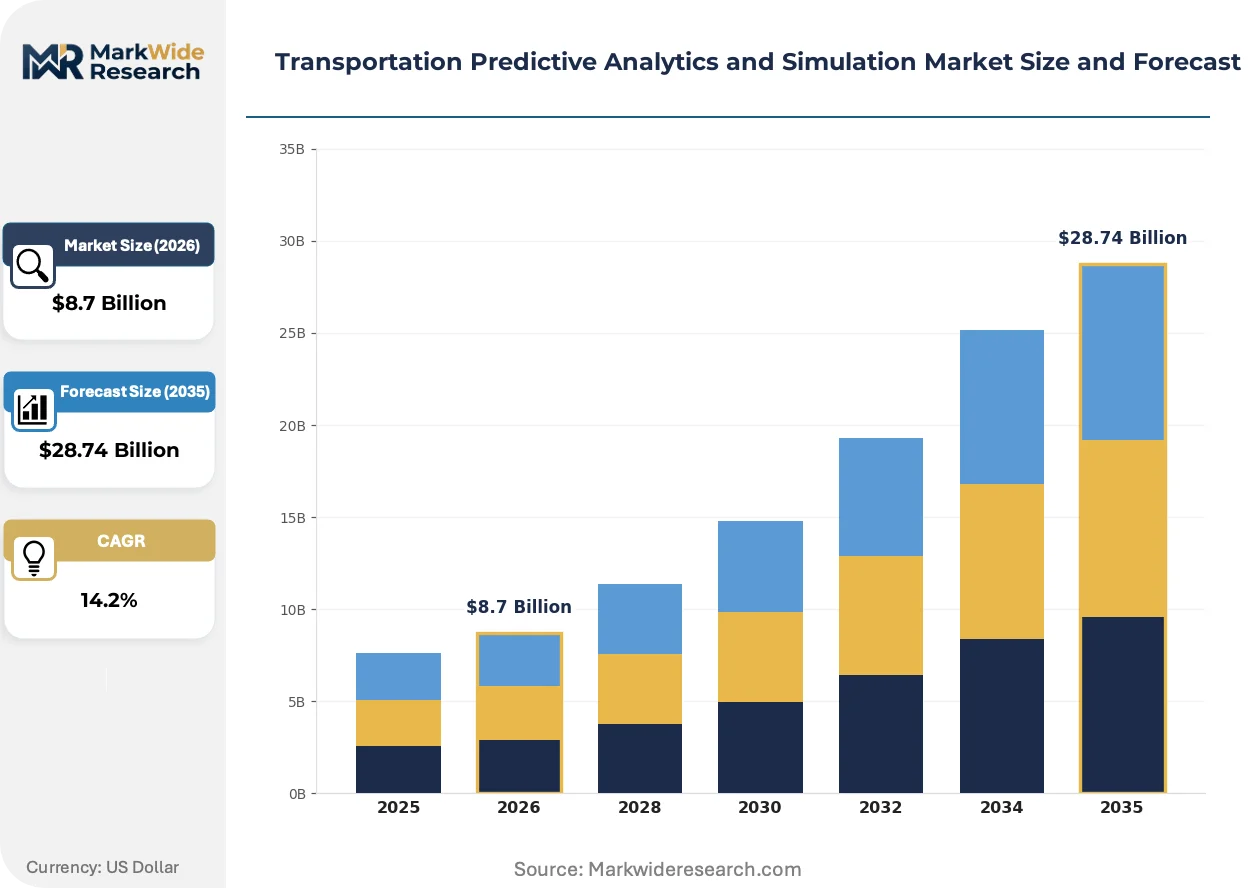
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Machine Learning, Data Mining, Simulation Tools, Predictive Modeling Application: Traffic Management, Fleet Optimization, Public Transportation, Infrastructure Planning End User: Government Agencies, Logistics Providers, Transportation Companies, Research Institutions Deployment: Cloud-based, On-Premise, Hybrid, SaaS |
| Companies Covered | IBM Corporation, SAP AG, Siemens AG, Oracle Corporation, PTV Group, Cubic Corporation, INRIX, Trimble Inc., SAS Institute Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Transportation Predictive Analytics and Simulation Market Strategic Shifts
Edge computing architectures are redistributing computational load across transportation networks, enabling real-time inference at sensor locations previously dependent on centralized cloud processing.
Digital twin technology is miniaturizing from corridor-scale deployments to individual vehicle and infrastructure asset models. Fleet operators are adopting these granular simulations to isolate component-level failure propagation paths. The compression of model scope is miniaturizing hardware requirements and expanding addressable use cases to mid-size operators previously priced out of enterprise platforms.
The EU AI Act's conformity assessment framework for transport-critical algorithms is mandating third-party validation of machine learning pipelines. Vendors must now maintain audit trails documenting training data provenance and model drift metrics. European railway operators are responding by consolidating procurement around providers with pre-certified quality management systems.
Buyers are unbundling software licenses from implementation services, treating predictive analytics as composable infrastructure rather than turnkey solutions. Large freight operators are assembling internal data science teams to customize open-source simulation kernels. This capability-building is most visible in Germany and the Netherlands, where logistics firms compete for talent against automotive and aerospace employers.
Transportation Predictive Analytics and Simulation Market Segmentation
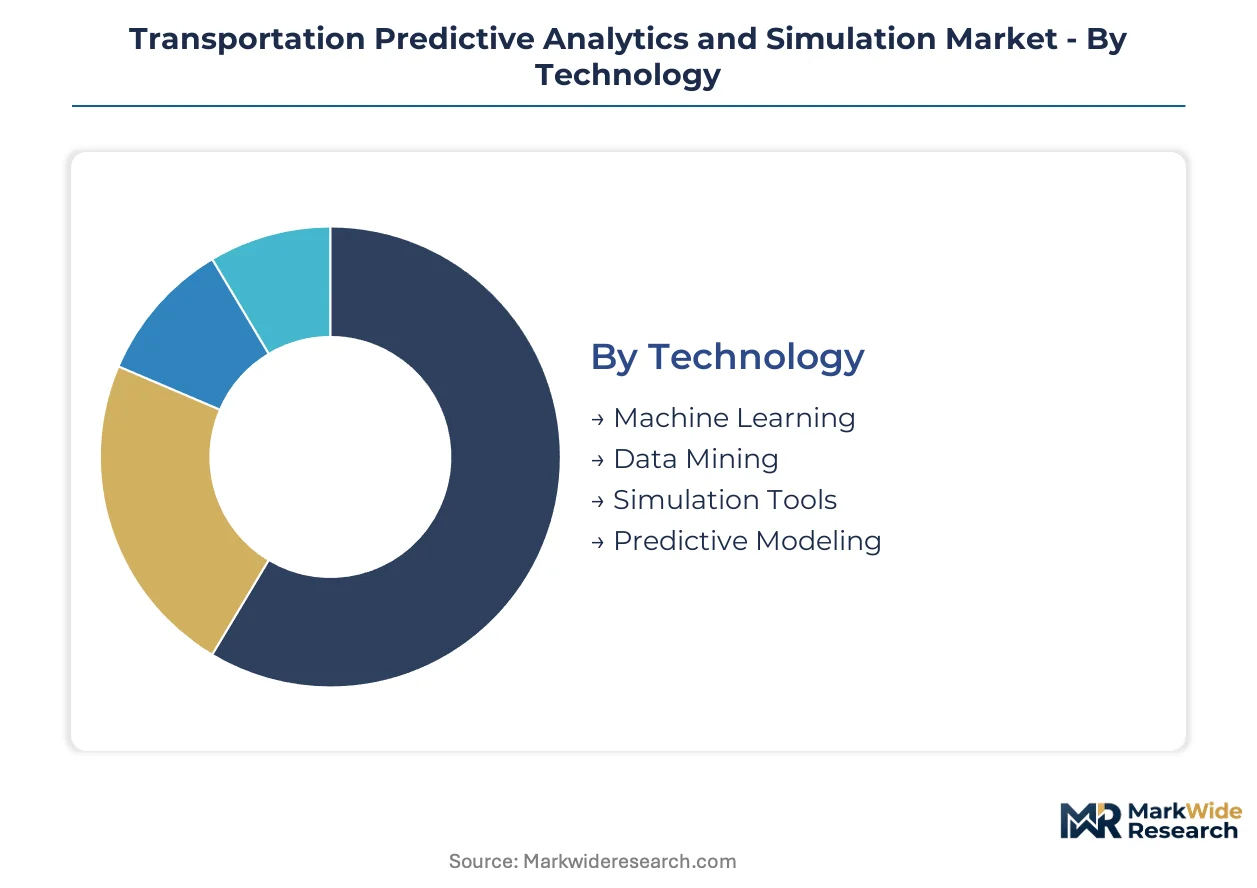
Technology choice determines regulatory exposure and margin structure in transportation analytics. Vendors architect platforms around specific compliance frameworks, while buyers segment procurement by functional safety requirements and data sovereignty obligations.
Technology:
The EU AI Act's risk-based classification system creates divergent compliance burdens across algorithmic approaches, compressing qualification timelines for transport-critical applications.
- Machine Learning:Neural network architectures process historical and real-time mobility data through supervised learning pipelines to forecast asset degradation and network congestion. Freight operators in Germany prioritize these platforms for predictive maintenance, driven by ISO 26262 functional safety mandates and automotive OEM procurement specifications.
- Simulation Tools:Discrete-event engines model traffic flows, autonomous vehicle penetration scenarios, and multimodal logistics networks with physics-based precision. Urban planners in Singapore and Dubai commission these tools for mixed-fleet scenario generation, responding to infrastructure investment cycles and smart city funding allocations.
- Data Mining:Pattern recognition systems extract operational intelligence from legacy transportation management databases.
- Predictive Modeling:Statistical frameworks quantify confidence intervals for capacity planning and demand forecasting.
Established volume favors Machine Learning; emerging adoption favors Simulation Tools.
Application:
Deployment scale and integration complexity separate enterprise-grade implementations from pilot programs.
- Fleet Optimization:Cloud-native platforms unify predictive maintenance, route planning, and emissions compliance reporting into single operational views. Logistics providers across North American freight corridors expand adoption, responding to EPA modeling mandates and corridor throughput guarantees.
- Traffic Management:Real-time inference systems process sensor feeds to forecast congestion and adjust signal timing. Government agencies in the United States deploy these under Federal Highway Administration guidance, requiring sovereign data residency for interstate corridor contracts.
- Public Transportation:Ridership forecasting and service scheduling algorithms optimize rail and bus network utilization.
- Infrastructure Planning:Long-horizon simulation models evaluate capital project returns against demographic and mobility projections.
Procurement concentration favors Fleet Optimization; regulatory tailwinds favor Traffic Management.
End User:
Contract structure and technical capability determine whether buyers seek turnkey solutions or composable infrastructure.
- Logistics Providers:Freight operators assemble internal data science teams to customize open-source simulation kernels, unbundling software licenses from implementation services. German and Dutch firms compete for talent against automotive and aerospace employers, building proprietary predictive capabilities.
- Government Agencies:Sovereign data residency requirements force vendors to maintain redundant cloud architectures, elevating operational overhead and favoring hybrid cloud specialists for large infrastructure contracts.
- Transportation Companies:Rail and roadway operators co-develop digital twin networks with automotive OEMs.
- Research Institutions:Academic consortia calibrate physics-based models against empirical traffic data.
Capability building favors Logistics Providers; procurement scale favors Government Agencies.
Deployment:
Capital intensity and operational control trade off across architecture choices.
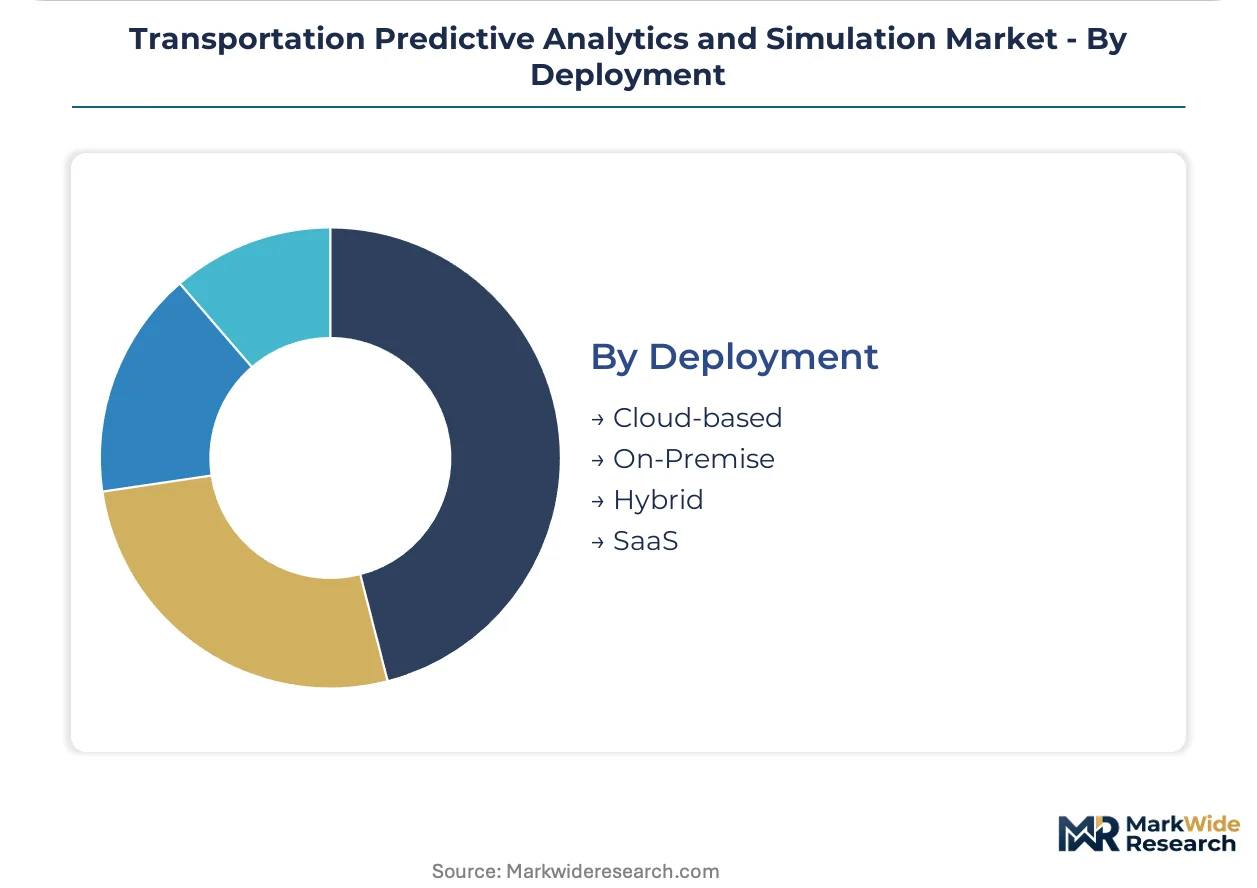
- Cloud-based:Centralized processing enables rapid scaling and reduced hardware capital for mid-size operators previously priced out of enterprise platforms. Fleet operators favor these deployments where data sovereignty constraints permit.
- Hybrid:Edge computing architectures redistribute computational load across transportation networks, enabling real-time inference at sensor locations. Railway operators in Germany consolidate procurement around providers with pre-certified quality management systems under EU AI Act conformity assessment frameworks.
- On-Premise:Dedicated infrastructure satisfies classified or critical safety system requirements.
- SaaS:Subscription pricing lowers entry barriers for pilot programs and seasonal demand patterns.
Margin compression favors Cloud-based; compliance premiums favor Hybrid.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany and the United States show the lowest price elasticity, absorbing premium pricing for compliance-certified platforms. Southeast Asian logistics operators remain the most price-sensitive segment, driving demand for cloud-native deployments with reduced implementation overhead.
United States
Fleet operators across the I-95 and I-10 freight corridors are expanding predictive maintenance platform adoption. The EPA's emissions modeling mandates for fleet compliance reporting amplify demand for integrated simulation platforms. Chicago and Dallas-Fort Worth anchor the densest concentration of logistics providers building internal data science capabilities.
Germany
Automotive OEMs and railway operators in Baden-Württemberg and Bavaria co-develop multimodal digital twin networks. The EU AI Act's conformity assessment requirements compress vendor qualification timelines and reshape procurement specifications. Stuttgart and Munich host the primary clusters of physics-based simulation engineering talent.
Singapore
Urban planners commission simulation tools modeling autonomous vehicle penetration in mixed-fleet scenarios. The Land Transport Authority's smart city funding allocations prioritize infrastructure investment cycles with embedded predictive analytics. The Jurong Lake District and Punggol Digital District serve as testbeds for edge computing architectures in traffic management.
China
Port authorities in Shanghai and Shenzhen seek unified platforms correlating rail, roadway, and maritime predictive signals. MIIT standards on intelligent transportation systems tighten product certification requirements for algorithmic decision-making tools. The Yangtze River Delta concentrates the largest deployment of corridor-scale digital twin networks.
Netherlands
Logistics firms in Rotterdam and Amsterdam compete for data science talent against automotive and aerospace employers. The CSRD's sustainability reporting obligations extend to fleet emissions forecasting, amplifying demand for predictive modeling tools. The Randstad region anchors Europe's densest concentration of unbundled software procurement from implementation services.
Transportation Predictive Analytics and Simulation Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier in transportation predictive analytics. Hybrid cloud architects and physics-based simulation specialists occupy distinct competitive lanes with limited direct overlap. Three archetypes dominate: infrastructure-scale platform providers, compliance-certified system integrators, and open-source simulation kernel specialists. Strategic consolidation through vertical technology acquisitions and geographic expansion into sovereign data residency markets represent the primary competitive moves.
Within the infrastructure-scale tier, IBM Corporation exemplifies hybrid cloud positioning for government contracts requiring sovereign data residency. Siemens AG anchors the physics-based simulation specialist segment with rail and roadway digital twin deployments. SAP AG occupies a position bridging enterprise resource planning integration with predictive maintenance workflows for freight operators.
| Leading Market Players |
|---|
| IBM Corporation |
| SAP AG |
| Siemens AG |
| Oracle Corporation |
| PTV Group |
| Cubic Corporation |
| INRIX |
| Trimble Inc. |
| SAS Institute Inc. |
| Others |
Value Chain & Pricing Dynamics
Long-term SaaS capacity reservation contracts lock in both supply access and price visibility for freight operators across North American freight corridors, insulating vendors from spot-market volatility while embedding EU AI Act compliance costs into baseline pricing. These structures concentrate procurement power among logistics providers with sovereign data residency requirements, compressing margins for pure-cloud competitors unable to absorb redundant infrastructure overhead.
Pricing Analysis
After-sales revenue from predictive maintenance service contracts and algorithmic audit documentation drives lifetime value beyond initial software licensing. Three-tier pricing structure across premium, standard, and economy levels segments by ISO 26262 certification grade and data sovereignty architecture, with German automotive OEMs absorbing premium tiers for functional safety compliance. Pricing pressure stems from unbundling trends as logistics providers assemble internal data science teams to customize open-source simulation kernels. Southeast Asian operators exhibit highest price sensitivity, while buyers in Germany and the United States show lowest elasticity for compliance-certified platforms.
Supply Chain Analysis
Extended lead times for GPU accelerators and edge computing hardware constrain deployment velocity for real-time inference systems. Component manufacturing concentrates in Taiwan, South Korea, and the United States for specialized semiconductors, while cloud infrastructure provisioning draws from hyperscaler data center networks in Germany, Singapore, and the United States. Supply chain risk centers on single-source vulnerability for physics-based simulation engineering talent concentrated among defense and aerospace contractors. Distribution runs through direct enterprise sales teams for government contracts and channel partners for mid-size fleet operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a service-attach opportunity where recurring revenue from predictive maintenance contracts and algorithmic compliance documentation expands faster than perpetual software licensing. Vendors must architect offerings around ongoing calibration and audit-trail maintenance rather than upfront implementation fees.
For Market Incumbents: Consolidate procurement relationships with European railway operators by pre-certifying quality management systems under EU AI Act conformity assessment frameworks. Acquire specialized simulation engineering talent from defense contractors to address capability scarcity in physics-based model calibration. Deepen backward integration into edge computing hardware to reduce hyperscaler dependency and defend margin position against cloud-native entrants.
For New Entrants and Emerging Players: Lead with open-source simulation kernel customization services targeting mid-size logistics providers in the Netherlands and Germany competing for data science talent. Penetrate the autonomous vehicle penetration modeling segment for urban planners in Singapore and Dubai, where smart city funding allocations prioritize scenario-generation capabilities. Position around rapid deployment velocity and reduced implementation overhead versus legacy system integration friction.
For Investors and Strategic Acquirers: Capital is best deployed toward hybrid cloud specialists with pre-existing sovereign data residency architectures and compliance-certified quality management systems. Long-term viability hinges on vendors' ability to maintain audit trails documenting training data provenance and model drift metrics across the analysis window. Monitor consolidation signals among European railway operators as procurement teams await clarity on California's emerging algorithmic auditing technical documentation standards.
| Strategic Initiative | Industry Significance |
|---|---|
| Physics-ML Convergence Development | Combines discrete-event simulation with neural networks for premium rail and roadway digital twin positioning. |
| EU AI Act Pre-Certification Investment | Compresses vendor qualification timelines and reshapes procurement specifications for transport-critical algorithms. |
| Edge Computing Architecture Deployment | Enables real-time inference at sensor locations across German railway networks and Singapore traffic management. |
| Simulation Engineering Talent Acquisition | Addresses workforce scarcity concentrated among defense contractors for physics-based model calibration. |
| Cross-Modal Cargo Visibility Platform Launch | Unifies rail, roadway, and maritime predictive signals for port authorities in Shanghai and Shenzhen. |
Study Parameters
A standing panel of fleet operations directors, predictive maintenance platform engineers, EU regulatory compliance officers, and smart city infrastructure planners provided ongoing calibration across the study period. Primary interviews with these stakeholders combined with secondary validation against SEC filings from listed vendors, EPA emissions modeling guidance documents, EU AI Act conformity assessment frameworks, and Federal Highway Administration real-time system management directives. Bottom-up segment sizing triangulated against top-down market aggregation across technology, application, end user, and deployment dimensions.
Consistency checks validated volume and value outputs against external benchmarks including hyperscaler transportation vertical revenue disclosures and automotive OEM digital twin investment announcements. The analytical framework modeled machine learning, simulation tools, data mining, and predictive modeling technologies across fleet optimization, traffic management, public transportation, and infrastructure planning applications. CAGRs derived from logistic diffusion curves for autonomous vehicle penetration scenarios and capital expenditure cycles for multimodal logistics networks.
The analysis sits within stated boundaries; outcomes outside sustained EPA emissions enforcement, EU AI Act implementation timelines, or smart city funding allocation continuity would require recalibration. Forecasts reflect documented assumptions regarding algorithmic auditing obligation expansion and physics-based simulation talent mobility. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Testing and Simulation
On Board Diagnostics Device Market
Automotive Testing and Simulation
Vehicle Radar Test System Market
Automotive Testing and Simulation
Rail Track and Rolling Stock Advanced NDT Inspection Systems Market
Automotive Testing and Simulation
Automotive TIC Market
Automotive Testing and Simulation
Automotive Chassis Dynamometer Market
Automotive Testing and Simulation
Chassis Dynamometers Market
Automotive Testing and Simulation
Vehicle Emission Testers Market
Automotive Testing and Simulation
Car Crash Simulator Systems and Services Market
Automotive Testing and Simulation
Automotive Diagnostic Tools Market
Automotive Testing and Simulation
ADAS Calibration and Alignment Equipment Systems Market
Automotive Testing and Simulation
Electric Vehicle Edrive Test Equipment Market
Automotive Testing and Simulation
Electric Vehicle Test Bench Market
Automotive Testing and Simulation
Driving Simulator Market
Automotive Testing and Simulation
Dynamometer Market
Automotive Testing and Simulation
Vehicle Crash Testing Services Market
Automotive Testing and Simulation
Wheel Alignment Equipment Market