
 Electric Vehicle Test Equipment Market | 2026-2036
Electric Vehicle Test Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Vehicle Test Equipment Market Analysis
ISO 6469-1 qualification for high-voltage battery safety is unwinding the competitive landscape for entry-level equipment vendors. Keysight Technologies leverages its RF measurement heritage to dominate electromagnetic compatibility validation for next-generation inverters. Chroma ATE Inc. anchors its position through backward integration into power electronics, supplying both test systems and the semiconductor loads they require. AVL List GmbH competes by sustaining deep relationships with European premium automakers that demand turnkey powertrain test cells.
Electric vehicle test equipment comprises specialized instrumentation for validating battery electrochemistry, electric motor torque maps, onboard charger efficiency, and high-voltage isolation integrity under thermal cycling and vibration profiles. Its primary purpose is ensuring that powertrain components meet OEM durability targets and regulatory safety thresholds before series production. Battery testers capture the largest margin pool as cell chemistry diversity expands, while charging testers represent the fastest-growing segment due to interoperability demands across CCS, CHAdeMO, and GB/T protocols. Automated testing technology is displacing manual protocols in manufacturing lines, though research and development applications still require manual intervention for root-cause failure analysis.
The EPA tailpipe standards and NHTSA FMVSS 305 high-voltage safety rules shape what equipment North American labs must deploy, while China's GB/T standards and MIIT new-energy vehicle catalog requirements dictate test sequences for domestic manufacturers. ECE R100 from the United Nations Economic Commission for Europe governs battery thermal propagation testing that European and Asian regulators increasingly reference. Stakeholders must decide whether to build multi-protocol platforms that span regional standards or specialize in single-jurisdiction compliance workflows.
Market Dynamics
Automakers are consolidating validation workflows around unified battery-electronics test platforms, collapsing the traditional separation between cell cycling and power electronics qualification into single-vendor relationships.
Growth Catalysts
- ECE R100 thermal propagation mandates:European and Asian regulators now require documented battery failure containment, forcing OEMs to upgrade thermal imaging and abuse testing infrastructure.
- Cell chemistry diversification:LFP, NMC, and solid-state formats each demand distinct formation protocols, multiplying the test equipment installed base per gigafactory.
- China's Ningbo-Shenzhen corridor:Domestic EV brands operate captive facilities that source equipment locally, creating sustained demand concentration independent of export markets.
Market Restraints
- Semiconductor load scarcity:IGBT and SiC module shortages constrain power electronics test bench deliveries, extending lead times for high-voltage inverter validation systems.
- Single-source dependency:Precision current sensors and cryogenic contactors concentrate among German and Japanese component suppliers, exposing equipment builders to geographic supply risk.
- Protocol fragmentation:CCS, CHAdeMO, and GB/T charging standards require distinct communication stacks, forcing multi-million-dollar hardware redundancy for global platform coverage.
Strategic Opportunities
- India's PLI scheme for cell manufacturing:Domestic battery production incentives are attracting test equipment vendors to establish local calibration and service presence ahead of capacity ramp.
- Second-life battery grading:End-of-life EV packs require electrochemical characterization for stationary storage redeployment, opening aftermarket test service revenue streams.
- Wireless power transfer validation:Inductive charging interoperability standards are creating demand for electromagnetic field mapping equipment absent from legacy DC test portfolios.
Industry Challenges
- High-voltage safety certification timelines:ISO 6469-1 and ECE R100 qualification cycles extend 18-24 months, compressing equipment vendor R&D windows between standard revisions.
- Multiphysics simulation integration:Coupling electrochemical-thermal-mechanical models with physical test hardware requires scarce cross-disciplinary engineering talent combining battery science and controls expertise.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Vehicle Test Equipment Market |
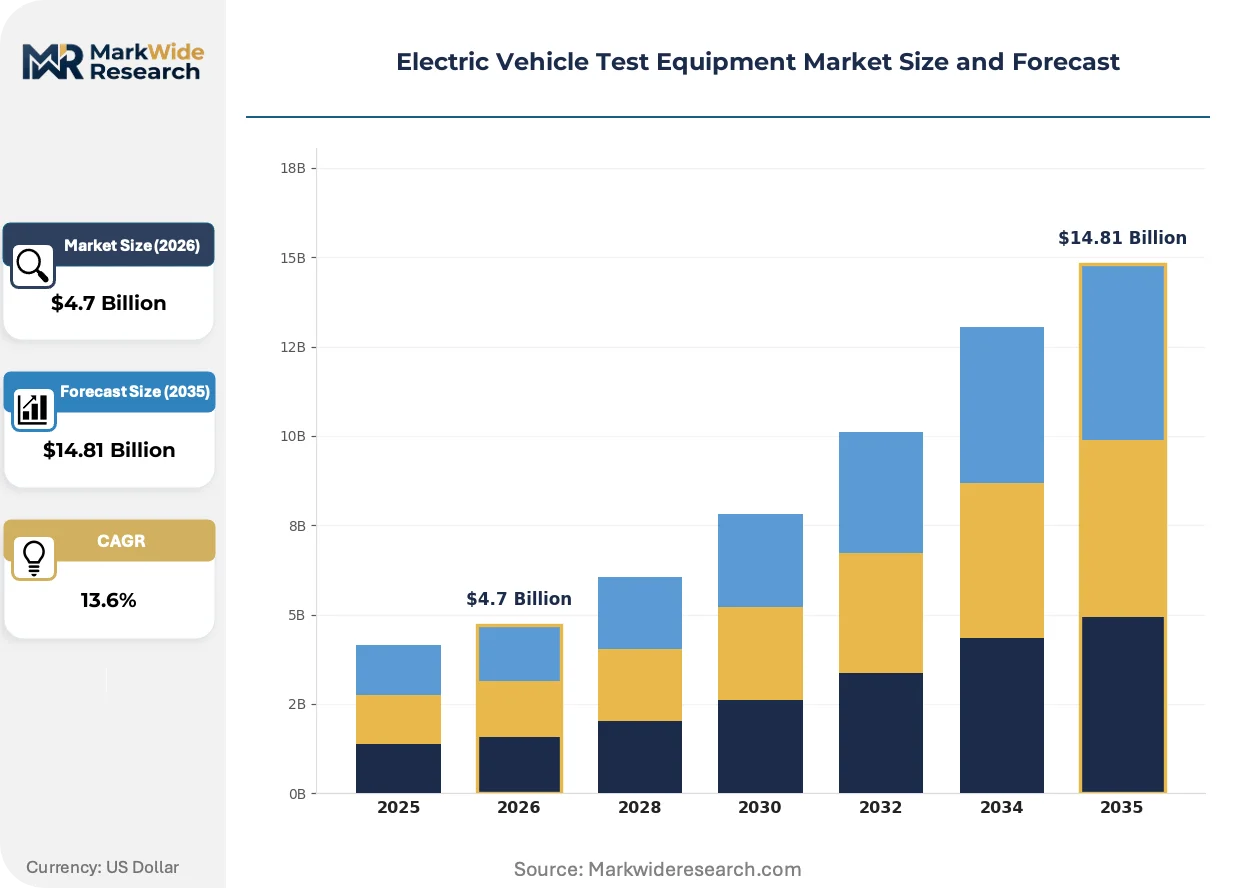
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $14.81 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Battery Testers, Power Train Testers, Charging Testers, Safety Testers Application: Manufacturing, Research and Development, Quality Assurance, Compliance Testing Technology: Dynamic Testing, Static Testing, Automated Testing, Manual Testing End User: Automakers, Tier-1 Suppliers, Testing Laboratories, Aftermarket Providers |
| Companies Covered | Keysight Technologies, National Instruments, AVL List GmbH, Rohde & Schwarz, Chroma ATE Inc., TÜV Rheinland, Ametek Inc., Kikusui Electronics Corporation, Horiba Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Vehicle Test Equipment Market Emerging Trajectories
Test equipment architectures are converging around software-defined instrumentation that decouples measurement hardware from protocol-specific firmware, enabling faster reconfiguration across evolving standards.
Modular battery cyclers with swappable channel cards are fragmenting the traditional monolithic tester market. Cell manufacturers in South Korea and China now specify 5-10 channel increments rather than 100-channel fixed cabinets, allowing capacity to scale with production ramp. This granularity is compressing average contract values while expanding addressable unit volumes.
The EPA's tightened tailpipe standards and NHTSA FMVSS 305 high-voltage safety rules are mandating more granular state-of-charge validation across temperature extremes. North American labs must now deploy thermal chambers capable of -40°C to 85°C cycling with simultaneous vibration input. Equipment vendors are responding with integrated environmental-structural-electrical test cells previously sold as separate systems.
Automotive procurement teams are unbundling test equipment ownership from maintenance contracts, favoring performance-based service agreements where vendors guarantee uptime and calibration compliance. Tier-1 suppliers in Germany and Japan now specify outcome metrics—mean time between failures, traceability audit readiness—rather than hardware specifications alone. This shift is visible most acutely in powertrain validation centers where downtime costs exceed equipment depreciation.
Electric Vehicle Test Equipment Market Segmentation
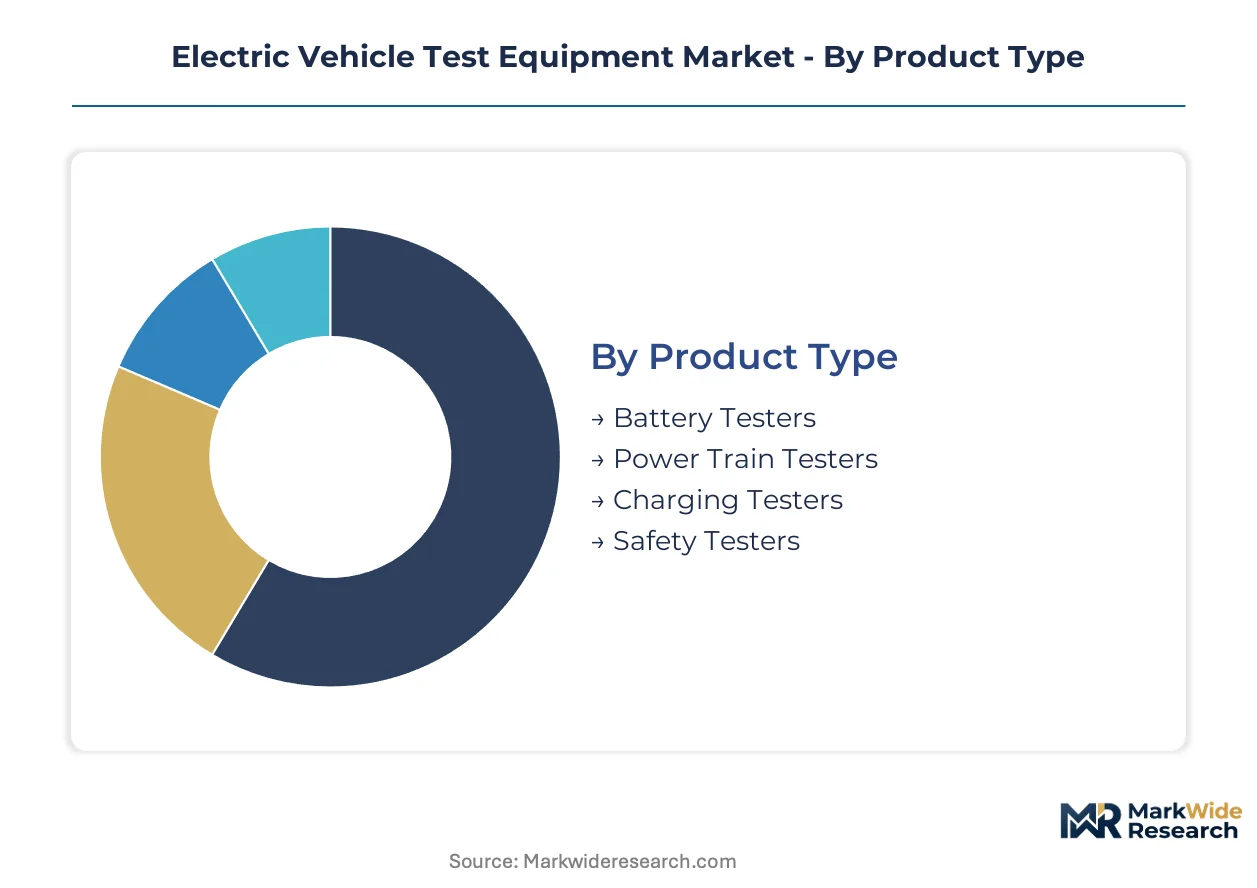
Segmentation reveals how regulatory mandates and manufacturing workflows fragment demand across distinct equipment categories. Test equipment vendors must align product architectures with the specific validation protocols each segment requires.
Product Type:
ECE R100 thermal propagation testing and EPA tailpipe standards impose divergent hardware requirements across product categories, with battery safety mandates commanding the most capital-intensive instrumentation.
- Battery Testers:These systems validate cell electrochemistry, thermal runaway containment, and cycle life under ISO 6469-1 protocols. Demand concentrates in China's Ningbo-Shenzhen corridor where CATL and BYD operate captive gigafactory labs. Cell chemistry diversification between LFP and NMC formats forces parallel equipment installations per facility.
- Charging Testers:Equipment validates CCS, CHAdeMO, and GB/T protocol interoperability across power levels from 7kW AC to 350kW DC. European automakers in Germany source these systems to meet ECE R100 electromagnetic compatibility requirements for next-generation inverters.
- Power Train Testers:Systems map electric motor torque curves and inverter efficiency across thermal profiles. Tier-1 suppliers deploy these for power electronics qualification before OEM integration.
- Safety Testers:High-voltage isolation and ground fault detection equipment ensures FMVSS 305 compliance for North American market entry.
Battery testers handle the majority of throughput; charging testers are expanding most quickly on share.
Application:
Cost tier differentiation separates high-volume manufacturing validation from low-volume R&D instrumentation, with procurement patterns diverging sharply on automation requirements and calibration frequency.
- Manufacturing:Automated inline testing systems perform 100% production validation with cycle times under 90 seconds. South Korean cell plants specify modular channel configurations that scale from 5 to 500 channels.
- Research and Development:Manual-intervention protocols dominate root-cause failure analysis where engineers require flexible test parameter adjustment. European premium automakers maintain dedicated R&D cells separate from production lines.
- Quality Assurance:Statistical sampling protocols validate batch consistency for outgoing shipment certification.
- Compliance Testing:Third-party laboratories perform homologation testing against ECE R100, GB/T, and FMVSS 305 standards for market access documentation.
Manufacturing absorbs the greatest installed base; compliance testing shows the steepest expansion trajectory as regulatory scope widens.
Technology:
Volume concentration favors automated platforms in high-throughput environments, while manual systems retain share in failure analysis where human diagnostic judgment remains irreplaceable.
- Automated Testing:Software-defined instrumentation decouples measurement hardware from protocol-specific firmware, enabling rapid reconfiguration across evolving standards. China's domestic EV brands deploy these systems for 24/7 production line operation.
- Dynamic Testing:Real-time electrochemical-thermal-mechanical coupling simulates drive cycle loads on battery packs under vibration and temperature cycling.
- Static Testing:Stationary capacity measurement and impedance spectroscopy characterize cell formation without mechanical stress inputs.
- Manual Testing:Engineer-operated protocols persist in root-cause analysis where automated systems cannot replicate diagnostic reasoning.
Automated testing commands the dominant share; dynamic testing is gaining share fastest as multiphysics simulation integration advances.
End User:
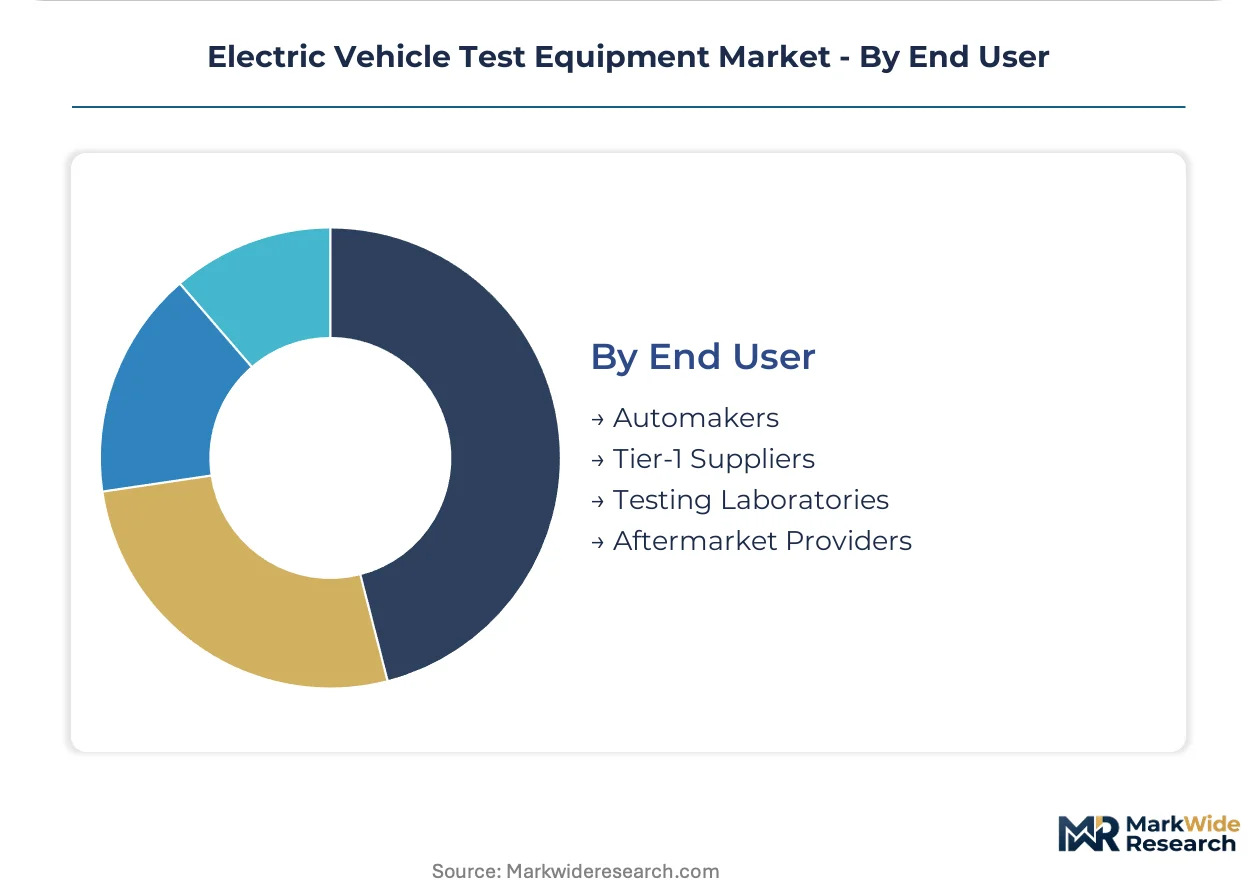
Customer type determines procurement sophistication, with automakers demanding turnkey powertrain test cells while aftermarket providers seek portable diagnostic equipment.
- Automakers:German OEMs specify integrated environmental-structural-electrical test cells previously purchased as separate systems, consolidating validation around unified battery-electronics platforms.
- Tier-1 Suppliers:Power electronics specialists in Japan and Germany source equipment under performance-based service agreements where vendors guarantee uptime metrics rather than hardware specifications alone.
- Testing Laboratories:Independent validation centers require multi-protocol platforms spanning CCS, CHAdeMO, and GB/T standards for global OEM clientele.
- Aftermarket Providers:Second-life battery grading operations demand portable electrochemical characterization systems for stationary storage redeployment.
Automakers represent the largest equipment purchaser; aftermarket providers are climbing the fastest as circular economy regulations mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive OEMs with captive validation labs concentrate equipment procurement in three distinct manufacturing corridors, each governed by divergent regulatory frameworks and local supplier ecosystems.
China
Domestic EV brands in Ningbo and Shenzhen operate integrated test facilities that source equipment locally, bypassing import dependencies. MIIT catalog requirements and GB/T standards dictate validation sequences for battery systems and charging interfaces. CATL and BYD anchor captive gigafactory labs where cell chemistry diversification between LFP and NMC formats drives parallel equipment installations.
Germany
Premium automakers expand in-house validation capacity to meet ECE R100 thermal propagation mandates for battery safety. KBA enforcement of UN regulations accelerates upgrade cycles for thermal imaging and abuse testing infrastructure. Bavaria and Baden-Württemberg host concentrated powertrain development centers where turnkey test cell procurement dominates vendor relationships.
United States
EPA tailpipe standards and NHTSA FMVSS 305 high-voltage safety rules shape lab equipment specifications for North American market entry. Michigan and California anchor validation operations where Tier-1 suppliers deploy integrated environmental-structural-electrical test cells. Modular procurement patterns favor performance-based service agreements over hardware ownership.
Japan
METI industrial policy supports domestic equipment manufacturing for power electronics validation. Precision current sensor supply chains concentrate among component specialists serving Tokyo and Nagoya industrial zones. Toyota and Honda maintain dedicated R&D cells separate from production lines, sustaining demand for manual-intervention protocols in root-cause analysis.
South Korea
Cell manufacturers specify modular battery cyclers with swappable channel cards, scaling from 5 to 500 channels per facility. MFDS alignment with international battery safety standards streamlines export validation workflows. Seoul and Busan manufacturing corridors drive demand for automated inline testing systems with sub-90-second cycle times.
Electric Vehicle Test Equipment Market Vendor Landscape
Player mix skews toward diversified instrumentation conglomerates with adjacent RF and power electronics heritage, supplemented by specialized automotive engineering houses and captive testing service providers. Market structure exhibits tiered concentration: a narrow premium segment serves European OEM turnkey requirements, a broad mid-market addresses Asian cell manufacturer modularity demands, and a fragmented base supplies aftermarket diagnostic equipment. Strategic archetypes include measurement heritage players leveraging electromagnetic compatibility expertise, power electronics specialists with backward integration into semiconductor loads, and engineering service firms bundling equipment with validation consulting. Dominant competitive moves center on geographic expansion into India's PLI-subsidized cell manufacturing zones and portfolio diversification into second-life battery grading services.
Within the measurement heritage tier, Keysight Technologies and Rohde & Schwarz occupy positions anchored in RF instrumentation expertise repurposed for inverter electromagnetic compatibility validation. Chroma ATE Inc. exemplifies the power electronics specialist archetype through its position supplying both test systems and captive semiconductor load components. AVL List GmbH represents the engineering-integrated model among European automotive service providers, sustaining relationships centered on turnkey powertrain test cell delivery rather than discrete equipment sales.
| Leading Market Players |
|---|
| Keysight Technologies |
| National Instruments |
| AVL List GmbH |
| Rohde & Schwarz |
| Chroma ATE Inc. |
| TÜV Rheinland |
| Ametek Inc. |
| Kikusui Electronics Corporation |
| Horiba Ltd. |
| Others |
Supply Flow & Price Mechanics
SiC module substitution for IGBT power stages is redrawing procurement geography while compressing margin structures across German and Japanese component tiers. Equipment builders now face dual sourcing mandates from Tier-1 suppliers that simultaneously demand cost containment and geographic risk distribution.
Pricing Analysis
Cost-plus contracts with semiconductor price indexation dominate procurement for high-voltage inverter validation systems. Three-tier pricing structure across premium, standard, and economy levels separates turnkey powertrain test cells from modular battery cyclers and portable diagnostic units. Pricing pressure stems from China's captive facility buildouts that source locally rather than import. Cell manufacturers in South Korea exhibit the highest price sensitivity due to modular channel procurement patterns, while German premium automakers prioritize uptime guarantees over unit cost.
Supply Chain Analysis
Inventory cycles for precision current sensors and cryogenic contactors now stretch 26-34 weeks, constraining power electronics test bench deliveries. Component sourcing draws from Germany, Japan, and South Korea for precision instrumentation, with semiconductor loads concentrated among Taiwanese and Chinese foundries. Single-source dependency on German and Japanese sensor suppliers creates geographic concentration risk. Distribution runs through direct OEM relationships for turnkey systems and regional service partners for modular equipment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ISO 6469-1 and ECE R100 regulatory tightening is accelerating equipment replacement cycles, creating a high-growth disruption window for vendors with pre-qualified safety testing portfolios.
For Market Incumbents: Shield service revenue streams by embedding performance-based uptime guarantees into multi-year maintenance contracts. Lock in backward integration into semiconductor load production to insulate margins from foundry pricing volatility. Consolidate calibration and service presence in India's PLI-subsidized cell manufacturing zones before domestic competitors establish footholds. For New Entrants and Emerging Players: Aftermarket second-life battery grading services represent a service-layer gap where incumbents under-serve with legacy DC test portfolios. Penetrate the circular economy compliance segment through portable electrochemical characterization systems. Pursue wireless power transfer validation as a greenfield application absent from established vendor roadmaps. For Investors and Strategic Acquirers: The market sits at a standard-consolidation phase that favors engineering-integrated service providers with captive test cell deployment capabilities. Long-term viability hinges on software-defined instrumentation architectures that decouple hardware from protocol firmware. Monitor India's PLI scheme disbursement velocity as the inflection signal for regional capacity buildout timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Semiconductor Loads | Captive SiC module production insulates margins from foundry pricing volatility. |
| Performance-Based Service Agreements | Uptime guarantees align vendor incentives with German Tier-1 downtime cost structures. |
| Modular Channel Card Architecture | Swappable 5-10 channel increments match South Korean cell manufacturer scaling patterns. |
| Multi-Protocol Platform Development | Unified CCS/CHAdeMO/GB/T stacks reduce hardware redundancy for testing laboratories. |
| India PLI Zone Service Expansion | Local calibration presence captures domestic battery production incentive flows. |
Methodological Framework
Operator-level perspectives from OEM platform engineers, Tier-1 supplier procurement leads, testing laboratory technical directors, and aftermarket service operators anchored the qualitative base. Primary interview data combined with secondary validation from SEC equipment vendor filings, MIIT new-energy vehicle catalog submissions, and UN ECE regulatory documentation. Bottom-up equipment unit estimates triangulated against top-down gigafactory capacity announcements across the analysis window.
Sensitivity analysis tested forecast robustness across cell chemistry adoption scenarios and regulatory implementation timelines. Segmentation modeling spanned product type, application tier, automation technology, and end-user archetype dimensions. CAGRs derived from equipment replacement cycle analysis and gigafactory capacity ramp schedules. Forecast inputs incorporated ECE R100 thermal propagation mandate compliance deadlines and China's GB/T standard revision trajectories.
Underlying assumptions cover semiconductor load availability and regulatory enforcement consistency, with deviation risk concentrated in IGBT/SiC module supply disruptions and ISO 6469-1 qualification timeline extensions. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Testing and Simulation
Commercial Vehicle and Off-Highway RADAR Market
Automotive Testing and Simulation
Fleet Over-the-Air Software Update Validation Test Platforms Market
Automotive Testing and Simulation
Autonomous Valet Parking System Scenario-Based Test Equipment Market
Automotive Testing and Simulation
Advanced Driver Assistance Systems Testing Equipment Market
Automotive Testing and Simulation
Chassis Dynamometers Market
Automotive Testing and Simulation
Automotive Spot Weld Inspection System Market
Automotive Testing and Simulation
Automotive Prognostics Market
Automotive Testing and Simulation
Diagnostic Tools for Evs Market
Automotive Testing and Simulation
Driving Simulator Market
Automotive Testing and Simulation
Transportation Predictive Analytics and Simulation Market
Automotive Testing and Simulation
Automotive Exhaust Analyzer Market
Automotive Testing and Simulation
Automotive on-Board Diagnostics Market
Automotive Testing and Simulation
Automotive Hardware-In-The-Loop Simulation Market
Automotive Testing and Simulation
Automotive Crash Test Dummies Market
Automotive Testing and Simulation
Automotive Diagnostic Tools Market
Automotive Testing and Simulation
Vehicle Chassis Dynamometers Market