
 Automotive Diagnostic Tools Market | 2026-2036
Automotive Diagnostic Tools Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Diagnostic Tools Market Analysis
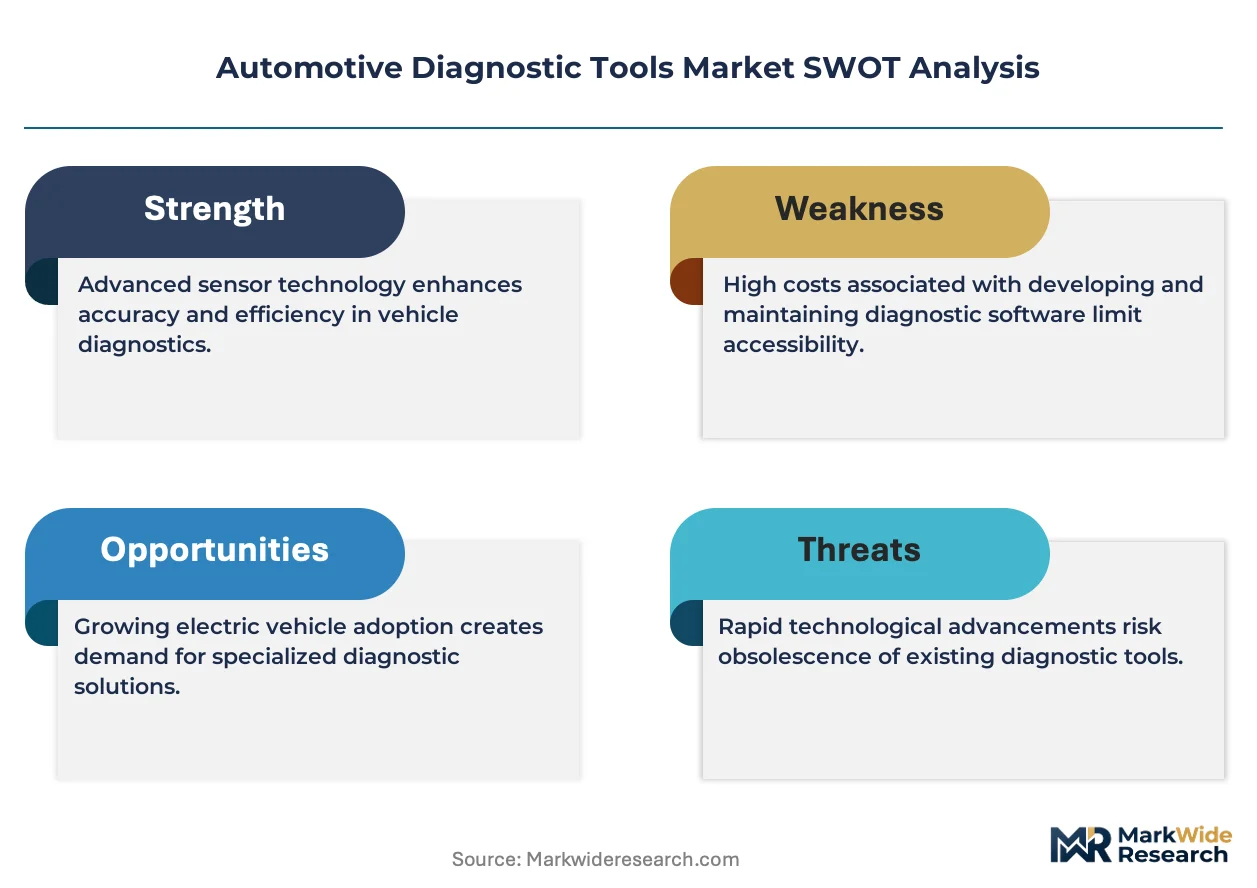
The gap between proprietary OEM diagnostic architectures and aftermarket interoperability is narrowing as vehicle networks migrate to Ethernet-based backbone topologies. Robert Bosch GmbH leverages its embedded systems heritage to dominate integrated diagnostic platforms for electrified powertrains. Snap-on Incorporated sustains premium positioning through dense channel control across North American independent repair shops. Continental AG competes by anchoring its portfolio in V2X communication modules that bundle diagnostic telemetry with connectivity stacks.
Automotive diagnostic tools comprise electronic instruments that interface with vehicle control modules to extract fault codes, monitor real-time sensor parameters, and execute actuator tests via standardized protocols such as ISO 15765-4 CAN and SAE J1979 OBD-II command sets. Their primary commercial purpose is to reduce mean time to repair while ensuring compliance with emission and safety mandates. Wireless technology adoption is accelerating fastest among fleet operators seeking over-the-air diagnostics, while wired Ethernet segments command margin pools in high-throughput dealership environments where OEMs mandate factory-grade scan tools. Repair shops represent the volume anchor across application categories, though emission testing is tightening specifications in jurisdictions with advancing clean-air deadlines.
The US EPA and California Air Resources Board enforce OBD-II and emerging OBD-III mandates that dictate hardware refresh cycles for emission testing equipment. The EU Green Deal and F-Gas Regulation indirectly shape diagnostic tool demand by tightening vehicle climate-system leak detection requirements. Stakeholders must monitor how cybersecurity certification under UN R155 reshapes tool authentication protocols and aftermarket access permissions.
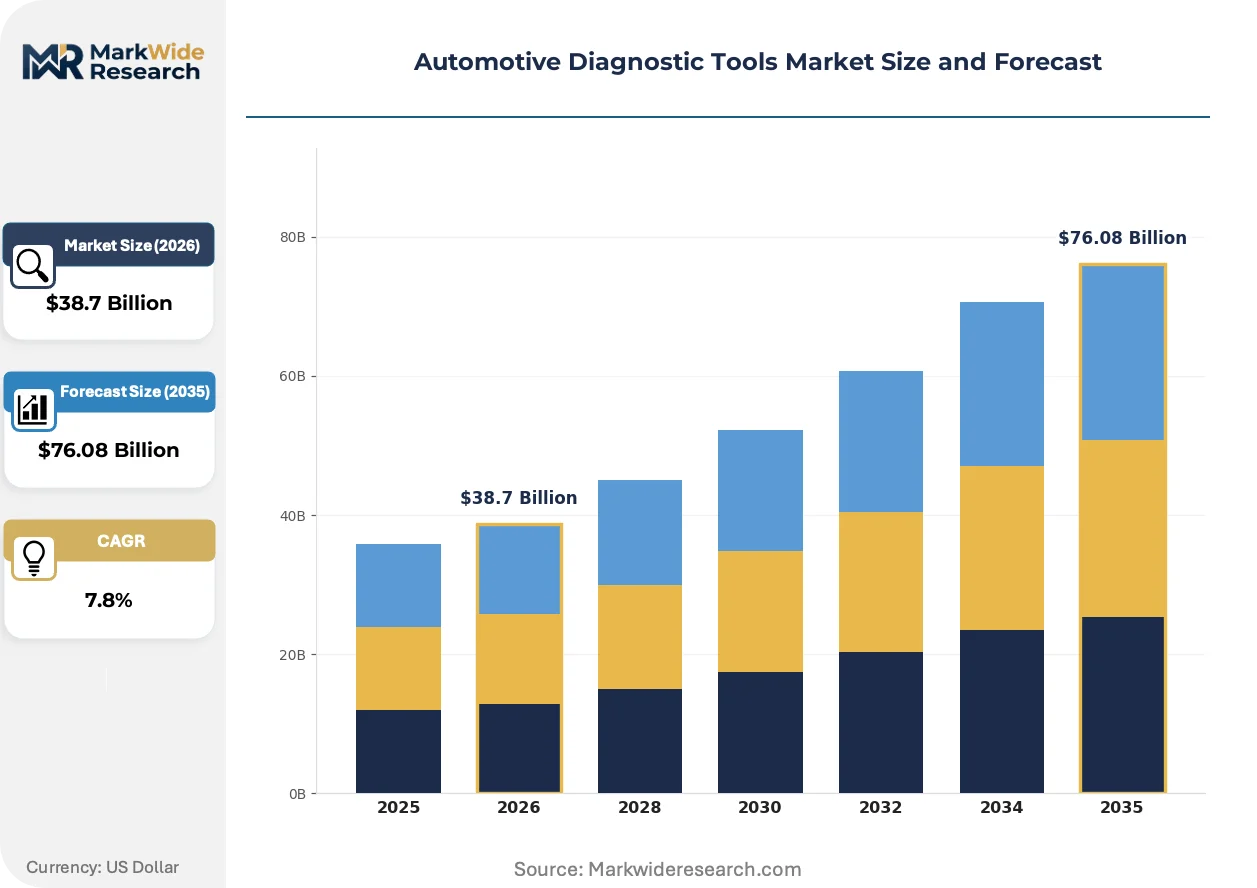
Market Dynamics
Vehicle network architecture migration from CAN bus to Ethernet backbone topologies is compressing diagnostic protocol stacks and forcing hardware refresh cycles across aftermarket and OEM-aligned tool manufacturers.
Growth Catalysts
- OBD-III Readiness Mandates:California Air Resources Board and EU Green Deal emission verification protocols are accelerating hardware replacement cycles for testing equipment in Germany and the United States.
- Connected Fleet Telemetry:Fleet operators are expanding adoption of over-the-air diagnostic platforms to reduce vehicle downtime and centralize maintenance scheduling.
- Electrified Powertrain Complexity:High-voltage battery management systems and inverter diagnostics require specialized tooling that legacy scan equipment cannot address.
Market Restraints
- Semiconductor Supply Concentration:Taiwan and South Korea fabrication capacity constraints limit production scaling for diagnostic tool processors and automotive-grade memory modules.
- Cybersecurity Certification Friction:UN R155 vehicle cybersecurity mandates add authentication layers that restrict aftermarket access permissions and extend product development timelines.
- Proprietary OEM Gatekeeping:Manufacturer-specific diagnostic encryption limits interoperability for independent repair shops seeking factory-grade fault resolution.
Strategic Opportunities
- V2X-Integrated Diagnostics:Vehicle-to-everything communication modules that bundle telemetry with connectivity stacks open new revenue pools in telematics service providers.
- Emerging Market Fleet Digitization:Brazil and India commercial vehicle operators are adopting cloud-connected diagnostic platforms to manage dispersed asset bases.
- EU F-Gas Regulation Tailwind:Climate-system leak detection requirements are tightening specifications for HVAC diagnostic tooling across European service networks.
Industry Challenges
- Automotive Ethernet Skill Shortage:Technician training programs lag behind 100BASE-T1 and 1000BASE-T1 protocol deployment in dealership environments.
- Multi-Protocol Integration Complexity:Service bays must maintain parallel CAN, LIN, FlexRay, and Ethernet diagnostic equipment, inflating capex requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Diagnostic Tools Market |
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $76.08 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: OBD II Scanners, Multimeters, Code Readers, Oscilloscopes Technology: Wireless, Wired, Bluetooth, Ethernet Application: Vehicle Maintenance, Troubleshooting, Performance Optimization, Emission Testing End User: OEMs, Repair Shops, Fleet Operators, DIY Mechanics |
| Companies Covered | Robert Bosch GmbH, Snap-on Incorporated, Continental AG, Denso Corporation, ACTIA Group, Softing AG, Horiba Ltd., SGS SA, Fortive Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Diagnostic Tools Market Emerging Trajectories
Diagnostic tooling is converging around software-defined architectures that decouple hardware interfaces from analysis engines, enabling subscription-based feature activation and remote calibration updates.
Automotive Ethernet diagnostic interfaces are hybridizing physical layer testing with protocol analysis functions. Tier 1 suppliers are adopting these consolidated platforms to reduce bench equipment footprint. The technology is hybridizing previously separate signal integrity verification and application-layer diagnostics into unified workflows.
EU F-Gas Regulation and California Air Resources Board mandates are reshaping climate-system diagnostic specifications. Leak detection sensitivity thresholds now require mass spectrometry integration in service-grade equipment. European independent shops are retrofitting existing refrigerant analyzers to meet these tightened protocols.
Fleet procurement patterns now favor diagnostic-as-a-service arrangements over capital equipment purchases. Third-party telematics providers are displacing traditional tool distributors in commercial vehicle accounts. This shift concentrates most visibly in United States long-haul trucking and last-mile delivery segments.
Automotive Diagnostic Tools Market Segmentation
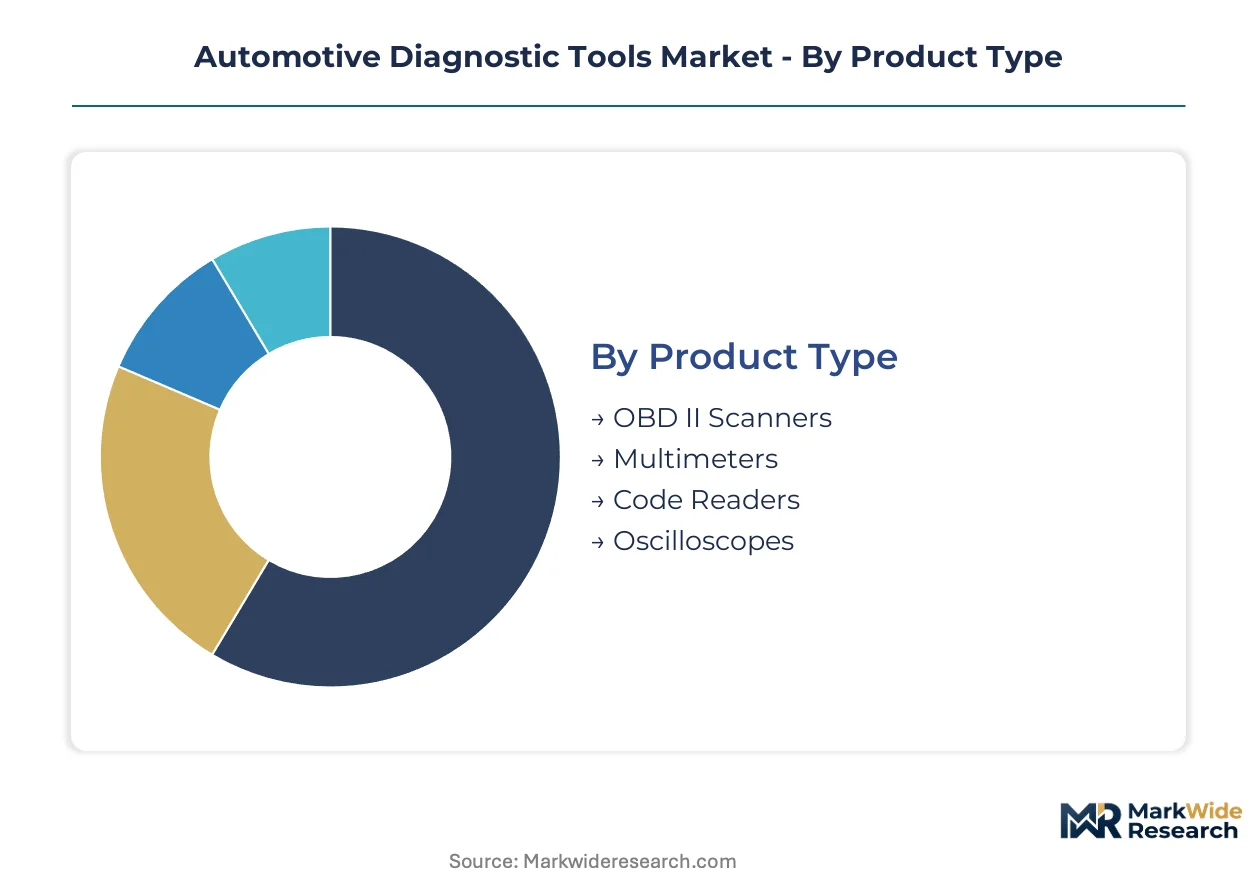
Diagnostic tool procurement cycles vary dramatically by segment, with fleet-facing technologies refreshing every 18-24 months while legacy wired equipment persists for 7-10 years in independent repair environments. Understanding these replacement rhythms shapes inventory planning and channel investment decisions across the value chain.
Product Type:
OBD II Scanners turn over fastest due to regulatory protocol updates, while Oscilloscopes retain field utility for decades with firmware refresh cycles.
- OBD II Scanners:Handheld or tablet-based devices executing ISO 15765-4 CAN and SAE J1979 command sets for fault code extraction and emission readiness verification. Demand concentrates in California and Germany where CARB and EU Green Deal mandates accelerate hardware replacement for emission testing compliance.
- Multimeters:Electrical measurement instruments for voltage, current, and resistance diagnostics across 12V and 48V vehicle architectures. Fleet operators in the United States specify automotive-grade units with CAT III safety ratings for high-voltage hybrid servicing.
- Code Readers:Entry-level fault code retrieval devices with limited bidirectional control capabilities. DIY mechanics in Germany and China drive volume through retail auto parts channels.
- Oscilloscopes:High-sampling-rate signal analyzers for sensor waveform validation and intermittent fault tracing. Dealership environments in the United States maintain these for complex drivability diagnostics where scan tool data proves insufficient.
OBD II Scanners dominate installed base. Oscilloscopes represent where expansion concentrates as electrified powertrain complexity demands signal-level verification.
Technology:
Cost tiers separate subscription-based wireless platforms from capital-intensive Ethernet infrastructure, with Bluetooth bridging mid-market mobility needs.
- Wireless:Cellular or Wi-Fi-enabled diagnostic platforms supporting over-the-air firmware updates and remote technician collaboration. Fleet operators across the United States and Germany are displacing wired equipment with diagnostic-as-a-service arrangements that centralize maintenance scheduling.
- Wired:USB or dedicated cable connections ensuring deterministic latency for factory-grade programming and calibration sequences. OEM dealerships in Germany mandate these for security-critical ECU flashing where wireless introduces attack surface.
- Bluetooth:Short-range wireless pairing between scan tools and technician tablets or smartphones. Independent repair shops in the United States favor these for bay mobility without cellular subscription overhead.
- Ethernet:100BASE-T1 and 1000BASE-T1 automotive Ethernet interfaces for high-throughput diagnostic data on modern vehicle backbone architectures. German OEM service networks are upgrading to these as CAN bus bandwidth proves inadequate for ADAS calibration data volumes.
Wired technology anchors legacy installed base. Wireless platforms are gaining share fastest among commercial vehicle accounts.
Application:
Volume concentrates in routine maintenance, while emission testing commands premium pricing due to regulatory certification requirements.
- Vehicle Maintenance:Scheduled service diagnostics including oil life monitoring, brake wear assessment, and battery health verification. Fleet operators in the United States deploy connected platforms to automate maintenance interval compliance across dispersed asset bases.
- Troubleshooting:Reactive fault isolation for drivability complaints, warning lamp illumination, and component failure diagnosis. Repair shops in Germany handle these cases under stringent manufacturer warranty protocols that demand factory-grade tool compatibility.
- Performance Optimization:Tuning and calibration for powertrain efficiency, transmission shift quality, and aftermarket modification support. Enthusiast segments in the United States drive demand through specialized tuning shops.
- Emission Testing:Regulatory compliance verification for exhaust constituents, evaporative system integrity, and OBD system readiness. California and German jurisdictions enforce the strictest equipment specifications under CARB and EU Green Deal frameworks.
Vehicle Maintenance represents the volume anchor. Emission Testing is where pricing power concentrates due to certification barriers.
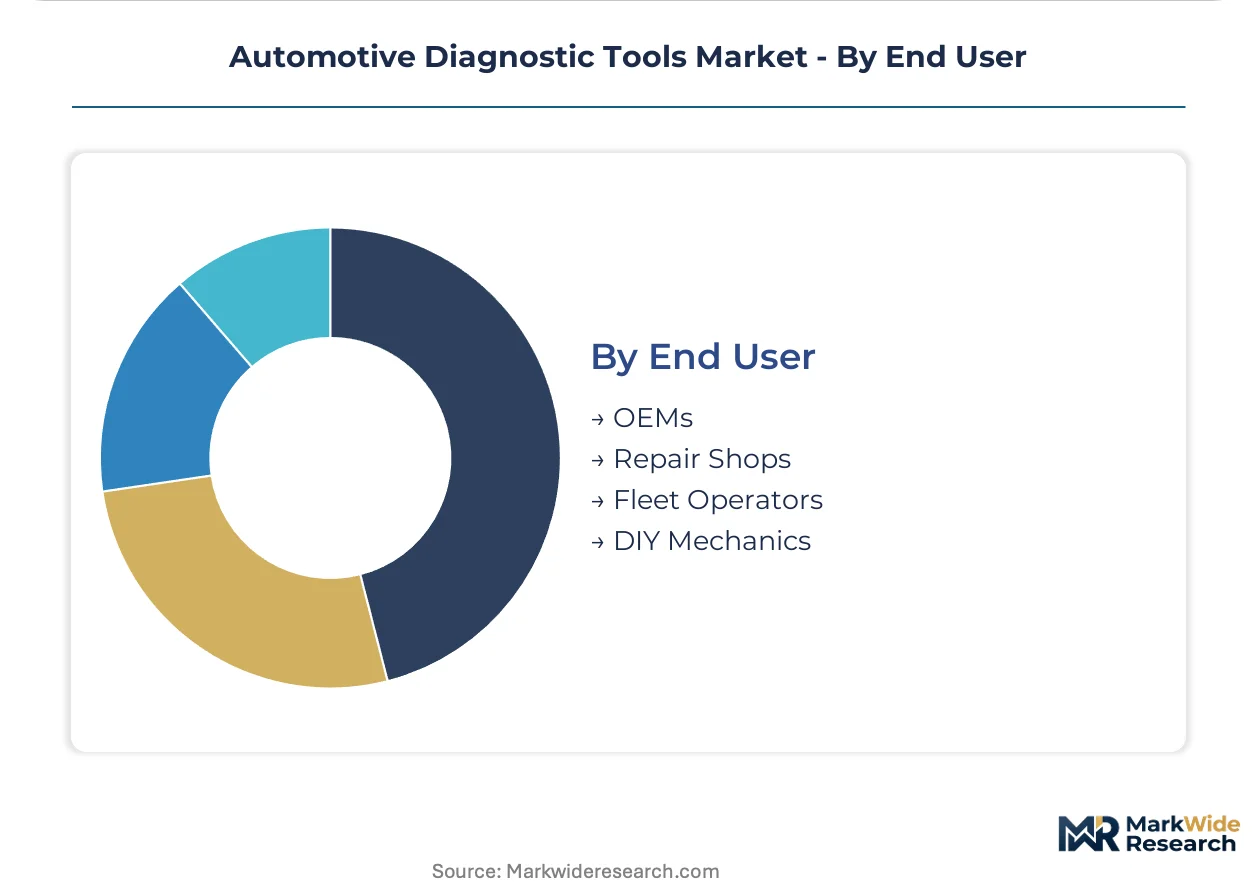
End User:
Customer type determines procurement modality, with OEMs specifying multi-year tool contracts and DIY mechanics driving retail price sensitivity.
- OEMs:Vehicle manufacturers and authorized dealer networks requiring factory-exclusive diagnostic platforms with encrypted security access. German and United States OEMs mandate Ethernet-based tools for new vehicle architectures.
- Repair Shops:Independent service facilities seeking multi-brand compatibility across varying vehicle ages and emission standards. These operators in Germany face tightening EU F-Gas Regulation requirements for climate-system tooling.
- Fleet Operators:Commercial vehicle and logistics companies adopting centralized diagnostic telemetry for asset utilization optimization. Long-haul trucking fleets in the United States are expanding fastest.
- DIY Mechanics:Consumer purchasers of entry-level code readers and basic multimeters for home garage diagnostics. Price sensitivity here limits average selling prices compared to professional segments.
Repair Shops dominate installed base. Fleet Operators are where expansion concentrates through telematics-integrated procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany exports diagnostic hardware and embedded software platforms to North American and Chinese service networks, establishing the primary trade-flow corridor for factory-grade equipment. California and Shanghai serve as the dominant import destinations for Ethernet-based diagnostic infrastructure.
United States
Fleet digitization and OBD-III readiness mandates drive procurement of connected diagnostic platforms. The EPA and California Air Resources Board enforce emission verification protocols that accelerate hardware replacement cycles. Long-haul trucking operators in Texas and California are displacing wired equipment with diagnostic-as-a-service subscriptions.
Germany
Electrified powertrain complexity and V2X communication integration sustain demand for high-throughput diagnostic systems. The EU Green Deal and F-Gas Regulation tighten climate-system leak detection specifications for service-grade equipment. Automotive OEM service networks in Bavaria and Baden-Württemberg mandate Ethernet-based tools for ADAS calibration.
China
Domestic EV production scale and fleet operator expansion create concentrated demand for battery management system diagnostics. MIIT and GB standards govern vehicle network security and diagnostic access permissions. Yangtze River Delta manufacturing clusters in Shanghai and Jiangsu province supply hardware to both domestic and export markets.
Japan
Precision manufacturing heritage and semiconductor integration capabilities support specialized diagnostic component production. METI oversees automotive cybersecurity standards that shape tool authentication requirements. Kanto region technology corridors around Tokyo supply high-sampling-rate signal analysis modules to German and US equipment manufacturers.
India
Commercial vehicle fleet digitization and dispersed asset management needs accelerate cloud-connected diagnostic adoption. The central automotive regulator enforces emission testing equipment specifications under evolving national standards. Maharashtra and Gujarat industrial zones host assembly operations for entry-level code readers serving domestic and Southeast Asian retail channels.
Automotive Diagnostic Tools Market Vendor Landscape
Channel-controlling players compete with product-specialist players across fragmented aftermarket and consolidated OEM-aligned segments. The vendor base organizes around three strategic archetypes: integrated automotive suppliers leveraging embedded systems heritage, tool manufacturers dominating dense distribution networks, and telematics providers bundling diagnostics with fleet connectivity stacks. Consolidation concentrates among Ethernet infrastructure specialists and V2X module integrators. Geographic expansion and strategic partnerships represent the dominant competitive moves as regulatory mandates fragment national certification requirements.
Within the integrated supplier tier, Robert Bosch GmbH and Continental AG exemplify archetypes that anchor factory-grade diagnostic ecosystems through embedded systems control. Snap-on Incorporated occupies a position representing channel-dominant players that sustain premium positioning through dense North American repair shop networks. These three entities collectively illustrate how heritage in automotive electronics, distribution infrastructure, or connectivity integration determines competitive positioning across diverging procurement modalities.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| Snap-on Incorporated |
| Continental AG |
| Denso Corporation |
| ACTIA Group |
| Softing AG |
| Horiba Ltd. |
| SGS SA |
| Fortive Corporation |
| Others |
Supply Flow & Price Mechanics
Semiconductor fabrication concentration in Taiwan and South Korea creates simultaneous pricing tier compression and supply vulnerability for diagnostic tool manufacturers, forcing tier-one OEMs toward captive silicon sourcing while aftermarket vendors absorb margin erosion through firmware monetization strategies.
Pricing Analysis
Ethernet-generation diagnostic interfaces command substantial premiums over CAN-bus legacy equipment, while Bluetooth-bridged mid-market tools face the steepest cost compression. Three-tier pricing structure across premium, standard, and economy levels separates factory-grade OEM-mandated platforms from independent shop equipment and DIY entry-level devices. Pricing pressure stems from fleet operator migration toward diagnostic-as-a-service subscriptions that displace capital equipment purchases. DIY mechanics in retail channels exhibit highest price sensitivity, constraining code reader margins, whereas German OEM service networks demonstrate lowest sensitivity due to ADAS calibration compliance requirements.
Supply Chain Analysis
Automotive-grade processors and high-sampling-rate analog front-ends feed from Taiwan Semiconductor Manufacturing, Samsung Foundry, and Texas Instruments fabrication networks. Raw material dependencies span silicon wafers, AEC-Q100 qualified memory modules, and shielded twisted-pair cabling for 100BASE-T1 physical layers. Single-source vulnerability concentrates in advanced node semiconductor capacity where automotive qualification timelines extend procurement lead times. Distribution runs through authorized distributor networks serving OEM dealer channels alongside direct-to-fleet telematics provider arrangements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive Ethernet protocol mastery now separates viable competitors from obsolescing players, with technician certification pipelines and software-defined architecture capabilities representing the scarcest strategic assets across the value chain.
For Market Incumbents: Build switching-cost moats through embedded fleet telematics integration that bundles diagnostic telemetry with maintenance scheduling workflows. Deepen backward integration into automotive-grade semiconductor sourcing to offset Taiwan foundry concentration risk. Expand Ethernet tool certification programs for dealership technicians before ADAS calibration mandates tighten further. For New Entrants and Emerging Players: Cloud-connected diagnostic platforms for dispersed commercial vehicle fleets in Brazil and India represent the most penetrable entry point where incumbent channel control remains weakest. Target mid-market repair shops seeking multi-protocol compatibility without OEM-mandated Ethernet infrastructure investment. Pursue white-label partnerships with telematics service providers rather than direct distribution builds. For Investors and Strategic Acquirers: OBD-III mandate implementation timelines across California and the European Union reshape the acquisition landscape toward cybersecurity-certified tool developers with UN R155 compliance pathways. Long-term viability centers on software-defined architectures capable of subscription revenue conversion. Acquire specialists in 1000BASE-T1 signal integrity verification and V2X module integration. Monitor EPA and CARB equipment specification releases as inflection indicators for hardware replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Diagnostic Platform Development | Enables subscription revenue models for fleet operators in Texas and California. |
| Automotive Ethernet Certification Investment | Secures OEM dealership tool mandates under German ADAS calibration protocols. |
| Cybersecurity Compliance Pathway Establishment | UN R155 certification unlocks aftermarket access permissions for independent shops. |
| V2X Module Integration Partnership | Bundles diagnostic telemetry with connectivity stacks for telematics providers. |
| Emerging Market Fleet Digitization Expansion | Captures cloud-connected diagnostic demand in Brazil and India commercial vehicle segments. |
Methodological Framework
Cross-validation between primary field interviews and secondary regulatory filings anchors the qualitative findings in this analysis. Conversations with OEM platform engineers, Tier 1 supplier procurement leads, aftermarket distributor operations heads, and fleet telematics directors informed demand-side dynamics. Secondary sources encompass EPA and CARB equipment specification documents, EU Green Deal implementation guidance, UN R155 cybersecurity certification records, and vehicle production databases from IHS Markit. Bottom-up segment sizing triangulates against top-down market aggregation across the projection horizon.
Calibration against historical replacement cycle data and regulatory mandate implementation timelines shaped the analytical framework. Segmentation dimensions span product type, technology generation, application intensity, and end-user procurement modality. CAGRs derive from fitted growth curves incorporating fleet digitization penetration rates and Ethernet architecture deployment schedules. Electrified powertrain service complexity indices and OBD-III readiness compliance deadlines serve as industry-specific forecast inputs.
Practitioners should monitor semiconductor fabrication capacity allocation shifts and cybersecurity certification backlog durations for early signals of supply constraint or market access friction. Forecasts reflect assumptions regarding regulatory implementation pacing and fleet operator technology refresh cadence. Cross-checking against vehicle registration data and OEM service tool procurement disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Testing and Simulation
Automotive Spot Weld Inspection System Market
Automotive Testing and Simulation
Motor Testing Equipment Market
Automotive Testing and Simulation
Automotive on-Board Diagnostics Market
Automotive Testing and Simulation
Dynamometer Market
Automotive Testing and Simulation
Diagnostic Tools for Evs Market
Automotive Testing and Simulation
Automotive Emission Analyzer Market
Automotive Testing and Simulation
ADAS Calibration Equipment Market
Automotive Testing and Simulation
Autonomous Tank Farm Inspection and Corrosion Mapping Robot Systems Market
Automotive Testing and Simulation
Automotive Emission Test Equipment Market
Automotive Testing and Simulation
Advanced Driver Assistance Systems Testing Equipment Market
Automotive Testing and Simulation
Automotive Hardware-In-The-Loop Simulation Market
Automotive Testing and Simulation
Global Automotive Wind Tunnel Market
Automotive Testing and Simulation
NDT in Automotive & Transportation Market
Automotive Testing and Simulation
Automotive Crash Test Dummies Market
Automotive Testing and Simulation
Automotive Test Equipment Market
Automotive Testing and Simulation
Vehicle Radar Test System Market