
 ADAS Calibration and Alignment Equipment Systems Market | 2026-2036
ADAS Calibration and Alignment Equipment Systems Market Size, Share, and Industry Trends Forecast 2026-2036
ADAS Calibration and Alignment Equipment Systems Market Insights
The capital-intensity divergence between full-stack platform providers and modular tool suppliers is bifurcating competitive dynamics in the ADAS calibration equipment landscape. Robert Bosch GmbH leverages captive sensor manufacturing to bundle calibration protocols with its original hardware, sustaining integrated margin pools across the value chain. Hunter Engineering Company anchors the North American aftermarket through dealership-certified service bay networks, while Autel Intelligent Technology competes on portable, software-upgradeable units that reduce technician training overhead for independent workshops.
ADAS calibration and alignment equipment systems comprise precision measurement and adjustment apparatus designed to restore sensor geometric accuracy, typically achieving angular tolerances within 0.1 degrees for camera and radar modules after vehicle repair or component replacement. These systems employ laser-projected target boards, optical pattern recognition, and electromagnetic field mapping to verify that forward-facing cameras, millimeter-wave radar, and LiDAR units maintain factory-specified boresight alignment. Camera calibration tools dominate current revenue as windshield-integrated ADAS modules require post-replacement recalibration, while LiDAR calibration systems represent the fastest-expanding segment as luxury and autonomous vehicle programs multiply sensor counts per platform. Service workshops generate the highest equipment utilization rates among application categories, though vehicle assembly lines command premium pricing for gantry-mounted, fully automated alignment stations.
FDA-equivalent automotive safety oversight in the United States flows through NHTSA, whose automatic emergency braking mandate directly expands the installed base of radar and camera systems requiring periodic calibration. Europe's ECE R79 and ECE R152 type-approval frameworks, enforced by national KBA authorities in Germany and equivalent bodies, specify sensor alignment as a condition of vehicle roadworthiness certification. Stakeholders must monitor how software-defined vehicle architectures shift calibration from physical tool-based procedures to over-the-air parameter updates, potentially compressing hardware demand in premium segments while expanding subscription-based validation services.
Market Dynamics
Software-defined vehicle architectures are compressing hardware calibration demand as automakers migrate sensor alignment to over-the-air parameter updates, forcing equipment suppliers to pivot toward validation-as-a-service revenue models.
Growth Catalysts
- NHTSA Automatic Emergency Braking Mandate:US regulators require forward collision warning systems on all light vehicles, expanding the installed base of radar and camera modules requiring periodic recalibration at service facilities.
- Windshield-Integrated ADAS Proliferation:Camera modules embedded in windshields now require post-replacement geometric restoration, driving repeat calibration visits to collision repair shops and glass service networks.
- Euro NCAP Safety Rating Protocols:European consumer testing programs award points for advanced driver assistance features, compelling OEMs to fit additional sensors per platform and maintain alignment specifications across vehicle lifecycles.
Market Restraints
- High-Precision Optics Cost Volatility:Laser-projected target boards and optical pattern recognition systems depend on specialized glass and semiconductor components subject to supply fluctuations.
- Technician Certification Bottlenecks:OEM-specific calibration protocols require brand-authorized training programs that limit service capacity expansion at independent workshops.
- Over-the-Air Calibration Substitution:Software-defined architectures enable remote parameter adjustment for certain sensor types, threatening hardware-based tool demand in premium vehicle segments.
Strategic Opportunities
- India Commercial Vehicle Fleet Modernization:Domestic truck and bus operators adopting Level-2 ADAS under government safety initiatives generate demand for portable calibration equipment at regional service depots.
- LiDAR Calibration Systems:Autonomous vehicle programs multiplying sensor counts per platform create equipment requirements for electromagnetic field mapping of three-dimensional perception modules.
- Subscription Validation Services:Equipment manufacturers can bundle hardware with cloud-based alignment verification and compliance documentation for multi-location service networks.
Industry Challenges
- Multi-Protocol Technician Training:Each OEM deploys proprietary calibration procedures, forcing service providers to maintain parallel certification tracks for German, Japanese, and domestic brand coverage.
- Integration Complexity with Legacy Bay Infrastructure:Older alignment lifts and diagnostic stations require retrofitting to accommodate camera target positioning systems and radar reflector arrays.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | ADAS Calibration and Alignment Equipment Systems Market |
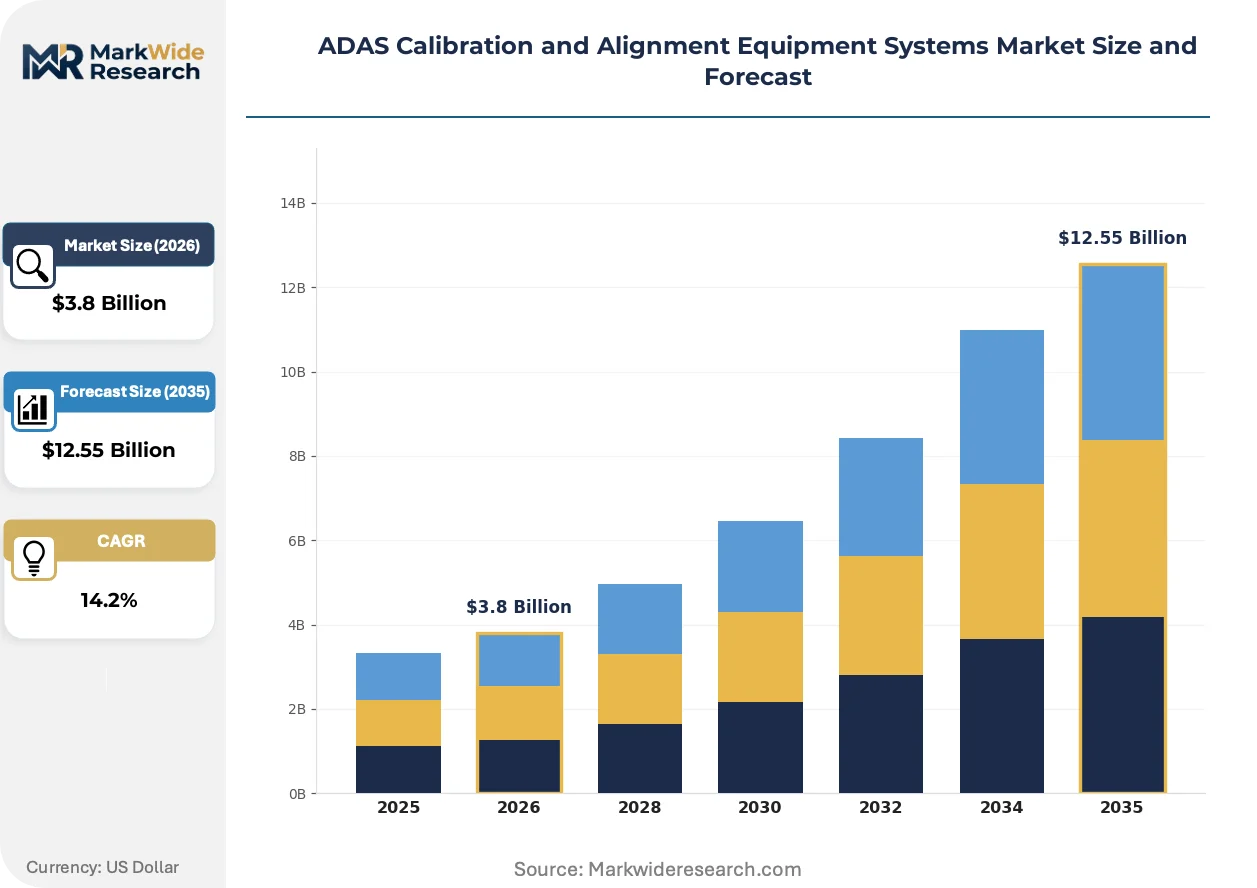
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.55 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Camera Calibration Tools, Radar Alignment Devices, LiDAR Calibration Systems, Sensor Fusion Calibration Units Technology: Laser-Based, Optical Systems, Ultrasonic, Infrared, Magnetic Field Sensors Application: Vehicle Assembly Lines, Service Workshops, Testing Facilities, Research & Development Centers End User: OEMs, Aftermarket Service Providers, Calibration Centers, Automotive Tier-1 Suppliers |
| Companies Covered | Robert Bosch GmbH, MAHLE GmbH, HELLA GmbH & Co. KGaA, Autel Intelligent Technology, TEXA S.p.A., Launch Tech Co., Hunter Engineering Company, Snap-on, Hofmann Megaplan GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
ADAS Calibration and Alignment Equipment Systems Market Trends and Innovations
Modular, software-upgradeable calibration platforms are displacing fixed-function equipment as independent workshops prioritize capital flexibility over integrated OEM systems.
Portable camera calibration units is decomposing the traditional service bay model by enabling mobile technician deployment to fleet depots and glass replacement sites. Independent operators in North America and Europe are adopting these units to capture windshield recalibration volume without dedicated bay investment. This technology is compressing revenue concentration among dealership-certified networks by democratizing access to OEM-grade alignment capabilities.
Europe's ECE R79 and ECE R152 type-approval frameworks specify sensor alignment as a mandatory condition of vehicle roadworthiness certification. German KBA enforcement and equivalent national bodies require documented calibration after collision repair or component replacement. Service workshops across Germany, France, and Italy are responding by investing in gantry-mounted automated stations that generate compliance certificates accepted by regulatory inspectors.
Glass replacement networks are consolidating procurement of calibration services through national partnership agreements rather than maintaining in-house equipment fleets. Belron and Safelite in North America are shifting toward centralized calibration hubs with mobile technician dispatch, replacing distributed bay-based models. This concentration is most visible in US metropolitan corridors where windshield replacement volume justifies dedicated fleet deployment over fixed facility investment.
ADAS Calibration and Alignment Equipment Systems Market Segmentation
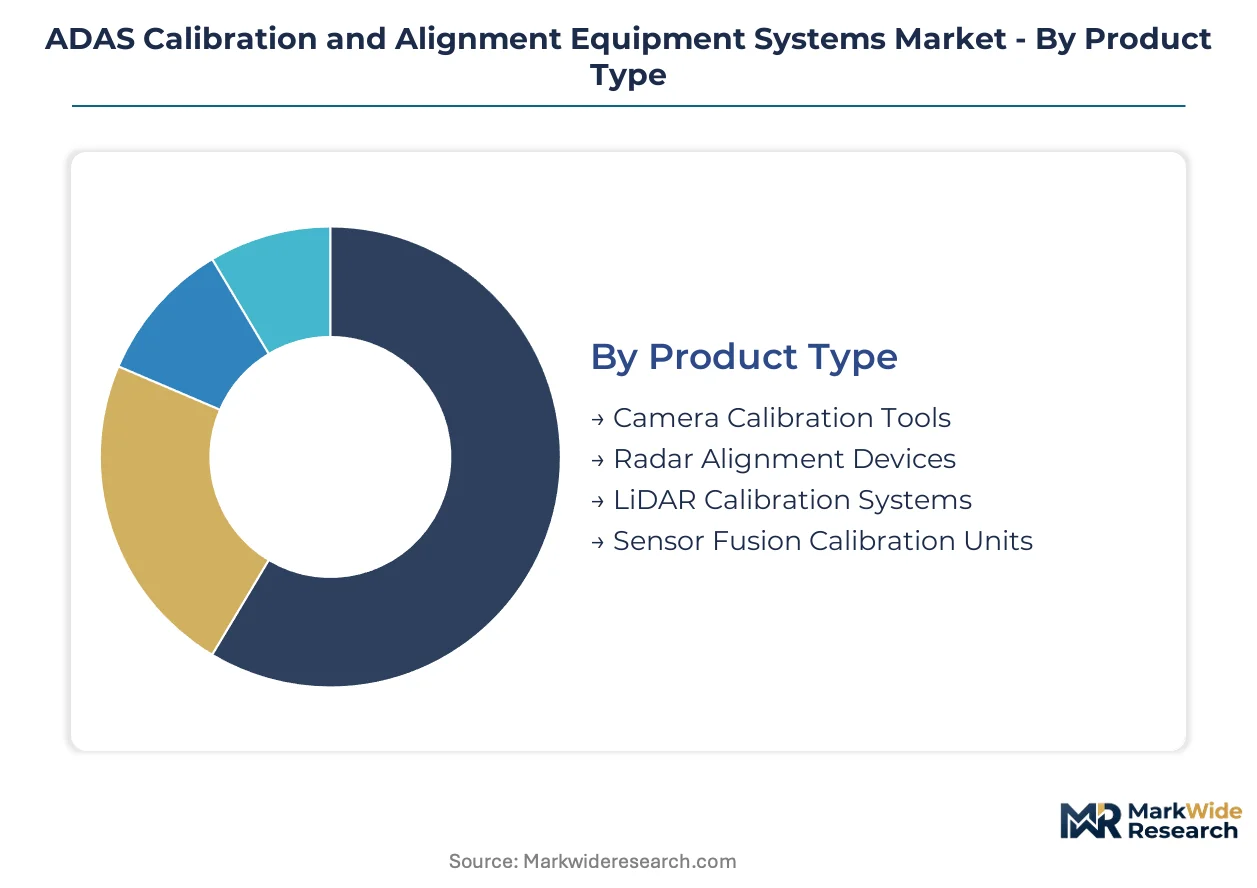
ADAS calibration equipment segments diverge sharply in their exposure to software-defined vehicle substitution. Product-level and technology-level categories face distinct competitive pressures as automakers shift from physical alignment tools toward over-the-air parameter updates.
Product Type:
Camera calibration tools face the most immediate substitution threat from remote software updates, while LiDAR systems retain irreplaceable hardware dependencies due to three-dimensional electromagnetic field mapping requirements.
- Camera Calibration Tools:These systems employ laser-projected target boards and optical pattern recognition to restore windshield-integrated camera geometric accuracy within 0.1-degree angular tolerances. Demand concentrates at collision repair shops and glass replacement networks across the United States and Germany, where NHTSA mandates and KBA roadworthiness enforcement drive repeat recalibration visits after windshield replacement.
- LiDAR Calibration Systems:Electromagnetic field mapping apparatus verifies three-dimensional perception module alignment for autonomous vehicle programs. Procurement is accelerating in China as domestic EV manufacturers deploy Level-2-plus driving systems at scale, creating equipment requirements that resist over-the-air substitution due to physical sensor positioning constraints.
- Radar Alignment Devices:Millimeter-wave radar reflector arrays and positioning systems restore forward collision warning system accuracy.
- Sensor Fusion Calibration Units:Integrated platforms simultaneously align camera, radar, and LiDAR modules for multi-sensor ADAS architectures.
Camera calibration tools anchor the volume base while LiDAR calibration systems gain share at the steepest rate.
Technology:
Cost tier stratification separates premium optical systems from commoditized ultrasonic alternatives, with mid-tier laser-based platforms capturing the largest procurement volumes across independent workshops.
- Laser-Based:High-precision laser projection systems generate calibration patterns with sub-millimeter accuracy for camera and radar alignment. These platforms dominate procurement at vehicle assembly lines in Japan and Germany, where METI production standards and KBA type-approval frameworks mandate factory-specified geometric restoration.
- Optical Systems:Pattern recognition cameras and structured light projectors verify sensor boresight alignment through visual feedback loops. Adoption is expanding fastest in service workshops across France and Italy, where ECE R79 enforcement requires documented compliance certificates that optical systems generate automatically.
- Ultrasonic:Short-range proximity sensor calibration for parking assistance systems.
- Infrared:Thermal camera alignment for night vision and pedestrian detection modules.
- Magnetic Field Sensors:Compass and orientation calibration for navigation-integrated ADAS.
Laser-based technology commands the premium tier while optical systems expand most quickly into mid-market service networks.
Application:
Volume concentration favors service workshops over assembly lines, though manufacturing applications sustain premium pricing through gantry-mounted automation requirements.
- Service Workshops:Bay-based and portable calibration units address post-collision and post-replacement recalibration demand. These facilities generate the highest equipment utilization rates across North America, where Safelite and Belron networks consolidate procurement through centralized calibration hubs with mobile technician dispatch.
- Vehicle Assembly Lines:Fully automated gantry-mounted alignment stations integrate into production sequences at OEM facilities. Installation concentrates in Germany and China, where Volkswagen, BMW, and domestic Chinese EV manufacturers require end-of-line sensor verification before vehicle release.
- Testing Facilities:Validation equipment for homologation and type-approval certification.
- Research & Development Centers:Prototype calibration systems for next-generation ADAS architecture development.
Service workshops anchor the volume base while vehicle assembly lines command the highest per-unit pricing.
End User:
Customer type determines procurement patterns, with aftermarket service providers prioritizing portable flexibility against OEM preferences for integrated platform ecosystems.
- Aftermarket Service Providers:Independent workshops and glass replacement networks prioritize software-upgradeable, portable units that reduce technician training overhead. Procurement is accelerating across India as commercial vehicle fleet operators adopt Level-2 ADAS under government safety initiatives, generating demand for regional depot deployment.
- OEMs:Vehicle manufacturers specify captive calibration protocols bundled with original sensor hardware. These relationships concentrate in Germany and Japan, where Robert Bosch GmbH and integrated Tier-1 suppliers sustain margin pools across the value chain through proprietary alignment procedures.
- Calibration Centers:Dedicated facilities providing third-party verification and compliance documentation.
- Automotive Tier-1 Suppliers:Component manufacturers requiring in-house validation for sensor module production.
Aftermarket service providers anchor the volume base while OEMs sustain the premium pricing tier.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German equipment manufacturers command premium pricing for gantry-mounted assembly line systems, while Chinese suppliers compete aggressively on portable units for regional service networks. This asymmetry shapes procurement patterns across major automotive production clusters.
United States
Windshield replacement networks drive equipment demand as Safelite and Belron consolidate calibration services through centralized hubs with mobile technician dispatch. NHTSA automatic emergency braking mandates expand the installed base of radar and camera modules requiring periodic recalibration. Detroit-area collision repair clusters invest in dealership-certified bay networks to capture OEM warranty work.
Germany
KBA roadworthiness enforcement under ECE R79 and ECE R152 frameworks mandates documented sensor alignment after collision repair. Stuttgart and Munich automotive corridors host end-of-line verification stations at BMW and Volkswagen facilities. Independent workshops across Bavaria and Baden-Württemberg adopt gantry-mounted automated systems to generate compliance certificates for regulatory inspectors.
China
Domestic EV manufacturers deploy Level-2-plus driving systems at scale, creating procurement volume for LiDAR calibration equipment that resists over-the-air substitution. MIIT production standards govern sensor verification protocols at assembly plants in the Yangtze River Delta and Pearl River Delta. Regional service depots in Guangdong and Jiangsu provinces source portable units for fleet maintenance networks.
Japan
METI standards mandate factory-specified geometric restoration at vehicle assembly lines, sustaining demand for laser-based calibration platforms with sub-millimeter accuracy. Toyota and Honda production facilities in the Chubu and Kanto regions specify captive calibration protocols bundled with original sensor hardware. Aftermarket service providers in Osaka-Kobe industrial corridors prioritize software-upgradeable units to reduce technician training overhead.
India
Commercial vehicle fleet operators adopt Level-2 ADAS under government safety initiatives, generating demand for portable calibration equipment at regional depots. BIS standards for automotive electronics create compliance requirements for sensor alignment documentation. Maharashtra and Gujarat industrial corridors host emerging service networks targeting truck and bus operator maintenance contracts.
ADAS Calibration and Alignment Equipment Systems Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a bifurcated competitive structure. Integrated platform providers sustain margin pools through proprietary calibration protocols bundled with original hardware, while modular tool suppliers compete on capital flexibility and reduced technician training requirements. Three archetypes dominate: full-stack OEM-captive suppliers, portable equipment specialists, and aftermarket service network enablers. Capacity expansion and strategic partnerships represent the dominant competitive moves as suppliers position for software-defined vehicle transitions.
Within the integrated platform tier, Robert Bosch GmbH and HELLA GmbH & Co. KGaA exemplify the OEM-captive model through their German engineering heritage and Tier-1 supplier positioning. Among portable equipment specialists, Autel Intelligent Technology and TEXA S.p.A. occupy positions emphasizing software-upgradeable architectures for independent workshops. Hunter Engineering Company anchors the North American aftermarket through its US-based dealership certification networks.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| MAHLE GmbH |
| HELLA GmbH & Co. KGaA |
| Autel Intelligent Technology |
| TEXA S.p.A. |
| Launch Tech Co. |
| Hunter Engineering Company |
| Snap-on |
| Hofmann Megaplan GmbH |
| Others |
Pricing and Supply Chain Analysis
Assembly line throughput volumes at German and Chinese OEM facilities create scale economies that compress per-unit equipment costs while sustaining premium pricing for gantry-mounted automated stations. This concentration of high-volume procurement in specific manufacturing corridors simultaneously shapes supplier location decisions and establishes price floors for mid-tier portable equipment serving fragmented aftermarket networks.
Pricing Analysis
The customization-premium spread between configured-to-order gantry systems and standard portable units spans three distinct pricing tiers: premium laser-based platforms for vehicle assembly lines, mid-tier optical systems for service workshops, and economy ultrasonic units for basic parking sensor calibration. Price differentiation hinges on certification grade under ECE R79 and KBA frameworks plus geographic delivery costs from German engineering centers. Pricing pressure stems from Chinese suppliers competing aggressively on portable units for regional service networks. Independent workshops in India and Southeast Asia exhibit the highest price sensitivity, while OEM captive procurement in Germany and Japan sustains the lowest.
Supply Chain Analysis
Specialized glass substrate availability from German and Japanese optical manufacturers creates a chokepoint that constrains laser-projected target board production capacity. Component sourcing draws from semiconductor foundries in Taiwan, precision optics workshops in Germany, and aluminum extrusion facilities in China. Single-source vulnerability concentrates in high-precision laser diode supply from Japanese vendors. Distribution runs through Tier-1 supplier integration for OEM assembly lines and independent distributors for aftermarket service networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Software-defined vehicle architectures are forcing a platform-economics inflection as calibration shifts from physical tools toward over-the-air parameter ecosystems, requiring stakeholders to reposition around validation-as-a-service interoperability.
For Market Incumbents: Compound proprietary calibration protocol bundling with sensor hardware to defend integrated margin pools against modular tool suppliers. Deepen backward integration into laser optics manufacturing to offset supply volatility in German and Japanese substrate markets. Prioritize certification investment under evolving ECE R79 enforcement to maintain OEM-captive relationships. For New Entrants and Emerging Players: Certification fast-track partnerships with Indian BIS and Chinese MIIT authorities unlock penetration of commercial vehicle fleet modernization programs. Target portable equipment deployment at regional depots in Maharashtra and Guangdong provinces where glass replacement networks consolidate procurement through mobile technician hubs. Pursue software-upgradeable architectures that reduce technician training overhead for independent workshop adoption. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors modular platform providers with recurring revenue attachment over fixed-function equipment manufacturers facing substitution risk. Long-term viability concentrates on validation-as-a-service capabilities that transcend hardware commoditization. Monitor NHTSA rulemaking expansion as the inflection signal indicating sustained sensor installation growth or accelerated over-the-air migration.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Bundles calibration protocols with original sensor hardware to sustain integrated margin pools across OEM value chains. |
| Geographic Expansion | Captures fleet depot demand in India and Southeast Asia through portable unit deployment at regional service networks. |
| Strategic Partnership | Aligns with glass replacement networks like Safelite and Belron for centralized calibration hub consolidation. |
| Product Launch | Introduces software-upgradeable architectures that reduce technician certification overhead for independent workshops. |
| Acquisition of Specialist Firm | Consolidates laser optics manufacturing capabilities to secure supply chain resilience against substrate volatility. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with Tier-1 supplier procurement officers, OEM platform engineers, aftermarket distributors, and dealership operations managers; and secondary validation against vehicle production databases, IHS Markit registration data, SEC filings from listed equipment manufacturers, and customs records for optical component trade flows. Bottom-up triangulation across service workshop equipment counts and top-down reconciliation against OEM assembly line procurement volumes anchored market sizing.
Across the analysis window, the analytical framework modeled segmentation dimensions spanning product type, technology tier, application setting, and end-user archetype. CAGRs were derived from equipment installation trajectories at vehicle assembly lines and utilization rates across service networks. Forecast inputs incorporated NHTSA mandate compliance timelines and Euro NCAP safety rating protocol evolution.
Decision-makers should treat outputs as directional under assumptions of sustained regulatory enforcement for sensor alignment documentation; material deviation in over-the-air calibration penetration would warrant model refresh. Practitioners should keep alternative scenarios live as software-defined vehicle architectures and MIIT production standards evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Testing and Simulation
Automotive Emission Analyzer Market
Automotive Testing and Simulation
NDT in Automotive & Transportation Market
Automotive Testing and Simulation
Automotive Crash Test Dummies Market
Automotive Testing and Simulation
Rail Track and Rolling Stock Advanced NDT Inspection Systems Market
Automotive Testing and Simulation
Automotive on-Board Diagnostics Market
Automotive Testing and Simulation
Chassis Dynamometers Market
Automotive Testing and Simulation
Electric Vehicle Test Bench Market
Automotive Testing and Simulation
Automotive TIC Market
Automotive Testing and Simulation
Car Crash Simulator Systems and Services Market
Automotive Testing and Simulation
Automotive Weigh in Motion Market
Automotive Testing and Simulation
Driving Simulator Market
Automotive Testing and Simulation
Vehicle Simulation Software Market
Automotive Testing and Simulation
On-Board Data Logger and Road Test Equipment System Market
Automotive Testing and Simulation
Automotive Hardware-In-The-Loop Simulation Market
Automotive Testing and Simulation
Dynamometer Market
Automotive Testing and Simulation
High-Speed Highway Pilot and Lane Change Scenario Test Platforms Market