
 Tire Testing Machine Market | 2026-2036
Tire Testing Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Tire Testing Machine Market Analytics
EU-label-grade precision is collapsing the gap between entry-level and premium testing platforms. Zwick Roell LP leverages its materials-testing heritage to dominate structural tire component validation. MTS Systems Corporation anchors its position through road-load simulation systems that OEMs specify for durability programs. Hofmann Maschinen- und Anlagenbau GmbH specializes in uniformity and geometry measurement lines that tire makers install at plant gates.
A tire testing machine evaluates structural integrity, rolling resistance, and dynamic performance of pneumatic tires under controlled laboratory conditions, typically employing load cells, force transducers, and environmental chambers to replicate operational stresses. These systems enable tire manufacturers and automotive OEMs to certify products against safety and efficiency benchmarks before commercial release. Dynamic testers command the largest installed base due to their versatility in simulating highway and off-road duty cycles. Electric actuator technology is displacing hydraulic systems in new installations as laboratories target energy efficiency and reduced maintenance intervals. Research institutions represent a fast-growing end-user category as universities partner with manufacturers on sustainable tire material programs.
The EPA regulates tire fuel efficiency ratings under its SmartWay program, compelling manufacturers to invest in correlated rolling-resistance rigs. ECE R30 and ECE R54 United Nations standards govern tire construction and load capacity for passenger and commercial applications, shaping the test protocols that machines must execute. China's GB standards and NMPA-equivalent certification requirements for tire imports add complexity for multinational testing networks. Stakeholders must weigh capital deployment between universal platforms and application-specific cells as regulatory scopes diverge across destination markets.
Market Dynamics
Electric actuator architectures are displacing hydraulic systems across new tire testing installations as laboratories prioritize energy efficiency and reduced maintenance downtime. This transition is compressing the competitive gap between mid-tier and premium platform providers while reshaping capital deployment strategies for validation infrastructure.
Growth Catalysts
- ECE R30 and ECE R54 harmonization:United Nations standards governing tire construction and load capacity for passenger and commercial vehicles are mandating correlated test protocols that expand machine utilization rates in European laboratories.
- Research institution partnerships:Universities collaborating with manufacturers on sustainable tire material programs are creating dedicated testing demand outside traditional OEM and supplier channels.
- China's GB standards and NMPA-equivalent certification:Import requirements for tire products are compelling multinational testing networks to install duplicate validation capacity within Chinese borders.
Market Restraints
- High-precision load cell supply concentration:German and Japanese sensor manufacturers control critical metrology component supply, creating vulnerability for testing platform assemblers in other geographies.
- Capital intensity of climatic chamber integration:Environmental simulation capabilities for extreme temperature and humidity testing require substantial upfront investment that limits mid-scale laboratory expansion.
- Regulatory divergence across destination markets:EPA SmartWay fuel efficiency ratings, EU tire labeling grades, and China's dual carbon compliance frameworks force redundant test sequence development.
Strategic Opportunities
- India's PLI scheme for automotive components:Domestic tire manufacturing incentives are driving greenfield plant construction that requires gate-line uniformity and geometry measurement systems.
- Digital twin convergence with physical testing:Virtual validation platforms are creating hybrid procurement models where simulation software licenses bundle with reduced-capacity physical test cells.
- Retreading and circular economy certification:Emerging protocols for remanufactured commercial tires are opening specialized durability and structural integrity test demand from fleet operators.
Industry Challenges
- Metrology engineer scarcity:Specialized expertise in force transducer calibration and correlation protocol development is concentrating among aging technician populations in Germany and Japan.
- Legacy hydraulic system integration complexity:Laboratories with installed hydraulic bases face expensive retrofit pathways to electric architectures without full replacement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tire Testing Machine Market |
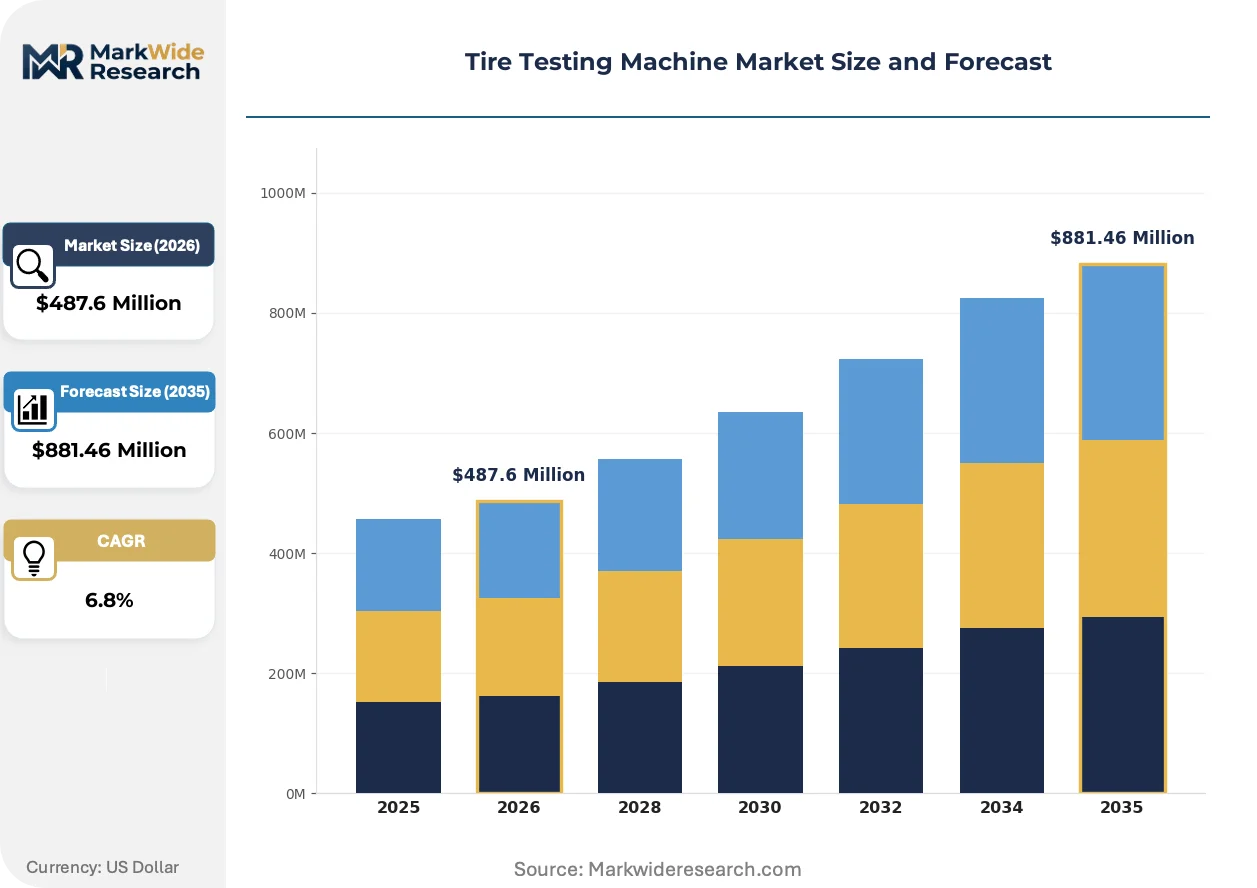
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Static Testers, Dynamic Testers, Endurance Testers, Performance Testers Technology: Hydraulic Systems, Pneumatic Systems, Electric Actuators, Mechanical Systems Application: Passenger Vehicles, Commercial Vehicles, Two-Wheelers, Racing Vehicles End User: Tire Manufacturers, Research Institutions, Quality Testing Labs, Automotive OEMs |
| Companies Covered | AMETEK, Inc, Zwick Roell LP, MTS Systems Corporation, Kobelco Technology, Calspan Corporation, A&D Technology, Kistler Group, Hofmann Maschinen- und Anlagenbau GmbH, Burke Porter Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tire Testing Machine Market Evolving Landscape
Testing methodology is bifurcating between high-throughput production gate systems and R&D-grade precision platforms as tire makers separate validation workflows. This split is generating divergent equipment specifications and procurement timelines across the value chain.
Electric actuator technology is fragmenting the traditional hydraulic-dominated installed base. Road-load simulation systems employing linear motor drives deliver superior force control fidelity for durability programs while cutting energy consumption by half versus fluid-power alternatives. Tier-one suppliers in Germany and Japan are accelerating adoption for new laboratory construction, compressing the addressable market for hydraulic component providers.
REACH and EU Green Deal compliance frameworks are mandating material traceability and lifecycle assessment documentation for tire products. Testing laboratories must now correlate mechanical performance data with chemical composition analysis, forcing upgrades to integrated data management platforms. European OEM validation centers are responding by specifying machines with embedded spectroscopy and thermal analysis modules.
Service unbundling is disrupting traditional capital-equipment purchasing in the North American aftermarket. Independent testing laboratories are shifting toward per-test pricing and equipment-as-a-service arrangements rather than outright platform ownership. This reconfiguration is most visible among commercial tire retreaders in the United States, where variable-volume operations prefer operational expenditure models aligned with seasonal demand fluctuation.
Tire Testing Machine Market Segmentation
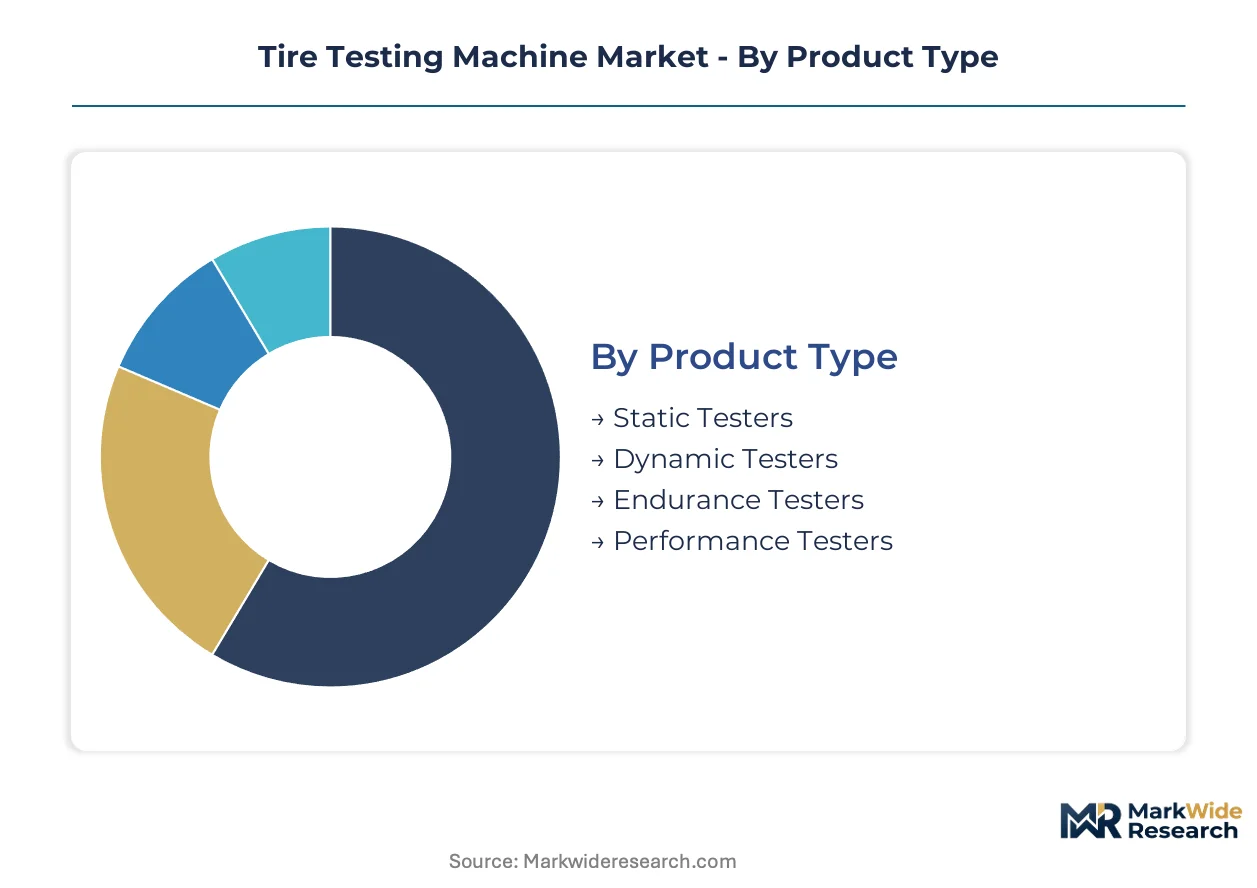
Tire testing machine procurement diverges sharply between high-volume production gate validation and R&D-grade precision certification. Equipment specifications track regulatory tier requirements rather than uniform performance benchmarks across end-use categories.
Product Type:
ECE R30 passenger tire protocols and ECE R54 commercial standards mandate distinct test sequence capabilities that shape platform architecture decisions.
- Dynamic Testers:These systems simulate highway and off-road duty cycles through programmable load profiles and environmental conditioning. OEM validation centers in Germany specify these for rolling resistance and wet grip correlation under EU tire labeling regulations.
- Static Testers:Structural integrity and dimensional compliance verification occurs through fixed-load protocols without motion simulation. Tire makers deploy these at plant gates for uniformity screening where throughput speed outweighs dynamic fidelity.
- Endurance Testers:Long-cycle durability rigs subject tires to accelerated wear protocols for commercial vehicle certification.
- Performance Testers:Specialized platforms execute high-speed and handling characterization for racing and premium passenger segments.
Established volume favors Static Testers; emerging adoption favors Dynamic Testers.
Technology:
Energy efficiency mandates and maintenance cost pressures are reconfiguring capital deployment across actuator architectures.
- Electric Actuators:Linear motor drives deliver force control precision for durability programs while cutting energy consumption versus hydraulic alternatives. New laboratory construction in Japan and Germany specifies these exclusively for correlated test protocols.
- Hydraulic Systems:Legacy fluid-power bases dominate existing installations but face expensive retrofit pathways without full replacement. Research institutions with established infrastructure retain these for high-load commercial vehicle testing.
- Pneumatic Systems:Compressed air mechanisms serve low-force applications in two-wheeler and specialty tire validation.
- Mechanical Systems:Simple mechanical linkages persist in entry-level uniformity measurement for emerging market tire plants.
Capital renewal favors Electric Actuators; installed base protection sustains Hydraulic Systems.
Application:
Vehicle category certification complexity determines test cell specification depth and automation requirements.
- Passenger Vehicles:Rolling resistance and wet grip validation for EU tire labeling drives precision investment. OEMs in Germany and France operate dedicated R&D centers with correlated measurement repeatability.
- Commercial Vehicles:Load capacity and durability protocols under ECE R54 demand high-force endurance platforms. Fleet operator retreading certification is opening specialized structural integrity test demand.
- Two-Wheelers:Lightweight tire validation requires adapted load ranges and rim interface specifications distinct from automotive platforms.
- Racing Vehicles:Extreme performance characterization for motorsport applications commands premium thermal and high-speed simulation capabilities.
Regulatory stringency concentrates in Passenger Vehicles; volume expansion is climbing the fastest in Commercial Vehicles.
End User:
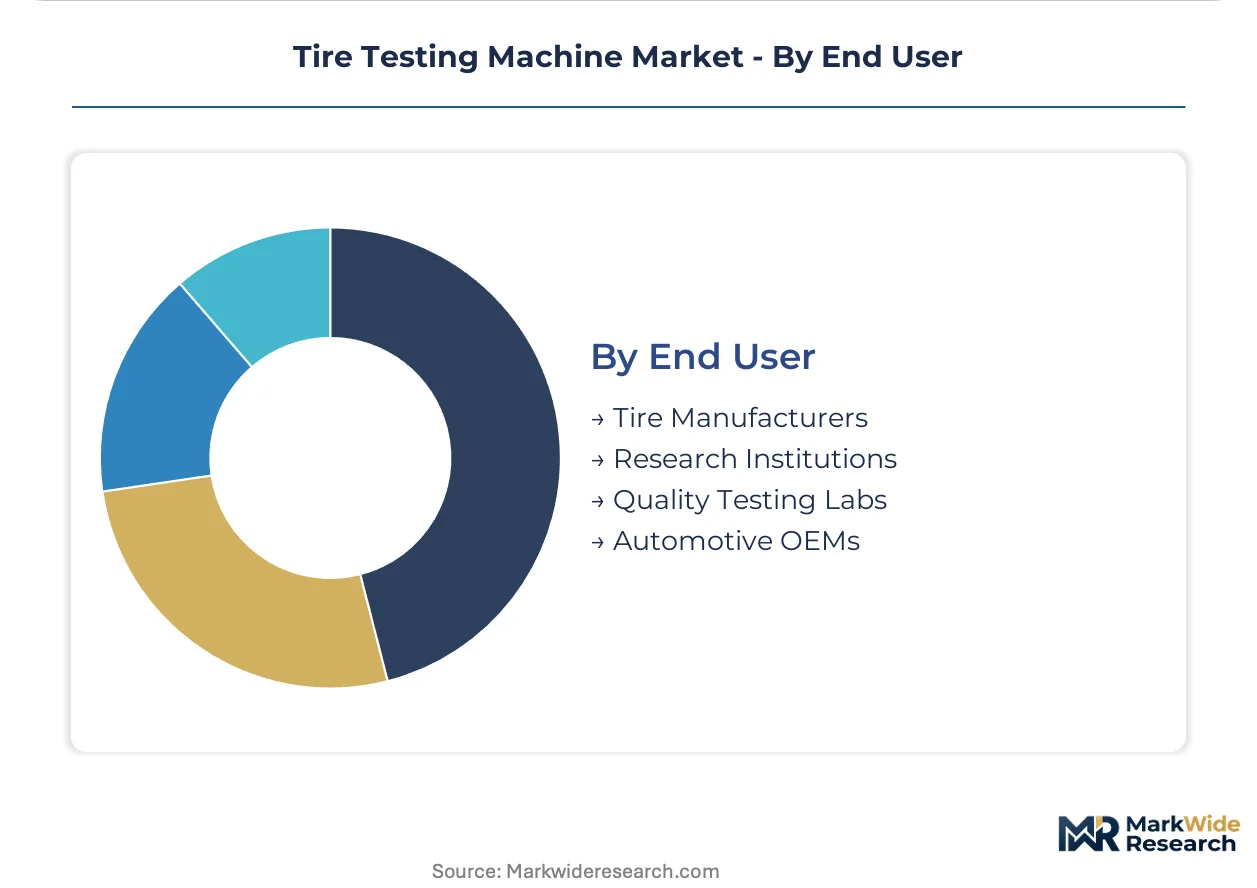
Procurement authority separates between captive manufacturing validation and third-party certification services.
- Tire Manufacturers:Integrated production gate systems and R&D laboratories require matched platform fleets for internal correlation. Continental and Michelin operate large testing centers with unified data management.
- Automotive OEMs:Validation programs for vehicle platform homologation specify road-load simulation systems from approved supplier lists. These stakeholders drive durability protocol standardization across tire sourcing.
- Research Institutions:University partnerships on sustainable tire materials are creating dedicated testing demand outside traditional supply channels.
- Quality Testing Labs:Independent certification services face margin pressure from equipment-as-a-service pricing models in North America.
Capital intensity dominates Tire Manufacturers; partnership flexibility favors Research Institutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in tire testing equipment reveal concentrated supply from German and Japanese engineering bases against dispersed demand from emerging manufacturing centers. Laboratories in importing regions face tariff and certification transfer costs that favor localized assembly partnerships.
Germany
Continental and Michelin operate large R&D testing centers demanding correlated measurement systems for EU tire labeling compliance. The KBA enforces ECE R30 and ECE R54 homologation protocols that shape machine specification standards. Stuttgart and Hanover clusters anchor structural validation expertise for premium passenger tire programs.
United States
EPA SmartWay fuel efficiency ratings compel manufacturers to invest in rolling-resistance rigs for commercial vehicle certification. Independent testing laboratories in Michigan and Ohio are shifting toward equipment-as-a-service arrangements. Detroit-area validation centers specify road-load simulation systems for OEM durability programs.
China
GB standards and NMPA-equivalent certification requirements for tire imports drive duplicate validation capacity installation. Domestic tire makers in Shandong and Jiangsu provinces are expanding plant-gate uniformity screening. Shanghai laboratories are upgrading climatic chamber integration for extreme temperature protocol execution.
Japan
METI efficiency mandates and JIS standards precision requirements sustain premium platform demand from tire makers. Toyota and Honda validation centers in Nagoya and Tokyo specify electric actuator architectures for new installations. Yokohama-based suppliers dominate high-precision load cell component supply.
India
PLI scheme incentives for automotive components are driving greenfield tire plant construction requiring gate-line measurement systems. BIS certification protocols are mandating local testing capacity for imported tire validation. Gujarat and Tamil Nadu manufacturing corridors are attracting uniformity and geometry equipment deployment.
Tire Testing Machine Market Competitive Landscape
Listed leaders compete with private specialists across capital intensity and technology integration dimensions. The vendor base separates between consolidated platform providers with full-stack capabilities and fragmented component specialists serving niche validation protocols. Two strategic archetypes dominate: diversified materials-testing conglomerates leveraging cross-industry calibration expertise, and dedicated tire-system fabricators with road-load simulation heritage. Competitive moves center on electric actuator architecture transitions and service unbundling toward per-test pricing models.
Within the diversified testing conglomerate tier, AMETEK, Inc. and Zwick Roell LP exemplify archetypes combining materials-testing heritage with tire-specific validation platforms. MTS Systems Corporation anchors the dedicated simulation specialist position through road-load system expertise. These three entities represent distinct strategic positions: cross-industry calibration leverage, structural component validation focus, and dynamic performance simulation specialization respectively.
| Leading Market Players |
|---|
| AMETEK, Inc |
| Zwick Roell LP |
| MTS Systems Corporation |
| Kobelco Technology |
| Calspan Corporation |
| A&D Technology |
| Kistler Group |
| Hofmann Maschinen- und Anlagenbau GmbH |
| Burke Porter Group |
| Others |
Value Network & Pricing Analysis
Electric actuator adoption in new tire testing installations is displacing hydraulic system demand across European and Japanese laboratories, simultaneously shifting component sourcing from fluid-power suppliers in Germany toward linear motor specialists in Japan while compressing platform pricing premiums that hydraulic architectures once commanded.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels in the tire testing machine market. Premium electric-actuator platforms with EU-label-grade repeatability command substantial certification premiums, while mid-tier systems face cost compression from Chinese manufacturers offering plant-gate uniformity solutions. Tire manufacturers with captive R&D centers exhibit lowest price sensitivity, whereas independent quality testing laboratories in North America demonstrate acute responsiveness to equipment-as-a-service alternatives.
Supply Chain Analysis
Inbound logistics costs through Hamburg and Yokohama ports constrain just-in-time delivery schedules for high-precision load cells sourced from German and Japanese sensor manufacturers. Critical metrology components draw from concentrated engineering bases in Stuttgart and Yokohama, while climatic chamber subsystems feed from Austrian and Italian thermal equipment specialists. Single-source vulnerability in force transducer calibration expertise creates supply chain risk, with distribution running through authorized service networks rather than direct OEM channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electric actuator technology is reshaping competitive positioning in tire testing equipment, with ECE R30 and ECE R54 harmonization creating sustained demand inflection for correlated validation platforms.
For Market Incumbents: Compound defensive positioning by accelerating electric architecture roadmaps ahead of hydraulic retrofit demand collapse, and deepen backward integration into load cell metrology to offset German-Japanese sensor supply concentration. Prioritize certification investment for EU tire labeling compliance as Continental and Michelin consolidate approved supplier lists. For New Entrants and Emerging Players: Lead with India's PLI scheme greenfield tire plants as the most penetrable geography, targeting gate-line uniformity and geometry measurement systems for domestic manufacturers in Gujarat and Tamil Nadu. Pursue university partnership channels for sustainable tire material testing demand outside established OEM procurement hierarchies. For Investors and Strategic Acquirers: The market sits at a technology-transition phase that favors electric-actuator specialists with road-load simulation heritage. Long-term viability hinges on service unbundling capabilities and software integration for digital twin convergence. Watch for inflection in commercial vehicle retreading certification protocols as fleet operator demand signal.| Strategic Initiative | Industry Significance |
|---|---|
| Electric Actuator Platform Migration | Linear motor architectures cut energy consumption by half versus hydraulic alternatives for durability programs. |
| Equipment-as-a-Service Model Deployment | Per-test pricing aligns operational expenditure with seasonal demand fluctuation in North American aftermarket. |
| Digital Twin Software Integration | Virtual validation platforms bundle with reduced-capacity physical test cells in hybrid procurement models. |
| Climatic Chamber Capability Expansion | Extreme temperature protocol execution meets REACH and EU Green Deal lifecycle assessment documentation mandates. |
| Research Institution Partnership Channel | University collaborations on sustainable tire materials create dedicated testing demand outside traditional supply channels. |
Research Methodology
A standing panel of tire manufacturer R&D directors, automotive OEM validation engineers, independent laboratory operations managers, and metrology equipment procurement specialists provided ongoing calibration throughout the study period. Primary fieldwork combined structured interviews with secondary validation against SEC filings from AMETEK and MTS Systems, customs and trade data for testing equipment import flows, and technical documentation from ECE and EPA regulatory repositories. Bottom-up demand modeling triangulated against top-down industry capacity assessments.
Consistency checks validated volume and value outputs against external benchmarks across the projection horizon. The analytical framework modeled segmentation dimensions including product type (dynamic, static, endurance, performance testers), technology architecture (electric, hydraulic, pneumatic, mechanical), application category (passenger, commercial, two-wheeler, racing vehicles), and end-user procurement authority (tire manufacturers, automotive OEMs, research institutions, quality testing labs). CAGRs were derived from regression analysis of historical installation data correlated with regulatory mandate timelines and OEM capital expenditure cycles.
Forecasts assume regulatory continuity in ECE R30/R54 harmonization, EPA SmartWay efficiency ratings, and China's GB standards; material policy shifts in EU tire labeling grades or NMPA certification requirements would require re-modeling. Practitioners should keep alternative scenarios live as electric actuator adoption rates and research institution partnership volumes evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Testing and Simulation
On Board Diagnostics Device Market
Automotive Testing and Simulation
Global Automotive Wind Tunnel Market
Automotive Testing and Simulation
Automotive Chassis Dynamometer Market
Automotive Testing and Simulation
Automotive Simulation Market
Automotive Testing and Simulation
Vehicle Emission Testers Market
Automotive Testing and Simulation
Motor Testing Equipment Market
Automotive Testing and Simulation
Automotive Durability Testing Market
Automotive Testing and Simulation
Automotive Test Equipment Market
Automotive Testing and Simulation
Diagnostic Tools for Evs Market
Automotive Testing and Simulation
Vehicle Simulation Software Market
Automotive Testing and Simulation
Automotive Prognostics Market
Automotive Testing and Simulation
NDT in Automotive & Transportation Market
Automotive Testing and Simulation
Automotive Exhaust Analyzer Market
Automotive Testing and Simulation
Driving Simulator Market
Automotive Testing and Simulation
Fleet Over-the-Air Software Update Validation Test Platforms Market
Automotive Testing and Simulation
Electric Vehicle Edrive Test Equipment Market