
 Automotive Chassis Dynamometer Market | 2026-2036
Automotive Chassis Dynamometer Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Chassis Dynamometer Market Analysis
The automotive chassis dynamometer market is pivoting on a widening gap between premium emission-certification systems and commodity garage-grade units. HORIBA leverages its vertical integration in measurement instrumentation to command the high-accuracy tier for regulatory compliance. AVL List GmbH anchors European OEM relationships through powertrain test cell ecosystems. Mustang Dynamometer competes on accessible price points for aftermarket brake and performance testing.
An automotive chassis dynamometer is a precision instrument that simulates road load conditions on a stationary platform, using roller assemblies, eddy-current or electric motor-based load units, and real-time data acquisition to measure powertrain output, emissions, and fuel consumption. Multi-axle configurations are capturing the fastest expansion as electric and all-wheel-drive vehicle architectures proliferate. Digital technology segments are absorbing disproportionate R&D investment because software-defined test protocols reduce recalibration downtime. Emission testing applications retain the deepest margin pools given regulatory mandate durability.
The EPA enforces Tier 3 emission standards that require chassis dynamometer verification for light-duty certification in the United States. EMA oversees Euro 7 development, which will extend real-driving emission testing and tighten chassis-based validation protocols across Europe. Japan's METI coordinates alignment with UN R83 and R101 standards through national type-approval procedures. Stakeholders must weigh whether to build captive test capacity or outsource to independent laboratories as regulatory cycle complexity outpaces in-house equipment refresh rates.
Market Dynamics
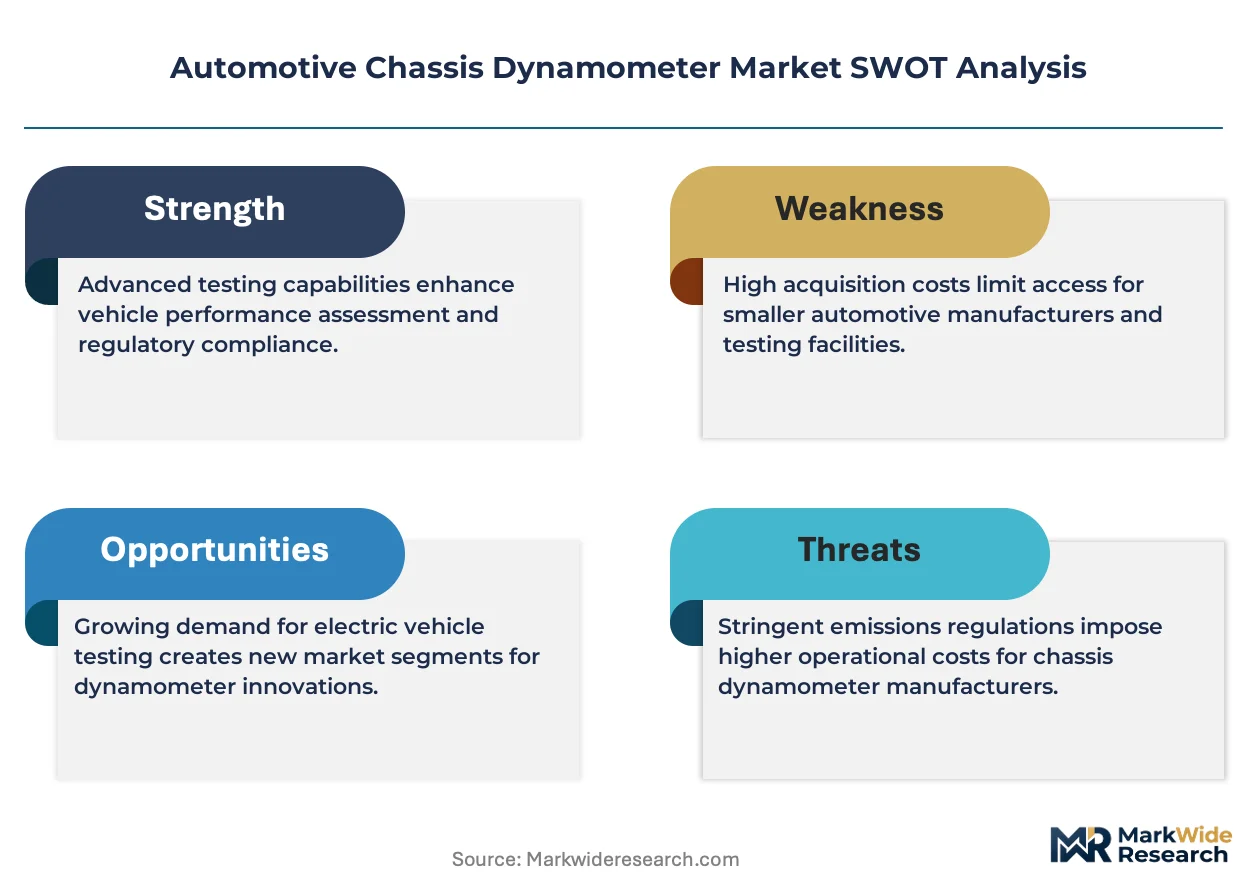
Electric vehicle powertrain architectures are fragmenting validation protocols as OEMs demand simultaneous testing of multi-axle torque vectoring, regenerative braking, and battery thermal management on single platforms.
Growth Catalysts
- Euro 7 emission standards:The EMA's proposed real-driving emission testing protocols mandate chassis dynamometer verification for all light-duty vehicles, expanding test-cycle complexity and equipment upgrade cycles across European certification laboratories.
- Electric motor load units:Eddy-current systems face displacement by precision electric motor-based load units that enable instantaneous torque replication for EV powertrain characterization, pulling R&D investment from Japanese and German test equipment suppliers.
- All-wheel-drive proliferation:Premium SUV and light truck segments in the United States now exceed 60% AWD penetration, forcing independent test facilities to deploy multi-axle dynamometer configurations.
Market Restraints
- High-purity copper and rare-earth magnet costs:Electric motor-based load units depend on neodymium-iron-boron magnets and specialized winding materials, exposing equipment margins to supply concentration in Chinese processing facilities.
- Calibration infrastructure scarcity:Accredited metrology laboratories capable of certifying dynamometer accuracy to ISO 17025 standards concentrate in Germany, Japan, and the United States, creating regional bottlenecks for equipment commissioning.
- EPA Tier 3 compliance timeline compression:Accelerated certification deadlines for 2027 model-year vehicles strain test facility throughput without proportional expansion of chassis dynamometer capacity.
Strategic Opportunities
- India automotive testing:The country's PLI scheme for electric vehicle manufacturing lacks corresponding investment in indigenous chassis dynamometer infrastructure, creating import substitution potential for multi-axle test systems.
- Software-defined test protocols:Convergence of chassis dynamometer hardware with vehicle-in-the-loop simulation platforms enables remote protocol updates, reducing recalibration downtime for contract test laboratories.
- Aftermarket performance tuning:Independent garages in the United States seek affordable single-axle systems for brake validation and power verification, opening a volume tier below regulatory-grade equipment.
Industry Challenges
- Embedded software validation:Chassis dynamometer systems now require cybersecurity certification under UN R155 and R156, extending commissioning timelines and demanding specialized engineering competencies scarce among traditional mechanical test equipment vendors.
- Legacy facility retrofit:Existing single-axle installations in European independent laboratories face physical space constraints and foundation load limitations when upgrading to multi-axle configurations for EV testing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Chassis Dynamometer Market |
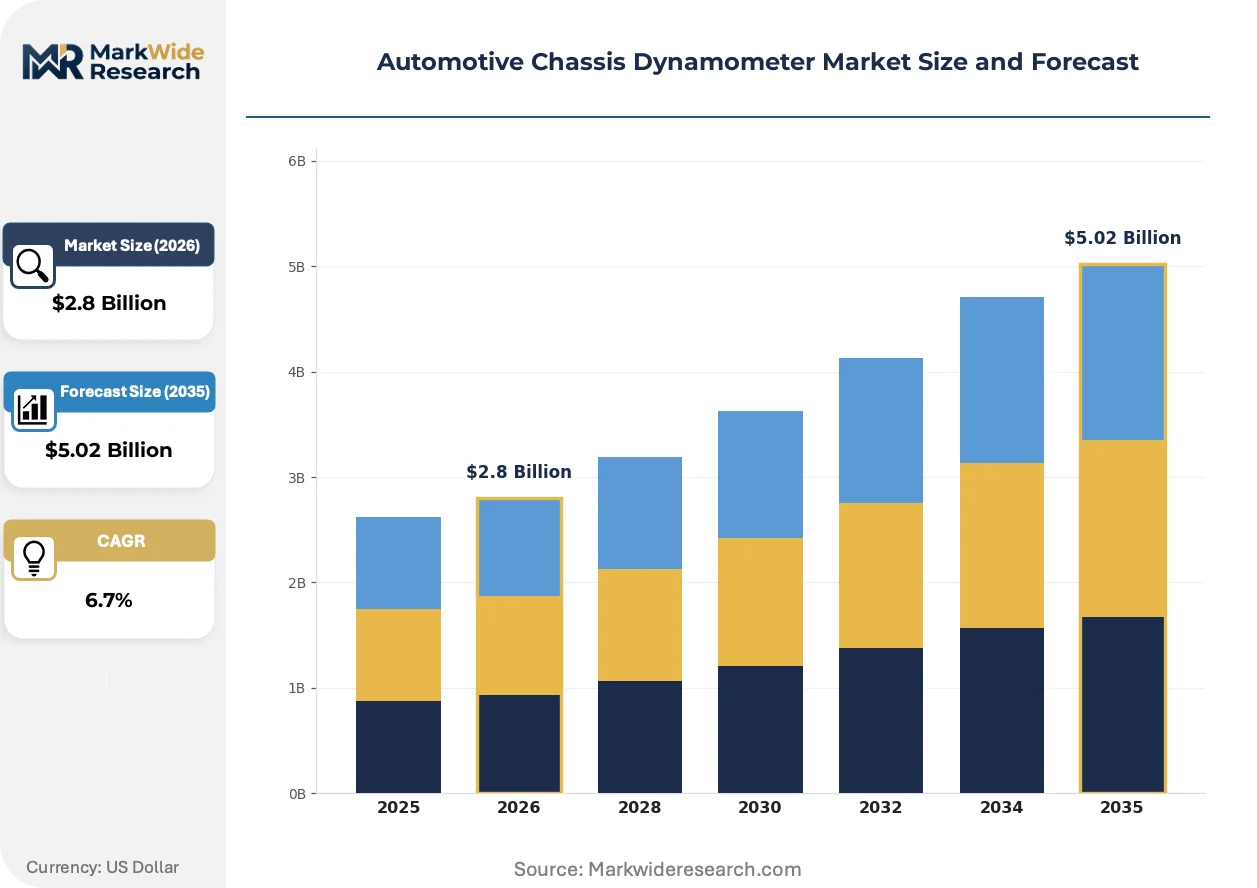
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Axle, Multi-Axle, Engine Test, Hybrid Technology: Electric, Hydraulic, Mechanical, Digital End User: Automakers, Research Institutes, Regulatory Bodies, Aftermarket Services Application: Performance Testing, Emission Testing, Brake Testing, Diagnostics |
| Companies Covered | HORIBA, AVL List GmbH, Mustang Dynamometer, Meidensha Corporation, MAHA Maschinenbau Haldenwang, Rototest, ONO SOKKI CO.,LTD, MTS Systems Corporation, Sierra Instruments, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Chassis Dynamometer Market Emerging Trajectories
Digital twin architectures are penetrating chassis dynamometer design, enabling predictive maintenance and virtual commissioning that compresses deployment timelines for complex multi-axle installations.
Hardware-in-the-loop (HIL) integration is converging with chassis dynamometer platforms as AVL and HORIBA deploy unified test cells where physical roller systems interface with real-time vehicle simulation models. Tier 1 suppliers in Germany now specify combined HIL-dynamometer configurations for powertrain control unit validation. This convergence is compressing the boundary between virtual development and physical certification, reducing prototype vehicle requirements by enabling software-first test protocols.
EPA enforcement of Tier 3 emission standards is tightening evaporative emission test procedures that require chassis dynamometer-based running loss verification. The industrial consequence is expanded test cell infrastructure at OEM captive facilities and independent laboratories in Michigan and California. Light-duty diesel and gasoline direct injection platforms face the most stringent new protocols, driving demand for enhanced hydrocarbon sampling systems integrated with dynamometer control software.
Contract test laboratory procurement now favors outcome-based service agreements where fees tie to certified test completion rather than equipment time allocation. Independent facilities in Japan and Germany are displacing traditional hourly billing with fixed-price certification packages. This shift is most visible in Euro 7 pre-compliance testing, where OEMs transfer regulatory risk to test providers in exchange for volume commitments.
Automotive Chassis Dynamometer Market Segmentation
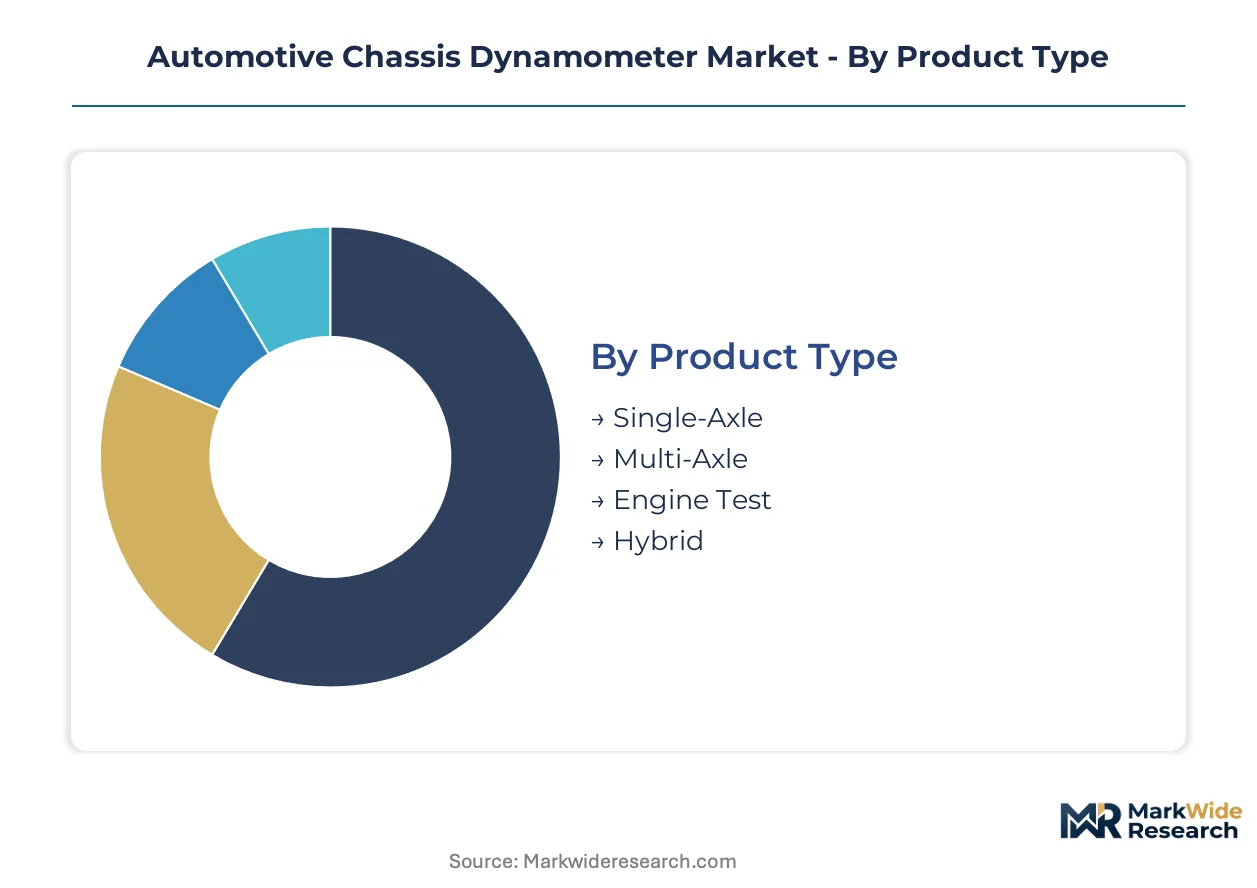
Chassis dynamometer procurement splits sharply between certification-grade systems commanding premium pricing and service-bay units sold on accessibility. Segment boundaries are blurring as electric powertrain validation forces multi-axle configurations into facilities previously served by single-axle equipment.
Product Type:
Volume concentrates in single-axle units for brake and baseline performance work, while premium margins attach to multi-axle systems capable of all-wheel-drive electric vehicle validation.
- Single-Axle:Roller assemblies accommodate one driven axle with eddy-current or mechanical load absorption. Demand clusters at independent garages in the United States for brake validation and power verification where capital constraints favor accessible price points.
- Multi-Axle:Synchronized roller sets enable simultaneous torque measurement across all axles with independent load control per wheel. European OEM captive facilities in Germany are pulling capacity expansion here as premium SUV and light truck architectures exceed sixty percent all-wheel-drive penetration.
- Engine Test:Dedicated powertrain stands isolate internal combustion units from chassis integration for mapping and durability work. Research institutes in Japan maintain concentrated deployment for thermal efficiency studies.
- Hybrid:Configurable platforms switch between conventional and electric load simulation within single test cycles. Regulatory bodies in California specify these for Tier 3 compliance verification spanning combustion and electrified powertrains.
Mature deployment sits with Single-Axle. Newer deployment is concentrated in Multi-Axle.
Technology:
Application requirements separate instantaneous torque replication from cost-optimized steady-state loading.
- Electric:Precision motor-based load units achieve millisecond torque response with regenerative energy recovery. Japanese and German test equipment suppliers are absorbing disproportionate R&D investment here as EV powertrain characterization demands exceed eddy-current capabilities.
- Hydraulic:Pressurized fluid systems deliver high-force loading for heavy-duty and commercial vehicle testing. Aftermarket services in the United States favor these for truck brake validation where peak load requirements exceed electric motor cost-effectiveness.
- Mechanical:Friction brake and water brake absorbers provide baseline loading without electrical infrastructure. Emerging market facilities in India import these for initial certification capacity before upgrading to electric systems.
- Digital:Software-defined control architectures enable remote protocol updates and vehicle-in-the-loop integration. Contract laboratories in Germany are specifying these for Euro 7 pre-compliance work where test cycle complexity outpaces hardware refresh cycles.
Established installations favor Hydraulic and Mechanical. Steepest expansion trajectory belongs to Digital.
End User:
Procurement authority divides between captive OEM facilities optimizing throughput and independent laboratories competing on certification speed.
- Automakers:Volkswagen, Toyota, and Ford operate captive test cells with dedicated dynamometer lines for powertrain development and homologation. These facilities prioritize multi-axle electric configurations to compress EV program timelines.
- Research Institutes:Fraunhofer and JARI facilities advance measurement methodology and correlate laboratory results with on-road validation. Their procurement emphasizes Digital and Electric technologies for protocol development.
- Regulatory Bodies:EPA, KBA, and METI laboratories maintain reference equipment for type-approval arbitration and enforcement testing. These installations require ISO 17025 traceability and multi-axle capability for comprehensive vehicle certification.
- Aftermarket Services:Independent garages and performance tuners seek single-axle mechanical or hydraulic systems for brake testing and power verification. Price sensitivity here sustains commodity-tier equipment margins.
Capital intensity peaks with Regulatory Bodies. Volume scale concentrates in Aftermarket Services.
Application:
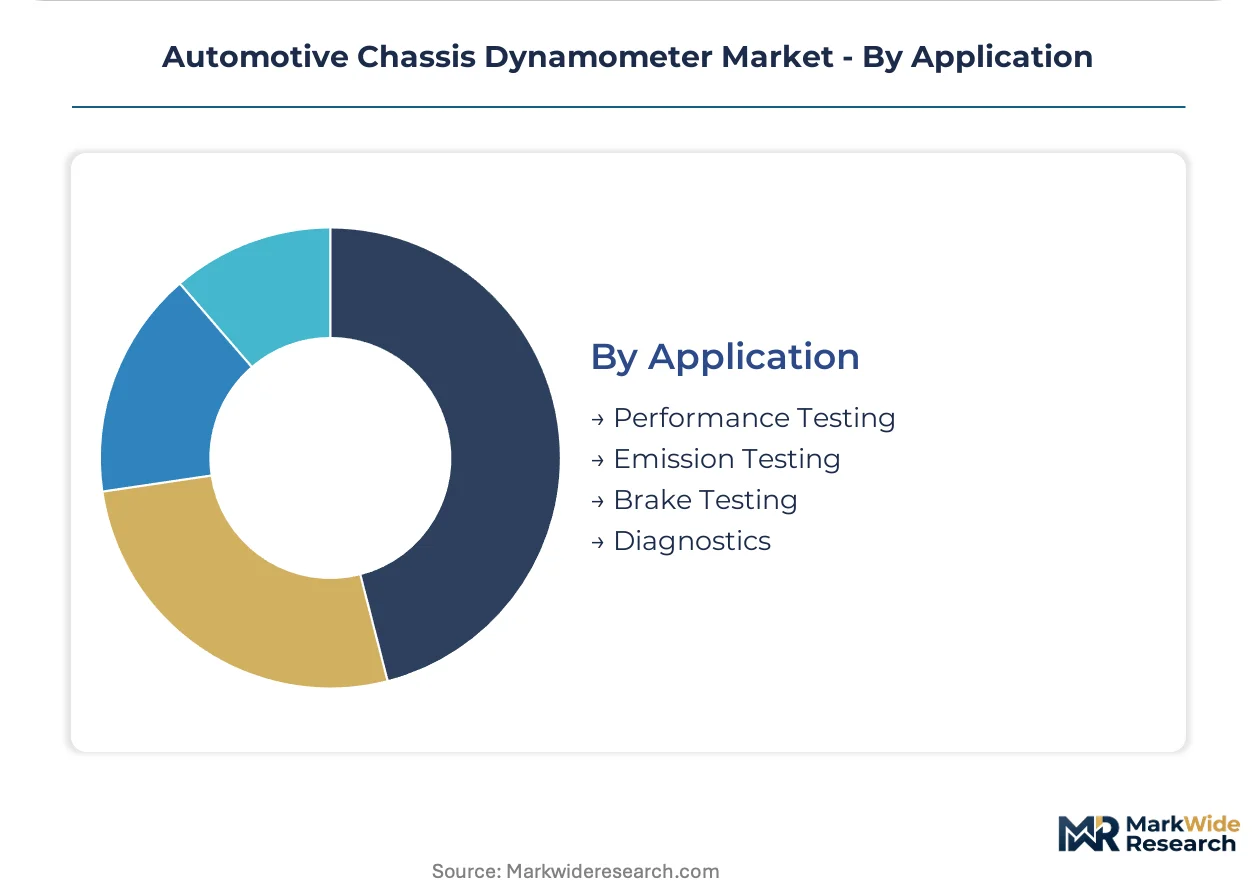
Regulatory mandate durability separates emission testing margins from performance testing volume.
- Performance Testing:Power output measurement and drivability mapping for development engineering. Automakers in Germany deploy multi-axle electric systems here to validate torque vectoring algorithms.
- Emission Testing:Chassis-based running loss verification and evaporative emission measurement under EPA Tier 3 and Euro 7 protocols. Regulatory bodies and contract laboratories absorb the deepest equipment investment here due to compliance mandate durability.
- Brake Testing:Thermal fade measurement and regulatory compliance for FMVSS and ECE R90. Aftermarket services in the United States drive single-axle demand for routine inspection and repair validation.
- Diagnostics:Fault isolation and control unit calibration on completed vehicles. Research institutes combine these protocols with hardware-in-the-loop simulation for software-first development approaches.
Margin concentration sits with Emission Testing. Volume throughput concentrates in Brake Testing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stuttgart anchors global chassis dynamometer demand through Germany's dense certification infrastructure. The concentration of OEM captive facilities and independent test laboratories in this industrial corridor shapes procurement patterns across Europe.
United States
Michigan and California host the densest concentration of EPA-certified test facilities for Tier 3 compliance verification. The EPA enforces accelerated certification timelines for 2027 model-year vehicles, straining throughput at Detroit-area laboratories. Independent contract test providers in Ann Arbor and Los Angeles are expanding multi-axle capacity to absorb outsourced validation work from captive OEM facilities.
Germany
KBA laboratories in Munich and Stuttgart maintain reference equipment for Euro 7 type-approval arbitration. The EMA's proposed real-driving emission testing protocols mandate chassis dynamometer verification, forcing equipment upgrade cycles across German certification laboratories. Fraunhofer research institutes in Braunschweig advance measurement methodology correlating laboratory results with on-road validation.
Japan
METI coordinates alignment with UN R83 and R101 standards through national type-approval procedures administered in Tsukuba and Yokohama. JARI facilities prioritize digital and electric technologies for protocol development supporting domestic OEM export certification. Japanese test equipment suppliers concentrate R&D investment in precision electric motor-based load units for EV powertrain characterization.
India
The PLI scheme for electric vehicle manufacturing lacks corresponding indigenous chassis dynamometer infrastructure, creating import substitution potential. Emerging market facilities in Pune and Chennai import mechanical systems for initial certification capacity before upgrading to electric configurations. National automotive test centers under the Ministry of Heavy Industries face equipment commissioning bottlenecks due to calibration infrastructure scarcity.
China
Shanghai and Beijing host the primary concentration of domestic test equipment manufacturing serving both captive OEM facilities and independent laboratories. MIIT-administered GB standards for new energy vehicle certification drive demand for multi-axle hybrid test systems. Processing concentration for neodymium-iron-boron magnets in Chinese facilities exposes equipment margins to supply-side pricing volatility for electric motor-based load units.
Automotive Chassis Dynamometer Market Vendor Landscape
Premium-margin players sit above commodity-margin players across certification-grade accuracy tiers. The market structure fragments between vertically integrated measurement instrumentation specialists and accessible price-point fabricators serving aftermarket garages. Three strategic archetypes dominate: regulatory-grade system integrators with captive metrology capabilities, multi-axle electric configuration specialists, and single-axle commodity producers. Competitive moves concentrate on backward integration into sensor manufacturing and geographic expansion into underpenetrated certification markets.
Within the regulatory-grade tier, HORIBA and AVL List GmbH exemplify vertically integrated specialists commanding high-accuracy market positions. Mustang Dynamometer occupies a position at the accessible end of the spectrum serving independent garages with price-optimized configurations. Japanese fabricators including Meidensha Corporation and ONO SOKKI anchor the precision electric motor-based load unit segment where EV powertrain characterization demands exceed legacy eddy-current capabilities.
| Leading Market Players |
|---|
| HORIBA |
| AVL List GmbH |
| Mustang Dynamometer |
| Meidensha Corporation |
| MAHA Maschinenbau Haldenwang |
| Rototest |
| ONO SOKKI CO.,LTD |
| MTS Systems Corporation |
| Sierra Instruments |
| Others |
Supply Flow & Price Mechanics
Euro 7 pre-compliance testing mandates from European OEM procurement offices are compressing equipment refresh cycles and forcing suppliers to absorb upfront engineering costs before volume orders materialize. This specification-driven demand pattern concentrates pricing power with vertically integrated metrology specialists capable of bundling certification-grade accuracy with software-defined protocol updates.
Pricing Analysis
Outcome-based service agreements now anchor pricing structures for contract test laboratories, with fees tied to certified test completion rather than hourly equipment allocation. Price differentiation separates ISO 17025-traceable regulatory-grade systems from commodity garage-grade units lacking accredited calibration chains. Pricing pressure intensifies in the single-axle aftermarket tier as independent US garages prioritize accessible capital expenditure over precision specifications. Regulatory bodies and captive OEM facilities exhibit the least price sensitivity, absorbing premium multi-axle electric configurations to compress EV program timelines.
Supply Chain Analysis
Electric motor-based load unit production rests on neodymium-iron-boron magnet processing concentrated in Chinese facilities and high-purity copper winding materials sourced from Chilean and Zambian mining operations. Specialized eddy-current brake assemblies and precision roller bearings draw from German and Japanese component fabricators with limited second-source alternatives. Single-source vulnerability in rare-earth magnet supply exposes equipment margins to export restriction risk and commodity price volatility. Distribution runs through direct OEM procurement channels for captive test cells and specialized industrial distributors serving independent laboratories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Euro 7 emission standards erect a formidable cost-of-compliance barrier that favors incumbent players with established KBA and EPA certification relationships, locking out undercapitalized entrants lacking metrology infrastructure.
For Market Incumbents: Lock in multi-year service contracts with European contract test laboratories before 2027 model-year certification deadlines strain capacity. Prioritize backward integration into precision sensor manufacturing to defend margins against rare-earth magnet cost volatility from Chinese processing concentration.
For New Entrants and Emerging Players: EPA Tier 3 compliance timeline compression in the United States opens a window for independent test facility operators to capture outsourced validation work from Detroit-area OEM captive facilities. Target single-axle aftermarket configurations for US independent garages where price sensitivity sustains volume-tier equipment demand and regulatory-grade accuracy specifications are absent.
For Investors and Strategic Acquirers: Re-rating potential sits with precision electric motor-based load unit specialists given EV powertrain characterization demands that exceed legacy eddy-current capabilities. Acquisition candidates with ISO 17025-accredited calibration infrastructure and software-defined test protocol capabilities offer the strongest long-term viability. Watch for EPA enforcement acceleration on Tier 3 evaporative emission test procedures as an inflection indicator for expanded test cell infrastructure investment.
| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Axle Capacity Expansion | European independent laboratories in Stuttgart and Munich absorb outsourced Euro 7 pre-compliance validation from OEM captive facilities. |
| Backward Integration into Sensor Manufacturing | HORIBA and AVL reduce exposure to third-party metrology component lead times and quality variance. |
| Software-Defined Test Protocol Development | Digital control architectures enable remote updates that reduce recalibration downtime for contract laboratories. |
| Geographic Manufacturing Footprint in India | PLI scheme for electric vehicle manufacturing creates import substitution opportunity for multi-axle test systems. |
| Charging Infrastructure Partnership | Integration of battery thermal management validation with dynamometer platforms addresses EV powertrain testing fragmentation. |
Methodological Framework
Document review covered EPA enforcement guidance, EMA Euro 7 protocol drafts, and METI type-approval procedures, complemented by interviews with OEM platform engineers, Tier 1 supplier procurement leads, independent test laboratory directors, and aftermarket service equipment distributors. Secondary validation drew from vehicle production databases, customs records for test equipment imports, and SEC filings of publicly traded measurement instrumentation suppliers. Bottom-up segment sizing triangulated against top-down market aggregation from regulatory body capacity announcements.
Segment-level outputs across product type, technology, end user, and application dimensions were modeled with regional production cluster and propulsion architecture as cross-cutting variables. CAGRs were derived from regression analysis of historical equipment procurement patterns against regulatory deadline schedules. Forecast inputs incorporated OEM EV program timeline disclosures and independent laboratory capacity expansion announcements.
The model assumes electric motor-based load unit adoption accelerates as EV powertrain characterization demands exceed eddy-current capabilities; alternative pathways prolonging hydraulic or mechanical system deployment would alter the outlook. Forecasts reflect assumptions on regulatory enforcement intensity and rare-earth magnet supply stability. A small set of triggers—including EPA Tier 3 deadline acceleration, Chinese export restriction events, and Euro 7 real-driving emission protocol finalization—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Testing and Simulation
Vehicle Scanner Market
Automotive Testing and Simulation
Automotive Prognostics Market
Automotive Testing and Simulation
Diagnostic Tools for Evs Market
Automotive Testing and Simulation
Rail Track and Rolling Stock Advanced NDT Inspection Systems Market
Automotive Testing and Simulation
NDT in Automotive & Transportation Market
Automotive Testing and Simulation
Global Track Geometry Measurement System (TGMS) Market
Automotive Testing and Simulation
Automotive Durability Testing Market
Automotive Testing and Simulation
Vehicle Radar Test System Market
Automotive Testing and Simulation
Electric Vehicle Edrive Test Equipment Market
Automotive Testing and Simulation
Automotive Emission Test Equipment Market
Automotive Testing and Simulation
Car Crash Simulator Systems and Services Market
Automotive Testing and Simulation
Torque Gauge Market
Automotive Testing and Simulation
Automotive on-Board Diagnostics Market
Automotive Testing and Simulation
Commercial Vehicle and Off-Highway RADAR Market
Automotive Testing and Simulation
Wheel Alignment Equipment Market
Automotive Testing and Simulation
Electric Vehicle Test Equipment Market