
 Rail Track and Rolling Stock Advanced NDT Inspection Systems Market | 2026-2036
Rail Track and Rolling Stock Advanced NDT Inspection Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Rail Track and Rolling Stock Advanced NDT Inspection Systems Market Insights
A widening capability gap between full-system integrators and component suppliers is reorganizing competitive tiers in rail NDT inspection. Wabtec Corporation leverages its locomotive installed base to bundle predictive diagnostics with original equipment, while MISTRAS Group anchors its position through specialized ultrasonic and eddy current service contracts with Class I railroads. Eddyfi Technologies differentiates by concentrating on portable phased-array instruments for field weld inspection.
Rail track and rolling stock advanced NDT inspection systems encompass non-destructive testing equipment that applies ultrasonic, electromagnetic, and optical sensing modalities to detect subsurface cracks, corrosion, and geometric deviations in rails, wheels, and axles without service interruption. These systems typically operate at inspection speeds between 30 and 100 km/h for track-mounted configurations, generating terabyte-scale datasets that feed machine-learning defect classification algorithms. Ultrasonic testing and magnetic flux leakage currently dominate capital allocation among infrastructure managers, while automated robots and drone-based inspection represent the fastest-expanding system categories as operators seek to reduce track possession windows. Fixed installations retain the deepest margin pools through long-term service agreements tied to signaling and traffic control infrastructure.
The Federal Railroad Administration enforces track safety standards under 49 CFR Part 213, mandating rail flaw detection at defined intervals that tighten for higher-speed operations, while the EU Agency for Railways harmonizes NDT performance criteria through the CCS TSI specification. Japan's MLIT rail bureau applies JIS E 1101 material standards that indirectly dictate inspection sensitivity thresholds for imported and domestic rail alike. Stakeholders must weigh the capital efficiency of upgrading legacy fixed installations against the operational flexibility of autonomous robotic platforms as traffic density and speed requirements intensify.
Market Dynamics
Continuous monitoring architectures are displacing scheduled manual inspections as infrastructure managers face tightening possession windows and escalating traffic density across high-speed corridors.
Growth Catalysts
- EU Agency for Railways CCS TSI:Harmonized NDT performance criteria mandate flaw detection sensitivity upgrades across trans-European networks, compelling infrastructure managers to modernize legacy ultrasonic installations.
- Machine learning classification:Terabyte-scale datasets from track-mounted sensors now feed neural networks that reduce false-positive rates and accelerate defect triage decisions.
- Deutsche Bahn digital rail program:Germany's 33,000-kilometer sensor network deployment creates reference architecture demand that neighboring rail operators replicate.
Market Restraints
- Specialized sensor supply concentration:High-frequency ultrasonic transducers and electromagnetic coils depend on precision manufacturing concentrated in German and Japanese component suppliers.
- 49 CFR Part 213 compliance costs:Federal Railroad Administration inspection interval mandates for higher-speed operations multiply capital requirements without proportional traffic revenue increases.
- Optical sensing substitution:Laser-based geometric measurement systems capture surface defects that magnetic flux leakage misses, fragmenting capital allocation across competing modalities.
Strategic Opportunities
- Autonomous robotic platforms:Track possession window compression in Japan and France creates demand for self-propelled inspection units that operate between scheduled services.
- Drone-based axle inspection:Wheel-set examination in railyards without uncoupling rolling stock opens service contracts with freight operators seeking throughput gains.
- EU Green Deal maintenance clauses:Extended asset life requirements for rail infrastructure embed NDT inspection into sustainability-linked financing instruments.
Industry Challenges
- Phased-array ultrasonic technician scarcity:Interpretation of B-scan imagery demands specialized certification that training pipelines have not matched to deployment scale.
- Legacy signaling integration:New sensor networks must interface with decades-old traffic control architectures that lack standardized data protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rail Track and Rolling Stock Advanced NDT Inspection Systems Market |
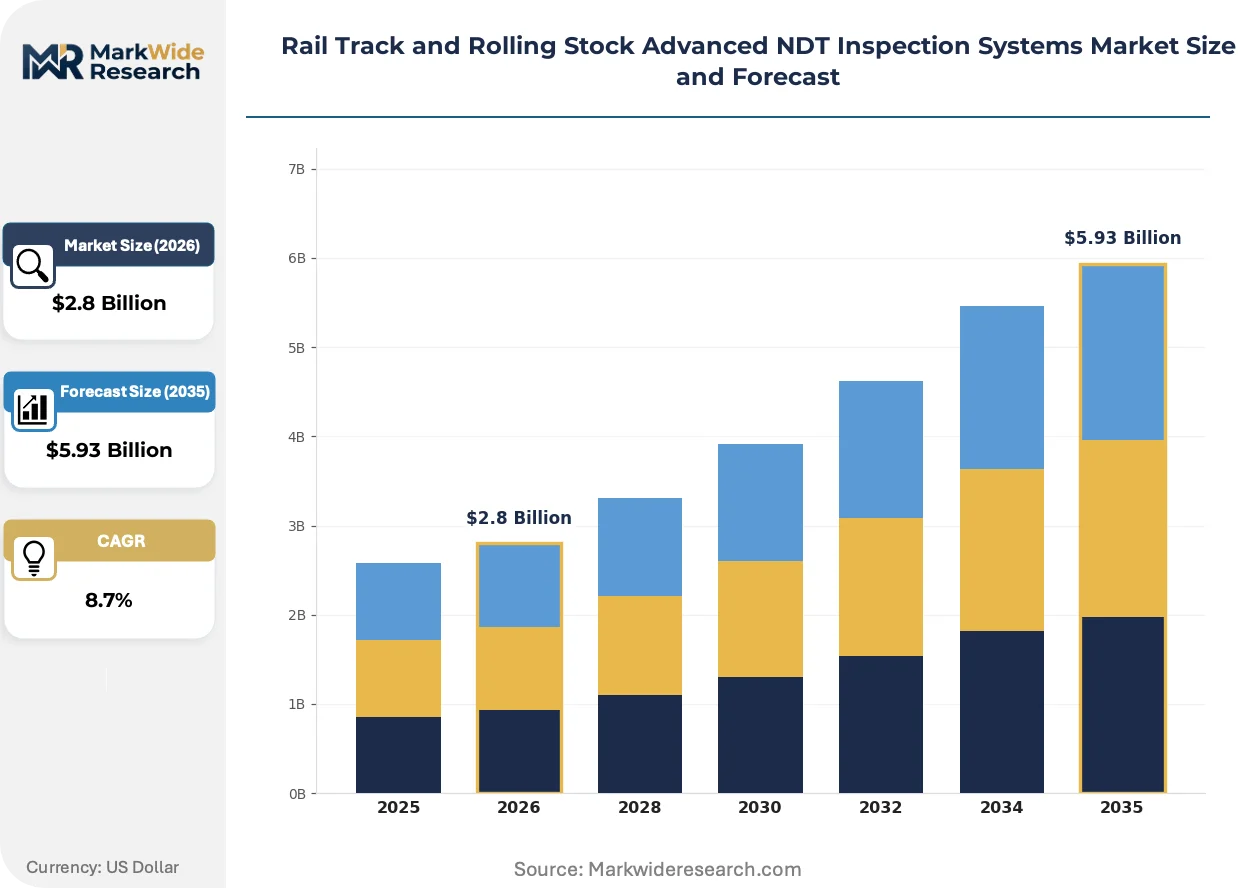
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.93 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Ultrasonic Testing, Eddy Current Testing, Magnetic Flux Leakage, Acoustic Emission, Visual Inspection, Laser Scanning Inspection Application: Rail Track Integrity, Wheel Defect Detection, Axle Inspection, Brake System Monitoring, Coupler Assessment, Pantograph Condition System Type: Portable Units, Fixed Installations, Automated Robots, Handheld Devices, Drone-Based Inspection, Remote Monitoring Systems End User: Rail Operators, Maintenance Providers, Safety Auditors, Infrastructure Managers, Government Bodies, OEM Inspectors |
| Companies Covered | Wabtec Corporation, Knorr-Bremse AG, HORIBA Group, RENK Group AG, ENSCO, MISTRAS Group, Eddyfi Technologies, Baker Hughes, Olympus Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rail Track and Rolling Stock Advanced NDT Inspection Systems Market Trends and Innovations
Inspection modality convergence and data architecture standardization are compressing procurement cycles while fragmenting vendor specialization boundaries across the value chain.
Phased-array ultrasonic instrumentation is miniaturizing from cart-mounted systems to handheld field units that maintenance crews deploy during brief track possessions. European infrastructure managers in Germany and France are accelerating adoption of portable configurations that reduce reliance on dedicated inspection trains. This form-factor shift is miniaturizing the addressable market for full-system integrators while expanding serviceable demand for component specialists.
Japan's MLIT rail bureau has tightened JIS E 1101 material standard enforcement for imported rail, indirectly mandating higher sensitivity thresholds for flaw detection equipment. Domestic and foreign suppliers must recalibrate ultrasonic testing systems to meet these specifications for market access. Rolling stock manufacturers sourcing rail from multiple origins face the steepest compliance burden as they harmonize inspection protocols across supply bases.
After-sales service unbundling is separating hardware procurement from predictive analytics subscriptions among Class I railroads. Infrastructure managers in North America now source inspection equipment through capital budgets while contracting algorithm training and defect classification separately. This bifurcation is most pronounced in the United States, where Union Pacific and BNSF negotiate multi-year data service agreements independent of original system vendors.
Rail Track and Rolling Stock Advanced NDT Inspection Systems Market Segmentation
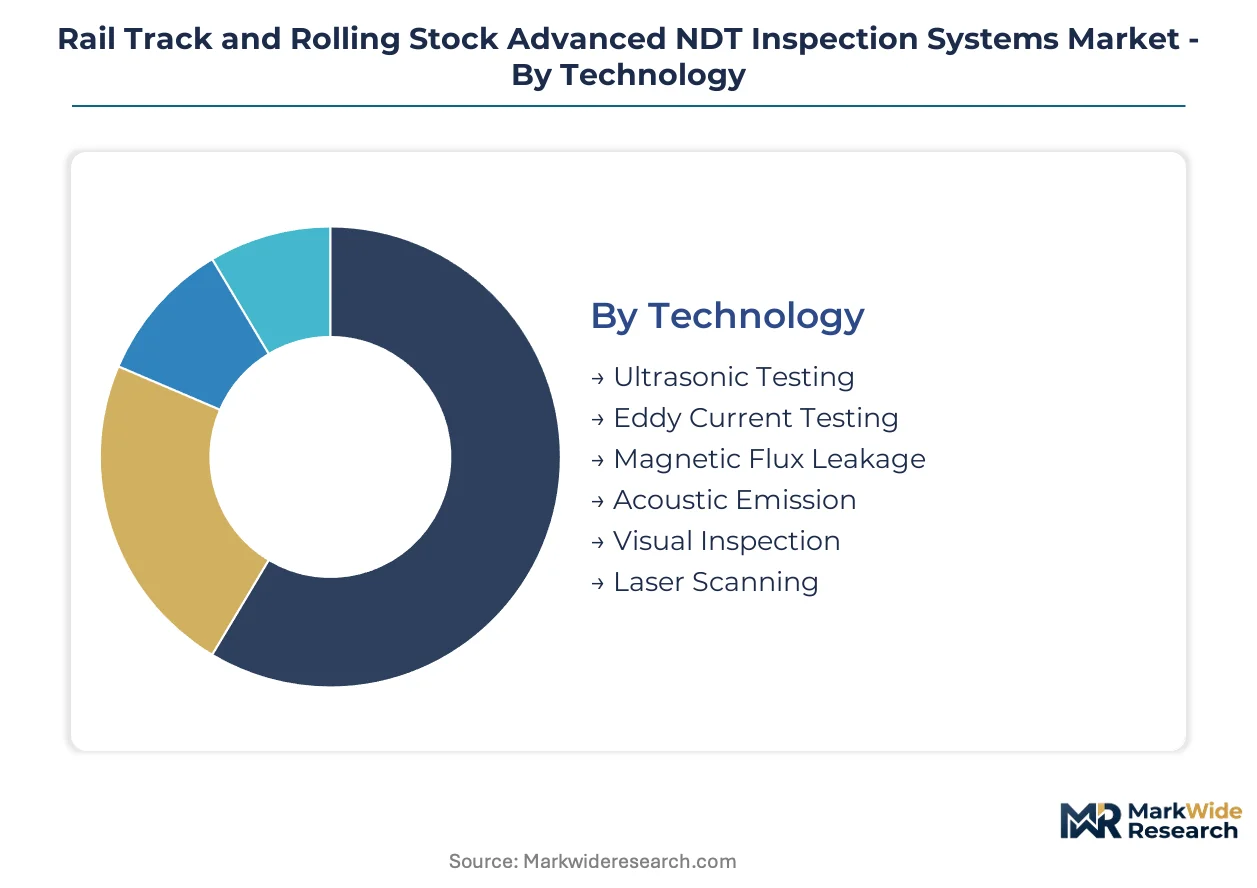
Segmentation in rail NDT inspection systems reveals how capital allocation splits between infrastructure-heavy fixed installations and mobility-focused portable platforms. Procurement patterns diverge sharply between high-speed corridors requiring continuous monitoring and regional networks relying on periodic manual inspection cycles.
Technology:
Margin pools concentrate in modalities that combine high capital intensity with recurring calibration service contracts, particularly where regulatory mandates specify minimum detection thresholds.
- Ultrasonic Testing:Phased-array configurations emit high-frequency acoustic pulses that map internal rail defects through time-of-flight analysis. Deutsche Bahn's sensor network deployment across Germany's high-speed corridors consumes the bulk of infrastructure manager capital, driven by EU Agency for Railways CCS TSI sensitivity mandates for trans-European routes.
- Magnetic Flux Leakage:Saturated magnetic fields reveal surface-breaking cracks through flux distortion patterns detected by Hall-effect sensors. North American Class I railroads under Federal Railroad Administration 49 CFR Part 213 pressure represent the densest demand cluster, with inspection interval tightening for operations above 80 mph multiplying system procurement.
- Eddy Current Testing:Alternating magnetic fields induce circulating currents that surface conductivity variations in wheel rims and axles.
- Acoustic Emission:Stress-wave monitoring captures propagating crack energy release during train passage.
- Visual Inspection:High-resolution imaging systems document surface corrosion and geometric deviations for compliance archives.
- Laser Scanning:Triangulation-based profilometry measures rail head wear and gauge geometry without contact.
The dominant share belongs to Ultrasonic Testing, while Laser Scanning is climbing the fastest as infrastructure managers seek track possession window compression.
Inspection Application:
Application segmentation tracks where traffic density and speed differentials create tiered safety-critical inspection regimes across network architectures.
- Rail Track Integrity:Continuous welded rail monitoring for internal transverse defects and rolling contact fatigue governs infrastructure manager procurement budgets. Japan's MLIT rail bureau enforcement of JIS E 1101 material standards for imported rail drives sensitivity upgrades in East Asian procurement specifications.
- Wheel Defect Detection:Tread hollows, thermal cracks, and out-of-round conditions demand high-throughput examination in railyards. French freight operators pursuing EU Green Deal extended asset life clauses generate expanding service contracts for automated wheel-set inspection without uncoupling.
- Axle Inspection:Subsurface fatigue in hollow axles requires ultrasonic immersion or phased-array scanning.
- Brake System Monitoring:Friction material thickness and thermal damage assessment supports predictive maintenance scheduling.
- Coupler Assessment:Knuckle wear and alignment tolerances affect interoperability across rolling stock fleets.
- Pantograph Condition:Carbon strip wear and head geometry inspection protects overhead catenary infrastructure.
Rail Track Integrity commands the deepest capital allocation, though Wheel Defect Detection is gaining share fastest through railyard automation investments.
System Type:
System configuration choices reflect the operational trade-off between inspection frequency and track access constraints across network hierarchies.
- Fixed Installations:Wayside sensor arrays at critical locations—tunnels, bridges, high-speed entry points—generate terabyte-scale datasets feeding machine-learning classification pipelines. Germany's 33,000-kilometer digital rail program establishes reference architectures that Dutch and Swiss infrastructure managers replicate for Alpine corridor monitoring.
- Automated Robots:Self-propelled units operating between scheduled services address possession window compression in dense networks. Japanese Shinkansen operators deploy autonomous platforms during overnight maintenance windows, avoiding traffic disruption on corridors exceeding 300 trains daily.
- Portable Units:Cart-mounted or backpack configurations enable rapid deployment to defect locations identified by continuous monitoring.
- Handheld Devices:Miniaturized phased-array instruments support field weld inspection during track possessions.
- Drone-Based Inspection:Aerial platforms examine overhead electrification and bridge soffits without scaffolding.
- Remote Monitoring Systems:Cloud-connected sensor networks enable centralized defect triage across distributed infrastructure.
Fixed Installations retain the largest installed base, though Automated Robots show the steepest expansion trajectory as possession windows contract.
End User:
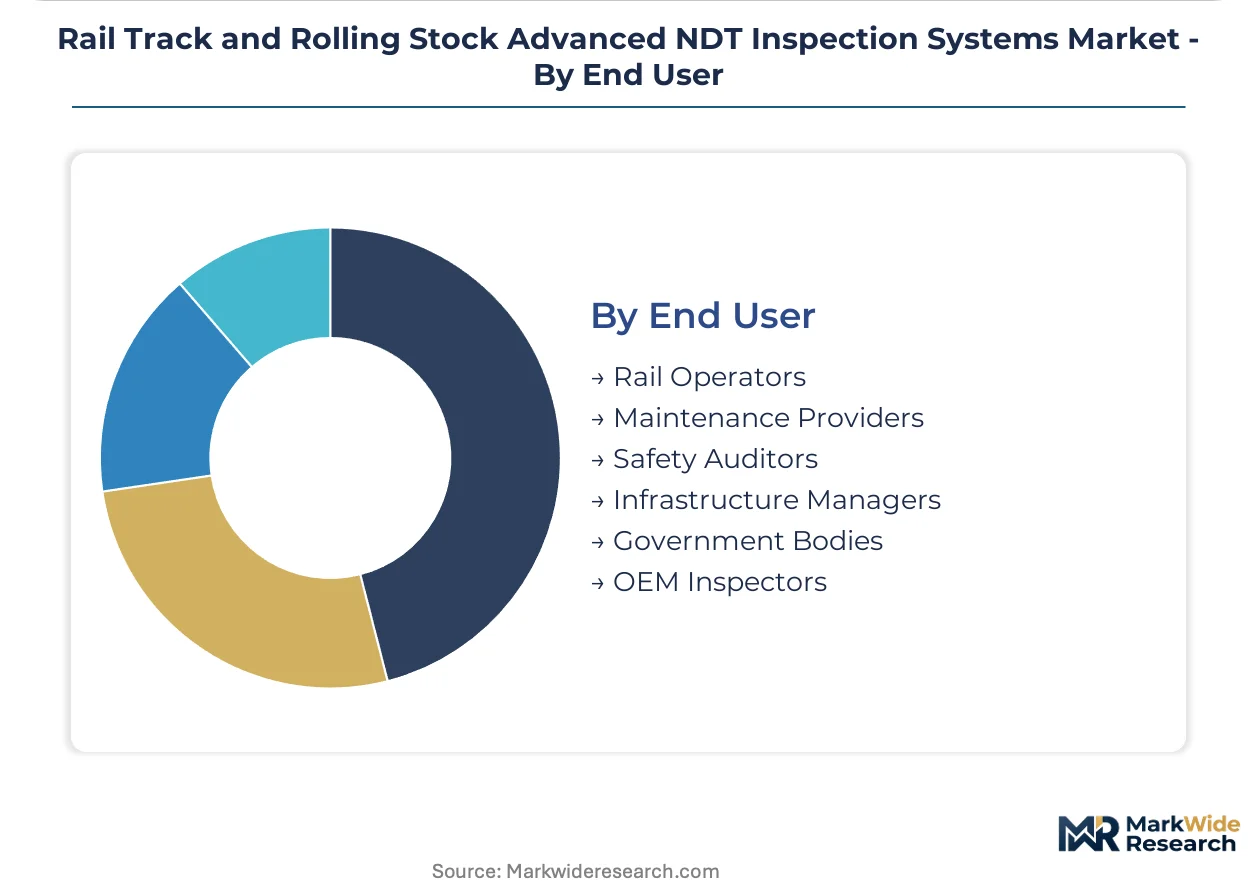
End-user segmentation captures how procurement authority splits between asset owners, contracted service providers, and regulatory enforcement bodies with divergent budget cycles.
- Rail Operators:Integrated passenger and freight carriers with direct asset ownership—Deutsche Bahn, SNCF, JR East—bundle inspection procurement with rolling stock and infrastructure capital programs. These entities negotiate multi-year service agreements that unbundle hardware from predictive analytics subscriptions.
- Infrastructure Managers:Separated track authorities—Network Rail, ProRail, Infrabel—face EU harmonized safety mandates compelling modernization of legacy ultrasonic installations across trans-European corridors.
- Maintenance Providers:Specialized contractors deliver inspection services under performance-based contracts.
- Safety Auditors:Independent verification bodies certify compliance with national and international standards.
- Government Bodies:National rail regulators specify inspection regime minima and audit enforcement.
- OEM Inspectors:Rolling stock manufacturers verify component integrity before delivery acceptance.
Rail Operators control the dominant procurement volume, while Infrastructure Managers are accelerating spending fastest under regulatory compliance pressure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany and Japan demonstrate the lowest price elasticity, absorbing premium sensor networks under regulatory mandates, while operators in India and Southeast Asia prioritize cost-efficient portable units despite accelerating traffic density.
Germany
Deutsche Bahn's digital rail program drives sensor network deployment across 33,000 kilometers of track, creating reference architectures that Dutch and Swiss infrastructure managers replicate for Alpine corridor monitoring. The EU Agency for Railways enforces CCS TSI harmonized NDT performance criteria that compel flaw detection sensitivity upgrades across trans-European networks. Bavaria and Baden-Württemberg concentrate manufacturing of high-frequency ultrasonic transducers, with precision component suppliers clustered around Stuttgart and Munich engineering ecosystems.
United States
Class I railroads under Federal Railroad Administration pressure represent the densest demand cluster for magnetic flux leakage systems, with inspection interval tightening for operations above 80 mph multiplying capital requirements. The FRA enforces track safety standards under 49 CFR Part 213, mandating rail flaw detection at defined intervals that escalate compliance costs without proportional traffic revenue increases. Chicago and Omaha serve as procurement decision centers where Union Pacific and BNSF negotiate multi-year data service agreements independent of original system vendors.
Japan
Shinkansen operators deploy autonomous robotic platforms during overnight maintenance windows, avoiding traffic disruption on corridors exceeding 300 trains daily. The MLIT rail bureau applies JIS E 1101 material standards that indirectly dictate inspection sensitivity thresholds for imported and domestic rail alike. The Kanto region around Tokyo anchors domestic supplier relationships, while Osaka-based maintenance providers specialize in wheel-set examination automation for freight operators.
France
SNCF bundles inspection procurement with rolling stock capital programs, negotiating multi-year service agreements that unbundle hardware from predictive analytics subscriptions. EU Green Deal extended asset life requirements embed NDT inspection into sustainability-linked financing instruments for rail infrastructure. The Île-de-France region and Lyon corridor concentrate deployment of self-propelled inspection units operating between scheduled services on high-speed lines.
India
Indian Railways accelerates procurement of automated track inspection systems as high-speed corridor development intensifies, though budget constraints favor phased-array portable units over fixed installations. The Central Electricity Authority and Bureau of Indian Standards indirectly influence rail material specifications that shape inspection equipment import requirements. The Delhi-Mumbai and Delhi-Kolkata industrial corridors concentrate maintenance provider activity, with Mumbai-based contractors delivering inspection services under performance-based contracts.
Rail Track and Rolling Stock Advanced NDT Inspection Systems Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier that fragments across modality-specific competencies and regional service footprints. Full-system integrators leverage installed equipment bases to bundle predictive diagnostics with original hardware, while component specialists anchor positions through ultrasonic and eddy current service contracts with Class I railroads. Portable instrument manufacturers occupy a distinct niche concentrated on field weld inspection applications. Competitive moves center on after-sales service unbundling that separates hardware procurement from predictive analytics subscriptions, alongside geographic expansion through reference architecture replication.
Among North American-integrated conglomerates, Wabtec Corporation occupies a position exemplifying the full-system integrator archetype, while MISTRAS Group anchors the specialized service contractor tier through long-term maintenance agreements. Canadian-based Eddyfi Technologies represents the portable instrumentation specialist segment, concentrating on miniaturized phased-array configurations for rapid deployment during brief track possessions.
| Leading Market Players |
|---|
| Wabtec Corporation |
| Knorr-Bremse AG |
| HORIBA Group |
| RENK Group AG |
| ENSCO |
| MISTRAS Group |
| Eddyfi Technologies |
| Baker Hughes |
| Olympus Corporation |
| Others |
Pricing and Supply Chain Analysis
Long-term service agreements with embedded calibration and algorithm update clauses lock in both supply access and price visibility for infrastructure managers navigating EU CCS TSI compliance mandates. These multi-year contracts insulate German and Japanese component suppliers from spot-market volatility while binding Class I railroads to predictable cost structures.
Pricing Analysis
After-sales service revenue tiers—spanning predictive analytics subscriptions, sensor recalibration, and defect classification algorithm updates—drive lifetime value for system integrators. Three-tier pricing structure across premium, standard, and economy levels segments buyers by inspection speed requirements and data processing depth. Cost compression in portable phased-array instrumentation intensifies as Chinese manufacturers enter the European certification pipeline. Regional freight operators in India and Southeast Asia exhibit the highest price sensitivity, absorbing only economy-tier hardware without bundled analytics.
Supply Chain Analysis
Germany and Japan anchor precision manufacturing of high-frequency ultrasonic transducers and electromagnetic sensor coils for rail NDT systems. Supply rests on specialized piezoelectric ceramics from Bavarian suppliers and precision-wound coils from Osaka-based component houses. Single-source vulnerability concentrates in Hall-effect sensor arrays for magnetic flux leakage detection. Distribution runs through system integrators that bundle hardware with installation and multi-year maintenance contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
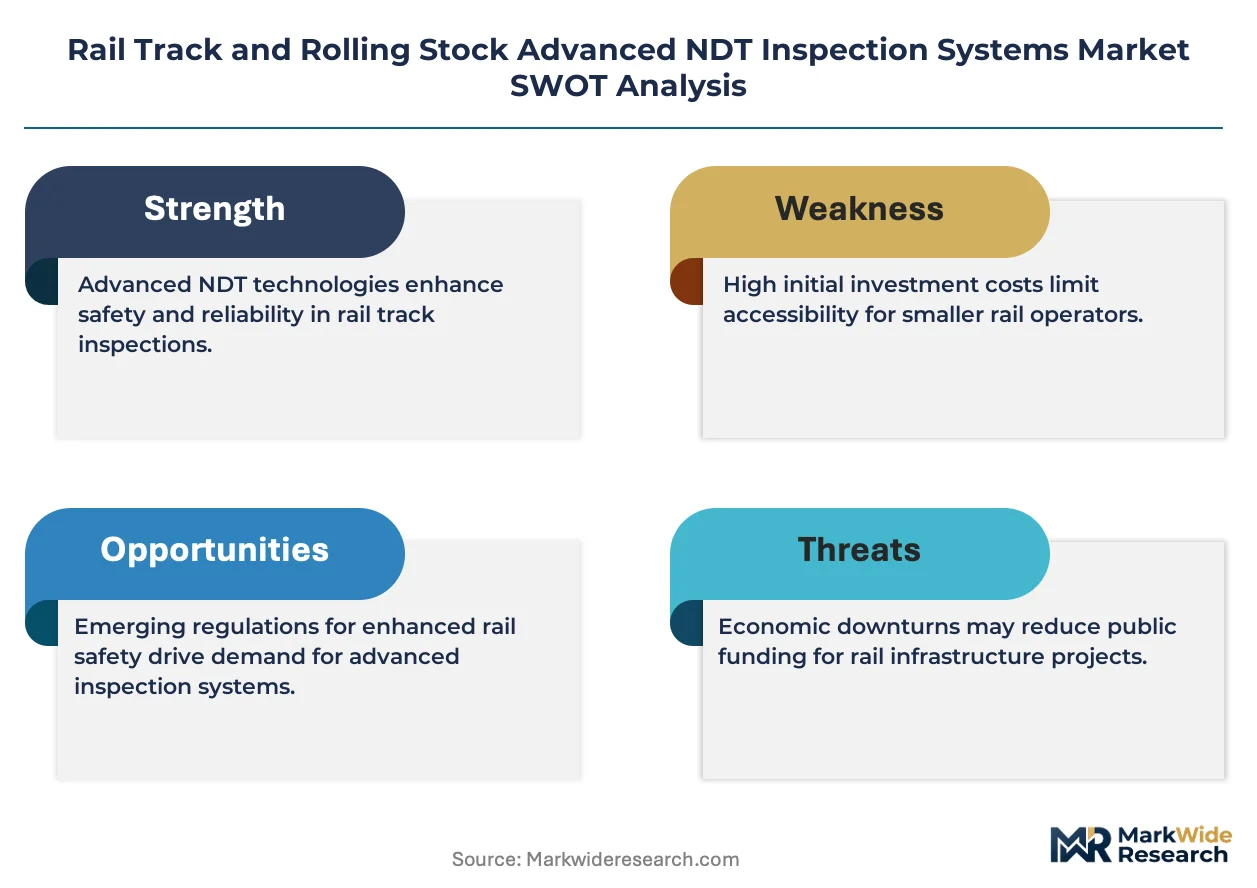
Optical sensing substitution—laser-based geometric measurement systems that capture surface defects magnetic flux leakage misses—threatens incumbent modality providers who fail to diversify. Incumbents must navigate this displacement pressure while defending installed-base revenue streams.
For Market Incumbents: Shield fixed-installation revenue pools by embedding predictive analytics subscriptions into CCS TSI-mandated upgrade cycles. Acquire portable instrumentation specialists to capture field weld inspection demand from Deutsche Bahn's maintenance contractors. Vertical integration into high-frequency transducer manufacturing reduces exposure to German component supplier pricing power.
For New Entrants and Emerging Players: EU CCS TSI certification fast-track opens access to trans-European corridor procurement from Dutch and Swiss infrastructure managers replicating German reference architectures. Target drone-based axle inspection services for French freight operators pursuing EU Green Deal extended asset life clauses. White-space concentration sits in handheld phased-array units for Indian Railways' budget-constrained corridor development.
For Investors and Strategic Acquirers: Component specialists with captive ultrasonic transducer technology and established Class I railroad service contracts represent the highest-conviction acquisition profile. Long-term viability hinges on algorithm differentiation rather than hardware margins as data service unbundling accelerates. Watch for MLIT enforcement actions on JIS E 1101 sensitivity thresholds as inflection indicators for East Asian procurement specification shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Sensor Network Platform Integration | Deutsche Bahn's digital rail program establishes reference architectures replicated across Alpine corridors. |
| Phased-Array Miniaturization | Portable configurations reduce track possession windows for SNCF and JR East maintenance crews. |
| Predictive Analytics Unbundling | Union Pacific and BNSF negotiate data service agreements independent of original system vendors. |
| EU CCS TSI Certification Investment | Harmonized sensitivity mandates compel flaw detection upgrades across trans-European networks. |
| Autonomous Robotic Deployment | Self-propelled units address possession window compression on Japanese Shinkansen corridors exceeding 300 trains daily. |
Research Methodology
The analysis maps ultrasonic testing, magnetic flux leakage, eddy current, and emerging optical sensing modalities, each validated through infrastructure manager procurement officers, Class I railroad maintenance directors, and component supplier technical leads. Primary interviews with EU Agency for Railways certification specialists and Japan MLIT standards engineers combined with secondary validation from Federal Railroad Administration enforcement databases, EU CCS TSI technical specifications, and customs trade records. Bottom-up equipment procurement tracking and top-down infrastructure spending estimates triangulate market sizing.
Consistency checks validated volume and value outputs against external benchmarks across the projection horizon. Segmentation dimensions modeled include inspection modality, system configuration, application type, and end-user procurement authority. CAGRs derive from equipment replacement cycles tied to regulatory interval tightening and traffic density growth assumptions. Forecast inputs incorporate Deutsche Bahn sensor network deployment timelines and Indian Railways high-speed corridor development schedules.
Underlying assumptions cover EU CCS TSI harmonization progress, MLIT enforcement consistency, and Class I railroad capital allocation stability, with deviation risk concentrated in optical sensing substitution rates and Chinese manufacturer certification timelines. Recalibration cycles align with material shifts in trans-European infrastructure modernization funding and Federal Railroad Administration rulemaking activity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Testing and Simulation
Motor Testing Equipment Market
Automotive Testing and Simulation
Automotive Simulation Market
Automotive Testing and Simulation
Automotive Battery Testing Market
Automotive Testing and Simulation
On Board Diagnostics Device Market
Automotive Testing and Simulation
Dynamometer Market
Automotive Testing and Simulation
On-Board Data Logger and Road Test Equipment System Market
Automotive Testing and Simulation
Vehicle Radar Test System Market
Automotive Testing and Simulation
Commercial Vehicle and Off-Highway RADAR Market
Automotive Testing and Simulation
Global Automotive Wind Tunnel Market
Automotive Testing and Simulation
Tire Testing Machine Market
Automotive Testing and Simulation
ADAS Calibration Equipment Market
Automotive Testing and Simulation
ADAS Calibration and Alignment Equipment Systems Market
Automotive Testing and Simulation
Autonomous Tank Farm Inspection and Corrosion Mapping Robot Systems Market
Automotive Testing and Simulation
Automotive Emission Test Equipment Market
Automotive Testing and Simulation
Automotive Test Equipment Market
Automotive Testing and Simulation
Torque Gauge Market