
 High-Speed Highway Pilot and Lane Change Scenario Test Platforms Market | 2026-2036
High-Speed Highway Pilot and Lane Change Scenario Test Platforms Market Size, Share, and Industry Trends Forecast 2026-2036
High-Speed Highway Pilot and Lane Change Scenario Test Platforms Market Insights
UN ECE R79 is consolidating the cost-of-entry calculus for automated lane change validation, forcing test platform vendors to prove functional safety across speed ranges above 60 km/h. dSPACE leverages its real-time processor architecture to dominate hardware-in-the-loop deployments for German OEMs. Applied Intuition sustains cloud-native simulation workflows that compete on scenario scalability. Foretellix anchors its position through coverage-driven verification methods that extend traceability to safety cases.
High-Speed Highway Pilot and Lane Change Scenario Test Platforms comprise integrated validation environments combining real-time hardware interfaces, sensor emulation, and traffic scenario generation to reproduce highway merge, split, and cut-in maneuvers with sub-millisecond timing precision. These systems enable repeatable verification of automated driving decisions before physical prototype deployment, reducing field test mileage requirements by orders of magnitude. Hardware-in-the-Loop systems occupy the largest installed base due to their maturity in powertrain and chassis validation, while Vehicle-in-the-Loop configurations represent the fastest-expanding segment as OEMs demand closed-loop testing with actual steering and braking actuators. Artificial Intelligence and Sensor Fusion technologies concentrate margin pools where platforms must emulate camera-radar-lidar fusion behavior under adversarial weather conditions.
NHTSA in the United States, UN ECE working groups in Europe, and Japan's MLIT shape demand through divergent approval frameworks for automated lane change functionality. NHTSA's standing general order on crash reporting compels OEMs to document scenario coverage, directly stimulating investment in traceable test databases. Stakeholders must monitor whether regulatory convergence or fragmentation wins as China, Japan, and European authorities advance incompatible certification roadmaps.
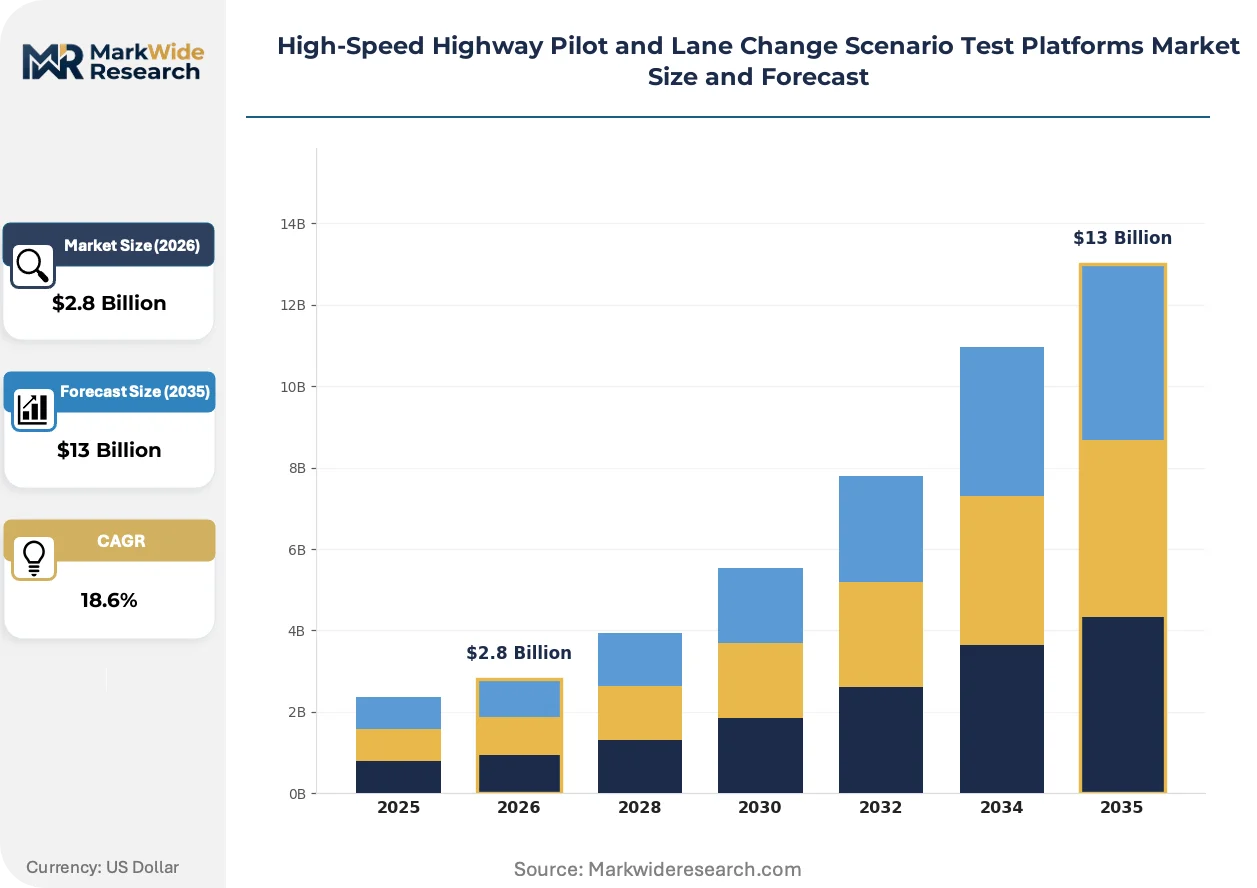
Market Dynamics
Hardware-in-the-loop and vehicle-in-the-loop architectures are converging under pressure from UN ECE R79 lane-keeping mandates, forcing test platform vendors to unify real-time processor performance with physical actuator feedback loops.
Growth Catalysts
- UN ECE R79 mandates:European type-approval requirements for automated lane-keeping systems above 60 km/h compel OEMs to procure validated test platforms with documented functional safety coverage.
- Sensor fusion complexity:Camera-radar-lidar integration under adversarial weather conditions demands sub-millisecond timing precision that only advanced emulation environments can deliver.
- German automotive clusters:Stuttgart and Munich validation centers concentrate procurement budgets as Tier-1 suppliers co-locate with OEM engineering teams.
Market Restraints
- Real-time processor supply concentration:Specialized compute hardware for hardware-in-the-loop systems sources from limited semiconductor foundries, creating procurement bottlenecks.
- Physical facility requirements:Vehicle-in-the-loop installations demand climate-controlled proving grounds with dynamic platform infrastructure, constraining deployment flexibility.
- Divergent certification roadmaps:NHTSA crash reporting protocols, UN ECE working group timelines, and Japan MLIT approval frameworks impose redundant validation cycles on global OEMs.
Strategic Opportunities
- Cloud-native simulation workflows:Scalable scenario generation without physical hardware footprint opens validation access to mid-size automotive suppliers previously excluded from high-capital testing.
- Traceable test databases:NHTSA standing general order on crash documentation creates demand for auditable scenario coverage platforms that link simulation runs to safety cases.
- Artificial intelligence verification:Neural network validation for highway pilot decisions requires new emulation capabilities at the intersection of software-in-the-loop and hardware-in-the-loop architectures.
Industry Challenges
- Functional safety engineering talent:ISO 26262 expertise for automotive software validation remains concentrated among specialists in Germany and Japan, constraining platform vendor expansion.
- Legacy chassis validation integration:Established hardware-in-the-loop installations for powertrain testing require costly retrofit to accommodate automated driving sensor emulation and traffic scenario injection.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High-Speed Highway Pilot and Lane Change Scenario Test Platforms Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $13 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hardware-in-the-Loop, Software-in-the-Loop, Vehicle-in-the-Loop, Scenario-Based Simulators, Modular Testbeds Technology: Artificial Intelligence, Sensor Fusion, Machine Learning, Real-Time Data Processing, V2X Communication Application: Autonomous Vehicle Validation, Driver Assistance Calibration, Safety Performance Testing, Behavior Prediction, Collision Avoidance End User: OEMs, Tier-1 Suppliers, System Integrators, Testing Laboratories, Research Institutions |
| Companies Covered | IPG Automotive, dSPACE, ANSYS, Vector Informatik, Siemens Digital Industries Software, Foretellix, Applied Intuition, Hexagon, MathWorks, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High-Speed Highway Pilot and Lane Change Scenario Test Platforms Market Trends and Innovations
Artificial intelligence is penetrating test platform architectures at every layer, from scenario generation algorithms to real-time sensor data synthesis, compressing the boundary between simulation fidelity and physical prototype validation.
Sensor emulation hardware is absorbing software-defined radio architectures for radar and lidar signal generation, enabling frequency-modulated continuous-wave replication without anechoic chamber infrastructure. German OEM validation centers are deploying these systems at scale for highway cut-in scenario verification. The technology is absorbing capital previously allocated to fleet-based field testing, reducing required physical mileage by orders of magnitude while maintaining regulatory traceability.
NHTSA standing general order on crash reporting compels documented scenario coverage for automated lane change functionality, creating procurement specifications that favor platforms with built-in audit trails. OEMs must demonstrate traceability from simulation parameters to safety case arguments. United States-based validation programs are responding by mandating coverage-driven verification methods in supplier contracts.
Buyer concentration among German, Japanese, and United States OEMs is consolidating procurement decisions into centralized validation centers with multi-year platform deployment cycles. Tier-1 suppliers are losing direct purchasing authority as OEMs internalize scenario database ownership and require vendor-neutral data formats. Stuttgart and Munich clusters exhibit this pattern most acutely, with supplier testing now subordinated to OEM-controlled vehicle-in-the-loop facilities.
High-Speed Highway Pilot and Lane Change Scenario Test Platforms Market Segmentation
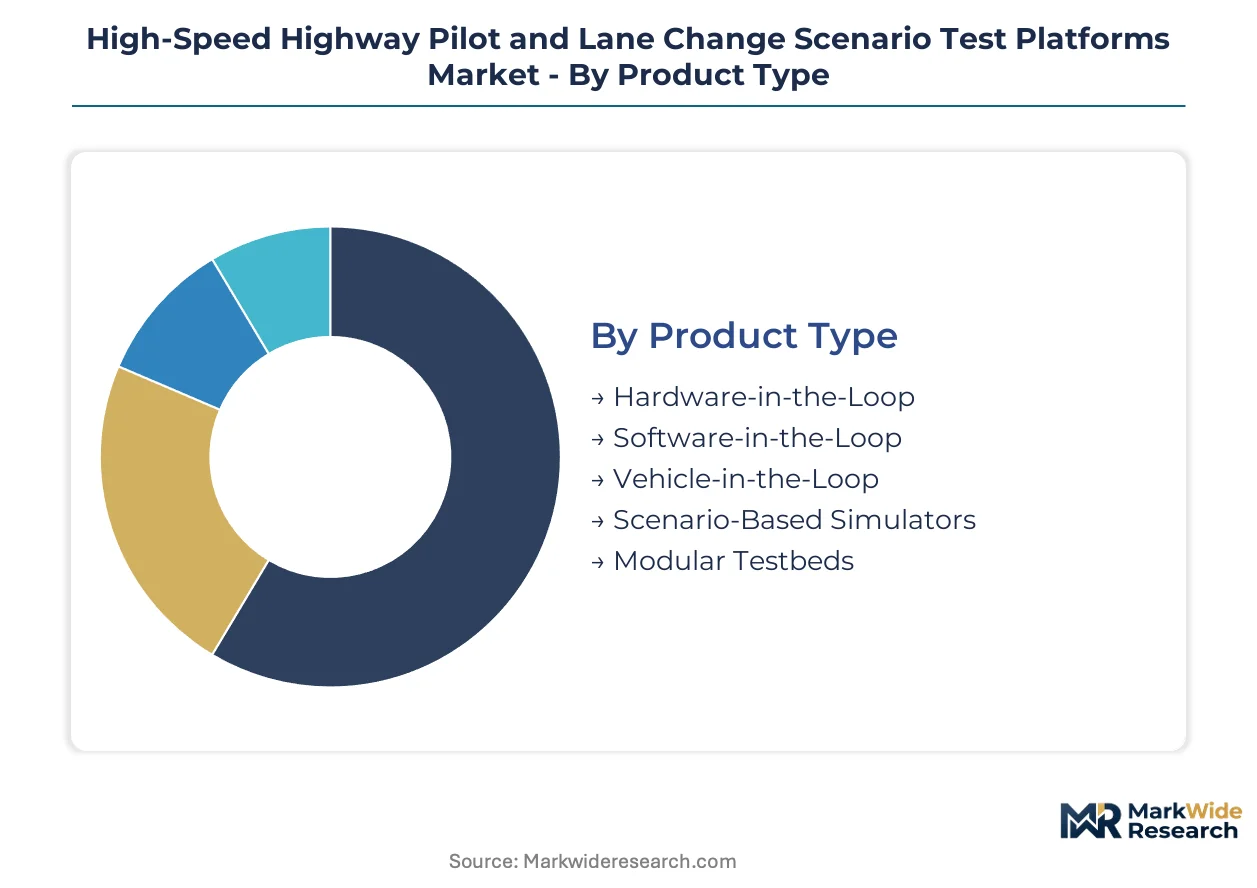
Test platform procurement decisions hinge on certification scope—UN ECE R79 mandates for lane-keeping above 60 km/h demand specific architectural capabilities that segment the market into functionally distinct tiers. OEM validation centers map product categories directly to regulatory approval pathways, concentrating investment where traceability requirements intersect with real-time performance thresholds.
Product Type:
UN ECE R79 lane-keeping mandates impose divergent certification burdens across architectures—hardware-in-the-loop dominates where functional safety documentation is mandatory, while vehicle-in-the-loop configurations face escalating physical facility requirements.
- Hardware-in-the-Loop:Real-time processor architectures interface with electronic control units to replicate steering and braking dynamics without physical vehicle deployment. German OEM validation centers in Stuttgart and Munich concentrate procurement here for UN ECE R79 documentation requirements, constrained by semiconductor foundry bottlenecks for specialized compute hardware.
- Vehicle-in-the-Loop:Closed-loop configurations integrate actual steering and braking actuators with dynamic platform infrastructure, demanding climate-controlled proving grounds. Fastest-expanding segment as OEMs internalize validation ownership, though physical facility requirements limit supplier flexibility.
- Software-in-the-Loop:Pure simulation environments enable early algorithm verification without hardware dependencies. Mid-size suppliers excluded from high-capital testing increasingly adopt these workflows for scenario scalability.
- Scenario-Based Simulators:Traffic pattern generation systems replicate highway merge, split, and cut-in maneuvers with sub-millisecond timing precision. NHTSA crash reporting protocols stimulate demand for documented scenario coverage.
- Modular Testbeds:Reconfigurable architectures allow incremental sensor emulation upgrades. Tier-1 suppliers favor these for backward compatibility with legacy chassis validation installations.
Leading the category by volume: Hardware-in-the-Loop. Growing fastest: Vehicle-in-the-Loop.
Technology:
Margin concentration tracks where emulation fidelity requirements intersect with adversarial condition testing—sensor fusion and real-time data processing command premium positioning due to UN ECE R79 timing precision mandates.
- Artificial Intelligence:Neural network validation for highway pilot decisions requires new emulation capabilities at the intersection of software-in-the-loop and hardware-in-the-loop architectures. German and Japanese OEMs concentrate procurement for ISO 26262 traceability.
- Sensor Fusion:Camera-radar-lidar integration under adversarial weather conditions demands sub-millisecond timing precision. Stuttgart validation centers deploy these systems at scale for highway cut-in scenario verification.
- Machine Learning:Algorithm training datasets for behavior prediction require scalable scenario generation without physical hardware footprint.
- Real-Time Data Processing:Sub-millisecond latency guarantees for closed-loop actuator control. Limited semiconductor foundry supply creates procurement bottlenecks.
- V2X Communication:Vehicle-to-everything signal emulation for cooperative lane change scenarios. Emerging demand as Japan's MLIT advances connected vehicle approval frameworks.
Commanding the highest margins: Sensor Fusion. Expanding most quickly: Artificial Intelligence.
Application:
Validation depth determines cost tier—autonomous vehicle validation absorbs capital previously allocated to fleet-based field testing, while driver assistance calibration serves as the entry point for mid-size suppliers.
- Autonomous Vehicle Validation:Comprehensive verification environments reduce required physical mileage by orders of magnitude while maintaining regulatory traceability. OEM validation programs in Germany, Japan, and the United States concentrate procurement budgets here.
- Safety Performance Testing:UN ECE R79 functional safety coverage documentation for lane-keeping systems above 60 km/h. NHTSA standing general order on crash reporting compels auditable scenario coverage platforms.
- Driver Assistance Calibration:Entry-tier validation for adaptive cruise control and lane departure warning systems. Mid-size automotive suppliers access through cloud-native simulation workflows.
- Behavior Prediction:Traffic participant trajectory forecasting for cut-in and merge scenarios. Requires coverage-driven verification methods extending traceability to safety cases.
- Collision Avoidance:Emergency maneuver verification under adversarial conditions. Stuttgart and Munich clusters deploy vehicle-in-the-loop configurations for this application.
Absorbing the largest capital share: Autonomous Vehicle Validation. Gaining share fastest: Safety Performance Testing.
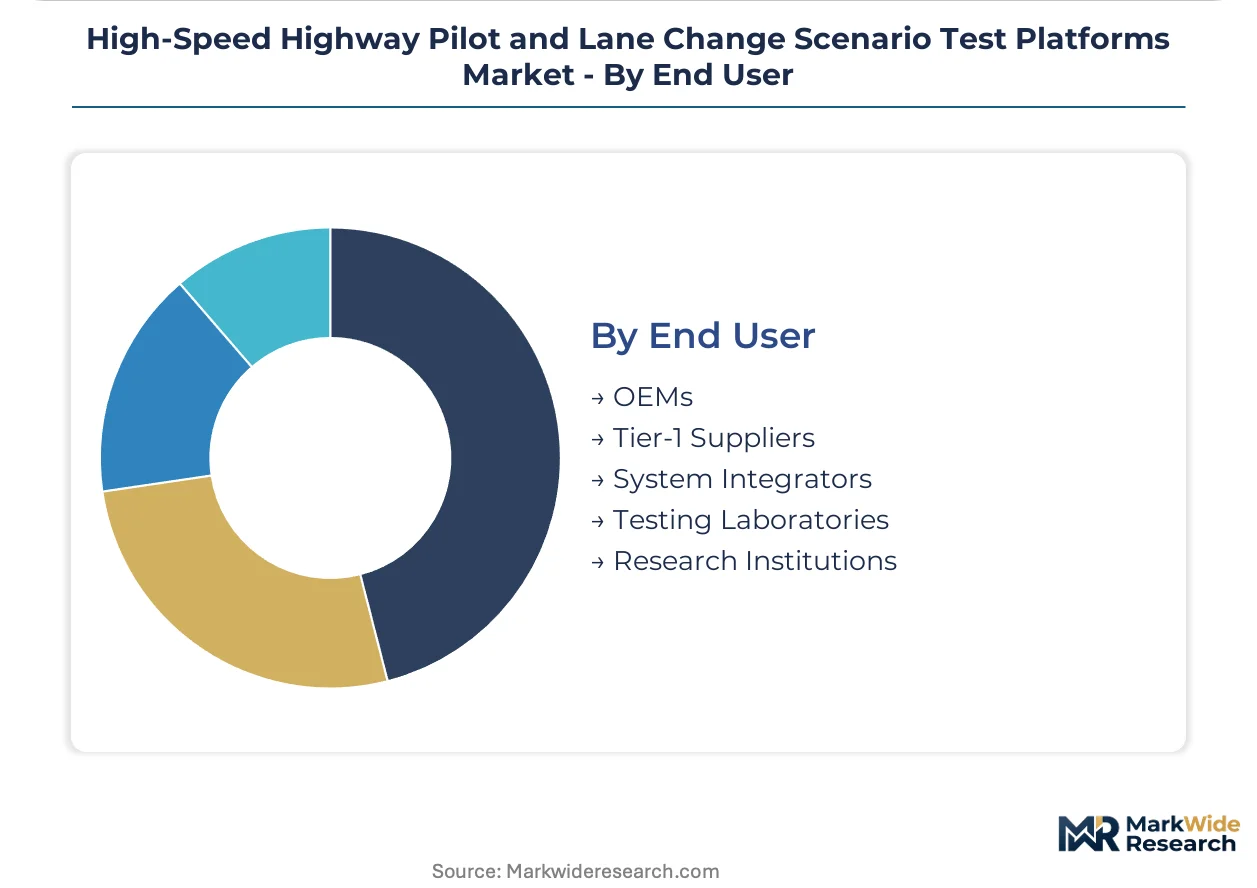
End User:
Buyer concentration is consolidating procurement decisions into centralized validation centers with multi-year platform deployment cycles—OEMs internalize scenario database ownership while Tier-1 suppliers lose direct purchasing authority.
- OEMs:German, Japanese, and United States manufacturers internalize validation center ownership and require vendor-neutral data formats. Stuttgart and Munich clusters exhibit this pattern most acutely.
- Tier-1 Suppliers:Steering and braking system specialists subordinate testing to OEM-controlled vehicle-in-the-loop facilities, retaining procurement only for modular testbed retrofits.
- System Integrators:Validation workflow assembly for mid-size automotive suppliers previously excluded from high-capital testing.
- Testing Laboratories:Third-party certification services for UN ECE R79 type-approval documentation. Concentrated in German automotive clusters.
- Research Institutions:Academic and government-funded scenario database development. Japan's MLIT-funded programs support this segment.
Controlling the largest procurement volume: OEMs. Expanding fastest: Testing Laboratories.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German automotive clusters in Stuttgart and Munich operate as the dominant special-economic-zone for test platform procurement, with validation center investments concentrating where Tier-1 suppliers co-locate with OEM engineering teams.
Germany
KBA type-approval requirements for automated lane-keeping systems above 60 km/h compel OEMs to procure validated hardware-in-the-loop platforms. UN ECE R79 mandates documented functional safety coverage. Stuttgart and Munich validation centers absorb capital previously allocated to fleet-based field testing.
United States
NHTSA standing general order on crash reporting stimulates investment in traceable test databases for automated lane change verification. Federal procurement specifications favor platforms with built-in audit trails. Detroit and Silicon Valley engineering centers internalize scenario database ownership.
Japan
MLIT approval frameworks for highway pilot functionality shape domestic validation program requirements. Government-funded scenario database development supports research institution partnerships. Nagoya and Tokyo metropolitan clusters deploy vehicle-in-the-loop configurations for cut-in scenario verification.
China
GB standards for intelligent connected vehicles establish emulation fidelity benchmarks for sensor fusion validation. MIIT-directed certification roadmaps advance incompatible with European and Japanese frameworks. Shanghai and Beijing automotive engineering centers concentrate procurement for domestic OEM programs.
South Korea
MFDS-aligned functional safety expectations for automotive software validation concentrate expertise demand. National R&D programs fund hardware-in-the-loop infrastructure for Hyundai-Kia supplier networks. Seoul Capital Area validation facilities expand procurement of real-time processor architectures.
High-Speed Highway Pilot and Lane Change Scenario Test Platforms Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across the test platform landscape, creating a tiered structure where scale advantages clash with architectural agility. Siemens Digital Industries Software and ANSYS leverage cross-industry simulation portfolios to anchor enterprise relationships. dSPACE and IPG Automotive exemplify pure-play specialists commanding premium positioning through real-time processor dominance. Competitive moves concentrate on strategic partnerships for sensor emulation integration and geographic expansion into German automotive clusters.
Among German-based validation specialists, dSPACE and Vector Informatik occupy positions within the hardware-in-the-loop tier, their Stuttgart and Munich proximity anchoring relationships with concentrated OEM procurement centers. Foretellix and Applied Intuition represent the coverage-driven verification archetype, sitting within cloud-native and scenario-scalability segments respectively. These five entities exemplify how competitive positioning fragments across architectural specialization rather than consolidating around unified platform offerings.
| Leading Market Players |
|---|
| IPG Automotive |
| dSPACE |
| ANSYS |
| Vector Informatik |
| Siemens Digital Industries Software |
| Foretellix |
| Applied Intuition |
| Hexagon |
| MathWorks |
| Others |
Pricing and Supply Chain Analysis
OEM consolidation of validation center ownership into Stuttgart and Munich clusters is forcing test platform vendors to absorb specialized compute hardware costs or surrender margin, compressing pricing power across hardware-in-the-loop and vehicle-in-the-loop tiers.
Pricing Analysis
Short lead-time premiums of 15-25 percent apply to real-time processor architectures sourced from limited semiconductor foundries, while spot inventory discounts emerge for modular testbed retrofits compatible with legacy chassis installations. Pricing stratifies across premium, standard, and economy tiers based on UN ECE R79 certification documentation depth and after-sales scenario database maintenance. Cost compression in the standard tier is intensifying because Tier-1 suppliers are losing direct procurement authority to OEM-controlled validation centers. Mid-size automotive suppliers exhibit the highest price sensitivity, while German OEMs prioritize traceability over unit cost.
Supply Chain Analysis
Freight costs for climate-controlled proving ground infrastructure and dynamic platform components from Germany, Japan, and the United States concentrate supply chain expenditure in the vehicle-in-the-loop segment. Real-time data processing hardware draws from Taiwan and South Korean semiconductor foundries, while sensor emulation modules source from German and Japanese precision electronics manufacturers. Single-source vulnerability in specialized compute hardware creates procurement bottlenecks when foundry capacity tightens. Distribution runs through OEM-direct contracts with multi-year deployment cycles, bypassing traditional Tier-1 supplier channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is becoming a vertical-integration race as platform vendors pursue captive supply of real-time processor architectures to escape semiconductor foundry dependency and defend margin pools.
For Market Incumbents: Lock in exclusive supply agreements with Taiwan and South Korean semiconductor foundries before capacity constraints tighten further. Defend position by acquiring scenario database specialists to maintain traceability advantages as NHTSA crash reporting protocols harden audit requirements. Internalize sensor emulation firmware development to reduce dependency on software-defined radio component vendors. For New Entrants and Emerging Players: Launch via cloud-native simulation workflows targeting mid-size automotive suppliers previously excluded from high-capital testing. White-space opportunities concentrate in artificial intelligence verification services for neural network highway pilot decisions, and in V2X communication emulation for Japan's MLIT-connected vehicle approval frameworks. Partner with system integrators to bypass OEM-direct procurement barriers. For Investors and Strategic Acquirers: Re-rating potential sits with pure-play coverage-driven verification specialists given NHTSA standing general order enforcement as a catalyst for traceable test database demand. Long-term viability favors vendors with ISO 26262 functional safety engineering depth and established relationships with German automotive clusters. Watch for regulatory convergence signals between UN ECE, NHTSA, and Japan MLIT frameworks as an inflection indicator for platform standardization plays.| Strategic Initiative | Industry Significance |
|---|---|
| Real-Time Processor Supply Agreement | Captive semiconductor access from Taiwan foundries secures hardware-in-the-loop production capacity against foundry bottlenecks. |
| Scenario Database Acquisition | Ownership of traceable test coverage libraries satisfies NHTSA crash reporting documentation requirements for automated lane change verification. |
| Vehicle-in-the-Loop Facility Expansion | Climate-controlled proving ground infrastructure in Stuttgart and Munich clusters anchors OEM validation center relationships. |
| Cloud-Native Simulation Platform Launch | Scalable workflow access opens mid-size supplier segment previously excluded from high-capital hardware testing. |
| Sensor Emulation Firmware Internalization | In-house software-defined radio development reduces dependency on external radar and lidar signal generation component vendors. |
Research Methodology
Multi-period observation of UN ECE R79 implementation timelines, NHTSA crash reporting enforcement patterns, and German automotive cluster procurement cycles anchored the trend analysis, supplemented by interviews with OEM platform engineers, Tier-1 supplier procurement leads, validation center operations directors, and semiconductor foundry account managers. Secondary validation drew from UN ECE working group documentation, NHTSA standing general order filings, KBA type-approval databases, MLIT policy circulars, and automotive industry production forecasts. Bottom-up segmentation modeling triangulated against top-down market sizing from hardware-in-the-loop and vehicle-in-the-loop installation tracking.
Input-output matrices mapped real-time processor supply constraints, scenario database ownership patterns, and regulatory documentation requirements to project adoption curves across the analysis window. Segmentation dimensions included product architecture, emulation technology tier, application depth, and end-user procurement authority. CAGRs derived from regression analysis of historical validation center capital expenditure patterns and forward-looking OEM platform deployment schedules. Forecast inputs incorporated sensor fusion complexity trajectories and adversarial weather condition testing mandates.
Regulatory timeline slippage, semiconductor foundry capacity allocation shifts, and OEM internalization of validation ownership are the dominant revision risks to modeled outcomes. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Testing and Simulation
Dynamometer Market
Automotive Testing and Simulation
Vehicle Emission Testers Market
Automotive Testing and Simulation
Global Automotive Wind Tunnel Market
Automotive Testing and Simulation
Automotive Durability Testing Market
Automotive Testing and Simulation
Vehicle Simulation Software Market
Automotive Testing and Simulation
Global Automotive Wind Tunnel Testing Equipment Market
Automotive Testing and Simulation
Automotive Chassis Dynamometer Market
Automotive Testing and Simulation
Automotive Test Equipment Market
Automotive Testing and Simulation
Automotive Exhaust Analyzer Market
Automotive Testing and Simulation
Automotive Spot Weld Inspection System Market
Automotive Testing and Simulation
Electric Vehicle Test Bench Market
Automotive Testing and Simulation
Automotive Battery Testing Market
Automotive Testing and Simulation
Automotive Hardware-In-The-Loop Simulation Market
Automotive Testing and Simulation
Automotive Emission Test Equipment Market
Automotive Testing and Simulation
Automotive Weigh in Motion Market
Automotive Testing and Simulation
Vehicle Radar Test System Market