
 Rivet Busters Market | 2026-2036
Rivet Busters Market Size, Share, and Industry Trends Forecast 2026-2036
Rivet Busters Market Analytics
Buyer concentration among tier-one shipbuilders and aerospace contractors is decoupling from traditional distributor networks as direct procurement channels expand. Atlas Copco leverages its captive compressor ecosystem to bundle rivet busters with air-system contracts, locking in fleet replacements. Ingersoll Rand sustains aftermarket revenue through certified rebuild centers that extend tool life cycles for cost-sensitive demolition crews. Chicago Pneumatic differentiates via compact chassis designs that navigate confined-space regulations in European rail maintenance depots.
A rivet buster is a percussive pneumatic or hydraulic tool engineered to shear hardened rivet heads through repeated impact energy, typically operating at 90–120 psi air pressure with stroke frequencies exceeding 2,000 blows per minute to dismantle structural steel assemblies. Pneumatic units dominate demolition and heavy shipbreaking yards where compressed air infrastructure already exists, while electric variants lead in automotive final-assembly plants seeking OSHA noise-exposure compliance. Hydraulic systems anchor high-torque applications in bridge decommissioning where concrete-embedded rivets demand sustained breaking force beyond pneumatic capacity.
FAA airworthiness directives and OSHA permissible exposure limits for hand-arm vibration jointly shape product certification requirements, forcing manufacturers to redesign damping systems or risk exclusion from federal contracting pools. EPA stationary source rules in shipyard zones add emissions-layer compliance for compressor-fed pneumatic fleets, pushing some operators toward battery-electric alternatives. Stakeholders must weigh tooling platform standardization against emerging battery-electric performance thresholds before committing capital to fleet replacements.
Market Dynamics
Shipyard operators in South Korea face tightening MEE emissions rules that force compressor fleet upgrades, redirecting capital toward battery-electric rivet busters and reshaping procurement priorities across maritime maintenance.
Growth Catalysts
- MEE Port Emissions Mandates:South Korean regulators enforce stricter equipment standards at Busan and Ulsan shipyards, accelerating pneumatic-to-electric conversions in heavy maintenance programs.
- OSHA Noise Compliance:European automotive assembly plants adopt electric variants to meet permissible exposure limits, expanding addressable demand beyond traditional demolition verticals.
- Bridge Decommissioning Surge:Aging steel infrastructure across Germany and Japan requires hydraulic systems for concrete-embedded rivet extraction, sustaining high-torque equipment orders.
Market Restraints
- Aluminum Alloy Input Volatility:Fluctuating primary metal prices compress margins for pneumatic chassis manufacturers dependent on die-cast housings.
- Compressor Infrastructure Lock-In:Shipyards with sunk capital in air-system networks face switching costs that delay electric adoption despite regulatory pressure.
- Hand-Arm Vibration Certification:FAA airworthiness directives and OSHA limits force expensive damping redesigns, excluding uncertified suppliers from federal contracting pools.
Strategic Opportunities
- Indian Port Modernization:Sagarmala infrastructure investments create first-mover advantage for electric tool vendors targeting Visakhapatnam and Chennai ship repair clusters.
- Battery-Electric Convergence:Lithium-ion cell density improvements enable cordless rivet busters to match pneumatic stroke frequencies, opening confined-space rail maintenance applications.
- EU Green Deal Procurement Incentives:Carbon-adjusted tender scoring favors low-emission equipment in publicly funded decommissioning contracts across France and Italy.
Industry Challenges
- Percussive Tool Technician Shortage:Specialized rebuild and calibration expertise concentrates at certified centers, creating service bottlenecks for remote demolition crews.
- Multi-Platform Fleet Integration:Contractors operating mixed pneumatic-electric-hydraulic inventories face incompatible maintenance protocols and spare parts complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rivet Busters Market |
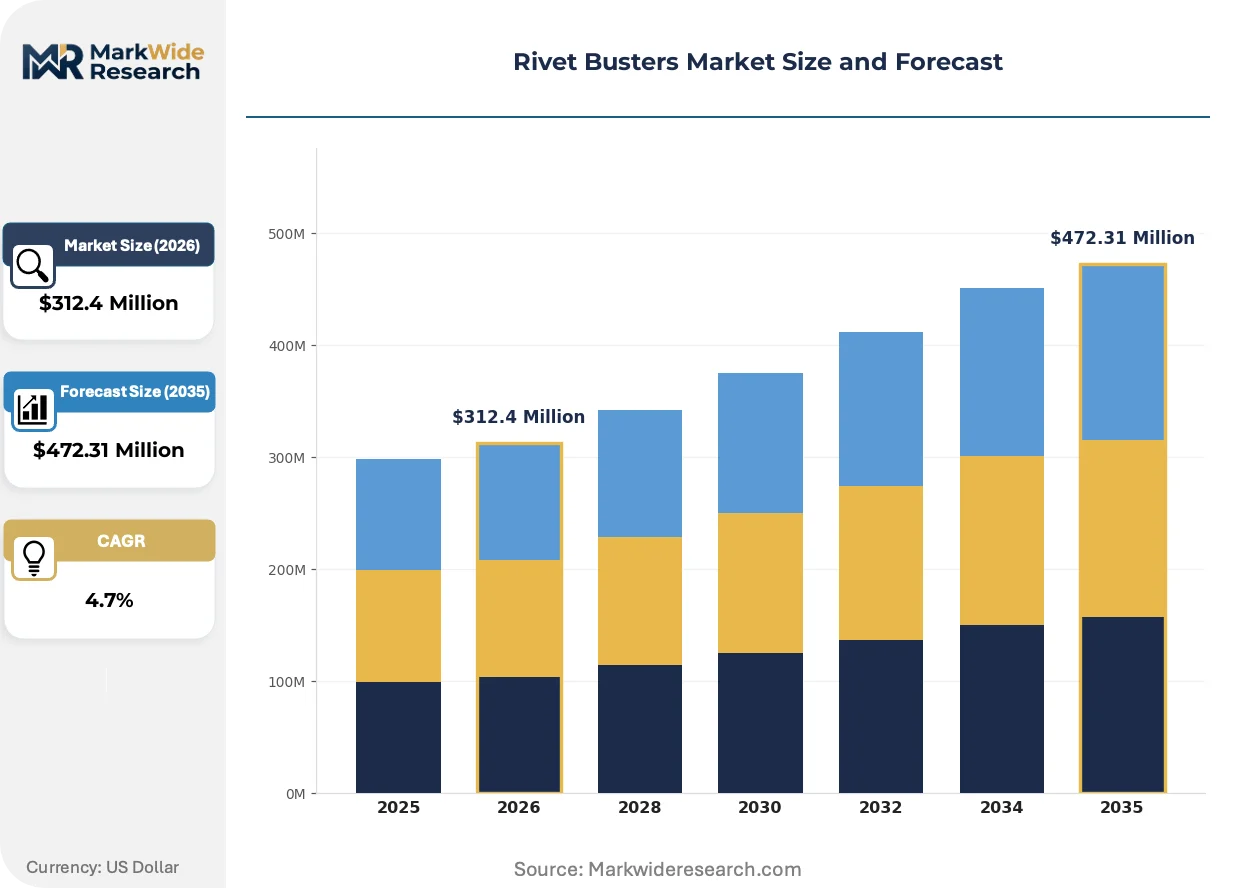
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $472.31 Million |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pneumatic, Electric, Hydraulic, Manual End User: Construction, Demolition, Manufacturing, Automotive Technology: Impact, Vibration, Torque, Noise Reduction Distribution Channel: Retail, Online, Direct Sales, Wholesale |
| Companies Covered | Atlas Copco, Ingersoll Rand, Chicago Pneumatic, Stanley Black & Decker, Bosch Rexroth, Makita Corporation, DeWalt, American Pneumatic Tools, Ohio Power Tool, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rivet Busters Market Evolving Landscape
Tool electrification is compressing the performance gap with pneumatic systems while regulatory emissions frameworks force infrastructure decisions at maritime facilities.
Brushless DC motor architectures with regenerative braking are electrifying rivet buster design, delivering sustained impact energy previously exclusive to compressor-fed units. German rail maintenance depots in Munich and Hamburg pilot these systems for tunnel work where exhaust and noise restrictions apply. The technology is electrifying competitive positioning by enabling new entrants to bypass captive compressor ecosystems that previously locked in incumbent suppliers.
REACH substance restrictions on hexavalent chromium plating force manufacturers to migrate toward ceramic coating alternatives for piston cylinders. The industrial consequence extends tool rebuild intervals and shifts warranty liability toward coating vendors. European demolition contractors face the steepest compliance timeline, with certification deadlines compressing procurement cycles for fleet replacements.
Direct procurement channels are displacing traditional distributor networks as tier-one shipbuilders and aerospace contractors consolidate supplier relationships. Atlas Copco and Ingersoll Rand now compete for air-system bundling contracts that lock in multi-year fleet commitments. This consolidation is most visible in South Korean shipyards, where Hyundai Heavy Industries and Samsung Heavy Industries centralize tooling procurement under integrated maintenance agreements.
Rivet Busters Market Segmentation
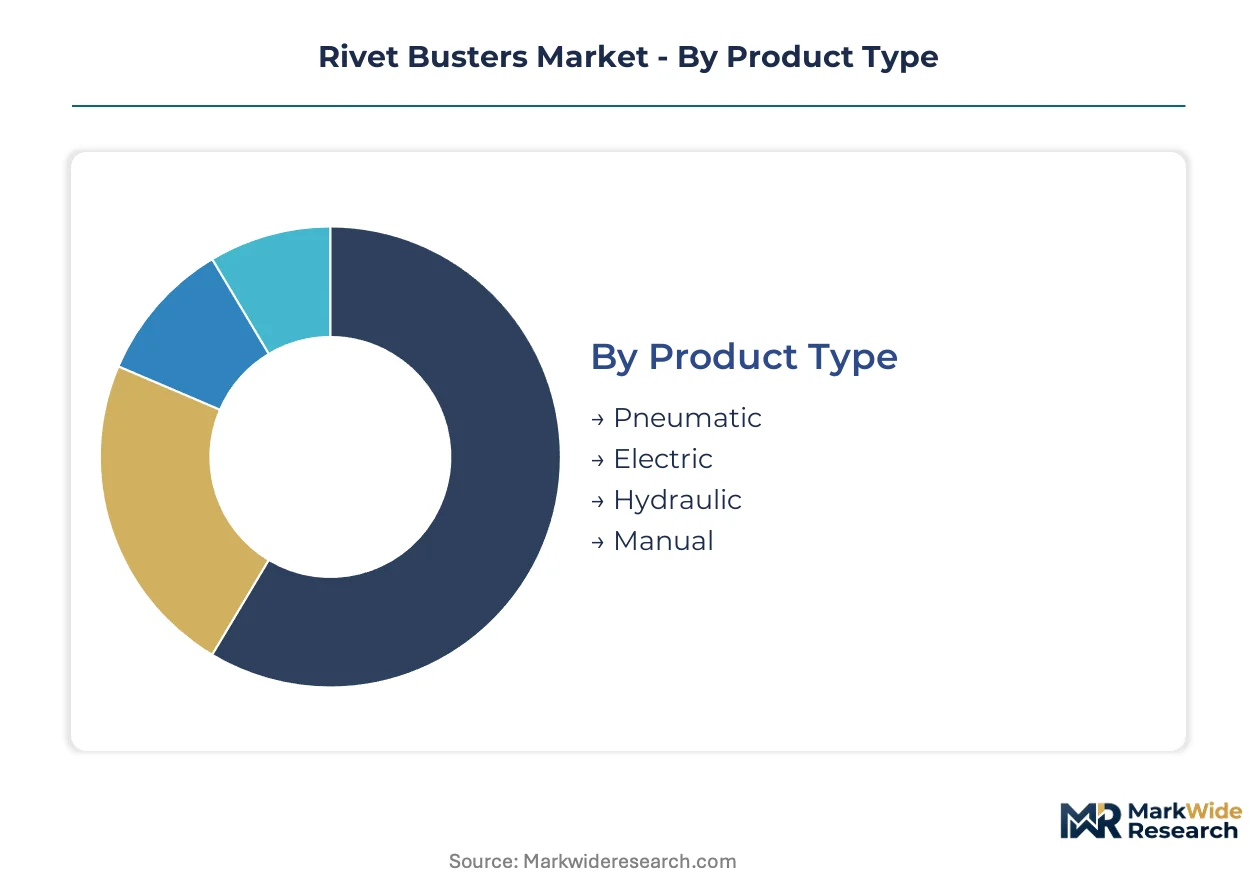
Tool selection in rivet busters hinges on infrastructure compatibility, regulatory exposure, and torque requirements. Procurement patterns diverge sharply between maritime operators locked into pneumatic systems and automotive plants prioritizing OSHA compliance.
Product Type:
Capital sunk into compressed air infrastructure versus battery-electric performance thresholds drives platform commitment.
- Pneumatic:Compressor-fed units deliver 90–120 psi operating pressure with stroke frequencies exceeding 2,000 blows per minute. Shipbreaking yards in South Korea and demolition contractors in Germany favor these systems where air infrastructure already exists, though MEE emissions rules now force fleet upgrade decisions.
- Electric:Brushless DC motor architectures with regenerative braking now match pneumatic stroke energy. European automotive assembly plants in Stuttgart and Wolfsburg adopt these variants to meet OSHA noise-exposure limits, expanding demand beyond traditional demolition verticals.
- Hydraulic:High-torque systems anchor bridge decommissioning across Japan and Germany where concrete-embedded rivets demand sustained breaking force.
- Manual:Hand-powered units serve confined-space rail maintenance in European tunnels where exhaust restrictions apply and power sources are unavailable.
Pneumatic leads on scale; electric leads on momentum.
End User:
Regulatory intensity and project scale separate volume buyers from premium-price adopters.
- Construction:Heavy civil contractors deploy hydraulic systems for structural steel dismantling. Infrastructure aging across Germany and Japan sustains equipment orders for bridge replacement programs.
- Demolition:Specialized crews operate mixed pneumatic-electric-hydraulic inventories. Certified rebuild centers concentrate expertise, creating service bottlenecks for remote operators.
- Manufacturing:Final-assembly plants prioritize noise compliance. European facilities lead conversion to electric variants under EU Green Deal procurement incentives.
- Automotive:OEM assembly lines demand OSHA-compliant tooling. Stuttgart and Wolfsburg plants drive specification standards for vibration-damped electric units.
Construction anchors volume; automotive commands price premiums.
Technology:
Certification requirements from FAA airworthiness directives and OSHA hand-arm vibration limits reshape R&D allocation.
- Impact:Repeated percussive energy delivery remains the core mechanism. Pneumatic and electric platforms compete on stroke frequency maintenance under sustained load.
- Vibration:Damping system redesigns absorb hand-arm transmission. Uncertified suppliers face exclusion from federal contracting pools.
- Torque:Sustained rotational force distinguishes hydraulic architectures. Bridge decommissioning in Japan relies on these systems for embedded rivet extraction.
- Noise Reduction:Electric motor enclosures and damping materials suppress decibel output. European rail maintenance depots in Munich pilot these systems for tunnel work.
Impact dominates installed base; noise reduction climbs fastest.
Distribution Channel:
Buyer concentration among tier-one shipbuilders is decoupling procurement from traditional networks.
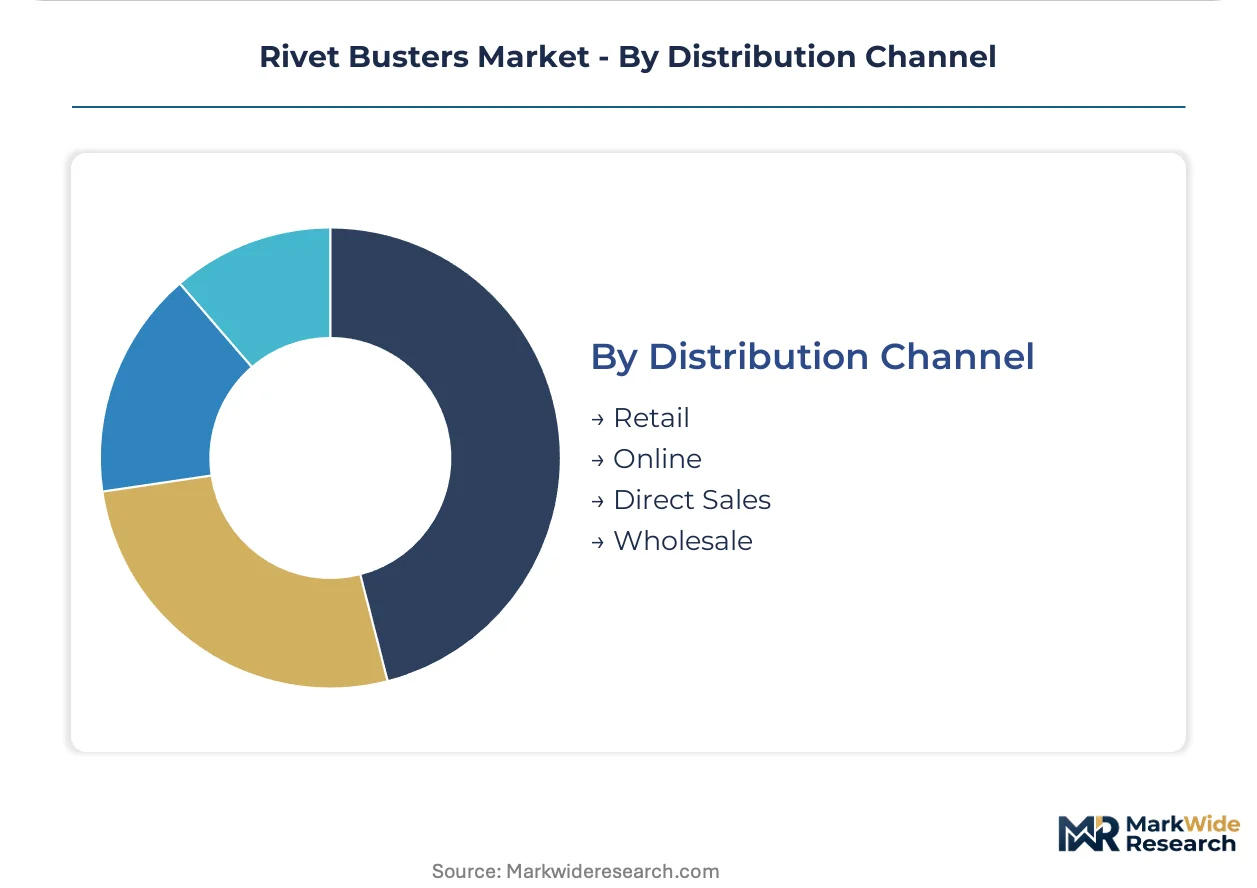
- Retail:Counter sales serve small contractors and emergency replacement demand. Margin compression limits manufacturer engagement.
- Online:Digital procurement expands for standardized electric units. European automotive plants leverage e-commerce for consumables and spare parts.
- Direct Sales:Atlas Copco and Ingersoll Rand compete for air-system bundling contracts. South Korean shipyards centralize tooling procurement under integrated maintenance agreements.
- Wholesale:Distributor networks retain demolition contractor relationships. Service capability and rebuild expertise differentiate regional players.
Direct sales capture strategic accounts; online expands fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Korean shipyards outpace German automotive plants in pneumatic-to-electric conversion urgency, while Japanese bridge contractors sustain hydraulic equipment demand through infrastructure aging programs.
United States
Bridge decommissioning crews across the Rust Belt drive hydraulic system procurement for concrete-embedded rivet extraction. OSHA hand-arm vibration limits force damping system redesigns for federal contracting eligibility. Pittsburgh and Cleveland anchor heavy civil contractor clusters where mixed pneumatic-electric-hydraulic inventories create service integration challenges.
Germany
Rail maintenance depots in Munich and Hamburg pilot brushless DC electric units for tunnel work under exhaust restrictions. REACH substance rules on hexavalent chromium plating compress procurement cycles for fleet replacements. Stuttgart automotive assembly plants command premium pricing for OSHA-compliant vibration-damped electric variants.
South Korea
Hyundai Heavy Industries and Samsung Heavy Industries centralize tooling procurement under integrated maintenance agreements. MEE emissions mandates at Busan and Ulsan ports force compressor fleet upgrades that redirect capital toward battery-electric alternatives. Daegu-Gyeongbuk manufacturing clusters face the steepest compliance timeline for port equipment standards.
Japan
Aging steel infrastructure across Honshu sustains hydraulic equipment orders for bridge replacement programs. METI industrial standards shape certification requirements for percussive tool imports. Osaka-Kansai demolition contractors concentrate certified rebuild expertise, creating service bottlenecks for remote operators.
India
Sagarmala port modernization investments create first-mover opportunities for electric tool vendors targeting Visakhapatnam and Chennai ship repair clusters. BIS equipment standards lag REACH and OSHA frameworks, allowing import flexibility. Gujarat and Maharashtra industrial corridors concentrate manufacturing demand for noise-compliant assembly tooling.
Rivet Busters Market Competitive Landscape
European producers anchor the premium-tier ecosystem; East Asian fabricators hold cost-optimized positions. Market structure consolidates around air-system bundling capabilities and certified rebuild networks. Three archetypes dominate: captive compressor ecosystem bundlers, aftermarket service specialists, and compact-design innovators. Strategic moves concentrate on direct procurement channel expansion and battery-electric portfolio diversification.
Among diversified industrial conglomerates, Atlas Copco, Ingersoll Rand, and Chicago Pneumatic occupy positions that exemplify distinct competitive vectors. Atlas Copco represents the captive ecosystem archetype through air-system contract bundling. Ingersoll Rand anchors aftermarket revenue models via certified rebuild center networks. Chicago Pneumatic exemplifies design-led differentiation for confined-space regulatory compliance.
| Leading Market Players |
|---|
| Atlas Copco |
| Ingersoll Rand |
| Chicago Pneumatic |
| Stanley Black & Decker |
| Bosch Rexroth |
| Makita Corporation |
| DeWalt |
| American Pneumatic Tools |
| Ohio Power Tool |
| Others |
Value Network & Pricing Analysis
Tier-one shipbuilders and aerospace contractors in South Korea and Germany command project-based contract pricing that bundles multi-year fleet commitments with air-system infrastructure, compressing margins for standalone tool vendors while locking in volume discounts for integrated procurement.
Pricing Analysis
Capacity additions in China and Vietnam are reshaping price floors for die-cast aluminum chassis components, intensifying cost compression in economy-tier pneumatic units. Three-tier pricing structure across premium vibration-damped, standard OSHA-compliant, and economy non-certified levels separates certified rebuild programs from disposable import alternatives. Pricing pressure stems from REACH substance compliance costs that manufacturers cannot fully pass to MEE-regulated South Korean ports. Demolition contractors in remote markets exhibit highest price sensitivity, while Stuttgart automotive plants absorb premiums for noise-compliant electric variants.
Supply Chain Analysis
Certified rebuild centers in Japan and Germany anchor reverse-logistics flows that extend tool life cycles through remanufactured piston assemblies and ceramic-coated cylinder replacements. Manufacturing concentration in China, Taiwan, and South Korea supplies brushless DC motors and lithium-ion cells that feed electric variant production. Die-cast aluminum housings, hexavalent chromium alternatives, and precision impact mechanisms constitute critical input dependencies. Single-source vulnerability concentrates in ceramic coating vendors serving REACH-compliant European orders. Distribution runs through direct sales channels for tier-one shipbuilders and wholesale networks for demolition contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The rivet busters market compounds regulatory value as MEE port emissions mandates and OSHA noise limits simultaneously force fleet replacement cycles across maritime and automotive verticals.
For Market Incumbents: Deepen captive compressor ecosystem bundling to defend against battery-electric entrants bypassing air-system infrastructure. Atlas Copco and Ingersoll Rand should expand certified rebuild center networks in India and Southeast Asia before Sagarmala port modernization peaks. Invest in vibration-damping R&D to maintain FAA airworthiness certification eligibility for federal contracting pools. For New Entrants and Emerging Players: The mid-tier price gap between premium German electric units and Chinese pneumatic imports offers white-space entry for brushless DC architectures with regenerative braking. Target Visakhapatnam and Chennai ship repair clusters where BIS standards lag REACH compliance, allowing import flexibility. Pursue EU Green Deal carbon-adjusted tender scoring as a go-to-market wedge for publicly funded decommissioning contracts in France and Italy. For Investors and Strategic Acquirers: Industrial conglomerates with captive compressor divisions are the most active acquirer in this space, seeking tool-line bolt-ons to complete air-system bundling capabilities. Long-term viability hinges on battery-electric portfolio conversion speed relative to MEE regulatory deadlines. Monitor lithium-ion cell density improvement trajectories as the inflection signal for cordless rivet buster performance parity with pneumatic systems.| Strategic Initiative | Industry Significance |
|---|---|
| Air-System Bundling Expansion | Atlas Copco locks in multi-year fleet replacements through captive compressor contracts at Busan shipyards. |
| Certified Rebuild Network Scale-Up | Ingersoll Rand extends aftermarket revenue by concentrating technician expertise in Osaka-Kansai clusters. |
| Brushless DC Platform Launch | New entrants bypass pneumatic infrastructure lock-in via regenerative braking architectures for tunnel rail maintenance. |
| Ceramic Coating Supply Agreement | European manufacturers secure REACH-compliant piston cylinder alternatives before hexavalent chromium deadlines. |
| Direct Procurement Channel Migration | Hyundai Heavy Industries consolidates supplier relationships under integrated maintenance agreements. |
Research Methodology
Multiple input streams — maintenance director interviews at German rail depots, procurement lead discussions at South Korean shipyards, and aftermarket service head conversations in Japan — were reconciled against customs trade data, SEC filings from diversified industrial conglomerates, and MEE regulatory documentation. Secondary validation drew from OSHA permissible exposure limit databases, FAA airworthiness directive records, and EU Green Deal tender scoring frameworks. Bottom-up tooling unit estimates and top-down infrastructure investment projections were triangulated for convergence.
Historical shipment data from compressor-fed and battery-electric fleet installations were cross-referenced against expert panel inputs from plant engineers and OEM procurement teams across the analysis window. Segmentation modeling incorporated product type, end-use vertical, technology certification tier, and distribution channel dynamics. CAGRs were derived from regression analysis of infrastructure replacement cycles and regulatory compliance deadlines. Industry-specific forecast inputs included MEE emissions mandate implementation timelines and lithium-ion cell density improvement curves.
Caveats apply where MEE enforcement intensity or lithium-ion cost curves could materially shift the outlook. Forecasts reflect assumptions about regulatory adherence rates and technology substitution elasticities that may revise with hand-arm vibration certification changes or aluminum alloy price volatility. Practitioners should monitor South Korean port equipment standard updates and brushless DC motor patent filings for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Fine Blanking Tools Market
Tools
Surface Planer Market
Tools
Portable Boring Machines Market
Tools
Boring Tools Market
Tools
Portable Rolling Toolbox Market
Tools
Rocket Wrench Market
Tools
Pruning Saw Market
Tools
China Power Tools Market
Tools
Foam Cutting Machine Market
Tools
Water Pump Pliers Market
Tools
Industrial Ladder Market
Tools
Global Scarifiers Market
Tools
Cutting Pipe and Perforating Pipe Drilling Tools Market
Tools
Masonry Cleaners Market
Tools
Collated Screws Market
Tools
Machine Vise Market