
 Global Diamond Tools Market | 2026-2036
Global Diamond Tools Market Size, Share, and Industry Trends Forecast 2026-2036
Global Diamond Tools Market Analysis
Tool-as-a-service subscription models for diamond consumables is pivoting how manufacturers monetize wear parts. Hilti Corporation leverages fleet management contracts to lock in contractor loyalty across European job sites. Saint-Gobain anchors its position through captive synthetic diamond production, insulating margin pools from raw material volatility. Husqvarna AB competes on remote diagnostics integration, embedding sensors into core drill rigs to predict bit replacement cycles.
Diamond tools are abrasive or cutting implements that embed synthetic or natural diamond grit within metal, resin, or electroplated bonding matrices, typically operating at surface speeds exceeding 25 meters per second to machine hardened ceramics, stone, concrete, and superalloys. Their primary commercial purpose centers on precision material removal where conventional abrasives fail due to thermal degradation or insufficient hardness. Cutting tools command the largest revenue pool given infrastructure demolition and stone quarrying volumes, while laser-based fabrication represents the fastest-growing technology segment as manufacturers seek tighter dimensional tolerances for aerospace turbine components. Metal bonded tools retain dominance in wet grinding applications where mechanical retention of diamond crystals withstands high normal forces.
The EPA enforces silica exposure limits under OSHA's Respirable Crystalline Silica Standard, compelling construction end users to specify vacuum-shrouded diamond cutting systems that suppress respirable dust at the point of generation. China's SAMR enforces GB standards for abrasive product safety certification, creating compliance barriers for imported electroplated tools lacking in-country testing documentation. ISO 9001 and ISO 14001 certifications function as de facto market access requirements for OEM supply contracts across automotive and aerospace tiers. Stakeholders must monitor bonding chemistry patent filings and synthetic diamond feedstock cost curves to anticipate which technology platforms will capture premium pricing in precision manufacturing segments.
Market Dynamics
Laser-based diamond fabrication is compressing tolerance thresholds for aerospace turbine blades while OSHA's silica enforcement reconfigures jobsite equipment specifications across developed construction markets.
Growth Catalysts
- EU F-Gas Regulation:Climate-controlled manufacturing mandates are accelerating capital expenditure on precision diamond grinding systems for heat-sensitive superalloy machining in German and French aerospace clusters.
- Guangdong Province concentration:Electronics and automotive OEM procurement in China's Pearl River Delta is pulling high-volume orders for resin-bonded precision tools serving semiconductor substrate processing.
- Wet grinding technology:Metal-bonded tool demand from stone quarrying operations in Italy and Brazil is expanding as mechanical diamond retention withstands elevated normal forces in continuous water-cooled environments.
Market Restraints
- Synthetic diamond feedstock volatility:Chemical vapor deposition substrate costs fluctuate with energy pricing and high-purity methane supply constraints from industrial gas distributors.
- Henan Province supply concentration:Overreliance on Chinese synthetic diamond production creates exposure to provincial environmental inspections and power rationing protocols.
- GB standards certification friction:China's SAMR testing documentation requirements delay market entry for electroplated tool imports lacking in-country laboratory validation.
Strategic Opportunities
- Tool-as-a-service models:Fleet management subscriptions for diamond consumables are penetrating European construction contractor procurement, locking replacement cycles through predictive wear monitoring.
- Remote diagnostics integration:Sensor-embedded core drill rigs enable predictive bit replacement scheduling, creating aftermarket revenue streams in Nordic infrastructure maintenance markets.
- Dual carbon alignment:China's MEE emissions targets are incentivizing domestic manufacturers to upgrade laser fabrication capacity, opening equipment supply contracts for foreign precision system vendors.
Industry Challenges
- Bonding chemistry patent thickets:Ceramic-metal matrix intellectual property disputes between established Japanese and European toolmakers complicate new entrant R&D pathways.
- ISO 14001 certification timelines:Automotive and aerospace OEM supply contracts require 12-18 month environmental management system validation, compressing qualification windows for tier-2 tool suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Diamond Tools Market |
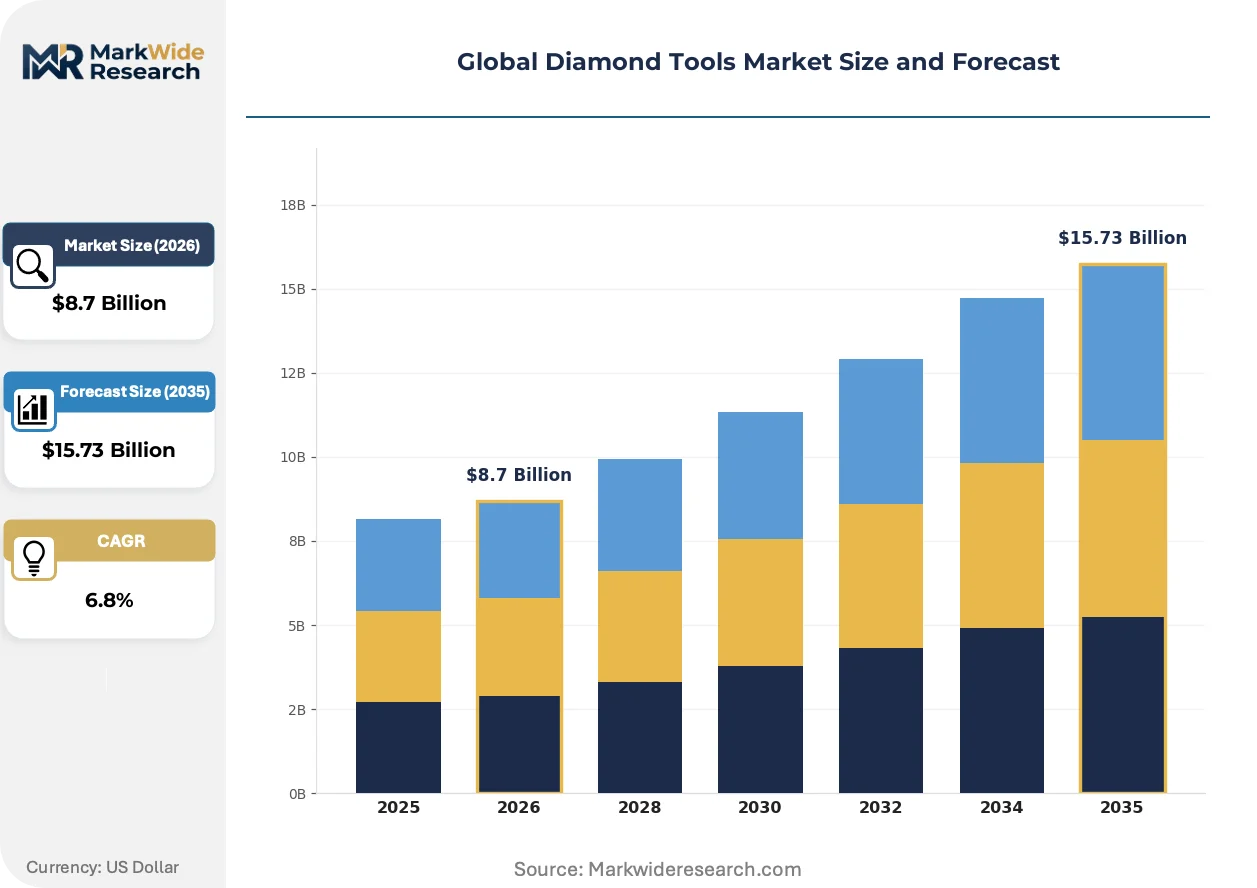
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cutting Tools, Grinding Tools, Drilling Tools, Polishing Tools Application: Construction, Automotive Manufacturing, Aerospace Engineering, Electrical Industry End User: Contractors, OEMs, Maintenance Providers, Retailers Technology: Laser-Based, Electroplated, Resin Bonded, Metal Bonded |
| Companies Covered | Hilti Corporation, Husqvarna AB, Saint-Gobain, Makita, Asahi Diamond Industrial, Sumitomo Electric Industries Ltd., Tyrolit, Bosch, Shinhan Diamond, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Diamond Tools Market Emerging Trajectories
Three intersecting developments are restructuring competitive advantage: manufacturing process substitution, regulatory compliance technology, and procurement model transformation.
Ultrashort-pulse laser ablation for diamond tool fabrication is overtaking conventional mechanical grinding for aerospace turbine blade root profiles. Rolls-Royce and Safran procurement specifications now mandate laser-processed cutting edges for nickel superalloy components. This precision threshold is compressing acceptable tolerance bands from micrometer to sub-micrometer scales, disqualifying mechanical tool vendors from premium tier contracts.
OSHA's Respirable Crystalline Silica Standard enforcement is mandating vacuum-shrouded diamond cutting systems on US construction sites. Contractors in California and New York metropolitan areas face inspection penalties for non-compliant equipment. Dust suppression at point-of-generation has become a disqualifying specification in public infrastructure bids, forcing rental fleet upgrades.
Subscription-based consumable procurement is displacing spot purchasing among European demolition contractors. Hilti fleet management contracts bundle bit replacement, logistics, and usage analytics. German and Dutch infrastructure specialists now specify total-cost-per-cut metrics rather than unit tool pricing, compressing vendor margins while extending contract durations.
Global Diamond Tools Market Segmentation
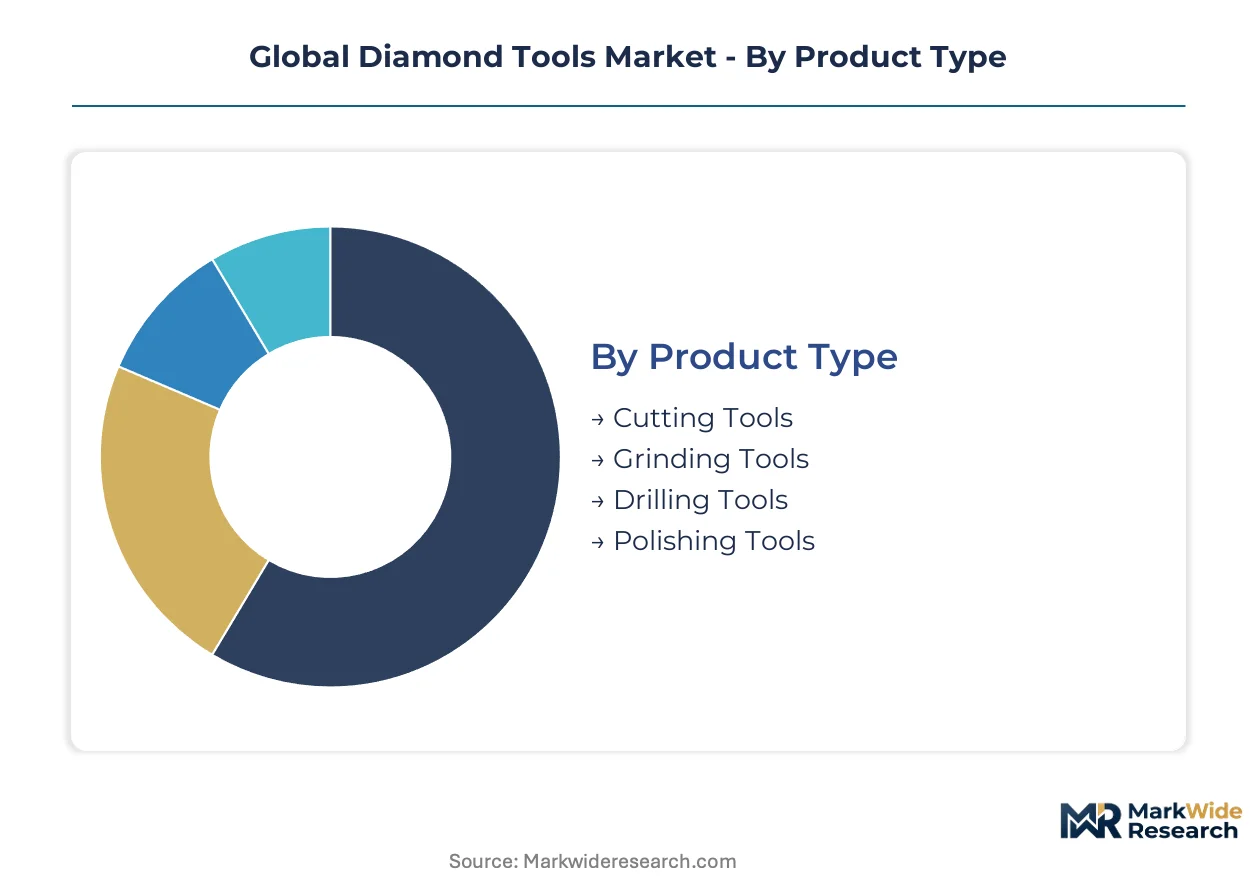
Segmentation in diamond tools reveals how procurement specifications diverge across end-use environments. Replacement cycle timing, bonding chemistry durability, and regulatory compliance requirements reshape vendor priorities differently across each dimension.
Product Type:
Upgrade urgency varies sharply by tool function, with infrastructure demolition cycles and precision manufacturing tolerances dictating replacement frequency.
- Cutting Tools:Metal-bonded diamond segments embedded in circular saw blades and wire saws machine reinforced concrete, granite, and engineered stone. Infrastructure demolition contractors in Germany specify laser-welded segments for autobahn bridge deck removal, where vacuum-shrouded systems satisfy OSHA silica enforcement.
- Grinding Tools:Resin-bonded cup wheels and metal-bonded profile wheels remove material from hardened ceramics and superalloys. Wet grinding applications in Italy's Carrara quarries and Brazil's Minas Gerais stone processing clusters consume metal-bonded variants for continuous water-cooled operations.
- Drilling Tools:Core drill bits with diamond-impregnated segments penetrate reinforced concrete and masonry for utility installation and structural assessment.
- Polishing Tools:Resin-bonded polishing pads achieve surface finishes on granite, marble, and concrete countertops for residential and commercial construction.
Volume placements concentrate in cutting tools; the faster expansion belongs to grinding tools.
Application:
Cost tier stratification separates commodity construction procurement from aerospace and automotive premium specifications.
- Construction:Demolition, renovation, and infrastructure projects consume diamond blades, core drills, and grinding discs in high volumes. German contractors now specify laser-based cutting equipment under tightened EU F-Gas climate-control mandates for indoor fabrication facilities.
- Automotive Manufacturing:Precision grinding of powertrain components and EV battery housing machining requires tight dimensional tolerances. Guangdong province automotive OEMs pull resin-bonded tool orders for aluminum alloy processing.
- Aerospace Engineering:Turbine blade root profiling and superalloy component finishing demand sub-micrometer precision. Rolls-Royce and Safran procurement specifications now mandate laser-processed cutting edges.
- Electrical Industry:Semiconductor substrate dicing and ceramic insulator machining utilize electroplated and resin-bonded precision tools.
Construction commands absolute volume; aerospace claims the steepest expansion trajectory.
End User:
Customer type determines contract structure, with fleet management subscriptions penetrating contractor segments while OEMs enforce certification barriers.
- Contractors:Infrastructure demolition and renovation specialists specify total-cost-per-cut metrics through tool-as-a-service subscriptions. Hilti fleet management contracts now dominate German and Dutch procurement.
- OEMs:Automotive and aerospace manufacturers require ISO 9001 and ISO 14001 certifications as de facto supply contract prerequisites, imposing 12-18 month qualification timelines.
- Maintenance Providers:Nordic infrastructure maintenance markets adopt sensor-embedded core drill rigs for predictive bit replacement scheduling.
- Retailers:Distributors serving residential renovation and small commercial contractors stock standardized cutting and grinding consumables.
Contractor channels absorb the highest shipment volumes; OEM qualification represents the most defensible margin tier.
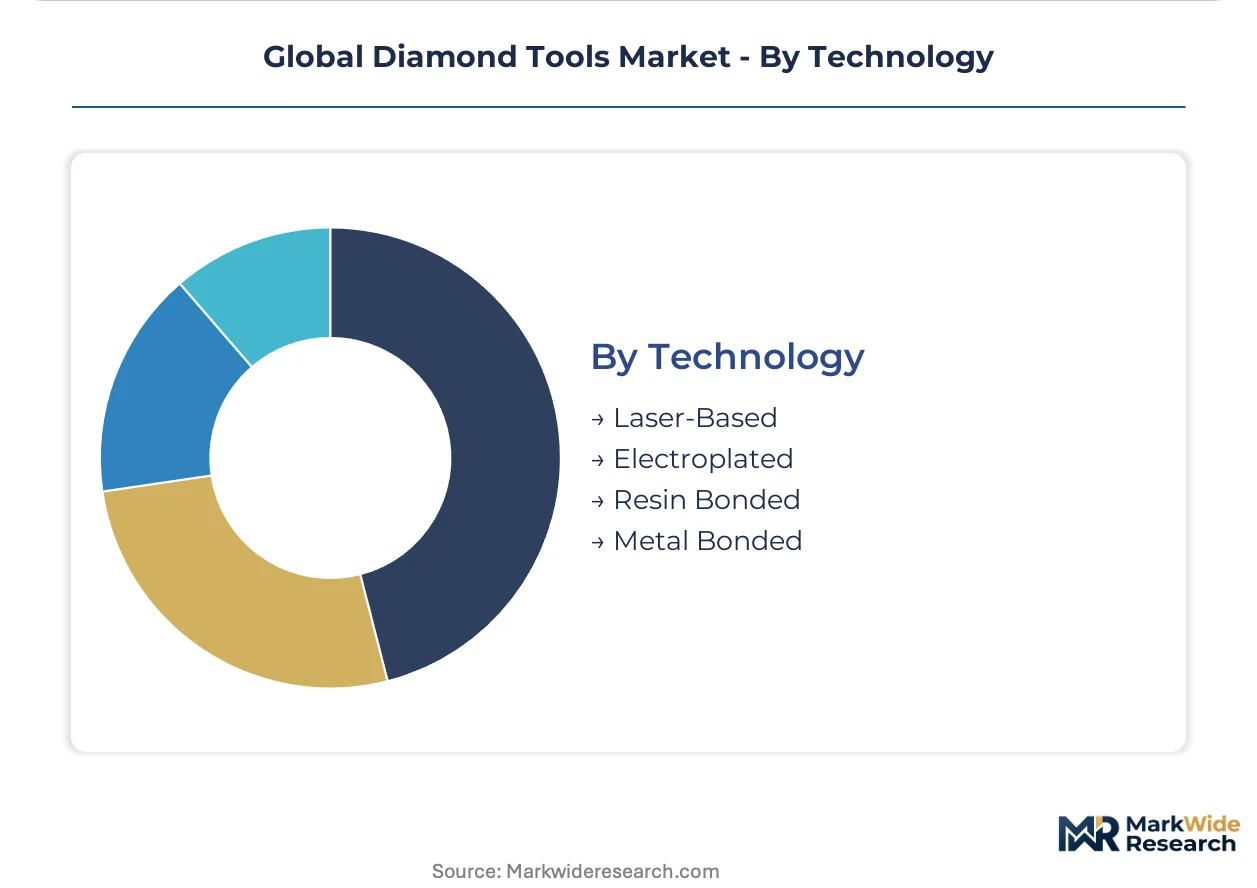
Technology:
Supply concentration in bonding chemistry patents and synthetic diamond feedstock shapes competitive entry barriers.
- Laser-Based:Ultrashort-pulse laser ablation fabricates cutting edges with sub-micrometer precision for aerospace turbine components. China's MEE emissions targets incentivize domestic manufacturers to upgrade laser fabrication capacity.
- Metal Bonded:Sintered metal matrices mechanically retain diamond crystals under high normal forces in wet grinding environments. Italian and Brazilian stone quarrying operations specify these for continuous water-cooled processing.
- Resin Bonded:Polymer matrices enable precision finishing with controlled material removal rates for semiconductor substrate processing.
- Electroplated:Single-layer nickel bonding provides aggressive cutting action for soft stone and composite materials, though China's SAMR testing documentation requirements delay import market entry.
Metal bonded retains the largest installed base; laser-based fabrication is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Synthetic diamond feedstock production concentrates in China's Henan province, while precision tool consumption clusters in German aerospace corridors and Guangdong manufacturing belts. This geographic split between upstream material supply and downstream value-added fabrication shapes trade flows and inventory strategies.
China
Henan province hosts the world's densest concentration of synthetic diamond manufacturing, with Zhengzhou-based producers supplying feedstock for both domestic tool fabricators and export markets. SAMR enforces GB standards certification for abrasive product safety, creating documentation barriers for electroplated tool imports lacking in-country laboratory validation. Guangdong province's Pearl River Delta precision machining clusters pull high-volume resin-bonded tool orders for semiconductor substrate processing serving electronics and automotive OEMs.
Germany
Construction contractors across Bavaria and North Rhine-Westphalia are expanding procurement of laser-based diamond cutting equipment for autobahn infrastructure demolition and indoor fabrication facilities. The EU F-Gas Regulation tightens refrigerant rules for climate-controlled manufacturing, accelerating capital expenditure on precision grinding systems for heat-sensitive superalloy machining in German and French aerospace clusters. Stuttgart and Munich aerospace corridors demand sub-micrometer tolerance tools for turbine blade root profiling.
United States
OSHA's Respirable Crystalline Silica Standard enforcement compels California and New York metropolitan contractors to specify vacuum-shrouded diamond cutting systems that suppress respirable dust at the point of generation. Dust suppression specifications have become disqualifying criteria in public infrastructure bids, forcing rental fleet upgrades across developed construction markets. Texas and Florida infrastructure maintenance providers adopt sensor-embedded core drill rigs for predictive bit replacement scheduling.
Italy
Carrara quarrying operations in Tuscany consume metal-bonded grinding tools for continuous water-cooled marble processing, where mechanical diamond retention withstands elevated normal forces. Wet grinding applications dominate stone extraction workflows, with Emilia-Romagna fabricators supplying precision profile wheels to domestic and export markets. Italian stone processing clusters anchor European demand for metal-bonded variants in abrasive environments.
Brazil
Minas Gerais stone processing clusters specify metal-bonded diamond tools for granite and engineered stone quarrying operations in continuous water-cooled environments. Brazilian stone extraction workflows mirror Italian wet grinding applications, with São Paulo-based distributors serving both domestic construction and export-oriented fabrication. ANVISA regulates industrial equipment safety certification, though diamond tool imports face fewer documentation barriers than Chinese GB standards requirements.
Global Diamond Tools Market Vendor Landscape
Top-tier vendors anchor premium aerospace and automotive OEM supply contracts, while mid-scale fabricators compete on construction sector volume and fleet management subscription penetration. The vendor base stratifies across three tiers: synthetic diamond feedstock integrators with captive material supply, precision system specialists commanding laser fabrication premiums, and construction-focused consumable suppliers monetizing replacement cycles. Strategic archetypes include backward-integrated material producers, sensor-embedded equipment innovators, and tool-as-a-service platform operators. Dominant competitive moves encompass predictive diagnostics integration and bonding chemistry patent thickets that complicate new entrant R&D pathways.
Among established European fabricators, Hilti Corporation and Husqvarna AB occupy positions representing divergent strategic vectors: the former exemplifies fleet management subscription models locking contractor loyalty across job sites, while the latter anchors remote diagnostics integration embedding sensors into equipment for predictive maintenance scheduling. Saint-Gobain represents the backward-integrated archetype, with captive synthetic diamond production insulating margin pools from raw material volatility. These three entities collectively illustrate how competitive positioning in diamond tools depends on whether vendors prioritize consumable replacement monetization, equipment-software integration, or upstream material control.
| Leading Market Players |
|---|
| Hilti Corporation |
| Husqvarna AB |
| Saint-Gobain |
| Makita |
| Asahi Diamond Industrial |
| Sumitomo Electric Industries Ltd. |
| Tyrolit |
| Bosch |
| Shinhan Diamond |
| Others |
Supply Flow & Price Mechanics
Laser fabrication adoption in aerospace turbine blade processing simultaneously compresses production tolerances and concentrates premium tool pricing power among vendors with captive synthetic diamond supply. This technology shift redraws cost curves across bonding chemistry tiers while amplifying margin pressure on mechanical grinding-dependent fabricators.
Pricing Analysis
Cost-down pressure on standard-grade consumables accelerates because Henan Province synthetic diamond feedstock volatility transmits directly into spot-priced electroplated tool segments. Three-tier pricing structure across premium, standard, and economy levels separates laser-processed aerospace specifications from construction-grade metal-bonded blades and commodity electroplated discs. ISO 14001 certification premiums defend margins in automotive OEM supply contracts. Contractors in German demolition markets exhibit highest price sensitivity through total-cost-per-cut procurement metrics, while aerospace tier-1 suppliers accept premium pricing for sub-micrometer tolerance guarantees.
Supply Chain Analysis
Specialized technician shortages in Zhengzhou synthetic diamond synthesis and Guangdong precision machining clusters constrain capacity expansion timelines for laser fabrication equipment. Supply concentrates in China, Germany, and Italy, with raw material dependencies spanning high-purity methane feedstock, nickel bonding powders, and cobalt matrix alloys. Single-source vulnerability in Henan Province environmental inspection protocols disrupts feedstock availability without geographic diversification. Distribution runs through OEM direct contracts for aerospace tiers and construction rental fleet operators for demolition segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure intensifies as bonding chemistry patent thickets and ISO certification timelines force sub-scale fabricators toward exit or acquisition, concentrating market share among backward-integrated material producers and fleet management platform operators.
For Market Incumbents: Deepen captive synthetic diamond production to insulate margin pools from Henan Province energy pricing volatility. Secure laser fabrication equipment supply contracts from Chinese manufacturers upgrading capacity under MEE emissions targets. Patent thickets in ceramic-metal matrix bonding chemistry block new entrant R&D pathways and defend aerospace OEM qualification positions. For New Entrants and Emerging Players: The mid-tier price-point gap between Hilti fleet management premiums and unbranded electroplated imports offers white-space entry through sensor-embedded core drill rigs for Nordic infrastructure maintenance markets. Target Brazilian stone quarrying operations where ANVISA certification friction remains lower than Chinese GB standards barriers. Lead with predictive bit replacement scheduling software bundled with metal-bonded wet grinding consumables. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by construction equipment rental platforms seeking consumable replacement revenue streams. Long-term viability favors vendors with dual carbon alignment credentials and laser fabrication capacity serving aerospace turbine blade contracts. Watch synthetic diamond feedstock cost curves as inflection indicator for margin compression timing in standard-grade segments.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Synthetic Diamond Feedstock | Captive CVD substrate production insulates Saint-Gobain margin pools from Henan Province power rationing exposure. |
| Fleet Management Subscription Launch | Hilti-style total-cost-per-cut contracts lock German contractor replacement cycles through predictive wear analytics. |
| Laser Fabrication Capacity Expansion | Ultrashort-pulse ablation systems capture Rolls-Royce turbine blade procurement specifications mandating sub-micrometer edges. |
| Sensor-Embedded Equipment Platform | Husqvarna remote diagnostics integration enables predictive bit replacement scheduling in Nordic infrastructure maintenance markets. |
| GB Standards Certification Investment | SAMR in-country laboratory validation accelerates electroplated tool market entry for Guangdong semiconductor substrate processing demand. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs while primary interviews with diamond tool plant managers, aerospace procurement leads, construction fleet operators, and aftermarket service heads supplied operational validation. OSHA enforcement records, EU F-Gas Regulation implementation documents, SAMR GB standards databases, and synthetic diamond production statistics from provincial Chinese bureaus supplemented triangulation. Bottom-up segment sizing across product type, application, and technology dimensions reconciled with top-down market value estimates.
Data-stream reconciliation across import-export statistics, OEM procurement contract disclosures, and rental fleet operator maintenance logs informed the analytical framework throughout the projection horizon. Segmentation modeling spanned cutting, grinding, drilling, and polishing tool categories; construction, automotive, aerospace, and electrical industry applications; metal-bonded, resin-bonded, electroplated, and laser-based technologies; plus contractor, OEM, and maintenance provider end-user channels. CAGRs derived from regression analysis of historical replacement cycle frequencies and capital expenditure trajectories in precision manufacturing clusters.
Inputs from trade associations and regulatory agencies were available through the study window; gaps in real-time synthetic diamond feedstock pricing and unreported fleet management contract terms introduce uncertainty bands around subscription revenue projections. Forecasts reflect documented assumptions regarding OSHA enforcement intensity and MEE emissions target implementation pace. Material deviation in Henan Province environmental inspection protocols or EU F-Gas Regulation refrigerant rule tightening warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Wood-Burning Tool Market
Tools
Stand Tile Saw Market
Tools
United States Machine Tools Market
Tools
Dumpy Level Market
Tools
Indexable Tool Inserts Market
Tools
Metal Cutting Machine Market
Tools
Automotive Torque Tools Market
Tools
Fastening Power Tools Market
Tools
Floor Pads Market
Tools
Bottle Jack Market
Tools
Auger Drill Bits Market
Tools
Global Table Saws Market
Tools
Multi Spindle Machines Market
Tools
Nail Gun Market
Tools
Landscaping Tools Market
Tools
Trim Press Market