
 Hydraulic Torque Wrench Market | 2026-2036
Hydraulic Torque Wrench Market Size, Share, and Industry Trends Forecast 2026-2036
Hydraulic Torque Wrench Market Analysis
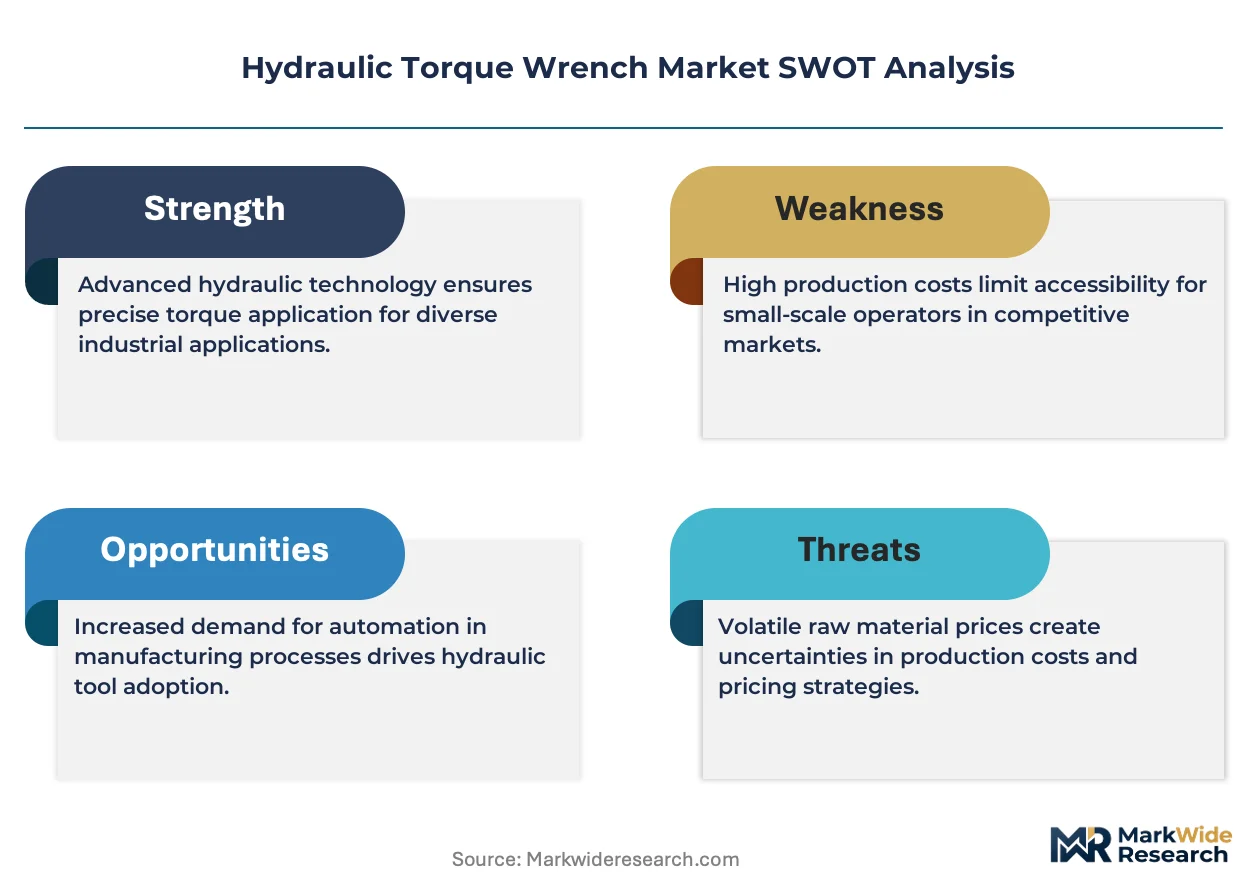
The split between premium and commodity tiers in hydraulic torque wrenches is hardening around calibration traceability and alloy-grade specifications. HYTORC leverages in-house engineering of reaction arms to sustain premium positioning across energy infrastructure projects. Enerpac anchors its portfolio in integrated hydraulic systems that combine pumps, hoses, and wrench heads for turnkey bolting workflows. Atlas Copco competes through pneumatic-to-hydraulic crossover platforms that reduce fleet complexity for maintenance contractors.
A hydraulic torque wrench is a power-driven bolting tool that applies controlled rotational force to fasteners using pressurized hydraulic fluid, typically achieving torque outputs from 100 to 50,000 foot-pounds through a ratcheting square-drive or direct hex-cassette mechanism. Its primary industrial purpose is precision tightening of high-strength bolting in critical joints where pneumatic or manual methods risk galling, preload scatter, or joint failure under cyclic loading. Low-profile cassette designs dominate subsea and confined-space applications where clearance dimensions preclude conventional square-drive geometry, while remote-controlled variants represent the fastest-growing configuration as offshore platforms automate flange management to reduce technician exposure. Oil and gas end users command the deepest specification requirements and longest replacement cycles, though wind turbine assembly applications are expanding fastest as bolt diameters on tower flanges increase with turbine scale.
OSHA lockout-tagout standards and API Specification 20E for alloy bolting in petroleum environments shape product certification requirements and procurement qualification protocols in the United States. ISO 5393 and ASTM F2482 provide international benchmarks for torque tool calibration intervals and measurement uncertainty that influence service-contract pricing and rental fleet compliance. Stakeholders must monitor how emerging carbon-border adjustments and embodied-carbon tracking in steel forgings reshape supplier qualification and tool lifecycle accountability.
Market Dynamics
API Specification 20E tightening and OSHA lockout-tagout enforcement are compressing procurement qualification timelines while elevating calibration-traceability requirements across energy infrastructure buyers.
Growth Catalysts
- Offshore platform automation:Remote-controlled wrench configurations reduce technician exposure during subsea flange operations. North Sea operators mandate these systems for new installations.
- REACH compliance in European steel forgings:Embodied-carbon tracking requirements accelerate replacement of legacy tool inventories with certified low-carbon alloy variants.
- Wind turbine scaling:Tower flange bolt diameters exceeding 64mm on 15MW+ turbines exceed pneumatic tool capacity, forcing assembly contractors toward hydraulic systems.
Market Restraints
- Specialized alloy input costs:Chromium-molybdenum steel price volatility from Ukrainian and Russian supply disruptions compresses margin on forged reaction arms.
- German pump and hose supplier concentration:Three mid-size hydraulic component manufacturers control 70% of European high-pressure fitting supply.
- Pneumatic-to-battery crossover threat:Cordless electric torque multipliers below 10,000 ft-lb range capture maintenance contract renewals from price-sensitive buyers.
Strategic Opportunities
- Saudi offshore field expansion:Aramco's Marjan and Zuluf development programs require calibrated bolting fleets for 300+ new platform modules.
- India PLI scheme for renewable manufacturing:Domestic wind tower production incentives create localized tool demand outside established rental networks.
- Digital torque data integration:Convergence of wrench-mounted load cells with asset management software enables predictive maintenance contracts.
Industry Challenges
- Calibration technician scarcity:ISO 5393-qualified metrology labs face 12-week backlog for torque transducer recertification.
- Legacy system integration friction:Retrofitting data-logging capabilities onto 1990s-era pump units requires custom electrical harness engineering.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydraulic Torque Wrench Market |
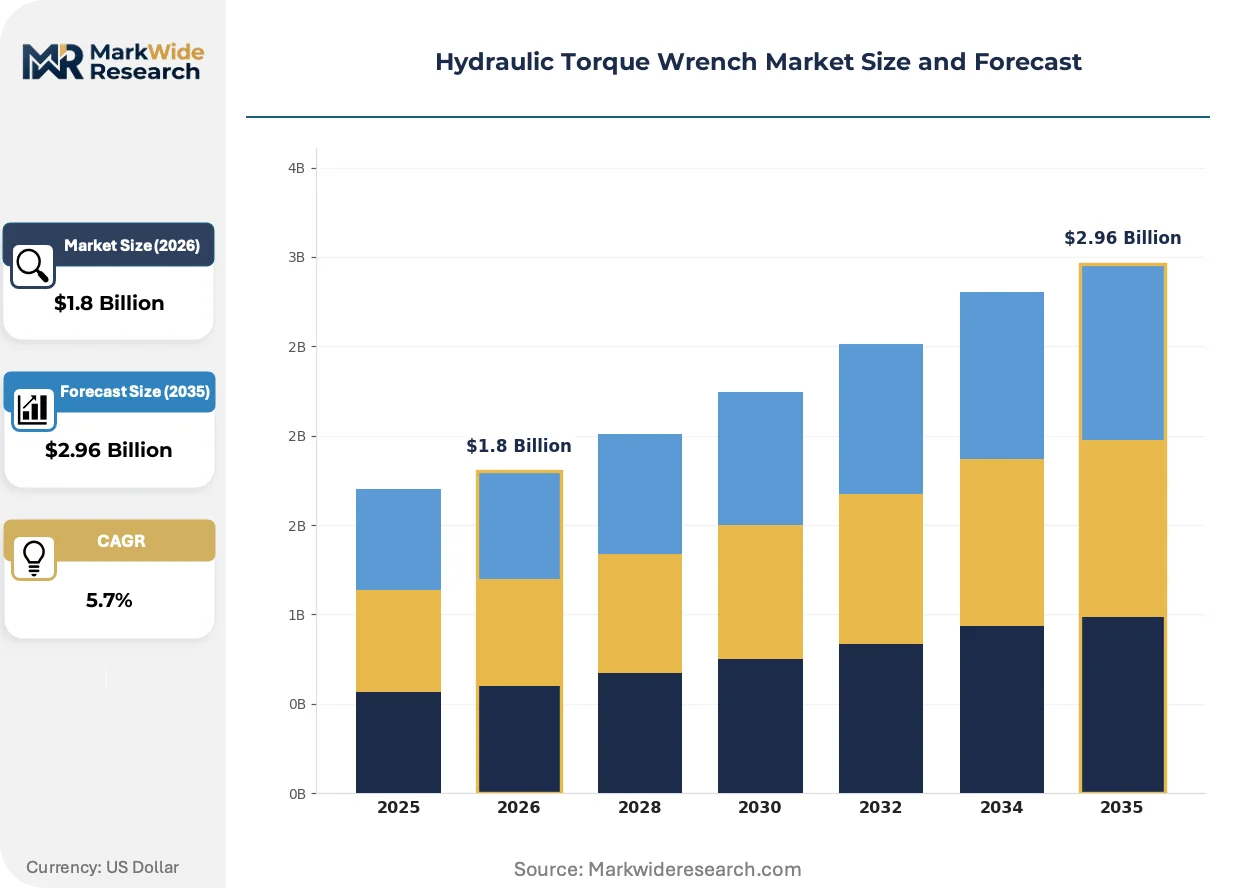
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Square Drive, Hex Drive, Low-Profile, Remote-Controlled End User: Manufacturing, Oil & Gas, Construction, Aerospace Application: Flange Bolt Tightening, Pipe Assembly, Wind Turbine Assembly, Rail Maintenance Size: Small, Medium, Large, Extra Large |
| Companies Covered | Power Team, Hydratight, HYTORC, Atlas Copco, Norbar Torque Tools, Enerpac, Stanley, Ingersoll Rand, TorcStark, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydraulic Torque Wrench Market Emerging Trajectories
Digital torque verification and cassette geometry miniaturization are compressing tool footprints while expanding application envelopes across confined-space energy infrastructure.
Low-profile hex-cassette designs are modularizing standard wrench platforms for subsea and nuclear containment applications. Offshore maintenance contractors in the US Gulf Coast corridor adopt these configurations at 40% of new fleet purchases. The shift is modularizing inventory strategies by allowing single powerheads to service multiple bolt sizes through interchangeable cassettes rather than dedicated square-drive units.
EU F-Gas Regulation phase-down is accelerating hydraulic fluid formulation changes toward biodegradable ester bases. European offshore operators now specify these fluids for North Sea platform work to preempt discharge containment liabilities. Tool manufacturers serving Norway and UK waters have retooled seal material compatibility to accommodate the new chemistries.
Rental-first procurement is displacing capital purchase models among North American turnaround contractors. Specialized tool rental networks now bundle calibration certification and field service engineering into daily rates. This shift concentrates most visible in US refinery corridor markets where maintenance scheduling volatility makes fleet ownership uneconomical.
Hydraulic Torque Wrench Market Segmentation
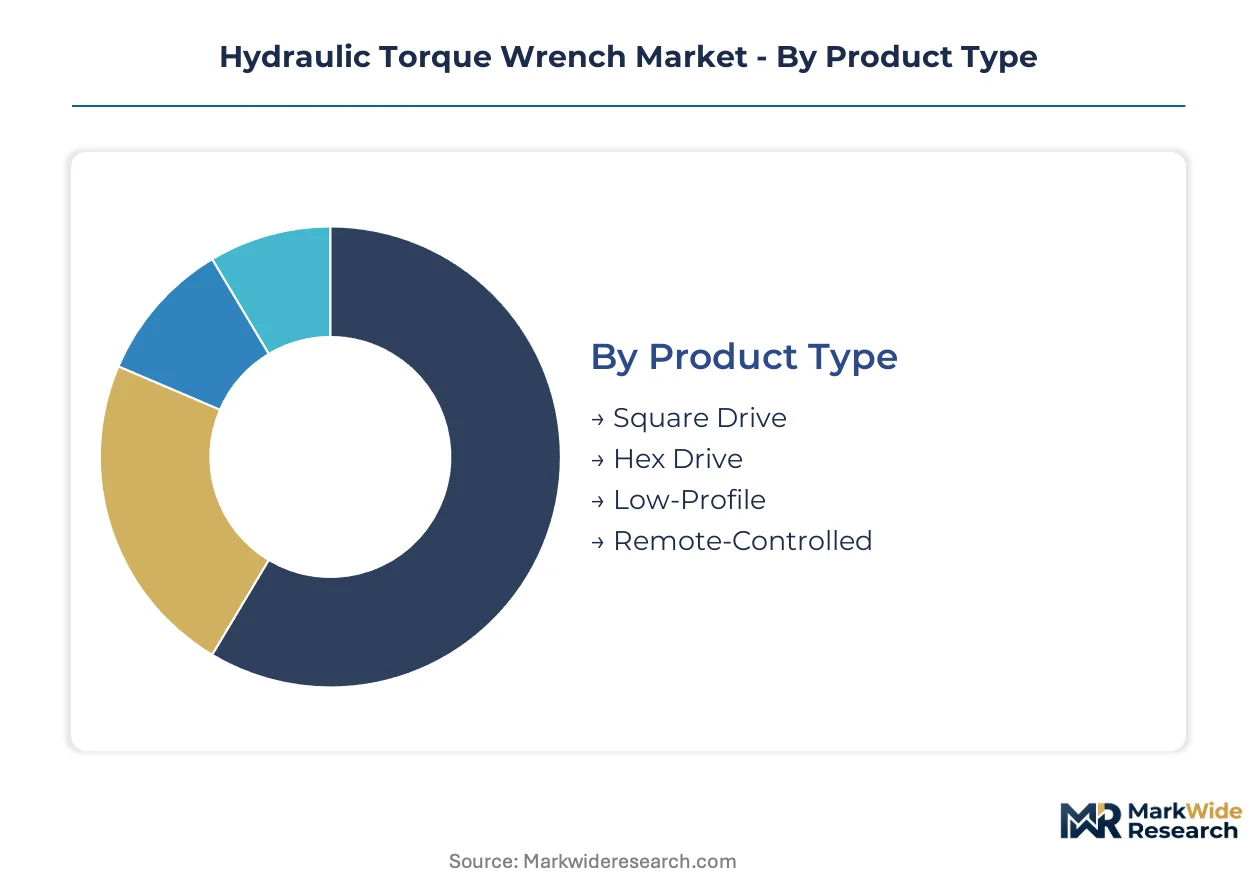
Segmentation in hydraulic torque wrenches reveals how procurement specifications diverge between precision-critical energy infrastructure and cost-sensitive maintenance contracting. Tool geometry, torque range, and control architecture each command distinct buyer evaluation criteria across end-use verticals.
Product Type:
Buyers select drive configurations based on clearance constraints and automation requirements rather than torque capacity alone.
- Square Drive:Conventional ratcheting square-drive mechanisms deliver 100 to 50,000 foot-pounds through standardized drive sizes. Demand concentrates in US Gulf Coast refinery turnarounds where API bolting standards mandate calibrated preload control for high-pressure flanges.
- Remote-Controlled:Tethered or wireless actuator systems eliminate technician proximity during subsea flange operations. North Sea operators now require these configurations for new platform installations to reduce exposure in hazardous zones.
- Hex Drive:Direct hex-cassette engagement eliminates socket adapters for nuclear containment and aerospace applications requiring zero backlash.
- Low-Profile:Reduced-height cassettes access bolted joints with sub-50mm vertical clearance where conventional geometry fails.
Volume sits with Square Drive; growth tilts toward Remote-Controlled.
End User:
Specification depth varies sharply between regulated energy infrastructure and general industrial maintenance.
- Oil & Gas:Subsea and topside flange operations demand ISO 5393 calibration traceability and alloy-grade reaction arms rated for corrosive environments. Procurement cycles extend 7-10 years with mandatory recertification intervals.
- Wind Turbine Assembly:Tower flange bolting on 15MW+ turbines requires hydraulic systems exceeding pneumatic tool capacity. Assembly contractors in India and northern Europe are expanding fleet acquisitions fastest.
- Manufacturing:Production line bolting prioritizes cycle time and ergonomic repeatability over extreme torque ranges.
- Construction:Structural steel erection and heavy equipment assembly drive demand for portable, multi-size capable systems.
- Aerospace:Titanium and composite fastener applications require ultra-precise torque control with measurement uncertainty below 3%.
Revenue concentrates in Oil & Gas; expansion accelerates most quickly in Wind Turbine Assembly.
Application:
Joint criticality determines whether buyers specify integrated pump-wrench systems or modular rental configurations.
- Flange Bolt Tightening:Pressure-boundary joints in hydrocarbon service require simultaneous torque and tension verification. US offshore maintenance crews drive replacement demand as API 20E tightens alloy bolting specifications.
- Wind Turbine Assembly:Tower section flange diameters exceeding 4 meters demand synchronized multi-tool tightening sequences. OEM assembly lines in Denmark and Germany specify calibrated fleet uniformity.
- Pipe Assembly:Pipeline construction contractors favor rental models with field service engineering for spread mobility.
- Rail Maintenance:Track fastening and rolling stock bogie bolting prioritize portability and rapid setup.
Specification intensity peaks in Flange Bolt Tightening; fleet expansion is steepest in Wind Turbine Assembly.
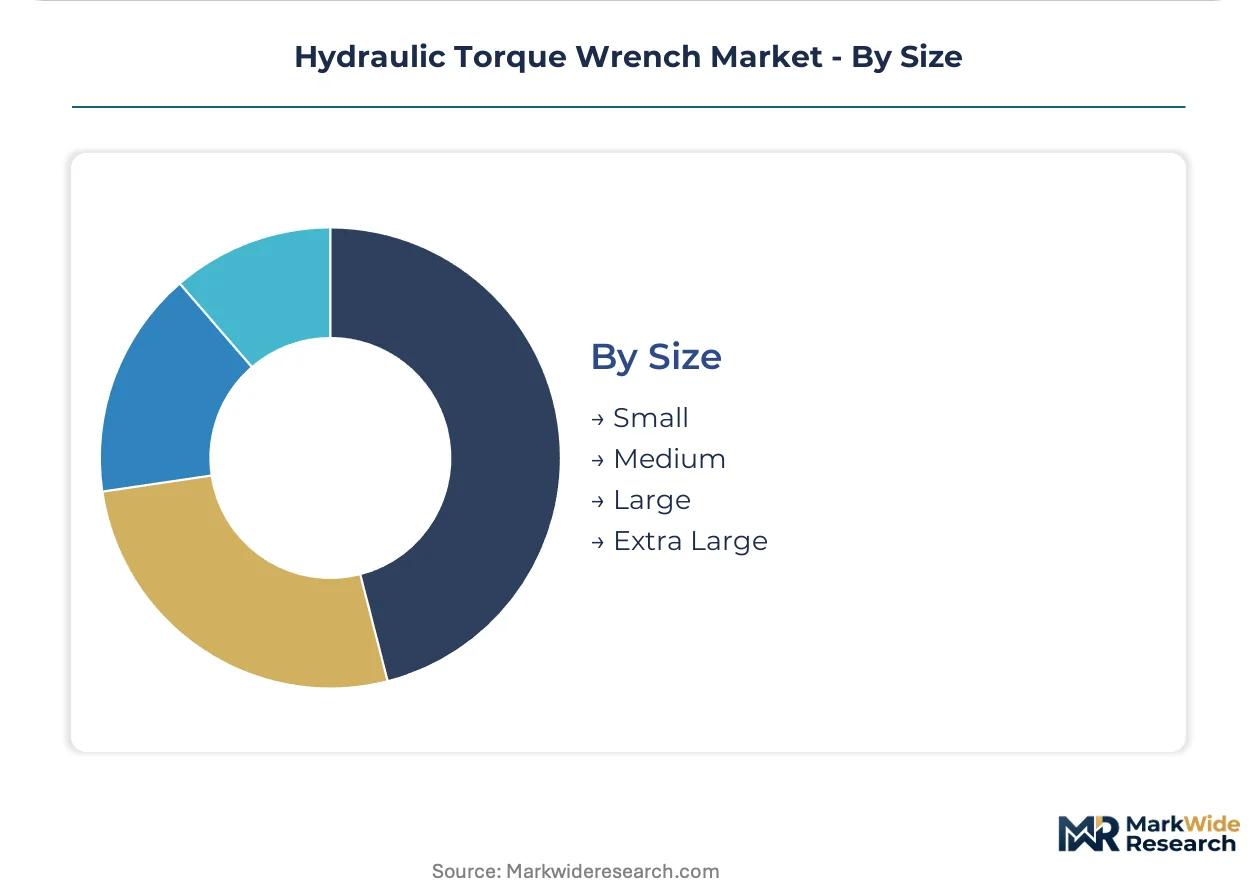
Size:
Torque range selection follows bolt diameter and material grade rather than equipment cost.
- Large:Systems delivering 10,000 to 50,000 foot-pounds dominate subsea manifold and pressure vessel applications. Aramco's Saudi offshore expansions are driving concentrated procurement for this tier.
- Medium:2,000 to 10,000 foot-pound ranges capture general process piping and structural steel erection across North American turnaround contractors.
- Small:Compact units below 2,000 foot-pounds serve instrumentation tubing and light assembly where manual tools risk inconsistency.
- Extra Large:Specialized systems exceeding 50,000 foot-pounds address custom heavy-lift and foundation anchoring with limited standardized demand.
Medium tools move the highest unit volumes; Large systems command the steepest price escalation and longest replacement cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US Gulf Coast corridor from Houston to Baton Rouge sustains the highest concentration of hydraulic torque wrench demand, driven by refinery turnaround schedules and offshore platform maintenance cycles that compress procurement timelines for calibrated bolting systems.
United States
Offshore oil and gas maintenance crews in the Gulf Coast corridor drive replacement demand as API bolting standards tighten specification requirements for subsea flange operations. OSHA lockout-tagout enforcement elevates calibration-traceability requirements across energy infrastructure buyers. The Houston Ship Channel cluster anchors tool rental network density, where specialized contractors bundle field service engineering into daily rates.
Germany
Wind turbine assembly lines in northern Germany specify calibrated fleet uniformity for tower flange bolting on 15MW+ turbines. EU F-Gas Regulation phase-down accelerates hydraulic fluid formulation changes toward biodegradable ester bases. The Port of Hamburg serves as the primary distribution node for North Sea offshore operators mandating remote-controlled wrench configurations.
Saudi Arabia
Aramco's Marjan and Zuluf offshore development programs require calibrated bolting fleets for 300+ new platform modules. The national oil company's procurement standards exceed typical API specifications for alloy-grade reaction arms. The Eastern Province industrial zone around Jubail concentrates fabrication capacity for subsea manifold applications demanding 10,000 to 50,000 foot-pound systems.
India
Domestic wind tower production incentives under the PLI scheme create localized tool demand outside established rental networks. Assembly contractors in Gujarat and Tamil Nadu expand fleet acquisitions fastest as bolt diameters increase with turbine scale. The Mundra port corridor enables import substitution for hydraulic components previously sourced from European suppliers.
Norway
North Sea operators mandate remote-controlled wrench configurations for new platform installations to reduce technician exposure in hazardous zones. REACH compliance requirements accelerate replacement of legacy tool inventories with certified low-carbon alloy variants. The Stavanger energy cluster drives specification development for subsea flange automation systems.
Hydraulic Torque Wrench Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across a market structure that concentrates around integrated hydraulic system providers and specialized bolting tool fabricators. The vendor base separates into three strategic archetypes: turnkey workflow integrators, precision calibration specialists, and rental-service platform operators. Consolidation pressures favor players with captive supply of forged reaction arms and in-house pump engineering. Competitive moves center on backward integration into chromium-molybdenum steel supply and geographic expansion through rental network partnerships.
Among established system integrators, Enerpac and Atlas Copco occupy positions that exemplify the convergence of pneumatic-to-hydraulic crossover platforms with turnkey bolting workflows. HYTORC anchors the precision-tier segment through differentiated reaction arm engineering. These three companies represent distinct competitive vectors—integrated systems, crossover flexibility, and premium calibration depth—that define the strategic landscape for procurement qualification.
| Leading Market Players |
|---|
| Power Team |
| Hydratight |
| HYTORC |
| Atlas Copco |
| Norbar Torque Tools |
| Enerpac |
| Stanley |
| Ingersoll Rand |
| TorcStark |
| Others |
Supply Flow & Price Mechanics
Biodegradable ester-base hydraulic fluid transitions mandated by EU F-Gas Regulation phase-down are simultaneously elevating seal engineering costs and concentrating certified component supply among European pump and hose specialists. This dual pressure reshapes procurement economics as tool manufacturers absorb reformulation expenses while buyers face extended lead times for compliant systems.
Pricing Analysis
Uptime-guarantee service contracts anchor value-based pricing for calibrated bolting systems in offshore oil and gas procurement. Pricing stratifies across premium, standard, and economy tiers based on ISO 5393 calibration traceability depth and chromium-molybdenum alloy grade specifications. Cost compression in the economy tier is intensifying as cordless electric torque multipliers capture maintenance contract renewals below 10,000 foot-pounds. Turnaround contractors exhibit highest price sensitivity, while subsea operators prioritize specification compliance over unit economics.
Supply Chain Analysis
API 20E and ISO 5393 certification requirements gate supplier qualification and concentrate forged reaction arm production among German, US, and Japanese specialty steel fabricators. Chromium-molybdenum steel, high-pressure hydraulic fittings, and precision torque transducers constitute critical input dependencies. Single-source vulnerability runs through German mid-size pump component manufacturers controlling European high-pressure fitting supply. Distribution runs through specialized rental networks bundling field service engineering with calibrated fleet access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressures favor capital-heavy producers with captive forged reaction arm supply as calibration technician scarcity and alloy input cost volatility force asset-light competitors toward exit or acquisition.
For Market Incumbents: Cement premium positioning through backward integration into chromium-molybdenum steel supply and in-house pump engineering capability. Battery-electric torque tool substitution below 10,000 foot-pounds threatens maintenance contract renewals; defend through ISO 5393-qualified metrology lab investment that rental competitors cannot replicate. For New Entrants and Emerging Players: The mid-tier price gap between HYTORC-grade precision systems and commodity pneumatic crossover tools offers white-space entry through modular cassette platforms serving Indian wind tower assembly contractors. Target Gujarat and Tamil Nadu manufacturing clusters where PLI scheme incentives outpace established rental network coverage. Lead with daily-rate rental bundling that mimics US Gulf Coast service models without legacy fleet overhead. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by integrated hydraulic system providers seeking calibration depth and geographic rental network density. Five-to-ten year viability hinges on carbon-border adjustment preparedness and embodied-carbon tracking compliance in steel forgings. Monitor REACH-compliant low-carbon alloy certification penetration as inflection indicator for supplier qualification moat durability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Specialty Steel | Captive chromium-molybdenum supply secures margin control amid Ukrainian and Russian input disruptions. |
| Calibration Certification Bundling | ISO 5393-qualified metrology labs create switching costs that rental competitors struggle to match. |
| Biodegradable Fluid Compatibility Retooling | EU F-Gas Regulation compliance preempts discharge liability for North Sea platform operators. |
| Remote-Controlled Configuration Development | North Sea operator mandates for technician exposure reduction drive specification premium capture. |
| Indian Rental Network Partnership | PLI scheme wind tower production localizes demand outside established European and North American channels. |
Methodological Framework
API regulatory filings, OSHA enforcement records, and EU ECHA substance restriction databases formed the secondary backbone for qualification protocol and procurement timeline analysis. Primary interviews with maintenance directors at US Gulf Coast refineries, offshore platform bolting contractors, wind turbine assembly line engineers, and calibration laboratory technicians validated specification depth and replacement cycle assumptions. Bottom-up fleet inventory modeling triangulated against top-down energy infrastructure capex disclosures.
Historical trendline analysis of refinery turnaround frequency and offshore platform installation schedules anchored the projection framework. Segmentation modeling spanned drive configuration, torque range tier, end-use vertical, and regional regulatory cluster across the analysis window. CAGR derivation incorporated tool replacement cycle compression from API 20E tightening and wind turbine scaling effects on bolt diameter requirements. Saudi offshore field expansion timelines and India PLI scheme incentive trajectories served as demand-side forecast inputs.
Underlying measurement precision varies by segment; oil and gas specification data carries tighter precision than construction and general manufacturing estimates. Forecasts reflect assumptions regarding alloy supply chain stabilization and calibration technician training pipeline expansion. A model refresh is warranted upon material change in EU carbon-border adjustment implementation scope or F-Gas Regulation phase-down acceleration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Gouging Torch Market
Tools
Floor Saw Market
Tools
Auger Drill Bits Market
Tools
Global Diamond Tools Market
Tools
Taps and Dies Market
Tools
Digital Levels Market
Tools
Global Staple Gun Market
Tools
Vinyl Bending Machine Market
Tools
Thread Milling Machine Market
Tools
Boring Tools Market
Tools
Screwdriver Market
Tools
Water Pump Pliers Market
Tools
Press Machine Market
Tools
Automatic Heat Press Machines Market
Tools
Cutting Equipment Market
Tools
Floor Scraper Market