
 Taps and Dies Market | 2026-2036
Taps and Dies Market Size, Share, and Industry Trends Forecast 2026-2036
Taps and Dies Market Outlook
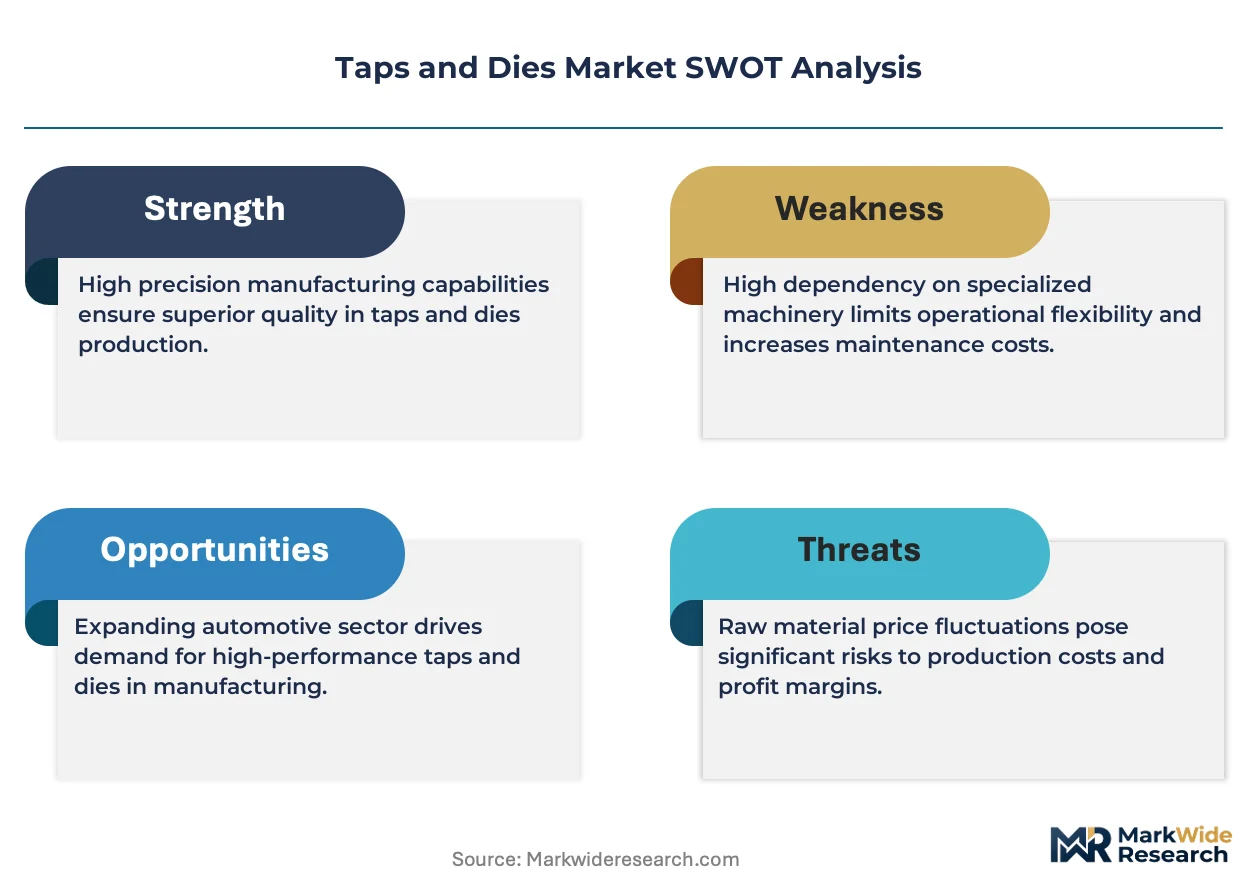
REACH is broadening the cost-of-entry calculus for European suppliers by mandating substitution assessments for cobalt and nickel in high-speed steel alloys. OSG Corporation leverages its coating technology leadership to sustain premium positioning in TiAlN-coated machine taps. Guhring anchors its competitiveness through integrated carbide blank production and captive grinding operations. Sandvik AB dominates superalloy threading applications with advanced substrate formulations that navigate increasingly stringent material restrictions.
Taps and dies are precision cutting tools engineered to cut internal threads (taps) or external threads (dies) in metal workpieces, typically manufactured from high-speed steel or solid carbide with hardness ratings exceeding 62 HRC after heat treatment. Machine taps with through-coolant channels now command the largest product type share as CNC machining centers proliferate across automated production lines. High-speed steel retains material dominance due to its toughness-cost balance, though carbide is displacing it in hardened-material aerospace applications where spindle speeds exceed conventional thresholds. TiAlN-coated variants represent the fastest-growing coating category as the layer withstands cutting temperatures above thermal decomposition limits of simpler TiN formulations.
FDA oversight of medical device threading specifications creates parallel compliance requirements for surgical instrument manufacturers sourcing precision taps. EPA metalworking fluid regulations in the United States and ECHA substance restrictions in Europe collectively reshape coolant compatibility testing for coated tool portfolios. Stakeholders must monitor evolving dual-use export controls on carbide substrates and decide whether to qualify alternative ceremet compositions before supply chain disruptions materialize.
Market Dynamics
The Taps and Dies Market is being fundamentally restructured by REACH-mandated cobalt substitution in high-speed steel formulations, which is forcing alloy reformulation across European supply chains while creating competitive separation between compliant and non-compliant producers.
Growth Catalysts
- Aerospace tolerance tightening:Flight-component specifications now demand sub-micron thread accuracy, pulling precision carbide threading tools into turbine blade and landing gear production.
- Through-coolant machine tap proliferation:CNC machining center penetration on automated lines is accelerating specification of internal coolant channels for chip evacuation and thermal stability.
- REACH substitution mandates:ECHA-driven cobalt assessments in high-speed steel alloys are creating first-mover advantages for suppliers with qualified reduced-cobalt formulations.
Market Restraints
- Tungsten carbide powder concentration:Raw material sourcing for solid carbide tools remains concentrated among limited suppliers, exposing pricing volatility to mining output fluctuations.
- Superalloy threading complexity:Inconel and titanium workpiece applications demand substrate hardness exceeding 65 HRC, restricting viable tool materials to premium carbide grades.
- Dual-use export controls:Carbide substrate restrictions on ceremet compositions are complicating cross-border qualification timelines for aerospace-certified threading portfolios.
Strategic Opportunities
- Additive manufacturing repair threading:3D-printed aerospace components require post-build thread machining, opening demand for specialized small-diameter taps in titanium and nickel superalloys.
- Medical device surgical instrument threading:FDA-mandated specifications for implantable device threads are creating captive demand from orthopedic and dental instrument manufacturers.
- India PLI scheme machining incentives:Production-linked incentives for precision manufacturing are accelerating local threading tool procurement from automotive and defense contractors.
Industry Challenges
- Grinding specialist scarcity:Precision thread form grinding requires 5-7 year skill development curves, constraining capacity expansion at integrated manufacturers.
- Coating qualification timelines:TiAlN and AlCrN PVD process validation for aerospace threading applications demands 18-24 month customer approval cycles.
- Legacy ERP integration friction:Tool life monitoring systems for predictive replacement scheduling face interoperability barriers with incumbent MES platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Taps and Dies Market |
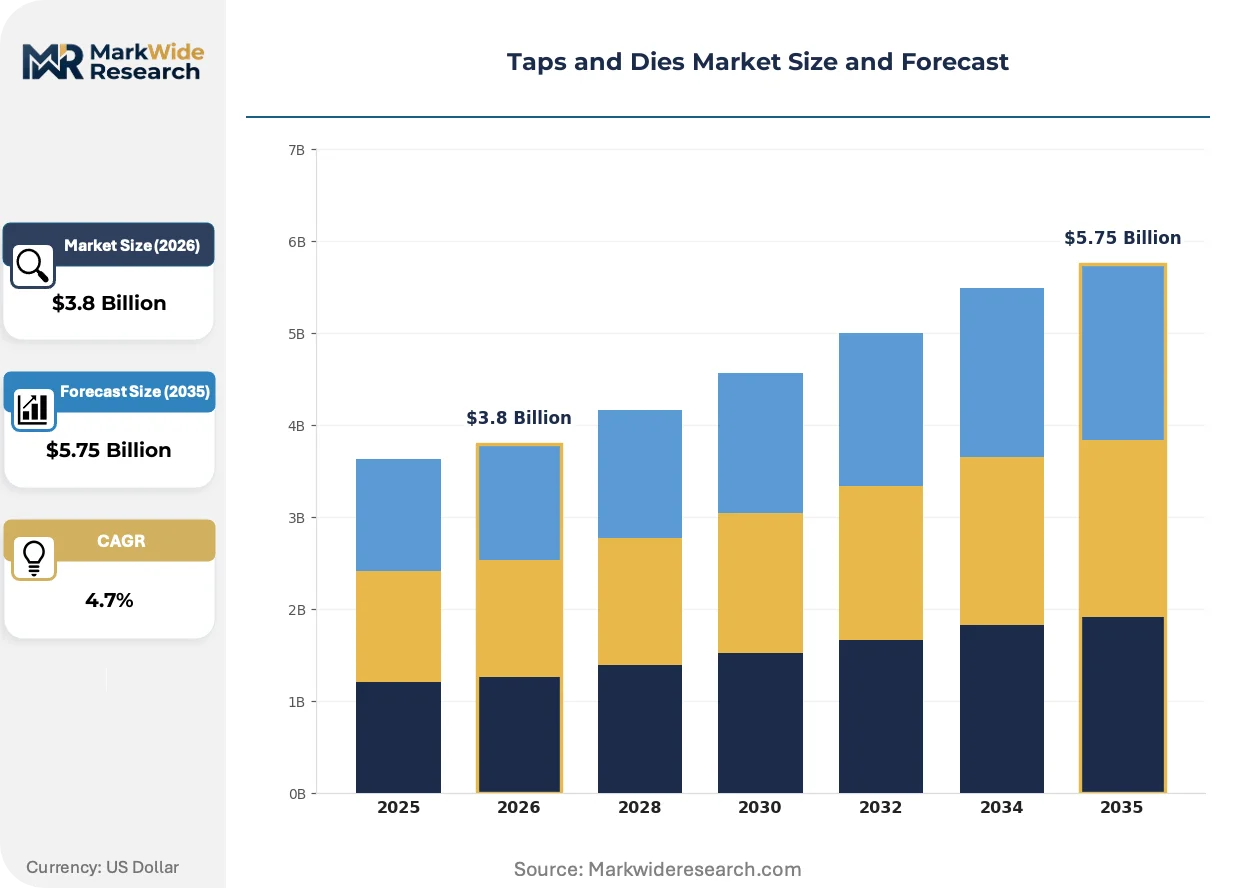
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.75 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hand Taps, Machine Taps, Taper Taps, Threading Dies Material: High-Speed Steel, Carbon Steel, Carbide, Alloy Steel Coating Type: Uncoated, TiN Coated, TiAlN Coated, Coated Application: Automotive Manufacturing, Aerospace Engineering, General Machining, Construction |
| Companies Covered | Kennametal, OSG Corporation, Guhring, Sandvik AB, Emuge, Walther Tools, Dormer Pramet, Chicago Latrobe, M.A. Ford, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Taps and Dies Market Strategic Shifts
Threading technology is converging around thermal management and material compliance, with coating chemistry and substrate formulation advancing in parallel rather than sequentially.
Physical vapor deposition of high-aluminum-content TiAlN coatings is rewriting performance benchmarks for high-speed steel taps in stainless steel applications. Automotive powertrain manufacturers in Germany's Baden-Württemberg cluster are specifying these variants for crankshaft and camshaft threading lines. The technology is compressing tool replacement intervals while extending usable cutting speeds beyond thermal decomposition thresholds of conventional TiN layers.
REACH substance restriction assessments now cover nickel and cobalt classifications in high-speed steel alloys, forcing European manufacturers to reformulate M35 and M42 grades. ECHA compliance deadlines are compressing substitution timelines for threading tool producers serving medical and aerospace end-uses. Suppliers with captive metallurgical laboratories in Germany and Switzerland are accelerating qualification of reduced-cobalt matrix compositions ahead of regulatory enforcement.
Consolidated procurement of threading portfolios by tier-one automotive suppliers is displacing fragmented multi-vendor sourcing patterns. Volkswagen Group and BMW procurement centers are mandating single-source threading contracts with integrated coating and regrind services. This concentration is most visible in Germany's automotive supply chain, where machining contractors face vendor reduction mandates tied to CSRD supply chain disclosure requirements.
Taps and Dies Market Segmentation
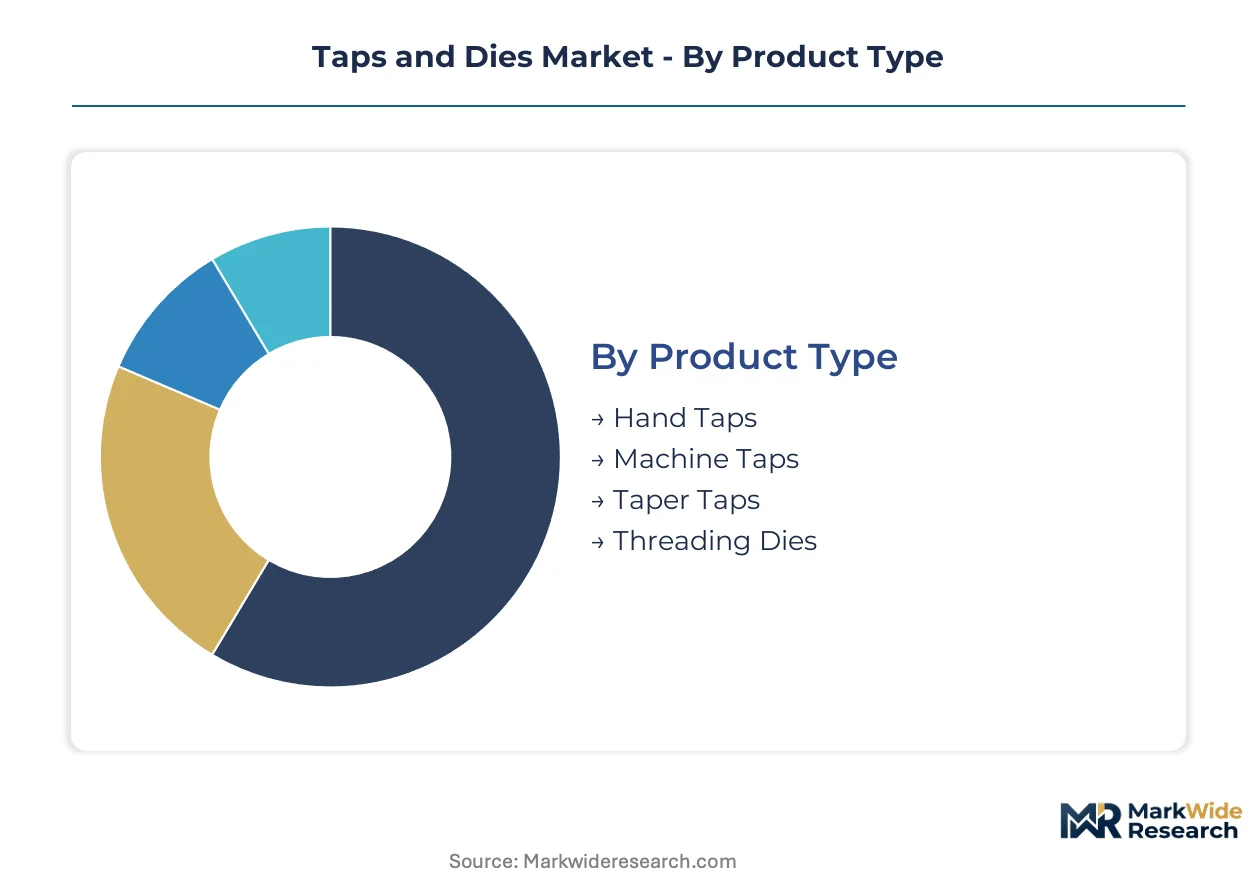
Threading tool procurement patterns diverge sharply between high-volume automotive lines and precision aerospace cells, with material specifications and coating investments tracking these operational economics. Understanding where volume concentrates versus where margins accumulate clarifies supplier positioning across divergent customer workflows.
Product Type:
Machine taps dominate unit economics through automated production penetration, while hand taps retain residual demand in maintenance and repair operations where spindle access is constrained.
- Machine Taps:Through-coolant internal channels accommodate CNC machining center thermal management requirements. Volkswagen Group procurement centers in Germany's Baden-Württemberg cluster specify these variants for crankshaft production lines where chip evacuation determines cycle time consistency.
- Threading Dies:External thread cutting for shaft and bolt applications demands adjustable die heads in automotive powertrain operations. BMW single-source contracts now mandate integrated regrind services for threading die portfolios serving transmission component lines.
- Hand Taps:Maintenance technicians in general machining shops employ these for repair threading where portable operation outweighs speed requirements.
- Taper Taps:Starting threads in blind holes requires the tapered lead for gradual chip load distribution in manual and semi-automated applications.
Today's leader: Machine Taps. Tomorrow's challenger: Threading Dies.
Material:
Cost-performance tradeoffs segment procurement between toughness-optimized high-speed steel and hardness-driven carbide specifications for hardened workpiece applications.
- High-Speed Steel:M35 and M42 grades balance fracture resistance against tool cost in stainless steel threading operations. REACH-mandated cobalt substitution assessments in Europe are forcing reformulation timelines for European suppliers serving medical device manufacturers.
- Carbide:Solid carbide substrates exceed 65 HRC hardness ratings for Inconel and titanium aerospace workpieces where spindle speeds surpass high-speed steel thermal limits. Sandvik AB dominates superalloy threading applications with advanced substrate formulations navigating material restrictions.
- Carbon Steel:Low-cost hand tap production for general-purpose threading in construction and maintenance applications where tool life expectations are modest.
- Alloy Steel:Intermediate hardness grades for threading operations requiring wear resistance beyond carbon steel without carbide price premiums.
High-speed steel commands present volume. Carbide claims the steepest expansion trajectory as aerospace tolerance requirements tighten.
Coating Type:
Thermal barrier performance separates specification tiers, with aluminum-rich formulations commanding aerospace qualification premiums over standard titanium nitride layers.
- TiAlN Coated:High-aluminum PVD layers withstand cutting temperatures above TiN decomposition thresholds in stainless steel applications. OSG Corporation leverages coating technology leadership to sustain premium positioning in machine tap specifications for automated lines.
- TiN Coated:Baseline gold-colored titanium nitride remains specified for general machining where thermal loads remain moderate and cost sensitivity dominates.
- Uncoated:Short-run applications and soft material threading where coating cost cannot be amortized across sufficient cutting cycles.
- Coated:Generic coating designation capturing alternative PVD formulations including AlCrN variants emerging from European supplier laboratories.
TiAlN layers accumulate specification momentum. TiN coatings defend installed base positions through cost-driven replacement cycles.
Application:
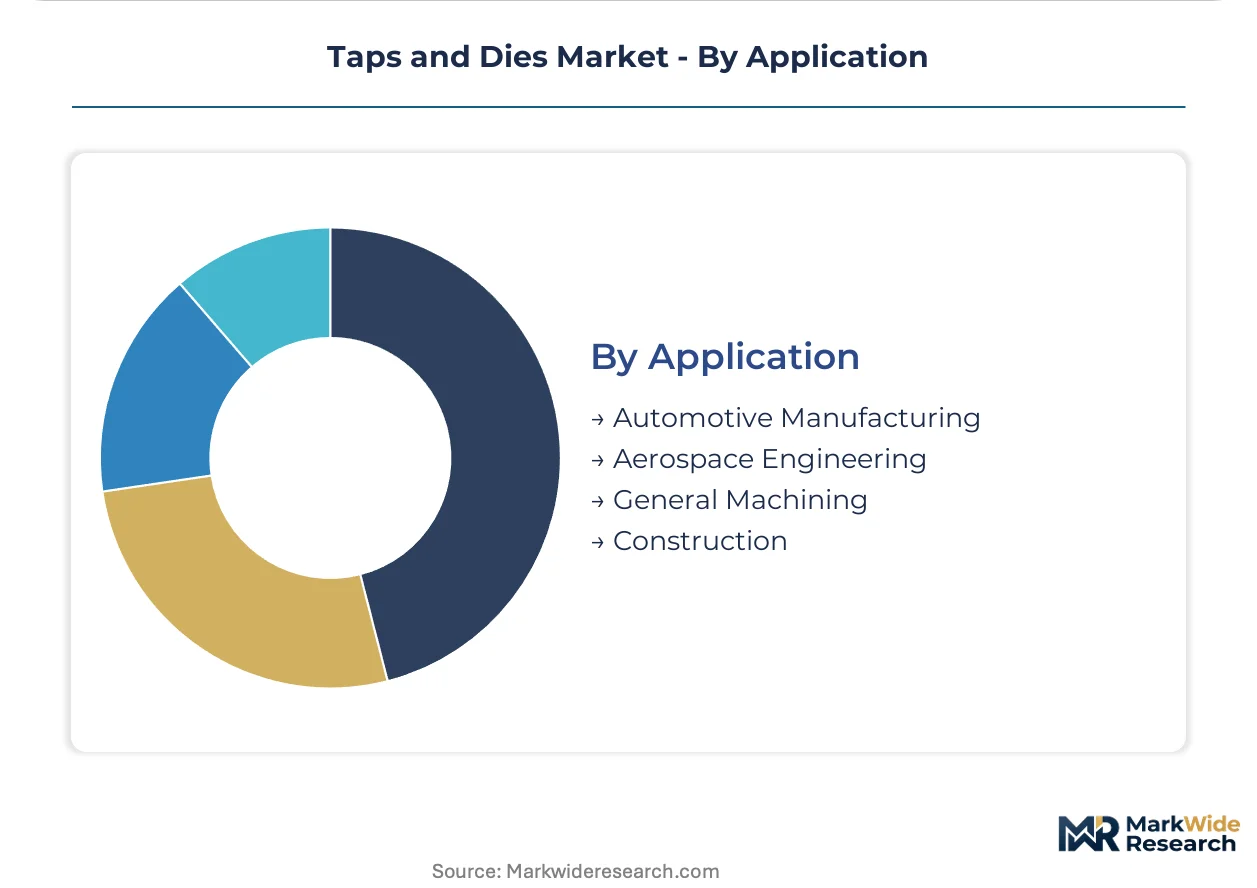
End-use concentration patterns align with regional manufacturing clusters, with automotive procurement scale contrasting aerospace qualification complexity.
- Automotive Manufacturing:Powertrain threading operations for crankshafts, camshafts, and transmission housings drive recurring high-volume demand. Germany's machining cluster concentrates specification authority for European automotive supply chains.
- Aerospace Engineering:Turbine blade and landing gear threading demands sub-micron accuracy with superalloy workpiece hardness exceeding conventional tool limits. Flight-component tolerances are pulling precision carbide threading tools into certified supplier portfolios.
- General Machining:Job shop and contract manufacturer demand spanning diverse materials and batch sizes with tooling flexibility prioritized over single-application optimization.
- Construction:Structural steel threading for infrastructure and commercial building applications where tool durability under abrasive conditions determines procurement decisions.
Automotive anchors present procurement volume. Aerospace engineering commands the fastest margin expansion as certification barriers concentrate supplier relationships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German tool-and-die masters anchor the European precision threading workforce, while Japanese grinding specialists and American carbide metallurgists concentrate in distinct regional clusters shaped by local manufacturing heritage.
Germany
Automotive powertrain and aerospace turbine threading drive tooling procurement from Stuttgart-based machining contractors. ECHA REACH substance restrictions on cobalt and nickel in high-speed steel alloys force Baden-Württemberg suppliers to accelerate reduced-cobalt M35 reformulation timelines. Volkswagen Group and BMW procurement centers in Wolfsburg and Munich now mandate single-source threading contracts with integrated regrind services.
United States
FDA medical device threading specifications and FAA flight-component tolerances pull precision carbide tools into orthopedic instrument and landing gear production. EPA metalworking fluid regulations reshape coolant compatibility testing for coated tool portfolios serving surgical instrument manufacturers. Aerospace engineering firms in Connecticut and Ohio expand superalloy threading capacity for Inconel turbine applications.
Japan
METI industrial technology roadmaps prioritize advanced coating chemistry for stainless steel threading operations in automotive and precision machinery sectors. OSG Corporation leverages domestic PVD expertise to sustain premium positioning in TiAlN-coated machine taps. Nagoya-area machining clusters supply Toyota and Honda powertrain lines with through-coolant threading tools.
India
PLI scheme production-linked incentives for precision manufacturing accelerate local threading tool procurement from automotive and defense contractors. BIS standards compliance requirements shape domestic supplier qualification for crankshaft and transmission component threading. Tamil Nadu and Maharashtra machining clusters concentrate demand from tier-one automotive suppliers.
China
MIIT advanced manufacturing initiatives and GB standards for cutting tool performance reshape domestic threading tool specification in automotive and general machinery sectors. Yangtze River Delta machining clusters concentrate demand for high-volume machine taps serving electric vehicle powertrain production. NMPA medical device regulations create parallel compliance requirements for surgical instrument threading.
Taps and Dies Market Competitive Environment
The competitive structure tilts toward integrated specialists with captive metallurgy and coating capabilities. Kennametal and Sandvik AB anchor the premium carbide substrate tier through advanced material formulations, while OSG Corporation and Guhring occupy positions defined by coating technology leadership and integrated blank production. Mid-scale regional fabricators compete on regrind service proximity and custom geometry flexibility. Strategic moves concentrate on backward integration into carbide powder sourcing and geographic expansion through distributor network consolidation in emerging manufacturing clusters.
Among Japanese specialists, OSG Corporation exemplifies the coating-technology archetype, while Guhring anchors the European integrated-manufacturer tier with captive grinding operations. Sandvik AB represents the superalloy-focused premium substrate specialist serving aerospace certification requirements. These three occupy positions that reflect distinct capability accumulation paths rather than convergent strategic imitation.
| Leading Market Players |
|---|
| Kennametal |
| OSG Corporation |
| Guhring |
| Sandvik AB |
| Emuge |
| Walther Tools |
| Dormer Pramet |
| Chicago Latrobe |
| M.A. Ford |
| Others |
Value Chain & Pricing Dynamics
German thread-grinding specialists in Baden-Württemberg and Stuttgart anchor the precision tooling workforce, with labor-cost differentials between these European clusters and emerging Asian manufacturing centers driving pricing-tier spreads across premium carbide and economy-grade high-speed steel offerings.
Pricing Analysis
Bundled regrind-and-coating service contracts now command premium positioning against unbundled transactional tool sales. Three-tier pricing structure across premium, standard, and economy levels separates aerospace-certified carbide substrates from automotive-grade high-speed steel and generic carbon steel hand taps. Price differentiation hinges on coating chemistry sophistication and captive metallurgical laboratory access. Cost compression in economy-grade carbon steel is intensifying because Chinese manufacturers are flooding general-purpose threading segments. Maintenance technicians in job shops exhibit the highest price sensitivity, while aerospace procurement centers prioritize performance guarantees over unit cost.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale automotive buyer demand from Volkswagen Group and BMW procurement centers, while specialized distributors serve fragmented job-shop demand across general machining applications. Raw material sourcing draws from tungsten carbide powder concentration in China, cobalt mining outputs from the Democratic Republic of Congo, and high-speed steel alloy production in Germany and Japan. Supply chain risk centers on single-source vulnerability for aerospace-certified carbide substrates subject to dual-use export controls. Distribution runs through integrated manufacturer-direct relationships for tier-one automotive contracts and regional distributor networks for aftermarket maintenance demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Taps and Dies Market represents a late-cycle quality story as flight-component tolerance tightening and REACH-mandated material compliance pull procurement toward premium substrate formulations with extended qualification timelines.
For Market Incumbents: Hedge cobalt supply exposure by accelerating captive qualification of reduced-cobalt M35 matrix compositions ahead of ECHA enforcement timelines. Secure grinding specialist pipelines through apprenticeship partnerships with Stuttgart-area technical institutes to defend against workforce scarcity. Deepen backward integration into carbide powder sourcing to buffer tungsten price volatility from Chinese mining output fluctuations.
For New Entrants and Emerging Players: The price-point gap between premium TiAlN-coated carbide and uncoated economy-grade hand taps offers white-space entry through mid-tier coated high-speed steel targeting Indian automotive PLI scheme contractors. Target Tamil Nadu and Maharashtra machining clusters where BIS standards compliance creates qualification barriers for unqualified imports. Pursue regrind-service bundling as the primary go-to-market angle to differentiate from commodity tool traders.
For Investors and Strategic Acquirers: Tier-one automotive suppliers with captive machining divisions are the most active acquirer in this space, consolidating threading tool portfolios to satisfy CSRD supply chain disclosure requirements. The acquisition target archetype combines captive coating capability with established aerospace certification relationships. Watch for inflection where REACH substance restriction assessments trigger forced supplier consolidation among non-compliant European fabricators.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Carbide Powder Production | Upstream control over tungsten sourcing buffers pricing volatility from Chinese mining concentration. |
| REACH-Compliant Alloy Reformulation | Reduced-cobalt M35 qualification ahead of ECHA deadlines captures first-mover positioning in European medical device supply chains. |
| Integrated Regrind Service Expansion | BMW and Volkswagen Group single-source contracts now mandate tool life extension services for transmission component lines. |
| TiAlN Coating Capacity Addition | High-aluminum PVD investment serves stainless steel threading demand from Baden-Württemberg automotive powertrain manufacturers. |
| Aerospace Certification Portfolio Acquisition | FAA and EASA-qualified threading tools for Inconel turbine applications command sustained margin premiums. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with tooling procurement managers at tier-one automotive suppliers, grinding operations directors at integrated manufacturers, aftermarket distribution channel heads, and aerospace quality assurance leads with secondary validation from SEC filings of listed tool manufacturers, ECHA substance restriction databases, MIIT advanced manufacturing initiative disclosures, and customs trade data for tungsten carbide powder flows. Bottom-up demand modeling across end-use applications triangulated against top-down market sizing from production capacity assessments.
Segment-weighting approaches distributed value and volume across product type, material grade, coating chemistry, and application vertical dimensions throughout the forecast period. CAGRs were derived from regression analysis of historical procurement patterns and forward-projected equipment installation rates at CNC machining centers. Industry-specific inputs included REACH compliance timeline assumptions, PLI scheme incentive disbursement schedules, and aerospace certification backlog durations.
Caveats apply where ECHA enforcement intensity, dual-use export control expansion, or tungsten supply disruptions could materially shift the outlook. Forecasts reflect documented assumptions regarding cobalt substitution technical feasibility and coating qualification cycle stability. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Parting-Off Blades Market
Tools
Belt File Sander Market
Tools
Cordless Bandsaw Sander Market
Tools
Concrete Saw Market
Tools
Industrial Cleaning Equipment Market
Tools
Construction Anchors Market
Tools
Wood-Sanding Machine Market
Tools
Woodcarving Tool Market
Tools
DIY Ball Mill Market
Tools
Bottle Jack Market
Tools
Portable Grinders Market
Tools
Grabber Pole Market
Tools
Trim Press Market
Tools
Screwdriver Market
Tools
Adoption of Benelux Power Tools Market
Tools
Wire Cutters Market