
 Handheld Pipe Cutter Market | 2026-2036
Handheld Pipe Cutter Market Size, Share, and Industry Trends Forecast 2026-2036
Handheld Pipe Cutter Market Insights
Specialty tool distribution is fragmenting as digital direct-to-contractor channels erode traditional wholesale lock-in. RIDGID leverages its service-center network to sustain loyalty among institutional plumbing fleets. Milwaukee Tool competes through battery-platform stickiness, while DeWalt anchors its position via multi-trade retail presence in big-box construction supply.
A handheld pipe cutter is a portable cutting instrument designed to sever cylindrical tubing through shearing, rotary scoring, or abrasive action, typically accommodating outer diameters from one-eighth inch to several inches depending on jaw capacity and blade geometry. The device serves plumbing, mechanical, and industrial maintenance crews who require field-accurate cuts without fixed shop equipment. Manual pipe cutter variants still dominate unit volumes due to low cost and zero power dependency, though electric pipe cutter configurations are capturing margin pools in commercial HVAC installation where speed offsets premium pricing. Material compatibility segmentation shows steel and copper applications remaining mature, while PEX and PVC cutters are expanding fastest in residential repiping and agricultural irrigation.
OSHA governs worker exposure to cutting hazards and blade guard standards for portable tools in US construction environments. ISO 11148 safety requirements for hand-held non-electric power tools shape export compliance for manufacturers serving European and Asian markets through CE marking alignment. Stakeholders must monitor how cordless platform wars and tightening silica-dust exposure rules reshape blade material selection and dust-collection attachment design.
Market Dynamics
OSHA blade guard mandates for portable cutting tools are compressing product development cycles, forcing manufacturers to redesign guard mechanisms and certification documentation before existing inventory turns obsolete.
Growth Catalysts
- Silica-dust exposure rules:OSHA tightening permissible exposure limits for respirable crystalline silica is accelerating demand for dust-collection attachments on abrasive pipe cutters in US construction.
- PEX residential repiping:Cross-linked polyethylene tubing replacement in aging US housing stock is pulling dedicated PEX cutter configurations into plumbing contractor tool belts.
- Battery-platform stickiness:Cordless ecosystem investments by commercial mechanical contractors are creating pull-through for compatible electric pipe cutter SKUs.
Market Restraints
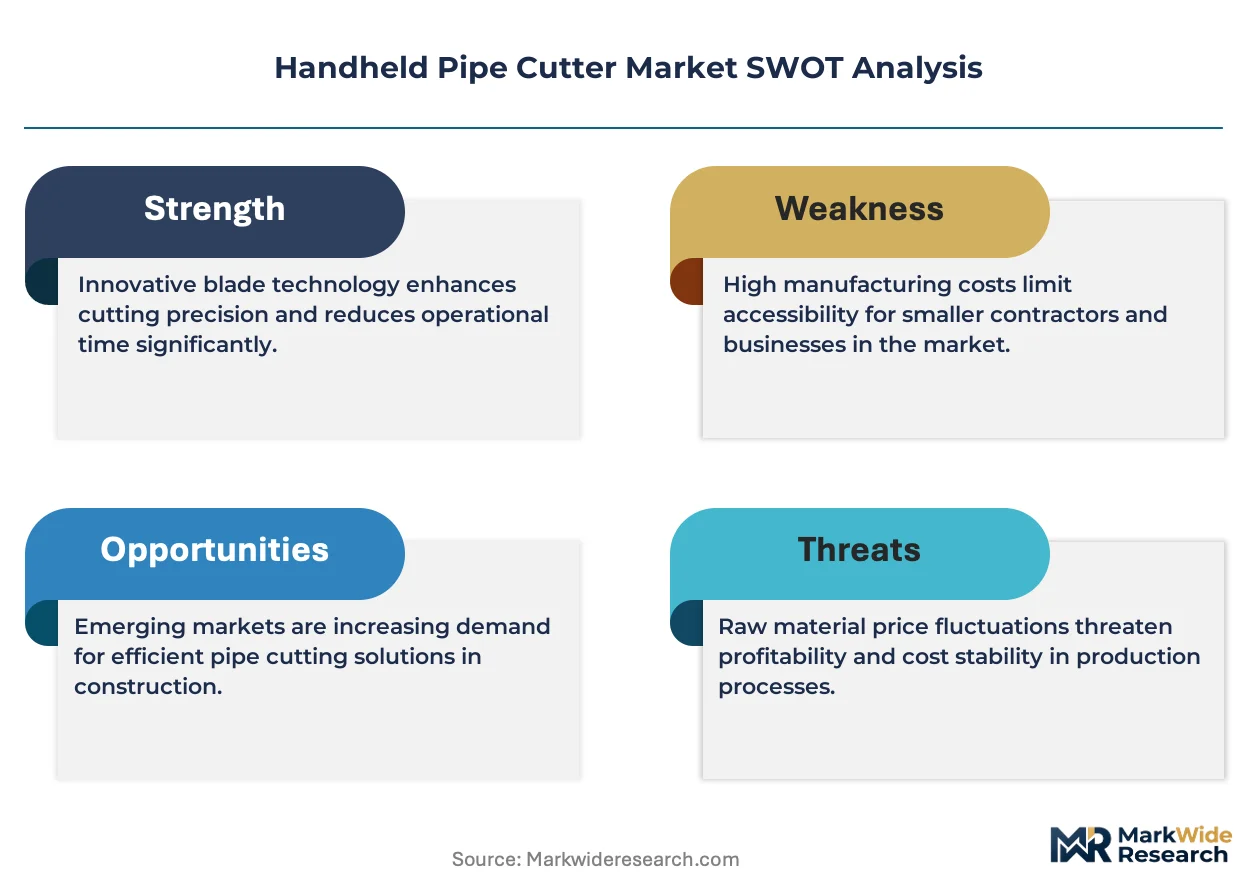
- High-speed steel input volatility:Tool steel price swings from European and Asian mill suppliers are compressing blade manufacturing margins without commensurate pricing power.
- Manual cutter durability:Zero-wear manual pipe cutter longevity limits replacement frequency, capping recurring revenue potential in mature copper and steel segments.
- Shop fabrication substitution:Fixed band saw and cold saw installations in mechanical contractor shops are absorbing volume from field-portable cutting for large-diameter runs.
Strategic Opportunities
- Agricultural irrigation PVC demand:Central Valley California and Arizona desert farming corridors are expanding PVC lateral installation, creating regional pull for large-capacity ratcheting cutters.
- ISO 11148 CE alignment:European conformity marking requirements for hand-held non-electric power tools create export certification services revenue for testing laboratories serving Asian manufacturers.
- Direct-to-contractor digital channels:Specialty tool e-commerce platforms are eroding traditional wholesale markups, enabling margin capture for brands with contractor database assets.
Industry Challenges
- Blade geometry talent scarcity:Cutting tool design expertise concentrated at legacy midwestern US manufacturers is retiring faster than apprenticeship pipelines replenish.
- Multi-certification timelines:Simultaneous OSHA, UL, and CE marking submissions for new electric cutter models extend time-to-revenue by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Handheld Pipe Cutter Market |
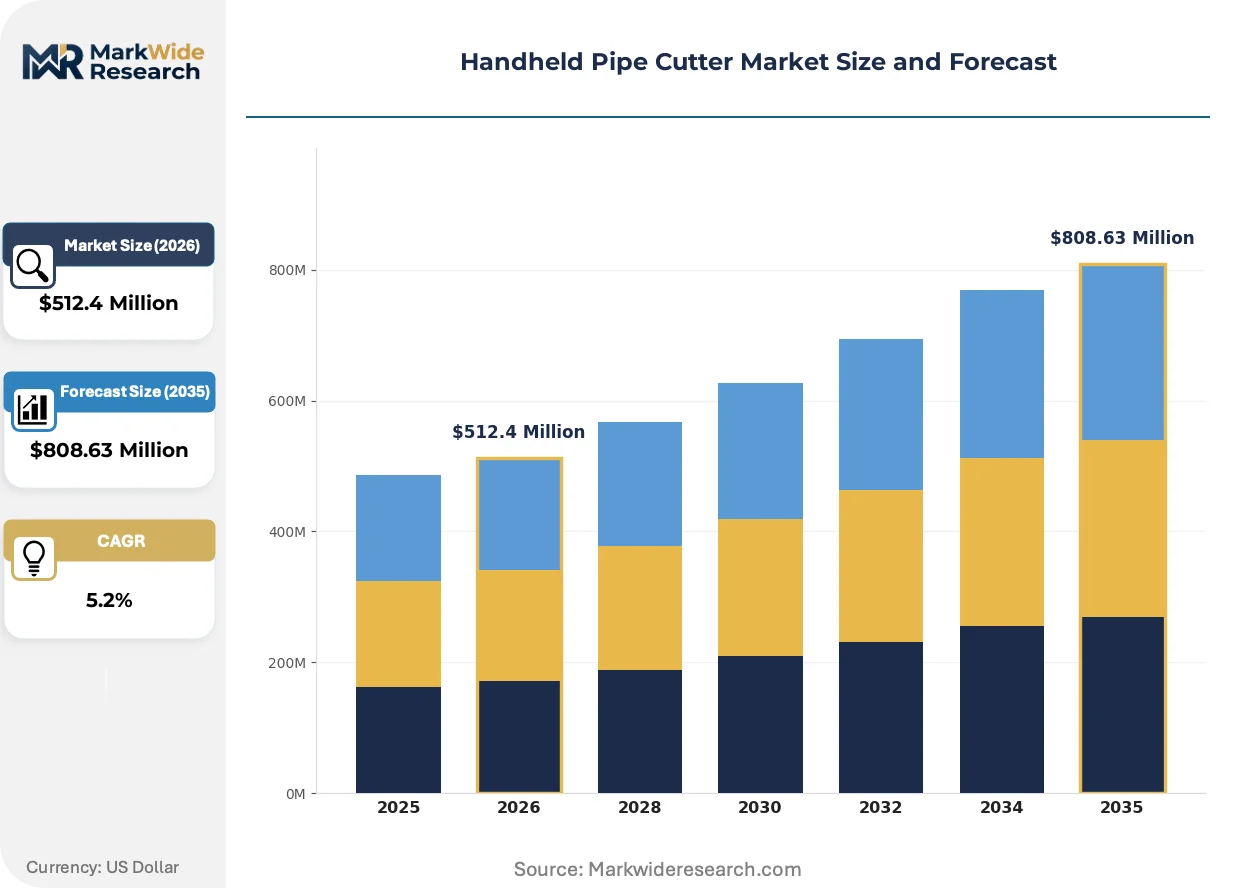
| Market Size in 2026 | $512.4 Million |
| Market Size in 2035 | $808.63 Million |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Pipe Cutter, Ratchet Pipe Cutter, Rotary Pipe Cutter, Spiral Pipe Cutter, Electric Pipe Cutter Material Compatibility: Copper, PVC, Steel, Aluminum, Cast Iron, PEX Application: Plumbing, HVAC Installation, Electrical Conduit, Industrial Maintenance, Agricultural Irrigation, Shipbuilding End User: Contractors, Maintenance Technicians, Fabricators, Utility Providers, Mechanical Engineers |
| Companies Covered | RIDGID, DeWalt, Milwaukee Tool, Klein Tools, Bahco, Rothenberger, Reed Manufacturing, Lenox Tools, Stanley Black & Decker, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Handheld Pipe Cutter Market Trends and Innovations
Tool connectivity and embedded sensing are rewiring how field crews interact with handheld cutting equipment, shifting value capture from hardware margins to data-enabled service layers.
Carbide-tipped scoring wheels are collapsing the performance gap between premium rotary cutters and economy stamped-steel alternatives. Commercial HVAC contractors in Texas and Florida Sun Belt corridors are specifying carbide-equipped models for stainless steel ductile iron cuts, compressing the addressable market for disposable-blade configurations. The technology is collapsing replacement parts revenue models as wheel longevity extends 3-4x over conventional hardened steel.
OSHA's ongoing blade guard standard revisions for portable power tools are forcing redesign cycles across electric pipe cutter portfolios. The 2024 proposed rulemaking on automatic brake engagement for cordless cutting tools is accelerating sensor integration investments. Battery-powered cutter SKUs targeting US commercial construction are absorbing the bulk of compliance engineering resources, delaying European market introductions.
Mechanical contractor procurement teams are consolidating vendor relationships around multi-trade tool platforms, bundling pipe cutters with press tools and drain cleaning equipment. Big-box construction supply chains are capturing this consolidation through exclusive house-brand electric cutter placements. The pattern is most pronounced in Sun Belt metropolitan markets where national mechanical contractors operate centralized fleet procurement functions.
Handheld Pipe Cutter Market Segmentation
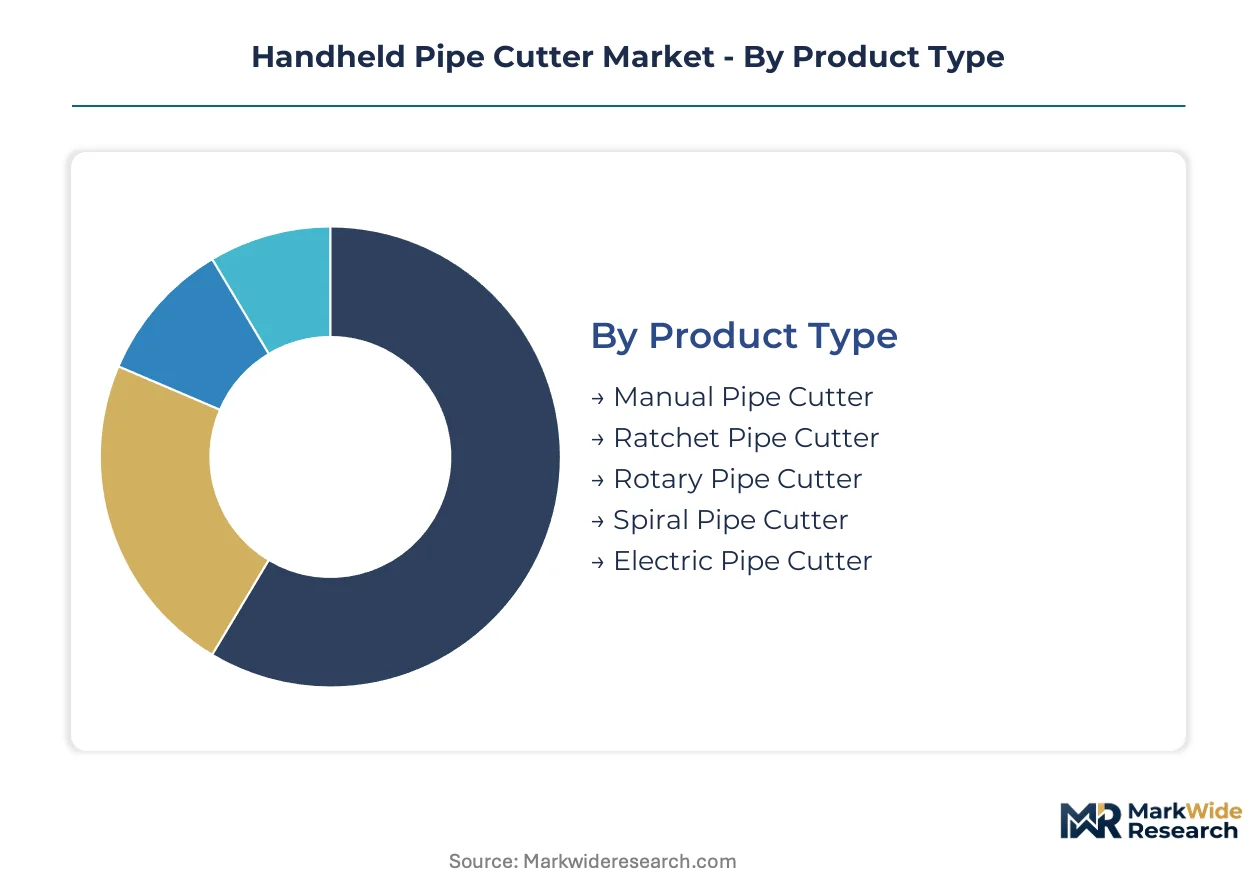
Segmentation in handheld pipe cutters reveals how blade geometry, power source, and material interface dictate replacement part economics and service attachment rates across contractor workflows. Distinct technical requirements in each slice reshape manufacturer R&D priorities and channel margin structures.
Product Type:
After-sales intensity varies sharply by cutter mechanism, with powered variants demanding firmware updates, battery replacement programs, and blade subscription services that manual tools cannot support.
- Manual Pipe Cutter:Zero-dependency shearing devices with hardened steel wheels and screw-feed mechanisms dominate residential plumbing tool belts. Sun Belt metropolitan repiping crews favor these for copper and steel work where power access is unreliable, though their indefinite lifespan caps recurring revenue for distributors.
- Electric Pipe Cutter:Cordless rotary and reciprocating configurations with brushless motors and lithium-ion packs command premium positioning in commercial HVAC installation. Texas and Florida mechanical contractors specify these for stainless steel ductile iron cuts where speed offsets acquisition cost, pulling through battery-platform ecosystem investments.
- Ratchet Pipe Cutter:Incremental jaw-closure mechanisms for tight-space cutting in industrial maintenance corridors.
- Rotary Pipe Cutter:Circumferential scoring wheels for clean cuts in electrical conduit and thin-wall tubing.
- Spiral Pipe Cutter:Continuous-feed abrasive chains for large-diameter cast iron and clay pipe in utility trenching.
Manual cutters hold the largest share; momentum sits with electric configurations as battery-platform stickiness deepens among commercial mechanical contractors.
Material Compatibility:
Blade metallurgy and wheel geometry requirements fragment the addressable market, with each material interface demanding distinct heat treatment and edge retention specifications.
- PEX:Low-friction blade coatings and compression-shear geometries accommodate cross-linked polyethylene's flexibility without crushing. California and Arizona residential repiping contractors are adding dedicated PEX cutters to standard tool inventories as aging copper infrastructure reaches replacement cycles.
- PVC:Ratcheting shear mechanisms with replaceable bypass blades serve agricultural irrigation lateral installation. Central Valley farming corridors are expanding PVC cutter demand as groundwater regulations accelerate pipeline modernization.
- Copper:Traditional scoring wheels for soft tubing in legacy plumbing maintenance.
- Steel:Heavy-duty rotary cutters with reinforced frames for mechanical contractor fabrication.
- Aluminum:Fine-tooth configurations for electrical conduit and lightweight ductwork.
- Cast Iron:Abrasive cutting chains and spiral mechanisms for sewer and drainage infrastructure.
Copper applications retain the largest installed base; PEX and PVC are climbing the fastest as polymer tubing displaces metal in residential and agricultural end-uses.
Application:
Worksite conditions and cut precision requirements segment the market by dust exposure, portability demands, and integration with adjacent tool systems.
- Plumbing:Compact manual and ratchet cutters for residential service calls and commercial rough-in work. OSHA silica-dust rules are accelerating dust-collection attachment adoption for abrasive cutting in occupied buildings.
- HVAC Installation:Electric rotary cutters with carbide-tipped wheels for stainless steel and ductile iron. Texas mechanical contractors specify these for speed-critical commercial projects where labor rates dominate total installed cost.
- Electrical Conduit:Precision scoring tools for thin-wall EMT and rigid conduit in commercial construction.
- Industrial Maintenance:Heavy-duty spiral and abrasive cutters for scheduled turnaround work in process facilities.
- Agricultural Irrigation:Large-capacity ratcheting cutters for PVC lateral and mainline installation in desert farming regions.
- Shipbuilding:Corrosion-resistant manual cutters for marine piping systems in coastal fabrication yards.
Plumbing commands the largest volume; HVAC installation is gaining share fastest as commercial mechanical contractors consolidate vendor relationships around multi-trade platforms.
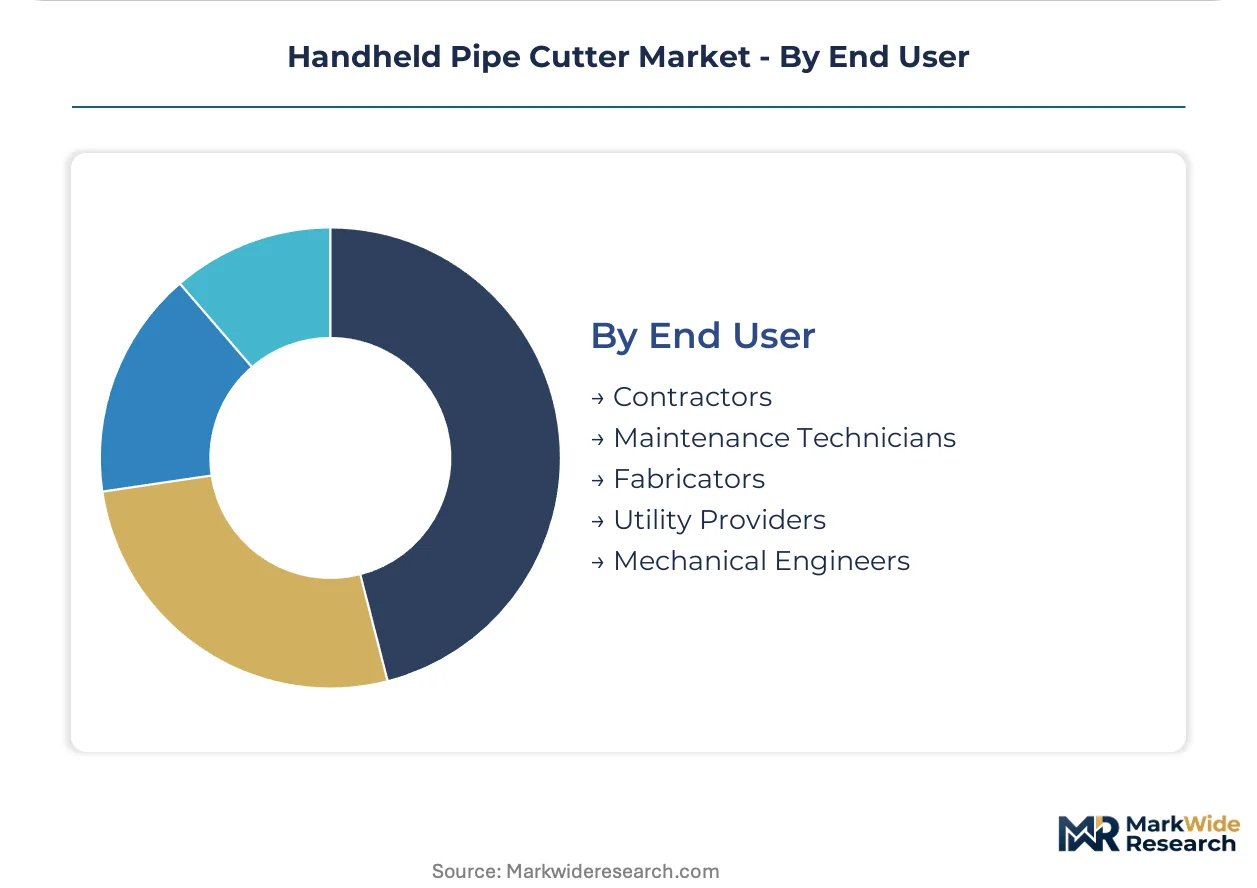
End User:
Procurement authority and fleet standardization patterns fragment the customer base between decentralized field purchase and centralized enterprise negotiation.
- Contractors:Plumbing and mechanical trade specialists with tool-belt purchase authority and brand loyalty to service-center networks. Sun Belt metropolitan markets show concentrated demand as national contractors operate centralized fleet procurement functions.
- Maintenance Technicians:Facility-based repair crews with standardized tool cribs and replacement part subscription programs.
- Fabricators:Shop-based metalworkers with fixed cutting equipment preferences that limit portable tool adoption.
- Utility Providers:Municipal and investor-owned water infrastructure crews with specification-driven procurement.
- Mechanical Engineers:Design-phase influencers who specify cutter compatibility in construction documentation.
Contractors represent the largest revenue pool; maintenance technicians are expanding most quickly as facility management outsourcing deepens tool standardization requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Houston Ship Channel anchors North American energy infrastructure throughput, while the Rhine-Main-Danube corridor stitches Central European industrial clusters into integrated supply networks. These waterways shape where pipe cutter inventories concentrate and how certification requirements propagate across contractor procurement offices.
United States
Sun Belt metropolitan construction corridors from Phoenix to Miami drive electric pipe cutter demand as mechanical contractors consolidate multi-trade fleet procurement. OSHA blade guard mandates for portable power tools are compressing product development cycles for cordless cutter SKUs. Dallas-Fort Worth and Houston anchor the largest contractor tool-belt markets, with centralized procurement functions at national mechanical firms standardizing battery-platform investments.
Germany
Industrial maintenance corridors along the Rhine-Ruhr and Stuttgart manufacturing belts sustain demand for precision rotary cutters in process facility turnaround work. CE marking requirements under EU machinery directives shape export compliance documentation for hand-held cutting tools. Bavaria's mechanical engineering clusters, particularly around Munich and Nuremberg, concentrate blade metallurgy R&D and heat-treatment expertise for premium cutter configurations.
China
Yangtze River Delta fabrication yards and Pearl River Delta export manufacturing sustain high-volume production of manual pipe cutter variants for global wholesale channels. GB standards for hand-held power tools and MIIT industrial safety regulations govern domestic certification requirements. Shenzhen and Dongguan tool clusters are absorbing ISO 11148 alignment investments to access European contractor markets through CE-marked product lines.
Japan
Kanto region commercial construction and Kansai shipbuilding yards maintain specialized demand for corrosion-resistant manual cutters in marine piping applications. METI industrial tool safety guidelines and JIS standards for portable cutting equipment shape domestic product specifications. Nagoya-area automotive supplier networks are standardizing pipe cutter compatibility with adjacent press-tool and fastening systems in multi-trade platforms.
India
Maharashtra and Gujarat industrial corridors are expanding PVC cutter demand as agricultural irrigation infrastructure modernizes under state groundwater regulation programs. BIS certification requirements for hand-operated cutting tools and state-level mechanical contractor licensing shape procurement specifications. Bangalore and Hyderabad construction markets are absorbing cordless electric cutter introductions as commercial building activity accelerates in southern metropolitan belts.
Handheld Pipe Cutter Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream on blade geometry and heat-treatment expertise. The vendor base organizes around battery-ecosystem anchoring, service-center network density, and carbide-tipping process control. Three archetypes dominate: multi-trade power tool platforms with battery stickiness, legacy Midwestern manufacturers with concentrated cutting-tool design talent, and Asian fabricators with scale-driven manual cutter production. Competitive moves center on cordless platform wars absorbing R&D resources and direct-to-contractor digital channels eroding traditional wholesale markups.
Among legacy American manufacturers, RIDGID and Reed Manufacturing occupy positions anchored by service-center network density and institutional plumbing fleet relationships. Milwaukee Tool exemplifies battery-platform stickiness, pulling electric pipe cutter SKUs through existing cordless ecosystem investments by commercial mechanical contractors. DeWalt anchors multi-trade retail presence in big-box construction supply chains, capturing contractor procurement consolidation through exclusive house-brand placements. These three represent distinct competitive vectors: service infrastructure, platform ecosystem, and retail channel control.
| Leading Market Players |
|---|
| RIDGID |
| DeWalt |
| Milwaukee Tool |
| Klein Tools |
| Bahco |
| Rothenberger |
| Reed Manufacturing |
| Lenox Tools |
| Stanley Black & Decker |
| Others |
Pricing and Supply Chain Analysis
Yangtze River Delta fabrication clusters anchor global manual pipe cutter capacity, with volume scale in Jiangsu and Zhejiang provinces translating directly into pricing leverage for economy-tier exports. Downward pressure on mid-range electric configurations intensifies as battery-platform wars compress margins for cordless SKUs competing on ecosystem stickiness rather than hardware differentiation.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates carbide-tipped rotary cutters with extended wheel life from disposable-blade manual variants and basic stamped-steel economy tools. Price differentiation hinges on certification grade—OSHA-compliant electric models with automatic brake engagement command substantial premiums over manual alternatives lacking UL or CE documentation. Cost compression in standard-tier electric cutters is intensifying because high-speed steel input volatility from European and Asian mill suppliers erodes blade manufacturing margins without commensurate pricing power. Residential plumbing contractors exhibit highest price sensitivity, prioritizing zero-dependency manual tools for copper work, while commercial HVAC mechanical contractors demonstrate lowest sensitivity as labor rates dominate total installed cost calculations.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk calculations for manual pipe cutter imports, with Section 301 duties disrupting traditional wholesale cost structures. Manufacturing concentrates in China, Germany, and the United States—Yangtze Delta clusters feed global wholesale channels with high-volume manual variants, Bavarian engineering belts supply precision rotary cutters for European process maintenance, and Midwestern US facilities retain carbide-tipping expertise for premium commercial grades. Raw material dependencies center on high-speed tool steel from European mills, lithium-ion battery cells from South Korean suppliers, and tungsten carbide feedstock for scoring wheel production. Single-source vulnerability in carbide sintering capacity creates chokepoints for premium cutter configurations. Distribution runs through big-box construction supply chains capturing procurement consolidation, direct-to-contractor digital platforms eroding traditional wholesale markups, and institutional service-center networks sustaining fleet loyalty.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Handheld pipe cutter demand tracks construction cycle recovery, with Sun Belt metropolitan building permits serving as the lead indicator for contractor tool-belt replenishment.
For Market Incumbents: Entrench battery-platform ecosystem investments by accelerating firmware-enabled service attachment rates and expanding certified repair network density. Defend against direct-to-contractor digital disintermediation by capturing contractor database assets through loyalty programs tied to blade subscription services. Prioritize backward integration into carbide-tipping process control to secure scoring wheel supply against single-source chokepoints. For New Entrants and Emerging Players: Build out agricultural irrigation-focused PVC cutter portfolios targeting Central Valley California and Arizona desert farming corridors where groundwater regulations accelerate pipeline modernization. Penetrate the maintenance technician segment through facility management outsourcing channels by offering standardized tool crib programs with replacement part subscription models. Lead with direct-to-contractor e-commerce platforms that bypass traditional wholesale markups and capture margin through contractor database assets. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors blade geometry specialists with concentrated heat-treatment expertise and captive carbide-tipping capabilities over pure-play battery-platform assemblers. Long-term viability across the projection horizon rests on manufacturers controlling scoring wheel metallurgy and firmware-enabled service layers rather than hardware margins alone. Target acquisition archetypes include legacy Midwestern manufacturers with retiring design talent pipelines and Asian fabricators pursuing ISO 11148 CE alignment for European market access. Monitor OSHA blade guard standard finalization as the signal for compliance engineering resource reallocation and product portfolio rationalization.| Strategic Initiative | Industry Significance |
|---|---|
| Carbide-Tipping Process Integration | Captive scoring wheel production secures 3-4x longevity premiums against disposable-blade alternatives. |
| Direct-to-Contractor Digital Platform Launch | E-commerce channels bypass wholesale markups and capture contractor database assets for subscription revenue. |
| Battery-Platform Ecosystem Expansion | Cordless stickiness deepens among commercial mechanical contractors consolidating multi-trade vendor relationships. |
| ISO 11148 CE Alignment Investment | European conformity marking opens export certification services revenue for Asian manufacturer testing. |
| Dust-Collection Attachment Development | OSHA silica-dust exposure rule compliance creates pull-through for abrasive cutter accessories in occupied buildings. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of trade customs data, SEC filings from listed tool manufacturers, OSHA regulatory dockets, and ISO standard documentation. Primary interviews engaged plumbing contractor fleet managers, mechanical HVAC procurement directors, big-box construction supply category buyers, aftermarket service-center operators, and blade metallurgy R&D leads. Secondary validation drew from distributor inventory reports, contractor association membership databases, and machinery directive compliance registries. Bottom-up segmentation modeling triangulated against top-down construction spending forecasts.
Forecast inputs incorporate product type evolution across manual, electric, ratchet, and rotary configurations; material compatibility shifts between copper, PEX, PVC, and steel applications; and end-user procurement patterns distinguishing decentralized field purchase from centralized enterprise negotiation. Modeled dimensions span power source dependency, blade geometry requirements, and regional certification clusters. CAGRs derive from installed base replacement cycles, new construction permit trajectories, and polymer tubing displacement rates in residential repiping. Industry-specific inputs include Sun Belt metropolitan building activity indices and agricultural irrigation infrastructure investment programs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by battery-platform integrators or direct-to-contractor digital entrants would shift outcomes beyond modeled parameters. Macroeconomic construction cycle deviation, OSHA blade guard standard acceleration, or carbide supply disruption would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Global Electric Portable Drill Market
Tools
Tile Cutter Market
Tools
Blowing Torch Market
Tools
Drywall Tool Market
Tools
Global Flange Fasteners Market
Tools
Gas Cutting Machine Market
Tools
L Allen Wrench Market
Tools
United States Machine Tools Market
Tools
Forging Press Market
Tools
Core Shooter Machine Market
Tools
Global Vertical Grinding Machine Market
Tools
Impact Wrenches Market
Tools
Global Cordless Power Tools Market
Tools
Tool Pliers Market
Tools
End Milling Machine Market
Tools
Bar Clamp Market