
 Portable Rolling Toolbox Market | 2026-2036
Portable Rolling Toolbox Market Size, Share, and Industry Trends Forecast 2026-2036
Portable Rolling Toolbox Market Analytics
Professional contractors is reorganizing demand patterns within the portable rolling toolbox category, displacing traditional DIY purchasers as the dominant buyer archetype. Milwaukee Tool leverages its battery ecosystem to anchor premium modular system offerings that integrate with power tool platforms. DeWalt sustains manufacturing scale across multiple material grades, while Stanley Black & Decker competes through broad channel control in home improvement retail.
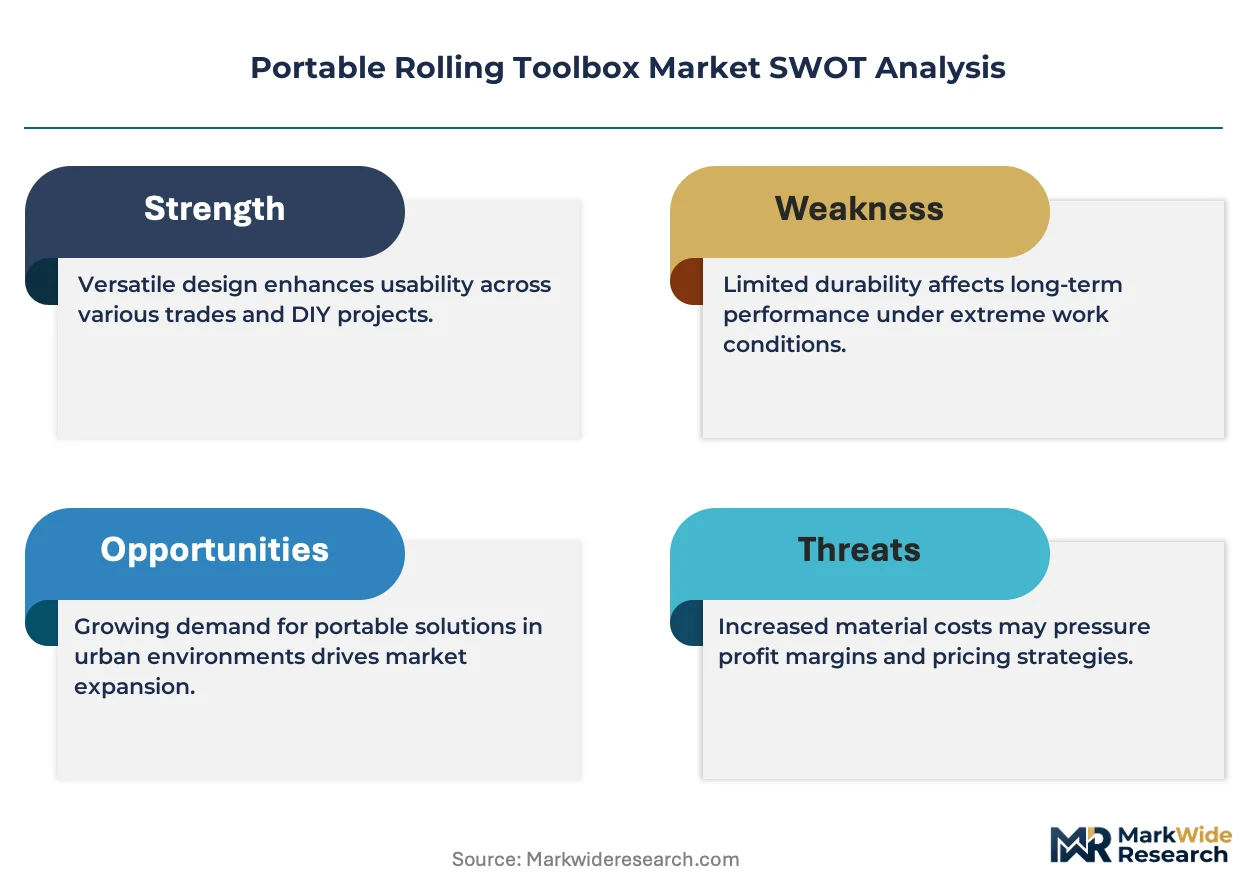
A portable rolling toolbox is a wheeled storage unit incorporating casters, telescoping handles, and compartmentalized interiors, typically fabricated from steel, plastic, or aluminum to protect hand tools and power equipment during transport and field use. These units serve commercial trades by reducing load strain and improving tool accessibility across dispersed work locations. Modular system configurations command margin concentration due to attachment compatibility and upgrade pathways, while steel-constructed job site boxes dominate replacement cycles in construction use cases where impact resistance determines product lifespan. Plastic variants are gaining fastest among home improvement users seeking lighter transport weights for residential applications.
OSHA workplace ergonomics standards and ANSI load rating certifications shape product design requirements, compelling manufacturers to validate caster durability and handle stress thresholds. The EPA oversees recycled content claims in composite material sourcing, affecting supplier qualification for environmentally positioned product lines. Stakeholders must monitor evolving trade professional purchasing consolidation through distributor partnerships and direct-to-contractor digital platforms.
Market Dynamics
Professional contractor purchasing consolidation is restructuring portable rolling toolbox demand, as trade professionals prioritize fleet-standardized modular systems over fragmented DIY-grade purchases. This shift compresses replacement cycles toward premium configurations while marginalizing non-integrated suppliers.
Growth Catalysts
- OSHA Ergonomic Mandates:Workplace material handling safety standards in the United States compel construction firms to replace fixed storage with wheeled configurations that reduce musculoskeletal injury risk.
- Battery Platform Convergence:Power tool ecosystem integration is anchoring rolling toolbox purchases, as contractors standardize on modular storage compatible with cordless charging systems.
- Residential Construction Velocity:Elevated single-family housing starts in the United States sustain replacement demand for job site mobility equipment among framing and finishing crews.
Market Restraints
- Steel Price Volatility:Cold-rolled steel input costs fluctuate with scrap metal and energy pricing, compressing margins on impact-resistant job site box variants.
- Asian Manufacturing Concentration:Caster and telescoping handle component sourcing clusters in China create supply vulnerability during logistics disruptions or tariff adjustments.
- Plastic Durability Ceiling:Polypropylene structural limits prevent penetration into heavy-duty commercial applications where load ratings exceed residential-grade specifications.
Strategic Opportunities
- Direct-to-Contractor Platforms:Digital procurement channels bypass traditional distributor markups, capturing margin from trade professionals managing multi-crew equipment fleets.
- EPA Recycled Content Positioning:Composite material sourcing with validated post-consumer plastic content qualifies suppliers for federal procurement preferences and sustainability-specified projects.
- ANSI Load Rating Certification:Third-party validated stress thresholds differentiate premium offerings in commercial segments where insurance and liability standards apply.
Industry Challenges
- Welding and Fabrication Skill Scarcity:Steel chassis production requires certified metalworkers, constraining domestic capacity expansion for impact-resistant product lines.
- Modular Patent Thickets:Attachment interface intellectual property held by power tool manufacturers creates licensing barriers for independent storage suppliers seeking ecosystem compatibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Portable Rolling Toolbox Market |
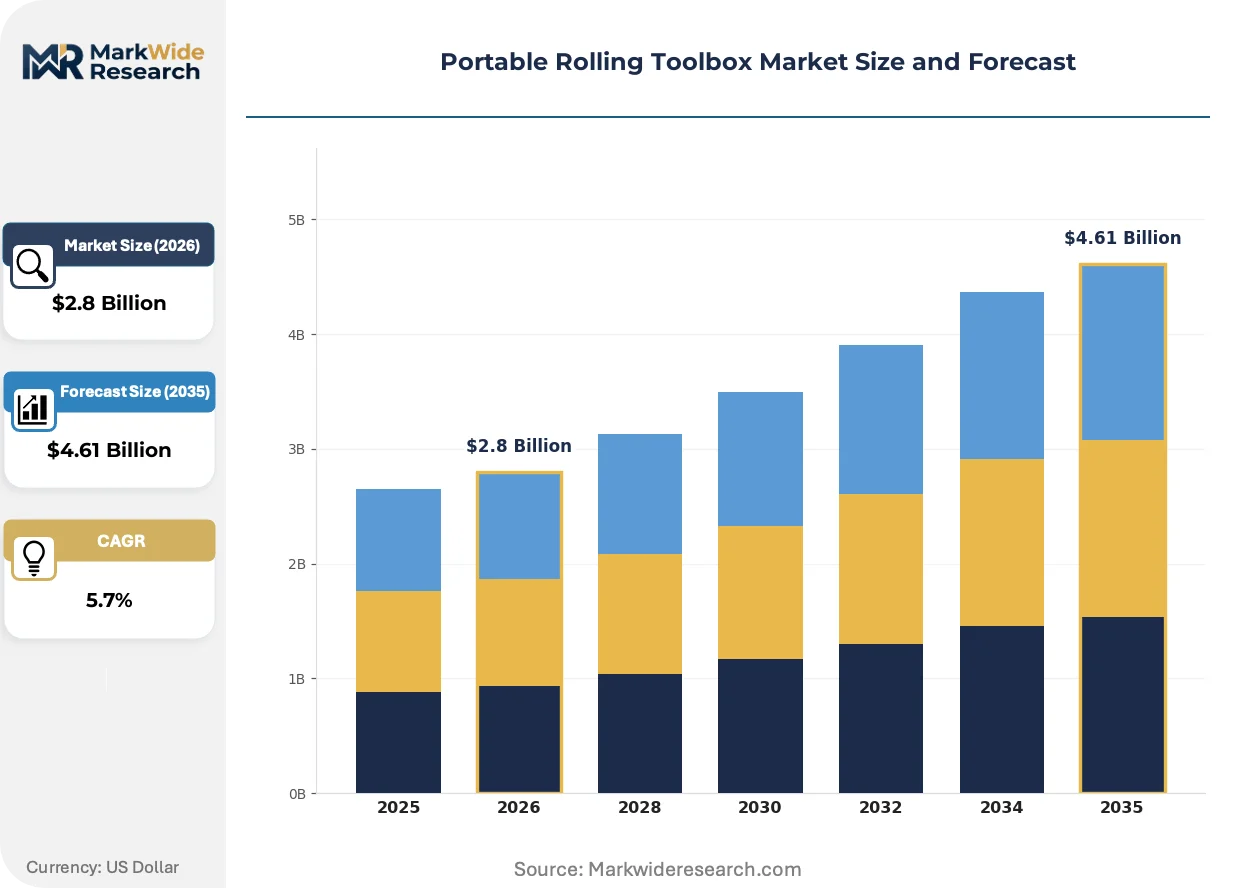
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.61 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Toolbox, Modular System, Tool Chest, Job Site Box Use Case: Home Improvement, Construction, Auto Repair, Gardening Material: Steel, Plastic, Aluminum, Composite Size: Small, Medium, Large, Extra Large |
| Companies Covered | DeWalt, Milwaukee Tool, Stanley Black & Decker, Craftsman, Ridgid, Flex, Klein Tools, Makita, Husky, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Portable Rolling Toolbox Market Evolving Landscape
Tool storage architecture is converging with power platform ecosystems, transforming standalone boxes into integrated system nodes. This reconfiguration privileges suppliers with captive battery technology while isolating pure-play storage manufacturers.
Aluminum honeycomb core construction is supplanting solid steel walls in mid-duty rolling toolboxes. The material delivers comparable impact resistance at 40 percent weight reduction. Commercial electricians and HVAC technicians are migrating fastest, as reduced transport strain improves job site mobility. This shift is compressing demand for conventional steel fabrication among regional manufacturers lacking aluminum forming capabilities.
OSHA workplace ergonomics guidelines are mandating validated caster performance and handle stress documentation. Manufacturers must submit third-party testing for load rating certification. Construction contractors in California and Texas face the strictest enforcement, driving specification upgrades on new equipment purchases.
Buying patterns among trade professionals are fragmenting across channel types. Independent distributors retain loyalty among older contractor demographics, while digital-native crews source through manufacturer-direct platforms. The United States exhibits the sharpest channel bifurcation, with regional hardware cooperatives losing share to integrated e-commerce fulfillment.
Portable Rolling Toolbox Market Segmentation
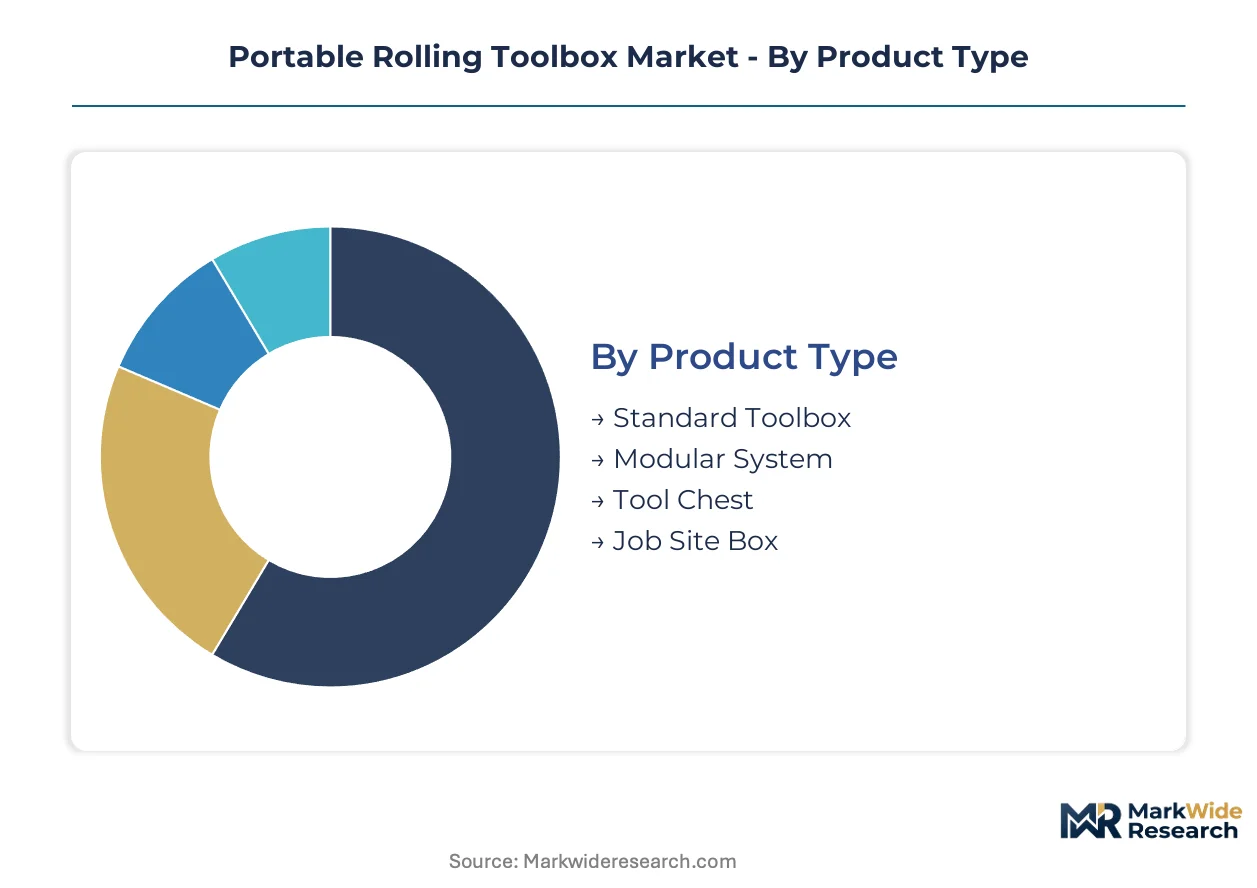
Portable rolling toolbox segmentation reveals divergent substitution pressures across material grades and configuration types. Professional contractors and trade specialists prioritize distinct performance attributes, fragmenting demand across durability tiers and mobility specifications.
Product Type:
Modular system configurations face the strongest substitution threat from integrated power tool platform ecosystems, while standalone categories compete on price and durability alone.
- Standard Toolbox:Basic wheeled units with fixed compartment layouts and telescoping handles serve residential DIY users and light commercial applications. Demand concentrates in United States home improvement retail channels where price sensitivity dominates purchasing decisions and replacement cycles extend beyond professional-grade equipment.
- Modular System:Interconnecting storage units with standardized attachment interfaces enable battery platform integration and upgrade pathways. Construction contractors in Texas and California drive specification upgrades as fleet standardization reduces cross-compatibility failures and improves job site logistics coordination.
- Tool Chest:Vertical stacking configurations with drawer-based organization serve stationary workshop environments requiring dense tool storage capacity.
- Job Site Box:Reinforced steel enclosures with weather sealing and security features protect equipment in exposed construction environments.
Standard toolbox configurations anchor the volume base while modular system offerings gain share at the steepest rate.
Use Case:
Construction applications command premium pricing tiers while residential use cases drive volume scale through retail distribution.
- Construction:Heavy-duty rolling storage withstands daily transport across dispersed job sites, impact loading, and environmental exposure. Framing and finishing crews in high-velocity United States housing markets sustain replacement demand as OSHA ergonomic mandates accelerate fleet upgrades.
- Home Improvement:Lightweight plastic and aluminum variants reduce transport strain for residential property maintenance tasks. DIY purchasers in suburban United States markets prioritize weight reduction and retail availability over impact resistance specifications.
- Auto Repair:Mechanic-grade configurations emphasize oil resistance, drawer precision, and compact footprints for shop bay mobility.
- Gardening:Weather-resistant storage protects hand tools and small power equipment during seasonal landscaping operations.
Construction use cases generate the highest per-unit margins while home improvement applications expand the addressable customer base most broadly.
Material:
Steel fabrication costs determine competitive positioning while alternative materials capture share through weight and corrosion advantages.
- Steel:Cold-rolled and powder-coated chassis deliver maximum impact resistance for commercial job site applications. Construction contractors specify steel variants for load ratings exceeding residential-grade requirements, though scrap metal price volatility compresses manufacturer margins.
- Plastic:Polypropylene and high-density polyethylene formulations reduce unit weight by half versus steel equivalents. Electricians and HVAC technicians in United States metropolitan markets adopt plastic variants fastest as reduced transport strain improves daily mobility.
- Aluminum:Honeycomb core construction delivers comparable impact resistance at substantial weight reduction for mid-duty commercial segments.
- Composite:Reinforced polymer blends incorporating post-consumer recycled content qualify for federal procurement preferences and sustainability-specified projects.
Steel construction retains the largest installed base while aluminum honeycomb configurations climb the fastest among trade professional segments.
Size:
Medium and large formats dominate commercial procurement while small variants serve specialized trade applications.
- Small:Compact rolling units accommodate specialized tool sets for electricians, plumbers, and technicians requiring narrow access corridors. Commercial service contractors in dense United States urban environments prioritize maneuverability over storage capacity.
- Medium:Balanced configurations serve generalist trade professionals with diverse tool inventories. Regional construction fleets standardize on medium formats to optimize vehicle loading efficiency and cross-crew compatibility.
- Large:Extended capacity units support framing crews and renovation specialists with bulky power tool requirements.
- Extra Large:Maximum-volume configurations serve stationary workshop installations and specialized industrial maintenance applications.
Medium size formats anchor commercial procurement volumes while small configurations expand fastest among specialized service trades.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Professional contractors dominate procurement across all major markets, with demand intensity tracking residential construction velocity and trade professional density. Regional variations reflect differing enforcement of workplace ergonomics standards and construction sector fragmentation.
United States
Framing and finishing crews drive replacement cycles as OSHA ergonomic mandates accelerate fleet upgrades from fixed storage to wheeled configurations. The EPA oversees recycled content claims in composite material sourcing, affecting supplier qualification for federal procurement. Houston and Dallas construction markets exhibit the steepest specification upgrades as Texas contractors standardize on modular system configurations.
Germany
Commercial trades prioritize aluminum honeycomb core constructions for weight reduction during daily transport across dispersed job sites. REACH chemical safety standards and CE marking requirements shape material validation for imported components. The Bavaria industrial corridor anchors domestic fabrication capacity for mid-duty commercial segments serving electrician and HVAC technician demand.
China
Component manufacturing clusters around caster and telescoping handle production for export markets, with MIIT industrial standards governing domestic product safety. GB standards for material handling equipment create compliance thresholds for manufacturers serving professional contractor segments. The Yangtze River Delta concentration of metal fabrication facilities supplies cold-rolled steel chassis to North American and European OEMs.
Japan
Compact rolling configurations gain traction among service technicians navigating dense urban corridors and narrow access environments. METI industrial policy supports lightweight material innovation through JIS standards certification programs. The Nagoya-Chubu manufacturing belt retains specialized aluminum forming capabilities for honeycomb core production serving regional trade professionals.
Australia
Mining maintenance crews and commercial construction fleets sustain demand for impact-resistant steel variants in exposed environmental conditions. The TGA does not directly regulate tool storage, though state-level workplace safety authorities enforce manual handling standards. Western Australia mining camps drive specification for weather-sealed job site boxes with security features protecting equipment in remote locations.
Portable Rolling Toolbox Market Competitive Landscape
Player mix skews toward diversified power tool manufacturers with captive storage portfolios rather than pure-play fabricators. The vendor base organizes around three strategic tiers: integrated power platform operators commanding premium positioning through battery ecosystem lock-in, broad-line manufacturers competing on channel density and retail footprint, and specialized metal fabricators serving regional contractor markets. Dominant competitive moves include modular patent portfolio expansion and direct-to-contractor digital platform development.
Within the integrated power platform tier, Milwaukee Tool and DeWalt exemplify archetypes leveraging battery ecosystem convergence to anchor rolling toolbox purchases. Stanley Black & Decker occupies a position spanning multiple competitive vectors through brand portfolio breadth. Klein Tools represents the specialized trade-focused archetype, with electrician-centric positioning distinguishing its market approach from generalist manufacturers.
| Leading Market Players |
|---|
| DeWalt |
| Milwaukee Tool |
| Stanley Black & Decker |
| Craftsman |
| Ridgid |
| Flex |
| Klein Tools |
| Makita |
| Husky |
| Others |
Value Network & Pricing Analysis
Capacity utilization at Yangtze River Delta steel fabrication facilities anchors cost structures across the portable rolling toolbox category, concentrating supply-side leverage among integrated power tool manufacturers while compressing margin floors for regional metalworkers lacking backward integration into cold-rolled steel sourcing.
Pricing Analysis
Cost-plus contracts with quarterly scrap metal indexation dominate procurement between OEMs and steel chassis suppliers. Three-tier pricing structure across premium modular systems, standard welded boxes, and economy plastic variants separates battery ecosystem integration from commodity-grade alternatives. Pricing pressure stems from polypropylene feedstock volatility affecting lightweight residential segments. DIY purchasers in United States home improvement channels exhibit highest price sensitivity, while fleet-standardized construction contractors prioritize ANSI certification tiers over unit cost.
Supply Chain Analysis
Ningbo-Zhoushan port congestion functions as the primary chokepoint for caster and telescoping handle component flows to North American assembly plants. Manufacturing gravity centers on China for stamped steel components, Vietnam for aluminum honeycomb forming, and Taiwan for precision caster bearings. Raw material dependencies include cold-rolled steel coils, high-density polyethylene resin, and zinc-alloy die-cast hardware. Single-source vulnerability concentrates in proprietary modular attachment interfaces patented by integrated power tool manufacturers. Distribution runs through home improvement retail cooperatives, independent distributor networks, and manufacturer-direct e-commerce platforms serving multi-crew contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Portable rolling toolbox market fragmentation creates white-space opportunities as contractor purchasing consolidates around fleet-standardized modular systems while marginalizing non-integrated suppliers serving fragmented DIY demand.
For Market Incumbents: Shield premium positioning by deepening captive battery ecosystem lock-in through expanded modular patent portfolios. Acquire regional aluminum honeycomb forming capabilities to defend against weight-reduction substitution. Channel control through direct-to-contractor digital platforms represents the critical defensive lever against distributor disintermediation.
For New Entrants and Emerging Players: ANSI load rating certification fast-track opens commercial construction segments where insurance and liability standards create specification barriers. Target electrician and HVAC technician segments in dense United States metropolitan markets adopting lightweight plastic variants fastest. Pursue EPA recycled content validation to qualify for federal procurement preferences and sustainability-specified infrastructure projects.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among modular system suppliers with attachment interface intellectual property generating upgrade pathway annuity streams. Long-term viability favors vertically integrated manufacturers with captive aluminum forming capabilities and direct contractor platform reach. Monitor OSHA ergonomic enforcement intensity in California and Texas as the signal indicating specification upgrade velocity and replacement cycle compression.
| Strategic Initiative | Industry Significance |
|---|---|
| Modular Patent Portfolio Expansion | Attachment interface IP creates ecosystem lock-in that anchors contractor fleet standardization decisions. |
| Direct-to-Contractor Platform Launch | Digital procurement bypasses distributor markups while capturing multi-crew equipment fleet management demand. |
| Aluminum Honeycomb Capacity Addition | Lightweight forming capabilities address electrician and HVAC technician weight-reduction preferences in metropolitan markets. |
| ANSI Certification Investment | Third-party load rating validation differentiates offerings where construction insurance standards apply. |
| EPA Recycled Content Qualification | Post-consumer plastic sourcing validates federal procurement preferences for sustainability-specified projects. |
Research Methodology
The analysis maps modular system configurations, standalone toolboxes, and job site box variants, each validated through primary interviews with construction fleet managers, independent distributor owners, home improvement retail category buyers, and aluminum fabrication plant engineers. Secondary sources include OSHA enforcement records, EPA recycled content certifications, customs import data for caster components, and SEC filings from diversified tool manufacturers. Bottom-up unit economics triangulate against top-down construction spending elasticity models.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include material grade, configuration type, use case intensity, and regional regulatory enforcement cluster. CAGRs derive from replacement cycle analysis, fleet standardization penetration curves, and ergonomic mandate compliance timelines. Industry-specific inputs incorporate single-family housing start velocity and scrap metal price covariance with steel chassis production costs.
Decision-makers should treat outputs as directional under sustained residential construction activity and stable OSHA enforcement intensity assumptions; material deviation would warrant model refresh. Forecasts reflect documented base conditions including aluminum forming capacity expansion and modular patent licensing availability. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Chainsaw Market
Tools
Metal Cutting Machine Market
Tools
US Power Tools Market
Tools
3D Milling Machines Market
Tools
Global Table Saws Market
Tools
Vise-Grip Pliers Market
Tools
Spindle Shaper Market
Tools
Workholding Tools Market
Tools
Screw Fastener Market
Tools
US Chalk Reel and Line Market
Tools
Aluminum Folding Ladders Market
Tools
Sander Market
Tools
Global Diamond Tools Market
Tools
Post Drivers Market
Tools
Spray Painting Machine Market
Tools
Telescopic Tool Boxes Market