
 L Allen Wrench Market | 2026-2036
L Allen Wrench Market Size, Share, and Industry Trends Forecast 2026-2036
L Allen Wrench Market Insights
Skilled maintenance technician shortages across industrial fabricators is reorganizing procurement priorities toward durable, multi-format tool kits. Bondhus Corporation leverages captive alloy steel forging to sustain margin control in premium ball end segments. Stanley Black & Decker competes through retail channel density and private-label scale in North American home improvement chains. Wiha Tools differentiates via precision-grade German manufacturing that commands professional mechanic loyalty in aviation and medical device sectors.
An L Allen wrench is a hexagonal key tool manufactured through cold forging or CNC machining from alloy steels with hardness ratings typically between HRC 52 and HRC 60, designed to drive socket head cap screws in confined spaces where conventional drivers cannot access. Ball end variants permit angled insertion up to 25 degrees, enabling faster assembly in automotive and electronics applications where straight-line access is obstructed. Chrome vanadium steel dominates material selection for professional users due to tensile strength and corrosion resistance, while carbon steel anchors economy-tier sales in furniture assembly and DIY channels. T-handle configurations lead industrial fabricator demand for high-torque applications, whereas folding Allen wrench sets occupy the portable maintenance segment favored by bicycle mechanics and field service technicians.
FDA device manufacturing guidelines and FAA maintenance protocols in the United States, plus REACH substance restrictions and CE marking requirements in Europe, mandate traceable alloy composition and dimensional tolerance documentation for tools used in regulated assembly environments. Japan's METI industrial standards and JIS specifications further constrain import eligibility for non-certified manufacturers seeking precision engineering contracts. Stakeholders must monitor evolving dual carbon goals in China and extended producer responsibility frameworks in the European Union, as these will reshape material sourcing compliance costs and regional competitive access without warning.
Market Dynamics
ISO 4762 and DIN 912 fastener tolerance tightening is forcing precision engineering workshops to replace worn hex keys at shorter intervals, compressing replacement cycles while elevating material specification requirements across maintenance procurement.
Growth Catalysts
- FAA maintenance protocols:Aviation MRO facilities in the United States must maintain traceable tool certification for airframe fastener work, driving systematic replacement of non-compliant inventory.
- Chrome vanadium steel:Tensile strength advantages in high-torque automotive assembly applications anchor professional-grade demand in Germany and Japan.
- Ball end geometry:25-degree angled insertion capability accelerates electronics and automotive line assembly where straight-line access is obstructed.
Market Restraints
- Alloy steel price volatility:Chrome vanadium input costs fluctuate with ferrovanadium spot markets, squeezing margin on mid-tier forged products.
- REACH substance documentation:ECHA compliance requirements for traceable alloy composition impose administrative burden on small-batch European importers.
- Power tool substitution:Cordless impact drivers with hex bit compatibility encroach on high-volume assembly applications previously served by manual wrenches.
Strategic Opportunities
- India PLI scheme:Production-linked incentives for precision manufacturing equipment create localized assembly opportunities for export-grade tool kits.
- Medical device assembly:FDA-validated sterile manufacturing environments require dedicated tool sets with lot traceability, opening premium certification tiers.
- E-commerce direct channels:Professional mechanic forums and specialized industrial marketplaces bypass traditional distribution markups for brand-direct procurement.
Industry Challenges
- Heat treatment certification:HRC 52-60 hardness validation requires capital-intensive metallurgical testing equipment that smaller forges struggle to maintain.
- Multi-standard compliance:Simultaneous ISO, JIS, and DIN dimensional tolerance adherence complicates single-SKU global distribution strategies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | L Allen Wrench Market |
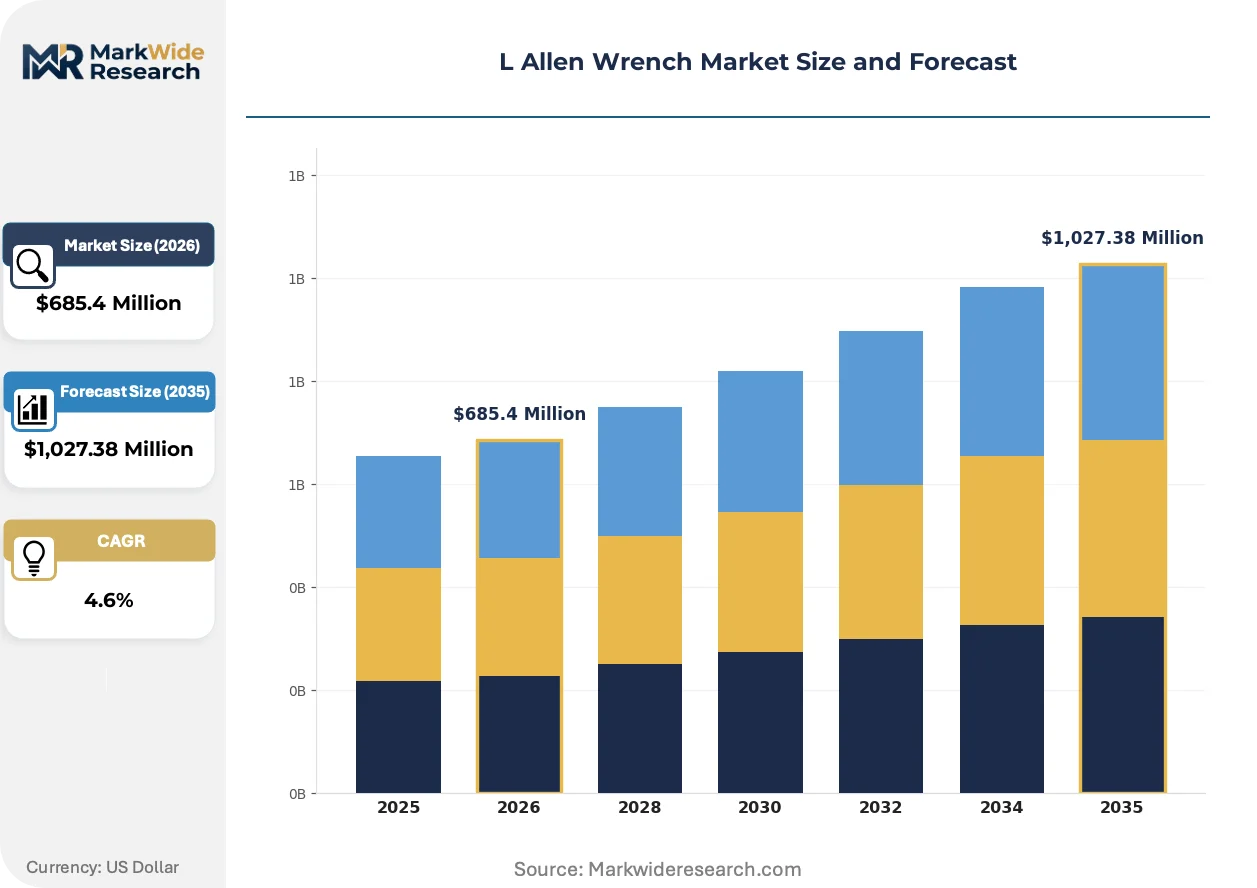
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,027.38 Million |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Allen Wrench, Ball End Allen Wrench, Folding Allen Wrench, T-Handle Allen Wrench, Telescoping Allen Wrench Material: Carbon Steel, Chrome Vanadium Steel, Stainless Steel, Alloy Steel, Titanium Application: Furniture Assembly, Electronics Repair, Bicycle Maintenance, Precision Engineering, DIY Projects End User: Home Users, Professional Mechanics, Maintenance Technicians, Industrial Fabricators, Hobbyists |
| Companies Covered | Apex Tool Group, Stanley Black & Decker, Bondhus Corporation, Wera Tools, Wiha Tools, Klein Tools, TEKTON, Armstrong Tools, GEDORE Tool Center, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
L Allen Wrench Market Trends and Innovations
Material science advances and regulatory documentation requirements are restructuring competitive advantage around certified metallurgical provenance rather than geometry alone. Tool manufacturers must now embed compliance data directly into product traceability systems.
Carbide-tipped ball end variants is supplanting conventional hardened steel in high-cycle industrial environments. Automotive transmission assembly plants in Stuttgart and Nagoya have adopted these inserts for 50,000+ fastener engagement durability. The technology is compressing replacement frequency and shifting procurement evaluation toward total cost-per-fastener metrics rather than unit price.
EU extended producer responsibility frameworks are mandating alloy recovery documentation and end-of-life recycling accountability for hand tools sold in member states. Manufacturers must now register material flows with national waste registries and finance collection infrastructure. Professional-grade suppliers with captive forging operations absorb these costs more readily than import-dependent distributors.
Maintenance departments at German automotive OEMs now specify supplier-managed inventory programs with consignment stocking and usage-based billing. Industrial distributors with VMI capability displace traditional wholesale relationships in high-volume MRO procurement. This pattern is visible across Bavarian and Baden-Württemberg manufacturing clusters where just-in-time tool availability carries line-down cost implications.
L Allen Wrench Market Segmentation
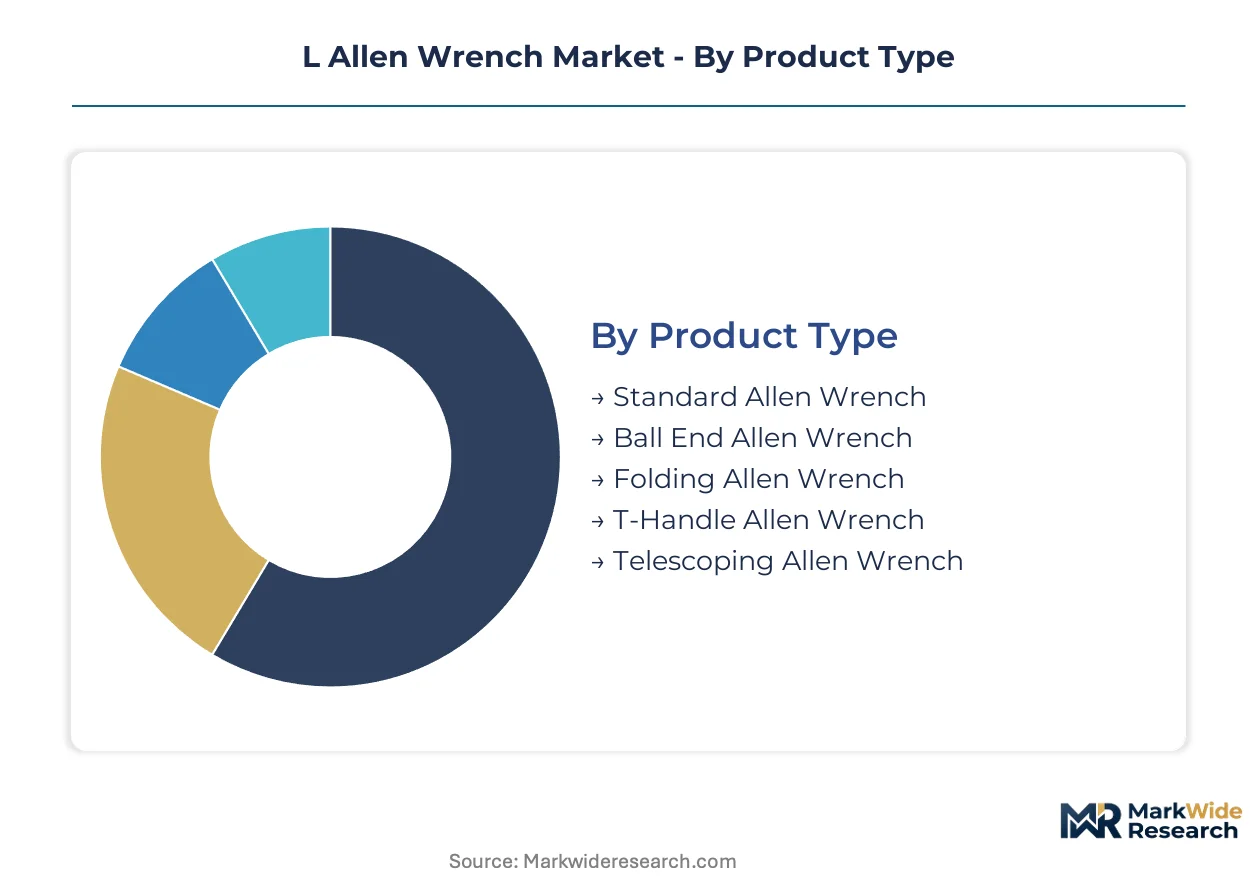
L Allen wrench procurement channels diverge sharply by segment, with industrial distributors capturing professional-grade volume while retail chains and direct e-commerce serve fragmented consumer demand. Material certification requirements and torque specifications determine which segments flow through authorized distributors versus open-market procurement.
Product Type:
Channel mix varies dramatically across product formats, with T-handle and ball end variants dominating industrial distributor relationships while folding and standard configurations concentrate in retail and direct-to-consumer channels.
- Ball End Allen Wrench:25-degree angled insertion geometry permits fastener engagement in obstructed automotive and electronics assembly environments. Demand concentrates in Stuttgart and Nagoya automotive transmission plants where line-side tool cribs mandate HRC 52-60 certified inventory with lot traceability.
- T-Handle Allen Wrench:Extended lever arm delivers high-torque capability for industrial fabricator maintenance bays. German automotive OEMs specify supplier-managed inventory programs with consignment stocking for this format, displacing traditional wholesale relationships in Bavarian manufacturing clusters.
- Standard Allen Wrench:Straight hexagonal shaft serves furniture assembly and basic maintenance where access is unobstructed.
- Folding Allen Wrench:Compact multi-size sets occupy portable maintenance kits favored by bicycle mechanics and field service technicians.
- Telescoping Allen Wrench:Adjustable reach configurations address deep-recess fastening in heavy equipment and aerospace applications.
By volume, standard Allen wrench leads. By growth pace, ball end is expanding most quickly.
Material:
Cost tier stratification separates captive-forged premium grades from import-dependent economy offerings, with certification burden falling disproportionately on mid-tier suppliers lacking in-house metallurgical testing.
- Chrome Vanadium Steel:Tensile strength and corrosion resistance anchor professional-grade demand in Germany, Japan, and the United States. FAA maintenance protocols and ISO 4762 fastener tolerance tightening force systematic replacement of non-compliant inventory in aviation MRO facilities.
- Alloy Steel:Cold-forged variants with validated hardness ratings serve precision engineering workshops facing compressed replacement cycles. Heat treatment certification requirements favor manufacturers with capital-intensive metallurgical testing equipment.
- Carbon Steel:Economy-tier material dominates furniture assembly and DIY channels where unit price sensitivity exceeds durability requirements.
- Stainless Steel:Corrosion-resistant specification serves marine, food processing, and medical device assembly environments.
- Titanium:Lightweight, non-magnetic properties address specialized aerospace and electronics manufacturing applications.
Chrome vanadium steel commands the premium tier. Alloy steel is gaining share fastest as ISO standards tighten tolerance requirements.
Application:
Customer type and procurement scale determine margin structure, with precision engineering and industrial maintenance supporting certified-supplier relationships while consumer applications tolerate commodity sourcing.
- Precision Engineering:ISO 4762 and DIN 912 compliance mandates traceable alloy composition and dimensional tolerance documentation. METI industrial standards and JIS specifications in Japan further constrain import eligibility for non-certified manufacturers.
- Bicycle Maintenance:Portable tool kit demand from professional mechanics and serious hobbyists favors folding multi-format sets with ball end geometry.
- Furniture Assembly:High-volume, low-specification consumption channels through big-box retail and e-commerce marketplaces.
- Electronics Repair:Miniature hex key requirements for consumer device servicing drive demand for precision-ground tip geometry.
- DIY Projects:Price-sensitive occasional-use segment served by carbon steel economy sets through home improvement chains.
Furniture assembly generates the highest unit volume. Precision engineering shows the steepest expansion trajectory as regulatory documentation requirements intensify.
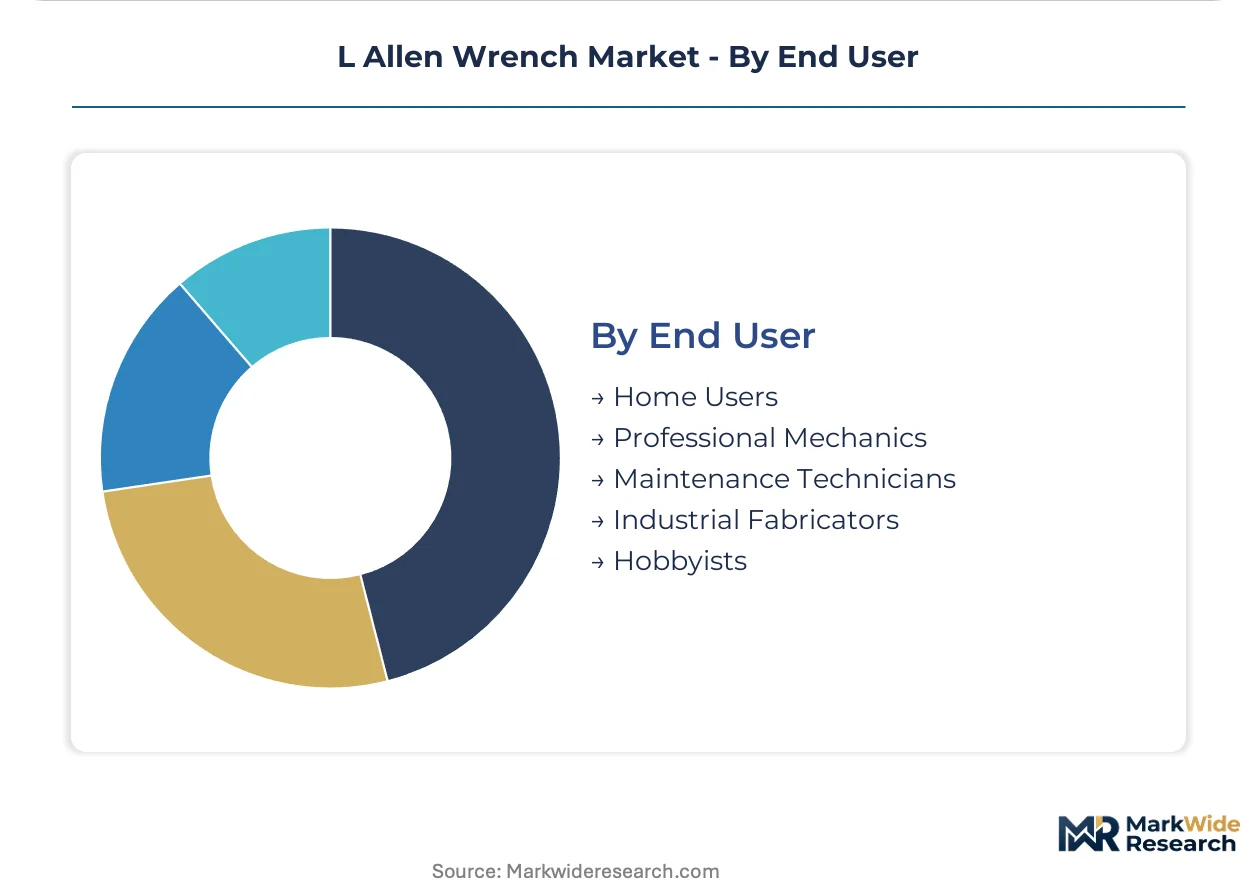
End User:
Procurement authority and compliance burden separate institutional buyers with vendor-managed inventory programs from fragmented individual purchasers.
- Industrial Fabricators:Just-in-time tool availability carries line-down cost implications, driving adoption of consignment stocking and usage-based billing arrangements. Skilled maintenance technician shortages reorganize priorities toward durable, multi-format tool kits.
- Professional Mechanics:Aviation and medical device sectors demand FDA-validated and FAA-traceable tool certification, opening premium certification tiers with lot-level documentation.
- Maintenance Technicians:Field service requirements favor portable, multi-size configurations with rapid fastener engagement capability.
- Home Users:Infrequent use patterns tolerate lower durability specifications and price-driven retail procurement.
- Hobbyists:Enthusiast segments in cycling and maker communities drive direct-channel brand loyalty through specialized forums and industrial marketplaces.
Home users represent the largest population. Industrial fabricators deliver the highest per-account revenue concentration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FAA maintenance protocols in the United States anchor the dominant geography for professional-grade L Allen wrench demand, with aviation MRO facilities driving systematic replacement of non-compliant inventory under traceable tool certification mandates.
United States
Aviation MRO facilities in Dallas-Fort Worth and Seattle-Tacoma clusters drive FAA-mandated tool certification demand. The Federal Aviation Administration requires lot-traceable alloy documentation for airframe fastener work. Wichita's aerospace manufacturing corridor concentrates procurement authority for high-specification ball end and T-handle configurations.
Germany
Automotive transmission plants in Stuttgart and industrial fabricators in Baden-Württemberg anchor European demand for chrome vanadium steel variants. ECHA REACH substance documentation requirements constrain import eligibility for non-certified suppliers. Bavarian manufacturing clusters have adopted supplier-managed inventory programs with consignment stocking for just-in-time tool availability.
Japan
Precision engineering workshops in Nagoya and Osaka face compressed replacement cycles as METI industrial standards tighten fastener tolerance requirements. JIS specifications further constrain import eligibility for manufacturers seeking certified contracts. Automotive OEMs in Aichi Prefecture specify HRC 52-60 hardness validation with metallurgical testing documentation.
China
Dual carbon goals under MEE oversight are reshaping material sourcing compliance costs for alloy steel forges in Yangtze River Delta manufacturing zones. GB standards and SAMR certification requirements elevate documentation burdens for export-grade production. Shenzhen electronics assembly plants drive miniature hex key demand for consumer device servicing applications.
India
The PLI scheme for precision manufacturing equipment creates localized assembly opportunities for export-grade tool kits in Maharashtra and Gujarat industrial corridors. BIS certification requirements and DGFT import protocols constrain non-standard product entry. Tamil Nadu automotive component suppliers are expanding maintenance technician training programs that elevate durable tool kit procurement priorities.
L Allen Wrench Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the L Allen wrench market, with captive forging operations conferring cost absorption advantages against import-dependent distributors. The structure separates premium certified suppliers serving aviation and medical device sectors from economy-tier carbon steel providers in furniture and DIY channels. Two strategic archetypes dominate: vertically integrated alloy forges with in-house heat treatment certification, and industrial distributors with vendor-managed inventory capability. Competitive moves concentrate on backward integration into raw material sourcing and geographic expansion through e-commerce direct channels that bypass traditional wholesale markups.
Among North American tool conglomerates, Stanley Black & Decker occupies a position exemplifying retail channel density and private-label scale, while Bondhus Corporation represents the captive alloy steel forging archetype in premium ball end segments. Wiha Tools anchors the precision-grade German manufacturing tier that commands professional mechanic loyalty in aviation and medical device sectors. These three companies illustrate how material certification capabilities and distribution configuration determine competitive access across regulated assembly environments.
| Leading Market Players |
|---|
| Apex Tool Group |
| Stanley Black & Decker |
| Bondhus Corporation |
| Wera Tools |
| Wiha Tools |
| Klein Tools |
| TEKTON |
| Armstrong Tools |
| GEDORE Tool Center |
| Others |
Pricing and Supply Chain Analysis
FAA maintenance protocols and ECHA REACH substance documentation simultaneously gate supply qualification and price differentiation in professional-grade L Allen wrench procurement. Certification burdens concentrate margin capture among captive-forged suppliers while compressing mid-tier competitors dependent on import sourcing.
Pricing Analysis
Long-term offtake contracts dominate industrial fabricator procurement, with supplier-managed inventory programs locking in volume commitments for chrome vanadium steel variants. Three-tier pricing structure across premium, standard, and economy levels separates FAA-traceable aviation grades from carbon steel furniture assembly sets. Price differentiation hinges on heat treatment certification and alloy composition documentation, with ISO 4762 compliance commanding substantial premiums. Cost compression in economy-tier forged products is intensifying because ferrovanadium spot market volatility squeezes mid-tier margins. DIY home improvement channels exhibit highest price sensitivity, while aviation MRO facilities prioritize lot traceability over unit cost.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes elevate inbound logistics costs for alloy steel imports serving European precision engineering workshops. Manufacturing gravity centers on Germany, Japan, and China, with Yangtze River Delta forges supplying carbon steel economy tiers and Stuttgart-area captive operations serving automotive OEM demand. Raw material flows draw from ferrovanadium producers, chrome ore processors, and specialty alloy recyclers. Single-source vulnerability concentrates in ferrovanadium supply channels tethered to South African and Russian extraction. Distribution runs through industrial distributors with VMI capability in Bavarian manufacturing clusters, alongside retail channel density in North American home improvement chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Procurement authority is consolidating among industrial fabricators adopting consignment stocking arrangements, fragmenting traditional wholesale relationships and shifting negotiating leverage toward volume-committed buyers with line-down cost exposure.
For Market Incumbents: Compound defensive positioning through backward integration into captive alloy steel forging and metallurgical testing certification. Power tool substitution with hex bit compatibility threatens high-volume assembly applications; counter through ball end geometry R&D and carbide-tipped insert development. Channel control via supplier-managed inventory programs in German automotive OEM clusters locks out import-dependent distributors. For New Entrants and Emerging Players: Aftermarket service and calibration gaps in aviation MRO traceability systems offer white-space entry points. Medical device assembly with FDA-validated sterile manufacturing requirements represents the most penetrable premium tier. E-commerce direct channels through professional mechanic forums bypass traditional distribution markups. Target India's PLI scheme for precision manufacturing equipment to establish localized assembly with export-grade certification. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across heat treatment certification and metallurgical testing equipment, favoring scaled incumbents over fragmented import distributors. Five-to-ten year viability rests on compliance infrastructure rather than geometry alone. Acquisition target archetype: mid-tier European forges with ECHA REACH documentation systems and established aviation sector relationships. Signal to watch: EU extended producer responsibility framework implementation accelerating alloy recovery documentation mandates.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alloy Steel Forging | Captive supply of chrome vanadium steel insulates margin from ferrovanadium spot volatility. |
| Heat Treatment Certification Investment | HRC 52-60 hardness validation opens FAA-traceable aviation MRO procurement channels. |
| Supplier-Managed Inventory Programs | Consignment stocking with German automotive OEMs displaces traditional wholesale relationships. |
| Carbide-Tipped Ball End Development | 50,000+ fastener engagement durability shifts procurement metrics to total cost-per-fastener. |
| E-Commerce Direct Channel Expansion | Professional mechanic forums enable brand-direct procurement bypassing distribution markups. |
Research Methodology
A spread of perspectives from maintenance directors at industrial fabricators, procurement leads at aviation MRO facilities, plant managers at alloy steel forges, and channel partners at industrial distributors converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation through customs trade data, SEC filings of tool conglomerates, FAA maintenance protocol documentation, and ECHA REACH substance registration databases. Bottom-up demand modeling across end-user segments triangulated against top-down supply-side capacity assessments.
Segmentation dimensions modeled include product format configuration, material grade tier, application environment, and end-user procurement authority across the analysis window. CAGRs were derived from replacement cycle compression rates under tightening ISO 4762 fastener tolerances and power tool substitution elasticity estimates. Industry-specific forecast inputs incorporated aviation MRO fleet expansion trajectories and automotive transmission plant tool crib specifications.
Underlying assumptions cover stable ferrovanadium alloy pricing, continued FAA traceability mandate enforcement, and ECHA documentation burden persistence, with deviation risk concentrated in dual carbon policy acceleration in China and extended producer responsibility framework implementation pace in the European Union. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Foam Cutting Machine Market
Tools
Digital Levels Market
Tools
Nail Gun Market
Tools
Digital Cutting Machine Market
Tools
Fiber Laser Cutting Machines Market
Tools
Trim Press Market
Tools
Workholding Tools Market
Tools
Global Protractor Market
Tools
Global Staple Gun Market
Tools
Tile Saw Market
Tools
Measuring Wheels Market
Tools
Tile Cutter Market
Tools
Pruning Saw Market
Tools
MIG Guns Market
Tools
Automatic Heat Press Machines Market
Tools
Digital Laser Levels Market