
 Laser Welding Equipment Market | 2026-2036
Laser Welding Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Laser Welding Equipment Market Outlook
Fiber laser source integration with automated beam delivery systems is reshaping production economics across precision manufacturing sectors. Trumpf leverages in-house resonator manufacturing to control core component supply chains from Germany. Han's Laser competes on system cost structures through vertically integrated production in Shenzhen. IPG Photonics anchors high-power fiber laser supply to North American and European OEM tool builders.
Laser welding equipment employs focused coherent light to melt and fuse metallic substrates with minimal heat-affected zones, typically operating at power densities exceeding 10^5 W/cm² for deep-penetration keyhole welding. The technology serves critical joining functions in battery tab welding, hermetic medical device sealing, and aerostructure assembly where distortion tolerance approaches zero. Fiber lasers command the dominant product type position due to wall-plug efficiency advantages and maintenance intervals stretching beyond 100,000 hours. Remote laser welding technology segments show accelerated trajectory as automakers deploy scanning optics to eliminate mechanical part repositioning. Solid-state lasers retain niche dominance in micro-welding applications where pulse energy stability below one millijoule determines yield rates.
FDA 21 CFR Part 820 quality system regulations and EU Machinery Directive 2006/42/EC conformity requirements shape equipment validation protocols for medical device and industrial machinery markets respectively. China's GB/T national standards for laser product safety and Japan's JIS B 6802 classification rules create divergent compliance pathways that manufacturers must navigate for market access. Stakeholders must monitor evolving battery format standards and solid-state battery architectures that will redefine joint geometry requirements and beam parameter specifications across the next technology cycle.
Market Dynamics
Electric vehicle battery architecture evolution is compressing joint tolerances below 50 microns, forcing automakers to replace mechanical fastening with fiber laser welding across gigafactory assembly lines. This shift cascades through equipment specifications, beam delivery optics, and validation protocols.
Growth Catalysts
- EU Machinery Directive 2006/42/EC:Conformity requirements for industrial machinery safety accelerate replacement of conventional arc welding systems with closed-loop laser solutions in European manufacturing facilities.
- Solid-state battery commercialization:Next-generation cell architectures with silicon-anode chemistries require hermetic sealing capabilities that fiber laser systems uniquely provide at production scale.
- German precision manufacturing clusters:Stuttgart and Munich automotive supplier ecosystems concentrate demand for high-throughput remote laser welding cells with integrated quality monitoring.
Market Restraints
- Optics supply concentration:German and Japanese suppliers dominate high-power beam delivery components, creating vulnerability to lead time volatility for system integrators.
- Technical limitation in aluminum-copper dissimilar joining:Intermetallic compound formation at the weld interface constrains battery tab-to-busbar connections without intermediate interlayers.
- Substitution threat from ultrasonic metal welding:Battery manufacturers deploy solid-state bonding for thin-foil applications where heat input must approach zero.
Strategic Opportunities
- Indian PLI scheme for advanced chemistry cells:Domestic battery manufacturing incentives create greenfield demand for laser welding equipment in Tamil Nadu and Gujarat production corridors.
- Technology convergence of AI vision and adaptive beam shaping:Real-time seam tracking with machine learning feedback loops enables zero-defect welding in reflective materials.
- Medical device hermetic sealing:FDA 21 CFR Part 820 quality system requirements drive adoption of pulsed fiber lasers for implantable device packaging.
Industry Challenges
- Multi-physics simulation expertise gap:System integrators struggle to recruit engineers capable of modeling keyhole dynamics and melt pool stability across parameter ranges.
- ISO 15614-11 welding procedure qualification timelines:Certification protocols for laser-arc hybrid processes extend equipment commissioning cycles by four to six months.
- Legacy robot controller integration friction:Fieldbus compatibility issues between modern laser sources and aging automotive line automation delay deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Laser Welding Equipment Market |
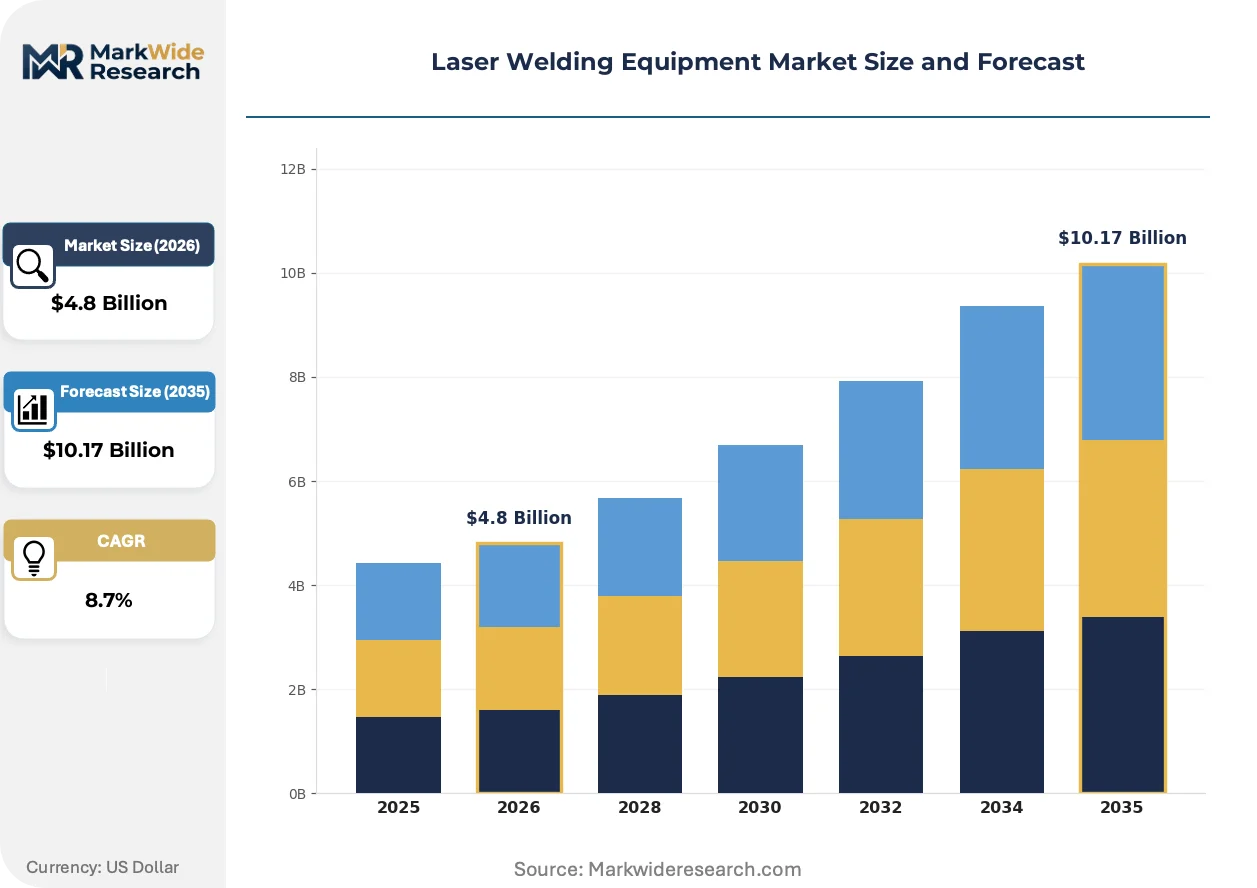
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solid-State Lasers, Fiber Lasers, CO2 Lasers, Diode Lasers Application: Aerospace, Automotive Manufacturing, Electronics, Medical Devices Technology: Laser Beam Welding, Hybrid Welding, Remote Laser Welding, Precision Laser Welding End User: Manufacturing, Construction, Automotive, Healthcare |
| Companies Covered | Han's Laser, LaserStar, Trumpf, UW Laser, Amada Miyachi, Coherent, SENFENG Laser, Alpha Laser, IPG Photonics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Laser Welding Equipment Market Strategic Shifts
Beam parameter agility and process monitoring intelligence are separating next-generation systems from commodity welding platforms. Equipment vendors race to embed adaptive control that compensates for gap variation and surface contamination without operator intervention.
Blue laser sources operating at 450 nanometers wavelength are rendering obsolete infrared systems for copper welding applications. Battery manufacturers in Germany and China adopt these sources to achieve spatter-free penetration at speeds exceeding two meters per minute. The technology is compressing heat-affected zones to sub-millimeter dimensions, enabling direct cell-to-pack architectures without module-level welding.
EU F-Gas Regulation phase-down schedules for fluorinated greenhouse gases are accelerating adoption of solid-state laser cooling systems using water-glycol mixtures. Industrial machinery OEMs face refrigerant compliance deadlines that disqualify conventional chiller designs. German system builders now specify closed-loop temperature control architectures that eliminate synthetic refrigerants entirely.
Buyers are consolidating vendor relationships around full-stack solution providers capable of beam source, optics, and motion integration. Tier-1 automotive suppliers in the United States now require single-point accountability for weld quality rather than multi-vendor system assembly. This pattern concentrates procurement authority with engineering teams possessing laser physics competency rather than traditional welding engineering backgrounds.
Laser Welding Equipment Market Segmentation
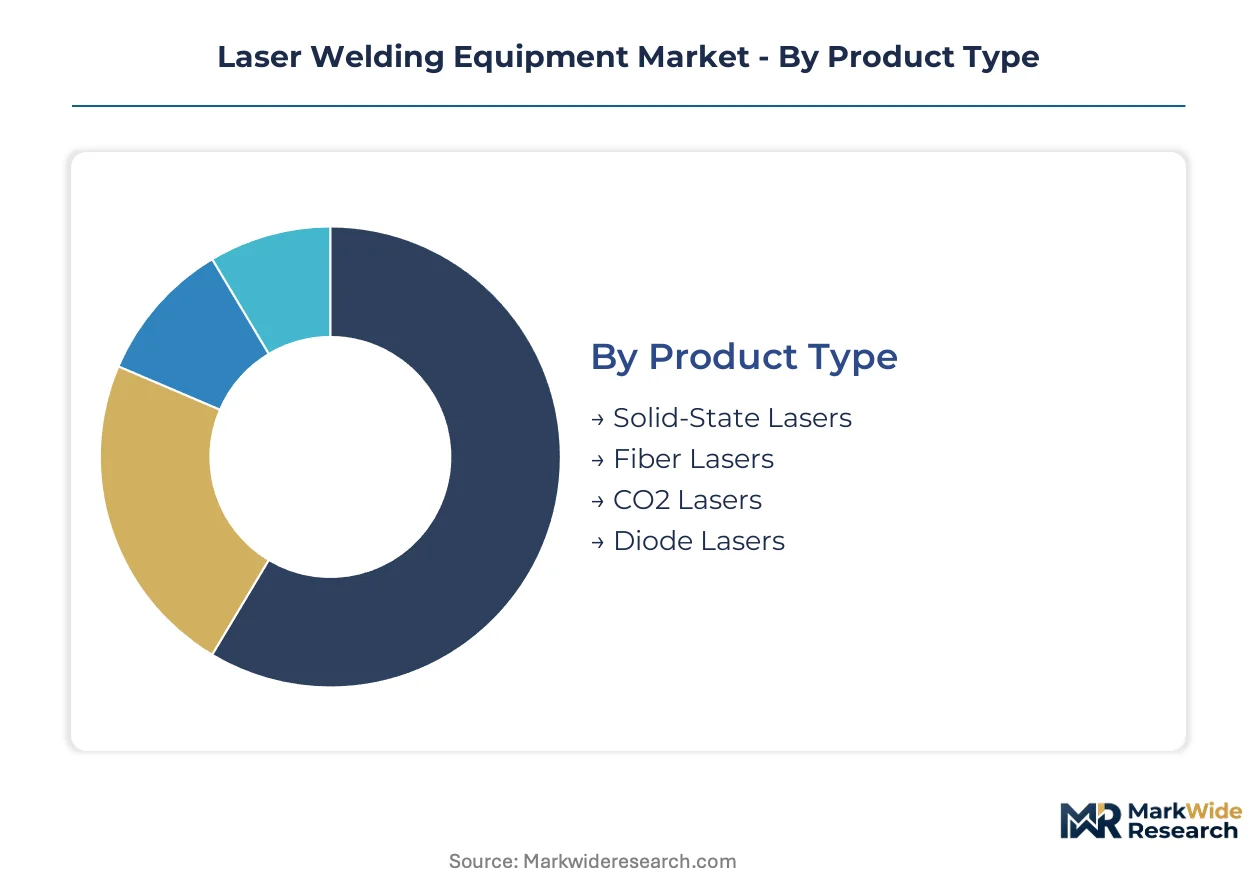
Segmentation in laser welding equipment reveals how power source physics, joint geometry requirements, and regulatory compliance layers create distinct procurement patterns across precision manufacturing sectors. Buyers prioritize wall-plug efficiency for high-volume automotive lines or pulse stability for hermetic medical sealing, with minimal overlap in vendor evaluation criteria.
Product Type:
Cost tier differentiation separates maintenance-intensive legacy systems from solid-state architectures with extended service intervals.
- Fiber Lasers:Ytterbium-doped fiber resonators deliver wall-plug efficiencies exceeding 30% with maintenance intervals stretching beyond 100,000 hours. German automotive suppliers in Stuttgart and Munich specify these sources for remote welding cells in EV battery pack assembly where throughput requirements exceed 500 joints per minute.
- Solid-State Lasers:Nd:YAG crystal architectures provide pulse energy stability below one millijoule for micro-welding applications. Demand concentrates in FDA-regulated medical device manufacturing where hermetic sealing of implantable pacemakers and neurostimulators requires sub-micron positioning repeatability.
- CO2 Lasers:Gas discharge systems at 10.6 micrometers wavelength retain niche applications in thick-section steel processing for construction equipment fabrication.
- Diode Lasers:Direct-emitting semiconductor sources at 800-1000 nanometers serve surface conduction welding of heat-sensitive electronics assemblies.
Fiber lasers command the established base. The steepest expansion runs through blue-wavelength diode-pumped sources for copper welding in next-generation battery architectures.
Application:
Joint tolerance specifications and distortion constraints determine technology selection across end-use verticals.
- Automotive Manufacturing:Gigafactory assembly lines for electric vehicles compress joint tolerances below 50 microns, displacing mechanical fastening with fiber laser welding across cell-to-pack architectures. China's NMPA battery certification requirements and EU Machinery Directive conformity protocols shape equipment validation specifications in parallel.
- Medical Devices:Implantable device packaging under FDA 21 CFR Part 820 quality system regulations demands pulsed fiber laser systems with hermetic sealing capabilities. German and Swiss precision manufacturing clusters concentrate procurement for cardiovascular stent and insulin pump assembly.
- Aerospace:Titanium and nickel superalloy joining for aerostructures requires keyhole welding at power densities exceeding 10^6 W/cm² with distortion tolerance approaching zero.
- Electronics:Miniaturized component welding for smartphones and wearables drives demand for sub-kilowatt fiber lasers with beam diameters below 100 microns.
Automotive manufacturing anchors procurement volume. Medical device applications deliver the highest margin expansion trajectory.
Technology:
Process maturity and integration complexity separate established arc-laser hybrid methods from emerging scanning-optic architectures.
- Remote Laser Welding:Scanning optics with 2D/3D beam deflection eliminate mechanical part repositioning, cutting cycle times by 60% in automotive body-in-white assembly. German OEMs in Wolfsburg and Munich deploy these systems with integrated seam tracking for gap variation compensation.
- Precision Laser Welding:Sub-kilowatt fiber sources with closed-loop power modulation serve micro-joining of dissimilar metals in electronics and medical device fabrication. China's GB/T laser safety standards and Japan's JIS B 6802 classification rules create divergent compliance pathways for equipment validation.
- Laser Beam Welding:Conventional focusing optic configurations remain standard for general fabrication in construction and heavy equipment manufacturing.
- Hybrid Welding:Laser-arc combination processes extend penetration depth in thick-section joining for shipbuilding and pressure vessel construction.
Laser beam welding retains the installed base. Remote laser welding systems are climbing the fastest as automakers eliminate mechanical repositioning stages.
End User:
Customer scale and in-house technical competency determine whether buyers procure turnkey cells or component-level integration.
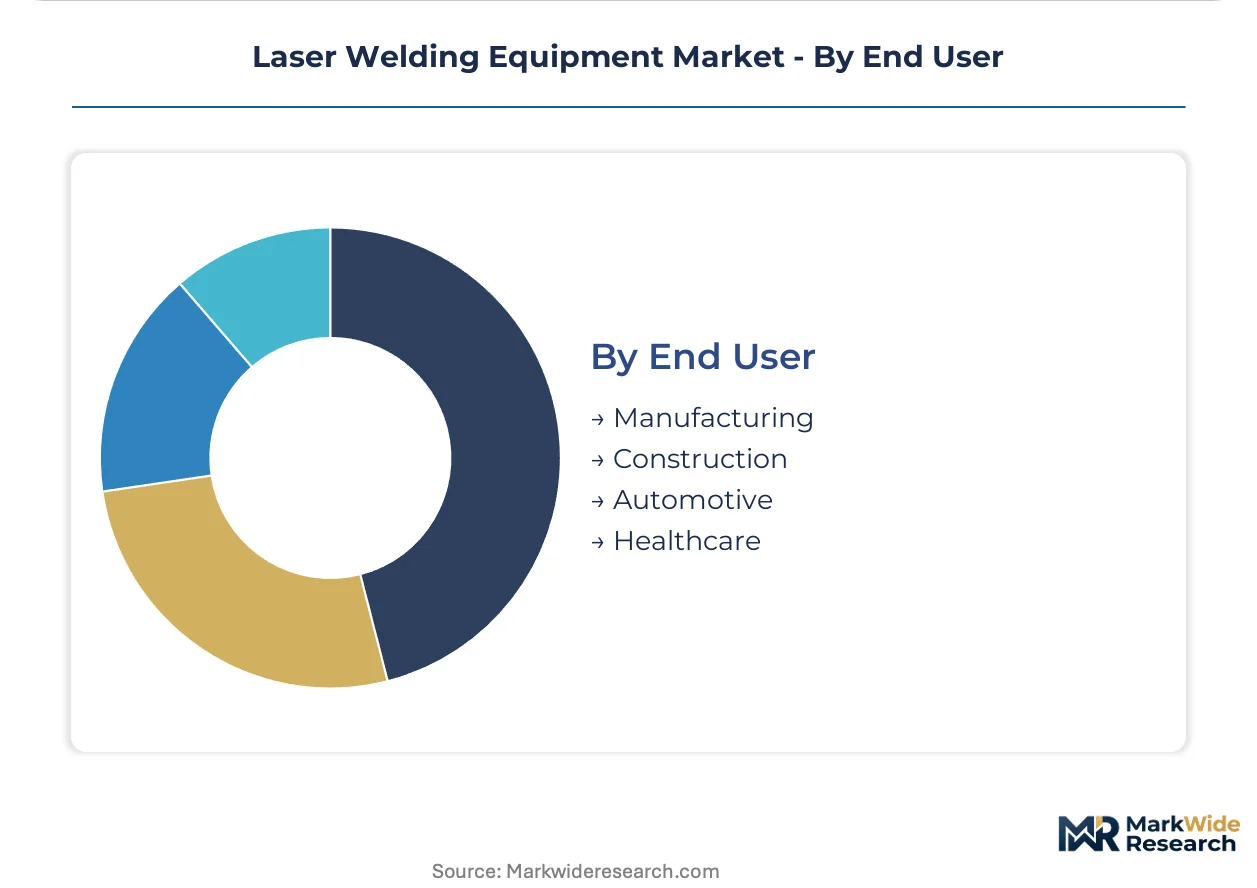
- Manufacturing:Tier-1 automotive suppliers and industrial machinery OEMs consolidate procurement around full-stack solution providers capable of beam source, optics, and motion integration. Single-point accountability for weld quality now supersedes multi-vendor system assembly in US and German procurement protocols.
- Healthcare:Medical device contract manufacturers prioritize FDA-validated process windows over capital cost minimization, creating demand for pulsed fiber systems with documented qualification protocols under 21 CFR Part 820.
- Automotive:EV battery manufacturers in China, Germany, and the United States specify equipment with real-time quality monitoring to satisfy internal yield targets and external regulatory filings.
- Construction:Structural steel fabricators favor CO2 and high-power fiber systems for thick-section joining with minimal preparation requirements.
Manufacturing end users represent the dominant procurement base. Healthcare applications are gaining share fastest as implantable device volumes expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment procurement clusters around precision manufacturing ecosystems where EV battery assembly, medical device fabrication, and aerospace component production concentrate. Buyers in Germany, China, and the United States dominate order volumes, with regulatory compliance requirements fragmenting vendor selection criteria across jurisdictions.
United States
FDA 21 CFR Part 820 quality system regulations drive medical device manufacturers toward validated pulsed fiber laser systems for hermetic sealing of implantable devices. NHTSA safety standards and IRA clean energy incentives accelerate EV battery gigafactory construction across Michigan, Ohio, and Tennessee. Detroit and Austin automotive supplier corridors concentrate demand for remote laser welding cells with integrated quality monitoring.
Germany
EU Machinery Directive 2006/42/EC conformity requirements and F-Gas Regulation refrigerant phase-down schedules reshape equipment specifications for industrial machinery OEMs. Stuttgart and Munich automotive supplier ecosystems anchor procurement for high-throughput fiber laser systems in battery pack assembly. KBA vehicle certification protocols extend validation timelines for welding procedure qualification.
China
NMPA battery certification requirements and GB/T national standards for laser product safety create divergent compliance pathways for domestic and export-oriented manufacturers. MIIT industrial policy supports domestic laser source production through the dual carbon goals framework. Shenzhen and Shanghai precision manufacturing clusters concentrate fiber laser system deployment for consumer electronics and EV battery production.
Japan
METI industrial technology roadmaps prioritize solid-state laser development for micro-welding applications in medical device and electronics manufacturing. JIS B 6802 classification rules govern laser safety equipment validation for domestic market access. Nagoya and Osaka automotive supplier networks maintain demand for hybrid laser-arc welding systems in body-in-white assembly.
India
PLI scheme incentives for advanced chemistry cell manufacturing create greenfield demand for laser welding equipment in Tamil Nadu and Gujarat production corridors. BIS standards harmonization with IEC laser safety classifications streamlines import certification for foreign equipment vendors. Pune and Chennai automotive component clusters initiate fiber laser adoption for EV subassembly joining.
Laser Welding Equipment Market Competitive Environment
Channel-controlling players compete with product-specialist players across a market structure that concentrates authority with full-stack solution providers capable of beam source, optics, and motion integration. German and Chinese manufacturers anchor opposite ends of the cost-performance spectrum, with Japanese specialists occupying micro-welding niches. Three archetypes dominate: vertically integrated resonator manufacturers, system integrators with captive optics production, and component-specialist vendors supplying OEM tool builders. Competitive moves center on backward integration into core laser source production and geographic expansion through localized service networks.
Within the German-engineering archetype, Trumpf GmbH + Co. KG and Alpha Laser GmbH represent full-stack solution providers with in-house resonator manufacturing capabilities. Shenzhen-based Han's Laser Technology Industry Group Co., Ltd. exemplifies the Chinese cost-optimized model through vertically integrated production. IPG Photonics Corporation anchors the component-specialist tier, supplying high-power fiber laser sources to North American and European OEM system builders. These three occupy positions that span the market's technical and commercial range without overlapping directly in buyer procurement evaluations.
| Leading Market Players |
|---|
| Han's Laser |
| LaserStar |
| Trumpf |
| UW Laser |
| Amada Miyachi |
| Coherent |
| SENFENG Laser |
| Alpha Laser |
| IPG Photonics |
| Others |
Value Chain & Pricing Dynamics
Tariff exposure between Germany and China on high-power beam delivery optics determines both pricing tier spreads and supply chain shape across laser welding equipment markets. Equipment manufacturers face margin compression when sourcing German precision optics for Chinese-assembled systems, forcing tiered pricing structures that separate premium validated systems from cost-optimized alternatives.
Pricing Analysis
Cost-plus contracts with rare-earth element indexation dominate fiber laser source procurement between OEM tool builders and resonator manufacturers. Pricing stratifies across premium, standard, and economy tiers based on FDA 21 CFR Part 820 validation status and wall-plug efficiency ratings. Cost compression in economy-tier fiber laser systems is intensifying because Han's Laser and SENFENG Laser deploy vertically integrated production in Shenzhen. Tier-1 automotive suppliers in Stuttgart and Detroit demonstrate the lowest price sensitivity, prioritizing single-point accountability for weld quality over capital cost minimization.
Supply Chain Analysis
Single-source dependency on German and Japanese suppliers for high-power beam delivery components dominates supply chain risk assessment for system integrators. Resonator manufacturing concentrates in Germany, China, and the United States, while precision optics production draws from Japan and Germany. Ytterbium-doped fiber, scanning galvanometers, and chiller systems with water-glycol cooling architectures represent critical input dependencies. Distribution runs through direct OEM partnerships for automotive gigafactory deployments and regional distributor networks for medical device contract manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Laser welding equipment markets sit at a platform-economics inflection where interoperability between beam sources, scanning optics, and adaptive control software determines competitive survival. Full-stack solution providers are consolidating procurement authority by offering single-point accountability for weld quality across automotive and medical device verticals.
For Market Incumbents: Build certification moats around FDA 21 CFR Part 820 and EU Machinery Directive validation protocols to defend against Chinese cost-optimized entrants. Anchor backward integration into ytterbium-doped fiber resonator production to control core component supply chains. Expand service networks in Tamil Nadu and Gujarat to capture PLI scheme-driven battery manufacturing demand before greenfield facilities lock in vendor relationships. For New Entrants and Emerging Players: India's advanced chemistry cell production corridors offer the most penetrable geography for laser welding equipment deployment, with BIS standards harmonization streamlining import certification. Target medical device hermetic sealing applications where FDA validation requirements create incumbent blind spots. Pursue technology licensing partnerships with German automotive suppliers seeking cost reduction without sacrificing EU conformity protocols. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors component-specialist vendors with captive optics production capabilities. Long-term viability rests on exposure to solid-state battery commercialization and silicon-anode chemistry transitions that redefine joint geometry requirements. Watch for NMPA battery certification timeline acceleration in China as the signal indicating gigafactory equipment procurement inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resonator Manufacturing | Trumpf controls core component supply chains from Stuttgart, insulating margin position against optics supply volatility. |
| Blue Laser Source Commercialization | 450-nanometer wavelength systems enable spatter-free copper welding for cell-to-pack architectures at speeds exceeding two meters per minute. |
| AI Vision and Adaptive Beam Shaping Convergence | Real-time seam tracking with machine learning feedback loops enables zero-defect welding in reflective aluminum-copper joints. |
| Geographic Expansion through Localized Service Networks | Equipment vendors establish Tamil Nadu and Gujarat presence to capture PLI scheme incentives for advanced chemistry cell manufacturing. |
| Closed-Loop Temperature Control Architecture Development | Water-glycol cooling systems eliminate synthetic refrigerants, satisfying EU F-Gas Regulation phase-down schedules for industrial machinery OEMs. |
Study Parameters
A spread of perspectives from OEM procurement managers, Tier-1 automotive supplier welding engineers, medical device contract manufacturing quality directors, and fiber laser source R&D heads converged on the working assumptions. Primary fieldwork combined structured interviews with equipment end-users and component suppliers, validated against secondary sources including SEC filings from IPG Photonics and Coherent, EU Machinery Directive implementation guidance, NMPA battery certification protocols, and MIIT industrial policy disclosures. Bottom-up equipment shipment data from German, Chinese, and United States manufacturing clusters triangulated against top-down market sizing derived from automotive production forecasts and medical device packaging demand.
Demand-supply balance framing anchored the analytical approach across the projection horizon. Segmentation dimensions modeled include laser source physics, joint geometry requirements, regulatory compliance layers, and end-user technical competency tiers. CAGRs emerged from equipment replacement cycle analysis, EV battery architecture evolution timelines, and solid-state battery commercialization trajectory assessments. Key forecast inputs incorporated gigafactory construction pipelines in Michigan, Ohio, and Tennessee alongside German precision manufacturing cluster expansion in Stuttgart and Munich.
The forecast holds incumbent behavior within observed patterns; aggressive vertical integration moves by Chinese system builders or accelerated solid-state battery chemistry transitions would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Walform Machines Market
Construction Equipment
Earthmover Market
Construction Equipment
Mini Cranes Market
Construction Equipment
Global Asphalt Crushers Market
Construction Equipment
Mobile Asphalt Plant Market
Construction Equipment
Brazil Metal Fabrication Equipment Market
Construction Equipment
Mobile Elevating Work Platform (MEWP) Market
Construction Equipment
Used Construction Equipment Market
Construction Equipment
Demolition Vessels Market
Construction Equipment
Global Pile Driving Equipment Market
Construction Equipment
Roadheaders Market
Construction Equipment
North America Crane Rental Market
Construction Equipment
China Construction Equipment Market
Construction Equipment
Truck Mounted Concrete Pump Market
Construction Equipment
Cranes Rental Market
Construction Equipment
Global Skid Steer Attachments Market