
 Machining Centers Market | 2026-2036
Machining Centers Market Size, Share, and Industry Trends Forecast 2026-2036
Machining Centers Market Intelligence
The bundling of automation solutions with core machine tools is rebalancing buyer choice from standalone hardware to integrated production cells. DMG MORI leverages its extensive global service network to support complex installations. In contrast, Haas Automation specializes in standardized, cost-effective machines for smaller job shops, while Makino differentiates through high-precision systems for demanding mold making and aerospace applications.
A machining center is an automated machine tool featuring an automatic tool changer and a worktable that performs various cutting operations like milling and drilling in one setup. Its primary purpose is to produce complex parts with high precision and repeatability. While CNC remains the core technology, 5-axis machining centers represent the fastest-growing product type, essential for aerospace manufacturing applications that require intricate geometries.
Machine safety and operational standards are governed by frameworks like Europe's CE marking and US-based OSHA regulations. Concurrently, ISO 9001 certification influences procurement decisions by signaling quality management consistency. The key decision for end-users now involves selecting the optimal level of automation and multi-axis capability against initial capital outlay.
Market Dynamics
The convergence of multi-axis machining with integrated automation is the central structural force. This shift, driven by aerospace and automotive demands for part complexity, rebalances value from standalone hardware to complete production systems.
Growth Catalysts
- 5-Axis Technology:Adoption of 5-axis systems is essential for producing intricate components with complex geometries demanded by the aerospace sector.
- Automotive Electrification:Germany's automotive industry drives demand for machining new EV components like battery trays, stimulating investment in advanced equipment.
- National Policies:China's industrial upgrade policies incentivize investment in high-precision machining centers for its advanced manufacturing hubs.
Market Restraints
- Capital Outlay:The substantial initial investment for advanced 5-axis machining centers presents a significant financial barrier for small and medium-sized enterprises (SMEs).
- Component Sourcing:High dependency on a few suppliers in Japan and Germany for critical components like high-speed spindles creates supply chain vulnerabilities.
- Programming Complexity:The difficulty in programming simultaneous 5-axis machines limits deployment, requiring scarce, highly skilled technical personnel.
Strategic Opportunities
- Medical Device Sector:Manufacturing custom orthopedic implants and surgical instruments from materials like titanium represents a key growth application for compact machining centers.
- Hybrid Manufacturing:Converging subtractive machining with additive technologies in one platform enables parts with complex internal channels and novel geometries.
- Southeast Asian Expansion:Industrialization in markets like Vietnam offers opportunities for vendors of standardized machines as local firms upgrade production capabilities.
Industry Challenges
- Skills Gap:A persistent shortage of qualified CNC programmers and technicians capable of managing automated, multi-axis systems hampers productivity.
- Legacy System Integration:Integrating new machining centers with older manufacturing execution systems (MES) on the factory floor is a major hurdle.
- Compliance Burden:Adhering to evolving safety standards like Europe's CE marking requires continuous investment in compliance engineering and documentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Machining Centers Market |
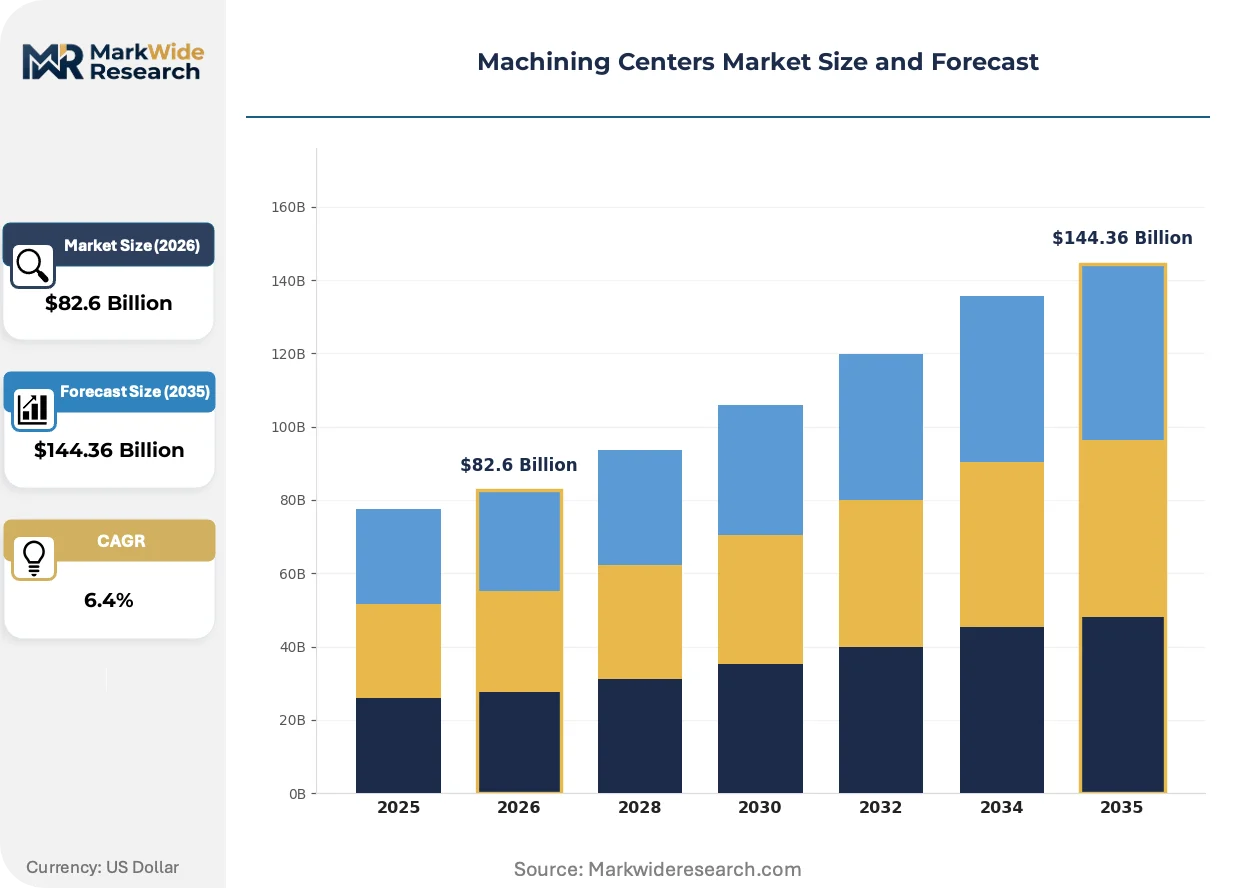
| Market Size in 2026 | $82.6 Billion |
| Market Size in 2035 | $144.36 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vertical Machining Centers, Horizontal Machining Centers, Gantry Machining Centers, 5-Axis Machining Centers, Composite Machining Centers Technology: CNC, DNC, Hybrid Machining, Multi-tasking, High-Speed Machining Application: Aerospace Manufacturing, Defense Equipment, Precision Tooling, Consumer Electronics, Mold Making End User Industry: OEM Manufacturers, Tier-1 Suppliers, Tool & Die Shops, Contract Machining Services, Maintenance Providers |
| Companies Covered | Okuma, Doosan, DMG MORI, CHIRON, Hurco, Mazak Corporation, Makino, GROB, Haas Automation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Machining Centers Market Strategic Shifts & Innovations
A shift towards intelligent, connected machining is underway. The focus is moving from raw cutting performance to data-driven optimization, where digital tools create more predictable and efficient manufacturing outcomes.
Digital twin technology creates a virtual replica of the machining process for simulation before cutting. Aerospace and medical firms adopt this to validate complex toolpaths on high-value parts. This simulation-first method is rewriting the traditional workflow, compressing the gap between design and shop-floor execution.
Europe's focus on industrial data sovereignty, guided by frameworks like the EU AI Act, shapes machine tool control development. This compels manufacturers to embed cybersecurity and transparent data governance into their equipment. German machine builders now position these secure connectivity features as a key differentiator.
End-user purchasing is evolving towards acquiring complete, pre-engineered production cells. This model favors direct collaboration with machine builders or system integrators, often bypassing traditional distributors. The trend is highly visible in the North American EV supply chain, where rapid scaling demands integrated lines.
Machining Centers Market Segmentation
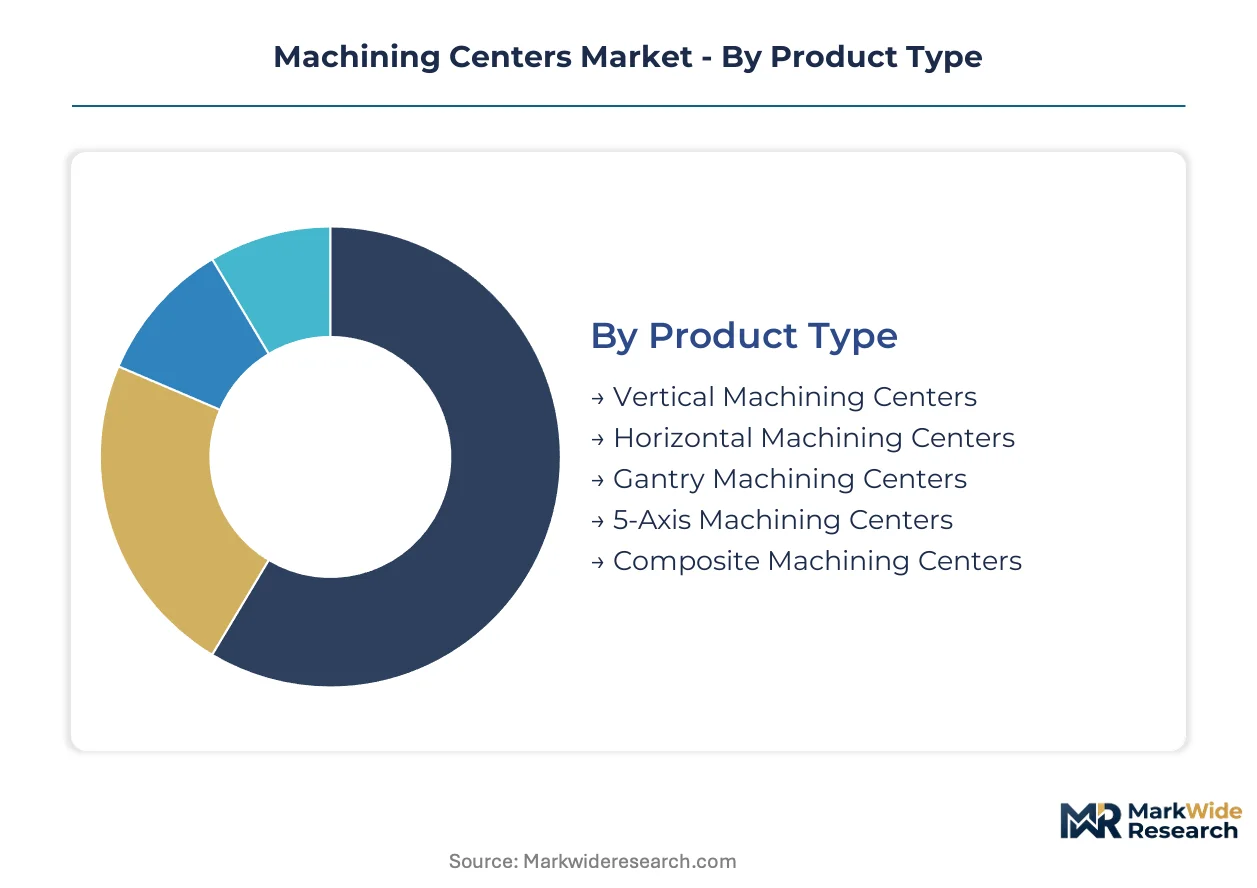
Understanding the Machining Centers Market segmentation reveals how varying technical requirements and operational scales influence procurement decisions. End-users evaluate product types, underlying technologies, specific applications, and their own industry position to optimize manufacturing capabilities.
Product Type:
Buyer-decision drivers often center on the complexity of parts and the required precision for manufacturing processes.
- 5-Axis Machining Centers:These advanced machines offer simultaneous movement along five axes, enabling the production of highly intricate parts with complex geometries in a single setup. Aerospace manufacturing in Germany and China demands these systems for turbine blades and structural components.
- Vertical Machining Centers:Characterized by a vertically oriented spindle, these machines are widely adopted for general-purpose milling, drilling, and tapping operations on flat workpieces. Smaller job shops globally rely on their cost-effectiveness and versatility for diverse production runs.
- Horizontal Machining Centers:Featuring a horizontally oriented spindle, these machines facilitate efficient chip evacuation and often integrate pallet changers for continuous operation.
- Gantry Machining Centers:These large-format machines are suitable for processing oversized workpieces, commonly found in industries like heavy machinery and shipbuilding.
- Composite Machining Centers:Specialized for cutting composite materials, these centers feature optimized dust extraction and tool designs to handle abrasive and layered materials effectively.
Volume sits with Vertical Machining Centers; growth tilts toward 5-Axis Machining Centers.
Technology:
Application-driven adoption patterns dictate the integration of specific machining technologies into production workflows.
- CNC:Computer Numerical Control (CNC) forms the core technology, allowing automated, precise control of machine tools through pre-programmed instructions. This technology underpins nearly all modern machining centers, ensuring high repeatability.
- Hybrid Machining:This technology combines additive and subtractive manufacturing processes on a single platform, enabling the creation of complex internal geometries and rapid prototyping. Aerospace and medical device firms in Europe are exploring these systems for novel part designs.
- DNC:Direct Numerical Control (DNC) systems connect multiple CNC machines to a central computer, facilitating program management and data transfer across a factory floor.
- Multi-tasking:These machines integrate multiple operations, such as turning and milling, onto one platform, reducing setup times and part handling.
- High-Speed Machining:Characterized by high spindle speeds and feed rates, this technology is employed for rapid material removal and fine finishing, particularly in mold making.
Market expansion is driven by Hybrid Machining; CNC secures high-value niches.
Application:
Precision requirements drive choices for machining center applications across diverse manufacturing sectors.
- Aerospace Manufacturing:This sector requires machining centers capable of extremely tight tolerances and processing high-strength, lightweight materials like titanium and aluminum alloys. The demand for intricate engine components and structural parts from companies like Airbus and Boeing drives investment.
- Mold Making:This application demands high-precision, fine-surface finishing capabilities for creating complex molds and dies used in plastic injection and metal casting. German mold makers utilize advanced centers for rapid prototyping and high-quality surface finishes.
- Defense Equipment:Manufacturing components for defense equipment involves precise machining of robust materials, often with stringent traceability and security requirements.
- Precision Tooling:This category encompasses the production of custom cutting tools, jigs, and fixtures, demanding high accuracy and specialized material handling.
- Consumer Electronics:Machining centers produce intricate components for devices like smartphones and laptops, focusing on high volume and consistent quality.
Aerospace Manufacturing represents the fastest-growing trajectory; Precision Tooling maintains consistent demand.
End User Industry:
Operational scale influences procurement strategies for machining centers across various industrial end-users.
- OEM Manufacturers:Original Equipment Manufacturers (OEMs) purchase machining centers for large-scale production of their core products, often requiring integrated automation and high throughput. Automotive manufacturers in Germany are key OEM buyers for electric vehicle component production.
- Tool & Die Shops:These specialized shops focus on producing custom tools, molds, and dies for other manufacturers, demanding high-precision and versatile machining centers. Small and medium-sized enterprises (SMEs) often operate in this segment.
- Tier-1 Suppliers:These companies supply major components directly to OEMs, necessitating robust and reliable machining centers to meet strict quality and volume requirements.
- Contract Machining Services:Firms offering contract machining services provide specialized production capabilities to clients, often requiring flexible and multi-purpose machines to handle diverse job orders.
- Maintenance Providers:These entities utilize machining centers for repair, refurbishment, and custom part fabrication to support operational machinery and equipment.
OEM Manufacturers drive the largest volume; Tool & Die Shops capture specialized demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Machining Centers Market exhibits a clear production-versus-consumption divide, with advanced manufacturing nations driving both innovation and demand. Key regional hubs specialize in either high-precision component supply or large-scale integrated system deployment. This dynamic shapes investment patterns and technological adoption across diverse industrial sectors.
Germany
Germany's automotive industry drives substantial demand for advanced machining centers, particularly for electric vehicle component production. The country's CE marking framework guides machine tool design and operational safety standards. Industrial clusters in Baden-Württemberg lead in high-precision mold making and integrated production cell development.
China
China's industrial upgrade policies incentivize significant investment in high-precision machining centers for its expanding advanced manufacturing hubs. GB standards dictate quality and performance benchmarks for imported and domestically produced equipment. The Yangtze River Delta region concentrates demand for sophisticated systems in aerospace and consumer electronics manufacturing.
United States
United States aerospace manufacturing demands machining centers capable of intricate geometries and processing high-strength alloys. OSHA regulations ensure workplace safety and operational standards for machine tool installations. The Pacific Northwest region, with its aerospace industry base, consistently invests in simultaneous 5-axis systems.
Japan
Japanese firms remain critical suppliers of high-speed spindles and other precision components for global machining centers. METI policies support advanced manufacturing technologies and automation within domestic industries. The Chubu region, a hub for automotive and machinery production, actively deploys multi-tasking and high-speed machining solutions.
Vietnam
Vietnam's industrialization efforts create opportunities for vendors of standardized and cost-effective machining centers as local firms upgrade production capabilities. The country's DGFT policies aim to stimulate manufacturing sector growth and foreign investment. Ho Chi Minh City and surrounding industrial zones are experiencing increased procurement of vertical machining centers for diverse applications.
Machining Centers Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across the Machining Centers Market, creating a tiered competitive structure. Players segment their offerings based on precision, automation level, and cost-effectiveness. Strategic archetypes include integrated solution providers, standardized machine manufacturers, and high-precision system developers. Competitive moves often involve portfolio diversification to capture varied end-user needs and technology licensing to enhance core capabilities.
Within the advanced and specialized segments, DMG MORI represents integrated production cells and extensive global service networks. Haas Automation exemplifies standardized, cost-effective machines tailored for smaller job shops and general-purpose applications. Makino occupies a position in high-precision systems, targeting demanding mold making and aerospace applications that require exceptional surface finishes and tight tolerances.
| Leading Market Players |
|---|
| Okuma |
| Doosan |
| DMG MORI |
| CHIRON |
| Hurco |
| Mazak Corporation |
| Makino |
| GROB |
| Haas Automation |
Cost & Logistics Intelligence
The global steel price index, influenced by energy costs and iron ore futures, cascades through the machining centers supply chain, affecting the cost of machine frames and critical components. This influences the final pricing tiers for end-users.
Pricing Analysis
Pricing pressure intensifies for standardized vertical machining centers due to increased competition from Asian manufacturers. The dominant pricing structure is value-based, often bundled with automation solutions. Price differentiation stems from multi-axis capability and integrated after-sales service networks. Smaller job shops exhibit high price sensitivity, prioritizing cost-effectiveness, while aerospace OEMs focus on precision and reliability, showing less sensitivity to initial capital outlay.
Supply Chain Analysis
Remanufacturing and refurbishment flows for older machining centers extend asset lifecycles, reducing demand for new units in certain segments. Geographic supply concentration for critical components like high-speed spindles and advanced control systems rests heavily in Japan and Germany. The market depends on specialized castings and precision-machined sub-assemblies. A structural risk involves single-source vulnerability for these high-performance components. Distribution often runs through direct sales channels for complex integrated systems, complemented by specialized distributors for standardized machines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The machining centers market is fundamentally supply-constrained, driven by a persistent skills gap for CNC programmers and technicians. This scarcity of specialized human capital props up pricing for advanced multi-axis systems, particularly in aerospace and medical applications.
For Market Incumbents:Anticipate continued demand for integrated production cells by bundling automation solutions with core machine tools. Deepen vertical integration into high-precision component manufacturing to mitigate supply chain vulnerabilities, especially for high-speed spindles. The threat from programming complexity and the skills gap requires investment in user-friendly interfaces and training programs. Incumbents should leverage extensive global service networks as a key differentiator against emerging competitors.
For New Entrants and Emerging Players:Launch via direct sales and online configurators for standardized vertical machining centers targeting smaller job shops. Focus on cost-effective, easy-to-operate machines for underpenetrated markets, such as Southeast Asia's industrialization efforts. Offer bundled software solutions that simplify CNC programming for less skilled operators. Target the general-purpose milling and drilling applications where high-end precision is not the primary driver.
For Investors and Strategic Acquirers:Distressed-cycle entries favor mid-sized specialists in Germany and Japan with unique intellectual property in 5-axis technology or advanced control systems. The long-term viability remains strong, driven by aerospace and medical device sectors requiring high precision. Target companies with strong R&D pipelines for hybrid manufacturing solutions. The signal to watch is the adoption rate of digital twin technology across a broader industrial base.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in 5-Axis Production | Addresses the growing demand from aerospace manufacturing for intricate geometries and high-strength alloys. |
| Investment in Programming Training Programs | Mitigates the skills gap for CNC programmers, enhancing productivity and machine utilization across industries. |
| Strategic Partnership with Automation Providers | Facilitates the development of complete, pre-engineered production cells for OEM manufacturers like automotive firms. |
| R&D in Hybrid Manufacturing Technologies | Enables novel part designs with complex internal channels for medical device and aerospace applications. |
| Compliance Engineering for CE Marking | Ensures market access and operational safety standards for equipment sold within Europe, a key demand region. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs, validated through primary interviews with industry stakeholders. This included plant managers, procurement leads at OEMs, R&D directors, and aftermarket service managers. The analysis integrated bottom-up and top-down triangulation, reconciling demand-side and supply-side data streams. This approach ensured comprehensive coverage across the machining centers market.
Data-stream reconciliation across primary and secondary sources informed the analytical framework over the projection horizon. Segmentation dimensions modeled included product type, technology, application, end-user industry, and regional manufacturing output. Compound Annual Growth Rates (CAGRs) derived from historical trends and projected technological adoption rates. Key forecast inputs included capital expenditure plans of automotive OEMs and aerospace production schedules.
Geopolitical instability, raw material price volatility, and evolving trade policies are the dominant revision risks for machining centers forecasts. The analysis reflects assumptions regarding technological advancements and end-user investment patterns. Practitioners should monitor global industrial output and skilled labor availability for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Screwdriver Market
Tools
Global Construction Camera Market
Tools
Industrial Floor Scrubber Market
Tools
Edging Tool Market
Tools
Broaching Tools Market
Tools
Cutting Tools Market
Tools
Set Screw Market
Tools
Pneumatic Bolting Tools Market
Tools
Structural Wood Screws Market
Tools
Industrial Plate Bending Machines Market
Tools
Pruning Saw Market
Tools
Blowing Torch Market
Tools
Garden Digging Tools Market
Tools
Lathe Machines Market
Tools
Vise-Grip Pliers Market
Tools
Grinding Discs Market