
 Europe Power Tools Market | 2026-2036
Europe Power Tools Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Power Tools Market Insights
Modular battery-platform bundling is repositioning buyer choice across the Europe power tools market, as professionals prioritize interchangeable systems over standalone units. Robert Bosch GmbH leverages its extensive service network to sustain loyalty among trade professionals. Hilti Corporation differentiates through fleet-management subscriptions that anchor recurring revenue. Makita Corporation competes on Lithium-Ion battery density, extending runtime benchmarks for cordless platforms.
Europe power tools encompass electrically or pneumatically driven handheld and stationary devices engineered for cutting, drilling, fastening, grinding, or surface preparation, typically operating at voltages from 12V to 54V DC or 110V-240V AC with torque ratings spanning 10 Nm to 1,000 Nm depending on application. These tools serve construction, automotive assembly, metal fabrication, and consumer maintenance tasks where precision, portability, and repeatability determine output quality. Brushless motor technology commands the premium tier, eliminating commutator wear while delivering higher efficiency densities than brushed equivalents. Cordless drills lead volume shipments, though angle grinders generate disproportionate aftermarket attachment revenue. The construction industry end-user segment absorbs the largest share of professional-grade units, while DIY enthusiasts drive seasonal spikes through hardware chains and online retail.
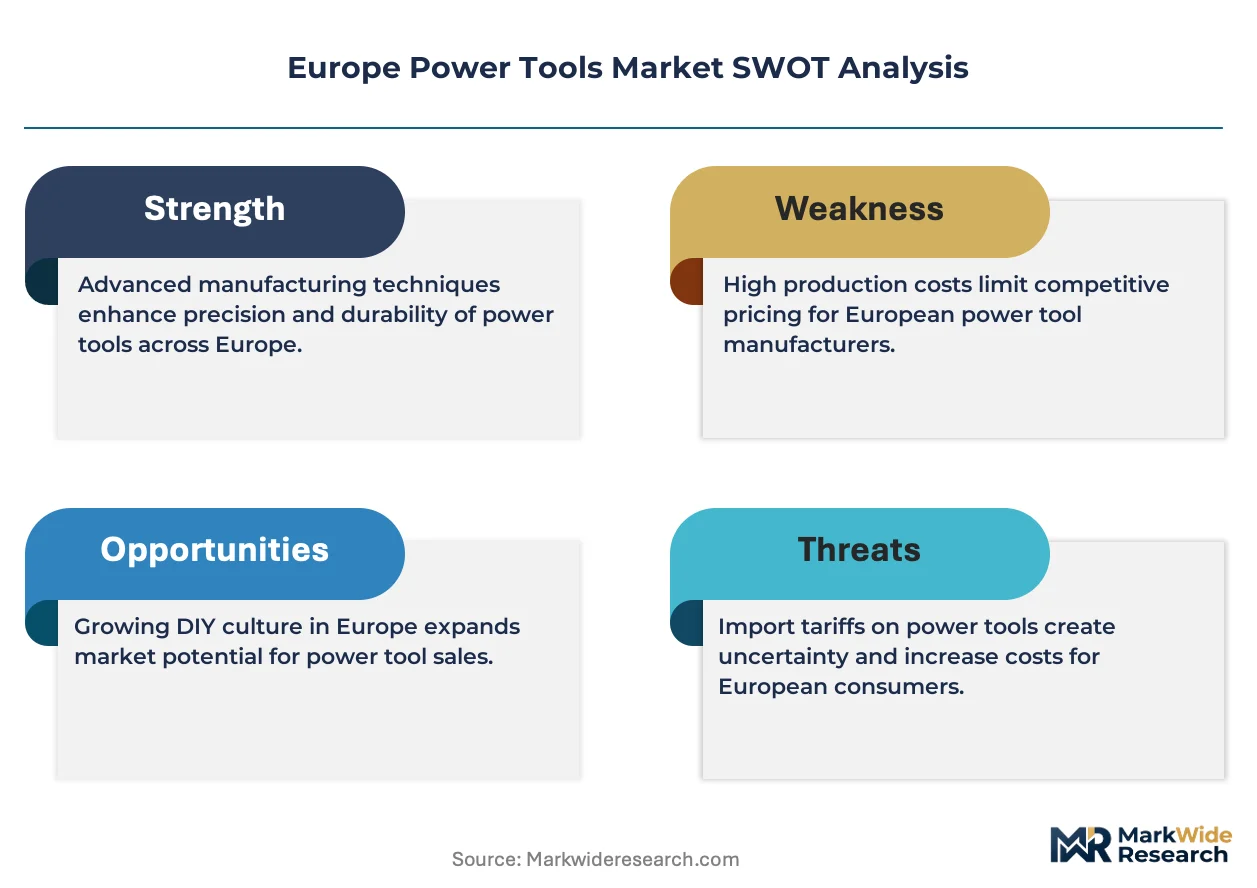
CE marking mandates govern mechanical safety and electromagnetic compatibility for all power tools sold within the European Economic Area, while the EU F-Gas Regulation accelerates displacement of pneumatic systems by battery-electric alternatives in controlled environments. REACH compliance constrains material selections for housings and coatings, elevating compliance costs for smaller manufacturers. Ecodesign directives progressively tighten efficiency thresholds for corded electric motors, reshaping R&D allocation across the supplier base. Stakeholders must monitor battery-platform interoperability standards and the pace of cordless substitution in heavy-duty applications previously dominated by pneumatic systems.
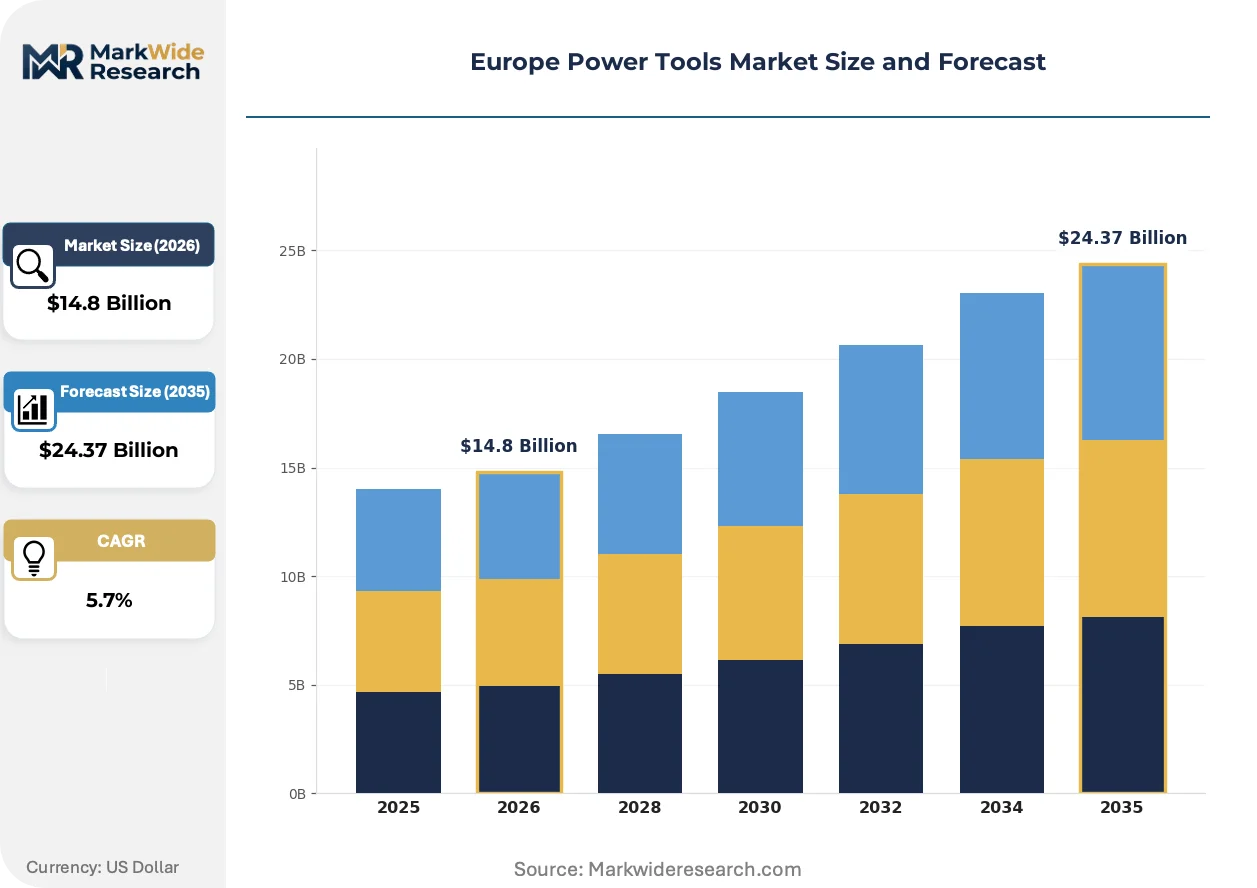
Market Dynamics
Modular battery-platform bundling is consolidating buyer preference across the Europe power tools market, as trade professionals abandon standalone-tool purchasing in favor of interchangeable ecosystems that reduce fleet complexity and total cost of ownership.
Growth Catalysts
- EU F-Gas Regulation:The phasedown of hydrofluorocarbon-based pneumatic systems in controlled environments accelerates displacement by battery-electric platforms, particularly in automotive assembly and cleanroom metal fabrication.
- Polish construction corridors:Rapid urbanization along the Warsaw-Kraków axis and Gdańsk port expansion generate concentrated demand for cordless drilling and fastening systems among mid-sized contractors.
- Brushless motor technology:Elimination of commutator wear and higher efficiency densities enable extended runtime benchmarks, expanding cordless viability into heavy-duty applications previously reserved for corded or pneumatic alternatives.
Market Restraints
- Lithium-ion cell supply concentration:Dependence on East Asian cathode and cell manufacturing exposes European assemblers to freight volatility and geopolitical friction in critical mineral procurement.
- REACH compliance costs:Restrictions on housing polymers and coating chemistries elevate material qualification expenses, disproportionately burdening smaller manufacturers without dedicated regulatory affairs functions.
- Pneumatic legacy infrastructure:Existing compressed-air installations in German and Italian metalworking facilities create switching friction that slows cordless adoption in heavy-torque grinding and cutting applications.
Strategic Opportunities
- Romanian manufacturing clusters:Greenfield production facilities in Transylvania and Banat offer proximity to Western European distribution networks with lower labor cost structures for mid-range tool assembly.
- Fleet-management subscriptions:Tool-as-a-service models anchored by usage-based billing and predictive maintenance telemetry open recurring revenue streams among cost-conscious construction consortia.
- Ecodesign directive tightening:Progressive efficiency thresholds for corded electric motors create competitive advantage for suppliers with advanced motor-control IP and thermal management expertise.
Industry Challenges
- Battery-platform interoperability standards:Fragmented fast-charging protocols and connector geometries across manufacturers force contractors into single-brand lock-in, complicating fleet diversification.
- Brushless motor controller calibration:Precision winding and Hall-sensor alignment require specialized technician training that outpaces vocational education output in Eastern European service networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Power Tools Market |
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $24.37 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cordless Drills, Angle Grinders, Circular Saws, Hammer Drills Technology: Brushless Motors, Lithium-Ion Batteries, Pneumatic Systems, Electric Motors End User: Construction Industry, Automotive Sector, DIY Enthusiasts, Manufacturing Facilities Distribution Channel: Online Retail, Specialty Stores, Hardware Chains, Wholesalers |
| Companies Covered | Techtronic Industries, Hilti Corporation, Robert Bosch GmbH, FEIN, Metabo, Stanley Black & Decker, Atlas Copco AB, Emerson Electric, Makita Corporation, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Power Tools Market Trends and Innovations
Three convergent forces are restructuring competitive advantage in the Europe power tools market: motor electrification, regulatory chemistry constraints, and procurement model digitization. Each trend reshapes where value accumulates across the value chain.
Brushless permanent-magnet motor architecture is rewriting performance benchmarks for cordless platforms. German residential contractors now specify runtime-per-charge metrics as primary selection criteria, compressing the viable supplier base to firms with proprietary winding and thermal-management IP. This technology shift is compressing margins for brushed-motor legacy portfolios while elevating service-contract attach rates.
The EU F-Gas Regulation mandates progressive hydrofluorocarbon phase-down through 2030, forcing automotive assembly plants and cleanroom fabricators to retire pneumatic fastening systems. Battery-electric alternatives with sealed brushless motors capture displaced demand, though compressed-air infrastructure sunk costs in Northern Italian metalworking clusters slow transition velocity.
Trade professionals now specify tools through integrated procurement portals that bundle hardware, warranty extensions, and consumable replenishment into single vendor relationships. Hardware distributors in France and Benelux respond with private-label battery platforms that undercut premium OEM pricing for price-sensitive municipal maintenance crews.
Europe Power Tools Market Segmentation
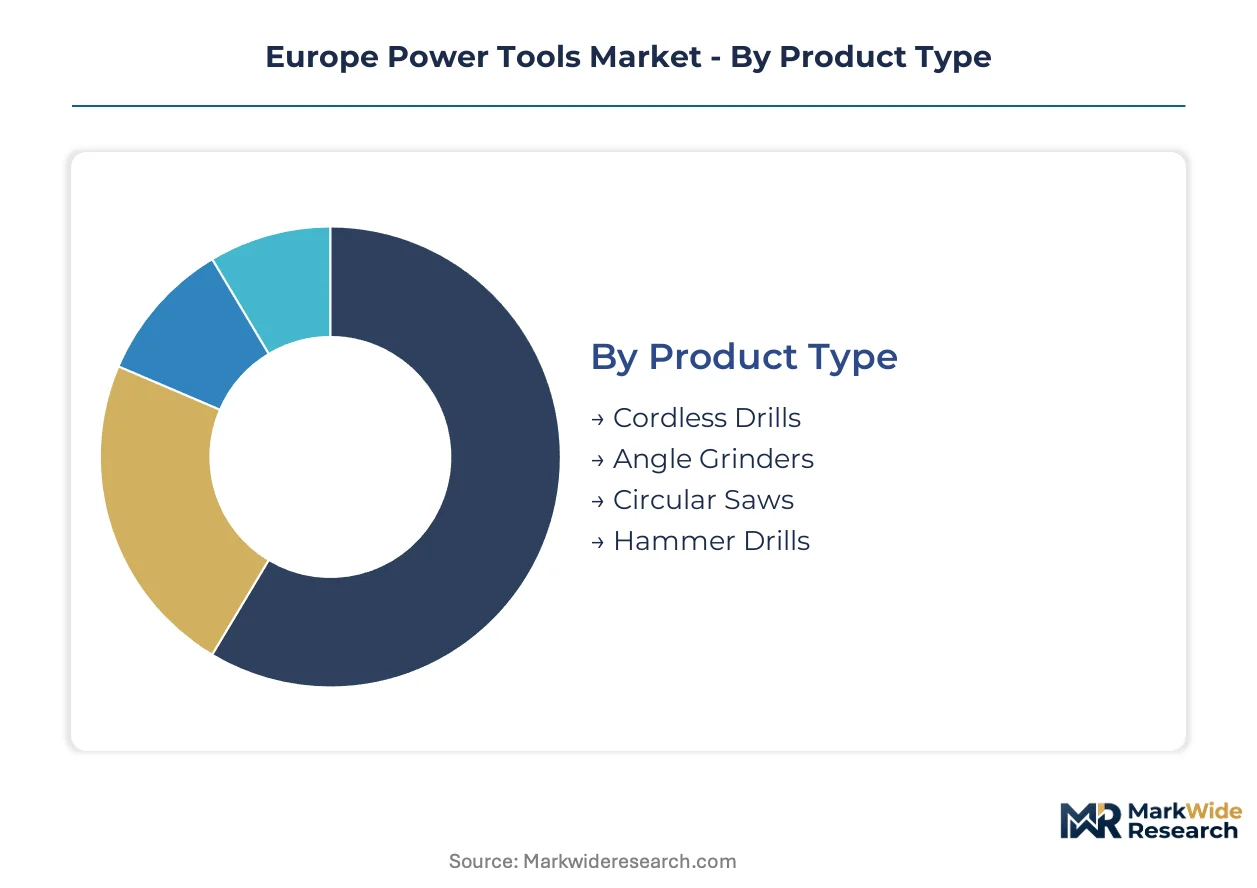
Segmentation in the Europe power tools market reveals how procurement patterns diverge across professional and consumer tiers. Technical specifications, battery platform compatibility, and channel accessibility determine supplier selection criteria within each category.
Product Type:
Supply concentration in high-torque cordless platforms is tilting manufacturing capacity toward professional-grade assemblies with interchangeable battery ecosystems.
- Cordless Drills:These 12V to 54V DC handheld units deliver 10 Nm to 80 Nm torque for fastening and drilling operations. German residential contractors prioritize runtime-per-charge metrics, compressing supplier selection to firms with proprietary thermal-management IP.
- Angle Grinders:Disc-driven cutting and grinding tools operating at 110V-240V AC or 18V-54V DC generate disproportionate aftermarket attachment revenue through flap disc and wire wheel replenishment cycles.
- Circular Saws:Cordless variants with brushless motors now penetrate Polish construction corridors where mid-sized contractors demand portability without generator dependency.
- Hammer Drills:Rotary-percussion tools for masonry applications retain corded dominance in heavy-torque scenarios despite cordless encroachment in residential renovation.
Cordless drills absorb the bulk of installed capacity; angle grinders are expanding most quickly through consumable attachment economics.
Technology:
Cost tier stratification separates premium brushless architectures from legacy brushed systems, with battery chemistry commanding the decisive price inflection.
- Brushless Motors:Permanent-magnet designs eliminate commutator wear while delivering 15-20% efficiency gains over brushed equivalents. CE marking mandates for electromagnetic compatibility favor established suppliers with dedicated compliance functions.
- Lithium-Ion Batteries:Cell supply concentration in East Asian cathode manufacturing exposes European assemblers to freight volatility and critical mineral procurement friction.
- Pneumatic Systems:Compressed-air tools face phased displacement under EU F-Gas Regulation in automotive assembly cleanrooms, though sunk infrastructure costs slow transition in Northern Italian metalworking clusters.
- Electric Motors:Brushed AC/DC designs serve price-sensitive DIY segments through hardware chains in France and Benelux, where private-label platforms undercut premium OEM positioning.
Brushless motors capture the premium tier margin pool; lithium-ion battery platforms are gaining share fastest as cordless substitution accelerates.
End User:
Volume concentration in construction trades creates procurement scale that shapes distributor inventory and manufacturer R&D allocation.
- Construction Industry:Professional contractors specify fleet-management subscriptions with predictive maintenance telemetry. Warsaw-Kraków corridor urbanization drives concentrated demand for cordless fastening systems.
- Automotive Sector:Assembly plants mandate sealed brushless motors for cleanroom fastening applications as EU F-Gas Regulation phases down hydrofluorocarbon pneumatic systems.
- DIY Enthusiasts:Seasonal demand spikes through online retail and hardware chains favor 12V-18V entry-level platforms with standardized charger compatibility.
- Manufacturing Facilities:Metal fabrication shops in Germany and Italy exhibit switching friction from legacy compressed-air infrastructure, slowing cordless adoption in heavy-torque grinding.
Construction industry procurement absorbs the bulk of professional-grade unit shipments; automotive sector specification is climbing the fastest as regulatory chemistry constraints tighten.
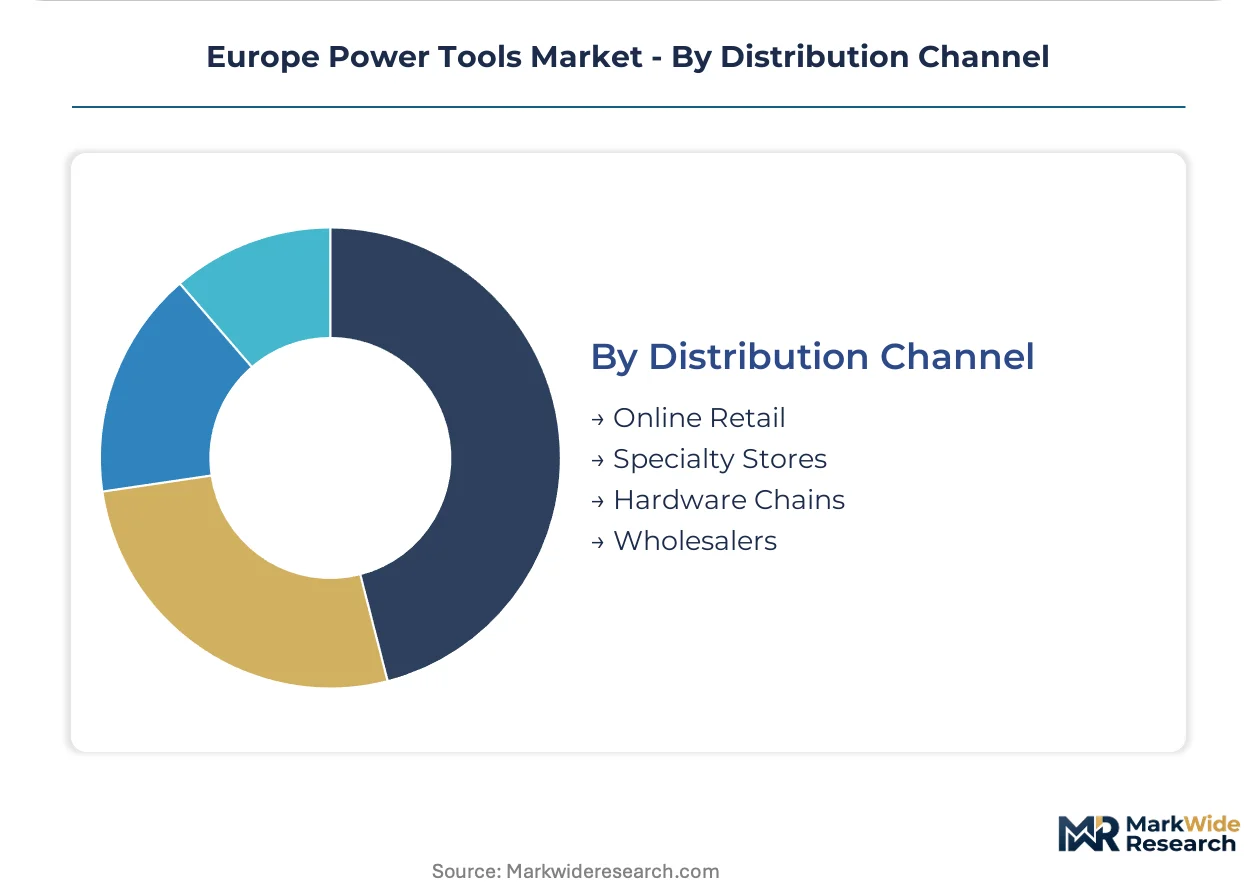
Distribution Channel:
Customer type differentiation separates integrated procurement portals serving trade professionals from transactional retail serving intermittent users.
- Online Retail:E-commerce platforms capture DIY seasonal spikes and price-sensitive municipal maintenance crews through transparent specification comparison and bundled warranty extensions.
- Specialty Stores:Independent distributors with technical staff anchor loyalty among trade professionals requiring application-specific guidance and same-day spare parts availability.
- Hardware Chains:Big-box retailers in France and Benelux deploy private-label battery platforms that commoditize mid-range cordless specifications.
- Wholesalers:Bulk procurement intermediaries serve construction consortia with volume pricing and fleet-management subscription integration.
Hardware chains move the bulk of entry-tier volume; online retail is expanding most quickly through procurement portal digitization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German manufacturing absorbs the bulk of premium-grade power tool consumption, while Polish assembly plants and Romanian production facilities tilt the region toward net supply expansion. CE marking mandates and REACH compliance create regulatory friction that favors established suppliers with dedicated certification functions.
Germany
Residential contractors in Bavaria and North Rhine-Westphalia specify runtime-per-charge metrics as primary selection criteria for cordless platforms. The KBA enforces machinery safety standards that compress supplier qualification timelines for brushless motor architectures. Stuttgart's metalworking clusters exhibit switching friction from legacy pneumatic infrastructure, slowing cordless adoption in heavy-torque grinding applications.
Poland
Urbanization along the Warsaw-Kraków corridor generates concentrated demand for cordless drilling and fastening systems among mid-sized construction consortia. The Polish Centre for Accreditation coordinates CE marking conformity assessments that gate market access for Asian-origin battery platforms. Gdańsk port expansion drives fleet turnover among marine fabrication contractors specifying sealed brushless motors for corrosion resistance.
Italy
Metal fabrication shops in Lombardy and Emilia-Romagna retain compressed-air infrastructure that creates switching costs for cordless alternatives in high-torque cutting operations. ECHA enforcement of REACH restrictions on housing polymers elevates material qualification expenses for coating chemistries used in tool housings. Turin's automotive assembly plants mandate battery-electric fastening systems as EU F-Gas Regulation phases down hydrofluorocarbon pneumatic alternatives.
Romania
Greenfield production facilities in Transylvania and Banat offer proximity to Western European distribution networks with lower labor cost structures for mid-range tool assembly. The Romanian Accreditation Association administers Ecodesign directive compliance testing that gates efficiency certification for corded electric motors. Cluj-Napoca's emerging industrial parks attract battery-pack assembly investments serving Central European OEM demand.
France
Municipal maintenance crews in Île-de-France and Auvergne-Rhône-Alpes favor private-label battery platforms that undercut premium OEM pricing through hardware chain distribution. ANSM oversight of electromagnetic compatibility testing adds certification lead times for brushless motor controllers. Lyon's construction equipment distributors anchor loyalty among trade professionals through integrated procurement portals bundling hardware and consumable replenishment.
Europe Power Tools Market Competitive Landscape
The competitive structure tilts toward diversified industrial conglomerates with captive battery chemistry and motor-control IP portfolios. German and Japanese headquarters locations dominate the premium tier, while Taiwanese and American entities compete on volume scale through hardware chain distribution. Two strategic archetypes anchor positioning: full-ecosystem suppliers bundling interchangeable battery platforms across tool categories, and fleet-management specialists monetizing usage-based subscriptions with predictive maintenance telemetry. Capacity expansion into Romanian manufacturing clusters and strategic partnerships with East Asian cell suppliers constitute the dominant competitive moves.
Among diversified industrial conglomerates, Robert Bosch GmbH and Techtronic Industries exemplify the full-ecosystem archetype through extensive service networks and battery-platform bundling. Hilti Corporation occupies a distinct position within the fleet-management tier, anchoring recurring revenue models among cost-conscious construction consortia. Makita Corporation represents the premium cordless specialist segment, competing on Lithium-Ion battery density benchmarks. These three entities collectively illustrate how motor-control IP, thermal management expertise, and procurement portal digitization separate viable suppliers from commoditized competitors.
| Leading Market Players |
|---|
| Techtronic Industries |
| Hilti Corporation |
| Robert Bosch GmbH |
| FEIN |
| Metabo |
| Stanley Black & Decker |
| Atlas Copco AB |
| Emerson Electric |
| Makita Corporation |
| Others |
Pricing and Supply Chain Analysis
Captive battery-pack assembly in Cluj-Napoca and Transylvania anchors both cost positioning and procurement leverage for mid-range European tool manufacturers. This backward integration into lithium-ion cell housing reduces exposure to East Asian cathode pricing volatility while compressing landed costs for Warsaw-Kraków corridor contractors.
Pricing Analysis
Margin tightening in the DIY tier reflects hardware chain private-label proliferation across France and Benelux. Three-tier pricing structure across premium brushless, standard cordless, and economy corded levels separates runtime benchmarks from thermal-management IP. Pricing pressure intensifies as municipal maintenance crews migrate to online procurement portals with transparent specification comparison. Construction consortia exhibit lowest price sensitivity due to fleet-management subscription bundling.
Supply Chain Analysis
Direct-to-specialty-distributor channels handle trade professional demand requiring same-day spare parts availability. Cell manufacturing concentrates in China, South Korea, and Japan, drawing from cobalt, nickel, and lithium carbonate feedstocks. Single-source vulnerability in East Asian cathode supply exposes European assemblers to freight volatility and critical mineral procurement friction. Distribution runs through independent distributors with technical staff, hardware chains, and integrated procurement portals serving distinct buyer archetypes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe power tools market functions as a vertical-integration race where captive battery chemistry and motor-control IP determine margin retention. Players pursue upstream control over lithium-ion cell housing and downstream fleet-management telemetry to escape commodity pricing.
For Market Incumbents: Deepen thermal-management R&D investment to extend runtime benchmarks beyond Makita Corporation's lithium-ion density positioning. Add Romanian assembly capacity in Banat to serve Polish construction corridor demand with reduced logistics exposure. Defend against hardware chain private-label erosion through proprietary battery-platform lock-in and predictive maintenance subscription attach rates. For New Entrants and Emerging Players: Launch via online retail procurement portals targeting price-sensitive municipal maintenance crews in French Auvergne-Rhône-Alpes with CE-marked entry-tier platforms. Penetrate the DIY enthusiast segment through transparent specification comparison and bundled warranty extensions. Exploit certification gaps for Asian-origin battery platforms awaiting Polish Centre for Accreditation conformity assessments. For Investors and Strategic Acquirers: Exit pathways concentrate in fleet-management subscription specialists with predictive maintenance telemetry and recurring revenue visibility. Long-term viability hinges on backward integration into cell housing or downstream control over integrated procurement portals. Monitor Ecodesign directive tightening velocity as inflection indicator for corded motor efficiency investment returns.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Platform Standardization | Interoperability investments reduce contractor fleet complexity and anchor single-brand loyalty across tool categories. |
| Backward Integration into Cell Housing | Romanian assembly capacity lowers landed costs and mitigates East Asian cathode supply concentration risk. |
| Fleet-Management Subscription Launch | Usage-based billing with predictive maintenance telemetry opens recurring revenue streams among construction consortia. |
| Brushless Motor IP Acquisition | Proprietary winding and thermal-management expertise compresses supplier qualification timelines under KBA machinery safety standards. |
| Online Procurement Portal Partnership | Digital bundling of hardware, warranty extensions, and consumable replenishment captures municipal maintenance crew demand. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this Europe power tools analysis. Primary interviews with plant engineers at German metalworking clusters, procurement leads at Polish construction consortia, aftermarket service heads at French distributors, and channel partners in Romanian industrial parks combined with ECHA REACH restriction databases, EU F-Gas Regulation compliance filings, and CE marking conformity assessments. Bottom-up unit shipment modeling triangulated against top-down construction spending correlations.
Granularity-level modeling operated at product type, technology tier, end-user segment, and distribution channel dimensions across the analysis window. CAGRs derived from segment-specific volume trajectories weighted by Polish urbanization velocity, German brushless motor adoption curves, and Italian pneumatic infrastructure retirement friction. Forecast inputs included lithium-ion cell supply pipeline visibility and Ecodesign directive efficiency threshold schedules.
The model assumes a particular technology adoption path; alternative pathways for solid-state battery chemistry or hydrogen pneumatic systems would alter the outlook. Forecasts reflect base-case assumptions regarding REACH compliance cost trajectories and East Asian cathode supply stability. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Europe Machine Tools Market
Tools
Leather Embossing Machine Market
Tools
Water Pump Pliers Market
Tools
Fatigue Testing Machine Market
Tools
Telescopic Tool Boxes Market
Tools
Construction Anchors Market
Tools
Crimping Tool Market
Tools
Portable Pressure Washer Market
Tools
China Power Tools Market
Tools
Industrial Plate Bending Machines Market
Tools
Air Hammer Market
Tools
Orbital Recip Saw Market
Tools
Tool Boxes Market
Tools
Welding Products Market
Tools
Grinding Machines Market
Tools
Press Machine Market