
 Water Quality Monitoring Systems Market | 2026-2036
Water Quality Monitoring Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Water Quality Monitoring Systems Market Analysis
Market Context
Subscription-based calibration and remote diagnostics is recalibrating how vendors monetize hardware deployments, shifting revenue toward recurring service contracts. Danaher Corporation leverages its diagnostics heritage to bundle consumable reagents with instrument leases, locking in multi-year revenue streams. Xylem anchors its competitive position through integrated software platforms that unify sensor fleets across distributed water networks. HORIBA, Ltd. specializes in high-precision optical modules for regulatory-grade compliance monitoring, occupying a premium tier in environmental agency procurement.
Technical Definition and Segment Structure
Water quality monitoring systems encompass integrated hardware-software platforms that measure chemical, physical, and biological parameters—such as dissolved oxygen, turbidity, pH, and heavy metal concentrations—to assess water safety and ecosystem health. These systems deploy electrochemical or optical transducers with detection thresholds ranging from parts-per-million to parts-per-billion, serving industrial discharge compliance, drinking water safety, and environmental protection mandates. Portable monitors lead unit shipments due to emergency response and field audit requirements, though fixed station monitors capture the dominant share of lifetime value through perpetual data streams and maintenance contracts. Multi-parameter sensors represent the fastest-growing product configuration as utilities consolidate discrete probes to reduce capital footprint and simplify telemetry integration.
Regulatory Framework and Outlook
The US EPA enforces the Safe Drinking Water Act and Clean Water Act, mandating continuous monitoring for regulated contaminants and driving replacement of legacy grab-sample methods with automated systems. The EU Water Framework Directive and Drinking Water Directive impose comparable obligations across member states, while China's MEE implements surface water quality standards that expand monitoring network density. India's CPCB mandates online effluent monitoring for industrial clusters, creating localized demand spikes. Stakeholders must track how regulatory granularity evolves—whether through emerging contaminant lists or real-time reporting mandates—to align R&D pipelines with enforceable detection requirements.
Market Dynamics
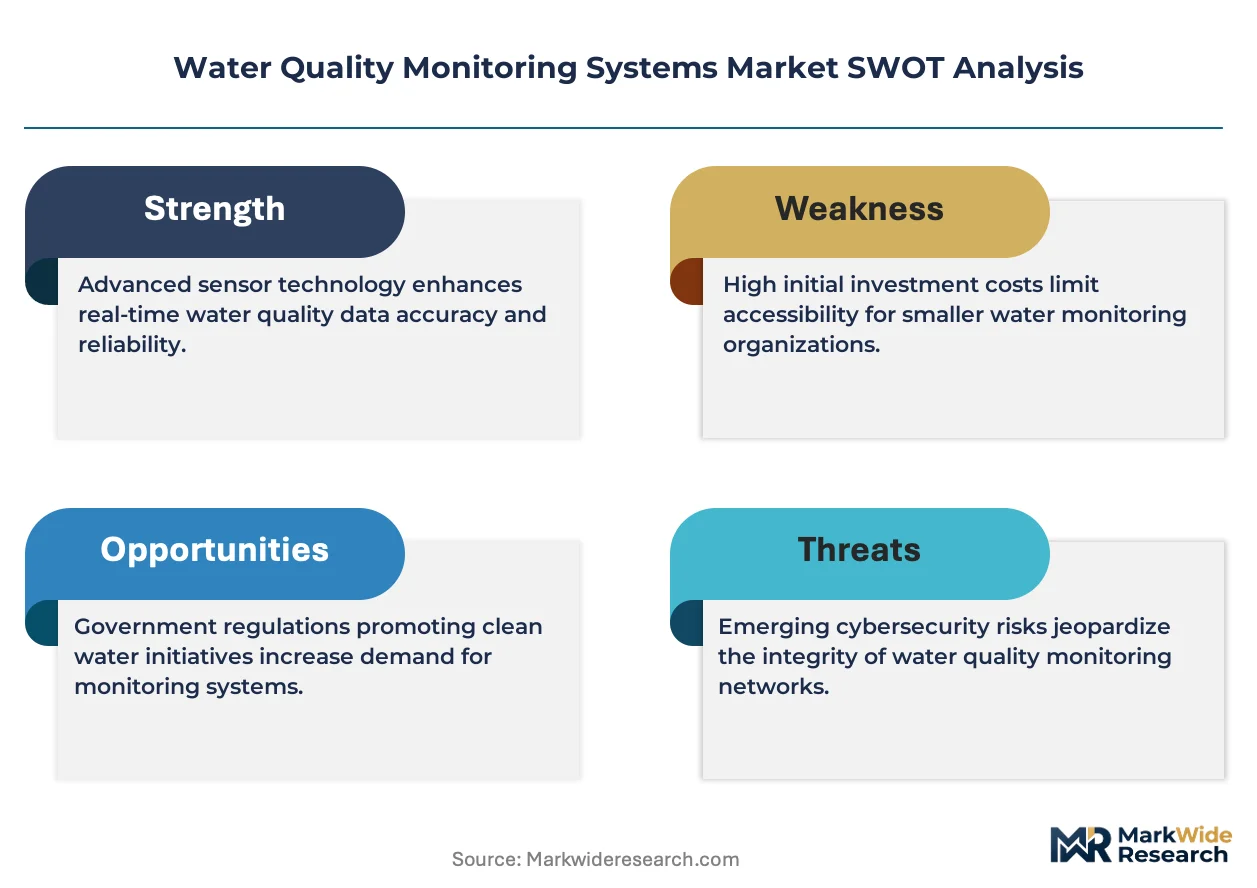
Sensor fusion architectures are compressing hardware margins while elevating software and analytics to primary profit centers, forcing vendors to restructure from equipment sellers to data service providers.
Growth Catalysts
- EU Drinking Water Directive revisions:Real-time monitoring mandates for emerging contaminants are accelerating replacement of legacy grab-sample systems with continuous analyzers across municipal networks.
- Industrial cluster expansion in India:CPCB-mandated online effluent monitoring for textile and pharmaceutical zones is generating localized demand spikes for multi-parameter probe stations.
- Optical sensor miniaturization:Solid-state photonic transducers are displacing electrochemical cells in portable field instruments, extending deployment cycles and reducing calibration frequency.
Market Restraints
- Reference reagent supply concentration:Certified standard solutions for regulatory compliance traceability are concentrated among three European specialty chemical suppliers, creating input vulnerability.
- MEMS fabrication bottlenecks:Precision microfluidic channels for lab-on-chip analyzers face capacity constraints at foundries serving automotive and consumer electronics priorities.
- Interoperability friction from proprietary protocols:Manufacturer-specific data formats impede sensor fleet consolidation, forcing utilities into single-vendor lock-in or expensive middleware development.
Strategic Opportunities
- US EPA Lead and Copper Rule implementation:Revised corrosion control monitoring requirements are opening replacement cycles for aging distribution system sensors in mid-sized municipal utilities.
- Edge AI inference on sensor nodes:On-device anomaly detection is converging with low-power wide-area telemetry to enable predictive maintenance without cloud dependency.
- Agricultural runoff monitoring in Brazil:ANVISA and state environmental agencies are expanding watershed monitoring networks for pesticide compliance, creating greenfield deployment opportunities.
Industry Challenges
- Field calibration technician scarcity:Specialized electrochemistry expertise for EPA Method compliance verification is concentrating among aging workforces in rural utility districts.
- Legacy SCADA integration complexity:Proprietary Modbus and DNP3 implementations from 1990s-era plant control systems resist API-based data extraction without hardware retrofit.
Report Scope
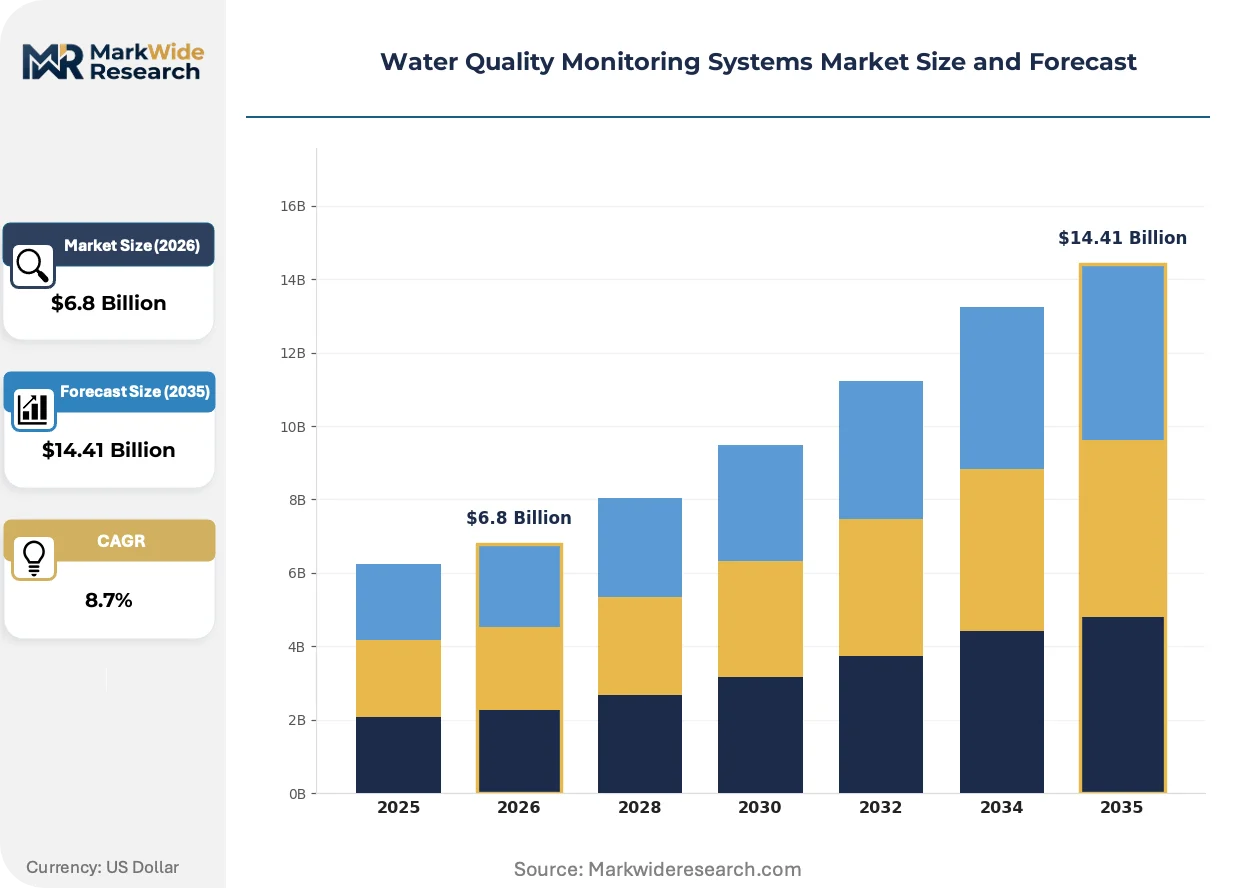
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Water Quality Monitoring Systems Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.41 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Monitors, Fixed Station Monitors, Multi-parameter Sensors, Submersible Sensors End User: Environmental Agencies, Water Treatment Facilities, Research Institutes, Agricultural Sector Technology: Electrochemical Sensors, Optical Sensors, Biological Sensors, Advanced Analytical Techniques Application: Surface Water Monitoring, Groundwater Quality, Wastewater Treatment, Aquaculture Management |
| Companies Covered | Danaher Corporation, Xylem, HORIBA, Ltd., General Electric Company, Evoqua Water Technologies, Emerson Electric Co., Siemens, Agilent Technologies, Inc., Thermo Fisher Scientific Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Water Quality Monitoring Systems Market Emerging Trajectories
Digital twin architectures are migrating from predictive maintenance into real-time water quality simulation, compressing the feedback loop between sensor measurement and treatment process adjustment.
Solid-state optical sensors is unifying dissolved oxygen, turbidity, and chlorophyll detection into single-chip platforms. German utility digitization programs are deploying these at scale across Rhine basin monitoring networks. The technology is unifying previously discrete instrument categories, collapsing vendor portfolios and procurement cycles from multi-year to single-source agreements.
REACH authorization requirements for mercury-containing electrodes are accelerating electrochemical sensor redesign across EU member states. Industrial discharge permit holders must replace polarographic dissolved oxygen probes with optical alternatives before sunset dates. Food and beverage processors in the Netherlands and Belgium are front-running compliance through early optical platform adoption.
Subscription calibration services are displacing in-house maintenance teams at North American municipal utilities. Third-party service providers now handle sensor validation, reagent replenishment, and EPA-compliant documentation. This pattern is most visible in California and Texas water districts facing staffing constraints and audit scrutiny under Safe Drinking Water Act enforcement.
Water Quality Monitoring Systems Market Segmentation
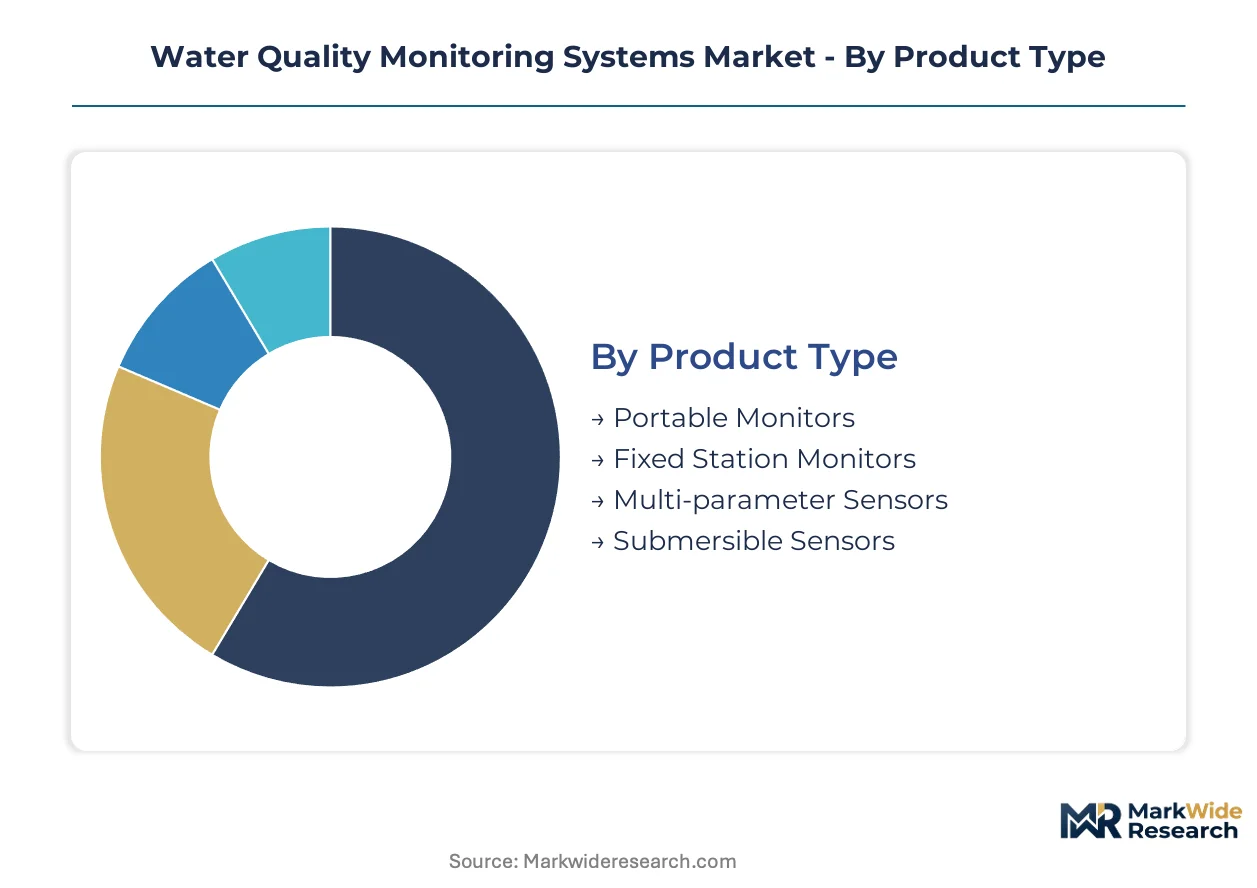
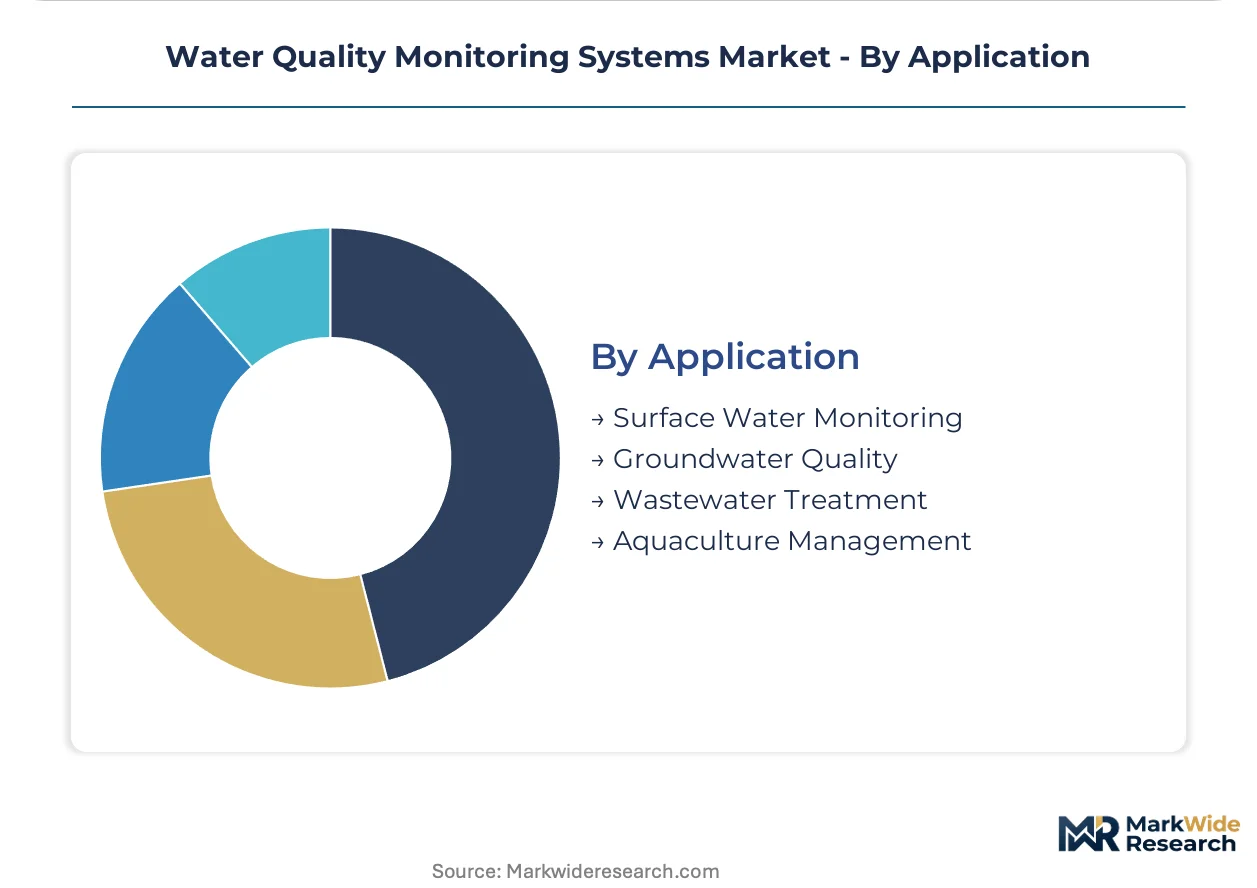
Water quality monitoring systems fragment across four distinct dimensions that shape procurement patterns and vendor positioning. Product configuration determines capital intensity and maintenance cadence. End-user requirements diverge sharply between regulatory compliance and operational optimization. Technology selection drives calibration protocols and detection thresholds. Application context dictates sensor durability and telemetry architecture.
Product Type:
Capital allocation priorities separate emergency response deployments from permanent network infrastructure.
- Portable Monitors:Handheld electrochemical or optical units with battery-powered operation and field-swappable probe heads. Demand concentrates in California and Texas water districts facing Safe Drinking Water Act audit scrutiny and staffing constraints. Emergency response teams and field auditors drive replacement cycles.
- Fixed Station Monitors:Permanently installed multi-probe assemblies with continuous telemetry to SCADA or cloud platforms. German utility digitization programs across Rhine basin networks prioritize these for real-time distribution system oversight. Perpetual data streams and multi-year maintenance contracts capture dominant lifetime value.
- Multi-parameter Sensors:Consolidated probe platforms measuring pH, dissolved oxygen, turbidity, and conductivity through unified housings. Utilities deploy these to reduce capital footprint and simplify integration.
- Submersible Sensors:Pressure-rated transducers for deep reservoir, ocean, or sewer line deployment. Industrial discharge monitoring in Indian textile clusters generates localized procurement.
Volume sits with fixed station monitors; growth tilts toward multi-parameter sensors.
End User:
Regulatory enforcement intensity varies dramatically across institutional buyer categories.
- Environmental Agencies:National and state regulators operating compliance networks with certified reference standards. The US EPA and China's MEE drive optical sensor adoption for emerging contaminant detection. Procurement mandates traceability documentation and third-party validation.
- Water Treatment Facilities:Municipal and industrial plants optimizing coagulation, disinfection, and corrosion control. Mid-sized US utilities accelerate replacement under revised Lead and Copper Rule requirements. Subscription calibration services displace in-house maintenance teams.
- Research Institutes:Academic and government laboratories requiring ppb-level detection for method development. Funding cycles drive irregular procurement patterns.
- Agricultural Sector:Irrigation districts and large-scale farms monitoring nutrient runoff and salinity. Brazilian watershed networks expand for ANVISA pesticide compliance.
Environmental agencies anchor procurement volume; water treatment facilities show the steepest expansion trajectory.
Technology:
Detection principle selection determines calibration frequency, reagent dependency, and regulatory acceptance.
- Electrochemical Sensors:Ion-selective electrodes and amperometric cells measuring pH, conductivity, and specific ions through redox reactions. REACH authorization deadlines for mercury electrodes accelerate displacement in EU member states. Industrial discharge permit holders face sunset-driven replacement cycles.
- Optical Sensors:Solid-state photonic transducers using absorbance, fluorescence, or scattering for turbidity, chlorophyll, and dissolved oxygen. German utilities deploy these at scale for extended deployment cycles and reduced calibration needs. Food and beverage processors in the Netherlands and Belgium front-run compliance through early adoption.
- Biological Sensors:Whole-cell or enzyme-based detection systems for toxicity screening and pathogen indication. Research applications dominate commercial deployment.
- Advanced Analytical Techniques:Lab-on-chip microfluidics and spectroscopic platforms for multi-analyte quantification. MEMS fabrication bottlenecks constrain foundry capacity.
Electrochemical sensors retain installed base dominance; optical platforms gain share fastest.
Application:
Physical deployment environment dictates sensor housing specifications and data transmission requirements.
- Surface Water Monitoring:River, lake, and reservoir networks tracking eutrophication, sediment loading, and thermal pollution. China's MEE surface water quality standards expand network density across provincial jurisdictions.
- Groundwater Quality:Well-based monitoring for aquifer protection and remediation verification. Agricultural nitrate tracking drives deployment in intensive farming regions.
- Wastewater Treatment:Influent and effluent monitoring for process control and discharge permit compliance. India's CPCB mandates online systems for industrial cluster effluent.
- Aquaculture Management:Dissolved oxygen and ammonia tracking in intensive fish and shellfish operations. Edge AI inference enables predictive aeration control without cloud dependency.
Wastewater treatment commands capital deployment; aquaculture management climbs the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in Germany, Japan, and the United States, while consumption tilts toward China and India where regulatory mandates expand network density. Sensor fabrication and optical module assembly cluster near precision manufacturing hubs. Deployment demand spreads across municipal utilities and industrial discharge monitoring.
United States
Mid-sized municipal utilities accelerate sensor replacement cycles under the EPA's revised Lead and Copper Rule corrosion control requirements. California and Texas water districts facing Safe Drinking Water Act audit scrutiny contract third-party calibration services. The Southwest confronts drought-driven groundwater quality monitoring expansion across agricultural irrigation districts.
Germany
Rhine basin utility digitization programs deploy solid-state optical sensors at scale for real-time distribution network oversight. REACH authorization deadlines for mercury electrodes force electrochemical probe redesign across industrial discharge permit holders. Food and beverage processors in the Netherlands and Belgium front-run compliance through early optical platform adoption.
China
MEE surface water quality standards expand provincial monitoring network density across river and reservoir systems. Yangtze River Delta municipalities consolidate discrete probes into multi-parameter sensors to reduce capital footprint. Textile and pharmaceutical clusters in Zhejiang and Jiangsu provinces face intensifying online effluent monitoring mandates.
India
CPCB-mandated online effluent monitoring for industrial zones generates localized demand spikes for multi-parameter probe stations. Textile processing clusters in Gujarat and Tamil Nadu deploy fixed station monitors for discharge permit compliance. Agricultural nitrate tracking drives groundwater sensor deployment in intensive farming regions of Punjab and Haryana.
Brazil
ANVISA and state environmental agencies expand watershed monitoring networks for pesticide compliance across agricultural runoff zones. São Paulo and Minas Gerais utilities pilot edge AI inference on sensor nodes for predictive maintenance. Aquaculture operations in southern states adopt dissolved oxygen monitoring for intensive fish production systems.
Water Quality Monitoring Systems Market Vendor Landscape
Top-tier vendors anchor premium regulatory-grade instrumentation, while mid-tier specialists compete on modular configurations and regional service density. The vendor base stratifies across three tiers: diversified conglomerates with diagnostics heritage, water-focused pure-plays with integrated software platforms, and component specialists supplying optical transducers and electrochemical cells. Strategic moves concentrate on sensor fusion architectures that compress hardware margins while elevating analytics subscriptions, plus backward integration into reagent supply chains to lock recurring revenue streams.
Among diversified technology conglomerates, Danaher Corporation and General Electric Company exemplify archetypes that bundle consumable reagents with instrument leases. Xylem occupies a position within the water-focused pure-play tier, anchoring competitive positioning through integrated software platforms. HORIBA, Ltd. represents the precision component specialist archetype, supplying optical modules for regulatory-grade compliance monitoring. These three patterns—conglomerate bundling, platform integration, and component specialization—structure competitive rivalry across procurement cycles.
| Leading Market Players |
|---|
| Danaher Corporation |
| Xylem |
| HORIBA, Ltd. |
| General Electric Company |
| Evoqua Water Technologies |
| Emerson Electric Co. |
| Siemens |
| Agilent Technologies, Inc. |
| Thermo Fisher Scientific Inc. |
| Others |
Supply Flow & Price Mechanics
Regulatory-grade certification tiers split procurement between EPA-compliant optical systems and uncertified field instruments, with that bifurcation driving divergent supply chain footprints and margin structures across German utility digitization programs and Indian textile cluster deployments. Premium instrumentation commands captive reagent supply chains while commodity probes compete on spot-market component sourcing.
Pricing Analysis
Margin tightening in portable monitors reflects solid-state photonic displacement of electrochemical cells as REACH mercury electrode deadlines accelerate platform replacement. Subscription-based calibration services now dominate municipal utility procurement in California and Texas, bundling sensor validation with EPA-compliant documentation. Three-tier pricing structure across premium, standard, and economy levels separates regulatory-grade optical modules from field-audit handhelds and uncertified OEM components. Water treatment facilities show highest price sensitivity due to staffing constraints; environmental agencies demonstrate lowest sensitivity given traceability mandates.
Supply Chain Analysis
Regional distribution centers in Germany, Japan, and the United States anchor hub-and-spoke fulfillment patterns for precision optical modules and electrochemical cell assemblies. Critical inputs draw from three European specialty chemical suppliers for certified reference reagents, Taiwanese foundries for MEMS microfluidic channels, and Japanese component houses for solid-state photonic transducers. Single-source vulnerability concentrates in mercury-free electrode substrates facing REACH authorization bottlenecks. Distribution runs through authorized service networks for calibration-dependent systems and direct OEM channels for portable instruments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
MEMS fabrication capacity constraints at foundries serving automotive and consumer electronics priorities prop pricing power for vendors with captive microfluidic production. Supply scarcity favors incumbents with backward integration into precision manufacturing.
For Market Incumbents: Lock in multi-year reagent supply agreements with European specialty chemical houses before REACH authorization deadlines tighten input availability. Secure foundry allocation for MEMS microfluidic channels through equity partnerships or capacity reservations. Optical sensor miniaturization threatens electrochemical installed bases; accelerate platform consolidation to unified photonic architectures. For New Entrants and Emerging Players: Edge AI inference modules on low-power sensor nodes offer entry points into Brazilian aquaculture operations and São Paulo utility pilot programs where predictive maintenance capabilities remain underdeveloped. Agricultural runoff monitoring in Minas Gerais watershed networks presents the most penetrable greenfield segment. Partner with regional telemetry providers for LPWAN integration rather than building proprietary communication stacks. For Investors and Strategic Acquirers: Re-rating potential sits with component specialists commanding optical transducer IP given EU Drinking Water Directive real-time monitoring mandates. Long-term viability hinges on recurring revenue attachment rates exceeding hardware depreciation cycles. Watch for CPCB enforcement intensity in Gujarat and Tamil Nadu textile clusters as inflection indicator for Indian market acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Reagent Supply | Captive production of certified reference solutions locks recurring revenue streams under EPA Method compliance requirements. |
| Platform Integration | Unified software layers consolidating sensor fleets across distributed networks anchor Xylem's competitive positioning in German utility digitization programs. |
| Acquisition of Specialist Firm | Optical module specialists with regulatory-grade certifications command premium multiples as REACH deadlines accelerate electrochemical displacement. |
| Geographic Expansion | Direct presence in Zhejiang and Jiangsu provinces captures MEE-mandated online effluent monitoring demand from textile and pharmaceutical clusters. |
| Product Launch | Multi-parameter sensor platforms reduce capital footprint and simplify telemetry integration for mid-sized US utilities under revised Lead and Copper Rule requirements. |
Methodological Framework
Document review covered regulatory filings from EPA, MEE, and CPCB, complemented by interviews with municipal utility operations directors, industrial discharge compliance officers, optical sensor R&D leads, and third-party calibration service providers. Secondary sources included customs trade data for instrument and reagent flows, SEC 10-K disclosures from diversified technology conglomerates, and utility procurement databases tracking SCADA integration spend. Bottom-up unit economics for sensor deployments were triangulated against top-down market sizing from national monitoring network expansion mandates.
Historical replacement cycle patterns were cross-referenced against expert panel inputs on regulatory enforcement intensity and technology substitution timelines across the projection horizon. Segmentation modeling captured product configuration, end-user category, detection principle technology, and application context dimensions. CAGRs were derived from installed base growth net of obsolescence, with industry-specific inputs including EPA corrosion control monitoring requirements and EU REACH authorization sunset schedules.
Forecast precision tightens around the base case; tail outcomes carry wider variance under foundry capacity reallocation to automotive MEMS demand or prolonged CPCB enforcement gaps in Indian industrial clusters. Periodic stress-testing of base assumptions is recommended given regulatory granularity evolution around emerging contaminant lists and real-time reporting mandates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Environmental Monitoring
Global Indoor Air Quality Solutions Market
Environmental Monitoring
Green Mining Market
Environmental Monitoring
Global Weather Forecasting Services Market
Environmental Monitoring
Global Environmental Remediation Market
Environmental Monitoring
Asia Pacific Air Quality Monitoring Market
Environmental Monitoring
Ecotoxicological Studies Market
Environmental Monitoring
Carbon Monoxide Analyzers Market
Environmental Monitoring
Environment Testing Services Market
Environmental Monitoring
US Environmental Testing Market
Environmental Monitoring
South America Air Quality Monitoring Market
Environmental Monitoring
Global Environmental Sensor Market
Environmental Monitoring
Water Pipeline Leak Detection System Market
Environmental Monitoring
Air Quality Monitoring Equipment Market
Environmental Monitoring
Environmental Test Equipment Market
Environmental Monitoring
Real-Time Flood Monitoring and Warning System Market
Environmental Monitoring
United States Erosion Sediment Control Market