
 Global Environmental Sensor Market | 2026-2036
Global Environmental Sensor Market Size, Share, and Industry Trends Forecast 2026-2036
Global Environmental Sensor Market Analysis
Project finance for municipal sensor networks is tilting competition toward vendors with balance-sheet capacity to underwrite decade-long service contracts. Siemens AG leverages its project-lending relationships to anchor European smart-city deployments. Honeywell International Inc. sustains manufacturing scale across North American environmental compliance programs. Bosch Sensortec GmbH specializes in miniaturized gas-sensing modules that occupy premium slots in portable air-quality instruments.
An environmental sensor converts physical or chemical parameters—temperature, humidity, gas concentration, particulate density, or luminous intensity—into quantifiable electrical signals, typically operating across detection ranges from parts-per-billion to percentage-level concentrations with response times under thirty seconds. These instruments serve industrial safety, regulatory compliance, and ecological research by enabling real-time ambient monitoring. Gas sensors lead product-type revenue because petrochemical and utility sectors require continuous emissions surveillance, while IoT-Based technology grows fastest as edge-computing architectures reduce latency for distributed monitoring grids. Wireless deployments dominate weather-station applications where cellular or LoRa backhaul eliminates cabling across remote terrain.
The US EPA mandates ambient air-quality standards that shape sensor accuracy requirements and calibration protocols for federal monitoring stations. The EU Green Deal and F-Gas Regulation tighten emissions-accounting rules, forcing industrial operators across Germany and France to deploy continuous monitoring arrays. China's MEE enforces real-time pollution disclosure from heavy industry, creating captive demand for domestically certified instruments. Stakeholders must weigh certification reciprocity between jurisdictions against the cost of maintaining parallel product lines for divergent regulatory test methods.
Market Dynamics
Project finance structures for municipal sensor networks are consolidating vendor selection around balance-sheet capacity to absorb decade-long service obligations, tilting procurement toward industrial conglomerates with captive lending arms.
Growth Catalysts
- EU Green Deal disclosure mandates:Industrial operators across Germany and France must deploy continuous emissions monitoring arrays, creating installed-base expansion for certified instrument suppliers.
- Edge-computing architectures:IoT-based sensor grids with localized data processing reduce latency for distributed air-quality networks in Seoul and Barcelona smart-city deployments.
- China's MEE enforcement tightening:Real-time pollution disclosure requirements from heavy industry in the Yangtze River Delta and Pearl River Delta generate captive demand for domestically certified monitoring equipment.
Market Restraints
- MEMS fabrication concentration:Foundry capacity for miniaturized gas-sensing modules clusters in Taiwan and South Korea, exposing supply chains to single-source vulnerability.
- Calibration gas cost volatility:Specialty reference gases for sensor validation face price pressure from rare gas extraction constraints, elevating total cost of ownership for precision instruments.
- Cross-jurisdiction certification friction:Divergent test methods between EPA protocols and EU MCERTS standards force parallel product line maintenance, compressing margin on multi-regional deployments.
Strategic Opportunities
- India's industrial corridor buildout:The PLI scheme for electronics manufacturing incentivizes local assembly of air-quality nodes for Delhi-Mumbai freight corridors and smart-city programs.
- Agricultural emissions monitoring:Nitrous oxide and methane sensing for precision agriculture remains underpenetrated, with livestock and rice paddy applications requiring new form-factor development.
- Blockchain-verified data integrity:Convergence of distributed ledger technology with sensor telemetry creates tamper-proof audit trails for carbon-credit verification and ESG reporting.
Industry Challenges
- Cross-disciplinary talent scarcity:Firmware engineers with simultaneous expertise in electrochemical sensing chemistry and wireless protocol stacks command premium compensation, constraining R&D scaling.
- Legacy SCADA integration friction:Brownfield industrial sites in North American utilities require protocol translation layers to mesh new IP-based sensor networks with existing Modbus and DNP3 infrastructure.
- IP licensing complexity in optical sensing:Tunable diode laser absorption spectroscopy patents held by academic consortia create royalty stacking for multi-gas analyzers targeting petrochemical applications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Environmental Sensor Market |
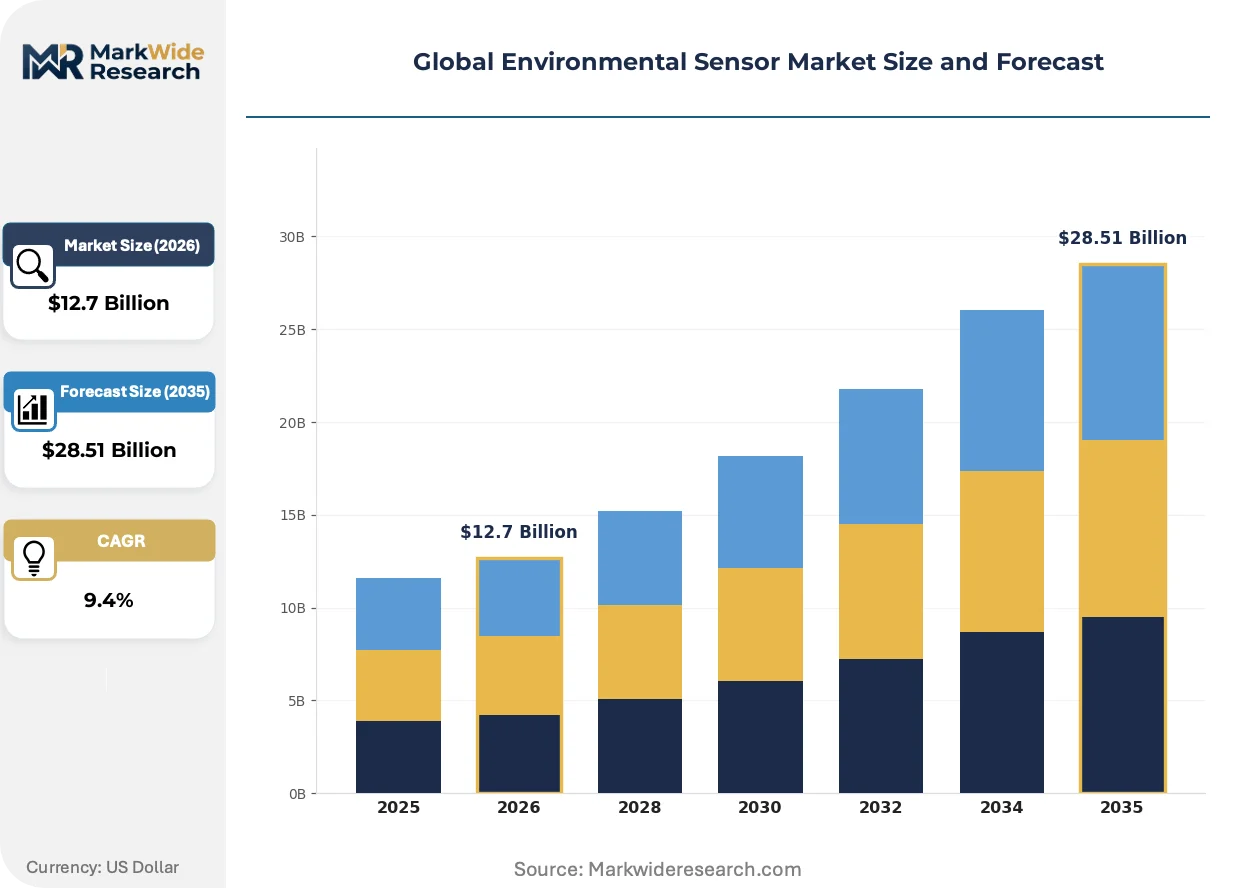
| Market Size in 2026 | $12.7 Billion |
| Market Size in 2035 | $28.51 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gas Sensors, Temperature Sensors, Humidity Sensors, Light Sensors Technology: Wireless, IoT-Based, Electromechanical, Infrared End User: Government Agencies, Research Institutions, Manufacturing Plants, Environmental Organizations Application: Air Quality Monitoring, Water Quality Monitoring, Soil Monitoring, Weather Stations |
| Companies Covered | Honeywell International Inc., Siemens AG, Bosch Sensortec GmbH, Sensirion AG, STMicroelectronics N.V., ams OSRAM AG, Texas Instruments Incorporated, OMRON Corporation, ABB Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Environmental Sensor Market Emerging Trajectories
Optical sensing modalities and AI-driven calibration drift compensation are compressing maintenance intervals while expanding detection selectivity for complex gas matrices.
Metal-oxide semiconductor (MOS) gas sensors detect volatile organic compounds through resistance changes in heated tin-oxide films. Petrochemical facilities in the US Gulf Coast and Rotterdam harbor are retrofitting fixed-point detectors with these lower-cost alternatives to photoionization detectors. The technology is migrating from safety-critical alarm systems to process optimization feedback loops where absolute accuracy matters less than trend detection.
The EU F-Gas Regulation mandates phasedown of hydrofluorocarbon refrigerants and tightens leakage monitoring requirements for commercial cooling systems. Industrial refrigeration operators must install continuous leak-detection arrays with minimum detection thresholds. Packaged food cold-chain logistics across France, Germany, and Italy represent the most affected segment, with warehouse operators consolidating sensor procurement through HVAC service contracts rather than direct instrument purchase.
Performance-based service agreements are displacing capital-equipment sales in municipal air-quality monitoring. City governments in Barcelona, Seoul, and São Paulo now contract for guaranteed data-availability metrics rather than owning sensor hardware. This shift concentrates vendor risk on uptime performance and predictive maintenance execution, rewarding suppliers with remote diagnostic platforms and regional spare-pool networks.
Global Environmental Sensor Market Segmentation
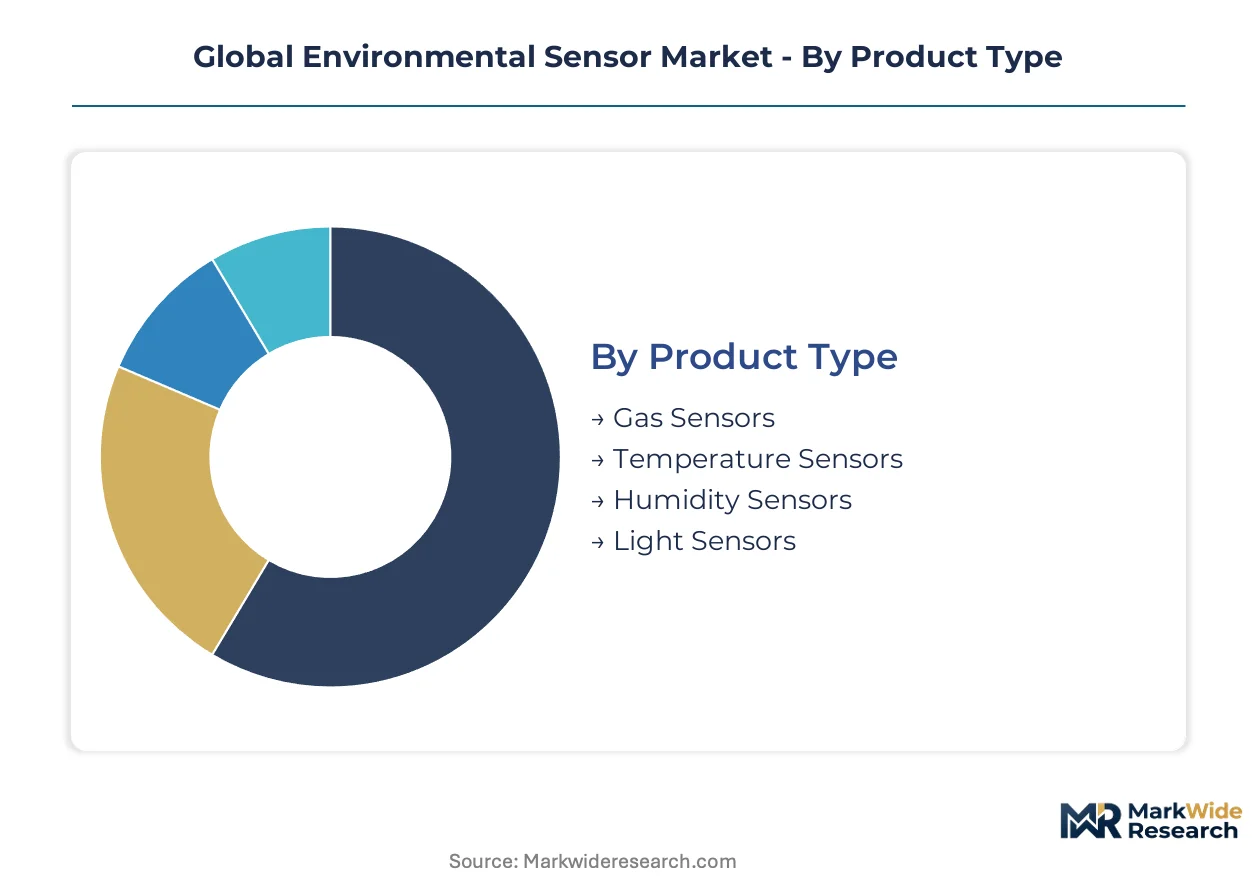
Environmental sensor procurement patterns diverge sharply across application contexts, with industrial safety deployments demanding ruggedized hardware and municipal networks prioritizing service-level agreements over capital ownership. Understanding these segment boundaries clarifies where vendors must build calibration infrastructure versus where wireless connectivity determines contract awards.
Product Type:
After-sales intensity varies dramatically by sensing modality, with electrochemical gas sensors requiring quarterly recalibration against certified reference standards while solid-state humidity chips need only annual validation.
- Gas Sensors:Electrochemical and metal-oxide semiconductor architectures detect volatile organic compounds, carbon monoxide, and nitrogen oxides through resistance or current changes. Petrochemical facilities in the US Gulf Coast and Rotterdam harbor deploy fixed-point arrays for continuous emissions surveillance, driven by EPA and EU F-Gas Regulation leak-detection mandates. By volume, Gas Sensors lead. By growth pace, Light Sensors is ahead.
- Temperature Sensors:Thermocouple, RTD, and thermistor variants span industrial process control from cryogenic storage to combustion monitoring. Cold-chain logistics operators across France, Germany, and Italy embed these in warehouse management systems to satisfy EU Green Deal traceability requirements for refrigerated goods.
- Humidity Sensors:Capacitive and resistive polymer films measure relative humidity for HVAC optimization and agricultural greenhouse control. Semiconductor foundries in Taiwan and South Korea deploy these for cleanroom environmental management where moisture control protects wafer yields.
- Light Sensors:Photodiode and phototransistor devices convert luminous intensity to electrical signals for smart building automation and precision agriculture. Edge-computing architectures in Seoul and Barcelona smart-city deployments integrate these with occupancy detection for municipal energy management.
Margin structures favor Gas Sensors due to recurring calibration service revenue, while Humidity Sensors compete primarily on unit economics in high-volume building automation.
Technology:
Deployment architecture determines whether vendors capture value through hardware margins or long-term data-platform subscriptions, with wireless and IoT-Based systems tilting toward the latter.
- Wireless:Cellular, LoRa, and Zigbee protocols eliminate cabling costs across remote weather stations and distributed air-quality grids. Municipal networks in São Paulo and Barcelona favor these for rapid deployment without trenching permits. Wireless expands most quickly in agricultural and remote monitoring applications where backhaul infrastructure is absent.
- IoT-Based:Edge-computing nodes with localized data processing reduce latency for real-time pollution alerts and predictive maintenance triggers. Smart-city programs in Seoul deploy these for traffic-adaptive air-quality management.
- Electromechanical:Traditional transducer designs with direct electrical output dominate legacy industrial installations where protocol compatibility with existing SCADA systems outweighs connectivity features. North American utilities rely on these for brownfield integration with Modbus infrastructure.
- Infrared:Non-dispersive infrared and tunable diode laser absorption spectroscopy enable selective multi-gas detection for complex petrochemical process streams. Patent licensing from academic consortia elevates cost structures for these precision instruments.
IoT-Based systems command premium pricing through software recurring revenue, while Electromechanical faces substitution pressure from connected alternatives.
End User:
Procurement sophistication separates institutional buyers with dedicated metrology teams from commercial operators outsourcing environmental compliance entirely.
- Government Agencies:National environmental regulators and municipal authorities operate reference-grade monitoring stations with strict EPA, EU MCERTS, or China MEE certification requirements. These buyers prioritize data defensibility for enforcement actions over unit cost.
- Research Institutions:Universities and national laboratories deploy research-grade instruments for atmospheric chemistry and climate studies. Funding from the EU Green Deal and national science foundations in Germany and France sustains demand for novel sensing modalities.
- Manufacturing Plants:Industrial operators across China's Yangtze River Delta install continuous emissions monitoring to satisfy MEE real-time disclosure mandates. These buyers favor integrated solutions combining hardware, installation, and compliance reporting.
- Environmental Organizations:Non-governmental monitors and community science programs deploy lower-cost sensors for advocacy and public awareness campaigns. Calibration limitations restrict data use in regulatory proceedings.
Government Agencies anchor volume through multi-year network expansion programs, while Manufacturing Plants show steepest expansion trajectory as enforcement tightens across industrial corridors.
Application:
Site conditions dictate sensor packaging, with corrosive marine environments and submersible deployments demanding specialized encapsulation that standard ambient monitors cannot satisfy.
- Air Quality Monitoring:Particulate, gas, and meteorological sensors track urban pollution, industrial emissions, and wildfire smoke. Barcelona, Seoul, and São Paulo smart-city contracts specify guaranteed data-availability metrics rather than hardware ownership.
- Water Quality Monitoring:Dissolved oxygen, pH, conductivity, and turbidity sensors protect drinking water sources and wastewater discharge compliance. Coastal municipalities in the Netherlands deploy these for real-time harbor water quality management.
- Soil Monitoring:Moisture, temperature, and nutrient sensors enable precision irrigation and fertilizer optimization. Agricultural deployments in India's Punjab and Haryana states expand with PLI scheme support for electronics manufacturing.
- Weather Stations:Multi-parameter atmospheric sensors support aviation, agriculture, and disaster preparedness. Wireless backhaul dominates remote installations across Australia's Bureau of Meteorology network.
Air Quality Monitoring holds the largest installed base, while Soil Monitoring gains share fastest as precision agriculture adoption accelerates in water-stressed regions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Green Deal disclosure mandates and China's MEE enforcement tightening are redrawing procurement geography for environmental sensors. Industrial operators and municipal authorities across multiple jurisdictions now prioritize certified instruments with decade-long service viability.
United States
Petrochemical facilities along the US Gulf Coast deploy continuous emissions monitoring arrays to satisfy EPA ambient air-quality standards. The agency's calibration protocols shape sensor accuracy requirements for federal monitoring stations. Houston and Baton Rouge industrial corridors anchor fixed-point detector installations for leak-detection compliance.
Germany
Industrial refrigeration operators across the Rhine-Ruhr region install continuous leak-detection arrays under EU F-Gas Regulation mandates. The phasedown of hydrofluorocarbon refrigerants tightens monitoring thresholds for commercial cooling systems. Packaged food cold-chain logistics in Bavaria consolidate sensor procurement through HVAC service contracts.
China
Heavy industry in the Yangtze River Delta and Pearl River Delta generates captive demand for domestically certified monitoring equipment under MEE real-time pollution disclosure requirements. The ministry's enforcement tightening drives integrated solutions combining hardware, installation, and compliance reporting. Shanghai and Suzhou municipal authorities anchor smart-city air-quality node deployments.
South Korea
Seoul's smart-city infrastructure drives municipal procurement of air-quality nodes with edge-computing architectures for traffic-adaptive pollution management. The metropolitan government's performance-based service agreements displace capital-equipment sales in favor of guaranteed data-availability metrics. Busan-Ulsan industrial clusters supplement urban networks with port emissions monitoring.
India
The PLI scheme for electronics manufacturing incentivizes local assembly of air-quality nodes for Delhi-Mumbai freight corridors and smart-city programs. Agricultural deployments in Punjab and Haryana states expand soil monitoring for precision irrigation under scheme support. National environmental regulators operate reference-grade stations with strict certification requirements for enforcement data defensibility.
Global Environmental Sensor Market Vendor Landscape
Channel-controlling players compete with product-specialist players for municipal and industrial contracts. Project finance structures for decade-long service obligations favor vendors with captive lending arms or balance-sheet capacity to underwrite performance guarantees. Three archetypes dominate: industrial conglomerates leveraging project-lending relationships, semiconductor specialists supplying miniaturized modules, and electromechanical incumbents defending legacy installed bases. Competitive moves concentrate on strategic partnerships for regional spare-pool networks and portfolio diversification into predictive maintenance platforms.
Among Germany-based industrial conglomerates, Siemens AG exemplifies the channel-control archetype through project-lending relationships anchoring European smart-city deployments. Honeywell International Inc. occupies a position at the scale-driven end, sustaining manufacturing breadth across North American environmental compliance programs. Bosch Sensortec GmbH represents the miniaturization specialist tier, supplying gas-sensing modules for portable air-quality instruments.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| Siemens AG |
| Bosch Sensortec GmbH |
| Sensirion AG |
| STMicroelectronics N.V. |
| ams OSRAM AG |
| Texas Instruments Incorporated |
| OMRON Corporation |
| ABB Ltd. |
| Others |
Supply Flow & Price Mechanics
Taiwanese foundry capacity for MEMS gas-sensing modules dictates downstream pricing power for precision instruments, with supply tightness in Hsinchu Science Park amplifying premium tiers for certified industrial deployments.
Pricing Analysis
Certification level (EPA-grade, EU MCERTS, China MEE) creates the primary spread between price tiers, with reference-grade instruments commanding three-tier pricing structure across premium, standard, and economy levels based on calibration traceability. Subscription-based service agreements for municipal networks displace per-unit transactional sales in Barcelona and Seoul, compressing upfront hardware margins while extending revenue duration. Price erosion runs through economy-tier humidity sensors as commoditized building automation volumes expand. Manufacturing plants in China's industrial corridors show highest price sensitivity due to integrated procurement mandates, while government agencies prioritize data defensibility over unit cost.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk calculations for electrochemical sensor assemblies, forcing dual-sourcing strategies across contract manufacturers. Foundry concentration in Taiwan, South Korea, and Malaysia feeds from rare earth substrates and specialty polymer membranes for sensing films. Single-source vulnerability in calibration gas extraction from Ukrainian and Russian feedstocks elevates total cost of ownership for precision instruments. Distribution runs through HVAC service contractors in European cold-chain logistics and direct municipal procurement in Asian smart-city programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The environmental sensor market is recovering from cyclical lows in industrial capital expenditure, with enforcement tightening across China's MEE and the EU Green Deal acting as the demand restart mechanism.
For Market Incumbents: Pre-empt substitution pressure from optical sensing modalities by embedding AI-driven drift compensation in electrochemical product lines. Acquire regional calibration service networks in India's industrial corridors to defend against emerging domestic assemblers. Deepen backward integration into MEMS foundry partnerships to secure capacity allocation during supply crunches.
For New Entrants and Emerging Players: Mid-market commercial buildings in Southeast Asia represent the most penetrable entry point, with Bangkok and Jakarta smart-city programs lacking established service contractors. Agricultural emissions monitoring for livestock and rice paddy applications remains structurally underpenetrated, requiring new form-factor development. Pursue white-label partnerships with HVAC OEMs in European cold-chain logistics to bypass direct certification barriers.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among municipal service-contract specialists with predictive maintenance platforms. Long-term viability hinges on regulatory enforcement durability rather than technology differentiation alone. Target acquisition archetypes: regional spare-pool operators in South Korea and India with established MEE or PLI scheme relationships. Watch for inflection in blockchain-verified data integrity adoption as carbon-credit verification standardization accelerates.
| Strategic Initiative | Industry Significance |
|---|---|
| Regional Spare-Pool Network Expansion | Seoul and Barcelona municipal contracts now specify guaranteed uptime metrics requiring localized inventory. |
| AI-Driven Calibration Drift Compensation | Edge-computing architectures in Rotterdam harbor installations reduce maintenance intervals for petrochemical operators. |
| Backward Integration into MEMS Foundry Capacity | Taiwanese foundry allocation constraints favor vendors with captive wafer supply agreements. |
| Blockchain-Verified Data Integrity Platform | Tamper-proof audit trails for EU Green Deal emissions disclosure create defensible pricing premiums. |
| Agricultural Form-Factor Development | Precision agriculture nitrous oxide sensing in India's Punjab state expands addressable market beyond industrial safety. |
Methodological Framework
The analysis maps gas-sensing, humidity-monitoring, and optical-detection sub-sectors, each validated through plant engineers at petrochemical facilities, municipal procurement officers in smart-city programs, and calibration service technicians. Primary interviews with HVAC contractors in European cold-chain logistics and MEE compliance officers in China's Yangtze River Delta combined with secondary validation from EPA enforcement databases, EU ETS emissions registries, and China MEE real-time disclosure portals. Bottom-up unit shipment estimates triangulated against top-down industrial capital expenditure tracking across the analysis window.
Assumptions held enforcement intensity constant while varying technology substitution rates and foundry capacity expansion timelines across the projection horizon. The analytical framework modeled product type, technology architecture, end-user procurement sophistication, and application environment as segmentation dimensions. CAGRs derived from installed-base replacement cycles, regulatory mandate phase-in schedules, and smart-city budget allocation patterns. Forecast inputs included MEE disclosure threshold tightening schedules and EU F-Gas Regulation leakage monitoring mandate expansion.
Macroeconomic conditions sit as an overlay; deviation in industrial capital expenditure cycles or municipal bond financing costs would shift the trajectory. Forecasts reflect documented assumptions on regulatory enforcement durability, foundry capacity utilization, and certification reciprocity negotiations. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Environmental Monitoring
Weather Modification Equipment Market
Environmental Monitoring
Environmental Test Equipment Market
Environmental Monitoring
Environmental Monitoring (Surface Water) Market
Environmental Monitoring
Canada Cloud Seeding Market
Environmental Monitoring
Continuous Emission Monitoring Systems (CEMS) Market
Environmental Monitoring
Environmental Hazard Monitoring (EHM) Software Market
Environmental Monitoring
Food Security Technology Market
Environmental Monitoring
Biofuel Testing Services Market
Environmental Monitoring
Asia Pacific Air Quality Monitoring Market
Environmental Monitoring
Environment Monitoring Devices Market
Environmental Monitoring
Water Pipeline Leak Detection System Market
Environmental Monitoring
US Cloud Seeding Market
Environmental Monitoring
Real-Time Flood Monitoring and Warning System Market
Environmental Monitoring
Russia Cloud Seeding Market
Environmental Monitoring
Water Testing Market
Environmental Monitoring
Europe Air Quality Monitoring Market