
 Asia Pacific Air Quality Monitoring Market | 2026-2036
Asia Pacific Air Quality Monitoring Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Air Quality Monitoring Market Insights
Multi-source procurement for sensor components is broadening as vendors diversify supply chains across the region. Honeywell International Inc. leverages its building automation footprint to bundle air quality modules into integrated HVAC offerings. Horiba Ltd anchors its position through deep specialization in automotive emissions testing equipment that extends into ambient monitoring applications. TSI Inc. competes on precision aerosol instrumentation for research and regulatory compliance laboratories.
Asia Pacific air quality monitoring encompasses the systematic measurement of atmospheric pollutants including particulate matter, nitrogen oxides, sulfur dioxide, ozone, and volatile organic compounds using calibrated instruments with detection thresholds reaching parts-per-billion sensitivity. These systems serve industrial compliance, public health alerting, and environmental research functions across urban and peri-urban zones. Indoor monitors command stable replacement demand from healthcare providers upgrading infection-control infrastructure, while laser spectroscopy technology captures expanding share in high-accuracy regulatory networks. Cloud-based deployment architectures are displacing on-premise installations as government agencies prioritize real-time data federation across distributed sensor grids.
China's MEE enforces ambient air quality standards that mandate continuous emissions monitoring at major industrial facilities, while India's CPCB implements National Ambient Air Quality Standards revisions that tighten PM2.5 and PM10 thresholds for metropolitan zones. Japan's METI coordinates sensor standardization through JIS frameworks that facilitate cross-border equipment certification. Stakeholders must weigh calibration protocol harmonization against the fragmentation of national data architectures as procurement scales across the region.
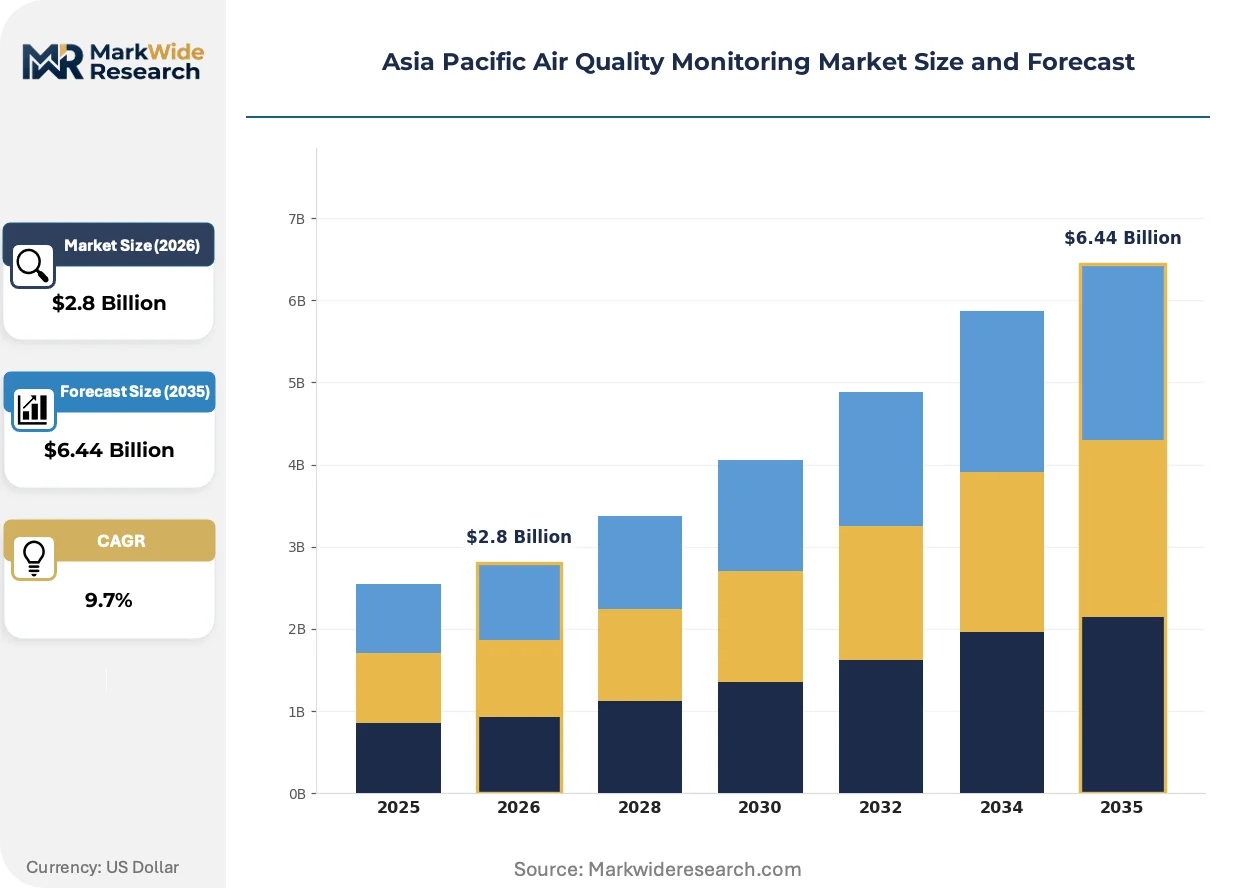
Market Dynamics
Cloud-native sensor networks are compressing replacement cycles across Asia Pacific municipal procurement, as real-time data federation requirements override legacy calibration protocols and on-premise architectures.
Growth Catalysts
- China's MEE ambient standards:Continuous emissions monitoring mandates at industrial facilities are forcing facility-wide sensor retrofits and expanding addressable hardware demand.
- Particulate matter thresholds:India's CPCB revisions to National Ambient Air Quality Standards are tightening PM2.5 and PM10 limits for Delhi, Mumbai, and Bangalore metropolitan zones.
- Laser spectroscopy:Detection sensitivity reaching parts-per-billion is capturing share in high-accuracy regulatory networks previously served by gas chromatography.
Market Restraints
- Sensor component concentration:Optical source and MEMS foundry capacity clusters in East Asian manufacturing corridors create single-point vulnerability for module vendors.
- Calibration gas supply:Certified reference material for ozone and NOx span checks faces price volatility due to specialty chemical production bottlenecks.
- Data architecture fragmentation:India's CPCB, China's MEE, and Japan's METI operate non-interoperable national reporting platforms that complicate cross-border equipment certification.
Strategic Opportunities
- Vietnam industrial corridors:Foreign direct investment in electronics and textiles manufacturing is outpacing installed emissions monitoring capacity around Ho Chi Minh City and Hanoi.
- Healthcare infection control:Hospital infrastructure upgrades across Southeast Asia are generating replacement demand for indoor air quality monitors with bioaerosol detection.
- JIS-METI standardization:Cross-border equipment certification frameworks are reducing re-engineering costs for vendors entering multiple Asia Pacific markets.
Industry Challenges
- Field calibration expertise:Shortage of technicians trained in zero-span verification and optical cell maintenance is extending deployment timelines for distributed sensor grids.
- Legacy system integration:Municipal agencies in older Chinese and Indian cities face protocol translation costs when federating 1990s-era analog stations with IP-native architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Air Quality Monitoring Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $6.44 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Indoor Monitors, Outdoor Monitors, Portable Monitors, Stationary Monitors Technology: Electrochemical Sensors, Laser Spectroscopy, Infrared Sensors, Ultraviolet Sensors End User: Government Agencies, Environmental Organizations, Healthcare Providers, Industrial Facilities Deployment: Cloud-Based, On-Premise, Hybrid, Embedded Systems |
| Companies Covered | Honeywell International Inc., Horiba Ltd, Siemens AG, TSI Inc., Emerson Electric Co., Thermo Fisher Scientific Inc., Teledyne Technologies Inc., Aeroqual Limited, 3M Co., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Air Quality Monitoring Market Trends and Innovations
Real-time data architectures are overriding traditional batch-processing workflows, compressing the interval between pollutant detection and public health alert issuance across Asia Pacific urban corridors.
Low-cost electrochemical sensor arrays are decentralizing ambient monitoring infrastructure by enabling dense neighborhood-scale deployments that previously required centralized reference stations. Municipal agencies in Chinese prefecture-level cities are adopting these networks at accelerated procurement cycles. The technology is decentralizing regulatory compliance costs from capital-intensive laboratory instrumentation to distributed operational expenditure models.
Japan's METI JIS frameworks for sensor interoperability are harmonizing cross-border equipment certification requirements across East Asian markets. Industrial consequences include reduced re-engineering overhead for vendors operating in multiple jurisdictions. Equipment categories targeting multi-country deployment are responding with modular firmware architectures that adapt to national data reporting protocols.
Subscription-based data service contracts are displacing outright hardware ownership in Indian and Chinese municipal procurement. State environmental protection bureaus and city air quality management offices are the primary segments adopting this model. The shift is most visible in tier-two Chinese cities where budget constraints favor operational expenditure classification over capital approval processes.
Asia Pacific Air Quality Monitoring Market Segmentation
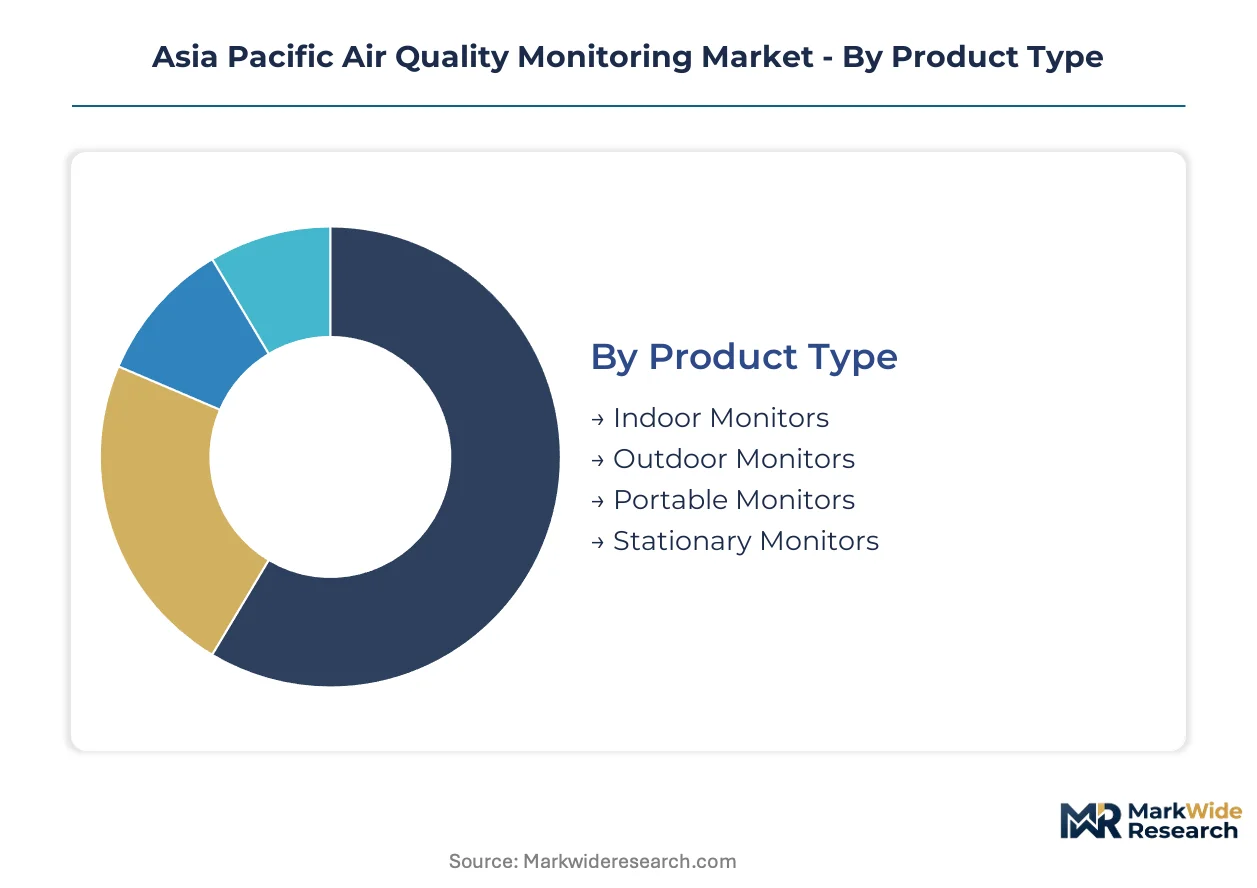
Asia Pacific air quality monitoring procurement divides sharply between high-accuracy regulatory networks and cost-optimized distributed grids. Vendors configure hardware and service bundles differently across these boundaries, with calibration protocols and data architectures serving as the primary differentiators.
Product Type:
Buyers in this category separate by installation permanence and mobility requirements, with facility managers prioritizing fixed infrastructure and field teams demanding transportable instrumentation.
- Indoor Monitors:These units detect particulate matter, CO2, and volatile organic compounds within enclosed environments using compact electrochemical or optical sensors. Demand concentrates in Singapore and Bangkok hospital systems upgrading infection-control infrastructure following regional pandemic preparedness mandates. Procurement runs through facilities management budgets rather than environmental agency capital allocations.
- Outdoor Monitors:Ruggedized enclosures house reference-grade analyzers for continuous ambient measurement across urban corridors. China's MEE mandates at prefecture-level cities are forcing replacement cycles for legacy stations in Beijing, Shanghai, and Guangzhou metropolitan zones. These systems require certified calibration gases and shelter infrastructure that indoor units bypass.
- Portable Monitors:Handheld or backpack-mounted units enable rapid deployment for industrial compliance spot-checks and emergency response scenarios.
- Stationary Monitors:Permanent installations at industrial fence lines and urban reference stations provide continuous regulatory-grade data streams.
Outdoor monitors lead volumes today; portable monitors are gaining share fastest.
Technology:
Detection sensitivity thresholds and capital cost structures determine technology selection, with regulatory laboratories demanding parts-per-billion precision and municipal networks accepting higher detection limits for density.
- Electrochemical Sensors:Compact, low-power devices measure target gases through redox reactions at electrode surfaces. Dense neighborhood-scale deployments across Chinese tier-two cities are accelerating procurement from Shenzhen and Chengdu environmental protection bureaus. The technology sacrifices absolute accuracy for unit economics that enable grid saturation.
- Laser Spectroscopy:Tunable diode lasers achieve sub-ppb detection limits for NOx, SO2, and methane through absorption spectroscopy. Japan's METI-coordinated reference networks and South Korean NIER stations specify these systems for national ambient monitoring standards compliance. Capital costs limit deployment to regulatory anchor stations rather than distributed grids.
- Infrared Sensors:Non-dispersive infrared detection targets CO and CO2 measurement in industrial stack monitoring applications.
- Ultraviolet Sensors:UV fluorescence and absorption methods specialize in ozone and sulfur compound quantification for photochemical smog assessment.
Electrochemical sensors dominate shipment volumes; laser spectroscopy commands the steepest expansion trajectory in value terms.
End User:
Budget authority and compliance liability shape purchasing patterns, with government agencies optimizing for total cost of ownership and industrial facilities prioritizing audit defensibility.
- Government Agencies:National environmental ministries and city air quality management offices procure networked infrastructure for public reporting and policy evaluation. India's CPCB and China's MEE operate parallel procurement streams for continuous ambient monitoring stations, with data federation requirements increasingly favoring cloud-native architectures over legacy on-premise installations.
- Industrial Facilities:Power generation, steel, and chemical plants install fence-line and stack monitoring to satisfy emissions permits. Vietnam's electronics manufacturing corridors around Ho Chi Minh City are outpacing installed monitoring capacity as foreign direct investment accelerates.
- Environmental Organizations:Research institutes and NGOs deploy supplementary monitoring to validate official data or assess non-attainment zones.
- Healthcare Providers:Hospital HVAC integration and operating theater air quality management drive indoor monitor procurement across Southeast Asian medical infrastructure upgrades.
Government agencies anchor current demand; industrial facilities are expanding most quickly as enforcement tightens.
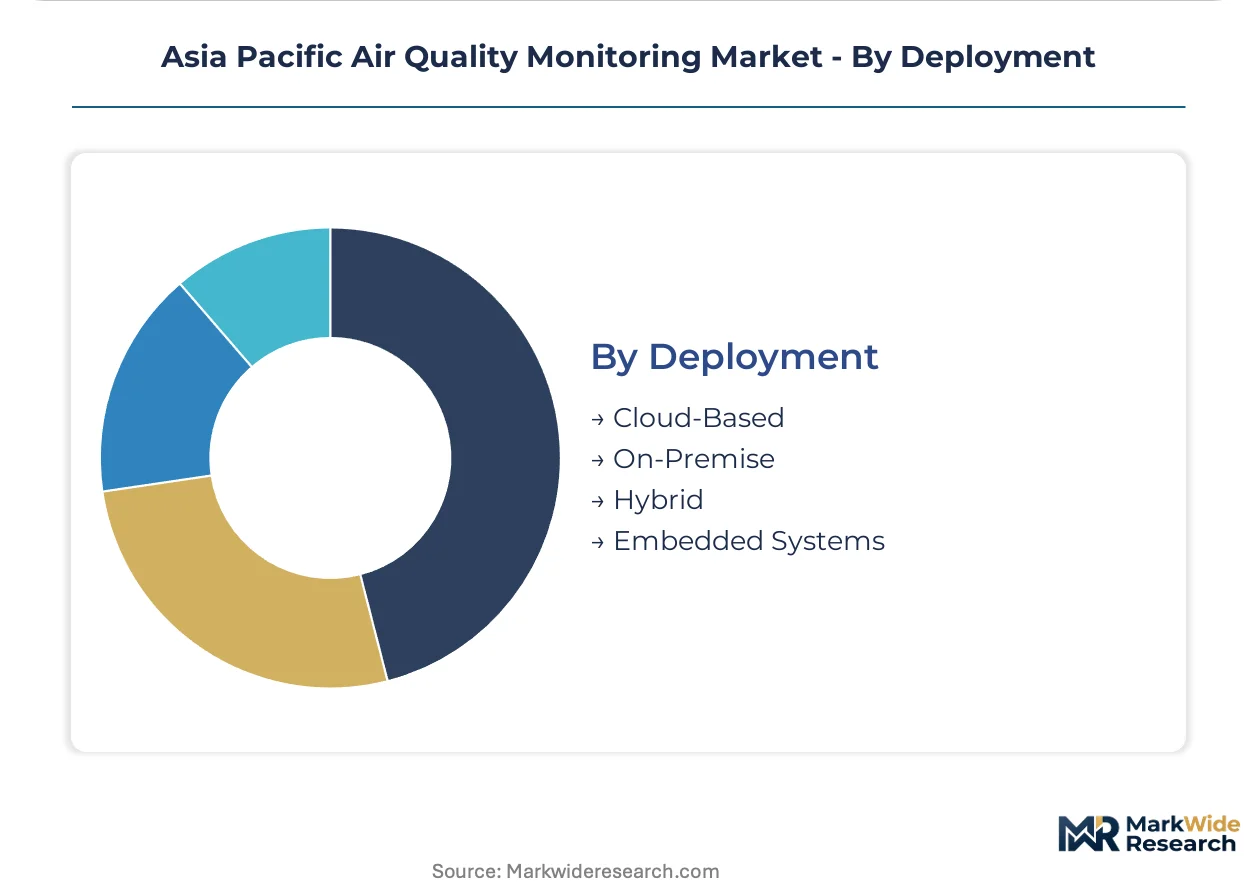
Deployment:
Data sovereignty requirements and legacy infrastructure vintage determine architecture selection, with newer municipalities skipping on-premise buildouts entirely.
- Cloud-Based:Sensor data streams directly to vendor-managed platforms with API access for agency dashboards. Chinese tier-two cities and Indian state pollution control boards are adopting this model to bypass capital approval processes and accelerate deployment timelines. Subscription contracts displace hardware ownership in municipal procurement.
- On-Premise:Local servers maintain air-gapped data storage for facilities with cybersecurity mandates or unreliable connectivity. Legacy installations in older Chinese and Indian cities require protocol translation layers to federate with modern networks.
- Hybrid:Edge preprocessing with cloud aggregation balances latency requirements against storage scalability for metropolitan-scale grids.
- Embedded Systems:Integrated sensor-firmware combinations serve OEM channels for HVAC and automotive integration.
Cloud-based architectures are climbing the fastest; on-premise retains share in defense and critical infrastructure verticals.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
East Asian manufacturing corridors anchor regional procurement volumes, with sensor network deployments concentrated in urban agglomerations facing tightening emissions standards. Government mandates across the region are accelerating replacement cycles for legacy monitoring infrastructure.
China
Prefecture-level cities are retrofitting distributed sensor grids under MEE continuous emissions monitoring mandates. The Yangtze River Delta and Pearl River Delta industrial clusters drive hardware demand from environmental protection bureaus in Shanghai, Suzhou, and Shenzhen. Cloud-native architectures are displacing legacy on-premise installations as tier-two municipalities bypass capital approval constraints.
India
CPCB revisions to National Ambient Air Quality Standards are tightening PM2.5 and PM10 thresholds for Delhi, Mumbai, and Bangalore metropolitan zones. State pollution control boards are adopting subscription-based data service contracts to accelerate deployment timelines. Industrial corridors in Gujarat and Maharashtra face expanding compliance liability as enforcement capacity catches up with permit requirements.
Japan
METI-coordinated JIS frameworks for sensor interoperability are harmonizing cross-border equipment certification across East Asian markets. National Institute of Environmental Research stations specify laser spectroscopy systems for reference-grade monitoring networks. The Kanto and Kansai metropolitan zones maintain dense ambient monitoring infrastructure with standardized data reporting protocols.
South Korea
NIER operates continuous ambient monitoring stations specifying high-accuracy instrumentation for national air quality standards compliance. The Seoul Capital Area and Busan-Ulsan industrial corridor drive replacement demand as legacy stations reach end-of-life. Domestic semiconductor manufacturing clusters are expanding fence-line monitoring capacity ahead of regulatory tightening.
Vietnam
Foreign direct investment in electronics and textiles manufacturing is outpacing installed emissions monitoring capacity around Ho Chi Minh City and Hanoi. Provincial environmental departments are procuring portable and stationary monitors to close compliance gaps. Industrial zones in Binh Duong and Bac Ninh provinces face accelerating permit enforcement as manufacturing scales.
Asia Pacific Air Quality Monitoring Market Competitive Landscape
Global majors compete with regional champions across technology specialization and government procurement channels. The vendor base stratifies into three tiers: diversified industrial conglomerates bundling air quality modules into broader automation portfolios, precision instrumentation specialists serving regulatory laboratories, and emerging sensor manufacturers capturing municipal distributed grid contracts. Consolidation pressure is mounting as cloud-native architectures favor vendors with integrated data platform capabilities. Dominant competitive moves include strategic partnerships for local calibration service networks and portfolio diversification into indoor air quality monitoring for healthcare verticals.
Within the precision instrumentation tier, Horiba Ltd and TSI Inc. exemplify specialization strategies that anchor positions in regulatory compliance and research applications. Honeywell International Inc. occupies a position among diversified industrial conglomerates leveraging building automation footprints to bundle air quality modules into integrated HVAC offerings. These three companies represent distinct archetypes: deep vertical specialization, precision aerosol instrumentation, and platform-scale integration.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| Horiba Ltd |
| Siemens AG |
| TSI Inc. |
| Emerson Electric Co. |
| Thermo Fisher Scientific Inc. |
| Teledyne Technologies Inc. |
| Aeroqual Limited |
| 3M Co. |
| Others |
Pricing and Supply Chain Analysis
Optical source components and MEMS foundry capacity concentrated in East Asian manufacturing corridors propagate cost volatility through three distinct pricing tiers, with laser spectroscopy modules commanding premium positioning against electrochemical sensor economies.
Pricing Analysis
Input-cost pass-through from specialty chemical bottlenecks in certified reference materials compresses margins at the regulatory-grade tier while subscription-based SaaS contracts for cloud-native municipal deployments stabilize recurring revenue streams. Price differentiation hinges on calibration protocol complexity and JIS certification status, with Japanese METI-compliant systems carrying brand premiums against uncertified alternatives. Pricing pressure stems from Chinese tier-two cities favoring operational expenditure models over capital-intensive hardware procurement. Government environmental protection bureaus exhibit highest price sensitivity; research laboratories demonstrate lowest sensitivity due to grant-funded acquisition budgets.
Supply Chain Analysis
Freight cost escalation across intra-Asia shipping lanes amplifies landed costs for optical source imports from Japan and South Korea into Chinese assembly facilities. Manufacturing concentrates in China, Japan, and South Korea, with raw material dependencies spanning germanium substrates for infrared detectors, rare-earth dopants for laser diodes, and high-purity aluminum oxide for sensor housings. Single-source vulnerability in tunable diode laser fabrication creates structural risk for high-accuracy regulatory network suppliers. Distribution runs through direct municipal procurement channels in China and India, with systems integrators dominating Japanese and South Korean deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia Pacific air quality monitoring market functions as a regulatory compounder, with China's MEE continuous emissions monitoring mandates forcing facility-wide sensor retrofits that expand addressable hardware demand across industrial corridors.
For Market Incumbents: Extend cloud-native platform capabilities to capture subscription-based municipal procurement in Chinese tier-two cities and Indian state pollution control boards. Consolidate calibration service networks through partnerships with regional technical institutes to address field technician shortages threatening deployment timelines. Vertical integration into optical source manufacturing reduces exposure to East Asian foundry concentration risks. For New Entrants and Emerging Players: Launch via portable monitor distribution targeting Vietnam's electronics manufacturing corridors around Ho Chi Minh City and Hanoi, where foreign direct investment outpaces installed emissions monitoring capacity. Penetrate healthcare infection-control verticals across Southeast Asian hospital infrastructure upgrades with bioaerosol detection features. Pursue white-label partnerships with HVAC OEMs seeking integrated air quality modules. For Investors and Strategic Acquirers: Roll-up economics work for precision instrumentation specialists because calibration protocol fragmentation and national data architecture silos reward vendors with multi-country certification capabilities. Target vendors with JIS-METI harmonized equipment and established service networks across East Asian markets. Watch for inflection when India's CPCB enforcement capacity catches up with permit requirements in Gujarat and Maharashtra industrial corridors.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Platform Integration | Chinese tier-two cities bypass capital approval constraints through subscription procurement models. |
| JIS-METI Certification Investment | Cross-border equipment standardization reduces re-engineering overhead for multi-country vendors. |
| Calibration Service Network Expansion | Field technician scarcity in distributed sensor grid deployment creates captive service revenue. |
| Healthcare Vertical Diversification | Southeast Asian hospital infection-control mandates generate replacement demand for indoor monitors. |
| Laser Spectroscopy Capacity Addition | Parts-per-billion detection requirements in Japanese NIER and South Korean national networks anchor premium positioning. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with environmental protection bureau procurement officers, industrial facility compliance managers, sensor manufacturer product strategists, and calibration service technicians with secondary validation against MEE enforcement circulars, CPCB ambient standards revisions, METI JIS framework documents, and municipal tender databases. Bottom-up shipment estimates triangulated against top-down addressable market sizing across the analysis window.
Comparable historical reference periods anchored the projection horizon, with analytical frameworks modeling technology type, installation permanence, deployment architecture, and end-user budget authority as core segmentation dimensions. CAGRs derived from trend extrapolation of replacement cycle compression and regulatory mandate acceleration, incorporating laser spectroscopy adoption curves and cloud-native procurement penetration as industry-specific inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt calibration gas supply disruptions or sudden harmonization of India's CPCB, China's MEE, and Japan's METI data reporting platforms. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Environmental Monitoring
Real-Time Flood Monitoring and Warning System Market
Environmental Monitoring
US Cloud Seeding Market
Environmental Monitoring
Water Quality Monitoring Equipment Market
Environmental Monitoring
Environment Monitoring Devices Market
Environmental Monitoring
Global on-Line Total Organic Carbon (TOC) Analyzer Market
Environmental Monitoring
Green Mining Market
Environmental Monitoring
Ecotoxicological Studies Market
Environmental Monitoring
Latin America Cloud Seeding Market
Environmental Monitoring
US Environmental Testing Market
Environmental Monitoring
Biofuel Testing Services Market
Environmental Monitoring
Asia-Pacific Food and Environment Manual Testing Market
Environmental Monitoring
LAMEA Emission Monitoring System Market
Environmental Monitoring
Russia Cloud Seeding Market
Environmental Monitoring
Middle East and Africa Air Quality Monitoring Market
Environmental Monitoring
Testing, Inspection, and Certification for Natural Resources Market
Environmental Monitoring
Water Testing Market