
 Global Indoor Air Quality Solutions Market | 2026-2036
Global Indoor Air Quality Solutions Market Size, Share, and Industry Trends Forecast 2026-2036
Global Indoor Air Quality Solutions Market Outlook
A capital-intensity divergence between in-house plasma generation capabilities and outsourced filter media supply is redrawing competitive tiers. Montrose Environmental Group leverages its environmental consulting backbone to anchor integrated monitoring-to-remediation workflows. Camfil AB sustains manufacturing scale across multiple continents, while IQAir specializes in premium HEPA architectures for medical-grade environments.
Indoor air quality solutions encompass engineered systems and devices that remove, dilute, or neutralize airborne contaminants through mechanical filtration, photocatalytic oxidation, or bipolar ionization, typically targeting particulate matter below 2.5 microns and volatile organic compounds at concentrations measured in parts per billion. Their primary commercial purpose is to maintain breathable environments that comply with occupational exposure limits and reduce respiratory disease burden in enclosed spaces. Air purifiers and ventilation systems occupy the largest installed base, while UV-C technology segments are capturing accelerated interest from healthcare end users seeking pathogen suppression beyond standard filtration. Activated carbon applications dominate odor removal scenarios in industrial settings where chemical off-gassing thresholds are regulated.
The EPA sets baseline indoor air quality benchmarks for commercial buildings across the United States, while the EU Green Deal and F-Gas Regulation in Europe are restricting refrigerant-based dehumidification chemistries and mandating lower-carbon alternatives. China's MEE enforces ambient and indoor pollutant caps that directly shape product certification requirements for equipment sold into its construction pipeline. Stakeholders must monitor how fragmented national standards for PM2.5 measurement protocols affect cross-border equipment validation and service interoperability.
Market Dynamics
The building retrofit cycle across developed economies is compressing replacement timelines for HVAC infrastructure, forcing equipment manufacturers to align product refresh rates with accelerated capital deployment schedules in commercial real estate portfolios.
Growth Catalysts
- Healthcare filtration mandates:Hospital accreditation bodies in the United States now require HEPA-equivalent performance in surgical suites and isolation wards, expanding specification requirements for mechanical contractors.
- F-Gas Regulation phase-down:The European Union's refrigerant restrictions are accelerating adoption of non-chemically-based dehumidification and air handling architectures in commercial buildings.
- Plasma cluster manufacturing:Concentrated production of bipolar ionization modules in South Korea and Japan is reducing unit costs for building automation integrators.
Market Restraints
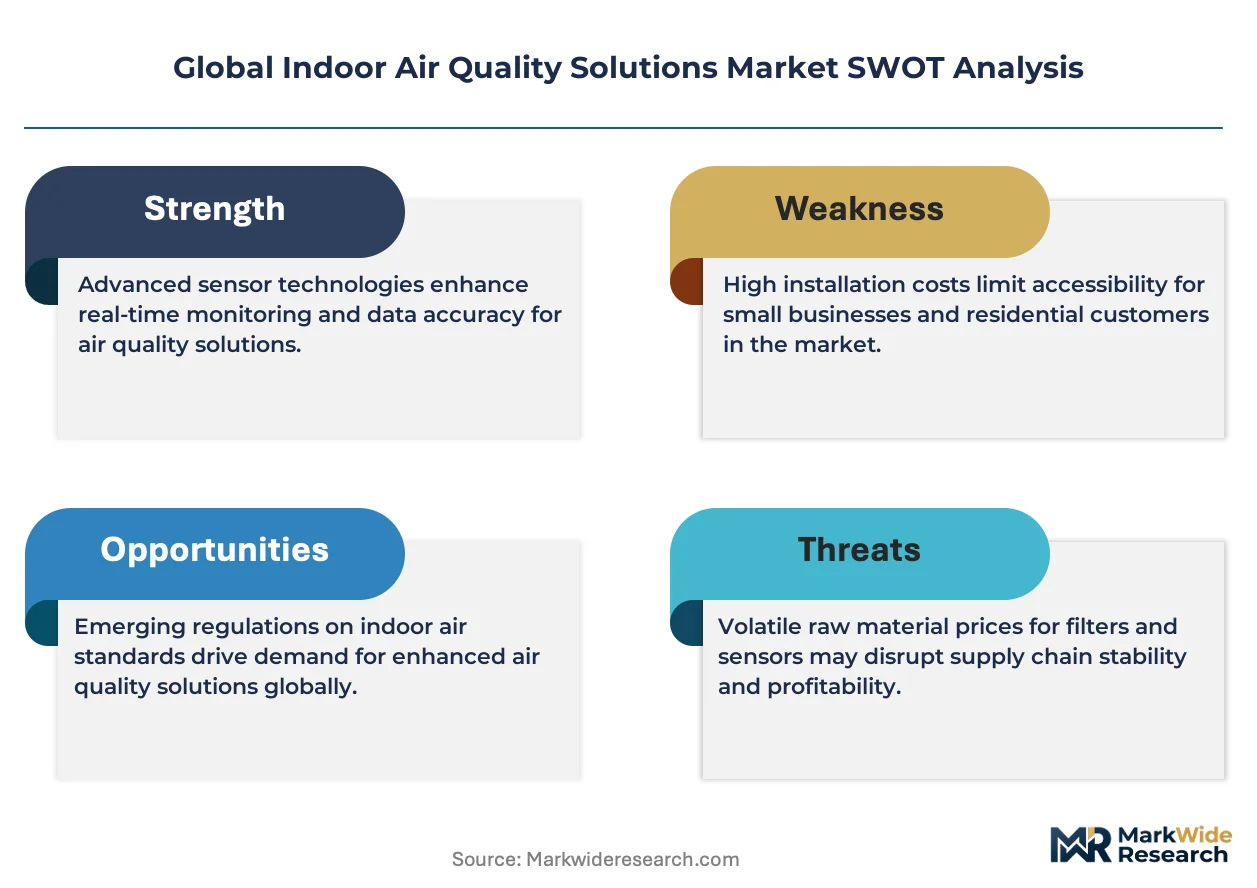
- Filter media supply concentration:High-efficiency glass microfiber production concentrates among three specialized German and Japanese suppliers, creating input vulnerability for downstream equipment assemblers.
- Activated carbon cost volatility:Coconut shell sourcing from Southeast Asian agricultural regions fluctuates with weather patterns, compressing margins for odor-control system manufacturers.
- Cross-border certification friction:China's GB standards for PM2.5 measurement protocols diverge from ISO methodologies, forcing duplicate testing expenditures for multinational product lines.
Strategic Opportunities
- India's construction pipeline:Green building certification adoption in Mumbai and Bangalore commercial towers is creating specification windows for low-energy recovery ventilation systems.
- UV-C pathogen suppression:Convergence of LED semiconductor advances with reflective chamber design is enabling retrofit installations in legacy ductwork without structural modification.
- Outcome-based service models:Facility management platforms in German industrial parks are unbundling air quality monitoring from equipment ownership, creating recurring revenue streams for sensor-network operators.
Industry Challenges
- Controls integration complexity:BACnet and Modbus protocol fragmentation across building management systems requires custom middleware development for multi-vendor deployments.
- Certification timeline compression:EPA Energy Star verification and AHRI performance certification queues have extended to 14-18 months, delaying product launches.
- Field commissioning skill scarcity:Qualified technicians for airflow balancing and IAQ sensor calibration are concentrated among aging workforce cohorts in North American and Western European markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Indoor Air Quality Solutions Market |
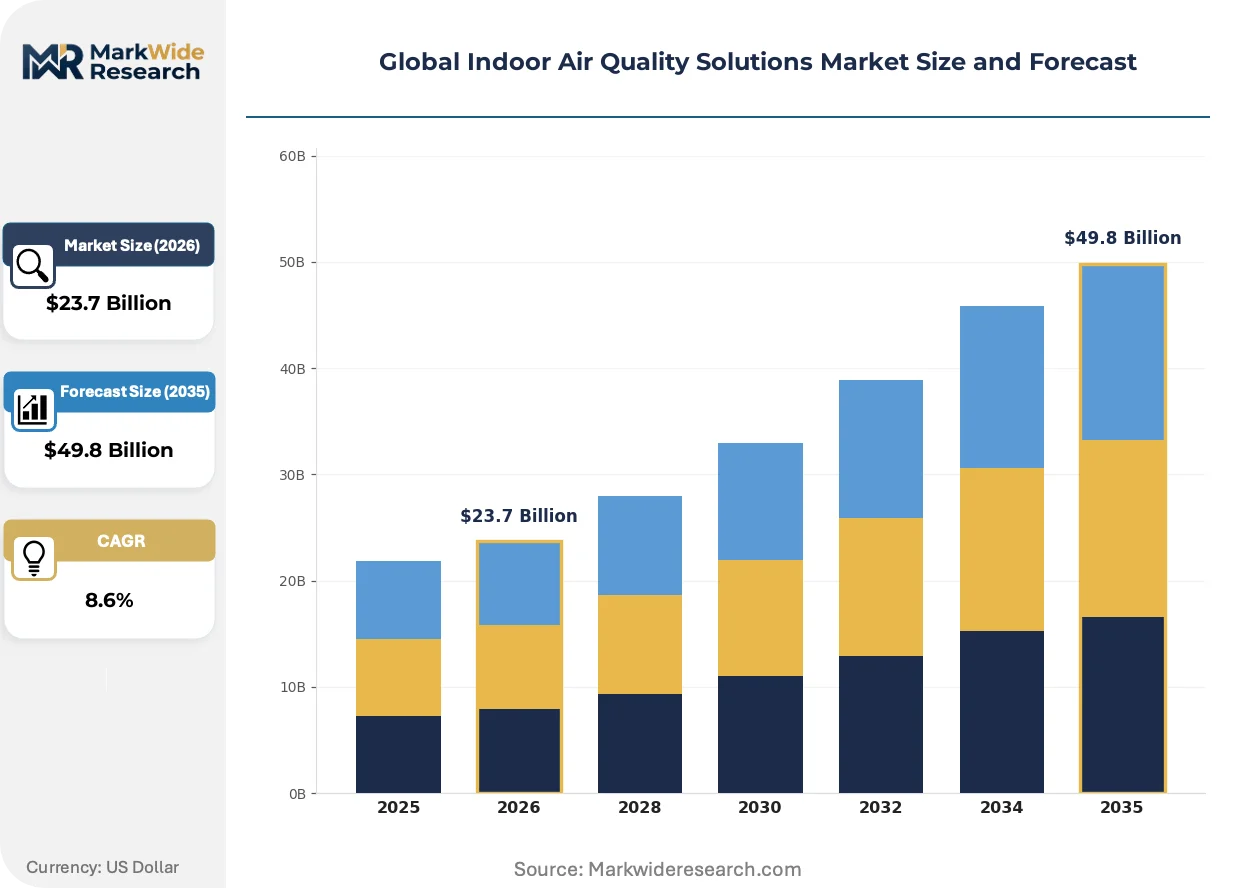
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $49.8 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Air Purifiers, Humidifiers, Dehumidifiers, Ventilation Systems Technology: HEPA, UV-C, Activated Carbon, Ionizers End User: Residential, Commercial, Industrial, Healthcare Application: Air Quality Monitoring, Pollution Control, Odor Removal, Temperature Regulation |
| Companies Covered | Montrose Environmental Group, Teledyne Technologies, IQAir, Global Plasma Solutions, Freudenberg Filtration Technologies, Comfort Systems USA, Camfil AB, Aspire Heating & Cooling, Ferguson Enterprises, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Indoor Air Quality Solutions Market Strategic Shifts
Photocatalytic oxidation architectures are migrating from industrial niche applications to mainstream commercial deployment, while regulatory pressure on refrigerant chemistries is forcing thermal management redesigns across product categories.
Electrostatic precipitator technology with washable collection cells is supplanting disposable media filters in high-particulate environments such as welding shops and food processing facilities. Automotive suppliers with cleanroom experience are adopting these systems to reduce consumable expenditure and waste handling liability. The shift is compressing aftermarket filter replacement revenue for incumbent suppliers while expanding upfront equipment margins.
The EU Green Deal's building renovation wave is mandating energy performance certificates that explicitly score ventilation efficiency and indoor pollutant levels. Member states must transpose these requirements into national building codes by fixed deadlines, forcing real estate investors to budget for air handling upgrades alongside envelope improvements. German and French commercial landlords are responding by pre-certifying assets to LEED and BREEAM standards to attract institutional capital.
Building operators in United States healthcare and education verticals are consolidating vendor relationships around single-source accountability for both monitoring hardware and maintenance service. This pattern displaces the traditional split between controls contractors and filter suppliers. Texas and California hospital systems are piloting ten-year performance contracts where equipment providers guarantee continuous compliance with ASHRAE ventilation standards.
Global Indoor Air Quality Solutions Market Segmentation
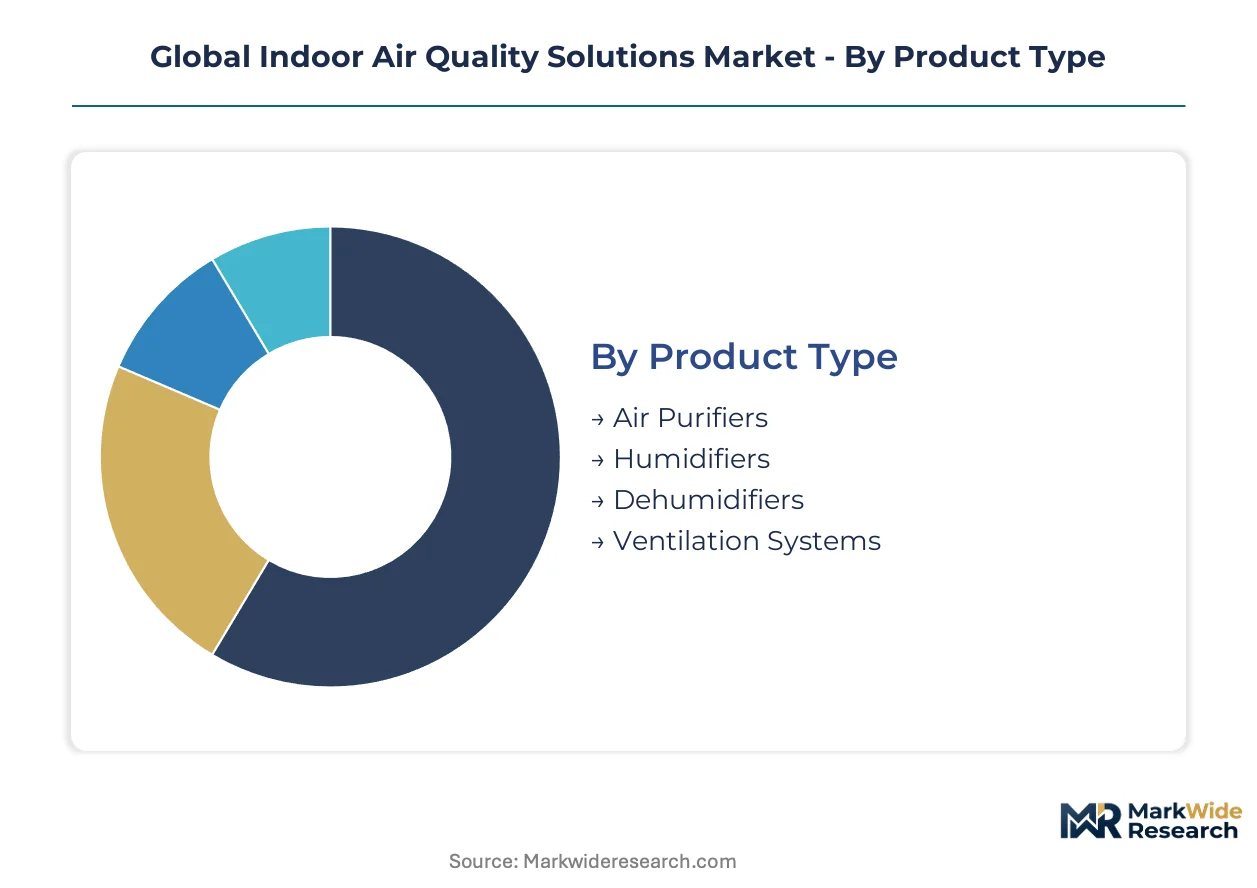
Product architecture and end-use requirements fragment the competitive landscape into distinct specification tiers. Technology selection and regulatory compliance thresholds vary sharply across residential, commercial, and healthcare deployments, forcing manufacturers to maintain parallel product lines with non-overlapping certification pathways.
Product Type:
Domestic demand concentrates in standalone units for residential retrofits, while export volumes flow through integrated HVAC infrastructure for new commercial construction in China and Germany.
- Air Purifiers:Portable and fixed-installation units deploy multi-stage filtration architectures combining pre-filters, HEPA media, and activated carbon beds. Demand clusters in United States urban residential markets where EPA indoor air quality guidelines drive replacement cycles, and in Chinese metropolitan areas responding to MEE pollutant caps.
- Ventilation Systems:Energy recovery ventilators and heat recovery ventilators exchange stale indoor air with filtered outdoor supply while transferring thermal energy to reduce HVAC load. German commercial real estate investors specify these units to meet EU Green Deal building renovation wave requirements and pre-certify assets to BREEAM standards.
- Humidifiers:Evaporative and ultrasonic technologies maintain 40-60% relative humidity to reduce respiratory irritation and static electricity in heated indoor environments.
- Dehumidifiers:Refrigerant-based and desiccant systems remove excess moisture to prevent mold proliferation; F-Gas Regulation phase-down is accelerating non-chemical alternatives in European markets.
Air purifiers command the established base. The steepest expansion runs through ventilation systems.
Technology:
Cost tiers separate premium medical-grade specifications from mass-market residential offerings, with certification complexity determining margin structure.
- HEPA:High-efficiency particulate air filters capture 99.97% of particles 0.3 microns in diameter using densely pleated glass microfiber media. United States hospital accreditation bodies mandate HEPA-equivalent performance in surgical suites, expanding specification requirements for mechanical contractors in Texas and California healthcare systems.
- UV-C:Ultraviolet germicidal irradiation at 254 nanometers disrupts pathogen DNA in reflective chamber designs. LED semiconductor advances enable retrofit installations in legacy United States ductwork without structural modification, capturing accelerated interest from healthcare end users seeking suppression beyond standard filtration.
- Activated Carbon:Porous carbon structures adsorb volatile organic compounds and odorous molecules through physisorption; coconut shell sourcing from Southeast Asian agricultural regions introduces cost volatility for odor-control system manufacturers.
- Ionizers:Bipolar ionization modules generate positive and negative ions that cluster around airborne particles, enabling capture by standard filters; concentrated production in South Korea and Japan is reducing unit costs for building automation integrators.
HEPA retains the dominant installed base. UV-C is climbing the fastest as healthcare filtration mandates tighten.
End User:
Application maturity varies from commoditized residential replacement markets to specification-intensive healthcare deployments with decade-long performance contracts.
- Healthcare:Operating theaters, isolation wards, and pharmaceutical cleanrooms demand continuous compliance with ASHRAE ventilation standards and HEPA-equivalent filtration. United States hospital systems in Texas and California pilot ten-year performance contracts where equipment providers guarantee air quality outcomes, consolidating vendor relationships around single-source accountability.
- Commercial:Office towers, retail centers, and hospitality properties balance occupant comfort with energy efficiency targets under LEED and BREEAM certification schemes. German and French commercial landlords pre-certify assets to attract institutional capital responding to EU Green Deal building renovation wave mandates.
- Residential:Single-family homes and multi-unit dwellings drive volume through replacement cycles triggered by visible filter degradation and seasonal allergen concerns.
- Industrial:Welding shops and food processing facilities deploy electrostatic precipitators with washable collection cells to reduce consumable expenditure and waste handling liability.
Commercial deployments anchor current revenue. Healthcare contracts are gaining share fastest through outcome-based service models.
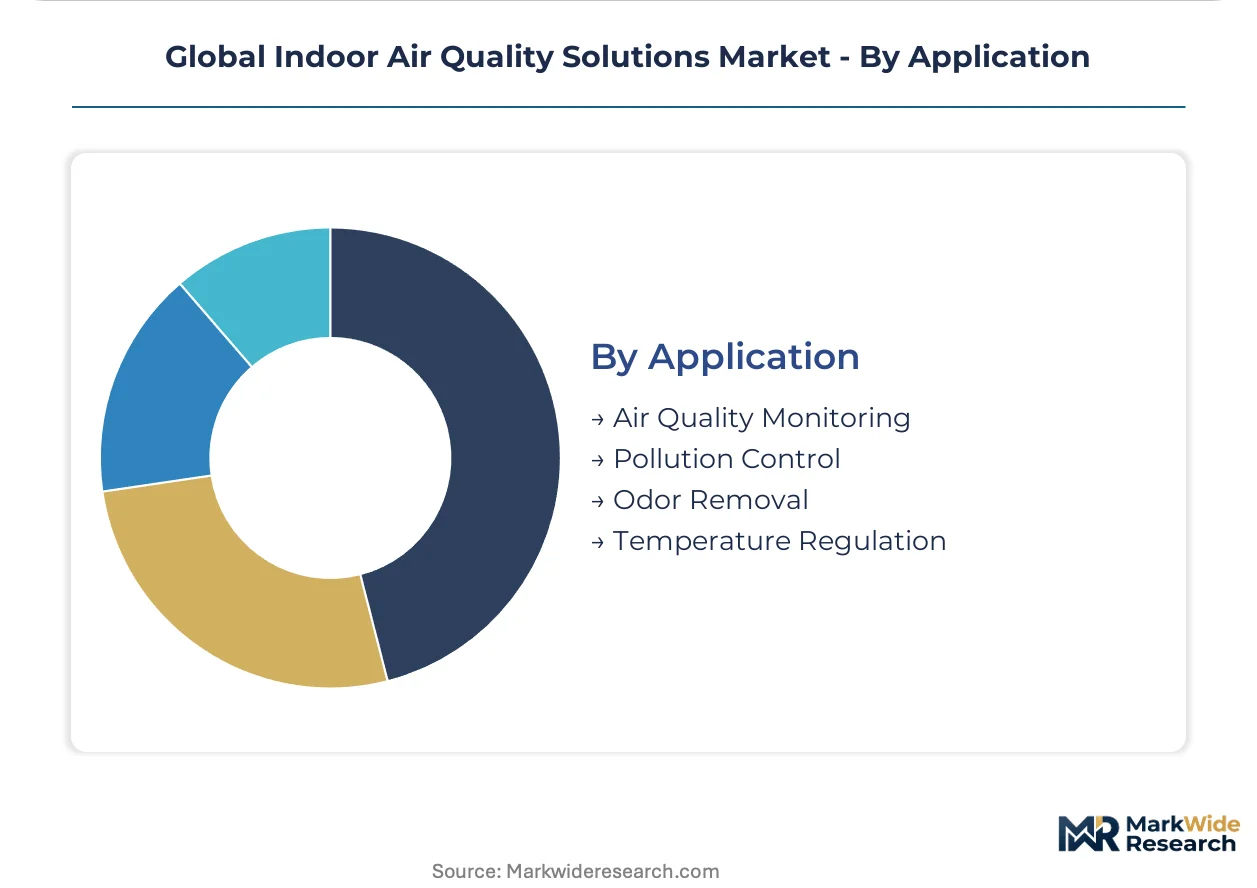
Application:
Customer procurement patterns separate capital equipment purchases from recurring sensor-network subscriptions, with interoperability requirements dictating vendor selection.
- Air Quality Monitoring:Distributed sensor networks measure PM2.5, CO2, VOCs, and humidity in real time, feeding data to building management systems via BACnet or Modbus protocols. German industrial parks unbundle monitoring from equipment ownership, creating recurring revenue streams for sensor-network operators.
- Pollution Control:Source capture and ambient filtration systems reduce occupational exposure to particulate matter below regulatory thresholds in manufacturing environments.
- Odor Removal:Activated carbon and photocatalytic oxidation systems address chemical off-gassing in industrial settings where concentration thresholds are regulated.
- Temperature Regulation:Integrated thermal management maintains setpoints while ventilation exchanges air, with F-Gas Regulation restricting refrigerant-based approaches in European commercial buildings.
Pollution control holds the largest equipment footprint. Air quality monitoring is expanding most quickly through facility management platform integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in the United States exceeds that in China by a substantial margin, reflecting tighter EPA compliance thresholds and higher specification requirements. German buyers command premium positioning through EU Green Deal mandates. Japanese procurement concentrates on plasma cluster modules with exacting performance standards.
United States
Healthcare filtration mandates and building retrofit cycles drive specification intensity. EPA indoor air quality guidelines and LEED certification standards tighten compliance thresholds continuously. Texas and California hospital systems pilot ten-year performance contracts guaranteeing ASHRAE ventilation compliance.
China
Construction pipeline expansion and MEE pollutant caps shape equipment certification requirements. GB standards for PM2.5 measurement protocols diverge from ISO methodologies, forcing duplicate testing expenditures. Yangtze River Delta metropolitan clusters absorb volumes of integrated HVAC infrastructure for new commercial towers.
Germany
EU Green Deal building renovation wave mandates energy performance certificates scoring ventilation efficiency. F-Gas Regulation phase-down accelerates non-chemical dehumidification architectures. Commercial landlords in Frankfurt and Munich pre-certify assets to BREEAM standards to attract institutional capital.
Japan
Plasma cluster manufacturing concentrates among specialized producers serving building automation integrators. METI efficiency standards and JIS certification requirements filter market entry. Osaka and Nagoya industrial corridors export bipolar ionization modules at declining unit costs.
India
Green building certification adoption in commercial towers creates specification windows for low-energy recovery ventilation. Central Electricity Authority efficiency norms and state-level construction codes shape procurement patterns. Mumbai and Bangalore developers specify imported filtration media for premium office assets.
Global Indoor Air Quality Solutions Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure. Premium-positioned specialists concentrate on medical-grade HEPA architectures and outcome-based service contracts. Scale-driven manufacturers sustain multi-continental production footprints for standardized filter media. Integrated environmental service providers bundle monitoring hardware with maintenance workflows. Dominant competitive moves include strategic partnerships between plasma module producers and building automation integrators, plus geographic expansion into India's construction pipeline.
Within the integrated service provider tier, Montrose Environmental Group anchors monitoring-to-remediation workflows through its environmental consulting backbone. Camfil AB occupies a position exemplifying manufacturing scale across multiple continents. IQAir represents the premium-tier specialist archetype, sitting within medical-grade HEPA architecture supply for healthcare end users.
| Leading Market Players |
|---|
| Montrose Environmental Group |
| Teledyne Technologies |
| IQAir |
| Global Plasma Solutions |
| Freudenberg Filtration Technologies |
| Comfort Systems USA |
| Camfil AB |
| Aspire Heating & Cooling |
| Ferguson Enterprises |
| Others |
Value Chain & Pricing Dynamics
EPA Energy Star verification and AHRI performance certification queues gate both supply qualification and price differentiation simultaneously, compressing product launch timelines for equipment providers while creating premium positioning for pre-certified portfolios that bypass extended validation cycles.
Pricing Analysis
Configured-to-order pricing for medical-grade HEPA architectures commands substantial premiums over standard residential units, with certification grade and after-sales service bundling as the primary differentiation drivers. Three-tier pricing structure across premium, standard, and economy levels stratifies by filtration efficiency and monitoring integration depth. Cost compression in mass-market residential tiers is intensifying because filter media supply concentration limits margin flexibility. Healthcare procurement committees demonstrate lowest price sensitivity, while residential replacement cycles remain highly elastic to visible filter degradation signals.
Supply Chain Analysis
Germany and Japan anchor high-efficiency glass microfiber production for HEPA media, while South Korea and Japan concentrate bipolar ionization module manufacturing. Downstream equipment assemblers draw from coconut shell activated carbon sourced across Southeast Asian agricultural regions, with supply vulnerability tethered to weather-induced harvest volatility. Single-source vulnerability concentrates among three specialized glass microfiber suppliers, creating input risk for premium filtration equipment. Distribution runs through mechanical contractors and building automation integrators serving commercial real estate portfolios and healthcare systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Air quality monitoring subscriptions and ten-year performance contracts expand faster than hardware sales, transforming capital equipment vendors into recurring-revenue service platforms with embedded sensor-network obligations.
For Market Incumbents: Compound service-attach rates by embedding monitoring hardware into long-term performance contracts that guarantee ASHRAE compliance, while deepening upstream control over glass microfiber supply through captive sourcing agreements or strategic partnerships with German and Japanese media producers. Certification investment in parallel EPA and GB standard validation defends positioning against emerging entrants exploiting timeline compression in multinational product launches. For New Entrants and Emerging Players: Differentiate on UV-C LED retrofit architectures for legacy United States healthcare ductwork, where LED semiconductor advances enable pathogen suppression without structural modification. India's green building certification pipeline in Mumbai and Bangalore commercial towers offers the most penetrable geography, with low-energy recovery ventilation specifications creating specification windows for imported technology partnerships with local mechanical contractors. For Investors and Strategic Acquirers: EU F-Gas Regulation phase-down reshapes the acquisition landscape toward non-chemical dehumidification and air handling architectures with refrigerant-free thermal management IP. Targets with outcome-based service contracts and embedded monitoring platforms demonstrate superior long-term viability through recurring revenue visibility. Watch for MEE pollutant cap enforcement tightening as the signal indicating accelerated replacement cycles in Chinese metropolitan construction clusters.| Strategic Initiative | Industry Significance |
|---|---|
| Outcome-Based Service Contract Expansion | Ten-year ASHRAE compliance guarantees in Texas and California hospital systems consolidate vendor relationships and displace split procurement models. |
| UV-C LED Retrofit Platform Launch | Reflective chamber designs leveraging semiconductor advances enable healthcare ductwork upgrades without structural modification or capital-intensive infrastructure replacement. |
| Backward Integration into Filter Media | Captive supply of high-efficiency glass microfiber reduces input vulnerability to German and Japanese supplier concentration and compresses cost structures. |
| Geographic Expansion into Indian Commercial Construction | Mumbai and Bangalore green building certifications create specification windows for energy recovery ventilation systems meeting Central Electricity Authority efficiency norms. |
| Strategic Partnership with Building Automation Integrators | Plasma cluster module producers in South Korea and Japan reduce unit costs through concentrated production scale while securing BACnet and Modbus protocol interoperability. |
Study Parameters
The analysis maps air purification equipment, ventilation systems, humidification and dehumidification technologies, and monitoring sensor networks, each validated through mechanical contractors, healthcare facilities managers, building automation integrators, and filter media procurement leads. Primary interviews with these stakeholders combine with secondary validation against EPA indoor air quality guidelines, EU Green Deal building renovation wave mandates, MEE pollutant cap enforcement records, and AHRI performance certification databases. Bottom-up equipment shipment analysis and top-down construction pipeline assessment triangulate market sizing across the projection horizon.
Consistency checks against external benchmarks validate volume and value outputs, with segmentation modeled across product architecture, filtration technology, end-use vertical, and application purpose throughout the forecast period. CAGRs derive from equipment replacement cycle analysis, regulatory compliance timeline compression, and healthcare accreditation mandate expansion. Industry-specific inputs include HVAC infrastructure retrofit rates in commercial real estate portfolios and plasma cluster module unit cost trajectories from South Korean and Japanese manufacturing concentration.
Material uncertainties — regulatory timeline delays, filter media supply disruptions, and cross-border certification protocol divergence — sit outside the modeled envelope. Forecasts reflect assumptions about enforcement continuity for EPA, EU Green Deal, and MEE standards. Recalibration cycles align with material shifts in healthcare filtration mandates and F-Gas Regulation phase-down implementation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Environmental Monitoring
Radon Gas Test Kits Market
Environmental Monitoring
Environmental Technology Market
Environmental Monitoring
Continuous Emission Monitoring Systems (CEMS) Market
Environmental Monitoring
Weather Modification Equipment Market
Environmental Monitoring
Ecotoxicological Studies Market
Environmental Monitoring
Quality Monitoring Sensor for Water Market
Environmental Monitoring
Pollution Monitoring Equipment Market
Environmental Monitoring
Water Testing Market
Environmental Monitoring
Cloud Seeding System Market
Environmental Monitoring
Water Quality Analyzer Market
Environmental Monitoring
Testing, Inspection, and Certification for Natural Resources Market
Environmental Monitoring
Asia-Pacific Cloud Seeding Market
Environmental Monitoring
End-Of-Pipe Air Pollution Control Equipment Market
Environmental Monitoring
Global on-Line Total Organic Carbon (TOC) Analyzer Market
Environmental Monitoring
Latin America Cloud Seeding Market
Environmental Monitoring
Green Mining Market