
 Real-Time Flood Monitoring and Warning System Market | 2026-2036
Real-Time Flood Monitoring and Warning System Market Size, Share, and Industry Trends Forecast 2026-2036
Real-Time Flood Monitoring and Warning System Market Intelligence
Multi-source procurement of sensor hardware and telemetry modules is realigning vendor relationships across the flood monitoring value chain. Xylem Inc. leverages its vertical integration in water analytics to dominate municipal deployment contracts. Vaisala Oyj anchors its position through specialized meteorological sensor calibration that competing generalists cannot replicate. Campbell Scientific, Inc. sustains niche leadership in ruggedized dataloggers purpose-built for remote watershed stations.
Real-time flood monitoring and warning systems integrate IoT sensors, satellite imaging, and radar systems to capture hydrological data with sub-hourly latency for predictive inundation mapping and automated alert dissemination. These systems process stream gauge readings, precipitation intensity, and terrain models through cloud-based or edge computing architectures to trigger evacuation protocols and infrastructure lockdowns. IoT Sensors and Radar Systems command the largest installed base but Satellite Imaging represents the fastest-expanding technology segment as constellation providers reduce revisit intervals. Cloud-Based deployment leads in new installations while Hybrid architectures capture margin pools from agencies requiring both local redundancy and centralized analytics access.
The EU Floods Directive and national regulators such as Germany's KBA-adjacent civil protection frameworks and the Netherlands' Rijkswaterstaat standards mandate minimum sensor density and alert response times that shape product certification requirements. Bangladesh's Bangladesh Water Development Board enforces similar technical specifications for transboundary river monitoring that foreign vendors must satisfy for tender eligibility. Stakeholders must monitor evolving interoperability standards between proprietary sensor protocols and open-data platforms as procurement specifications increasingly mandate API-accessible architectures.
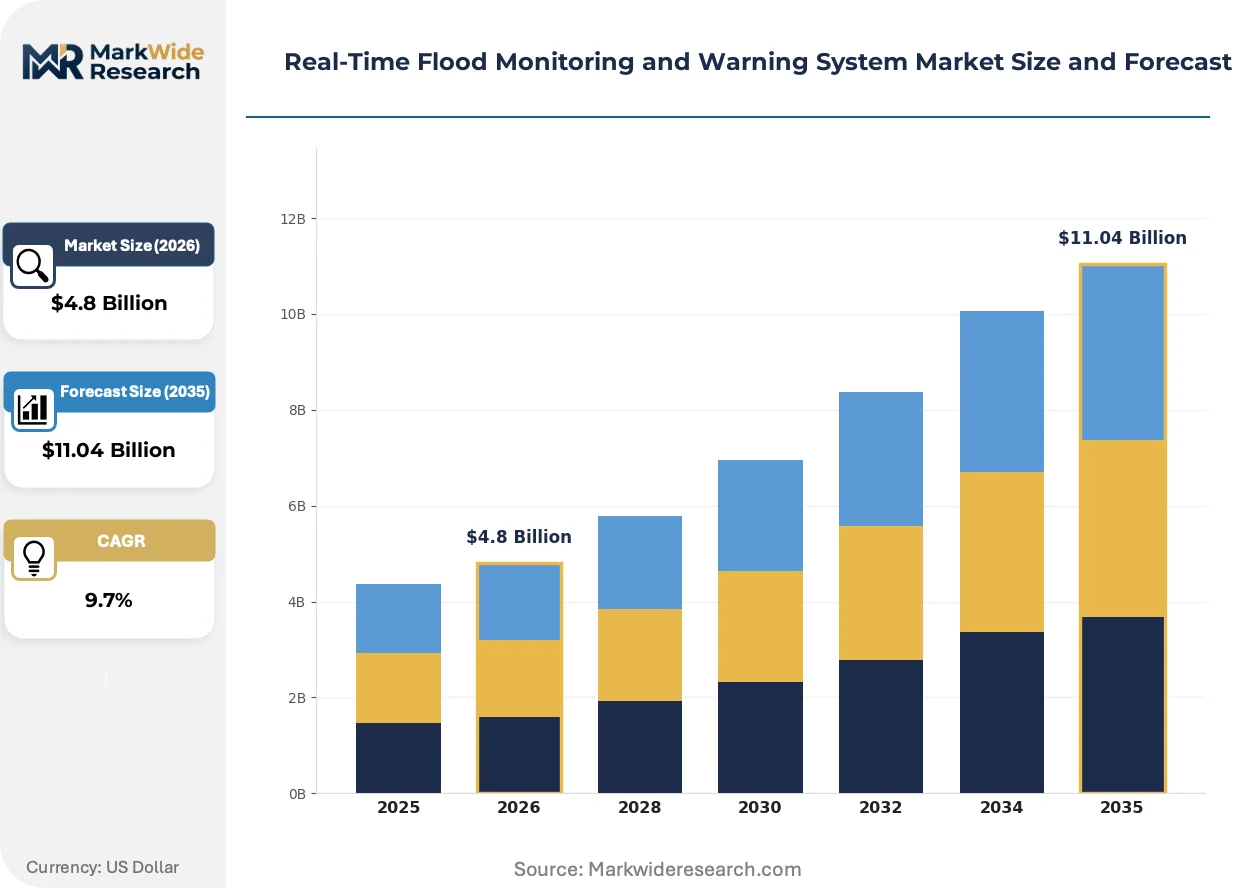
Market Dynamics
Municipal procurement departments are consolidating sensor vendor relationships around platforms offering API-accessible data architectures, compressing the competitive set for standalone hardware suppliers.
Growth Catalysts
- EU Floods Directive:Member states must upgrade early warning infrastructure to mandated response times, forcing water authorities into accelerated replacement cycles for legacy gauge networks.
- Cloud-Based Deployment:Agencies in Germany and the Netherlands favor centralized analytics platforms that reduce on-site maintenance burdens and enable cross-jurisdictional data sharing.
- Delta Region Exposure:Bangladesh's transboundary river monitoring requirements under the Bangladesh Water Development Board create tender eligibility standards that foreign vendors must satisfy.
Market Restraints
- Semiconductor Supply Concentration:Telemetry module production depends on foundry capacity concentrated in East Asia, exposing lead times to geopolitical disruption.
- Calibration Labor Scarcity:Meteorological sensor certification requires specialized technicians whose training pipelines lag deployment schedules in emerging markets.
- Legacy Protocol Entrenchment:Proprietary data formats from incumbent datalogger vendors create switching costs that delay open-platform adoption.
Strategic Opportunities
- Hybrid Architecture Demand:Agencies requiring both local redundancy and centralized access are creating margin pools for integrators capable of edge-cloud orchestration.
- Satellite Constellation Expansion:Reduced revisit intervals from commercial imaging providers are opening predictive inundation mapping contracts previously served only by radar.
- Interoperability Mandates:Procurement specifications increasingly require open-data platform compatibility, favoring vendors with middleware development capabilities.
Industry Challenges
- Field Technician Shortage:Remote watershed station maintenance requires hybrid skills in hydrology and RF communications that training institutions have not scaled.
- Integration Complexity:Municipal IT departments struggle to reconcile proprietary sensor protocols with centralized SCADA systems during multi-vendor deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Real-Time Flood Monitoring and Warning System Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $11.04 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: IoT Sensors, Satellite Imaging, Remote Sensing, Radar Systems Deployment: Cloud-Based, On-Premises, Hybrid, Edge Computing End User: Government Agencies, NGOs, Emergency Services, Research Institutions Application: Disaster Management, Urban Planning, Agriculture Monitoring, Water Resource Management |
| Companies Covered | Honeywell International Inc., OTT Hydromet, Vaisala Oyj, Xylem Inc., Campbell Scientific, Inc., Arteria Technologies Private Limited, Biz4intellia Inc., Siemens, Teledyne Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Real-Time Flood Monitoring and Warning System Market Strategic Shifts & Innovations
Edge computing architectures are absorbing processing workloads that previously required cloud round-trips, reshaping hardware specifications and vendor competitive positioning.
Machine learning inference at the sensor node is absorbing anomaly detection tasks that previously demanded backhaul bandwidth. Dutch water boards are piloting these capabilities at Rhine delta monitoring stations. The shift is compressing alert latency from minutes to seconds for critical infrastructure triggers.
REACH and RoHS compliance deadlines are forcing European vendors to redesign telemetry housings with restricted substance substitutions. Industrial consequences include accelerated R&D cycles and supplier qualification costs. German municipal procurement offices are now requiring material declarations as standard tender attachments.
Subscription-based service models are displacing capital purchase arrangements for satellite imagery analytics. Bangladesh's Water Development Board recently shifted to annual contracts for Ganges-Brahmaputra basin monitoring. The change transfers operational risk to vendors while locking in multi-year revenue visibility.
Real-Time Flood Monitoring and Warning System Market Segmentation
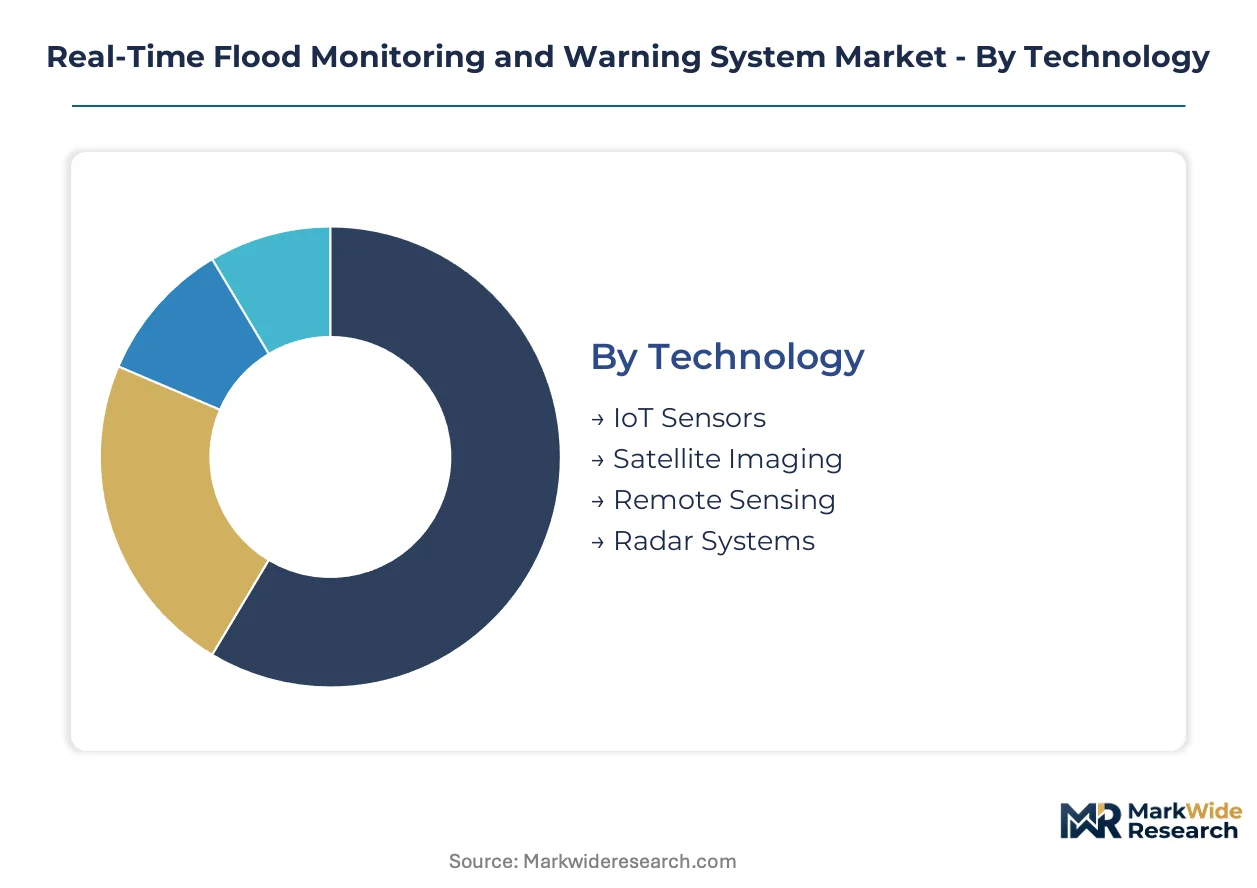
Technology and deployment configurations determine procurement specifications for flood monitoring infrastructure. Municipal authorities select architectures based on latency requirements, maintenance capacity, and interoperability mandates.
Technology:
Standardization dominates sensor hardware while satellite services fragment across constellation providers with varying revisit capabilities.
- IoT Sensors:Networks of submersible pressure transducers, ultrasonic level detectors, and soil moisture probes transmit via LoRaWAN or cellular telemetry. German municipal water authorities deploy dense arrays along Rhine tributaries to meet KBA-adjacent civil protection response-time mandates.
- Radar Systems:Ground-based weather radar and terrestrial interferometric SAR capture precipitation intensity and ground deformation. Bangladesh's Water Development Board specifies minimum radar coverage for Ganges-Brahmaputra transboundary monitoring tenders.
- Satellite Imaging:Synthetic aperture radar and multispectral optical constellations enable basin-scale monitoring without ground infrastructure. Bangladesh's Water Development Board recently shifted to annual subscription contracts for Ganges-Brahmaputra basin monitoring.
- Remote Sensing:Aerial LiDAR and drone-based photogrammetry supplement permanent installations for event-specific damage assessment. Dutch Rijkswaterstaat deploys these for post-flood dike integrity verification.
Leading the category by volume: IoT Sensors. Expanding most quickly: Satellite Imaging.
Deployment:
Cost tier structures separate capital-intensive on-premises installations from operational-expense cloud subscriptions.
- Cloud-Based:Centralized data lakes with API-accessible analytics reduce on-site IT staffing requirements. Agencies in Germany and the Netherlands favor these platforms for cross-jurisdictional data sharing.
- Hybrid:Edge preprocessing with cloud aggregation satisfies agencies requiring local redundancy plus centralized access. These architectures command premium pricing from integrators capable of edge-cloud orchestration.
- On-Premises:Fully localized SCADA integration meets air-gapped security requirements at critical infrastructure sites. German municipal procurement offices increasingly require material declarations as standard tender attachments under REACH and RoHS deadlines.
- Edge Computing:Sensor-node inference absorbs anomaly detection workloads that previously demanded backhaul bandwidth. Dutch water boards pilot these capabilities at Rhine delta stations, compressing alert latency from minutes to seconds.
Capturing the largest share of new installations: Cloud-Based. Steepest expansion trajectory: Hybrid.
End User:
Customer type determines procurement channel and contract structure, from sovereign tenders to research grants.
- Government Agencies:National water boards and municipal authorities issue multi-year framework agreements with technical compliance requirements. Bangladesh Water Development Board enforces sensor density and alert response specifications that foreign vendors must satisfy for tender eligibility.
- Emergency Services:Civil protection departments require mobile command interfaces with automated evacuation protocol triggers. Germany's KBA-adjacent frameworks mandate minimum integration standards for these systems.
- NGOs:Humanitarian organizations prioritize rapid deployability and low-power operation in infrastructure-scarce regions. These buyers favor portable telemetry kits over permanent installations.
- Research Institutions:Universities and hydrological institutes drive demand for open-data platform compatibility and raw sensor access. Procurement specifications increasingly require API-accessible architectures to enable academic collaboration.
Dominating procurement volume: Government Agencies. Gaining share fastest: Emergency Services.
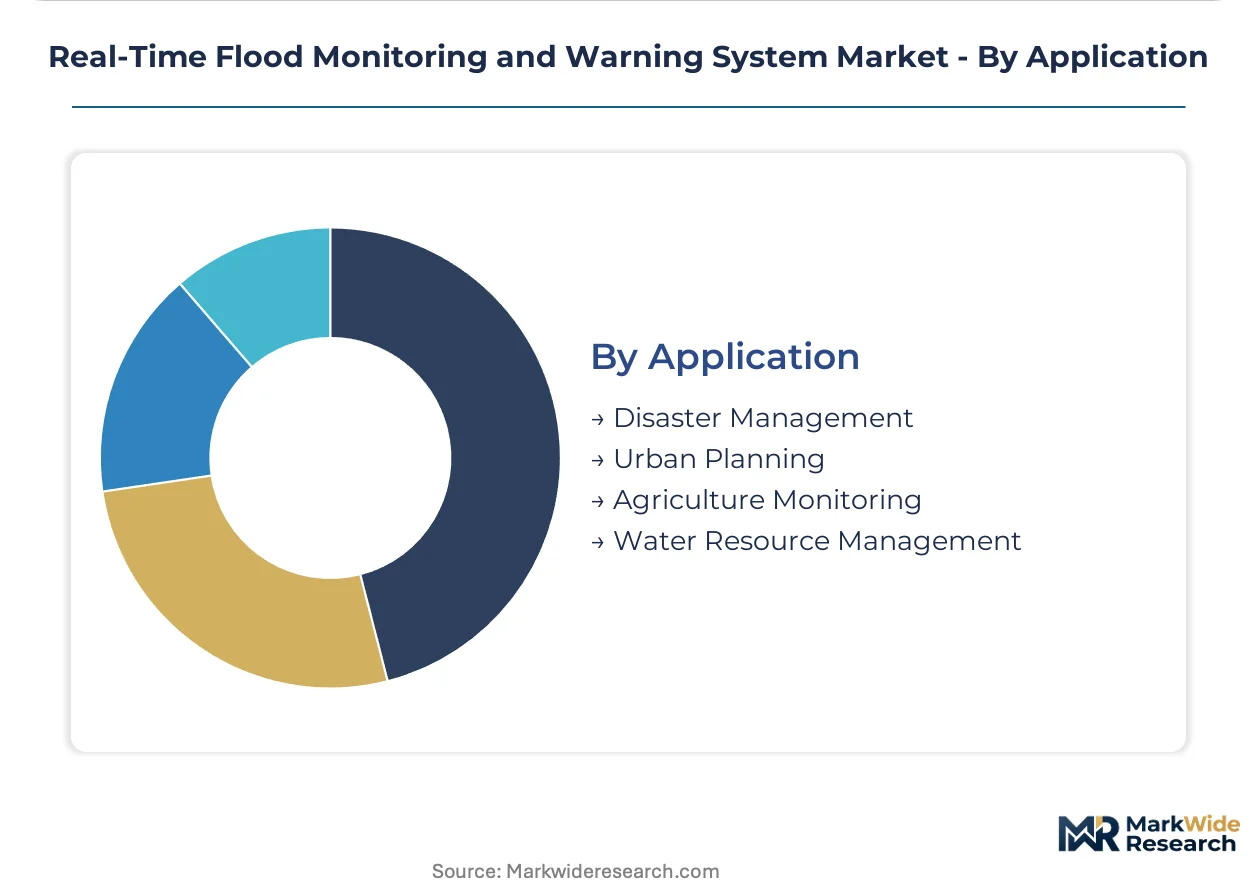
Application:
Maturity varies across use cases, with disaster response commanding established budgets while agricultural applications build evidence bases.
- Disaster Management:Real-time inundation mapping and automated alert dissemination for population evacuation. EU Floods Directive mandates drive replacement cycles for legacy gauge networks across member states.
- Water Resource Management:Reservoir operations, transboundary flow allocation, and irrigation scheduling. Bangladesh's delta exposure creates sustained demand for transboundary river monitoring systems.
- Urban Planning:Stormwater infrastructure design and flood risk zoning for new development. Dutch municipalities integrate these systems with spatial planning databases.
- Agriculture Monitoring:Field-level flood risk assessment and drainage optimization. Emerging applications in precision agriculture remain pilot-scale in most geographies.
Highest current deployment: Disaster Management. Climbing the fastest: Water Resource Management.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon foundries in Taiwan and South Korea supply telemetry modules that German and Dutch water authorities deploy along Rhine tributaries. Bangladesh procures transboundary monitoring hardware through Bangladesh Water Development Board tenders. Municipal procurement in delta regions drives sensor density mandates across three continents.
Germany
Rhine basin flood exposure and KBA-adjacent civil protection frameworks accelerate gauge network replacement cycles. Municipal water authorities enforce minimum sensor density specifications that shape vendor certification requirements. North Rhine-Westphalia hosts dense clusters of hydrological monitoring stations where edge computing pilots compress alert latencies.
Netherlands
Rijkswaterstaat standards mandate API-accessible data architectures for cross-jurisdictional water management. Delta region exposure creates sustained procurement volume for hybrid deployment configurations. Dutch water boards along the Rhine-Meuse-Scheldt delta pilot machine learning inference at sensor nodes.
Bangladesh
Ganges-Brahmaputra transboundary river monitoring requirements drive tender specifications for foreign vendor eligibility. Bangladesh Water Development Board enforces minimum radar coverage and alert response times. Dhaka-based procurement offices recently shifted satellite imagery contracts to annual subscription models.
United States
Army Corps of Engineers watershed management programs and FEMA floodplain mapping initiatives sustain federal procurement channels. Municipal stormwater infrastructure upgrades in hurricane-exposed states drive IoT sensor deployments. Houston-Galveston and Miami-Dade metropolitan areas concentrate pilot programs for integrated radar-satellite alert systems.
China
Yangtze River basin flood control authorities and MIIT IoT infrastructure standards shape domestic procurement specifications. Provincial water resource bureaus in Hubei and Sichuan deploy dense sensor networks for reservoir operations coordination. Chongqing municipality anchors manufacturing clusters for submersible pressure transducer production.
Real-Time Flood Monitoring and Warning System Market Key Industry Players
Vertical integration dominates the current landscape as water analytics specialists absorb telemetry module suppliers to secure municipal deployment contracts. The vendor base separates into three tiers: diversified industrial conglomerates with captive water divisions, pure-play environmental instrumentation firms, and regional system integrators serving single-country procurement channels. Strategic archetypes include full-stack platform providers, specialized sensor calibration houses, and edge-cloud orchestration specialists. M&A activity and API-accessibility investments constitute the dominant competitive moves as procurement specifications harden around open-data mandates.
Among diversified industrial technology providers, Honeywell International Inc., Siemens, and Teledyne Technologies exemplify scale-driven platform consolidation. These conglomerates occupy positions spanning building automation, industrial control systems, and environmental monitoring hardware. Their market presence reflects backward integration strategies that municipal procurement offices favor for multi-site framework agreements. Specialized instrumentation firms including Vaisala Oyj and Xylem Inc. represent pure-play archetypes focused on meteorological calibration and water analytics verticals respectively. Campbell Scientific, Inc. anchors the ruggedized datalogger niche for remote watershed applications.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| OTT Hydromet |
| Vaisala Oyj |
| Xylem Inc. |
| Campbell Scientific, Inc. |
| Arteria Technologies Private Limited |
| Biz4intellia Inc. |
| Siemens |
| Teledyne Technologies |
| Others |
Cost & Logistics Intelligence
Backward integration into telemetry module production anchors both supply security and margin control for vendors serving municipal procurement offices. German water authorities and Bangladesh's Water Development Board increasingly bundle long-term calibration services with hardware purchases, compressing standalone component pricing while elevating integrated platform premiums.
Pricing Analysis
Extended warranty and field-calibration bundling separates premium-tier vendors from unbundled hardware suppliers in municipal tenders. Three-tier pricing structure across premium, standard, and economy levels reflects differentiation by sensor certification grade and API-accessibility compliance. Cost compression in the economy tier is intensifying because semiconductor supply constraints force foundry allocation premiums onto smaller vendors. Research institutions and NGOs exhibit highest price sensitivity, while emergency services departments prioritize latency performance over unit cost.
Supply Chain Analysis
Domestic-content mandates in Bangladesh and evolving EU RoHS compliance deadlines are reshaping sourcing patterns for telemetry housings and sensor assemblies. Semiconductor foundry capacity concentrates in Taiwan and South Korea, while precision sensor manufacturing clusters in Germany and the Netherlands. Raw material dependencies span silicon wafers, rare-earth magnets for radar components, and specialized polymers for submersible housings. Single-source vulnerability in foundry exposure represents the dominant structural risk. Distribution runs through authorized system integrators holding municipal framework agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
A vertical-integration race is underway as water analytics specialists pursue captive control over sensor calibration capabilities to lock in municipal renewal contracts. API-accessibility investments and edge-computing R&D constitute the primary downstream levers shaping competitive position.
For Market Incumbents: Anchor municipal relationships through multi-year calibration service contracts that elevate switching costs for rival platforms. Deepen backward integration into LoRaWAN telemetry chipset supply to insulate margins from foundry allocation volatility. Prioritize hybrid architecture certification under Netherlands Rijkswaterstaat standards to capture premium deployment configurations. For New Entrants and Emerging Players: Channel partners serving Bangladesh's Water Development Board tender processes offer the most accessible entry pathway. Target agricultural monitoring applications in delta regions where incumbent footprint remains sparse. Pursue portable telemetry kit development for NGO procurement channels requiring rapid deployability in infrastructure-scarce watersheds. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to diversified industrial conglomerates seeking water analytics verticals. Long-term viability favors vendors with demonstrated API-accessible platform architectures and edge-cloud orchestration capabilities. Monitor procurement specification shifts toward open-data mandates as the inflection indicator for platform consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| API-Accessible Platform Development | Unlocks tender eligibility under Netherlands Rijkswaterstaat interoperability mandates. |
| Edge Computing Capability Acquisition | Captures hybrid architecture premiums from German municipal water authorities. |
| Calibration Service Contract Expansion | Elevates recurring revenue share and compresses rival switching opportunities. |
| Semiconductor Supply Agreement | Insulates production schedules from Taiwan foundry allocation volatility. |
| Satellite Imagery Subscription Pivot | Aligns with Bangladesh Water Development Board's shift to annual service models. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with municipal water authority procurement officers, hydrological station maintenance technicians, and telemetry module manufacturing executives combined with secondary validation from EU Floods Directive implementation reports, Bangladesh Water Development Board tender documents, and German KBA-adjacent civil protection framework guidelines. Bottom-up sensor deployment counts and top-down infrastructure spending estimates were triangulated to establish market sizing boundaries.
Granularity-level modeling tracked technology segments at the sensor-protocol level, deployment configurations at the edge-cloud architecture level, and end-user categories at the procurement-channel level across the projection horizon. CAGRs were derived from replacement-cycle analysis of legacy gauge networks and satellite constellation revisit-interval improvements. Forecast inputs incorporated Rhine basin flood exposure frequency and Ganges-Brahmaputra transboundary monitoring mandate expansion.
Caveats apply where semiconductor foundry capacity constraints or geopolitical disruption to East Asian supply corridors could materially shift the outlook. Forecasts reflect assumptions regarding EU member state compliance timelines and Bangladesh procurement office subscription-model adoption velocity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Environmental Monitoring
Indoor Air Quality Service Market
Environmental Monitoring
Biofuel Testing Services Market
Environmental Monitoring
Latin America Cloud Seeding Market
Environmental Monitoring
Emission Monitoring Systems Market
Environmental Monitoring
Global Water Quality Monitoring Market
Environmental Monitoring
Water Quality Monitoring Systems Market
Environmental Monitoring
Ecotoxicological Studies Market
Environmental Monitoring
Eco Funnel Market
Environmental Monitoring
North America Emission Monitoring System Market
Environmental Monitoring
Russia Cloud Seeding Market
Environmental Monitoring
Environmental Testing Market
Environmental Monitoring
Middle East and Africa Air Quality Monitoring Market
Environmental Monitoring
Global Cloud Seeding Equipment Market
Environmental Monitoring
Food Security Technology Market
Environmental Monitoring
End-Of-Pipe Air Pollution Control Equipment Market
Environmental Monitoring
Environmental Monitoring (Surface Water) Market