
 Global Weather Forecasting Services Market | 2026-2036
Global Weather Forecasting Services Market Size, Share, and Industry Trends Forecast 2026-2036
Global Weather Forecasting Services Market Foresight
The EU Green Deal is rebalancing procurement priorities across European energy providers, forcing utilities to integrate granular weather intelligence into renewable grid forecasting. Spire Global leverages its satellite constellation architecture to deliver proprietary atmospheric datasets that competitors struggle to replicate. Vaisala Oyj anchors its position through deep instrumentation expertise spanning ground-based sensor networks and upper-air measurement systems. DTN competes by controlling specialized agricultural and energy-sector channels with industry-specific alert protocols.
Weather forecasting services encompass the collection, processing, and dissemination of atmospheric data using numerical models, remote sensing platforms, and statistical techniques to predict temperature, precipitation, wind patterns, and severe weather events with defined spatial resolutions and temporal horizons. These services enable aviation operators to optimize flight paths, maritime companies to route vessels around hazardous conditions, and energy providers to anticipate renewable generation fluctuations. Short-term forecasting and severe weather alerts currently dominate revenue flows due to their critical role in operational safety and emergency response protocols. Machine learning algorithms represent the fastest-expanding technology dimension as vendors train models on satellite data analysis outputs to improve prediction accuracy beyond traditional numerical weather prediction alone. Cloud-based deployment models are capturing disproportionate growth as aviation operators and insurance firms demand scalable API integration without capital-intensive infrastructure commitments.
The European Union's F-Gas Regulation and GDPR framework shape how weather service vendors manage atmospheric sensor data and client information across transnational operations, while the FAA in the United States mandates specific meteorological thresholds for commercial flight planning and airport operations. India's CEA guidelines require power grid operators to incorporate renewable forecasting into dispatch schedules, creating compliance-driven subscription demand. Stakeholders must monitor how divergent data sovereignty requirements between jurisdictions affect cross-border satellite data sharing and model training datasets.
Market Dynamics
Machine learning is compressing prediction timelines across aviation, energy, and agricultural sectors, forcing legacy numerical weather prediction vendors to retrain engineering teams on neural architectures or cede subscription renewals to cloud-native entrants.
Growth Catalysts
- FAA Commercial Flight Planning Mandates:United States aviation operators must procure certified meteorological threshold data for route optimization, creating recurring subscription demand across short-term and medium-range forecasting tiers.
- India CEA Grid Dispatch Rules:Central Electricity Authority guidelines compel power operators to integrate renewable generation forecasts into daily schedules, mandating weather intelligence procurement.
- Cloud API Architectures:Scalable application programming interfaces allow insurance firms and maritime logistics providers to embed granular precipitation and wind data without infrastructure capital deployment.
Market Restraints
- Satellite Launch Cost Volatility:Proprietary atmospheric dataset providers face input cost pressure from launch vehicle pricing and orbital slot licensing fees.
- GDPR Cross-Border Data Friction:European Union data sovereignty requirements restrict transnational satellite data sharing and model training dataset transfers.
- Free Government Forecast Substitution:National meteorological services in Germany, Japan, and the United States provide baseline predictions that commoditize entry-level subscription tiers.
Strategic Opportunities
- Brazil Agricultural Risk Management:Underpenetrated soybean and sugarcane sectors lack granular microclimate forecasting for crop protection and harvest timing.
- EU Green Deal Emissions Monitoring:Renewable grid management mandates create compliance-driven demand for sub-hourly solar irradiance and wind speed intelligence.
- Edge Computing Convergence:On-device inference combines with 5G low-latency networks to enable real-time severe weather alerts for autonomous maritime vessels.
Industry Challenges
- Atmospheric Data Science Talent Scarcity:Neural architecture optimization for numerical weather prediction requires hybrid meteorology-machine learning expertise that academic pipelines underproduce.
- Legacy System Integration Complexity:Energy grid operators struggle to embed API-delivered forecasts into decades-old supervisory control and data acquisition architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Weather Forecasting Services Market |
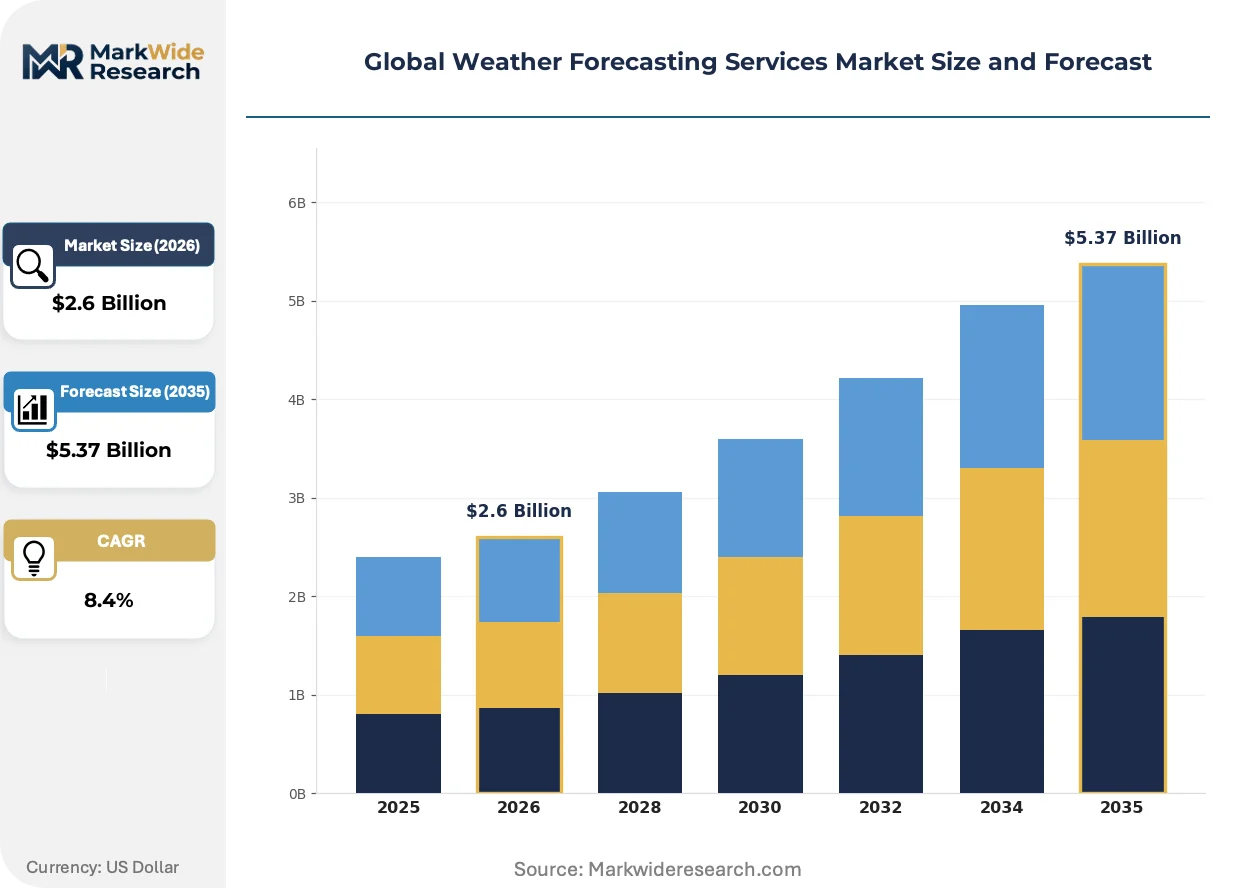
| Market Size in 2026 | $2.6 Billion |
| Market Size in 2035 | $5.37 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Short-Term Forecasting, Long-Term Forecasting, Severe Weather Alerts, Climate Modeling, Marine Forecasting, Agricultural Forecasting Deployment: Cloud-Based, On-Premises, Hybrid, SaaS, API Integration, Mobile Platforms End User: Aviation Operators, Maritime Companies, Energy Providers, Disaster Management Authorities, Event Organizers, Insurance Firms Technology: Numerical Weather Prediction, Statistical Models, Remote Sensing, Radar Technology, Satellite Data Analysis, Machine Learning Algorithms |
| Companies Covered | The Weather Company, AccuWeather Inc., DTN, StormGeo, Fugro, Vaisala Oyj, Spire Global Inc., Pelmorex Corp., Met Office, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Weather Forecasting Services Market Shifts & Advancements
Artificial intelligence architectures are absorbing forecasting workloads that previously required supercomputing clusters, compressing cost structures and democratizing access to previously elite-tier prediction accuracy.
Neural weather models are absorbing medium-range prediction tasks from traditional ensemble systems. European energy traders and Asian insurance underwriters are adopting these architectures fastest. The technology is absorbing capital that previously flowed into physical sensor network expansion.
The EU F-Gas Regulation restricts fluorinated greenhouse gas use in atmospheric measurement instruments. Manufacturers must redesign radiosonde and ozonesonde sensor packages to comply. Ground-based upper-air observation networks in France and Germany face equipment replacement cycles and certification delays.
Subscription unbundling is fragmenting historical all-inclusive contracts. Aviation operators now procure turbulence alerts, volcanic ash tracking, and lightning detection as separate microservices. This pattern is most visible in United States commercial airline procurement departments.
Global Weather Forecasting Services Market Segmentation
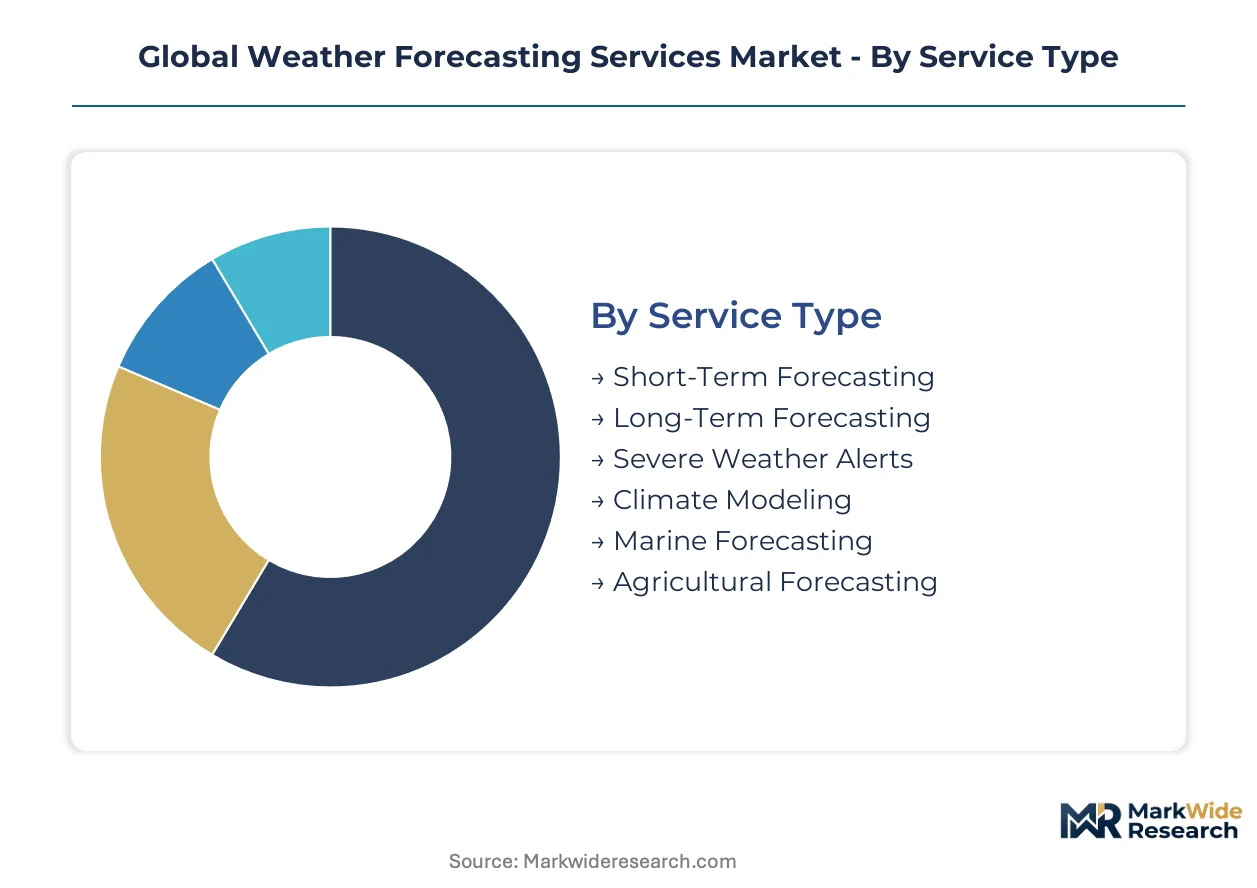
Weather forecasting services fragment across operational horizons, infrastructure preferences, and sector-specific compliance requirements. Each segmentation axis reveals distinct procurement patterns driven by regulatory mandates, data sovereignty concerns, and integration complexity.
Service Type:
Buyers differentiate primarily by prediction horizon and operational criticality, with aviation and energy sectors demanding distinct temporal resolutions.
- Short-Term Forecasting:Predictions spanning 0-72 hours using high-resolution numerical models refreshed at sub-hourly intervals. Aviation operators in the United States procure these services under FAA commercial flight planning mandates, with subscription tiers scaling by airport hub classification.
- Severe Weather Alerts:Automated notification systems triggered by threshold breaches in precipitation, wind velocity, or atmospheric pressure. Disaster management authorities in India and the United States represent concentrated demand as federal preparedness protocols harden.
- Long-Term Forecasting:Extended outlooks beyond 14 days for seasonal agricultural planning.
- Climate Modeling:Decadal-scale simulations supporting infrastructure investment decisions.
- Marine Forecasting:Wave height and sea state predictions for vessel routing optimization.
- Agricultural Forecasting:Microclimate intelligence for planting and harvest timing across commodity crop regions.
Short-Term Forecasting leads volumes today; Severe Weather Alerts is gaining share fastest.
Deployment:
Infrastructure commitments separate capital-constrained buyers from enterprises requiring data sovereignty guarantees.
- Cloud-Based:Scalable delivery through distributed server architectures enabling API consumption without hardware procurement. Insurance firms and maritime logistics providers in Germany and Japan favor this model to avoid capital deployment.
- API Integration:Direct data pipeline embedding into operational software stacks. Energy traders across European power exchanges demand this deployment mode for algorithmic trading system compatibility.
- On-Premises:Localized server installations for classified or sensitive atmospheric data processing.
- Hybrid:Mixed architectures balancing latency-sensitive workloads with archival storage economics.
- SaaS:Browser-accessible dashboards for non-technical decision makers in smaller agricultural cooperatives.
- Mobile Platforms:Smartphone-delivered alerts for field personnel and emergency responders.
Cloud-Based deployments dominate new subscriptions; API Integration shows the steepest expansion trajectory among energy sector buyers.
End User:
Sector-specific regulatory exposure determines service tier procurement and integration complexity.
- Aviation Operators:Commercial airlines and cargo carriers requiring certified meteorological data for flight planning. United States carriers face FAA-mandated threshold compliance creating recurring subscription demand across short and medium-range forecasting tiers.
- Energy Providers:Grid operators and renewable asset managers integrating weather intelligence into dispatch schedules. India's CEA guidelines compel power operators to procure renewable generation forecasts, mandating compliance-driven subscriptions.
- Maritime Companies:Container lines and bulk carriers routing vessels around hazardous conditions.
- Disaster Management Authorities:Government agencies coordinating emergency response protocols.
- Event Organizers:Outdoor venue operators managing cancellation insurance and attendee safety.
- Insurance Firms:Underwriters pricing weather-linked policies through parametric triggers.
Aviation Operators anchor current revenue; Energy Providers are expanding procurement most aggressively under renewable integration mandates.
Technology:
Computational methodology selection separates legacy infrastructure buyers from cloud-native adopters.
- Machine Learning Algorithms:Neural architectures trained on satellite and ground sensor outputs to improve prediction accuracy beyond traditional numerical methods. European energy traders and Asian insurance underwriters are adopting these systems fastest as capital shifts from physical sensor networks.
- Numerical Weather Prediction:Physics-based simulations running on supercomputing clusters. Legacy implementations persist among national meteorological services in Germany and Japan providing baseline forecasts.
- Satellite Data Analysis:Proprietary atmospheric dataset extraction from orbital sensor constellations.
- Remote Sensing:Ground-based and aerial observation platform integration.
- Radar Technology:Precipitation and wind velocity detection through Doppler systems.
- Statistical Models:Historical pattern matching for seasonal outlook generation.
Numerical Weather Prediction retains the largest installed base; Machine Learning Algorithms is climbing the fastest among new procurement decisions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Modern weather forecasting services trace their commercial lineage to post-war meteorological bureau commercialization in the United States, where aviation demand first transformed atmospheric science into subscription revenue. Federal disaster preparedness mandates and private agricultural risk management now sustain multi-tier procurement across distinct national regulatory environments.
United States
FAA commercial flight planning mandates compel aviation operators to procure certified meteorological threshold data for route optimization, generating recurring subscription demand across short-term and medium-range forecasting tiers. The FAA's specific meteorological requirements for commercial operations create compliance-driven procurement patterns. Dallas-Fort Worth and Chicago O'Hare hub operators represent concentrated demand centers where turbulence alerts and volcanic ash tracking deploy as separate microservices.
Germany
Energy traders across European power exchanges demand API integration for algorithmic trading system compatibility, driving cloud-native adoption among weather service vendors. The EU F-Gas Regulation restricts fluorinated greenhouse gas use in atmospheric measurement instruments, forcing equipment replacement cycles in ground-based observation networks. Frankfurt and Munich host dense concentrations of insurance underwriters pricing weather-linked policies through parametric triggers.
India
Central Electricity Authority guidelines compel power grid operators to incorporate renewable generation forecasts into daily dispatch schedules, mandating compliance-driven weather intelligence procurement. The CEA's renewable forecasting requirements create structural subscription demand from state-level distribution companies. Gujarat and Tamil Nadu renewable clusters exhibit the most aggressive procurement as solar and wind asset managers seek sub-hourly irradiance intelligence.
Japan
Maritime logistics providers favor cloud-based deployment models to avoid capital-intensive infrastructure commitments while embedding granular precipitation and wind data into vessel routing systems. METI oversight shapes industrial procurement standards for atmospheric data integration. Yokohama and Kobe port operators represent concentrated demand for wave height and sea state predictions around hazardous condition avoidance.
Brazil
Underpenetrated soybean and sugarcane sectors lack granular microclimate forecasting for crop protection and harvest timing, creating expansion opportunity for agricultural risk management services. ANVISA and national agricultural policy frameworks indirectly shape demand through crop insurance linkage requirements. São Paulo state and Mato Grosso agricultural belts exhibit emerging procurement as cooperatives seek seasonal outlook generation beyond free government baseline predictions.
Global Weather Forecasting Services Market Competitive Landscape
Premium-margin players sit above commodity-margin players across proprietary data asset depth and sector-specific certification tiers. The vendor landscape organizes around satellite constellation operators, deep instrumentation specialists, and channel-controlled vertical applications. Three archetypes dominate: constellation owners delivering proprietary atmospheric datasets, sensor network incumbents with ground-based measurement expertise, and sector-specialized alert protocol controllers. Competitive moves concentrate on API architecture expansion and machine learning model training dataset accumulation.
Within the satellite-native tier, Spire Global Inc. and Vaisala Oyj exemplify contrasting approaches to atmospheric data generation—one through orbital sensor architecture, the other through deep instrumentation heritage spanning ground-based networks. DTN occupies a position in sector-specific channel control, particularly across agricultural and energy alert protocols. The Weather Company and AccuWeather Inc. represent scale-driven archetypes with broad consumer and enterprise reach. These named entities anchor industry-level commentary without specifying individual strategic actions or financial positions.
| Leading Market Players |
|---|
| The Weather Company |
| AccuWeather Inc. |
| DTN |
| StormGeo |
| Fugro |
| Vaisala Oyj |
| Spire Global Inc. |
| Pelmorex Corp. |
| Met Office |
| Others |
Supply & Pricing Matrix
The EU Green Deal's emissions monitoring mandates gate qualified supply and premium-tier pricing access, as vendors must demonstrate F-Gas Regulation compliance in sensor instrumentation and GDPR-aligned data handling to serve European energy providers. Compliance-certified providers command subscription premiums while uncertified competitors face exclusion from renewable grid management procurement.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates certified meteorological data providers from baseline government forecast substitutes. Price differentiation rests on FAA certification tier for aviation operators and API integration complexity for energy traders. Cost compression in entry-level tiers intensifies because free government forecasts from Germany, Japan, and the United States commoditize basic prediction services. Agricultural cooperatives in Brazil exhibit highest price sensitivity; aviation operators under FAA mandates show lowest.
Supply Chain Analysis
Atmospheric data science talent scarcity in France and Germany constrains neural architecture optimization capacity for numerical weather prediction vendors. Proprietary dataset generation draws from orbital sensor constellations, ground-based radiosonde networks, and satellite launch vehicle procurement. Single-source vulnerability concentrates in launch vehicle providers and orbital slot licensing authorities. Distribution runs through cloud API architectures and direct enterprise software embedding.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where FAA commercial flight planning mandates, India CEA grid dispatch rules, and EU Green Deal emissions monitoring create structural subscription demand that compounds across compliance cycles.
For Market Incumbents: Lock in API architecture dominance through backward integration into proprietary satellite constellation operations, neutralizing cloud-native entrants. Defend margin position by accumulating machine learning training datasets that neural weather model competitors cannot replicate without orbital sensor access. For New Entrants and Emerging Players: Launch via mobile platform microservices targeting Brazilian agricultural cooperatives seeking microclimate forecasting beyond free government baselines. Target underpenetrated soybean and sugarcane sectors in São Paulo state and Mato Grosso through seasonal outlook generation partnerships with crop insurance providers. For Investors and Strategic Acquirers: Roll-up economics work for satellite-native atmospheric dataset providers because proprietary orbital sensor access creates irreplicable data moats that compound with each launch. Monitor India CEA guideline enforcement intensity as the inflection signal for renewable forecasting subscription acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Satellite Constellation Expansion | Proprietary orbital sensor networks enable differentiated atmospheric datasets that competitors cannot replicate without capital-intensive launch programs. |
| Machine Learning Model Training | Neural architectures trained on satellite outputs absorb medium-range prediction workloads from traditional ensemble systems. |
| API Architecture Development | Scalable cloud delivery enables insurance firms and maritime logistics providers to embed granular data without infrastructure deployment. |
| Regulatory Certification Investment | FAA meteorological threshold compliance and EU F-Gas Regulation alignment gate premium-tier aviation and energy sector procurement. |
| Agricultural Channel Partnership | Cooperative relationships in underpenetrated Brazilian soybean regions unlock seasonal forecasting demand beyond government baselines. |
Research Methodology
Coverage spans the United States, Germany, India, Japan, and Brazil, with primary inputs from each market's aviation operators, energy grid dispatch officers, maritime logistics coordinators, agricultural cooperative managers, and insurance underwriting specialists. Secondary validation draws from FAA regulatory filings, EIA power generation databases, EU F-Gas Regulation implementation reports, India CEA renewable forecasting guidelines, and METI industrial procurement standards. Bottom-up subscription volume estimates triangulate against top-down market sizing from national meteorological service disclosures and satellite operator revenue segmentation.
Granularity extends to prediction horizon tiers, deployment architecture preferences, and sector-specific compliance requirements across the modeling period. CAGRs derive from segment-level growth rate reconciliation against aggregate market trajectory assumptions. Forecast inputs incorporate aviation fleet expansion schedules, renewable capacity addition pipelines, and agricultural insurance penetration rates by commodity region.
Forecast precision tightens around the base case; tail outcomes carry wider variance under satellite launch cost volatility and GDPR cross-border data friction scenarios. Material deviation in FAA mandate enforcement intensity or India CEA guideline adoption timelines warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Environmental Monitoring
Emission Monitoring Systems Market
Environmental Monitoring
Food Security Technology Market
Environmental Monitoring
Environmental Radiation Monitor Market
Environmental Monitoring
LAMEA Emission Monitoring System Market
Environmental Monitoring
Global on-Line Total Organic Carbon (TOC) Analyzer Market
Environmental Monitoring
Biofuel Testing Services Market
Environmental Monitoring
Testing, Inspection, and Certification for Natural Resources Market
Environmental Monitoring
Global Environmental Remediation Market
Environmental Monitoring
US Cloud Seeding Market
Environmental Monitoring
United States Erosion Sediment Control Market
Environmental Monitoring
Asia-Pacific Cloud Seeding Market
Environmental Monitoring
Ecotoxicological Studies Market
Environmental Monitoring
Cloud Seeding System Market
Environmental Monitoring
Pollution Monitoring Equipment Market
Environmental Monitoring
Latin America Cloud Seeding Market
Environmental Monitoring
Environmental Monitoring (Surface Water) Market