
 United States Erosion Sediment Control Market | 2026-2036
United States Erosion Sediment Control Market Size, Share, and Industry Trends Forecast 2026-2036
United States Erosion Sediment Control Market Analytics
Geotextile fabrics are consolidating market share from traditional burlap and straw-based alternatives as contractors prioritize durability and reusability in large-scale earthwork. ACF Environmental leverages its distribution network across the Southeast to capture municipal highway contracts. GEI Works sustains competitive positioning through specialized manufacturing of custom sediment tanks for industrial site remediation. North American Green anchors its presence in the erosion control blanket segment with proprietary fiber-blend technologies.
United States erosion sediment control encompasses engineered systems and materials designed to intercept, filter, or stabilize soil particles during land disturbance activities, typically incorporating woven or non-woven synthetic geotextiles with specified tensile strengths exceeding 100 lbs/inch to withstand hydraulic and mechanical stress during precipitation events. The primary purpose centers on preventing sediment-laden runoff from entering waterways, thereby protecting aquatic ecosystems and ensuring compliance with federally mandated water quality standards. Silt fences represent the mature volume base, while compost socks are gaining fastest in residential development corridors where space constraints and aesthetic requirements favor flexible, biodegradable alternatives. Highway construction applications command premium pricing due to stringent DOT specifications and extended performance warranties.
EPA administers the National Pollutant Discharge Elimination System, which mandates sediment and erosion control plans for construction sites exceeding one acre, while OSHA enforces worker safety standards during installation of steep-slope stabilization systems. State environmental agencies in California, Texas, and Florida layer additional permitting requirements that elevate product certification thresholds and documentation burdens. Stakeholders must monitor evolving EPA effluent limitation guidelines and state-level green infrastructure mandates that will determine which material technologies qualify for public project procurement.
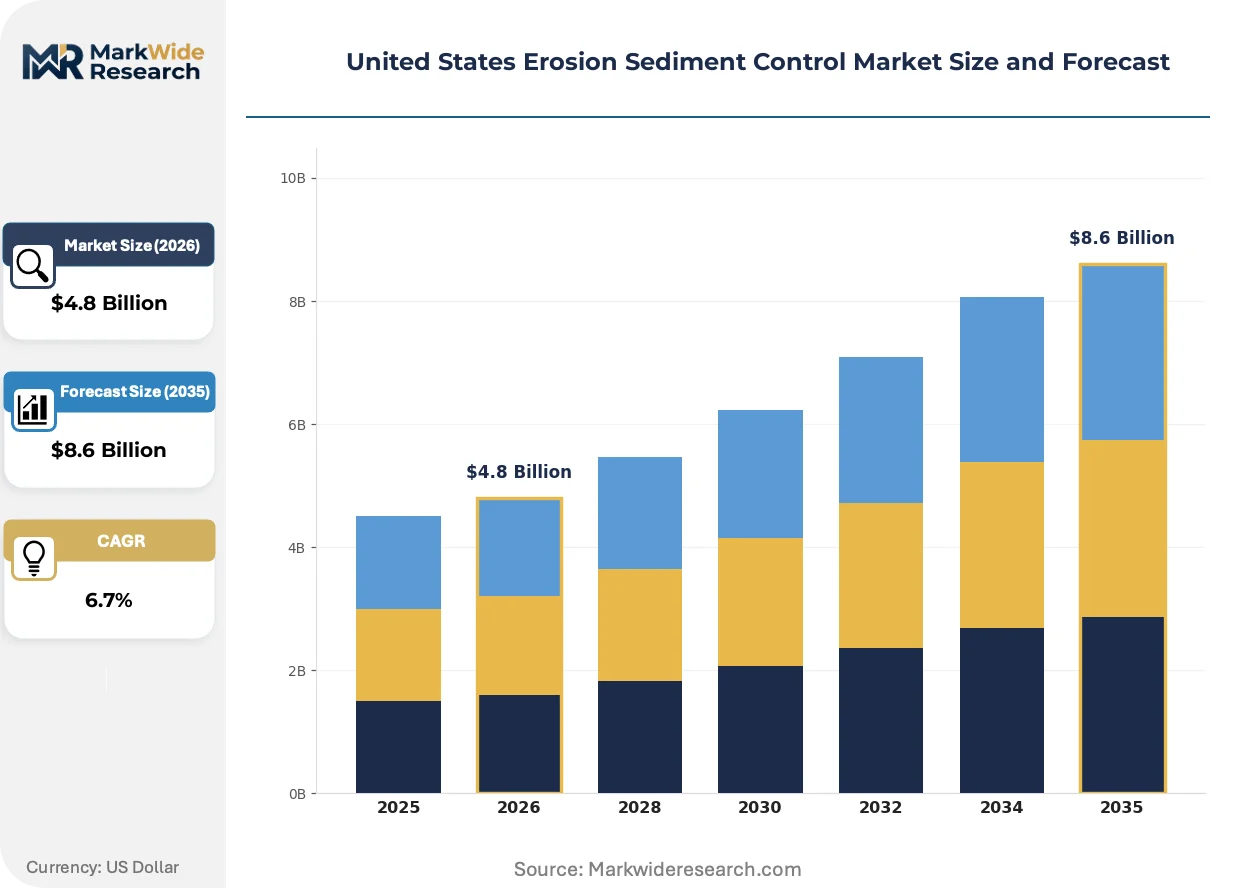
Market Dynamics
State-level NPDES permit tightening is compressing contractor timelines and elevating specification requirements for engineered geotextile systems across highway and residential development corridors.
Growth Catalysts
- Federal Stormwater Mandates:EPA effluent limitation guidelines for construction sites exceeding one acre mandate sediment control plans, forcing compliance spending on silt fences and sediment basins.
- Texas Infrastructure Surge:DOT expansion projects in Dallas-Fort Worth and Houston corridors are absorbing premium-grade erosion control blankets with extended performance warranties.
- Biodegradable Material Substitution:Compost socks manufactured from coconut coir and wood fiber blends are capturing residential development applications where aesthetic and space constraints favor flexible installation.
Market Restraints
- Petrochemical Input Volatility:Polypropylene resin price swings directly compress margins for woven geotextile manufacturers serving the Southeast distribution network.
- Domestic Manufacturing Concentration:Heavy reliance on Southeast U.S. production clusters creates vulnerability to hurricane-season supply interruptions and freight cost spikes.
- Permeability-Longevity Tradeoff:Biodegradable alternatives degrade before project completion in Florida's high-precipitation zones, forcing costly replacement cycles.
Strategic Opportunities
- California Green Infrastructure Mandates:Los Angeles County's low-impact development ordinances are creating specification pathways for permeable sediment control systems in infill construction.
- Industrial Site Remediation:Brownfield redevelopment in the Rust Belt is generating demand for custom sediment tanks with oil-separation capabilities.
- Direct Contractor Platforms:Digital procurement channels are compressing distributor markups and enabling manufacturers to capture municipal specification data directly.
Industry Challenges
- Certified Installer Scarcity:OSHA-mandated training for steep-slope stabilization systems has created bottlenecks in Colorado and Pacific Northwest mountain corridor projects.
- State-Specification Fragmentation:Florida's Department of Environmental Protection maintains divergent geotextile tensile strength thresholds from Texas DOT standards, forcing SKU proliferation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Erosion Sediment Control Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Silt Fences, Sediment Tanks, Erosion Control Blankets, Compost Socks End User: Construction, Mining, Agriculture, Land Development Application: Highway Construction, Residential Development, Industrial Sites, Environmental Restoration Material: Burlap, Geotextiles, Jute, Chemical Polymers |
| Companies Covered | ACF Environmental, Construction Eco Services, Syman Inc., GEI Works, Geosolutions, Inc., Erosion Management Services, Silt Management Supplies, North American Green, The Erosion Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Erosion Sediment Control Market Evolving Landscape
Material science advances and digital specification tools are compressing traditional product lifecycles and reshaping how engineers select erosion control systems for project-specific hydraulic conditions.
Photocatalytic geotextiles incorporating titanium dioxide nanoparticles are degrading organic pollutants in stormwater runoff while maintaining soil retention functions. Florida DOT pilot programs in Tampa Bay watersheds are validating performance data. This convergence of filtration and remediation functions is decentralizing the market away from single-purpose commodity products toward multi-functional engineered systems.
EPA's proposed Construction General Permit renewal will mandate real-time turbidity monitoring for sites exceeding five acres in sensitive watersheds. Industrial consequence includes hardware integration requirements for sediment basin outlets. Texas and California contractors are pre-emptively sourcing smart-valve systems to avoid construction season permitting delays.
Specification authority is migrating from general contractors to resident engineers armed with hydraulic modeling software. Midwest DOT districts now require computational fluid dynamics validation for slope stabilization designs. This technical elevation of procurement standards is visible most acutely in Colorado's mountain highway corridors where geotechnical engineers directly specify fiber-blend compositions.
United States Erosion Sediment Control Market Segmentation
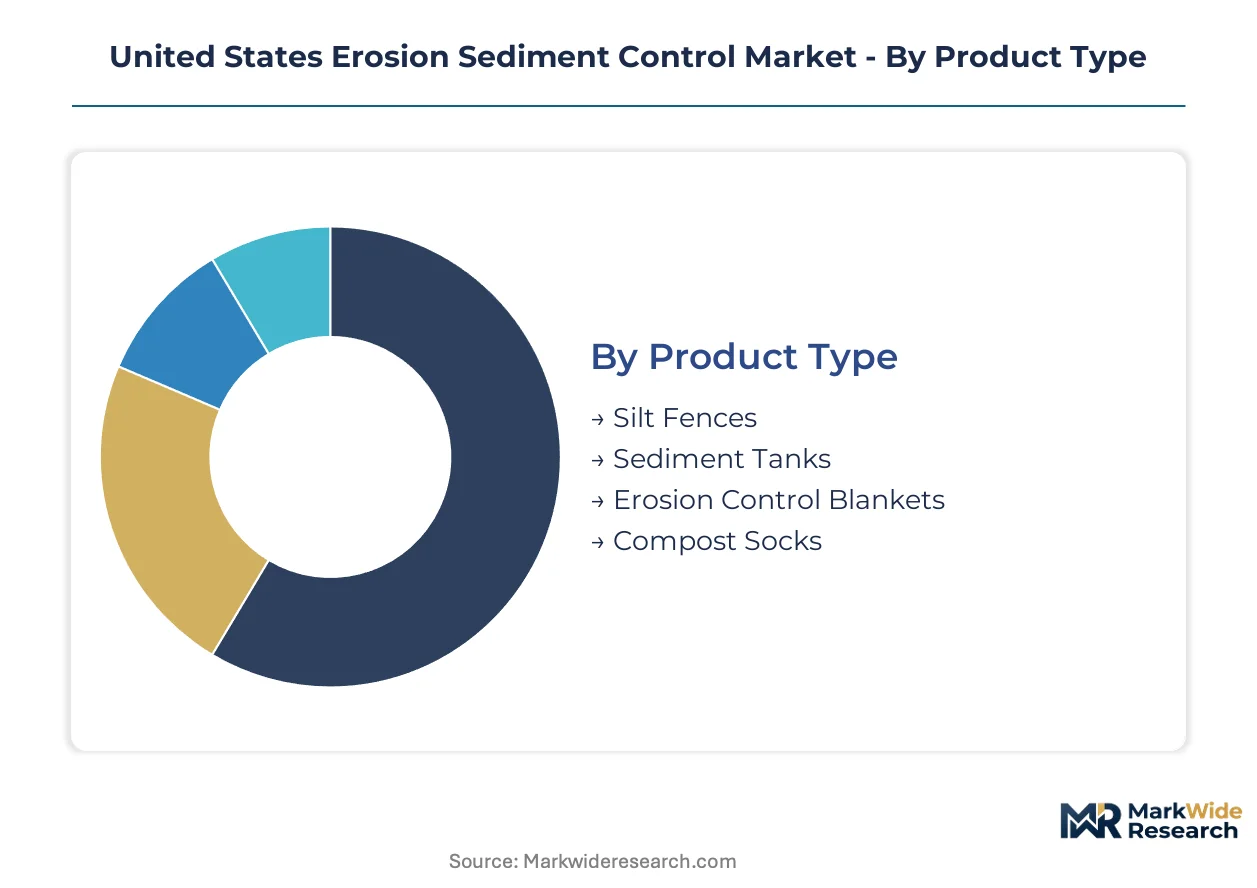
Erosion sediment control procurement hinges on matching material performance to site-specific hydraulic conditions and regulatory exposure. Contractors segment spending across four dimensions: product durability requirements, end-user risk profiles, application scale, and material biodegradability preferences.
Product Type:
Silt fences anchor volume through low unit costs and rapid installation, while engineered systems capture premium pricing through extended warranties and DOT certification.
- Silt Fences:Woven geotextile fabric with 100 lbs/inch minimum tensile strength intercepts sheet flow across disturbed construction sites. Texas DOT specifications dominate procurement volumes, though Florida's high-precipitation zones force replacement cycles that erode lifetime value.
- Erosion Control Blankets:Proprietary fiber-blend matrices stabilize steep slopes against hydraulic shear stress. Highway construction corridors in Colorado and Pacific Northwest mountain regions absorb premium-grade specifications with computational fluid dynamics validation requirements.
- Sediment Tanks:Custom-fabricated detention systems separate suspended solids from runoff prior to discharge. Industrial site remediation in Rust Belt brownfield zones drives specification for oil-separation capabilities.
- Compost Socks:Coconut coir and wood fiber blends filter sediment in space-constrained residential developments. Los Angeles County low-impact development ordinances are creating specification pathways for permeable alternatives.
Today's leader: Silt fences. Tomorrow's challenger: Erosion control blankets.
End User:
Risk tolerance and regulatory scrutiny separate price-sensitive agricultural buyers from compliance-driven construction operators facing EPA NPDES enforcement.
- Construction:EPA-mandated sediment control plans for sites exceeding one acre force systematic procurement of silt fences and sediment basins. California, Texas, and Florida layering additional state permitting requirements elevates product certification thresholds.
- Land Development:Residential infill projects prioritize aesthetic and space constraints, driving biodegradable material substitution in Dallas-Fort Worth and Houston corridors.
- Mining:Large-scale earthwork operations specify heavy-duty geotextile systems with mechanical anchoring for slope stabilization under sustained equipment traffic.
- Agriculture:Cost-sensitive operators favor burlap and straw-based alternatives for temporary field drainage and irrigation channel protection.
Construction commands absolute revenue share. Land development is climbing the fastest.
Application:
Scale and specification authority determine margin structure, with highway DOTs wielding engineering-driven procurement against developer-driven residential volume plays.
- Highway Construction:Stringent DOT specifications and extended performance warranties command premium pricing. Texas DOT expansion projects absorb engineered erosion control blankets with proprietary fiber-blend technologies.
- Residential Development:Space constraints and aesthetic requirements favor flexible, biodegradable alternatives. Compost socks manufactured from coconut coir capture share in infill corridors.
- Industrial Sites:Brownfield redevelopment generates demand for custom sediment tanks with oil-separation capabilities in Rust Belt zones.
- Environmental Restoration:Wetland and riparian buffer projects specify biodegradable materials that integrate with natural succession timelines.
Highway construction sets the specification standard. Residential development offers volume scale.
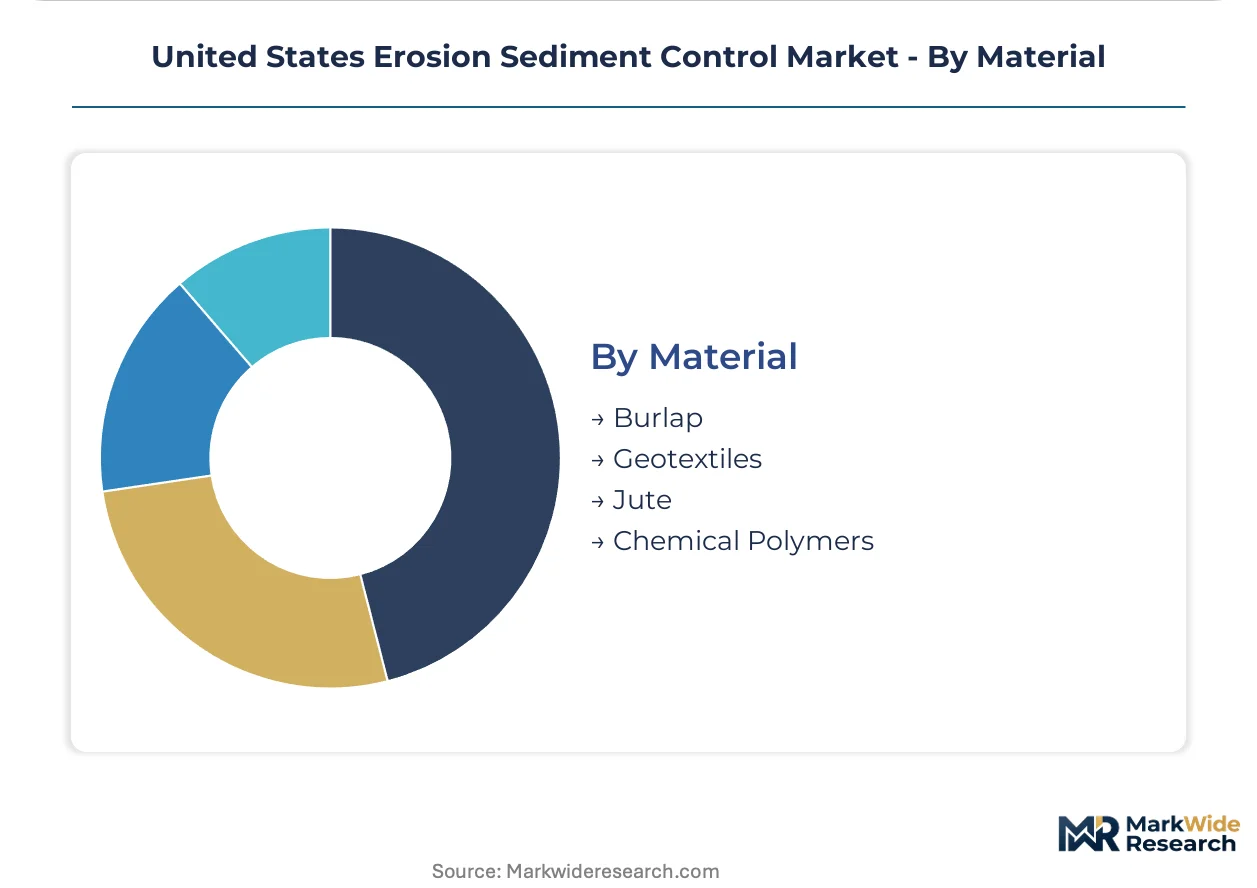
Material:
Performance longevity and environmental compatibility drive substitution patterns, with synthetic durability displacing natural biodegradability in high-stress applications.
- Geotextiles:Woven and non-woven synthetic fabrics with specified tensile strengths exceeding 100 lbs/inch withstand hydraulic and mechanical stress. Southeast U.S. production clusters supply highway construction agencies expanding procurement.
- Chemical Polymers:Polyacrylamide and polyvinyl acetate formulations stabilize soil particles through binding action. Petrochemical input volatility compresses margins for manufacturers.
- Burlap:Traditional woven jute fabric serves cost-sensitive temporary applications with limited performance warranties.
- Jute:Natural fiber erosion control blankets biodegrade within 12-24 months, suiting short-cycle agricultural and restoration projects.
Geotextiles dominate engineered applications. Chemical polymers face margin pressure from resin volatility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Southeast production clusters anchor national supply chains for woven geotextile manufacturers, with Texas and Florida absorbing disproportionate procurement volumes for highway and residential applications.
Texas
Dallas-Fort Worth and Houston corridors drive premium-grade erosion control blanket procurement through DOT expansion projects with extended performance warranties. EPA NPDES permit tightening compresses contractor timelines for sediment control plan implementation. The Permian Basin periphery generates parallel demand from oilfield infrastructure rehabilitation requiring heavy-duty slope stabilization.
California
Los Angeles County low-impact development ordinances create specification pathways for permeable sediment control systems in infill construction corridors. State environmental agencies layer additional permitting requirements above federal EPA baselines, elevating product certification thresholds. Sacramento Valley agricultural drainage projects sustain demand for cost-sensitive burlap alternatives in temporary channel protection.
Florida
High-precipitation zones in Tampa Bay watersheds force replacement cycles for biodegradable alternatives, eroding lifetime value despite aesthetic preferences in residential development. Florida Department of Environmental Protection maintains divergent geotextile tensile strength thresholds from neighboring states, forcing SKU proliferation for multi-state contractors. Miami-Dade coastal infrastructure resilience programs specify proprietary fiber-blend technologies for salt-air exposure conditions.
Pacific Northwest
Colorado mountain highway corridors and Oregon timber access roads require computational fluid dynamics validation for slope stabilization designs, elevating procurement standards. OSHA-mandated training for steep-slope stabilization systems creates certified installer scarcity in remote project zones. Seattle-Tacoma urban stormwater retrofit programs specify photocatalytic geotextiles for dual filtration-remediation functions.
Rust Belt
Brownfield redevelopment in Cleveland and Detroit industrial corridors generates demand for custom sediment tanks with oil-separation capabilities. Legacy manufacturing site remediation faces compressed timelines under state voluntary cleanup programs. Pittsburgh-area shale gas infrastructure maintenance absorbs heavy-duty geotextile systems for access road stabilization under sustained equipment traffic.
United States Erosion Sediment Control Market Competitive Landscape
Capacity expansion dominates the current landscape as Southeast distributors and specialty fabricators add production lines to capture municipal highway contract volumes. The vendor base clusters around three strategic archetypes: regional distribution networks with DOT specification expertise, custom fabrication specialists serving industrial remediation, and proprietary technology holders in fiber-blend matrices. M&A activity concentrates among mid-cap distributors seeking geographic coverage in Texas and Florida corridors, while portfolio diversification drives incumbents toward biodegradable material lines.
Among Southeast-based distributors, ACF Environmental anchors regional coverage for municipal highway procurement, while GEI Works occupies a position within the custom fabrication tier for industrial sediment tank applications. North American Green exemplifies the proprietary technology archetype through specialized positioning in erosion control blanket segments. These three company structures represent the dominant competitive vectors: distribution scale, manufacturing specialization, and materials innovation.
| Leading Market Players |
|---|
| ACF Environmental |
| Construction Eco Services |
| Syman Inc. |
| GEI Works |
| Geosolutions, Inc. |
| Erosion Management Services |
| Silt Management Supplies |
| North American Green |
| The Erosion Company |
| Others |
Value Network & Pricing Analysis
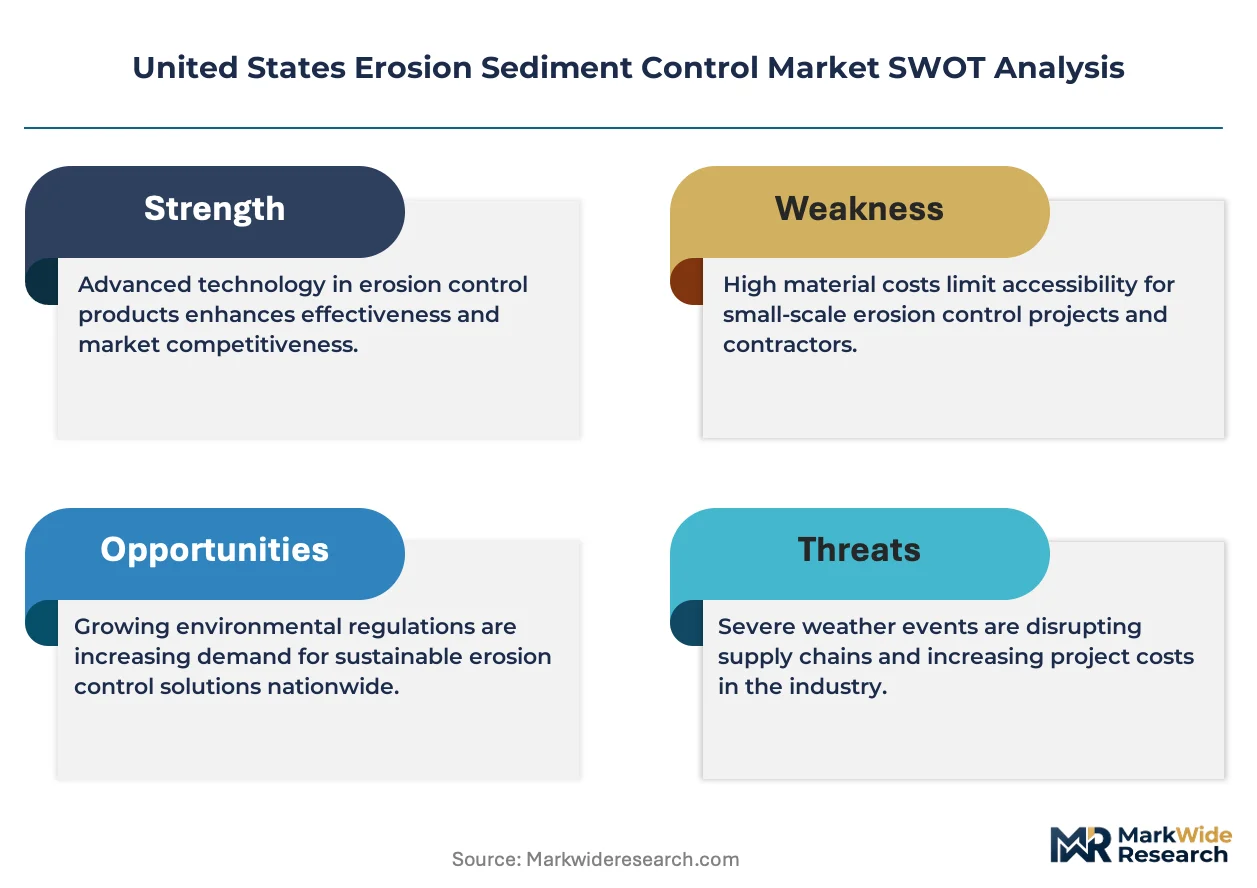
Certified installer scarcity in Colorado and Pacific Northwest mountain corridors widens the labor-cost spread between premium DOT-certified installations and economy-tier residential deployments, compressing margins at the standard tier where contractor training investments compete against price-sensitive developer procurement.
Pricing Analysis
Polypropylene resin price swings pass through directly to woven geotextile manufacturers, forcing three-tier pricing structure across premium DOT-specified, standard municipal, and economy residential levels. Price differentiation hinges on tensile strength certification thresholds and extended performance warranty terms. Margins are tightening due to petrochemical input volatility, with agricultural buyers exhibiting highest price sensitivity against highway construction agencies absorbing premium specifications.
Supply Chain Analysis
Domestic-content mandates in Buy America-compliant highway procurement anchor sourcing decisions, concentrating woven geotextile production in Southeast U.S. clusters. Raw material feeds draw from Gulf Coast polypropylene resin suppliers and domestic fiber-blend compounders. Single-source vulnerability runs through hurricane-exposed Georgia and Alabama manufacturing zones. Distribution runs through regional environmental supply houses with DOT specification expertise.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story as EPA stormwater enforcement hardens specification requirements toward engineered systems with extended performance warranties.
For Market Incumbents: Deepen backward integration into polypropylene resin sourcing to insulate margin compression from petrochemical volatility. Expand certified installer training capacity in Pacific Northwest and Colorado corridors to capture bottleneck premiums. Fortify against biodegradable material substitution by accelerating proprietary fiber-blend R&D. For New Entrants and Emerging Players: Direct contractor platforms offer the lowest-friction entry vector for bypassing established distributor markups. White-space concentrates in Los Angeles County low-impact development corridors where permeable sediment control specifications outpace local supply. Target industrial site remediation in Rust Belt brownfield zones with custom sediment tank fabrication capabilities. For Investors and Strategic Acquirers: Regional distributors with DOT specification expertise are the most active acquirer in this space, consolidating coverage across Texas and Florida highway corridors. Five-to-ten-year viability hinges on positioning ahead of EPA Construction General Permit renewal mandating real-time turbidity monitoring hardware integration. Monitor Florida Department of Environmental Protection geotextile tensile strength threshold revisions as inflection signal for multi-state SKU rationalization plays.| Strategic Initiative | Industry Significance |
|---|---|
| Certified Installer Network Expansion | OSHA-mandated training bottlenecks in mountain corridors create captureable scarcity premiums. |
| Proprietary Fiber-Blend R&D Investment | North American Green demonstrates how material science differentiation commands DOT specification lock-in. |
| Digital Procurement Platform Launch | Direct manufacturer-contractor channels compress distributor markups and yield municipal specification data. |
| Biodegradable Product Line Extension | Compost socks capture Los Angeles County low-impact development ordinance-driven demand. |
| Custom Sediment Tank Fabrication Capacity | Rust Belt brownfield remediation generates oil-separation capability premiums. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with DOT specification engineers, erosion control contractors, municipal procurement officers, and geotextile manufacturing plant managers with secondary validation against EPA effluent limitation guidelines, state NPDES permit databases, FHWA highway construction spending reports, and customs trade data for polypropylene resin flows. Bottom-up project pipeline enumeration triangulated against top-down construction spending forecasts.
Segment-weighting distributed value across product type, end-user risk profile, application scale, and material biodegradability preference dimensions, with highway construction specifications receiving elevated weighting due to DOT certification barriers. CAGRs derived from historical compliance spending elasticity to regulatory tightening events, cross-referenced with petrochemical input cost trajectories and regional infrastructure budget appropriations across the analysis window.
The model assumes a particular technology adoption path; alternative pathways for photocatalytic geotextile degradation functions would alter the outlook. Forecasts reflect assumptions regarding EPA permit renewal timing and state-level green infrastructure mandate propagation. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Environmental Monitoring
Quality Monitoring Sensor for Water Market
Environmental Monitoring
Environmental Test Equipment Market
Environmental Monitoring
Canada Cloud Seeding Market
Environmental Monitoring
Eco Funnel Market
Environmental Monitoring
India Cloud Seeding Market
Environmental Monitoring
LAMEA Emission Monitoring System Market
Environmental Monitoring
Pollution Monitoring Equipment Market
Environmental Monitoring
Ecotoxicological Studies Market
Environmental Monitoring
Environmental Remediation Technologies Market
Environmental Monitoring
Emission Monitoring Systems Market
Environmental Monitoring
Global Cloud Seeding Equipment Market
Environmental Monitoring
Environment Testing Services Market
Environmental Monitoring
Water Quality Analyzer Market
Environmental Monitoring
North America Emission Monitoring System Market
Environmental Monitoring
Carbon Monoxide Analyzers Market
Environmental Monitoring
Global Weather Forecasting Services Market