
 Water Pipeline Leak Detection System Market | 2026-2036
Water Pipeline Leak Detection System Market Size, Share, and Industry Trends Forecast 2026-2036
Water Pipeline Leak Detection System Market Intelligence
Performance expectations between premium fiber-optic systems and commodity acoustic loggers is decoupling as utility procurement teams separate high-risk transmission mains from routine distribution monitoring. Hermann Sewerin GmbH leverages decades of acoustic expertise to dominate European municipal tenders. Atmos International specializes in pressure-wave analytics for oil and gas crossover applications. Mueller Water Products anchors North American market presence through integrated meter-to-leak workflow platforms.
Water pipeline leak detection systems comprise sensor arrays, data loggers, and analytics software engineered to identify pressure anomalies, acoustic signatures, or thermal gradients indicative of breaches in pressurized conduits, typically operating at sampling frequencies between 1 Hz and 10 kHz depending on technology modality. These installations serve primarily to reduce non-revenue water, prevent contamination events, and extend asset life in buried infrastructure networks. Acoustic sensors occupy the largest installed base due to lower per-node cost and mature calibration protocols, while fiber optic sensors represent the fastest-expanding category as distributed temperature and strain sensing enables continuous kilometer-scale coverage. Pressure sensors command premium pricing in critical transmission applications where transient event detection determines emergency response timing.
The United States Environmental Protection Agency drives demand through enforceable maximum contaminant level goals and infrastructure replacement mandates under the Safe Drinking Water Act, while European utilities respond to EU Green Deal water efficiency targets and national leakage reduction commitments. Germany's KBA-equivalent technical standards for pipeline materials indirectly shape sensor compatibility requirements. Stakeholders must monitor regulatory calibration of non-revenue water thresholds against actual sensor deployment economics to avoid stranded technology commitments.
Market Dynamics
Municipal utilities face mounting pressure to reduce non-revenue water as EPA lead-and-copper rule revisions tighten compliance thresholds and state-level mandates accelerate sensor deployment across aging buried infrastructure networks.
Growth Catalysts
- EPA Infrastructure Mandates:The Safe Drinking Water Act drives enforceable maximum contaminant level goals and pipeline replacement schedules, compelling utilities to install continuous monitoring arrays.
- EU Green Deal Water Efficiency Targets:National leakage reduction commitments across Germany, France, and the Netherlands require kilometer-scale sensor coverage for distribution network certification.
- Acoustic Sensor Cost Curves:Mature calibration protocols and semiconductor manufacturing scale have compressed per-node acquisition costs below fiber-optic alternatives by an order of magnitude.
Market Restraints
- Fiber-Optic Component Concentration:Distributed temperature sensing interrogator units depend on specialized photonics foundries concentrated in Germany and Japan, creating supply vulnerability.
- Utility Capex Cycles:Municipal procurement operates on 5-7 year capital improvement timelines that misalign with annual sensor technology refresh rates.
- Pressure Transducer Calibration Drift:Piezoelectric elements in critical transmission applications require field recalibration every 18-24 months, elevating total cost of ownership.
Strategic Opportunities
- Australian Drought-Response Funding:Federal and state water loss programs in New South Wales and Victoria accelerate procurement of integrated meter-to-leak workflow platforms.
- AI-Enhanced Acoustic Analytics:Machine learning classification of leak signatures converges with edge computing architectures to enable real-time breach localization without cloud dependency.
- Performance-Based Service Contracts:Utilities in Germany and the Netherlands are piloting outcome-based arrangements where vendors assume risk for guaranteed non-revenue water reduction thresholds.
Industry Challenges
- SCADA Integration Complexity:Legacy distribution management systems operate on proprietary protocols that require custom middleware development for sensor data ingestion.
- Field Technician Certification Gaps:Distributed fiber-optic installations demand specialized fusion splicing and OTDR interpretation skills that exceed standard utility workforce capabilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Water Pipeline Leak Detection System Market |
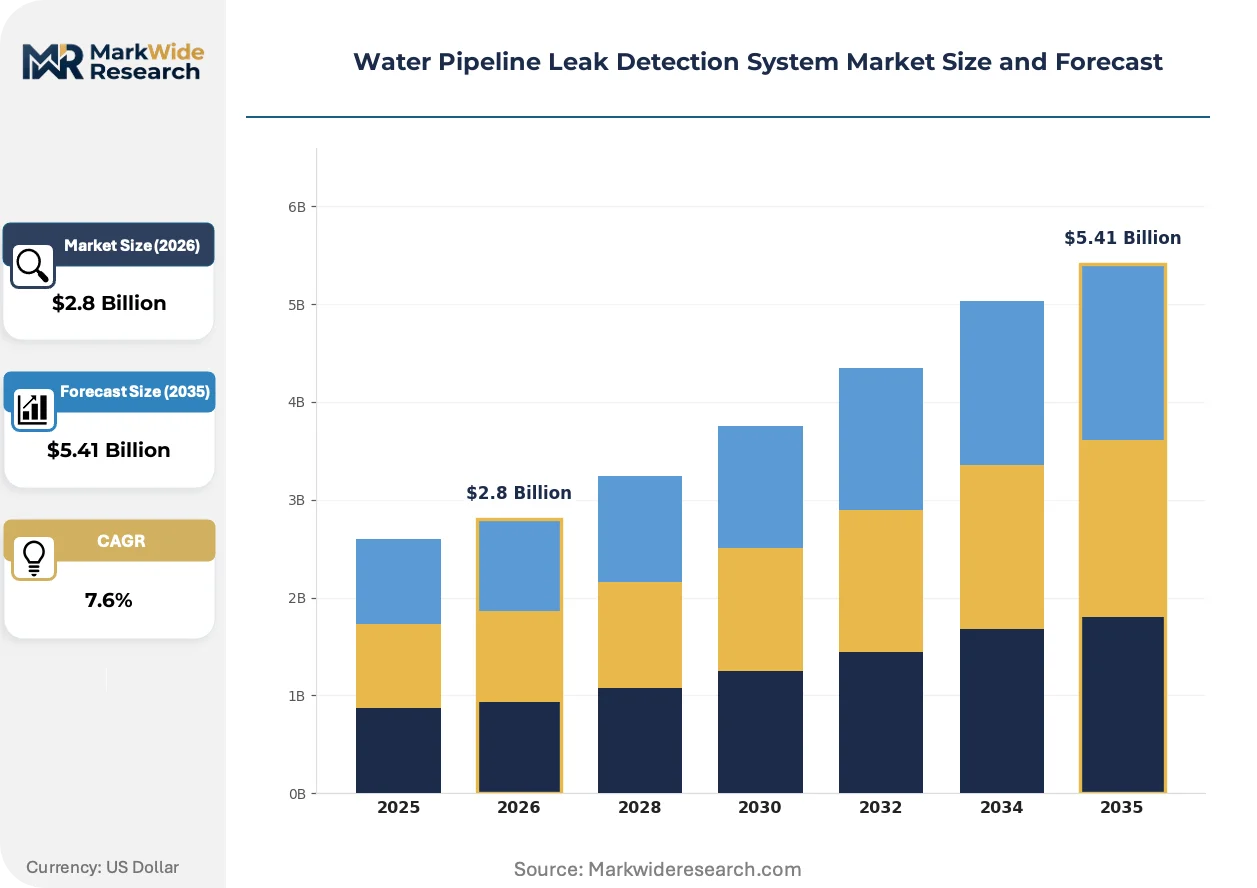
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.41 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Acoustic Sensors, Fiber Optic Sensors, Pressure Sensors, Electromagnetic Sensors End User: Municipal Utilities, Industrial Sector, Commercial Buildings, Residential Users Application: Leak Detection, Pressure Management, Asset Monitoring, Flow Measurement Installation: Surface Mount, In-Pipe, Underground, Remote Monitoring |
| Companies Covered | Hermann Sewerin GmbH, Atmos International, Mueller Water Products, Ovarro Limited, Badger Meter, Gutermann AG, Aqualeak Detection Ltd, QinetiQ Group, Xylem, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Water Pipeline Leak Detection System Market Strategic Shifts & Innovations
Sensor architecture is fragmenting into discrete functional modules that utilities can mix across risk tiers, while regulatory calibration of non-revenue water thresholds forces continuous technology refresh cycles.
Distributed acoustic sensing hardware is modularizing into interchangeable transducer nodes, data loggers, and analytics gateways that utilities configure separately for transmission mains versus distribution laterals. Large metropolitan operators in California and Texas deploy premium fiber-optic backbones for high-consequence pipelines while filling routine grid coverage with commodity acoustic loggers. This bifurcation compresses vendor margins at the mid-market tier while expanding addressable volume at the extremes.
EPA's revised Lead and Copper Rule Improvement requirements mandate inventory validation and replacement prioritization based on material verification, which directly expands demand for in-pipe inspection and leak correlation data. Water utilities must document service line materials by 2024 deadlines, creating immediate procurement urgency for sensor platforms that can isolate lead lateral locations. Large systems in Illinois, Michigan, and Ohio are accelerating pilot programs that integrate leak detection with geospatial asset mapping.
Utility engineering departments are unbundling sensor procurement from installation and maintenance services, treating hardware as capital expenditure and analytics as operational technology subscriptions. This separation disrupts traditional turnkey vendor relationships and elevates specialized systems integrators who bridge multiple sensor modalities. The shift is most pronounced in Germany, where municipal procurement codes favor disaggregated contracting to satisfy public tender transparency requirements.
Water Pipeline Leak Detection System Market Segmentation
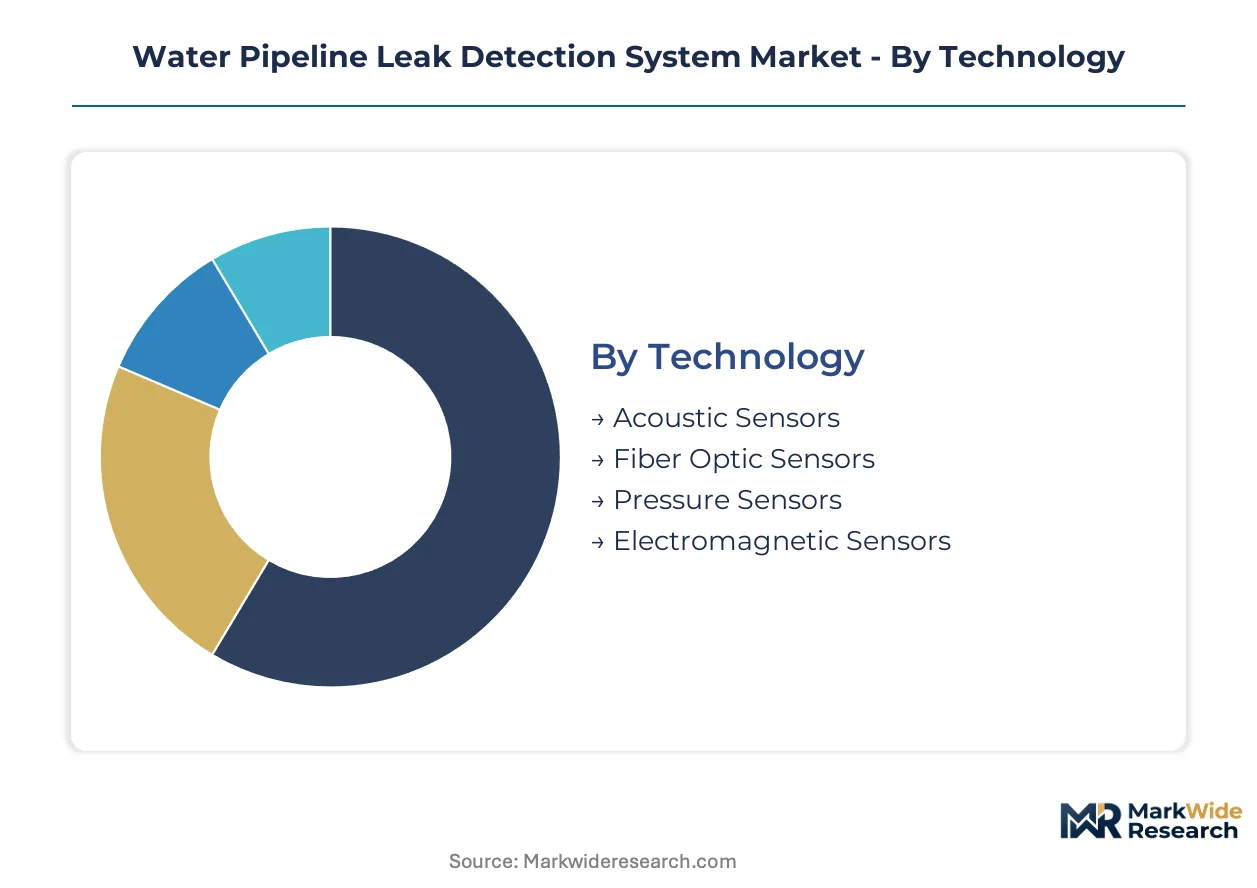
Technology modality, end-user procurement scale, and installation environment dictate sensor selection economics for water pipeline leak detection. Utility engineering departments unbundle hardware from analytics subscriptions, fragmenting traditional vendor relationships across each segment boundary.
Technology:
Procurement teams separate high-risk transmission mains from routine distribution monitoring based on failure consequence and sensor lifecycle cost.
- Acoustic Sensors:Piezoelectric transducers detect pressure-wave signatures from pipe breaches at sampling frequencies between 1 Hz and 10 kHz. Municipal utilities in the United States dominate demand as EPA lead-and-copper rule revisions compress deployment timelines for aging infrastructure inventory validation.
- Fiber Optic Sensors:Distributed temperature and strain sensing interrogators enable continuous kilometer-scale coverage through backscattered light analysis. Germany and Australia concentrate procurement as EU Green Deal water efficiency targets and federal drought-response funding accelerate premium sensor deployment across transmission networks.
- Pressure Sensors:Piezoelectric elements monitor transient events in critical transmission applications where emergency response timing determines asset protection.
- Electromagnetic Sensors:Inductive coils detect flow anomalies and metallic pipe corrosion signatures in specialized industrial feedwater systems.
Volume sits with Acoustic Sensors; growth tilts toward Fiber Optic Sensors.
End User:
Capital expenditure scale and regulatory exposure determine procurement sophistication across customer tiers.
- Municipal Utilities:Public water systems operate 5-7 year capital improvement cycles that misalign with annual sensor technology refresh rates. State-level non-revenue water mandates in Illinois, Michigan, and Ohio accelerate integrated meter-to-leak workflow procurement.
- Industrial Sector:Power generation and chemical processing facilities demand pressure-wave analytics for high-consequence cooling water and process feed lines.
- Commercial Buildings:Property management groups deploy surface-mount acoustic loggers for insurance compliance and leak liability reduction.
- Residential Users:Smart home integration drives demand for low-cost flow monitoring devices with cloud-based alert services.
Municipal Utilities command procurement volume; Industrial Sector applications expand most quickly.
Application:
Functional requirements fragment sensor architecture into discrete modules configurable across risk tiers.
- Leak Detection:Core function combining acoustic signature classification with pressure anomaly correlation. California and Texas metropolitan operators deploy mixed-modality arrays for high-consequence pipeline coverage.
- Pressure Management:Transient event detection determines emergency response timing in critical transmission infrastructure.
- Asset Monitoring:Strain and vibration sensing extends pipe life prediction for buried infrastructure networks.
- Flow Measurement:Ultrasonic and electromagnetic insertion meters support non-revenue water accounting and district metered area balancing.
Leak Detection anchors installed base; Asset Monitoring climbs the fastest as predictive maintenance programs mature.
Installation:
Deployment environment dictates technician skill requirements and total cost of ownership calculations.
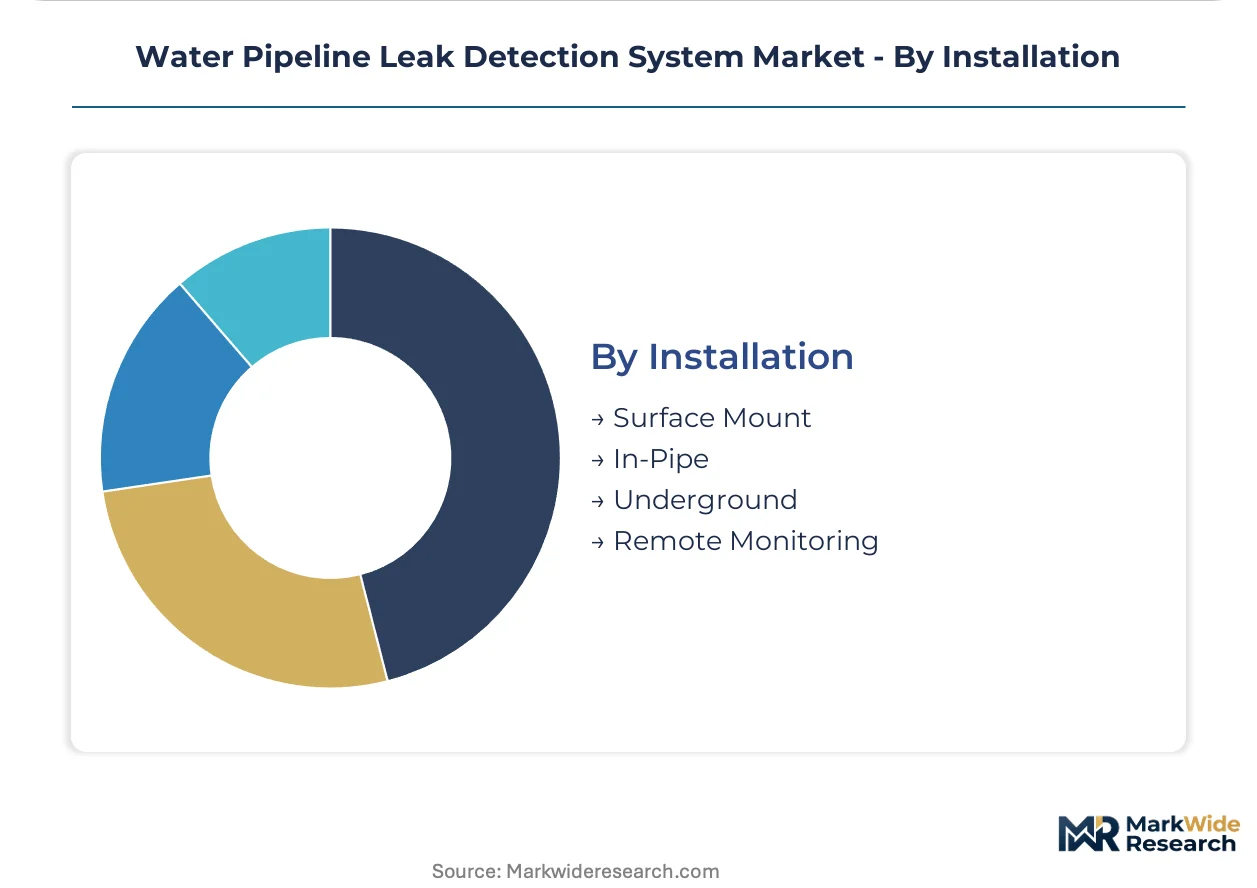
- Surface Mount:External clamp-on transducers and correlation loggers enable rapid deployment without service interruption. Standard utility workforce capabilities accommodate this tier across routine distribution grids.
- In-Pipe:Tethered inspection platforms and free-swimming acoustic sensors isolate lead lateral locations for EPA material verification deadlines.
- Underground:Direct burial installations demand specialized fusion splicing and OTDR interpretation skills that exceed standard municipal technician certification.
- Remote Monitoring:Cellular and satellite telemetry architectures enable cloud-independent edge computing for rural and isolated infrastructure.
Surface Mount dominates deployment volume; In-Pipe installations gain share fastest from regulatory inventory mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Houston anchors North American procurement velocity as Texas utilities accelerate sensor deployment across drought-stressed transmission networks. Metropolitan operators in California and Texas now deploy mixed-modality arrays combining premium fiber-optic backbones with commodity acoustic loggers.
United States
EPA lead-and-copper rule revisions compress deployment timelines for aging infrastructure inventory validation. The Safe Drinking Water Act mandates enforceable maximum contaminant level goals and pipeline replacement schedules. Large systems in Illinois, Michigan, and Ohio accelerate pilot programs integrating leak detection with geospatial asset mapping.
Germany
EU Green Deal water efficiency targets and national leakage reduction commitments require kilometer-scale sensor coverage for distribution network certification. KBA-equivalent technical standards for pipeline materials indirectly shape sensor compatibility requirements. Municipal procurement codes in Bavaria and North Rhine-Westphalia favor disaggregated contracting to satisfy public tender transparency requirements.
Australia
Federal and state water loss programs in New South Wales and Victoria accelerate procurement of integrated meter-to-leak workflow platforms. Drought-response funding from the national government elevates premium sensor deployment across transmission networks. Sydney Water and Melbourne metropolitan utilities pilot outcome-based service contracts with guaranteed non-revenue water reduction thresholds.
United Kingdom
Ofwat price review mechanisms pressure water companies to reduce leakage below statutory targets through continuous monitoring investment. The Environment Agency enforces abstraction licensing conditions that tighten permissible water loss rates. Thames Water and United Utilities deploy distributed acoustic sensing across high-consequence pipelines in London and the Northwest.
Japan
METI infrastructure modernization directives promote smart water grid investments to address earthquake-vulnerable buried pipelines. Aging population dynamics strain municipal workforce capacity for field maintenance of conventional detection systems. Tokyo Metropolitan Government accelerates fiber-optic sensor deployment across the Kanto region's critical transmission mains.
Water Pipeline Leak Detection System Market Key Industry Players
Premium-margin players sit above commodity-margin players across technology modality and installation complexity tiers. The vendor base separates into acoustic specialists, fiber-optic platform providers, and integrated workflow vendors. Three strategic archetypes dominate: European acoustic heritage houses, North American meter-to-leak integrators, and oil-and-gas crossover analytics firms. Competitive moves concentrate on AI-enhanced acoustic analytics development and performance-based service contract piloting.
Within the acoustic heritage tier, Hermann Sewerin GmbH and Gutermann AG exemplify decades-long municipal tender dominance through calibrated transducer expertise. Atmos International occupies a position bridging pressure-wave analytics from hydrocarbon transmission into water infrastructure applications. Mueller Water Products anchors the North American integrated workflow segment through meter-to-leak platform unification.
| Leading Market Players |
|---|
| Hermann Sewerin GmbH |
| Atmos International |
| Mueller Water Products |
| Ovarro Limited |
| Badger Meter |
| Gutermann AG |
| Aqualeak Detection Ltd |
| QinetiQ Group |
| Xylem |
| Others |
Cost & Logistics Intelligence
Family-owned acoustic heritage houses in Germany and Switzerland anchor supply discipline through multi-generational engineering investment, translating into rigid pricing protocols that resist commodity erosion despite pressure from semiconductor-scaled sensor producers. This ownership structure insulates premium-tier vendors from short-term margin compression while forcing mid-market players toward outcome-based contracting to defend position.
Pricing Analysis
Value-based pricing anchored to guaranteed non-revenue water reduction thresholds commands premium positioning in German and Dutch municipal tenders. Three-tier pricing structure across premium fiber-optic, standard acoustic correlation, and economy logger tiers reflects certification grade and after-sales bundling differentiation. Cost compression in commodity acoustic nodes intensifies as Chinese semiconductor foundries scale piezoelectric transducer output. Small rural utilities exhibit highest price sensitivity, while metropolitan operators in California and Texas prioritize uptime guarantees over per-node acquisition cost.
Supply Chain Analysis
Certification gating through EPA lead-and-copper compliance documentation and EU Green Deal water efficiency verification shapes vendor qualification requirements. Photonics foundries in Germany and Japan concentrate distributed temperature sensing interrogator production, drawing from specialized silica fiber and indium phosphide components. Single-source vulnerability in OTDR calibration equipment creates chokepoint exposure for fiber-optic deployment scale. Distribution runs through municipal procurement portals and specialized water infrastructure integrators rather than direct manufacturer channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EPA Lead and Copper Rule Improvement mandates erect a cost-of-compliance moat that favors incumbents with validated inventory correlation capabilities, raising capital barriers for unproven sensor platforms.
For Market Incumbents: Deepen acoustic analytics R&D investment to counter AI-native entrants attacking the signature-classification layer. Acquire specialized OTDR interpretation training capabilities to address field technician certification gaps threatening fiber-optic deployment velocity. Consolidate position through backward integration into edge computing hardware to capture analytics subscription revenue streams. For New Entrants and Emerging Players: Mid-sized industrial facilities with cooling water liability exposure represent an underserved buyer archetype with compressed procurement cycles and limited incumbent relationships. Penetrate this segment through pressure-wave analytics cross-licensed from oil and gas applications, bypassing municipal tender complexity. Target New South Wales and Victoria drought-response funding windows for first commercial reference deployments. For Investors and Strategic Acquirers: Distressed-cycle entries favor acoustic heritage specialists with established KBA-equivalent certification relationships in German-speaking Europe. Long-term viability hinges on AI-enhanced analytics integration rather than hardware commoditization trajectories. Watch for EPA enforcement variance across state environmental agencies as inflection signal for compliance-driven procurement acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| AI-Enhanced Acoustic Analytics Development | Machine learning classification of leak signatures enables real-time breach localization without cloud dependency for California utilities. |
| Performance-Based Service Contract Piloting | Outcome-based arrangements in Germany and Netherlands transfer non-revenue water reduction risk from municipalities to vendors. |
| Edge Computing Hardware Integration | On-device analytics processing addresses SCADA integration complexity and reduces latency for critical transmission applications. |
| Field Technician Certification Programs | OTDR interpretation and fusion splicing training closes workforce capability gaps threatening fiber-optic deployment scale. |
| Meter-to-Leak Workflow Platform Unification | Integrated data layers from AMI networks through leak correlation software compresses response time for Illinois and Ohio utilities. |
Research Approach
Independent corroboration across utility engineering directors, municipal procurement officers, and acoustic sensor calibration specialists underwrites the qualitative findings. Primary interviews with distribution network managers at metropolitan water authorities in California, Texas, and Germany combined with secondary validation from EPA enforcement databases, EU Green Deal implementation reports, and state-level non-revenue water mandate documentation. Bottom-up sensor deployment unit economics triangulate against top-down municipal capital expenditure forecasts.
Rate-of-change decomposition across technology modality adoption curves, regulatory compliance deadline clustering, and utility digitization program phasing structures the analytical framework. Segmentation dimensions span sensor technology, end-user procurement scale, installation environment, and application function. CAGRs derive from installed base growth trajectories and replacement cycle compression. Forecast inputs incorporate drought-response funding allocation patterns and lead lateral inventory verification urgency.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EPA enforcement variance and photonics component supply concentration. Projections reflect assumptions regarding municipal capex cycle alignment with sensor refresh rates and AI analytics adoption velocity. A model refresh is warranted upon material change in Lead and Copper Rule Improvement enforcement thresholds or distributed acoustic sensing cost curve inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Environmental Monitoring
Environmental Technology Market
Environmental Monitoring
Canada Cloud Seeding Market
Environmental Monitoring
Environmental Remediation Technologies Market
Environmental Monitoring
Carbon Monoxide Analyzers Market
Environmental Monitoring
Global Environmental Sensor Market
Environmental Monitoring
Environmental Hazard Monitoring (EHM) Software Market
Environmental Monitoring
Europe Air Quality Monitoring Market
Environmental Monitoring
End-Of-Pipe Air Pollution Control Equipment Market
Environmental Monitoring
Eco Funnel Market
Environmental Monitoring
Russia Cloud Seeding Market
Environmental Monitoring
Latin America Cloud Seeding Market
Environmental Monitoring
Asia Pacific Air Quality Monitoring Market
Environmental Monitoring
Environmental Radiation Monitor Market
Environmental Monitoring
United States Erosion Sediment Control Market
Environmental Monitoring
Global Indoor Air Quality Solutions Market
Environmental Monitoring
Soil Remediation Technologies Market