
 Ecotoxicological Studies Market | 2026-2036
Ecotoxicological Studies Market Size, Share, and Industry Trends Forecast 2026-2036
Ecotoxicological Studies Market Intelligence
Pharmaceutical developers is collapsing as the dominant buyer archetype for ecotoxicological contract research, while agrochemical and industrial chemical registrants capture expanded service volumes. Eurofins Scientific leverages its pan-European laboratory network to anchor aquatic and terrestrial toxicity study capacity across multiple regulatory jurisdictions. Charles River Laboratories sustains competitive positioning through specialized fish early life stage testing infrastructure that supports EPA and OECD guideline compliance. SGS dominates environmental fate and biodegradation study outsourcing for European chemical consortia navigating REACH data requirements.
Ecotoxicological studies comprise controlled laboratory, field, or computational investigations that measure adverse effects of chemicals, pharmaceuticals, or pollutants on non-target organisms under standardized OECD, EPA, or ISO test guidelines, typically quantifying lethal concentration thresholds, no-observed-effect concentrations, or population-level endpoints across multiple trophic levels to satisfy regulatory hazard classification and risk assessment mandates. Laboratory studies occupy the largest revenue share due to reproducible conditions and regulatory acceptability, while modeling approaches represent the fastest-expanding segment as in silico prediction tools gain regulatory traction under REACH and EPA New Chemicals programs. Risk assessment as a study purpose commands premium pricing relative to baseline hazard identification, reflecting the specialized toxicological expertise and weight-of-evidence synthesis required for product registration dossiers.
The EPA administers the Toxic Substances Control Act and Endangered Species Act consultation requirements that mandate ecotoxicity data for new chemical approvals, while the EMA and ECHA jointly enforce pharmaceutical and industrial chemical environmental risk assessment obligations across European markets. REACH authorization and restriction processes, alongside the EPA's updated aquatic life benchmarks, intensify demand for higher-tier multispecies and mesocosm studies that extend beyond standard acute toxicity protocols. Stakeholders must monitor evolving regulatory acceptance of alternative test methods and integrated testing strategies to optimize study portfolios against shifting data requirements.
Market Dynamics
REACH authorization timelines and EPA aquatic life benchmark updates are compressing study delivery windows while simultaneously expanding data requirements for higher-tier multispecies and mesocosm investigations.
Growth Catalysts
- REACH Substance Evaluation:ECHA's tightening data requirements for industrial chemical consortia generate sustained contract volumes for aquatic toxicity and environmental fate studies across European member states.
- Pharmaceutical Environmental Risk Assessment:EMA mandates for marketing authorization applications now embed aquatic toxicity testing as a standard dossier component, pulling service demand from drug developers.
- Computational Toxicology:In silico prediction tools under OECD QSAR guidelines are gaining regulatory traction, enabling faster screening workflows that expand total study throughput.
Market Restraints
- Specialized Infrastructure Costs:Fish early life stage testing requires purpose-built aquaculture facilities with temperature-controlled recirculation systems, creating capital barriers for new laboratory entrants.
- Reference Substance Supply Concentration:Certified reference materials for aquatic toxicity calibration concentrate among three European suppliers, exposing contract research organizations to input price volatility.
- Study Duration Rigidity:OECD 210 fish early life stage protocols mandate 28- to 32-day exposure periods that cannot compress, limiting revenue velocity for fixed-capacity laboratories.
Strategic Opportunities
- Integrated Testing Strategies:REACH and EPA New Chemicals programs now accept weight-of-evidence approaches combining in silico, in chemico, and in vivo data, creating service bundling opportunities for laboratories with cross-method capability.
- Biodegradation Study Outsourcing:European chemical consortia navigating REACH data requirements increasingly contract environmental fate studies to specialized providers rather than maintaining in-house anaerobic digester infrastructure.
- Terrestrial Toxicity Expansion:Soil macroorganism and plant testing protocols remain underserved relative to aquatic studies, presenting white space for laboratories with existing ecotoxicology expertise.
Industry Challenges
- Ecotoxicologist Talent Pipeline:Universities produce fewer graduates with combined toxicology and aquatic biology training than industry demand requires, extending recruitment cycles for specialized study directors.
- Guideline Revision Lag:OECD test guideline updates occur on multi-year cycles, leaving laboratories exposed to regulatory acceptance uncertainty for novel alternative methods during validation periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ecotoxicological Studies Market |
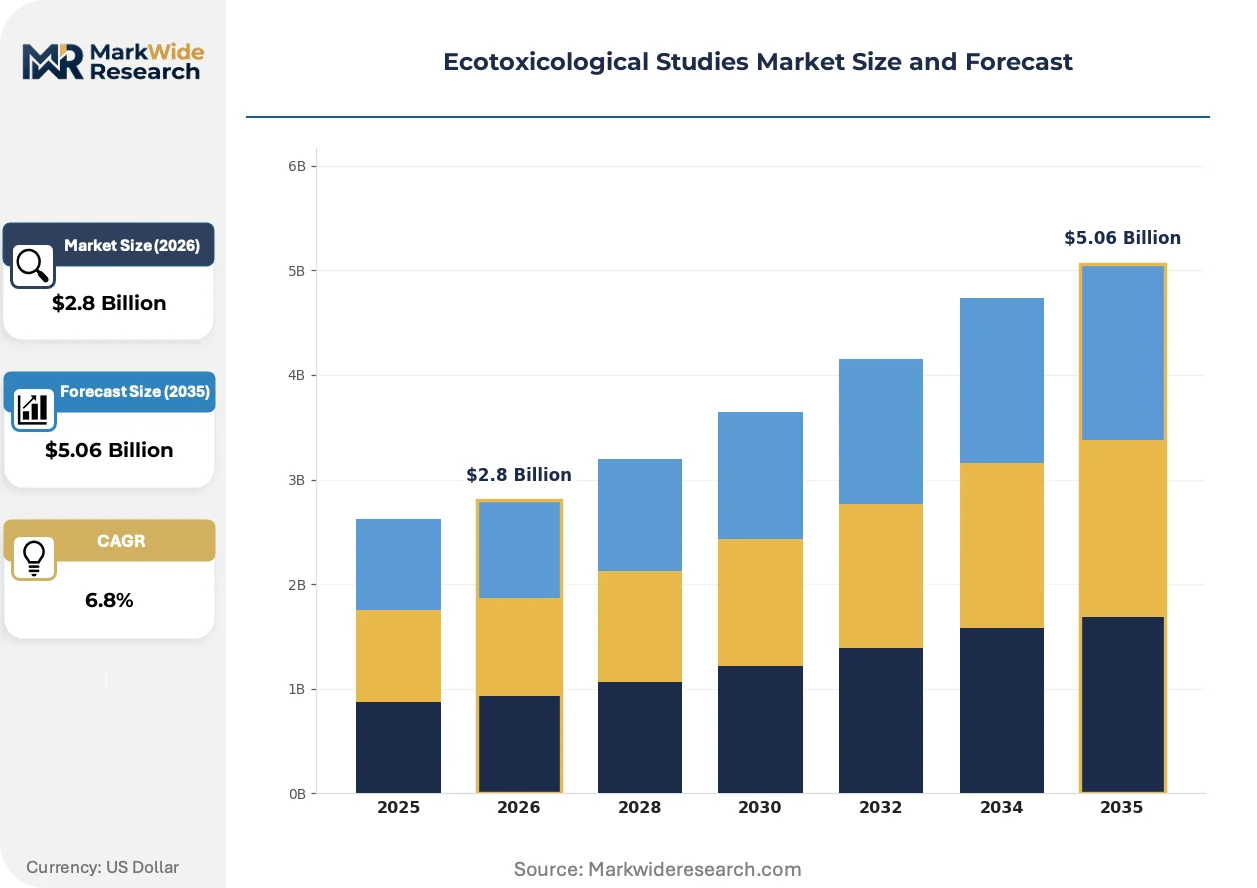
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.06 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Study Type: Laboratory Studies, Field Studies, Modeling Approaches, Risk Assessment Biological Organism: Bacteria, Algae, Invertebrates, Fish Effect Measurement: Mortality, Growth, Reproduction, Behavior Study Purpose: Regulatory Compliance, Environmental Impact, Hazard Identification, Risk Characterization |
| Companies Covered | Eurofins Scientific, Charles River Laboratories, SGS, Labcorp, Bureau Veritas, Smithers, Fera Science Limited, Intertek Group, TÜV SÜD, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ecotoxicological Studies Market Strategic Shifts & Innovations
Regulatory acceptance of non-animal methods and buyer pressure for faster study turnaround are restructuring how ecotoxicological data is generated, validated, and submitted for chemical registration.
High-throughput screening platforms using zebrafish embryos and automated behavioral analysis are fragmenting the traditional acute toxicity study market. Pharmaceutical developers now embed these platforms into early candidate selection workflows, compressing the timeline for environmental hazard flagging before regulatory dossier preparation begins. This fragmentation is displacing standalone acute fish toxicity contracts that previously represented standard entry-level service offerings.
EPA's updated Endangered Species Act consultation requirements for new chemical approvals now mandate species-specific toxicity data for listed aquatic organisms. Industrial chemical registrants must conduct additional whole-effluent toxicity testing or mesocosm studies when standard laboratory species differ from local endangered populations. The Great Lakes and Pacific Northwest manufacturing corridors face the steepest compliance cost escalation under these revised biological opinion procedures.
Contracting patterns among agrochemical registrants now favor multi-year framework agreements with fixed pricing over transactional study orders. Bayer CropScience and Syngenta affiliates in Germany and Switzerland have consolidated supplier panels to three preferred laboratories, extracting volume commitments in exchange for guaranteed capacity allocation. This concentration is most visible in the Rhine corridor, where industrial chemical producers cluster and maintain overlapping in-house and outsourced study demand.
Ecotoxicological Studies Market Segmentation
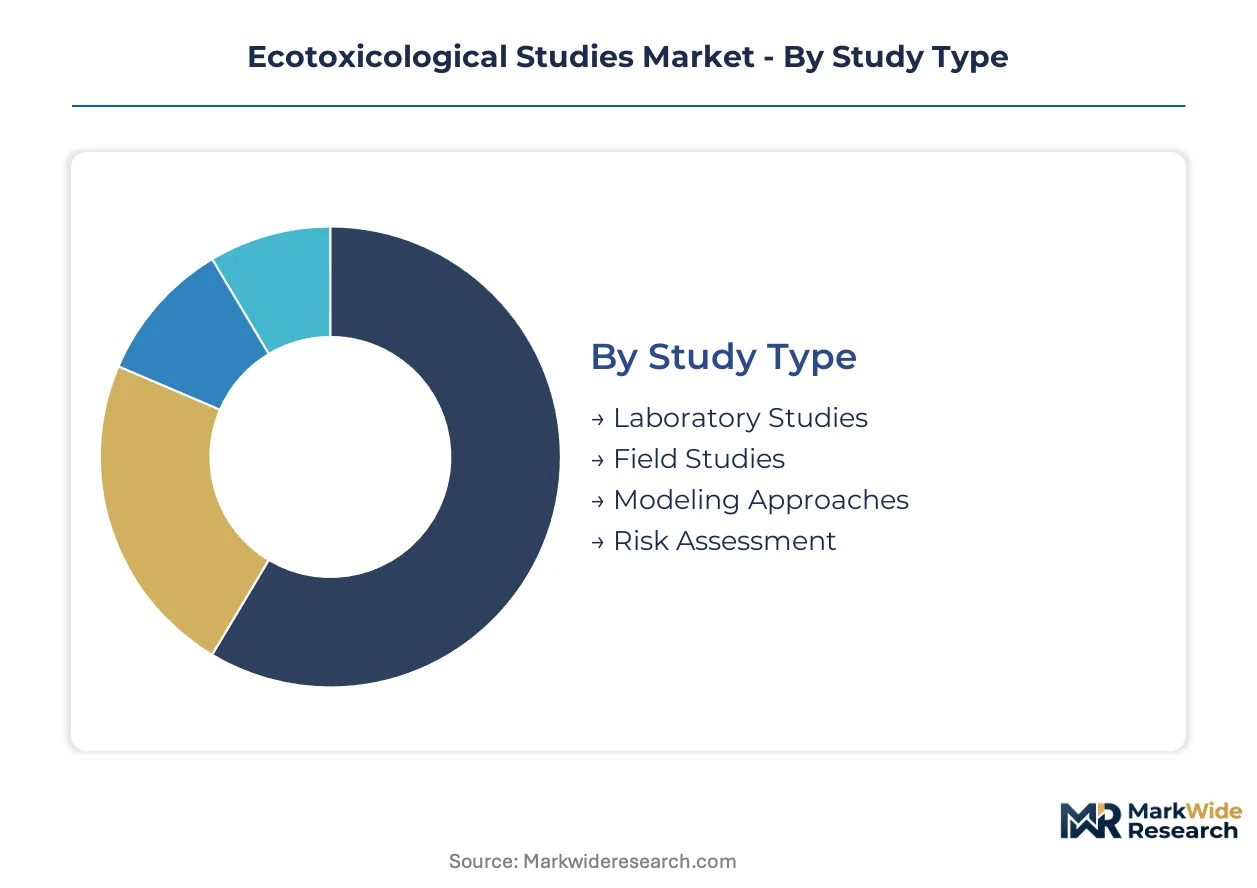
Ecotoxicological studies fragment across multiple technical dimensions that determine pricing, regulatory acceptance, and buyer procurement patterns. Contract research organizations configure service portfolios around study type capabilities and biological organism expertise to capture specific registration workflows.
Study Type:
Laboratory studies flow through established CRO channels with predictable regulatory acceptance, while modeling approaches increasingly route through specialized computational toxicology boutiques and in-house pharma teams.
- Laboratory Studies:Controlled exposure protocols under OECD, EPA, or ISO guidelines generate reproducible lethal concentration and no-observed-effect concentration data. Pharmaceutical manufacturers in Germany and agrochemical registrants in Switzerland concentrate procurement here for REACH and EMA dossier submissions. By volume, Laboratory Studies leads. By growth pace, Modeling Approaches is ahead.
- Field Studies:Mesocosm and whole-effluent toxicity investigations measure population-level endpoints in semi-natural conditions. EPA Endangered Species Act consultation requirements in the US Great Lakes corridor and Pacific Northwest manufacturing clusters drive specialized demand where standard laboratory species differ from listed populations.
- Modeling Approaches:In silico prediction tools under OECD QSAR guidelines enable rapid screening workflows. REACH and EPA New Chemicals programs now accept these for early-tier assessments, expanding throughput for candidate prioritization.
- Risk Assessment:Weight-of-evidence synthesis combining multiple data streams commands premium pricing. ECHA authorization processes and complex pharmaceutical environmental risk assessments require specialized toxicological expertise.
Service bundling across these channels depends on laboratory investment in both wet-lab infrastructure and computational platforms.
Biological Organism:
Organism selection tracks trophic level coverage requirements and regulatory guideline specifications, with capital-intensive fish facilities creating supply concentration at the top tier.
- Fish:Early life stage testing under OECD 210 mandates 28- to 32-day exposure periods with temperature-controlled recirculation infrastructure. Rhine corridor chemical producers and EPA-registrants maintain the densest outsourcing relationships here. Fish commands the highest study values. Algae expands most quickly as screening-tier demand surges.
- Invertebrates:Daphnia acute and chronic toxicity protocols serve as standard regulatory screening tools. REACH substance evaluation and industrial chemical classification workflows generate consistent contract volumes across European member states.
- Algae:OECD 201 growth inhibition studies provide rapid, cost-effective primary producer toxicity data. High-throughput platform integration is accelerating throughput for pharmaceutical candidate filtering.
- Bacteria:Activated sludge respiration and nitrification inhibition tests support biodegradation and environmental fate assessments. Anaerobic digester infrastructure requirements push this toward specialized providers.
Facility specialization around fish and invertebrates locks in premium positioning, while algae and bacteria capabilities commoditize more rapidly.
Effect Measurement:
Endpoint selection determines study duration, complexity, and regulatory weight, with multi-generational measurements requiring extended capacity commitments.
- Mortality:Acute lethal concentration thresholds remain the baseline regulatory requirement across jurisdictions. Standardized 48- to 96-hour protocols deliver rapid turnaround for initial hazard classification.
- Reproduction:Chronic daphnia and fish full life cycle studies measure fecundity and offspring viability. ECHA authorization and higher-tier REACH evaluations mandate these for persistent, bioaccumulative substances.
- Growth:Biomass and length endpoints in algae and fish early life stage protocols quantify sublethal effects. OECD guideline standardization ensures cross-laboratory comparability.
- Behavior:Automated tracking of locomotor and feeding responses in zebrafish embryos enables high-throughput neurotoxicity screening. Pharmaceutical developers embed these platforms into early candidate selection workflows.
Mortality studies dominate transaction volumes. Reproduction measurements carry the steepest pricing premiums due to duration and expertise requirements.
Study Purpose:
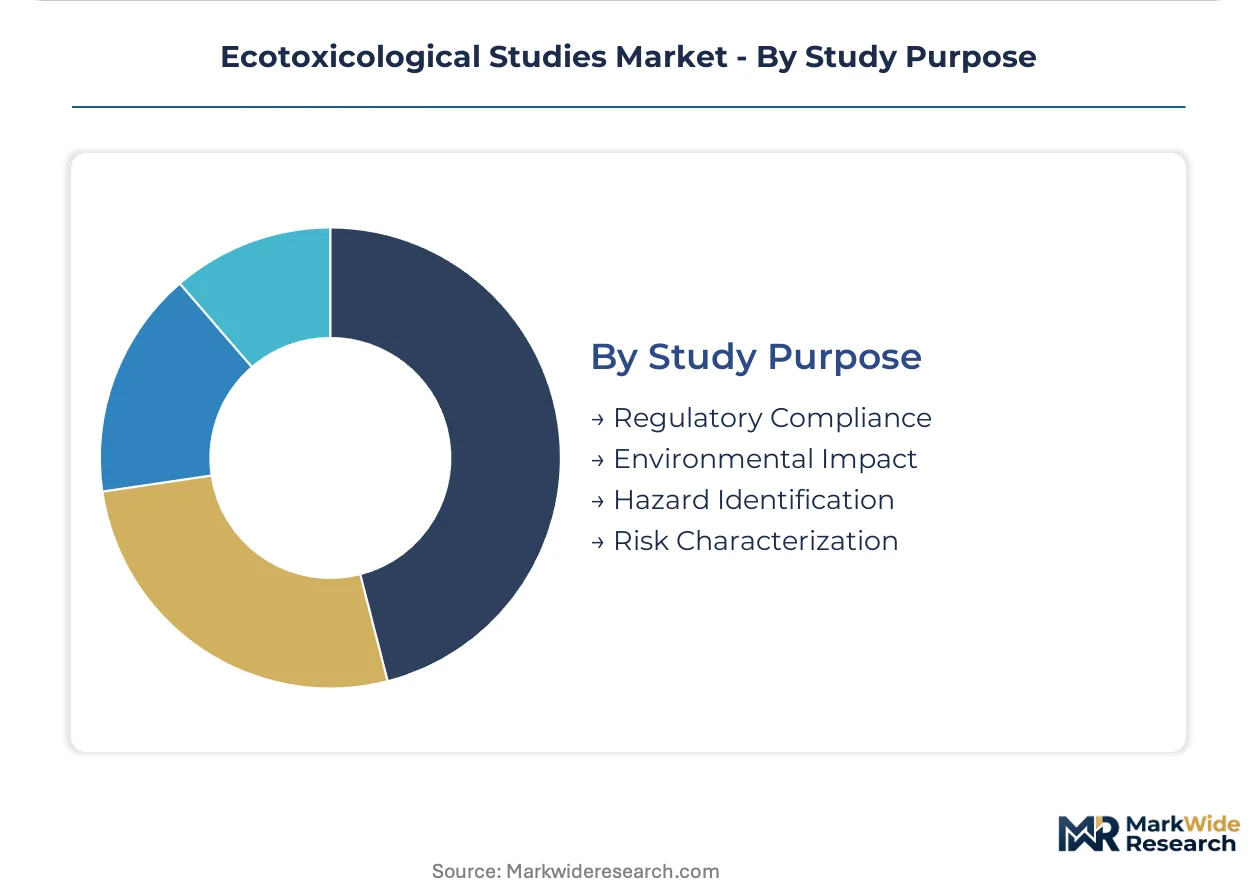
Purpose segmentation aligns with regulatory submission timelines and data quality standards, separating baseline hazard screening from complex risk characterization.
- Regulatory Compliance:Standardized dossier components for REACH registration, EMA marketing authorization, and EPA new chemical approvals. Chemical consortia and pharmaceutical developers procure these as non-discretionary expenditures.
- Risk Characterization:Probabilistic exposure and effects integration for product-specific environmental concentrations. Specialized expertise requirements limit provider pools and sustain margin structures.
- Hazard Identification:Initial toxicity profiling for candidate prioritization and classification. Computational tools and high-throughput screening are compressing traditional in vivo demand here.
- Environmental Impact:Site-specific assessments for manufacturing discharge permits and remediation evaluation. Industrial facilities along the Rhine and US manufacturing corridors drive localized demand.
Regulatory Compliance generates the deepest contract backlogs. Risk Characterization delivers the highest per-study margins.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine River corridor and its tributary chemical transport infrastructure anchors European ecotoxicological study demand, while EPA-regulated manufacturing corridors in the United States drive parallel contract research volumes.
Germany
Industrial chemical producers along the Rhine corridor generate dense outsourcing demand for aquatic toxicity and environmental fate studies. ECHA's REACH substance evaluation obligations tighten data requirements for industrial chemical consortia across member states. BASF and Bayer CropScience affiliates in Ludwigshafen and Leverkusen maintain overlapping in-house capabilities and external contract relationships.
United States
EPA-administered Toxic Substances Control Act and Endangered Species Act consultation requirements mandate ecotoxicity data for new chemical approvals. The agency's updated aquatic life benchmarks intensify demand for higher-tier multispecies and mesocosm studies. Manufacturing facilities in the Great Lakes corridor and Pacific Northwest face steepest compliance cost escalation under revised biological opinion procedures.
Switzerland
Swissmedic and federal environmental protection frameworks enforce pharmaceutical and chemical environmental risk assessment obligations. Syngenta affiliates in Basel have consolidated supplier panels to preferred laboratories, extracting volume commitments for guaranteed capacity allocation. The country's precision chemical manufacturing base sustains premium-priced study procurement.
United Kingdom
Fera Science Limited and specialized contract research organizations anchor post-Brexit regulatory compliance services. The Environment Agency's chemical registration requirements and retained REACH obligations sustain study demand. Industrial clusters in Yorkshire and the Northwest maintain consistent outsourcing relationships for aquatic and terrestrial toxicity protocols.
France
ANSM pharmaceutical environmental risk assessment mandates and industrial chemical classification workflows generate contract volumes across metropolitan regions. Eurofins Scientific leverages its pan-European laboratory network to anchor study capacity serving French registrants. Lyon and Paris-based chemical producers concentrate procurement for OECD guideline-compliant investigations.
Ecotoxicological Studies Market Key Industry Players
Listed leaders compete with private specialists across regulatory jurisdiction coverage and biological organism expertise. The vendor base clusters around three capability tiers: pan-European network operators with multi-country laboratory footprints, specialized fish testing facilities with purpose-built aquaculture infrastructure, and computational toxicology boutiques with in silico prediction platforms. Strategic moves concentrate on framework agreement consolidation among agrochemical registrants and capacity expansion into underserved terrestrial toxicity protocols.
Within the pan-European network tier, Eurofins Scientific exemplifies geographic coverage archetypes, while Charles River Laboratories occupies a position representing specialized fish early life stage testing infrastructure. SGS anchors the environmental fate and biodegradation study segment serving European chemical consortia navigating REACH data requirements.
| Leading Market Players |
|---|
| Eurofins Scientific |
| Charles River Laboratories |
| SGS |
| Labcorp |
| Bureau Veritas |
| Smithers |
| Fera Science Limited |
| Intertek Group |
| TÜV SÜD |
| Others |
Cost & Logistics Intelligence
Sixty-day lead times for certified reference materials in aquatic toxicity calibration concentrate pricing power among three European suppliers, compressing margins for contract research organizations while amplifying cost pass-through to pharmaceutical and agrochemical registrants. This inventory rigidity locks laboratories into long-term supplier relationships that resist spot-market arbitrage.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs ecotoxicological study procurement, with premium tiers capturing OECD 210 fish early life stage protocols requiring 28- to 32-day exposure periods and specialized aquaculture infrastructure. Price differentiation rests on certification level—GLP-compliant studies command substantial premiums over non-GLP screening—and volume scale, where multi-year framework agreements with Bayer CropScience and Syngenta affiliates extract 15-20% discounts. Cost compression in standard-tier acute toxicity screening is intensifying because high-throughput zebrafish embryo platforms displace traditional fish studies. Agrochemical registrants exhibit highest price sensitivity due to consolidated supplier panels, while pharmaceutical developers prioritize speed over unit cost.
Supply Chain Analysis
Certified reference material production concentrates in Germany, the United Kingdom, and the Netherlands, creating single-source vulnerability for aquatic toxicity calibration standards that feed into ECHA and EPA compliance workflows. Contract research organizations draw from temperature-controlled recirculation systems, anaerobic digester infrastructure, and automated behavioral analysis platforms as critical capital inputs. Tariff exposure on precision laboratory equipment imported from Switzerland and Japan elevates facility establishment costs. Distribution runs through pan-European laboratory networks and specialized computational toxicology boutiques serving REACH and EPA New Chemicals programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from in silico prediction tools gaining regulatory traction under OECD QSAR guidelines, compressing traditional wet-lab study volumes and forcing capability diversification.
For Market Incumbents: Secure multi-year framework agreements with agrochemical registrants in the Rhine corridor to lock in capacity utilization against computational toxicology displacement. Invest in integrated testing strategies combining in silico, in chemico, and in vivo capabilities to capture REACH and EPA weight-of-evidence acceptance. Build backward integration into certified reference material supply to reduce input price volatility exposure.
For New Entrants and Emerging Players: Terrestrial toxicity protocols for soil macroorganisms and plant testing represent under-served white space relative to saturated aquatic study markets. Target pharmaceutical developers embedding high-throughput zebrafish screening into early candidate selection workflows, where speed and automation outweigh established laboratory relationships. Lead with computational toxicology boutiques offering rapid QSAR screening before regulatory dossier preparation begins.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory compliance play because ECHA authorization timelines and EPA Endangered Species Act consultation requirements institutionalize non-discretionary study demand regardless of macroeconomic cycles. Acquisition candidates should display cross-method capability spanning wet-lab infrastructure and in silico platforms. Watch regulatory acceptance velocity for alternative test methods as the key inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Integrated Testing Strategy Investment | REACH and EPA weight-of-evidence acceptance expands service bundling opportunities across method types. |
| Terrestrial Toxicity Capability Buildout | Soil macroorganism and plant testing protocols remain underserved relative to aquatic studies. |
| Computational Toxicology Platform Acquisition | OECD QSAR guideline traction enables rapid screening workflows for pharmaceutical candidate prioritization. |
| Multi-Year Framework Agreement Expansion | Agrochemical registrant consolidation to preferred supplier panels extracts volume commitments. |
| Certified Reference Material Supply Integration | Backward integration into calibration standards reduces exposure to three-supplier concentration. |
Research Approach
Two parallel data streams informed the analysis: structured primary interviews with study directors at contract research organizations, regulatory affairs leads at pharmaceutical manufacturers, and procurement managers at agrochemical registrants; and secondary validation through ECHA registration dossiers, EPA New Chemicals program submissions, OECD test guideline documentation, and SEC filings from listed laboratory operators. Bottom-up study volume estimates triangulated against top-down market sizing derived from regulatory submission frequency and average per-study pricing.
Across the analysis window, the forecasting framework modeled ecotoxicological study demand by study type, biological organism, effect measurement endpoint, and study purpose, with additional segmentation by regulatory jurisdiction cluster. CAGRs were derived from regulatory pipeline analysis and historical submission patterns. Key inputs included REACH substance evaluation timelines, EPA aquatic life benchmark update schedules, and pharmaceutical environmental risk assessment mandate expansion rates.
Underlying assumptions cover sustained regulatory enforcement of ECHA authorization and EPA consultation requirements, with deviation risk concentrated in accelerated acceptance of alternative test methods that compress traditional in vivo study volumes. Practitioners should keep alternative scenarios live as OECD guideline revision cycles and integrated testing strategy validation evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Environmental Monitoring
Real-Time Flood Monitoring and Warning System Market
Environmental Monitoring
Water Pipeline Leak Detection System Market
Environmental Monitoring
Environmental Radiation Monitor Market
Environmental Monitoring
Asia Pacific Air Quality Monitoring Market
Environmental Monitoring
Environment Monitoring Devices Market
Environmental Monitoring
Canada Cloud Seeding Market
Environmental Monitoring
United States Erosion Sediment Control Market
Environmental Monitoring
Water Quality Monitoring Equipment Market
Environmental Monitoring
Green Mining Market
Environmental Monitoring
Emission Monitoring Systems Market
Environmental Monitoring
Weather Modification Equipment Market
Environmental Monitoring
Global Weather Forecasting Services Market
Environmental Monitoring
Global Indoor Air Quality Solutions Market
Environmental Monitoring
Environmental Hazard Monitoring (EHM) Software Market
Environmental Monitoring
India Cloud Seeding Market
Environmental Monitoring
Environmental Remediation Technologies Market